
 Solar PV Carport Market | 2026-2036
Solar PV Carport Market Size, Share, and Industry Trends Forecast 2026-2036
Solar PV Carport Market Insights
Energy-as-a-service contracting is pivoting how solar carport developers monetize installations, shifting capital burden from property owners to third-party operators. SunPower Corporation leverages its distributed generation expertise to anchor premium commercial deployments. DSD Renewables competes through proprietary canopy engineering that reduces foundation costs. Antai Technology Co. Ltd specializes in steel structure manufacturing at scale, extending its cost advantage across utility-scale parking arrays.
A solar PV carport integrates photovoltaic modules into elevated canopy structures installed above parking areas, typically spanning 15-25 feet in clearance height and engineered for wind loads exceeding 90 mph. The primary purpose is dual-use land optimization, generating electricity while providing weather protection for vehicles. Standard carports dominate volume deployments due to repeatable engineering and shorter permitting cycles. Bifacial PV technology captures the fastest growth within module selection, as rear-side albedo gain improves yield on reflective asphalt surfaces. Commercial entities represent the deepest margin pool among end users, given their balance-sheet capacity and sustainability disclosure obligations.
The Federal Energy Regulatory Commission shapes grid interconnection rules that determine project viability for large parking canopy arrays, while state-level renewable portfolio standards in California and New York mandate procurement thresholds that pull solar carport development forward. The EPA's greenhouse gas reporting requirements for commercial buildings create compliance-driven demand for on-site generation. Stakeholders must monitor evolving local parking code amendments that increasingly embed EV-ready infrastructure and solar readiness into new commercial construction.
Market Dynamics
Bifacial PV module technology is compressing project payback periods and forcing developers to re-engineer canopy geometries around rear-side albedo capture rather than single-plane efficiency maximization.
Growth Catalysts
- California's Solar-Ready Parking Mandate:New commercial construction in the state must incorporate EV-capable infrastructure and solar-ready electrical pathways, pulling forward carport deployment timelines.
- Logistics Campus Electrification:Amazon, FedEx, and UPS distribution centers are procuring covered parking-to-power systems to meet fleet electrification targets and Scope 3 disclosure requirements.
- Bifacial Module Cost Parity:Manufacturing scale in China and Southeast Asia has driven bifacial unit costs to match monofacial equivalents, eliminating the premium barrier to dual-sided energy capture.
Market Restraints
- Structural Steel Input Volatility:Galvanized steel canopy framing represents 35-40% of installed costs, exposing margins to scrap metal and zinc price swings tied to Chinese industrial output.
- Foundation Engineering Complexity:Poor soil conditions in coastal Florida and Gulf Coast Texas force expensive micropile or helical pier foundations that erode project economics.
- Grid Interconnection Queues:FERC Order 2023 implementation delays are extending utility study timelines to 18-24 months for parking canopy arrays exceeding 5 MW AC capacity.
Strategic Opportunities
- India Commercial Parking Retrofit:The country's Bureau of Energy Efficiency mandates solar readiness for buildings over 100 kW load, creating untapped demand across Mumbai and Bangalore office parks.
- Vehicle-to-Grid Integration:Bidirectional charging hardware converging with solar carport DC-coupled architecture enables parking assets to function as grid-stabilizing storage nodes.
- Energy-as-a-Service Channel Expansion:Third-party ownership platforms are bypassing traditional C&I loan markets, capturing customers with balance-sheet constraints through performance-guaranteed contracts.
Industry Challenges
- Electrical Design Talent Scarcity:Project developers face acute shortages of licensed professional engineers with combined expertise in medium-voltage interconnection and canopy structural loading.
- Jurisdictional Permitting Fragmentation:Local fire marshal interpretations of NEC Article 690 vary across municipal boundaries, forcing redundant plan reviews and field inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar PV Carport Market |
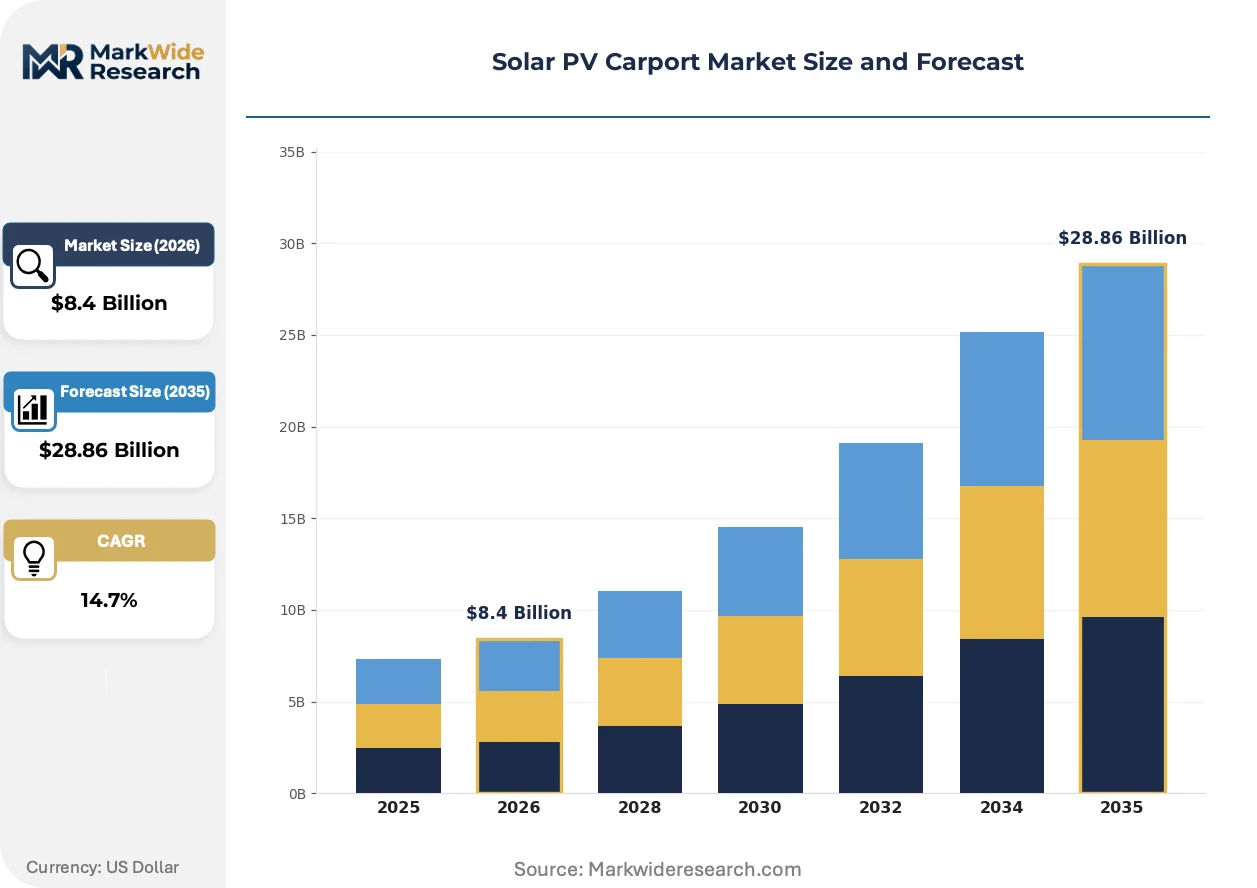
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $28.86 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Carports, Canopy Structures, Dual-Use Carports, Customized Solutions End User: Residential Users, Commercial Entities, Government Facilities, Educational Institutions Installation Type: On-Site Installation, Off-Site Preassembly, Integrated Systems, Modular Solutions Technology: Monocrystalline PV, Polycrystalline PV, Thin-Film PV, Bifacial PV |
| Companies Covered | FlexiSolar, Schletter, SunPower Corporation, DSD Renewables, Antai Technology Co. Ltd, Tata Power, iSun, Inc., Solar Optimum, Parasol Structures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar PV Carport Market Trends and Innovations
Technology convergence between photovoltaic generation, electric vehicle charging, and grid-interactive storage is redefining what parking infrastructure must deliver. Three forces are compressing development timelines and reshaping competitive positioning.
Agrivoltaic-compatible elevated canopy designs are overtaking standard fixed-tilt structures in premium commercial deployments. These systems integrate bifacial modules at 20-25 foot clearance heights to accommodate maintenance vehicle passage beneath while capturing ground-reflected irradiance. REITs and corporate campus operators in Texas and Arizona are specifying these configurations to preserve future land-use optionality.
Germany's EEG 2023 reform has eliminated the 52 GW solar capacity cap and introduced streamlined permitting for parking canopy systems under 1 MW. This regulatory unlocking is accelerating project origination across Bavarian automotive supplier parks. Developers are responding by pre-certifying standardized canopy designs to compress approval cycles.
Corporate buyers are consolidating procurement through sustainability-linked lease structures rather than traditional equipment purchase. This behavioral pivot transfers operational risk to specialized parking-to-power operators while capturing off-balance-sheet treatment. The pattern is most pronounced among Fortune 500 logistics networks with multi-site parking portfolios exceeding 10,000 covered spaces.
Solar PV Carport Market Segmentation
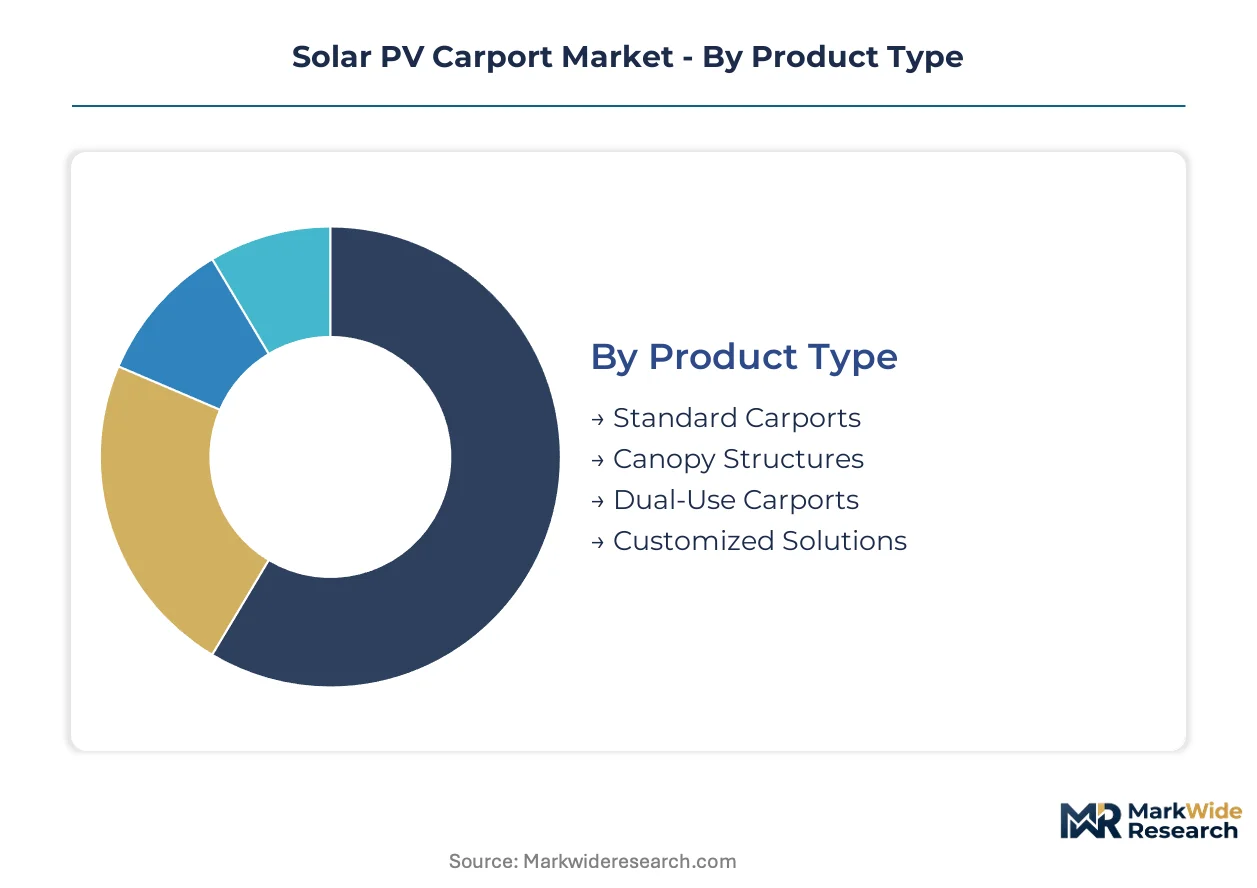
Solar PV carport segmentation reveals how engineering specifications, procurement pathways, and module technologies create distinct margin profiles. Developers must match canopy architecture to soil conditions, electrical load profiles, and interconnection voltage classes. The four segmentation dimensions below determine project economics and competitive positioning.
Product Type:
Certification burdens vary sharply across canopy geometries. Standard carports require only structural PE stamps and NEC Article 690 compliance. Customized solutions trigger additional wind tunnel testing and jurisdiction-specific fire marshal approval cycles.
- Standard Carports:Fixed-tilt steel structures with 15-18 foot clearance and repeatable foundation patterns. Amazon fulfillment centers in Texas and Arizona specify these for rapid deployment across multi-site parking portfolios.
- Canopy Structures:Elevated designs with integrated water management and architectural finishes. Premium commercial campuses in Germany and California select these to meet aesthetic guidelines while capturing bifacial albedo gains on reflective surfaces.
- Dual-Use Carports:Agrivoltaic-compatible systems with 20-25 foot clearance accommodating maintenance vehicle passage. Demand concentrates where land-use optionality preservation matters.
- Customized Solutions:Project-specific engineering for irregular site constraints or heritage overlay districts. Each deployment requires unique structural analysis and extended permitting timelines.
Leading the category by volume: Standard Carports. Expanding most quickly: Canopy Structures.
End User:
Customer type dictates financing structure and contract duration. Commercial entities leverage off-balance-sheet treatment through energy-as-a-service platforms. Government facilities navigate public procurement statutes with extended vendor qualification periods.
- Commercial Entities:Retail and logistics campuses with sustainability disclosure obligations. FedEx and UPS distribution centers procure covered parking-to-power systems to meet fleet electrification targets and Scope 3 reporting requirements.
- Residential Users:Single-family and multi-family property owners with limited parking bay counts. California's solar-ready parking mandate pulls forward deployment in new construction.
- Government Facilities:Federal, state, and municipal parking assets subject to public bidding rules. Procurement cycles extend 12-18 months but offer contract stability.
- Educational Institutions:University and K-12 campuses with predictable daytime load profiles. These buyers prioritize student-facing sustainability credentials and curriculum integration opportunities.
Deepest margin pool: Commercial Entities. Fastest procurement acceleration: Government Facilities responding to federal sustainability mandates.
Installation Type:
Delivery methodology determines labor cost exposure and weather risk allocation. On-site construction dominates in markets with restrictive transport access. Preassembly gains share where skilled electrician scarcity drives field cost inflation.
- On-Site Installation:Traditional stick-built construction with steel delivery, foundation work, and module mounting performed sequentially. Prevails in markets with complex soil conditions requiring adaptive foundation engineering.
- Off-Site Preassembly:Canopy modules fabricated in controlled factory environments and transported for rapid field connection. Reduces weather delays and compresses commissioning schedules.
- Integrated Systems:PV modules, inverters, and structural elements delivered as unified packages from single-source suppliers. Simplifies warranty management and reduces interface risk.
- Modular Solutions:Standardized canopy units with plug-and-play electrical connections. Enables phased deployment and future capacity expansion without full system redesign.
Cost tier separation: Off-Site Preassembly commands premium pricing for schedule certainty. Volume leader: On-Site Installation.
Technology:
Module selection determines energy yield per parking bay and rear-side gain capture capability. Bifacial architectures require canopy geometry re-engineering around ground reflectance optimization rather than single-plane efficiency maximization.
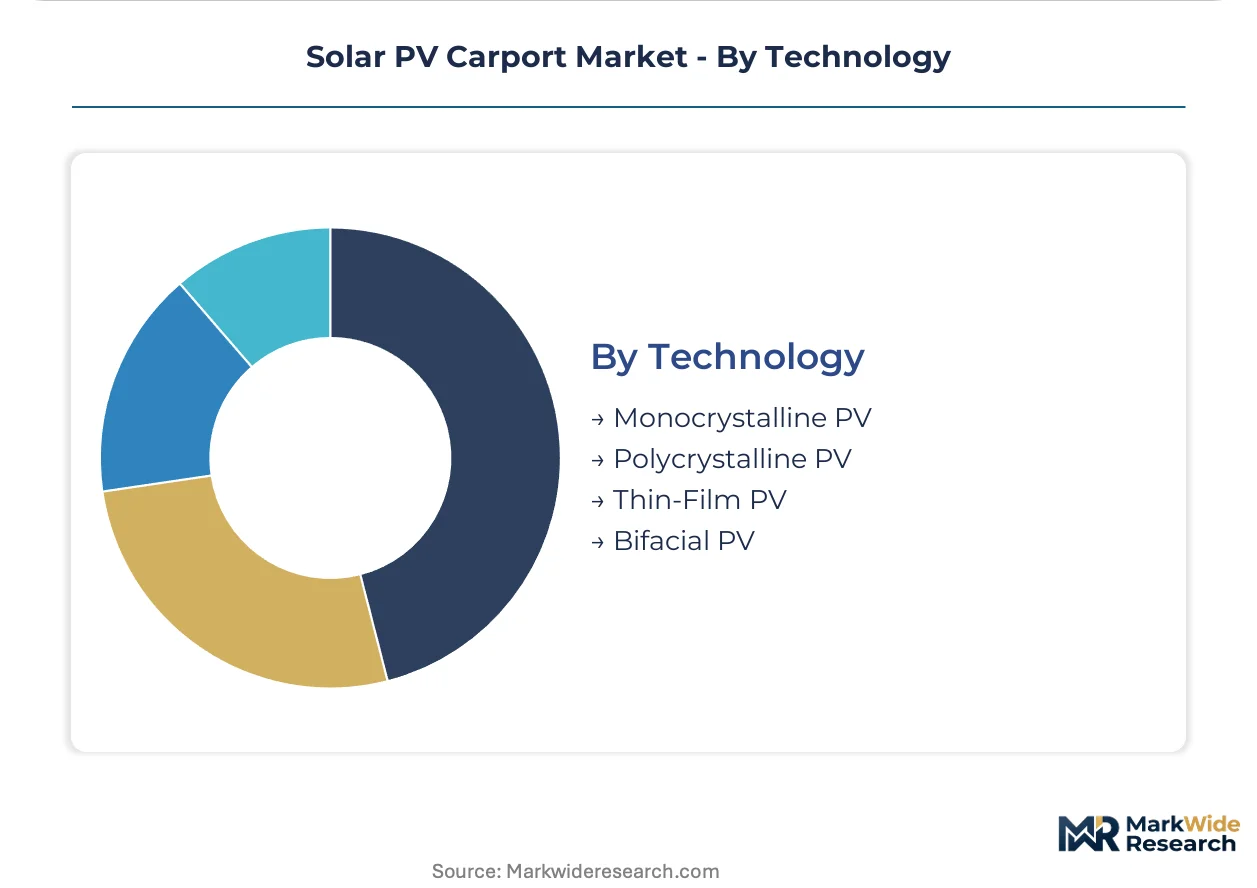
- Bifacial PV:Dual-sided energy capture exploiting albedo from asphalt and concrete surfaces. Manufacturing scale in China has driven unit costs to parity with monofacial equivalents, eliminating the premium barrier to adoption.
- Monocrystalline PV:Single-crystal silicon cells with highest commercial efficiency rates. Standard choice for space-constrained installations where wattage per square foot dominates project economics.
- Polycrystalline PV:Multi-crystal silicon with lower efficiency but historical cost advantage. Retains niche presence in price-sensitive utility-scale deployments.
- Thin-Film PV:Cadmium telluride or CIGS architectures with superior low-light performance and temperature coefficients. Selected for high-temperature climates where thermal degradation erodes crystalline silicon output.
Technology leadership by deployment velocity: Bifacial PV. Mature cost-optimized baseline: Monocrystalline PV.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phoenix anchors commercial solar carport deployment through its logistics corridor concentration and reflective desert surfaces that maximize bifacial module yield.
United States
California's solar-ready parking mandate and Texas logistics electrification drive procurement velocity. FERC Order 2023 shapes interconnection timelines for multi-megawatt canopy arrays. Amazon fulfillment centers across Dallas-Fort Worth and Phoenix specify standard carports for rapid multi-site rollout.
Germany
Bavarian automotive supplier parks and corporate campuses generate concentrated demand for premium canopy structures. EEG 2023 reform eliminated capacity caps and streamlined sub-1 MW permitting. Munich and Stuttgart industrial zones are pre-certifying standardized designs to compress approval cycles.
China
Manufacturing scale in bifacial module production has driven cost parity with monofacial equivalents. The country's dual carbon goals accelerate commercial parking retrofits in Shanghai and Shenzhen business districts. Yangtze River Delta steel fabricators supply structural components for domestic and export markets.
India
Bureau of Energy Efficiency mandates solar readiness for commercial buildings exceeding 100 kW load. Mumbai and Bangalore office parks present untapped retrofit demand across multi-site portfolios. State-level renewable purchase obligations in Maharashtra and Karnataka pull project origination forward.
United Arab Emirates
Dubai's commercial construction codes increasingly embed EV-ready infrastructure and solar electrical pathways. Reflective asphalt surfaces in desert climates optimize bifacial rear-side gain capture. Abu Dhabi government facilities navigate public procurement statutes with extended vendor qualification periods.
Solar PV Carport Market Competitive Landscape
Capital-heavy steel fabricators compete with asset-light canopy designers for project origination control. The market structures around three tiers: integrated manufacturers with captive structural production, specialized engineering firms with proprietary foundation systems, and regional installers with local permitting relationships. Dominant competitive moves include backward integration into steel galvanizing capacity and pre-certification of standardized designs to compress jurisdictional approval cycles.
Among Germany-based structural specialists, Schletter occupies a position within the premium engineering tier, exemplifying European precision in canopy load calculations. SunPower Corporation and DSD Renewables represent the integrated North American archetype, anchoring distributed generation expertise against commercial procurement consolidation. Antai Technology Co. Ltd sits within the scale-driven manufacturing segment, reflecting Chinese industrial capacity in galvanized steel production.
| Leading Market Players |
|---|
| FlexiSolar |
| Schletter |
| SunPower Corporation |
| DSD Renewables |
| Antai Technology Co. Ltd |
| Tata Power |
| iSun, Inc. |
| Solar Optimum |
| Parasol Structures |
| Others |
Pricing and Supply Chain Analysis
Hot-rolled coil steel indices from the Yangtze River Delta cascade through solar carport supply chains into three-tier pricing structures across premium, standard, and economy levels. Galvanized framing cost volatility forces developers to index long-term offtake contracts against regional metal benchmarks or absorb margin compression.
Pricing Analysis
Margin tightening in standard carport tiers reflects Chinese bifacial module oversupply and steel tariff exposure. Project-based pricing dominates, with differentiation driven by UL 2703 certification grade and foundation engineering complexity. Cost-down pressure accelerates as logistics campus buyers consolidate procurement through energy-as-a-service platforms. Government facilities exhibit lowest price sensitivity due to public procurement statutes; residential users face highest sensitivity given limited parking bay counts.
Supply Chain Analysis
Dual-sourcing requirements from REIT procurement officers mandate qualified steel fabricators in China and India alongside domestic US galvanizers. Bifacial PV modules, galvanized structural steel, and helical pier hardware anchor component dependencies. Single-source vulnerability concentrates in Yangtze River Delta steel capacity. Distribution runs through EPC contractors with FERC interconnection expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive galvanizing capacity and pre-certified canopy designs determine origination control. Backward integration into steel production separates margin leaders from price-takers.
For Market Incumbents: Extend pre-certification pipelines across municipal fire marshal jurisdictions to compress permitting cycles. Anchor proprietary foundation engineering for poor soil conditions in Florida and Texas Gulf Coast. Defend against DSD Renewables' canopy cost advantages through captive galvanizing investments.
For New Entrants and Emerging Players: Capture Bureau of Energy Efficiency compliance demand across Mumbai and Bangalore office parks before incumbent pre-certification spreads. Penetrate India's 100 kW commercial building retrofit segment through modular DC-coupled architecture with bidirectional EV charging integration.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized engineering firms with FERC interconnection expertise in California and Texas during grid study queue backlogs. Long-term viability hinges on vehicle-to-grid hardware convergence. Watch FERC Order 2023 implementation velocity as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Galvanizing | Captive steel coating capacity insulates margins from zinc price volatility. |
| Pre-Certification of Standardized Designs | UL 2703 and wind tunnel stamps compress jurisdictional approval timelines. |
| Energy-as-a-Service Platform Launch | Third-party ownership transfers capital burden from REIT balance sheets. |
| Vehicle-to-Grid Hardware Integration | Bidirectional charging converts parking assets into grid-stabilizing nodes. |
| Agrivoltaic-Compatible Canopy Engineering | Elevated 20-25 foot clearances preserve land-use optionality for Texas REITs. |
Research Methodology
Multi-period observation of bifacial module pricing trajectories and steel input indices anchored the trend analysis, supplemented by interviews with EPC contractors, REIT sustainability officers, FERC interconnection specialists, and galvanizing plant managers. Secondary validation drew from EIA generation data, FERC docket filings, state renewable portfolio standard progress reports, and customs records of galvanized steel imports. Bottom-up project pipeline aggregation triangulated against top-down regulatory mandate sizing.
Segment-weighting across product type, end user, installation methodology, and module technology dimensions shaped the analytical framework. CAGRs derived from capacity deployment trajectories across the projection horizon, incorporating interconnection queue timelines, parking code amendment velocity, and fleet electrification procurement schedules as industry-specific inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FERC Order 2023 implementation delays and Chinese industrial policy shifts. Deviation in galvanized steel tariff schedules or bifacial module trade remedy proceedings would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Europe Solar Microinverter Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
US Solar Carport Market
Solar Power Systems
Thin Film Photovoltaic Modules Market
Solar Power Systems
Italy Distributed Solar Power Generation Market
Solar Power Systems
Japan Solar Energy Market
Solar Power Systems
Europe Solar Backsheet Market
Solar Power Systems
Solar Energy Market
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
DSC Solar Technologies Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
Solar Shed Light Market
Solar Power Systems
South Korea Solar Energy Market
Solar Power Systems
Global Photovoltaic Glass Market
Solar Power Systems
US Solar Market
Solar Power Systems
Distributed Solar Energy Market