
 Equatorial Guinea Power EPC Market | 2026-2036
Equatorial Guinea Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Equatorial Guinea Power EPC Market Foresight
Grid-code compliance tier is collapsing the gap between legacy thermal installations and modern hybrid configurations. General Electric Company leverages its aeroderivative turbine portfolio to anchor gas-to-power projects along the Punta Europa industrial complex. Wärtsilä Corporation specializes in flexible engine technology that sustains grid stability amid intermittent renewable injection. Bechtel Corporation competes on lump-sum turnkey discipline for large-scale infrastructure, differentiating through risk-transfer mechanics that mainland developers prioritize.
Equatorial Guinea Power EPC encompasses engineering, procurement, and construction services for electricity generation, transmission, and distribution infrastructure, typically executed under lump-sum or cost-reimbursement contracts with performance guarantees tied to heat rate, availability, and commercial operation date milestones. The discipline integrates civil works, mechanical erection, electrical interconnection, and control system commissioning to deliver operable assets for utilities and industrial offtakers. Commissioning services command premium margin pools as owner-engineer oversight tightens on hybrid solar-gas projects, while hydropower construction occupies the mature segment with limited greenfield potential on Bioko Island. Procurement scope is accelerating fastest as developers source Chinese-manufactured photovoltaic modules and European switchgear under split-package strategies to manage currency exposure.
The Ministry of Mines and Hydrocarbons regulates power sector licensing and enforces local content quotas that shape contractor selection and workforce composition on public tenders. The country's national standards body applies electrical safety and environmental impact protocols that filter market access for foreign EPC firms without domestic partnerships. Stakeholders must monitor how Rio Muni mainland grid extension priorities compete with Bioko Island reliability investments for limited public capital deployment.
Market Dynamics
Grid-code compliance tier is collapsing the gap between legacy thermal installations and modern hybrid configurations across Equatorial Guinea's power infrastructure landscape. The Ministry of Mines and Hydrocarbons mandates stricter interconnection standards that force simultaneous retirement planning and greenfield development.
Growth Catalysts
- Rural Electrification Mandates:The Ministry of Mines and Hydrocarbons accelerates grid extension tenders into mainland Rio Muni's unserved settlements. These mandates unlock public capital for transmission infrastructure that private developers previously avoided.
- Punta Europa Petrochemical Expansion:Industrial users along this coastal corridor are expanding captive power needs. Methanol and LNG processing facilities require dedicated generation assets with guaranteed availability.
- Hybrid Solar-Gas Configuration:Declining photovoltaic module costs enable solar-diesel and solar-gas hybrid systems. Developers split-package Chinese modules with European switchgear to manage currency exposure.
Market Restraints
- Local Content Quotas:The Ministry of Mines and Hydrocarbons enforces workforce composition requirements that inflate project costs. Foreign EPC firms must form domestic partnerships to access public tenders.
- Limited Bioko Island Hydropower Potential:Geological constraints eliminate greenfield hydro development on the primary load center. Developers cannot rely on conventional renewable baseload for urban reliability.
- Currency Volatility:CFA franc exposure against euro-denominated equipment contracts creates margin uncertainty. Split-package procurement strategies only partially hedge this structural risk.
Strategic Opportunities
- Mainland Rio Muni Grid Extension:Underpenetrated coastal zones and interior settlements lack transmission access. EPC contractors can anchor regional offices in Bata to capture sequential tender waves.
- Commissioning Services Premium:Owner-engineer oversight tightens on hybrid projects, elevating specialized commissioning margins. Technical advisory roles command pricing power absent from pure construction.
- Flexible Engine Technology:Wärtsilä Corporation's grid stability solutions enable higher renewable penetration. Gas engine balancing capacity supports intermittent solar injection without full storage investment.
Industry Challenges
- Skilled Technician Scarcity:Specialized control system commissioning requires expertise scarce in the domestic labor pool. Training timelines extend project schedules beyond contractual milestones.
- Legacy Thermal Integration:Existing heavy fuel oil plants demand complex retrofitting to meet modern emissions standards. Hybrid project developers must engineer around obsolete infrastructure rather than greenfield sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equatorial Guinea Power EPC Market |
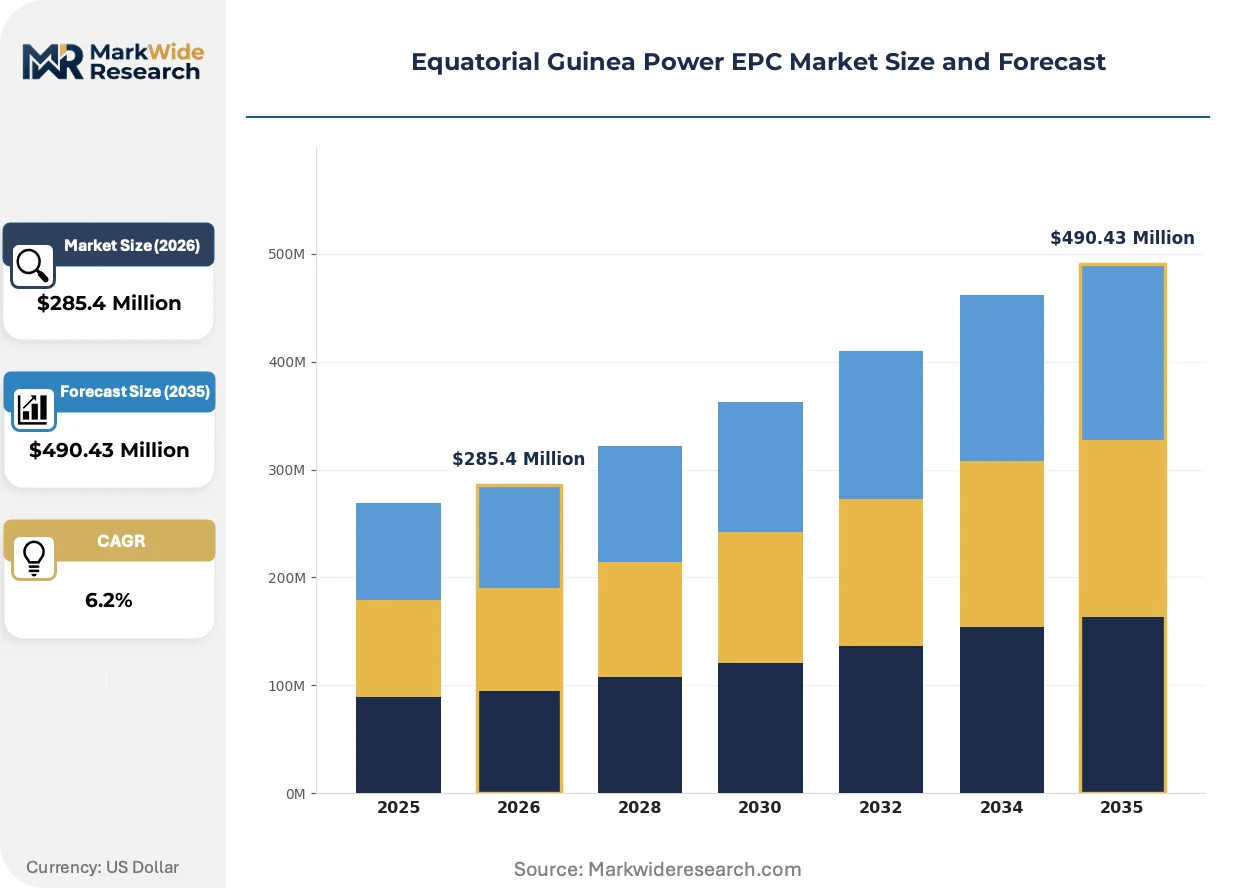
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $490.43 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Construction, Procurement, Commissioning Technology: Solar, Wind, Biomass, Hydropower End User: Government, Private Sector, Utilities, Industrial Users Project Size: Small Scale, Medium Scale, Large Scale, Gigawatt Scale |
| Companies Covered | General Electric Company, SNC-Lavalin Group Inc., Wärtsilä Corporation, Vinci SA, Larsen & Toubro Limited, Power Construction Corporation of China, Bechtel Corporation, Hyundai Engineering & Construction Co., Ltd., Siemens AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equatorial Guinea Power EPC Market Shifts & Advancements
Technology convergence and procurement evolution are restructuring how power infrastructure delivers value in Equatorial Guinea. Three developments dominate competitive positioning.
Containerized solar-plus-storage systems are fragmenting the traditional centralized generation model. Mining and remote industrial offtakers in Rio Muni deploy modular photovoltaic arrays with lithium-ion buffering. This configuration bypasses transmission bottlenecks while complicating national grid planning.
Ministry of Mines and Hydrocarbons licensing protocols now require environmental impact assessments with third-party verification. The regulation extends project development timelines by eight to fourteen months. International EPC firms absorb compliance costs through front-loaded engineering fees that local competitors cannot match.
Industrial offtakers unbundle engineering and construction scopes to retain procurement control. Petrochemical operators near Punta Europa source turbines independently while contracting civil works separately. This disintermediation compresses EPC margins but accelerates equipment delivery schedules for time-sensitive expansions.
Equatorial Guinea Power EPC Market Segmentation
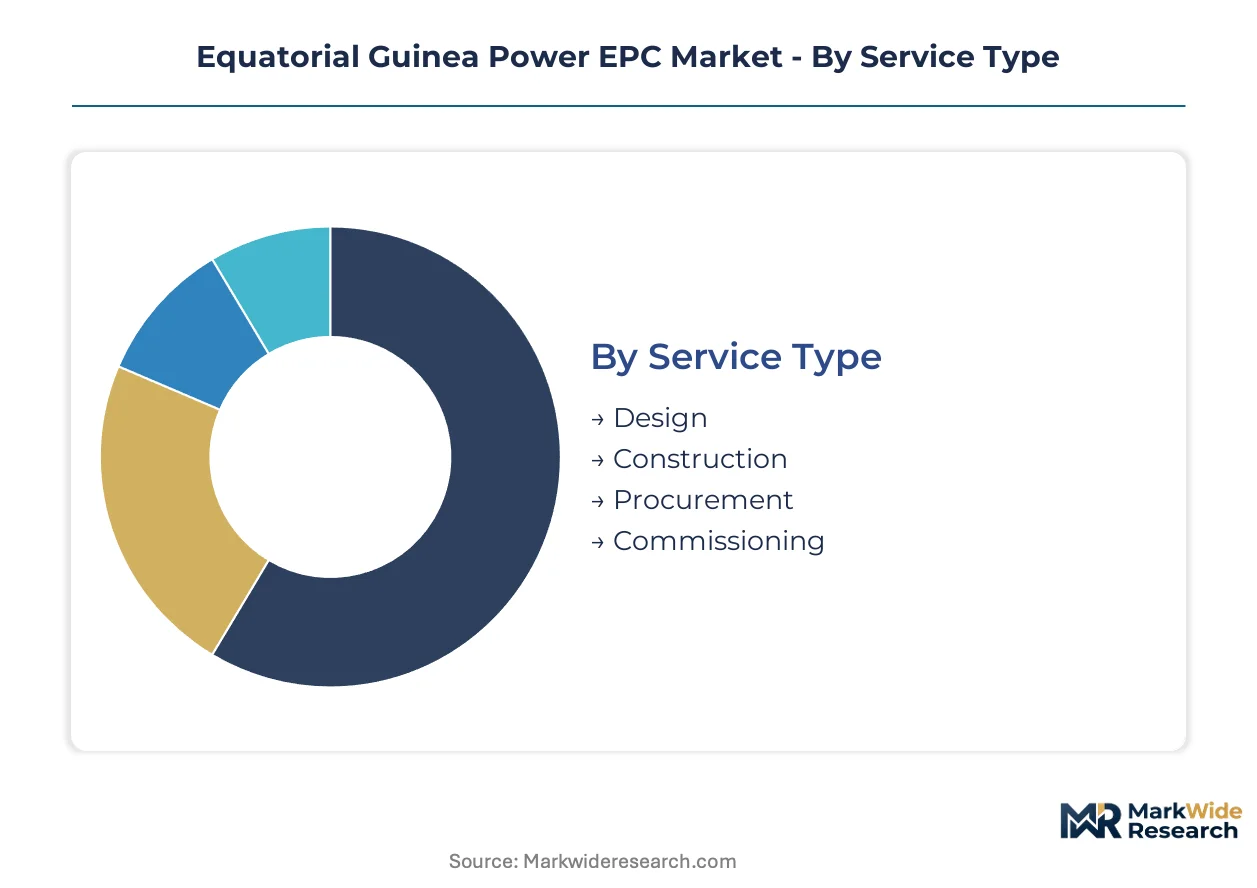
Segmentation in Equatorial Guinea's Power EPC market reveals how contract structures, technology choices, and offtaker profiles concentrate margin pools. Contractors must align capabilities with the specific risk-reward profiles each segment demands.
Service Type:
Commissioning commands the steepest margin premiums as owner-engineer oversight intensifies on hybrid solar-gas projects.
- Design:Front-end engineering packages establish project economics and secure financing. Bioko Island urban load centers and Rio Muni coastal zones drive demand for grid-code compliant substation designs that integrate legacy thermal assets with renewable injection.
- Construction:Civil works, mechanical erection, and electrical interconnection execute the physical asset delivery. Punta Europa petrochemical corridor projects require specialized foundations for aeroderivative turbine installations alongside methanol and LNG processing facilities.
- Procurement:Equipment sourcing accelerates fastest as developers adopt split-package strategies. Chinese-manufactured photovoltaic modules and European switchgear procurement manages currency exposure against euro-denominated contracts.
- Commissioning:Control system integration and performance testing validates heat rate and availability guarantees. Technical advisory roles on hybrid projects command pricing power absent from pure construction scopes.
Construction holds installed capacity. Commissioning is rotating up the share rankings.
Technology:
Solar deployment is climbing the fastest as declining module costs enable hybrid configurations.
- Solar:Photovoltaic arrays anchor the expanding hybrid solar-gas segment. Containerized solar-plus-storage systems fragment centralized generation models for mining and remote industrial offtakers in Rio Muni interior settlements.
- Wind:Onshore wind development remains nascent given resource assessment gaps. Early-stage resource mapping concentrates on mainland Rio Muni coastal exposure zones with limited operational track record.
- Biomass:Agricultural residue and forestry waste conversion occupies marginal commercial position. Feedstock logistics constraints limit scalability beyond isolated rural electrification pilots.
- Hydropower:Geological constraints eliminate greenfield development on Bioko Island. Existing run-of-river assets on Rio Muni represent mature infrastructure with limited expansion potential.
Solar holds installed capacity. Hydropower is rotating up the share rankings.
End User:
Industrial offtakers generate the most predictable revenue streams through captive power arrangements.
- Government:Ministry of Mines and Hydrocarbons tenders drive rural electrification mandates. Grid extension projects into unserved mainland settlements unlock public capital that private developers previously avoided.
- Private Sector:Commercial and residential developments on Bioko Island require distributed generation solutions. Urban load center reliability investments compete with mainland extension priorities for limited capital deployment.
- Utilities:National grid operator procurement focuses on transmission infrastructure and generation capacity additions. Grid-code compliance mandates force simultaneous retirement planning and greenfield development.
- Industrial Users:Petrochemical operators near Punta Europa expand methanol and LNG processing capacity with dedicated generation assets. Captive power needs guarantee availability requirements that utility-scale projects cannot match.
Industrial Users hold installed capacity. Government is rotating up the share rankings.
Project Size:
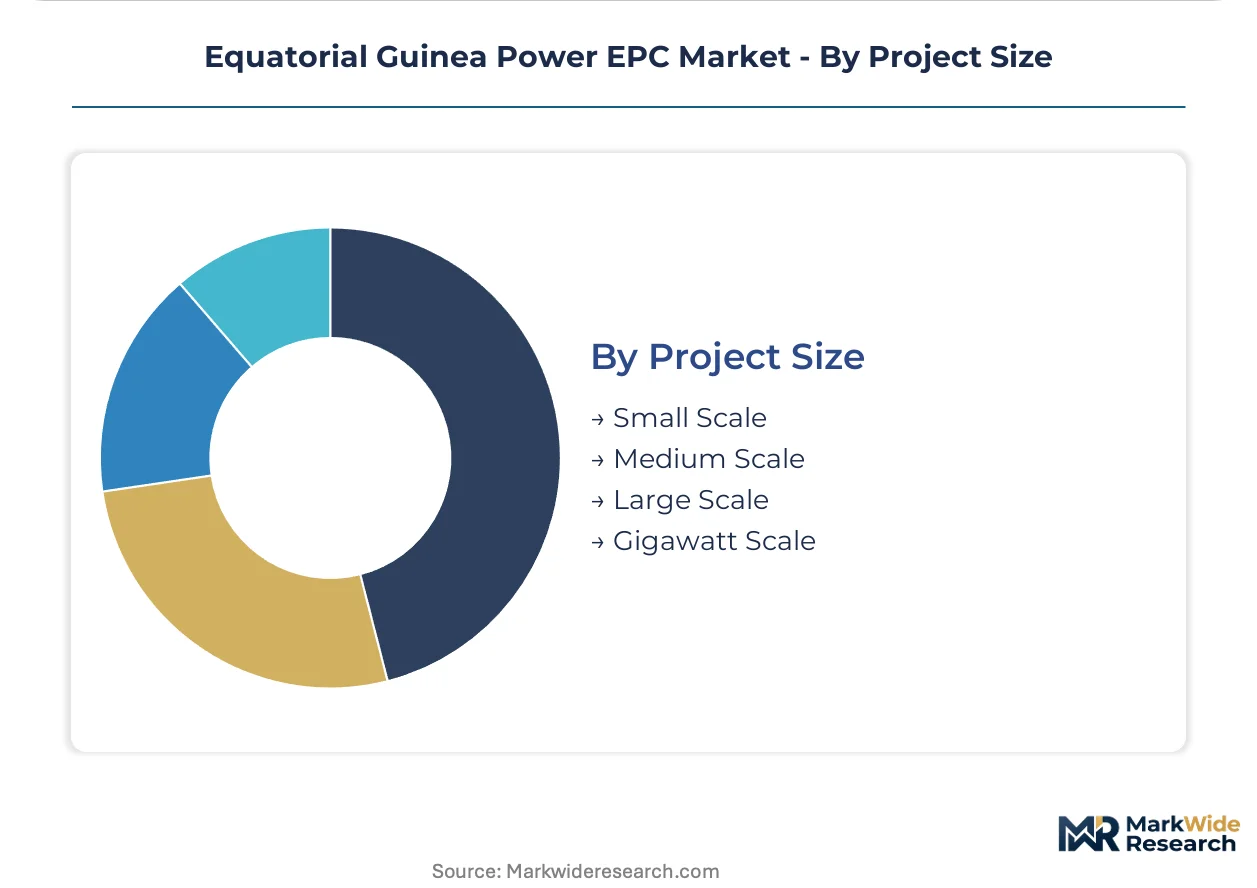
Large-scale projects concentrate EPC contractor attention through lump-sum turnkey discipline.
- Small Scale:Containerized solar-plus-storage systems serve remote mining and industrial offtakers. Modular deployment bypasses transmission bottlenecks while complicating national grid planning.
- Medium Scale:Distributed generation and rural electrification clusters occupy this tier. Bata regional office anchoring strategies target sequential tender waves in underpenetrated coastal zones.
- Large Scale:Grid-connected generation and transmission infrastructure dominates contractor portfolios. Risk-transfer mechanics and performance guarantees attract international EPC firms with balance sheet capacity.
- Gigawatt Scale:No projects currently approach this threshold in Equatorial Guinea's market. Future LNG-to-power integration or regional interconnection could eventually create gigawatt-scale opportunities.
Large Scale holds installed capacity. Small Scale is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equatorial Guinea exports LNG and methanol to European and Asian buyers, channeling hydrocarbon revenues into domestic power infrastructure through Ministry of Mines and Hydrocarbons procurement mandates.
Bioko Island
Urban load centers around Malabo drive reliability investments for commercial and residential consumers. The Ministry of Mines and Hydrocarbons prioritizes grid stability standards that force hybrid solar-gas integration. Punta Europa petrochemical facilities anchor captive power demand with guaranteed availability requirements.
Rio Muni Mainland Coastal Zone
Bata serves as the logistics hub for grid extension tenders into underpenetrated coastal settlements. Rural electrification mandates unlock public capital for transmission infrastructure previously avoided by private developers. Methanol and LNG processing corridors concentrate industrial offtaker demand.
Rio Muni Interior Settlements
Remote mining and agricultural operations deploy containerized solar-plus-storage systems bypassing transmission bottlenecks. The Ministry of Mines and Hydrocarbons licensing protocols require environmental assessments extending development timelines. Modular photovoltaic configurations complicate national grid planning.
Annobón Province
Island isolation necessitates distributed generation solutions independent of mainland grid connections. Small-scale diesel and solar hybrid systems serve limited population centers. Maritime logistics constraints inflate equipment delivery costs for EPC contractors.
Continental Border Regions
Cross-border electricity trade potential with Cameroon and Gabon remains undeveloped due to transmission infrastructure gaps. The country's national standards body applies electrical safety protocols filtering market access. Future regional interconnection could eventually unlock gigawatt-scale opportunities.
Equatorial Guinea Power EPC Market Competitive Landscape
Listed engineering conglomerates compete with private specialists across risk-transfer mechanics and local content compliance. The market structures around three tiers: international lump-sum turnkey contractors with balance sheet capacity, flexible technology providers specializing in grid stability solutions, and regional partnerships formed to satisfy domestic workforce quotas. Consolidation pressures intensify as owner-engineer oversight tightens on hybrid projects. Dominant competitive moves include strategic partnerships with domestic firms and technology licensing for aeroderivative and engine-based generation.
Within the international turnkey tier, General Electric Company and Bechtel Corporation exemplify risk-transfer discipline that attracts petrochemical offtakers. Wärtsilä Corporation occupies a distinct position among flexible engine specialists enabling higher renewable penetration without full storage investment. These three anchors represent the capability spectrum from gas-to-power integration through grid stability management to lump-sum construction execution.
| Leading Market Players |
|---|
| General Electric Company |
| SNC-Lavalin Group Inc. |
| Wärtsilä Corporation |
| Vinci SA |
| Larsen & Toubro Limited |
| Power Construction Corporation of China |
| Bechtel Corporation |
| Hyundai Engineering & Construction Co., Ltd. |
| Siemens AG |
| Others |
Supply & Pricing Matrix
Equipment scale economies at Chinese photovoltaic module manufacturers compress price floors for EPC contractors bidding hybrid solar-gas projects in Equatorial Guinea. The Ministry of Mines and Hydrocarbons procurement mandates concentrate demand around lump-sum turnkey structures that amplify margin pressure on smaller domestic partnerships lacking balance sheet capacity.
Pricing Analysis
Legacy heavy fuel oil generation, aeroderivative gas turbines, and containerized solar-plus-storage systems occupy distinct pricing tiers in contractor proposals. Three-tier pricing structure across premium commissioning services, standard construction scopes, and economy-grade civil works reflects certification depth and performance guarantee stringency. Cost compression in standard construction tiers stems from Chinese equipment sourcing and Bata-based regional office competition. Industrial offtakers near Punta Europa exhibit lowest price sensitivity due to captive power availability requirements, while government rural electrification tenders face acute budget constraints.
Supply Chain Analysis
Strait of Malacca transit routes for liquefied natural gas feedstock underpin generation fuel security for Bioko Island thermal assets. Chinese photovoltaic module manufacturing, European switchgear production, and South Korean battery cell fabrication anchor equipment sourcing. EPC contractors draw from euro-denominated European switchgear contracts and yuan-denominated Chinese module purchases, creating currency mismatch exposure. Single-source vulnerability concentrates in aeroderivative turbine supply where General Electric holds dominant position. Distribution runs through Bata port logistics for Rio Muni mainland projects and Malabo maritime terminals for Bioko Island delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equatorial Guinea's power EPC market sits in early-cycle expansion as rural electrification mandates penetrate mainland settlements previously beyond grid reach. Hybrid solar-gas technology adoption accelerates contractor capability requirements faster than domestic labor pools can supply.
For Market Incumbents: Secure commissioning service premiums through specialized control system expertise that foreign entrants cannot rapidly replicate. Deepen relationships with the Ministry of Mines and Hydrocarbons to anchor sequential rural electrification tender awards. Vertical integration into European switchgear procurement channels mitigates currency exposure threatening margin stability on split-package strategies.
For New Entrants and Emerging Players: Differentiate on containerized solar-plus-storage deployment speed for remote Rio Muni mining offtakers bypassing transmission bottlenecks. Target Annobón Province distributed generation gap where maritime logistics constraints exclude established Bata-based contractors. Partner with domestic workforce training providers to satisfy local content quotas blocking pure foreign market access.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among commissioning-specialist firms with hybrid project track records and Ministry certification. Long-term viability centers on firms capturing mainland grid extension waves before infrastructure saturation. Acquisition focus should target regional partnerships with established Bata logistics presence. Monitor Punta Europa petrochemical expansion announcements as capacity addition inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Content Partnership Formation | Domestic workforce quotas from the Ministry of Mines and Hydrocarbons filter public tender access. |
| Hybrid Technology Certification Investment | Grid-code compliance mandates from the national standards body elevate technical advisory pricing power. |
| Bata Regional Office Establishment | Mainland Rio Muni coastal zone logistics anchoring captures sequential rural electrification tender flows. |
| Split-Package Procurement Discipline | Chinese module and European switchgear sourcing manages CFA franc volatility against euro contracts. |
| Commissioning Capability Buildout | Owner-engineer oversight tightening on hybrid projects concentrates margin in specialized technical roles. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators; and secondary validation against EIA data, IEA reports, FERC-equivalent regulatory filings, and project development databases. Bottom-up capacity installation tracking and top-down Ministry of Mines and Hydrocarbons procurement pipeline assessment enabled triangulation.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning fuel source, generation capacity tier, project scale, and regional grid type. CAGRs derived from equipment cost trajectory analysis and public capital deployment patterns. Forecast inputs incorporated photovoltaic module price decline curves and Punta Europa industrial load growth projections.
Material uncertainties — regulatory enforcement intensity on local content quotas, CFA franc volatility magnitude, and Punta Europa petrochemical expansion timing — sit outside the modeled envelope. Forecasts reflect assumptions about Ministry procurement continuity and equipment supply chain stability. Practitioners should keep alternative scenarios live as hydrocarbon revenue allocation priorities and regional interconnection negotiations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Gas Turbine Compressor Market
Power Equipment
Global Power Supply Market
Power Equipment
Turbine Control Systems Market
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
Wind Turbine Equipment Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
Portable Power Station Market
Power Equipment
Japan Power EPC Market
Power Equipment
Process Air Heater Market
Power Equipment
United States Power Rental Market
Power Equipment
Europe Power Rental Market
Power Equipment
Global Transformerless UPS Market
Power Equipment
Power Plant Lightning Protection Services Market
Power Equipment
Global Power System Simulator Market
Power Equipment
Industrial Gas Turbine Ignition System Market
Power Equipment
Thailand Power EPC Market