
 Greece Renewable Energy Market | 2026-2036
Greece Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Greece Renewable Energy Market Foresight
The EU Green Deal is restructuring cost-of-entry calculus for Greek renewable developers, tightening emissions benchmarks and accelerating permitting timelines for clean energy assets. PPC Renewables leverages its legacy grid infrastructure to dominate onshore wind pipelines across mainland Greece. Terna Energy anchors its growth strategy in utility-scale solar plus storage configurations. Enel Green Power competes through proprietary tracking systems that optimize output in the Aegean's high-insolation zones.
Greece renewable energy encompasses electricity and heat production from solar photovoltaics, onshore and offshore wind turbines, biomass combustion systems, and run-of-river hydropower installations with capacities ranging from residential rooftop arrays to gigawatt-scale offshore wind farms. Solar power leads capacity additions as auction prices undercut conventional generation, while offshore wind represents the fastest-growing installation type as seabed leases advance in the Aegean and Ionian Seas. Hydropower occupies a mature position providing baseload flexibility and grid balancing services during seasonal demand peaks.
RAE, the Greek energy regulator, enforces competitive bidding frameworks that cap subsidy exposure and force merchant-price exposure on new projects. EU Green Deal targets and the national Recovery and Resilience Facility channel capital toward green hydrogen and storage hybrids, while EMA standards govern equipment certification for grid interconnection. Stakeholders must monitor auction calendar density and interconnection queue congestion as the decisive variables for project returns.
Market Dynamics
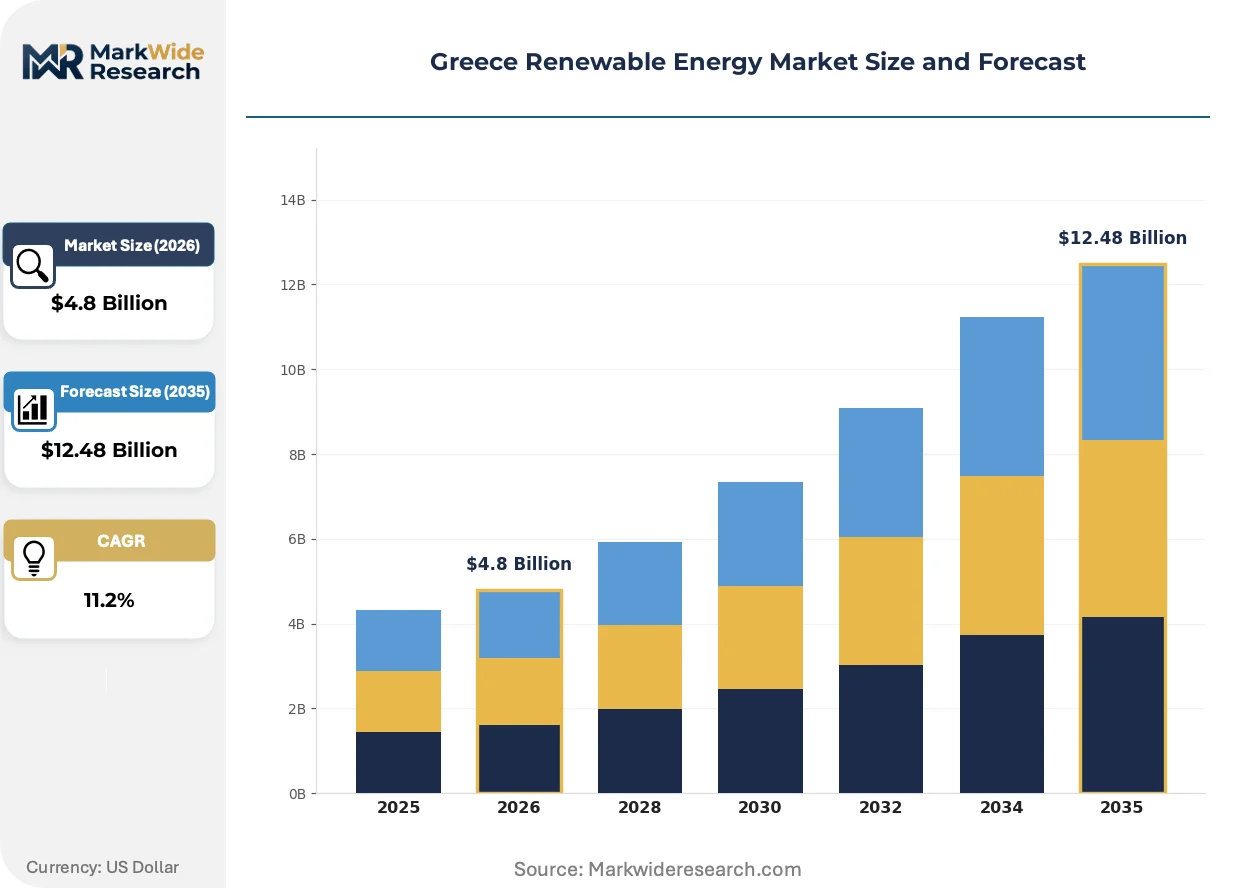
The Greek renewable energy sector is undergoing a fundamental restructuring as the EU Green Deal tightens emissions benchmarks and accelerates permitting timelines, forcing developers to recalibrate project economics around merchant-price exposure and storage integration requirements.
Growth Catalysts
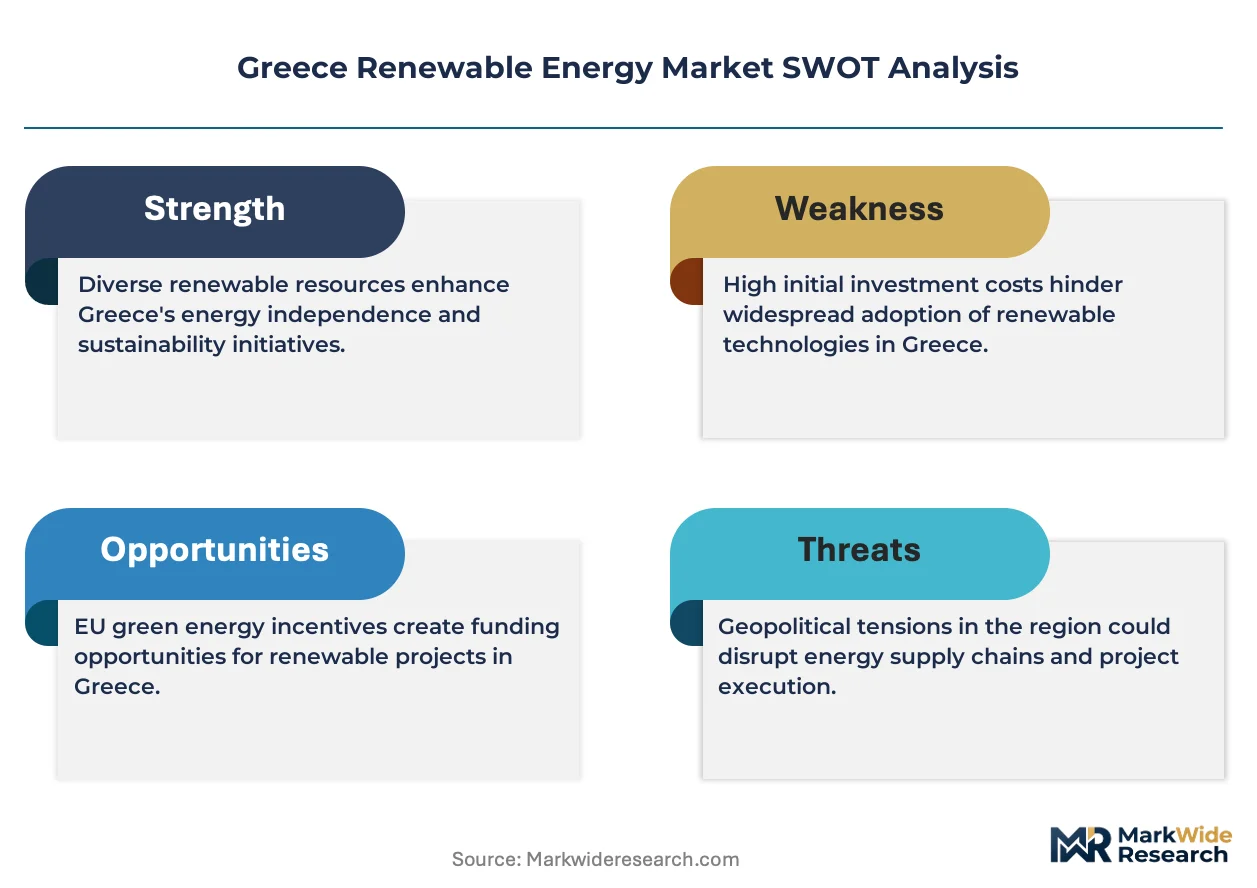
- EU Green Deal benchmarks:The EU Green Deal mandates stricter emissions standards that favor clean energy assets, compressing approval timelines for solar and wind installations across the Peloponnese and Crete.
- Island grid upgrades:Transmission infrastructure investments in Aegean islands unlock stranded renewable capacity, enabling gigawatt-scale project development in previously constrained zones.
- Green hydrogen pilots:The national Recovery and Resilience Facility channels capital toward hydrogen-storage hybrids, reshaping revenue models for utility-scale developers.
Market Restraints
- RAE competitive bidding caps:The Greek energy regulator's auction frameworks limit subsidy exposure, forcing developers to absorb merchant-price volatility without guaranteed offtake floors.
- Interconnection queue congestion:Grid connection backlogs in high-insolation zones delay project commissioning and compress internal rates of return.
- Seabed lease complexity:Offshore wind development in the Aegean and Ionian Seas faces prolonged maritime spatial planning negotiations with coastal municipalities.
Strategic Opportunities
- Crete untapped capacity:The island's superior solar irradiation and pending grid interconnection create first-mover advantages for utility-scale plus-storage configurations.
- Biomass combustion integration:Agricultural residue-to-energy systems offer baseload complementarity to intermittent solar and wind, qualifying for dedicated auction streams.
- EMA certification alignment:Streamlined equipment standards for grid interconnection reduce compliance costs for international component suppliers entering the Greek market.
Industry Challenges
- Specialized technician scarcity:Grid-scale battery integration and floating offshore installation require skills absent from Greece's conventional power plant workforce.
- Legacy lignite transition:Public Power Corporation's coal asset retirement creates stranded worker pools misaligned with renewable construction and O&M demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greece Renewable Energy Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar Power, Wind Energy, Biomass, Hydropower Application: Electricity Generation, Heating, Transportation, Off-Grid Solutions End User: Residential, Commercial, Industrial, Government Installation Type: Onshore, Offshore, Rooftop, Ground-Mounted |
| Companies Covered | PPC Renewables, TotalEnergies, EDF, Enel Green Power, Terna Energy, RWE Renewables Hellas, C. Rokas, Lightsource BP, SSE Renewables, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greece Renewable Energy Market Shifts & Advancements
Technology convergence and regulatory compression are actively restructuring how Greek developers design, finance, and operate renewable assets, with digitization and hybridization emerging as the dominant vectors of competitive differentiation.
Distributed solar-plus-storage systems are decentralizing electricity generation across the Greek archipelago, allowing island municipalities and industrial facilities to reduce transmission dependence. Hotel chains and agricultural processors in Crete and the Cyclades are deploying these configurations at accelerating pace. This decentralization is compressing centralized utility business models while creating new revenue streams for behind-the-meter energy management services.
The EU Green Deal's tightened emissions benchmarks are accelerating permitting pathways for clean energy projects while eliminating grandfathering protections for fossil assets. Greek developers now face compressed approval timelines but must demonstrate compliance with stricter environmental impact thresholds. Utility-scale solar pipelines in mainland Greece are responding by front-loading ecological assessments to secure grid connection priority.
Corporate offtake agreements are displacing traditional utility PPAs as the dominant procurement mechanism for new renewable capacity. Industrial consumers in aluminum, cement, and data center verticals are negotiating direct bilateral contracts with project developers. This pattern is most visible in the Peloponnese, where energy-intensive manufacturing clusters seek price certainty and green credentialing independent of incumbent utility structures.
Greece Renewable Energy Market Segmentation
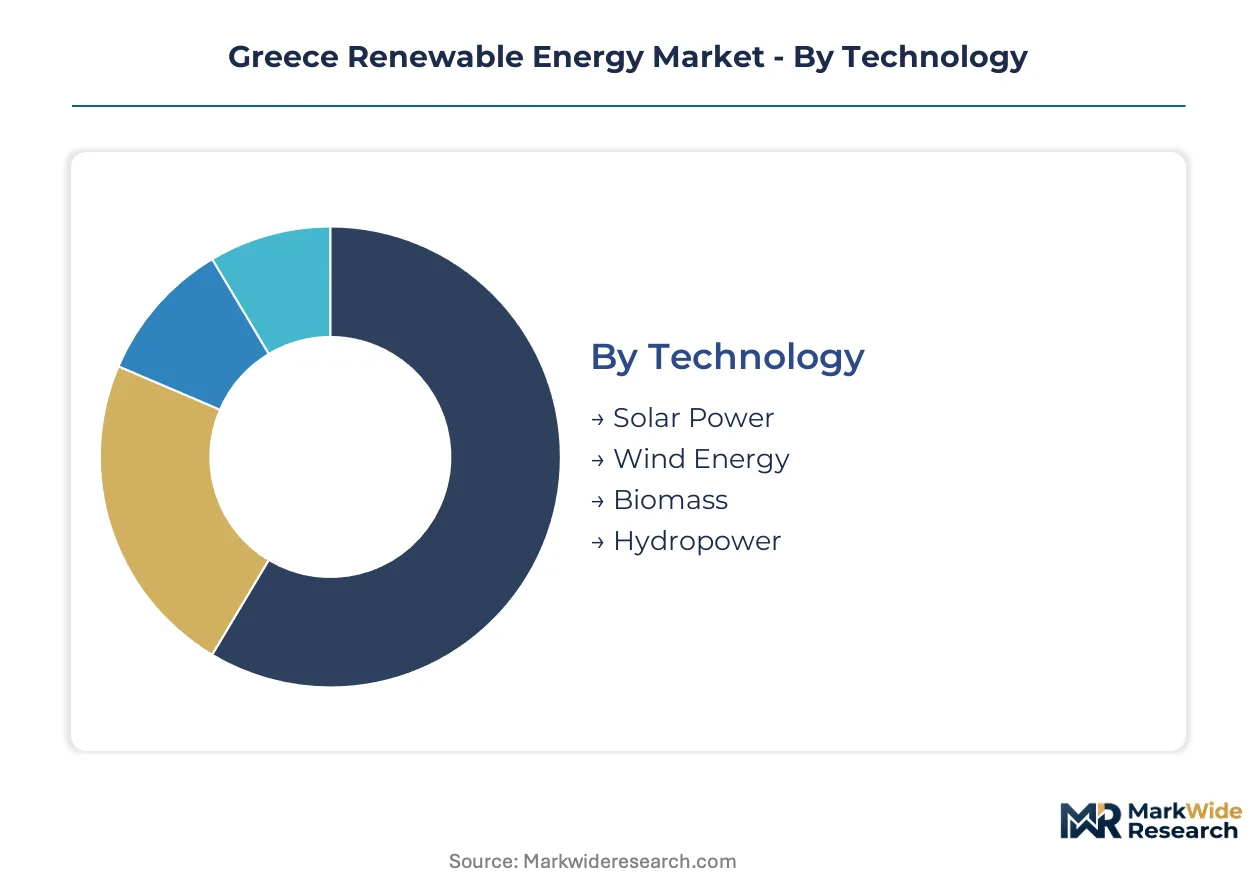
RAE auction frameworks and EU Green Deal compliance requirements create divergent certification burdens across technology and installation categories. Project developers must align segment selection with specific equipment standards and grid interconnection protocols enforced by Greek regulators.
Technology:
EMA certification and EU Green Deal emissions benchmarks impose distinct compliance timelines across generation technologies, with solar and wind facing accelerated permitting pathways compared to biomass and mature hydropower assets.
- Solar Power:Photovoltaic arrays convert sunlight through monocrystalline and thin-film panels, with tracking systems optimizing Aegean insolation. Utility-scale projects in the Peloponnese and Crete dominate procurement pipelines under competitive auction rules. EMA grid interconnection standards govern inverter specifications and voltage regulation for all capacity classes.
- Wind Energy:Onshore turbines harness mainland corridor flows while offshore installations target Aegean and Ionian seabed leases. Maritime spatial planning negotiations with coastal municipalities constrain project timelines. The technology requires dual permitting through RAE and national environmental authorities.
- Biomass:Agricultural residue combustion systems provide baseload complementarity to intermittent renewable generation.
- Hydropower:Run-of-river installations deliver seasonal flexibility and grid balancing services under mature regulatory frameworks.
Solar Power sits at the top of the volume ranking, with Wind Energy climbing the fastest.
Application:
End-use configuration determines subsidy eligibility and merchant-price exposure under RAE competitive bidding frameworks, with electricity generation capturing the bulk of Recovery and Resilience Facility capital allocation.
- Electricity Generation:Grid-connected solar and wind farms supply wholesale markets and bilateral corporate offtake agreements. Auction price caps force developers to absorb merchant volatility without guaranteed floor prices. Industrial consumers in aluminum and cement verticals negotiate direct procurement contracts in the Peloponnese.
- Heating:District systems and industrial process heat applications deploy biomass and solar thermal collectors. Agricultural processors in Crete accelerate deployment to reduce fossil dependence.
- Transportation:Green hydrogen pilots channel EU Green Deal funding toward fuel-cell mobility and port electrification.
- Off-Grid Solutions:Battery-backed solar systems serve island municipalities and remote industrial facilities across the Cyclades.
Electricity Generation commands the largest revenue pool, though Heating applications expand most quickly behind agricultural demand.
End User:
Customer scale dictates project finance structures and offtake security, with industrial consumers leveraging balance-sheet strength to bypass utility intermediaries.
- Industrial:Energy-intensive manufacturing clusters in cement, aluminum, and data center verticals procure renewable capacity through direct bilateral contracts. Price certainty and green credentialing drive procurement independent of incumbent utility structures. Corporate PPAs displace traditional utility agreements as the dominant mechanism.
- Commercial:Hotel chains and agricultural processors deploy distributed solar-plus-storage to reduce transmission dependence.
- Residential:Rooftop arrays qualify for net metering under RAE residential tariff structures.
- Government:Public sector procurement supports municipal building retrofits and island grid infrastructure.
Industrial end users anchor volume concentration, with Commercial installations gaining share fastest behind hospitality sector expansion.
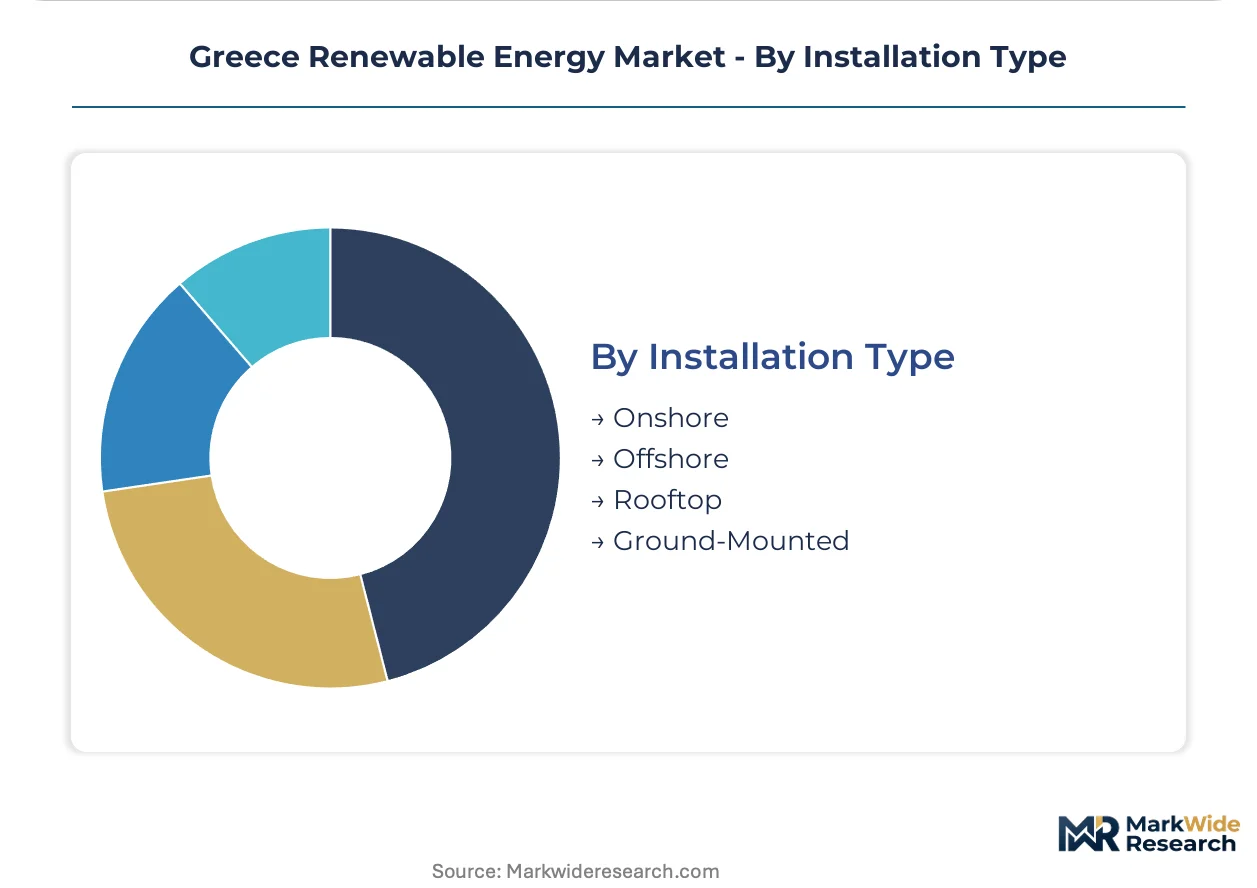
Installation Type:
Physical configuration determines land-use permitting complexity and grid interconnection queue priority, with offshore projects facing prolonged maritime negotiations.
- Onshore:Utility-scale wind and solar farms occupy mainland corridors across the Peloponnese and northern Greece. PPC Renewables leverages legacy grid infrastructure to dominate pipeline development. Land-use permits from regional authorities compress development timelines compared to offshore alternatives.
- Offshore:Floating and fixed-bottom wind installations target Aegean and Ionian seabed zones. Prolonged maritime spatial planning with coastal municipalities creates regulatory bottlenecks. The installation type carries the highest capital intensity but unlocks gigawatt-scale capacity.
- Rooftop:Distributed solar arrays serve residential and commercial behind-the-meter demand.
- Ground-Mounted:Utility-scale solar configurations optimize land availability in high-insolation zones.
Onshore installations lead cumulative capacity, while Offshore projects pursue the steepest expansion trajectory pending lease resolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled technicians and project engineers cluster around Athens and Thessaloniki, supplying deployment capacity for utility-scale solar and offshore wind installations across the Greek archipelago.
Peloponnese
Industrial aluminum and cement manufacturing drives corporate PPA demand for renewable electricity. The national Recovery and Resilience Facility channels capital toward grid modernization in this southern peninsula. Megalopolis and Patras anchor project development clusters where PPC Renewables leverages transmission infrastructure.
Crete
Superior solar irradiation and pending grid interconnection attract utility-scale plus-storage configurations. EU Green Deal funding accelerates ecological assessments for clean energy assets. Heraklion and Chania host hospitality sector deployments of distributed solar-plus-storage systems reducing transmission dependence.
Cyclades
Island municipalities and hotel chains deploy battery-backed solar to isolate from mainland grid constraints. Maritime spatial planning negotiations with coastal authorities shape offshore wind lease timelines. Mykonos and Santorini concentrate commercial behind-the-meter installations.
Thessaly
Agricultural residue-to-energy systems provide baseload complementarity to intermittent generation. RAE competitive bidding frameworks cap subsidy exposure for biomass projects. Larissa anchors processing facility clusters qualifying for dedicated auction streams.
Epirus
Run-of-river hydropower delivers seasonal flexibility and grid balancing under mature regulatory frameworks. EMA certification standards govern equipment specifications for interconnection. Ioannina and the Pindus mountain corridors concentrate small-scale hydro installations.
Greece Renewable Energy Market Competitive Landscape
The competitive structure tilts toward utility-backed developers with legacy grid access. Incumbent power producers and international energy majors divide procurement pipelines across auction frameworks. Strategic archetypes include state-affiliated utilities leveraging transmission infrastructure, European energy groups deploying capital at scale, and specialized renewable developers optimizing tracking and storage configurations. Dominant competitive moves encompass seabed lease accumulation for offshore wind and corporate PPA origination bypassing utility intermediaries.
Among Greece-based developers, PPC Renewables and Terna Energy exemplify the infrastructure-leveraged archetype, while Enel Green Power represents international energy group participation in Aegean solar deployment.
| Leading Market Players |
|---|
| PPC Renewables |
| TotalEnergies |
| EDF |
| Enel Green Power |
| Terna Energy |
| RWE Renewables Hellas |
| C. Rokas |
| Lightsource BP |
| SSE Renewables |
| Others |
Supply & Pricing Matrix
EU Green Deal emissions benchmarks gate qualified supply access and premium-tier pricing for Greek renewable developers, compressing approval timelines for certified equipment while excluding non-compliant vendors from auction participation. RAE competitive bidding frameworks amplify this filtering effect, rewarding EMA-certified component suppliers with grid interconnection priority while forcing merchant-price exposure on projects using uncertified hardware.
Pricing Analysis
Project-based long-term offtake contracts dominate Greek renewable procurement, with bundled engineering-procurement-construction services commanding premium pricing over unbundled component supply. Price differentiation rests on EMA certification tier and grid connection queue priority, with certified tracking systems and battery-integrated configurations capturing margin premiums. Cost compression in standard-tier solar modules is intensifying because Chinese manufacturers are flooding Mediterranean markets with uncertified inventory. Industrial offtakers in aluminum and cement verticals show least price sensitivity due to corporate sustainability mandates, while residential rooftop installers face acute budget constraints under net metering caps.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale developer demand for gigawatt-scale solar and offshore wind components across the Aegean. Manufacturing concentration in China, Germany, and Denmark feeds inverter, turbine, and floating platform supply to Greek EPC contractors. Polysilicon, rare-earth magnets, and high-voltage cable insulation constitute critical input dependencies. Single-source vulnerability in Chinese polysilicon refining creates exposure to export license disruptions. Distribution runs through Athens-based logistics hubs serving Peloponnese and Crete project clusters, with Thessaloniki anchoring northern Greece supply corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Greek renewable energy offers margin expansion through storage integration premiums and green hydrogen certification tiers, as EU Green Deal funding compresses capital costs for compliant project configurations. Merchant-price exposure risk is offset by rising corporate PPA willingness-to-pay for 24/7 clean power guarantees.
For Market Incumbents: Deepen backward integration into battery storage assembly to capture hybrid project premiums and defend against international IPPs with captive supply chains. PPC Renewables should accelerate Crete grid interconnection lock-up before competitors secure queue positions. Terna Energy must front-load ecological assessments to maintain permitting velocity under compressed EU Green Deal timelines.
For New Entrants and Emerging Players: The premium-to-economy price gap in floating offshore wind creates entry space for specialized marine EPC firms with Aegean seabed mapping capabilities. Target Cyclades island municipalities with distributed solar-plus-storage configurations bypassing mainland grid dependence. Originate bilateral corporate PPAs with hospitality chains seeking energy independence as the fastest penetration vector.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale solar developers with grid connection queue positions because RAE auction density is compressing standalone project returns below cost-of-capital thresholds. Acquisition targets should show 50+ MW pipelines in Peloponnese or Crete with pending environmental approvals. Watch RAE interconnection queue freeze announcements as the inflection signal for distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Utility-scale solar farms in Crete leverage superior insolation to undercut mainland generation costs. |
| Power Purchase Agreement | Corporate offtake contracts with aluminum smelters displace traditional utility procurement structures. |
| Technology Licensing | Floating offshore wind platforms unlock Aegean seabed zones previously inaccessible to fixed-bottom designs. |
| Vertical Integration into Storage | Battery manufacturing control secures supply priority for Greek developers facing EU-wide cell shortages. |
| Green Certification Program | EMA compliance accelerates grid interconnection timelines under RAE competitive bidding frameworks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with IPP project developers, EPC contractors, RAE regulatory officers, and grid operators with secondary validation against IEA renewable deployment databases, EU Green Deal implementation reports, and Greek customs equipment import records. Bottom-up project pipeline aggregation and top-down macroeconomic scenario modeling provided cross-checking triangulation.
Segment-weighting approaches distributed capacity and revenue forecasts across technology, application, end user, and installation type dimensions, with regional grid interconnection status and auction calendar density serving as Greece-specific adjustment factors. CAGRs were derived from installed base growth trajectories and merchant price evolution assumptions across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for green hydrogen electrolyzer scaling would alter the outlook for storage-hybrid project economics. Forecasts reflect base-case assumptions regarding RAE auction frequency and EU Green Deal funding continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
US Solar Tracker Market
Solar Power Systems
Denmark Solar Energy Market
Solar Power Systems
Residential Solar Inverter Market
Solar Power Systems
Solar Tracker Installation Market
Solar Power Systems
Vietnam Solar Energy Market
Solar Power Systems
Global Solar Panel Tracking Mount Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
GCC Solar Water Heater Market
Solar Power Systems
Flat Plate Solar Collector Market
Solar Power Systems
Europe Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Perovskite Solar Cell Market
Solar Power Systems
Solar Rooftop Sales Market
Solar Power Systems
South America Solar PV Inverters Market
Solar Power Systems
Austria Solar Energy Market
Solar Power Systems
Europe Solar Microinverter Market