
 Global Ultra Efficient Solar Power Market | 2026-2036
Global Ultra Efficient Solar Power Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ultra Efficient Solar Power Market Analysis
Chinese polysilicon and wafer producers is recalibrating capacity allocations toward n-type substrates as conversion efficiency thresholds tighten. JinkoSolar leverages vertically integrated ingot-to-module operations to sustain cost leadership in high-efficiency monocrystalline segments. LONGi anchors its competitive position through proprietary silicon wafer scaling that dominates the 182mm and 210mm formats. First Solar competes through differentiated thin-film cadmium telluride technology optimized for utility-scale desert installations.
Ultra efficient solar power denotes photovoltaic and concentrated solar systems achieving conversion efficiencies exceeding 22% in commercial modules, utilizing passivated emitter rear contact (PERC), tunnel oxide passivated contact (TOPCon), or heterojunction architectures to maximize photon capture and electron transport. These systems serve grid-connected and distributed generation applications where land constraints, balance-of-system costs, or irradiance variability demand maximum output per unit area. Bifacial modules command expanding share as albedo-dependent gains reshape utility project returns, while concentrated solar power retains structural relevance in high-direct-normal-irradiance zones requiring thermal storage integration. Nanostructured cell architectures represent the fastest-growing technology segment as laboratory-to-fab transfer accelerates, though photovoltaic systems occupy the dominant installed base across residential, commercial, and utility end users.
The EPA enforces domestic content and carbon intensity standards under the Inflation Reduction Act that condition tax credit eligibility on module sourcing and manufacturing location. EMA and REACH frameworks in Europe mandate extended producer responsibility and restricted substance controls that filter module designs entering EU markets. India's BIS certification and PLI scheme for solar PV manufacturing impose efficiency floors and local value-add requirements that reshape import dependency patterns. Stakeholders must monitor evolving efficiency certification protocols and subsidy eligibility criteria as jurisdictional requirements diverge and supply chain qualification costs escalate.
Market Dynamics
The transition from p-type to n-type cell architectures is compressing incumbent manufacturing assets and forcing module producers to retool deposition and diffusion lines. This technology inflection concentrates capital requirements among vertically integrated producers with captive wafer supply.
Growth Catalysts
- EU Green Deal carbon footprint disclosure:Mandatory module-level carbon accounting under the revised Renewable Energy Directive is filtering out high-emission imports and rewarding low-carbon manufacturing pathways.
- Utility-scale procurement in India:Grid parity achievement in Rajasthan and Gujarat is accelerating tenders specifying bifacial heterojunction modules with 22%+ efficiency floors.
- Albedo-dependent project economics:Desert and snow-field installations across the southwestern United States are capturing 8-15% rear-side gains that reshape levelized cost calculations.
Market Restraints
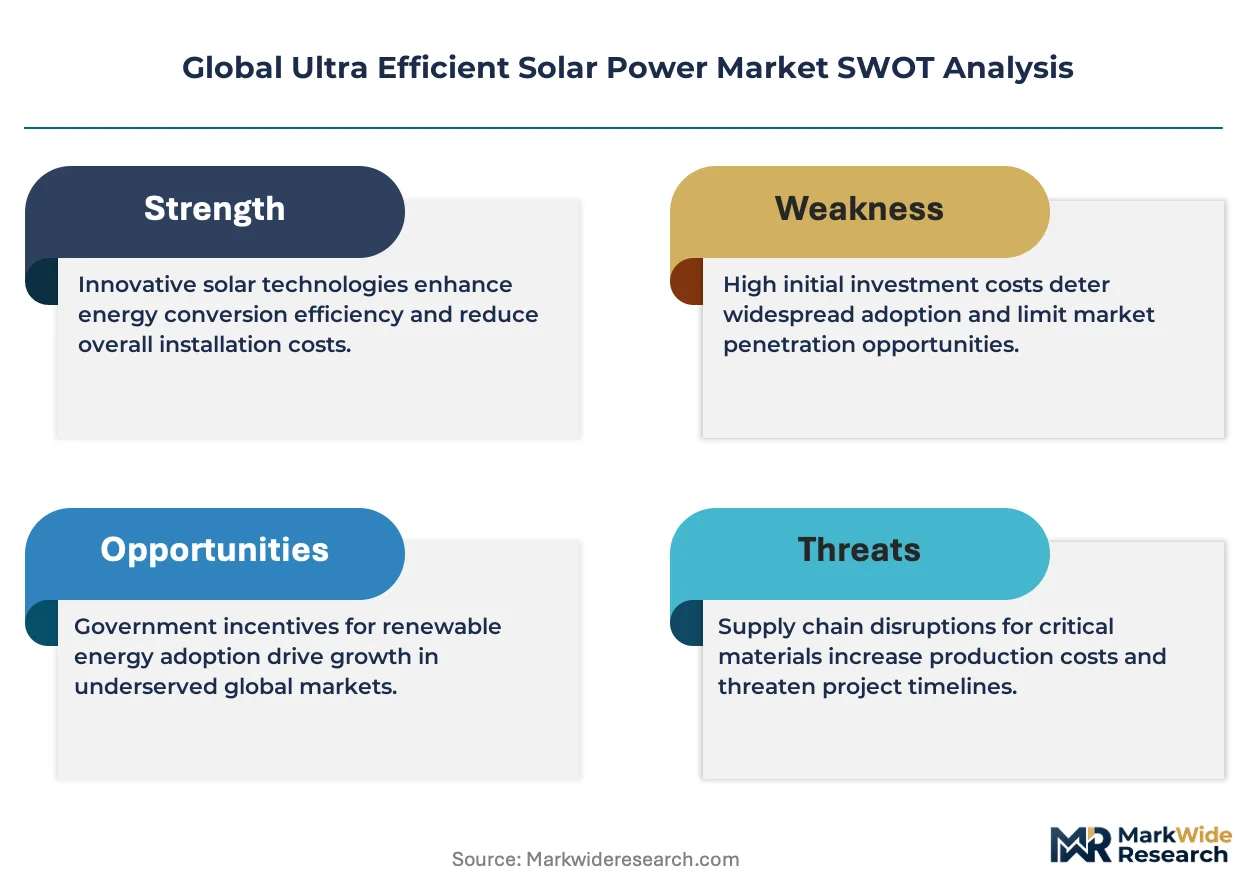
- Polysilicon supply concentration:Xinjiang and Inner Mongolia smelters account for the majority of metallurgical-grade silicon feedstock, creating geographic vulnerability to trade measures.
- Silver paste cost volatility:Heterojunction and TOPCon cells require 2-3x silver loading versus PERC, exposing margins to precious metal price swings.
- Interconnection bottleneck:Transmission queue delays in ERCOT and CAISO zones are deferring revenue recognition for completed utility-scale projects.
Strategic Opportunities
- Agrivoltaic deployment in Japan:METI feed-in tariff revisions for dual-use land applications are opening acreage previously excluded from solar development.
- Building-integrated photovoltaics:Architectural glass and facade segments in Germany and the Netherlands are demanding customized module form factors with aesthetic coatings.
- Green hydrogen offtake contracts:Electrolyzer developers in Spain and Australia are signing 15-20 year power purchase agreements that favor high-capacity-factor solar configurations.
Industry Challenges
- Cell metallization precision:Fine-line screen printing and copper plating yield rates remain below mass-production thresholds for sub-20-micron finger widths.
- Module recycling infrastructure:Extended producer responsibility frameworks in the European Union lack scaled processing capacity for end-of-life silicon and glass recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ultra Efficient Solar Power Market |
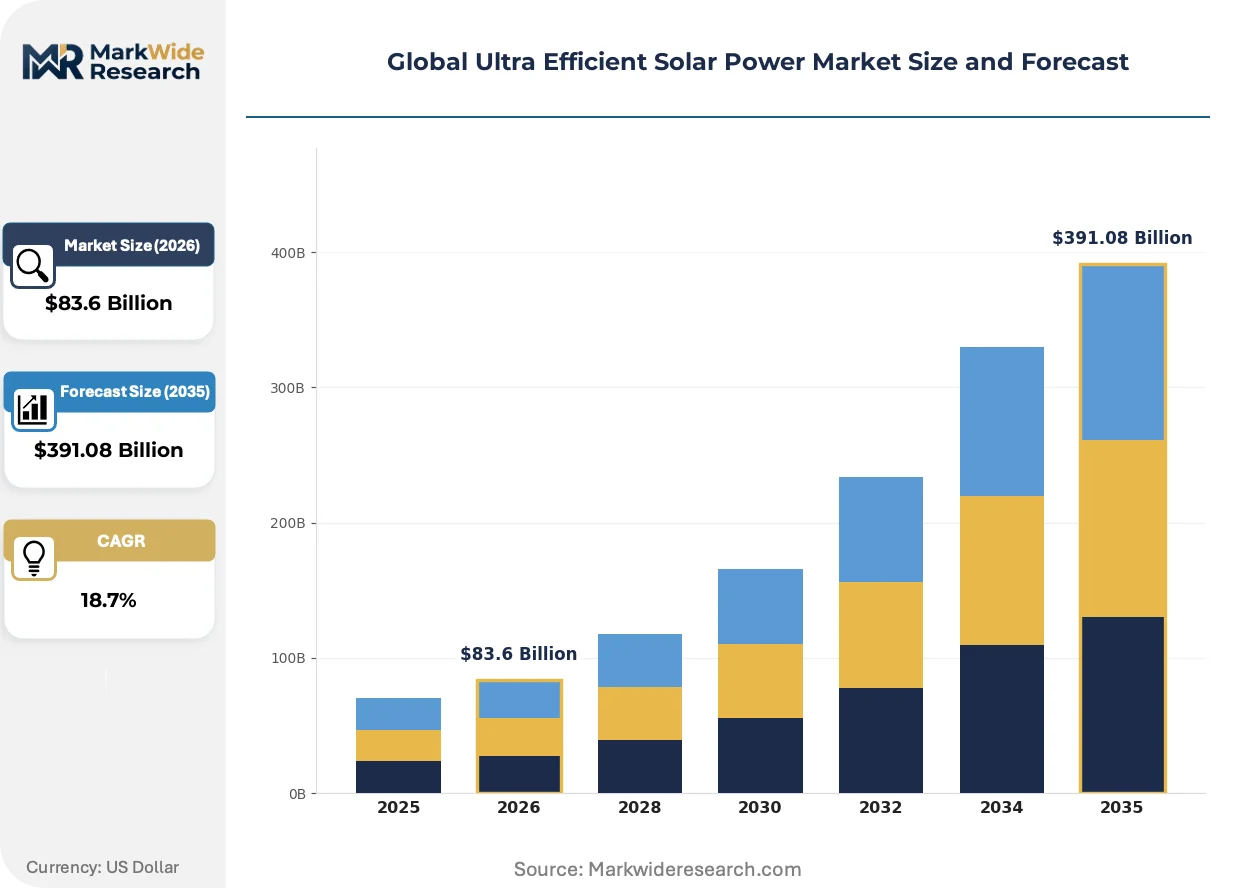
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $391.08 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Technology: Photovoltaic, Concentrated Solar Power, Hybrid Systems, Nanostructured End User: Residential, Commercial, Industrial, Utility Installation: On-Grid, Off-Grid, Rooftop, Ground-Mounted |
| Companies Covered | JinkoSolar, JA Solar, Trina Solar, LONGi, First Solar, Canadian Solar, Hanwha Q CELLS, SunPower, Panasonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ultra Efficient Solar Power Market Emerging Trajectories
Tunnel oxide passivated contact architectures are displacing conventional PERC lines as the default efficiency platform. Manufacturing equipment suppliers and cell producers are racing to stabilize deposition uniformity across larger wafer formats.
Tandem perovskite-silicon stacks are absorbing research investment and pilot line capacity from single-junction producers. Residential and premium commercial installers in South Korea and California are sampling early production batches. This technology is absorbing the high-efficiency premium previously captured by back-contact architectures.
The Inflation Reduction Act's domestic content bonus credit is restructuring module sourcing decisions. Developers must now trace polysilicon origin through wafer, cell, and final assembly to qualify for the full tax credit rate. Utility-scale procurement teams in Texas and Arizona are requalifying supplier bases and requesting audited supply chain documentation.
Long-term fixed-price contracts are displacing merchant exposure for independent power producers. Financial sponsors in Chile and Morocco are demanding 20-25 year offtake coverage before committing construction equity. This shift concentrates counterparty risk assessment capabilities among specialized renewable energy lenders.
Global Ultra Efficient Solar Power Market Segmentation
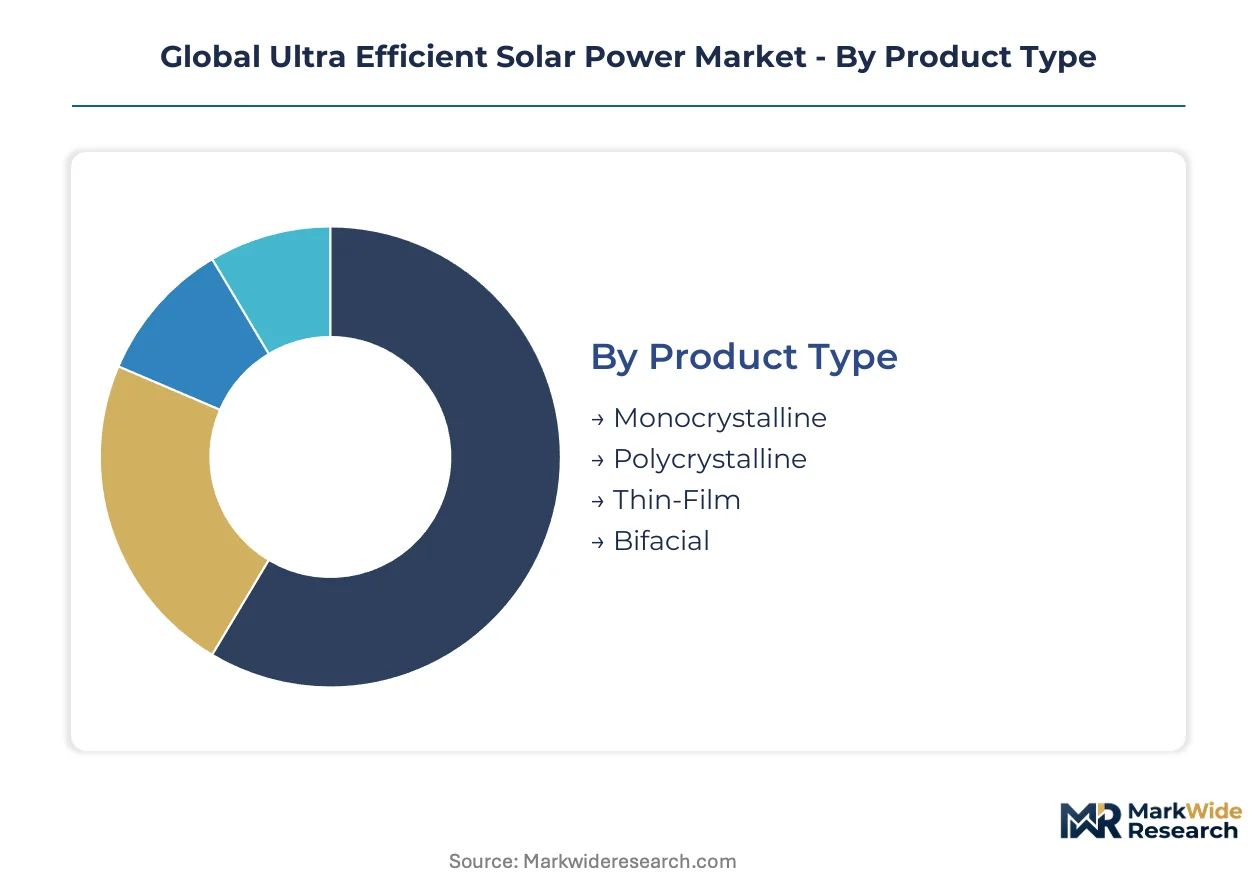
Ultra efficient solar power markets fragment across cell architectures, deployment scales, and grid integration modes. Each segmentation axis reveals distinct capital requirements, margin profiles, and regulatory exposure that shape supplier positioning.
Product Type:
Capital intensity varies sharply across wafer and thin-film manufacturing pathways, with crystalline silicon requiring the heaviest upfront equipment investment.
- Monocrystalline:Czochralski-grown single-crystal ingots yield the highest commercial conversion efficiencies, now exceeding 22% in mass production. Jiangsu and Anhui province clusters in China dominate ingot pulling and wafer slicing capacity, driven by utility-scale procurement demanding maximum output per hectare.
- Bifacial:Dual-glass modules capture direct and reflected irradiance, delivering 8-15% energy yield gains in high-albedo desert and snow-field environments. Rajasthan and Gujarat tenders in India now specify bifacial heterojunction configurations as baseline requirements.
- Polycrystalline:Directional solidification of multicrystalline ingots offers lower capital barriers but capped efficiency ceilings around 20%.
- Thin-Film:Cadmium telluride and copper indium gallium selenide deposition avoids silicon wafering entirely, concentrating manufacturing in Ohio and Malaysia facilities.
Monocrystalline absorbs the bulk of installed capacity; bifacial is expanding most quickly.
Technology:
Technology selection determines the balance between proven bankability and efficiency upside, with photovoltaic systems commanding the dominant financing ecosystem.
- Photovoltaic:Direct semiconductor conversion of photons to electrons underpins the vast majority of capacity additions. Tunnel oxide passivated contact and heterojunction architectures are displacing passivated emitter rear contact lines as the default efficiency platform across Chinese and Southeast Asian cell fabs.
- Nanostructured:Quantum dot and plasmonic light-trapping architectures represent the steepest expansion trajectory as laboratory-to-fab transfer accelerates. South Korean and California residential installers are sampling early production batches of perovskite-tandem configurations.
- Concentrated Solar Power:Parabolic trough and power tower systems with molten salt thermal storage retain structural relevance in high-direct-normal-irradiance zones including Morocco, Chile, and the southwestern United States.
- Hybrid Systems:Photovoltaic-thermal and solar-wind-battery combinations optimize capacity factor and grid stability for island and remote industrial applications.
Photovoltaic commands financing depth and supply chain scale; nanostructured approaches are climbing the fastest.
End User:
Customer scale determines project finance structures, with utility-scale developments accessing the lowest cost of capital and longest offtake tenors.
- Utility:Centralized power plants exceeding 100 megawatts dominate procurement volumes and drive technology roadmaps. Texas and Arizona developers are requalifying supplier bases to satisfy Inflation Reduction Act domestic content bonus credit requirements.
- Industrial:Captive generation for manufacturing facilities and data centers demands high capacity factors and predictable output. Electrolyzer developers in Spain and Australia are signing 15-20 year power purchase agreements favoring high-performance solar configurations.
- Commercial:Rooftop and carport installations for retail, logistics, and office properties balance visibility constraints with energy cost hedging.
- Residential:Distributed rooftop systems face soft costs including permitting and customer acquisition that vary dramatically across German, Australian, and US state-level regulatory environments.
Utility-scale deployment absorbs the bulk of module supply; industrial offtake is gaining share fastest.
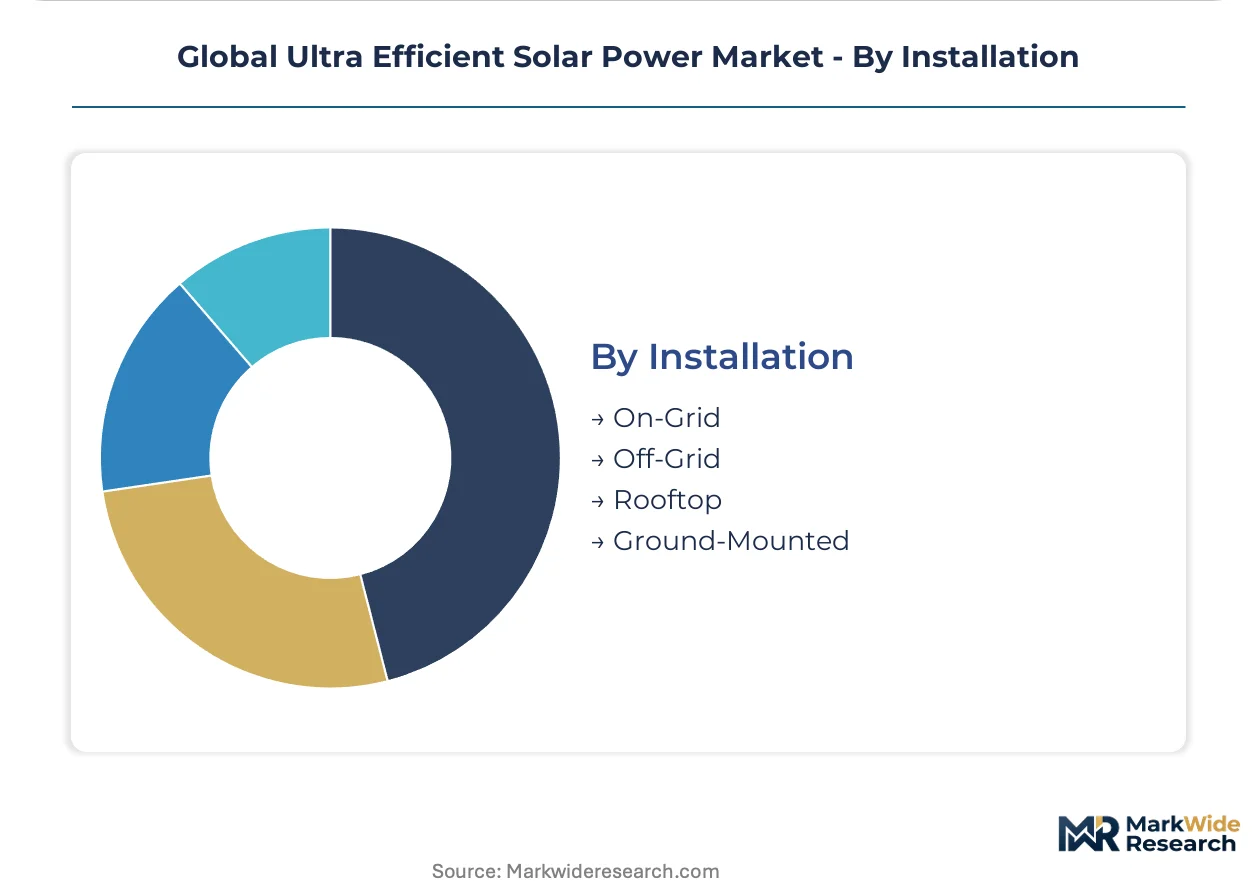
Installation:
Grid integration mode shapes balance-of-system costs and regulatory complexity, with on-grid configurations benefiting from established interconnection standards.
- Ground-Mounted:Utility-scale fixed-tilt and tracking installations minimize per-watt installation labor and maximize energy density. ERCOT and CAISO transmission queue delays are deferring revenue recognition for completed projects despite module readiness.
- On-Grid:Direct connection to distribution or transmission infrastructure enables net metering and wholesale market participation. India's BIS certification and PLI scheme impose efficiency floors and local value-add requirements that reshape import dependency patterns.
- Rooftop:Building-applied and building-integrated configurations face structural load assessments and fire safety code variations across German, Dutch, and Japanese jurisdictions.
- Off-Grid:Standalone systems with battery storage serve remote mining, agricultural, and rural electrification applications where grid extension is uneconomic.
Ground-mounted installations absorb the bulk of capacity additions; rooftop deployment is accelerating most quickly in building-integrated segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xinjiang and Inner Mongolia smelters anchor metallurgical-grade silicon feedstock for cell manufacturing. Utility-scale procurement concentrates in China, India, and the United States as grid parity reshapes project economics. Manufacturing clusters in Jiangsu and Anhui provinces achieve the lowest levelized cost of energy through integrated cell-to-module operations.
China
Jiangsu and Anhui province manufacturing clusters dominate n-type substrate production as conversion efficiency thresholds tighten. MIIT dual carbon goals and GB standards mandate module carbon intensity disclosures that filter high-emission imports. Yangtze River Delta facilities achieve captive wafer-to-module integration that compresses production costs below competitors.
United States
Texas and Arizona developers drive utility-scale procurement demanding audited supply chain documentation for tax credit eligibility. EPA domestic content requirements under the Inflation Reduction Act condition full credit rates on polysilicon origin tracing through final assembly. ERCOT and CAISO transmission queue delays defer revenue recognition despite module readiness at completed projects.
India
Rajasthan and Gujarat tenders specify bifacial heterojunction modules with 22% efficiency floors as grid parity accelerates. BIS certification and PLI scheme impose local value-add requirements that reshape import dependency patterns. Manufacturing investments concentrate in Gujarat and Tamil Nadu as developers seek to satisfy domestic content rules.
Germany
Building-integrated photovoltaic demand from architectural glass and facade segments drives customized module form factors. EMA and REACH frameworks mandate extended producer responsibility and restricted substance controls that filter designs entering EU markets. Bavaria and Baden-Württemberg industrial zones host precision engineering suppliers for deposition equipment.
Japan
METI feed-in tariff revisions for agrivoltaic dual-use applications open acreage previously excluded from solar development. Residential and premium commercial installers sample early production batches of high-efficiency configurations. Kanto and Kansai metropolitan areas concentrate distributed generation deployment where land constraints demand maximum output per unit area.
Global Ultra Efficient Solar Power Market Vendor Landscape
Global majors compete with regional champions across manufacturing scale and technology integration. The vendor base stratifies into three tiers: vertically integrated ingot-to-module operators, cell specialists dependent on merchant wafer supply, and thin-film technology differentiated from crystalline silicon. Strategic moves concentrate on capacity expansion in n-type architectures and backward integration into polysilicon to secure feedstock qualification for subsidy eligibility.
Among Chinese vertically integrated producers, JinkoSolar, LONGi, and JA Solar exemplify the scale-driven archetype that dominates 182mm and 210mm wafer formats. These entities anchor competitive positioning through captive supply chains that satisfy jurisdictional domestic content requirements. First Solar occupies a distinct position as a thin-film specialist optimized for utility-scale desert installations, representing the technology-differentiated tier that avoids silicon wafering entirely.
| Leading Market Players |
|---|
| JinkoSolar |
| JA Solar |
| Trina Solar |
| LONGi |
| First Solar |
| Canadian Solar |
| Hanwha Q CELLS |
| SunPower |
| Panasonic |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between IRA-compliant domestic content modules and standard imports manifests in divergent pricing bands and supply chain qualification costs. Developers in Texas and Arizona now pay premiums for audited polysilicon origin documentation that satisfies EPA tax credit eligibility, while merchant wafer buyers absorb silver paste volatility without subsidy offset.
Pricing Analysis
Warranty bundling separates premium module tiers from commodity offerings, with 25-30 year performance guarantees and degradation rate assurances now standard for utility-scale procurement. Three-tier pricing structure across premium, standard, and economy levels reflects efficiency certification, domestic content qualification, and bankability tier. Cost compression in standard-grade PERC modules is intensifying because Chinese ingot-to-module clusters achieve captive supply economics. Utility-scale developers exhibit highest price sensitivity, while residential installers in South Korea and California absorb premiums for early tandem perovskite-silicon batches.
Supply Chain Analysis
Single-source vulnerability sits with Xinjiang and Inner Mongolia metallurgical-grade silicon smelters that anchor polysilicon feedstock for n-type substrate production. Manufacturing equipment and silver paste draw from Germany, Japan, and South Korean precision engineering suppliers. Tariff exposure on Chinese cell imports into the United States and India is forcing requalification of alternative Southeast Asian module assembly locations. Distribution runs through vertically integrated ingot-to-module operators and specialized EPC contractors with captive installation crews.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around n-type technology transition costs that force cell specialists without captive wafer supply into exit or acquisition. Capital requirements for TOPCon and heterojunction deposition equipment are filtering out sub-scale producers.
For Market Incumbents: Deepen backward integration into polysilicon smelting to secure IRA domestic content bonus credit eligibility and insulate margins from silver paste volatility. Add n-type cell capacity in Jiangsu and Anhui province clusters where integrated manufacturing achieves lowest levelized cost. Acquire distressed PERC-line assets from exiting competitors to convert into tunnel oxide passivated contact platforms. For New Entrants and Emerging Players: Direct-to-utility digital procurement platforms offer white-space entry for module suppliers with certified domestic content documentation. Target agrivoltaic deployment in Japan where METI feed-in tariff revisions favor dual-use land configurations. Pursue building-integrated photovoltaic segments in Germany and the Netherlands where aesthetic customization commands price premiums and incumbent coverage is thin. For Investors and Strategic Acquirers: Re-rating potential sits with thin-film technology specialists given cadmium telluride differentiation in desert utility installations and exemption from silicon supply chain concentration. Long-term viability favors producers with 15-20 year power purchase agreement offtake coverage and electrolyzer developer relationships in Spain and Australia. Watch interconnection queue clearance rates in ERCOT and CAISO zones as inflection indicator for revenue recognition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Captive Xinjiang and Inner Mongolia smelter access secures IRA tax credit eligibility for US developers. |
| N-Type Cell Capacity Buildout | Tunnel oxide passivated contact and heterojunction lines displace PERC assets as default efficiency platform. |
| Long-Term Power Purchase Agreement | Electrolyzer developers in Spain and Australia favor 15-20 year offtake coverage for green hydrogen projects. |
| Domestic Content Certification Program | EPA audit requirements restructure module sourcing decisions toward traced polysilicon origin. |
| Agrivoltaic Technology Licensing | METI feed-in tariff revisions open Japanese acreage previously excluded from solar development. |
Methodological Framework
IEA renewable energy databases, EIA power plant filings, and FERC interconnection queue records formed the secondary backbone for capacity and project pipeline validation. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators combined with customs trade data and SEC equipment supplier filings. Bottom-up project-level aggregation and top-down manufacturing capacity triangulation anchored market size estimates.
Historical trendline analysis of module efficiency improvements and manufacturing cost curves informed projection frameworks across the analysis window. Segmentation modeling covered cell architecture, deployment scale, end-user category, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves incorporating polysilicon supply expansion, subsidy phase-out schedules, and interconnection clearance rates.
The model holds under continued IRA domestic content enforcement and stable silver paste pricing; deviation in tariff regimes or transmission buildout delays would shift capacity addition timelines. Forecasts reflect documented assumptions regarding technology transfer rates and jurisdictional subsidy continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Collector Panels Market
Solar Power Systems
Chile Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Photovoltaic Glass Market
Solar Power Systems
Solar PV Carport Market
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
Sweden Solar Energy Market
Solar Power Systems
Middle East and Africa Solar PV Inverters Market
Solar Power Systems
Residential Solar Panels Market
Solar Power Systems
Solar Panel Market
Solar Power Systems
Solar Photovoltaic Material Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
Chile Renewable Energy Market
Solar Power Systems
Printable Solar Cells Market
Solar Power Systems
Flexible Solar Panel Market
Solar Power Systems
Building Applied Photovoltaics (BAPV) Market