
 France EV Battery Pack Market | 2026-2036
France EV Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
France EV Battery Pack Market Insights
Modular pack architecture is recalibrating procurement decisions across French OEM supply chains. Automotive Cells Company anchors domestic cell-to-pack production through its Douai and Billy-Berclau gigafactories. Saft Groupe S.A. leverages its Bordeaux engineering heritage to dominate niche heavy-duty and aviation battery systems. Samsung SDI Co. Ltd. competes via premium nickel-cobalt chemistry tailored to European luxury EV platforms.
France EV Battery Pack denotes an integrated electrochemical energy storage system comprising cells, modules, thermal management hardware, and battery management electronics, typically delivering 300-800 volts DC output for traction applications. The assembly integrates laser-welded cell interconnects, dielectric coolant channels, and fire-resistant enclosures to ensure cycle stability across temperature extremes. Lithium-ion chemistry occupies the dominant share of current installations, though solid-state configurations are capturing development funding due to their promise of doubled energy density and eliminated thermal runaway risk. Within end-user categories, passenger vehicles lead absolute volume while commercial vehicles represent the fastest margin expansion as fleet operators electrify last-mile logistics under urban low-emission zone requirements.
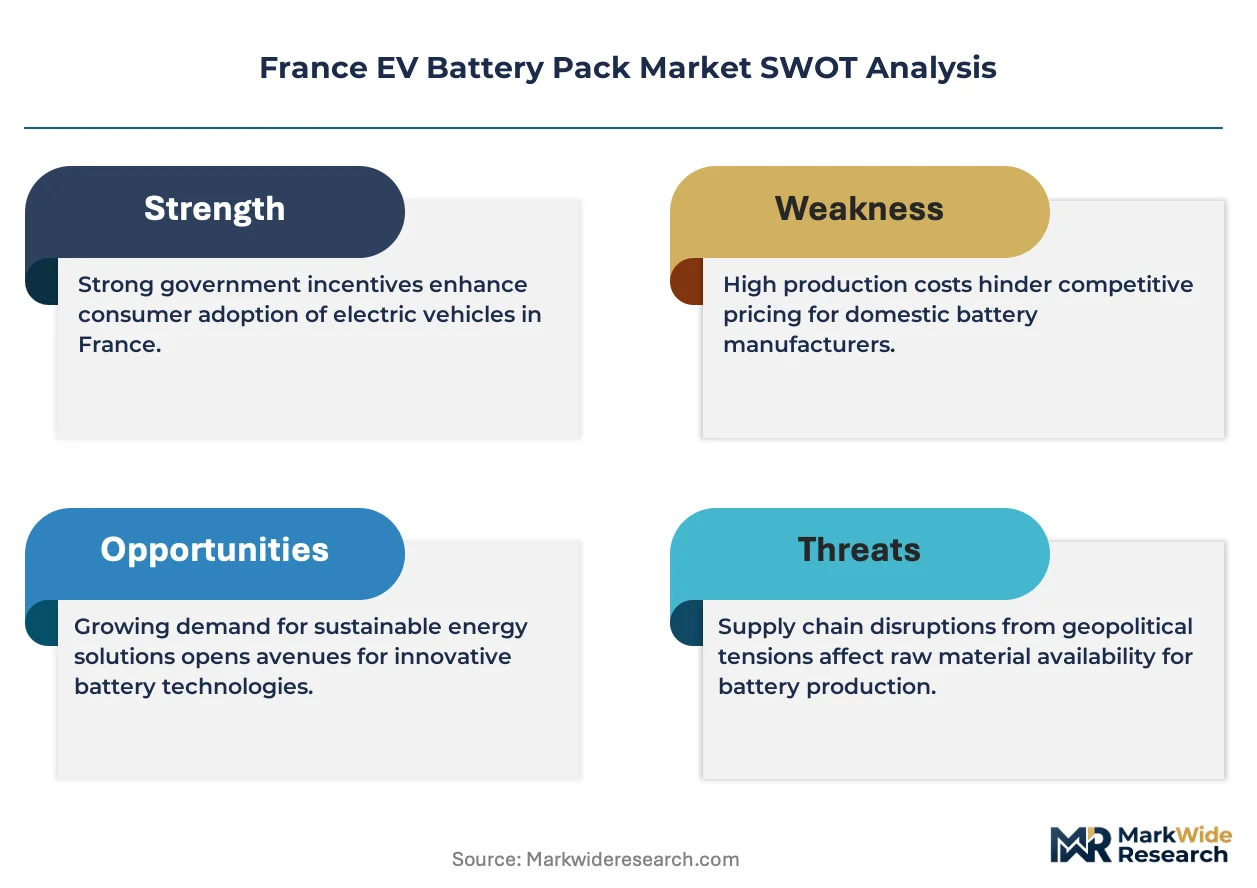
France's national regulator enforces battery safety and recycling protocols through transposed EU Battery Regulation mandates, while ANSM oversees occupational chemical exposure limits in cell manufacturing facilities. The EU Green Deal's carbon border adjustments are tightening embodied-emission standards for imported cells, reshaping supplier qualification criteria. Stakeholders must monitor how France's national critical minerals strategy interacts with EU-level raw material partnerships to secure cathode supply without dependency concentration.
Market Dynamics
EU Green Deal mandates are forcing French OEMs to electrify passenger vehicle lineups faster than supply chains can adapt, compressing pack qualification timelines and redirecting R&D budgets toward solid-state chemistry platforms.
Growth Catalysts
- EU Battery Regulation transposition:France's enforcement of recycled content mandates and carbon footprint declarations is creating guaranteed demand for domestically assembled packs with traceable supply chains.
- Heavy-duty electrification:Urban low-emission zones in Lyon, Marseille, and Toulouse are accelerating fleet operator demand for commercial vehicle battery systems with standardized swap interfaces.
- Solid-state R&D concentration:The Paris-Saclay battery innovation cluster is attracting public-private funding for next-generation platforms promising doubled energy density and eliminated thermal runaway risk.
Market Restraints
- Cathode material dependency:Concentrated cobalt and nickel sourcing from non-EU jurisdictions exposes pack assemblers to supply disruption and carbon border adjustment penalties under EU Green Deal trade mechanisms.
- Cell manufacturing scale gaps:Domestic gigafactory output from Automotive Cells Company remains insufficient to meet projected OEM demand, forcing continued reliance on imported cells from Asian suppliers.
- Thermal management complexity:Current liquid cooling architectures impose weight and packaging constraints that limit energy density gains achievable through cell chemistry improvements alone.
Strategic Opportunities
- Second-life stationary storage:Decommissioned automotive packs from early Renault and Peugeot EV fleets are creating a feedstock stream for grid-scale energy storage projects in Brittany and Occitanie.
- Aviation battery systems:Saft Groupe S.A.'s Bordeaux engineering base positions French suppliers to capture emerging demand from regional electric aircraft programs targeting 2030 certification.
- ANSM occupational safety alignment:Stricter chemical exposure protocols in cell manufacturing facilities are creating competitive advantage for pack assemblers with advanced automation and closed-loop electrolyte handling systems.
Industry Challenges
- Electrochemical engineering talent scarcity:French technical universities are producing insufficient graduates with expertise in solid-electrolyte interphase characterization and laser-welding process control for next-generation pack architectures.
- Cell-to-pack integration complexity:Eliminating module-level assembly requires redesign of thermal management hardware and battery management electronics, extending qualification timelines for OEM platform integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France EV Battery Pack Market |
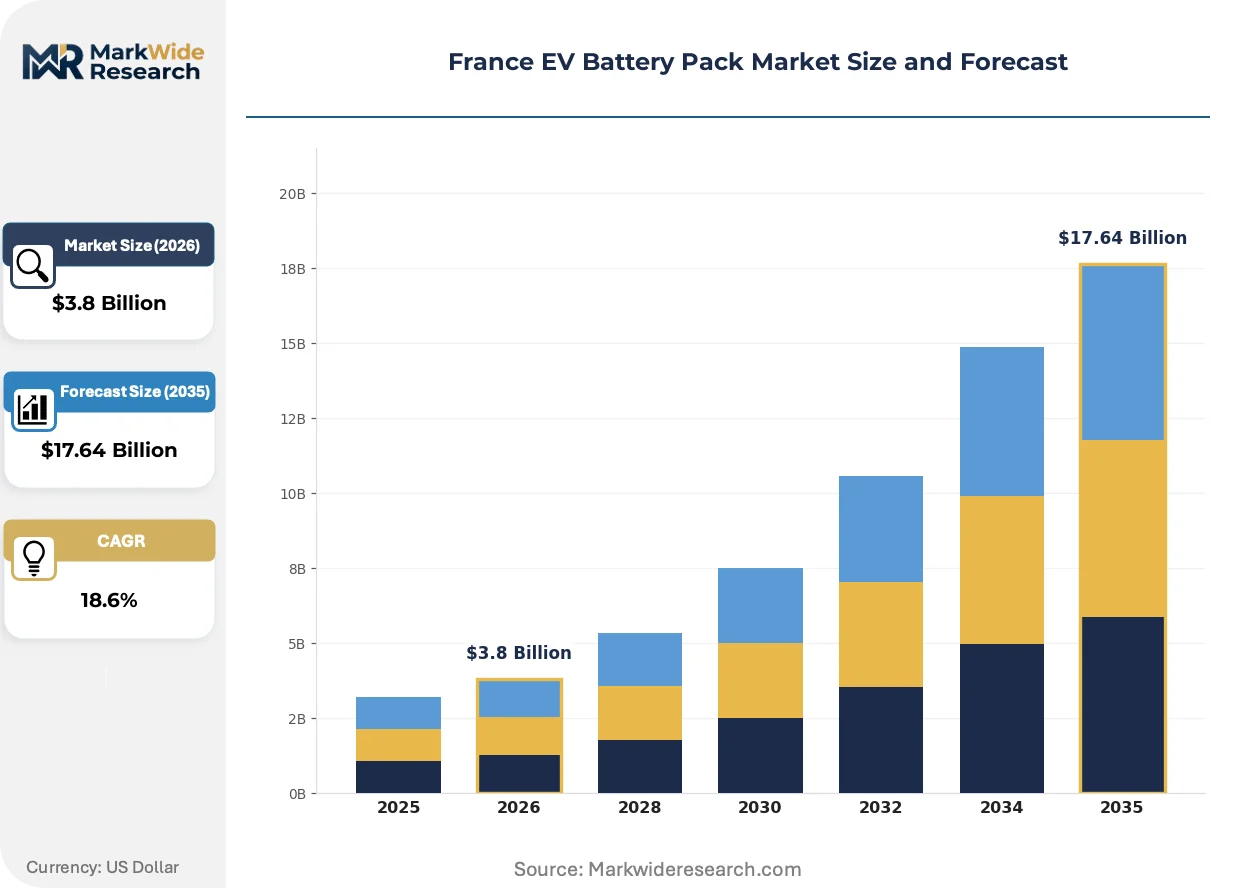
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Solid State, Nickel Metal Hydride, Lead Acid End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Public Transport Technology: Battery Management Systems, Thermal Management, Charging Technology, Energy Density Improvement Application: Energy Storage, Automotive, Grid Support, Others |
| Companies Covered | Automotive Cells Company (ACC), Contemporary Amperex Technology Co. Ltd. (CATL), LG Energy Solution Ltd., Blue Solutions SA, Forsee Power, Samsung SDI Co. Ltd., BYD Company Ltd., Saft Groupe S.A., Panasonic Holdings Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France EV Battery Pack Market Trends and Innovations
Pack architecture standardization is colliding with chemistry diversification, forcing suppliers to develop flexible assembly platforms capable of accommodating both incumbent lithium-ion and emerging solid-state cell formats without full line retooling.
Silicon-anode chemistries are electrifying premium passenger vehicle segments by delivering 20-40% energy density improvements over graphite-based systems. BMW and Mercedes-Benz procurement teams are qualifying French-assembled packs with high-silicon content for 2027 platform launches. This chemistry transition is electrifying the competitive landscape by rewarding suppliers with advanced slurry coating and pre-lithiation process capabilities.
France's transposition of the EU Battery Regulation is mandating digital battery passports with full supply chain traceability from 2027. Pack assemblers must deploy blockchain-verified data systems to document raw material origins, manufacturing carbon intensity, and end-of-life recycling pathways. The Hauts-de-France manufacturing corridor is responding fastest, with Douai and Billy-Berclau facilities piloting passport-compliant production lines ahead of enforcement deadlines.
Fleet operators are consolidating procurement around total-cost-of-ownership contracts that bundle pack hardware, thermal management maintenance, and residual value guarantees. Last-mile logistics providers in the Île-de-France region are displacing traditional capex purchases with performance-based agreements where suppliers retain pack ownership and responsibility for cycle-life degradation. This model shift is compressing supplier margins while extending customer lock-in duration.
France EV Battery Pack Market Segmentation
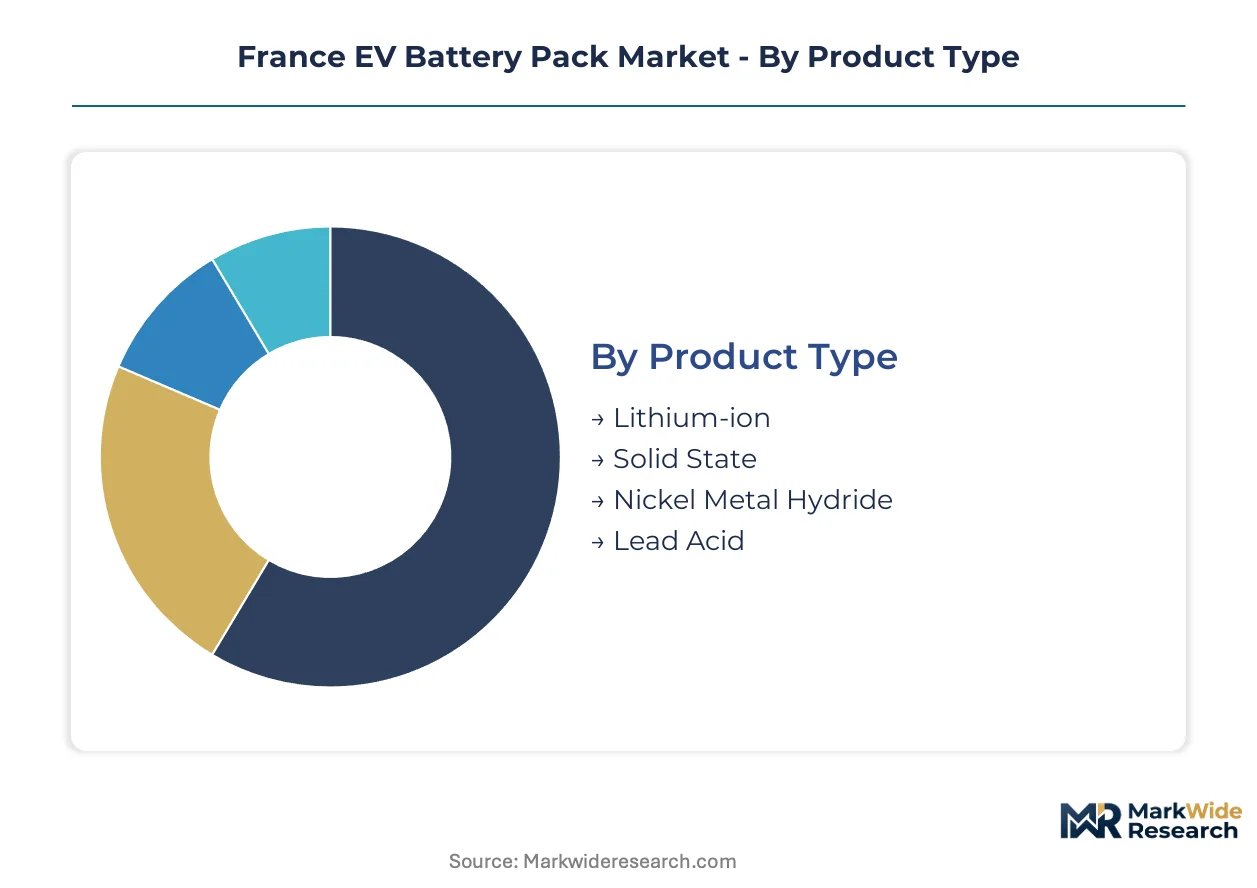
Segmentation in the France EV Battery Pack Market reveals how chemistry choices, vehicle platforms, and system architectures are diverging under regulatory pressure. OEM procurement teams now qualify suppliers across multiple technical dimensions simultaneously, compressing development timelines for pack integrators.
Product Type:
Replacement cycles for incumbent chemistries are shortening as solid-state platforms approach commercial readiness, forcing pack assemblers to maintain dual qualification pathways.
- Lithium-ion:Dominant chemistry employing nickel-cobalt-manganese or lithium-iron-phosphate cathodes with graphite or silicon-blend anodes, delivering 250-300 Wh/kg at pack level. Demand clusters around the Hauts-de-France corridor where Automotive Cells Company supplies Renault and Stellantis assembly lines under EU Battery Regulation traceability mandates.
- Solid State:Next-generation platforms replacing liquid electrolytes with ceramic or sulfide solid electrolytes, targeting 400-500 Wh/kg with eliminated thermal runaway risk. The Paris-Saclay battery innovation cluster is concentrating public-private R&D funding as French OEMs accelerate platform qualification timelines ahead of EU Green Deal fleet emission targets.
- Nickel Metal Hydride:Mature chemistry retaining niche presence in hybrid-electric vehicle applications with lower energy density but proven cycle stability.
- Lead Acid:Legacy technology constrained to auxiliary power and low-voltage subsystem support in commercial vehicle architectures.
Volume placements concentrate in Lithium-ion; the faster expansion belongs to Solid State.
End User:
Cost tier differentiation across vehicle categories is reshaping pack specification requirements, with premium passenger segments absorbing advanced silicon-anode chemistries while commercial fleets prioritize total-cost-of-ownership optimization.
- Passenger Vehicles:Premium and mass-market light-duty platforms requiring 60-100 kWh pack capacities with 800-volt architectures for fast-charging compatibility. French OEM electrification roadmaps under EU fleet emission rules are driving qualification demand at Douai and Billy-Berclau gigafactories.
- Commercial Vehicles:Medium and heavy-duty applications with standardized swap interfaces for last-mile logistics fleets operating under Lyon, Marseille, and Toulouse low-emission zone mandates. Margin expansion is climbing the fastest as fleet operators consolidate procurement around performance-based contracts with residual value guarantees.
- Two-Wheelers:Compact pack formats for electric motorcycles and scooters with simplified thermal management and lower voltage architectures.
- Public Transport:High-capacity systems for electric bus fleets with opportunity charging infrastructure and extended cycle-life requirements.
Passenger Vehicles dominate absolute pack shipments; Commercial Vehicles are gaining share fastest through fleet electrification mandates.
Technology:
Application-specific technology maturation is creating divergent supplier capability requirements, with thermal management and battery management electronics now representing distinct competitive moats.
- Battery Management Systems:Electronic control units monitoring cell-level voltage, temperature, and state-of-charge with predictive algorithms for degradation forecasting. ANSM chemical exposure protocols in French manufacturing facilities are favoring suppliers with automated assembly and closed-loop electrolyte handling.
- Thermal Management:Liquid cooling architectures with dielectric coolants, cold plates, and refrigerant loops maintaining cell temperatures within 15-35°C operating windows. Cell-to-pack integration trends are eliminating module-level thermal interfaces, requiring complete hardware redesigns.
- Charging Technology:Onboard and offboard power electronics enabling 150-350 kW DC fast charging with thermal preconditioning protocols.
- Energy Density Improvement:Materials engineering advances in silicon anode loading, dry electrode coating, and solid electrolyte integration.
Procurement concentration sits with Battery Management Systems; Thermal Management is expanding most quickly through cell-to-pack architectural transitions.
Application:
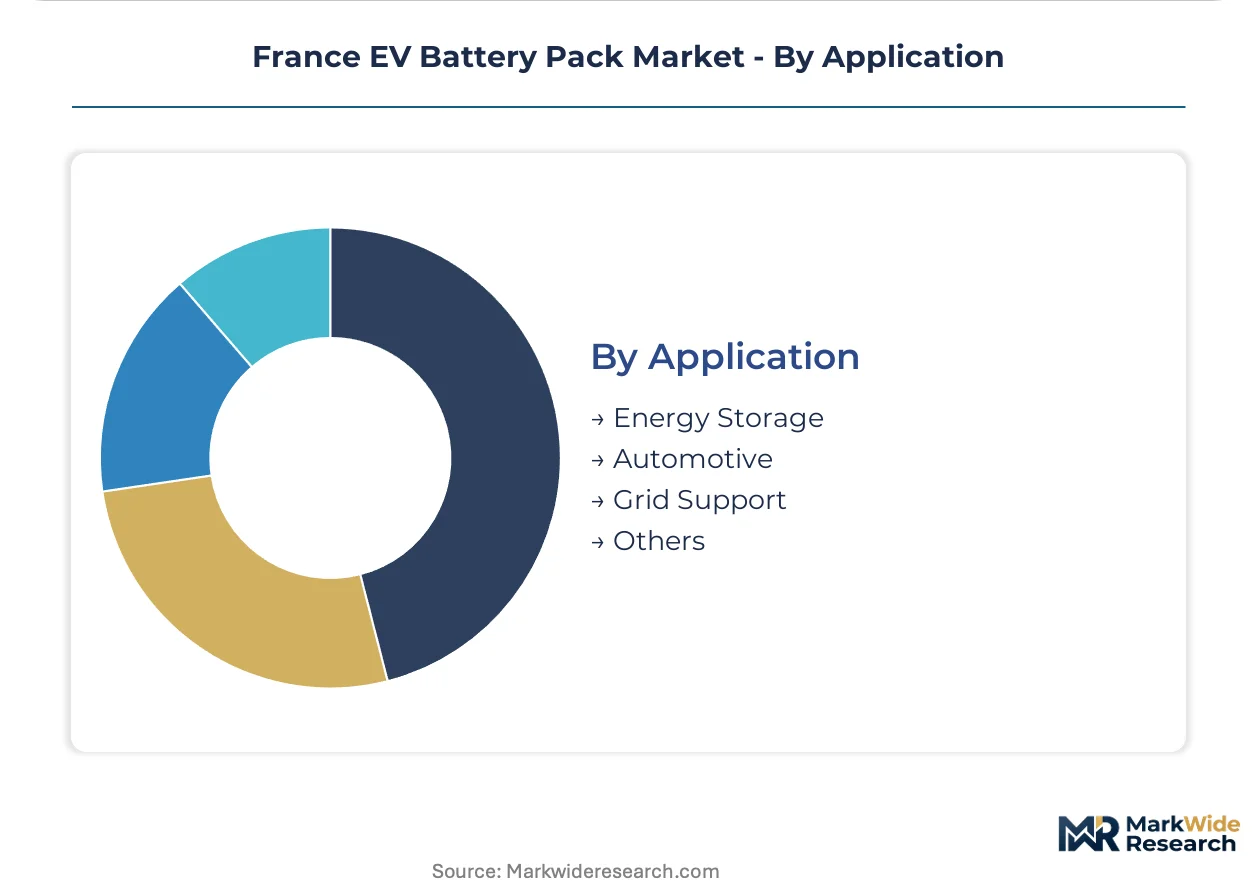
Geography-driven demand clustering is segmenting the market, with automotive traction applications anchoring volume while stationary storage creates second-life value recovery pathways.
- Automotive:Traction battery systems for passenger cars, vans, trucks, and buses with crash-resistant enclosures and electromagnetic compatibility certification. The Île-de-France region concentrates OEM engineering centers and pack qualification facilities.
- Energy Storage:Second-life repurposing of decommissioned automotive packs for behind-the-meter and grid-scale installations in Brittany and Occitanie, creating circular economy revenue streams under EU Battery Regulation recycling mandates.
- Grid Support:Frequency regulation and peak shaving services with rapid response capability.
- Others:Marine, aviation, and industrial mobility applications including Saft Groupe S.A.'s Bordeaux-engineered systems for regional electric aircraft programs.
Automotive commands the dominant placement volume; Energy Storage is climbing the fastest through early Renault and Peugeot EV fleet retirement schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's battery pack production capacity lags behind domestic EV consumption growth, creating import dependency from Asian cell manufacturers while EU Green Deal carbon border adjustments reshape supplier qualification criteria.
Île-de-France
Paris-Saclay battery innovation cluster concentrates solid-state R&D funding from public-private partnerships targeting next-generation energy density benchmarks. ANSM chemical exposure protocols govern cell manufacturing automation investments across the region. Saint-Quentin-en-Yvelines hosts pack qualification facilities serving Renault and Stellantis engineering centers.
Hauts-de-France
Douai and Billy-Berclau gigafactories anchor Automotive Cells Company's cell-to-pack production for domestic OEM supply chains. EU Battery Regulation recycled content mandates are accelerating traceability system deployment at these facilities. Dunkirk port infrastructure supports cathode precursor import logistics from EU critical minerals partnerships.
Auvergne-Rhône-Alpes
Lyon low-emission zone mandates are electrifying last-mile logistics fleets with standardized battery swap interfaces. The region's industrial automation heritage feeds thermal management hardware suppliers serving pack integrators. Grenoble microelectronics ecosystem supplies battery management system semiconductor components.
Nouvelle-Aquitaine
Saft Groupe S.A.'s Bordeaux engineering base dominates heavy-duty and aviation battery system development for regional electric aircraft programs. The region's aerospace supply chain is converging with electrochemical engineering capabilities under France's national critical minerals strategy. Poitiers research institutes contribute to solid-electrolyte characterization for next-generation platforms.
Occitanie
Toulouse low-emission zone requirements are accelerating commercial vehicle fleet electrification with performance-based procurement contracts. Second-life stationary storage projects in the region repurpose decommissioned automotive packs from early Renault EV fleets under EU Battery Regulation recycling mandates. Montpellier energy storage integrators are piloting grid-scale installations using retired pack feedstock.
France EV Battery Pack Market Competitive Landscape
The competitive structure tilts toward integrated cell-to-pack manufacturers with captive cathode supply agreements. Domestic players concentrate around Automotive Cells Company's gigafactory network while Asian suppliers compete through premium chemistry platforms. Three archetypes dominate: EU-based integrated manufacturers with traceable supply chains, Asian scale producers with cost-optimized lithium-ion platforms, and niche specialists in heavy-duty or aviation applications. Capacity expansion and strategic partnerships with critical minerals processors represent the dominant competitive moves.
Among French-based integrated manufacturers, Automotive Cells Company exemplifies the domestic cell-to-pack archetype with Douai and Billy-Berclau production facilities. Saft Groupe S.A. occupies a position within the niche specialist tier, leveraging Bordeaux engineering heritage for non-automotive battery systems. Samsung SDI Co. Ltd. represents the Asian premium chemistry segment competing via nickel-cobalt platforms tailored to European luxury EV specifications.
| Leading Market Players |
|---|
| Automotive Cells Company (ACC) |
| Contemporary Amperex Technology Co. Ltd. (CATL) |
| LG Energy Solution Ltd. |
| Blue Solutions SA |
| Forsee Power |
| Samsung SDI Co. Ltd. |
| BYD Company Ltd. |
| Saft Groupe S.A. |
| Panasonic Holdings Corporation |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers like Automotive Cells Company anchor French cell-to-pack manufacturing, creating pricing discipline through captive cathode supply agreements while EU Green Deal carbon border adjustments reshape import qualification economics for Asian competitors.
Pricing Analysis
Cost-down pressure on standard lithium-ion packs accelerates because Automotive Cells Company's Douai and Billy-Berclau output remains insufficient for domestic OEM demand, forcing continued reliance on imported cells. Three-tier pricing structure across premium silicon-anode, standard nickel-cobalt-manganese, and economy lithium-iron-phosphate levels separates OEM procurement tiers. ANSM chemical exposure compliance costs and EU Battery Regulation traceability mandates widen spreads between automated domestic assembly and imported alternatives. Fleet operators in commercial vehicle segments exhibit highest price sensitivity through total-cost-of-ownership contracting, while premium passenger OEMs absorb silicon-anode premiums for energy density gains.
Supply Chain Analysis
Electrochemical engineering talent scarcity across Hauts-de-France and Paris-Saclay clusters constrains cell-to-pack integration scale-up, forcing reliance on Asian process engineering support. Cathode precursor supply draws from EU critical minerals partnerships with Canada and Australia, while finished cell imports rest on South Korean and Chinese manufacturing concentration. Single-source vulnerability in cobalt and nickel sourcing from non-EU jurisdictions exposes pack assemblers to carbon border adjustment penalties. Distribution runs through Dunkirk port infrastructure for precursor logistics and direct OEM just-in-time delivery from Douai gigafactory capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's EV battery pack market remains supply-constrained, with Automotive Cells Company's gigafactory output trailing Renault and Stellantis electrification timelines and propping pricing for qualified domestic assembly.
For Market Incumbents: Deploy backward integration into cathode precursor processing to secure EU Battery Regulation recycled content compliance and defend against Asian scale producers with carbon-adjusted cost advantages. Accelerate automation investments under ANSM chemical exposure protocols to offset labor scarcity in solid-state qualification. Capture fleet operator consolidation through performance-based contracts with residual value guarantees.
For New Entrants and Emerging Players: Regional electric aircraft battery systems represent an underserved buyer archetype with Saft Groupe S.A.'s Bordeaux engineering base demonstrating viable niche positioning outside automotive volume competition. Second-life stationary storage integrators in Brittany and Occitanie offer penetrable entry points leveraging early Renault EV fleet retirement schedules. Pursue ANSM-aligned automation credentials as qualification shortcut for OEM supplier lists.
For Investors and Strategic Acquirers: Distressed-cycle entries favor thermal management hardware specialists with cell-to-pack redesign capabilities in Auvergne-Rhône-Alpes, where Grenoble microelectronics ecosystems feed battery management system semiconductor demand. Five-to-ten year viability hinges on solid-state platform qualification timelines and EU critical minerals strategy execution. Watch Automotive Cells Company capacity ramp signals against Stellantis and Renault platform launch schedules as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Integration Scale-Up | Douai and Billy-Berclau capacity expansion reduces OEM dependency on Asian cell imports under EU carbon border adjustments. |
| Solid-State R&D Partnership | Paris-Saclay cluster funding concentrates public-private investment for next-generation energy density benchmarks. |
| Cathode Precursor Supply Agreement | EU critical minerals partnerships with Canada and Australia secure recycled content compliance for Battery Regulation mandates. |
| Second-Life Storage Joint Venture | Occitanie grid-scale projects repurpose early Renault EV packs into stationary storage revenue streams. |
| Thermal Management Hardware Acquisition | Auvergne-Rhône-Alpes automation heritage feeds pack integrators redesigning liquid cooling architectures for cell-to-pack elimination. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, gigafactory operations managers, and ANSM compliance officers. ECHA substance registration databases, EU Battery Regulation transposition documents, and French customs import statistics provided validation layers. Bottom-up cell production estimates and top-down EV registration projections were triangulated against ANSM manufacturing facility disclosures.
Data-stream reconciliation across vehicle production forecasts, chemistry-specific energy density assumptions, and pack architecture transition timelines informed the analytical framework. Segmentation dimensions modeled included chemistry platform, vehicle class, thermal management architecture, and regional manufacturing cluster. CAGRs were derived from installed base growth rates and replacement cycle compression under EU fleet emission rules. Solid-state commercialization timelines and silicon-anode penetration curves served as chemistry-specific forecast inputs.
Revisions become necessary when EU critical minerals partnership execution falters, solid-state platform qualification timelines extend beyond OEM roadmap commitments, or carbon border adjustment enforcement intensifies import cost structures. Forecasts reflect assumptions regarding Automotive Cells Company capacity ramp schedules and Stellantis-Renault electrification commitments. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Europe Electric Vehicle Battery Market
EV Batteries
EV Battery Water Cold Plates Market
EV Batteries
Asia-Pacific EV Battery Pack Market
EV Batteries
China EV Battery Pack Market
EV Batteries
Traction Battery Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
United States Electric Vehicle Battery Materials Market
EV Batteries
United Kingdom Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Vehicle Solid State Battery Market
EV Batteries
Auto Storage Battery Market
EV Batteries
Electric Vehicle Battery Thermal Management Systems Market
EV Batteries
Canada EV Battery Pack Market
EV Batteries
Middle-East and Africa Electric Vehicle Battery Anode Market
EV Batteries
ASEAN Countries Electric Vehicle Battery Manufacturing Market
EV Batteries
Curved Lipo Battery Market