
 Mexico Solar Photovoltaic (PV) Market | 2026-2036
Mexico Solar Photovoltaic (PV) Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Solar Photovoltaic (PV) Market Foresight
Sonora's emerging solar manufacturing cluster is rewriting supply chain economics for Mexico's photovoltaic sector. Enel Green Power leverages its operational scale across multiple states to sustain project development momentum. Iberdrola anchors its competitive stance through integrated development-to-generation capabilities in the Mexican northwest. Jinko Solar competes aggressively on module cost positioning for utility-scale tenders.
Mexico Solar Photovoltaic systems convert sunlight into direct-current electricity through semiconductor junctions, with monocrystalline silicon cells achieving conversion efficiencies above 22% under standard test conditions. These installations primarily serve grid-connected power generation for utility off-takers and commercial-industrial consumers seeking tariff relief. Monocrystalline modules dominate the product mix due to superior efficiency density and declining wafer costs. Ground-mounted installations occupy the largest share of deployed capacity, while bifacial technology gains traction in high-irradiance regions for its dual-side energy yield advantage.
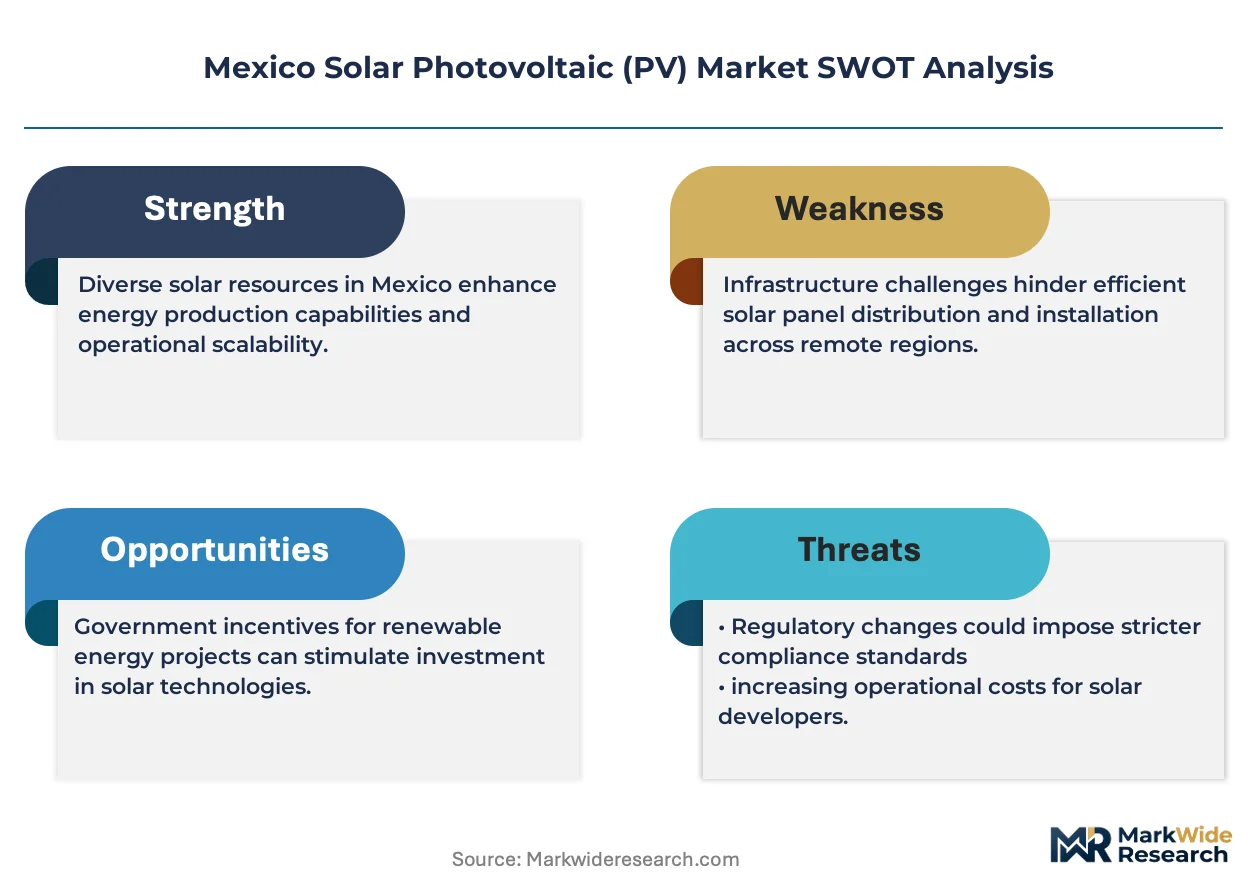
The Comisión Reguladora de Energía shapes market access through interconnection standards and power purchase agreement frameworks for private participants. Mexico's Secretaría de Energía and Comisión Federal de Electricidad jointly influence procurement rules under the country's electricity industry law, creating compliance thresholds for new project approvals. Stakeholders must monitor regulatory clarity on clean energy certificates and transmission priority to calibrate capital allocation across development pipelines.
Market Dynamics
Utility-scale procurement acceleration across Sonora, Chihuahua, and Baja California is compressing project development timelines and concentrating module demand in Mexico's industrial northwest corridor.
Growth Catalysts
- Clean Energy Certificates:Mexico's electricity industry law mandates procurement thresholds that oblige large consumers to source renewable power, creating guaranteed offtake for solar developers.
- Industrial Tariff Relief:Manufacturing clusters in Ciudad Juárez and Tijuana deploy rooftop systems to offset commercial electricity rates from Comisión Federal de Electricidad.
- Monocrystalline Efficiency Gains:Wafer cost declines above 22% conversion efficiency make ground-mounted installations economically competitive against combined-cycle gas generation.
Market Restraints
- Polysilicon Input Volatility:Raw material price swings in upstream metallurgical-grade silicon concentrate margin pressure on domestic module assemblers lacking long-term supply contracts.
- Permitting Timeline Uncertainty:Comisión Reguladora de Energía interconnection queue backlogs extend project commissioning windows by 18-24 months beyond original schedules.
- Transmission Bottlenecks:Limited high-voltage line capacity from northern generation zones to central load centers constrains dispatch priority for new solar parks.
Strategic Opportunities
- Bifacial Technology Penetration:Dual-side energy yield modules gain traction in high-irradiance zones like Mexicali Valley, capturing reflected albedo radiation from desert surfaces.
- Distributed Generation Reform:Net metering modifications under Secretaría de Energía consultation could unlock commercial rooftop deployment in Guadalajara and Monterrey metropolitan zones.
- Storage Hybridization:Lithium-ion battery pairing with solar farms addresses evening peak demand mismatches, qualifying projects for enhanced clean energy certificate valuations.
Industry Challenges
- Grid Code Compliance Complexity:New inverter synchronization standards from national energy regulator require firmware upgrades and testing protocols that delay commercial operation dates.
- EPC Talent Scarcity:Specialized electrical engineering expertise for utility-scale DC-to-AC conversion and medium-voltage substation integration remains concentrated among a limited contractor pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Solar Photovoltaic (PV) Market |
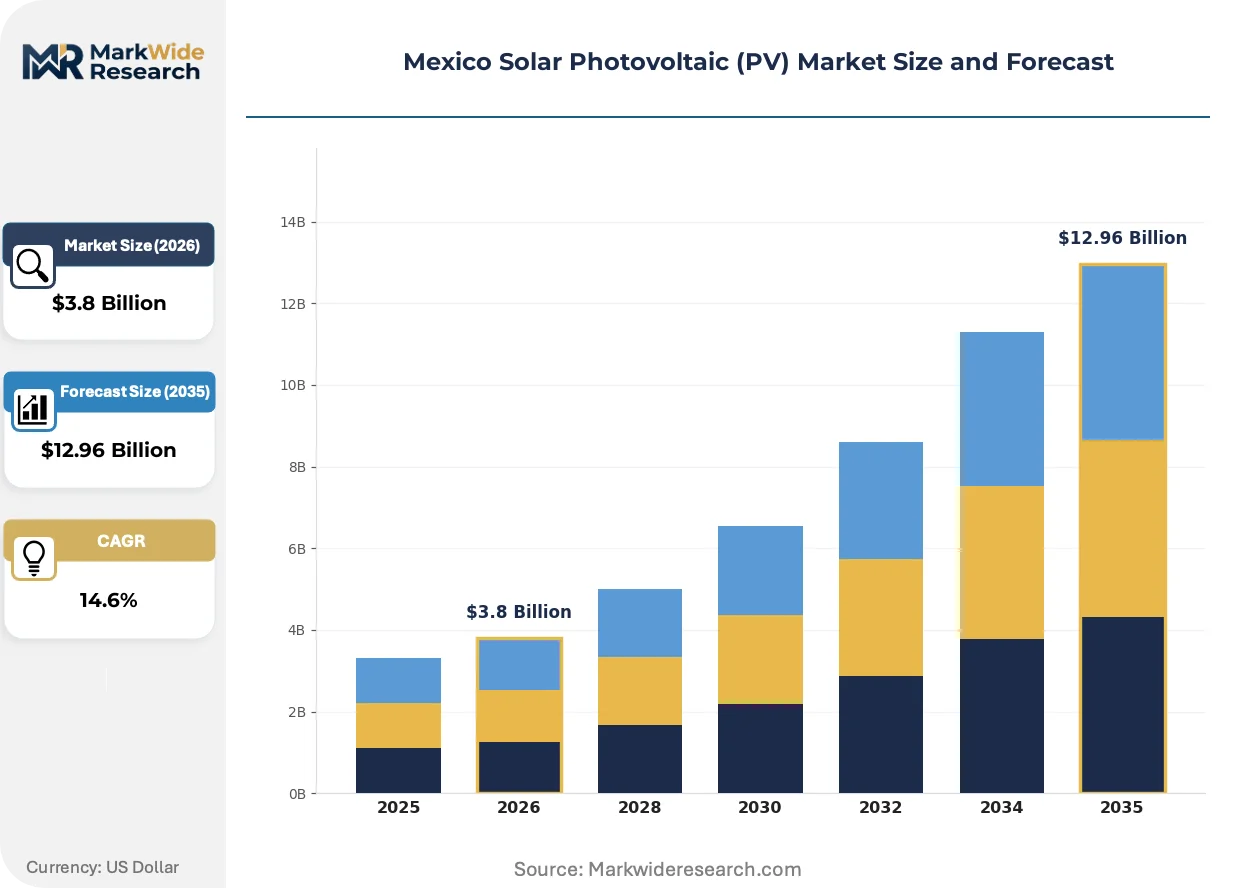
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Installation Type: Ground-Mounted, Rooftop, Building-Integrated, Floating End User: Residential, Commercial, Industrial, Utility Technology: Heterojunction, PERC, Cadmium Telluride, Organic Photovoltaic |
| Companies Covered | Comisión Federal de Electricidad (CFE), Enel Green Power, Iberdrola, Engie, Canadian Solar, Acciona, EDF Renewables, Jinko Solar, JA Solar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Solar Photovoltaic (PV) Market Shifts & Advancements
Digitalization of asset management and module-level power electronics are compressing operational expenditure structures while accelerating performance optimization across Mexico's solar fleet.
Power optimizers and module-level monitoring systems are virtualizing traditional string inverter architectures by enabling granular DC-to-DC conversion at each photovoltaic panel. Large-scale independent power producers in Sonora deploy these electronics to mitigate mismatch losses from soiling and shading across multi-hundred-megawatt arrays. This granular control is virtualizing centralized inverter maintenance schedules, shifting operational models toward predictive analytics and remote firmware diagnostics.
Reforms to Mexico's electricity industry law continue recalibrating market access rules for private generators under joint oversight from Secretaría de Energía and Comisión Federal de Electricidad. Clean energy certificate eligibility criteria and dispatch priority hierarchies remain subject to regulatory interpretation, creating compliance planning uncertainty for project financiers. Developers with advanced-stage pipelines in Baja California and Chihuahua are responding by securing dual-track permitting strategies that accommodate multiple regulatory scenarios.
Corporate power purchase agreements are displacing traditional utility-tendered offtake as the dominant procurement channel for new capacity additions. Multinational manufacturers with operations in Ciudad Juárez and Tijuana now contract directly with solar developers for dedicated clean energy supply, bypassing Comisión Federal de Electricidad intermediation. This direct contracting pattern concentrates most visibly in the automotive and electronics assembly verticals, where Scope 2 emissions targets drive renewable electricity sourcing decisions.
Mexico Solar Photovoltaic (PV) Market Segmentation
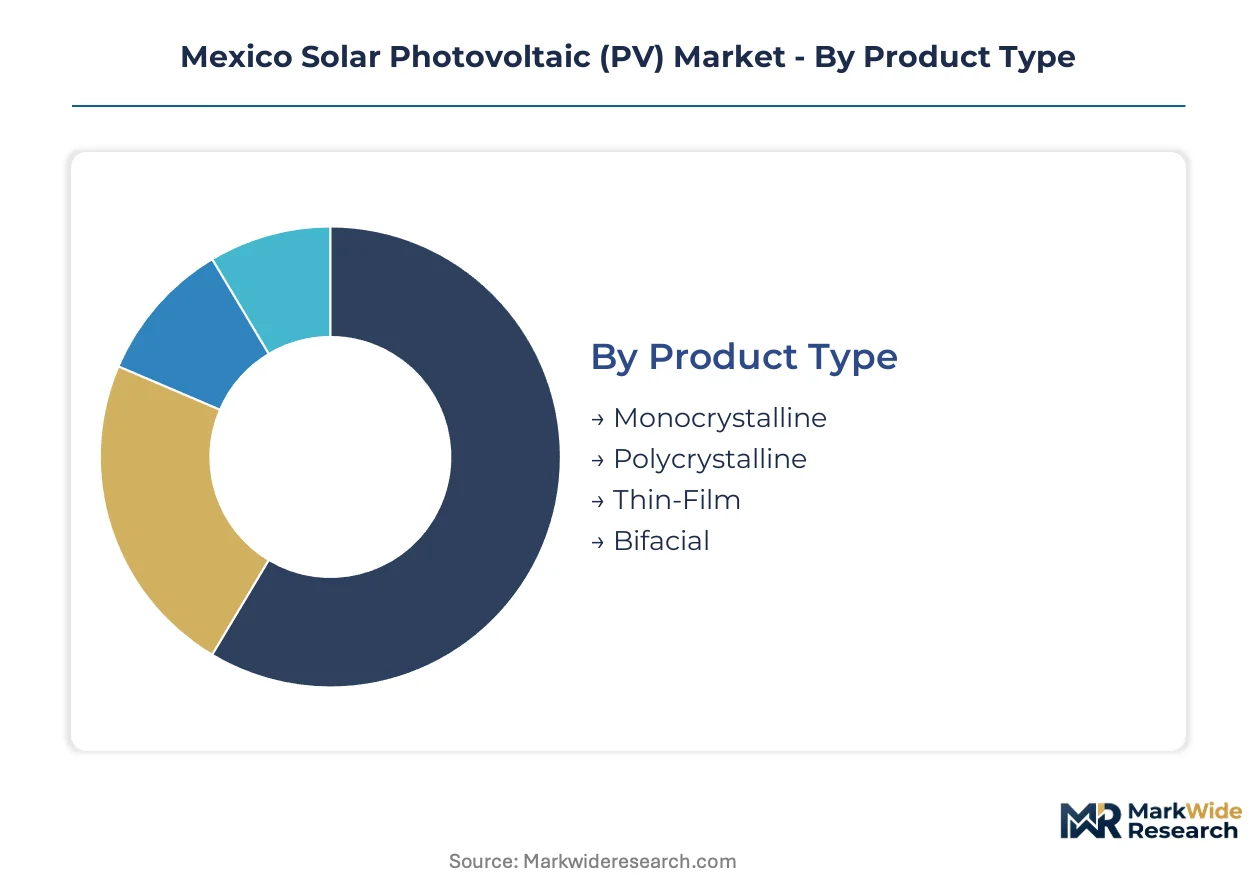
Segmentation across product architecture, mounting configuration, customer scale, and cell technology reveals how module specifications and installation economics align with distinct procurement channels in Mexico's solar market. Each dimension carries different warranty obligations, performance monitoring requirements, and service lifecycle intensity that reshape supplier economics.
Product Type:
After-sales service intensity varies sharply across crystalline and thin-film architectures, with degradation curve monitoring and inverter compatibility support demanding differentiated field engineering resources.
- Monocrystalline:Single-crystal silicon wafers deliver conversion efficiencies above 22% under standard test conditions. Industrial offtakers in Sonora's manufacturing corridor specify these modules for ground-mounted installations where land constraints favor maximum output density per hectare.
- Polycrystalline:Multi-crystalline silicon cells trade marginal efficiency for lower wafer production costs. Distributed generation developers in Guadalajara metropolitan zones deploy these where rooftop space availability reduces the premium on conversion efficiency.
- Thin-Film:Cadmium telluride and amorphous silicon architectures tolerate high-temperature performance degradation better than crystalline alternatives.
- Bifacial:Dual-side energy capture modules exploit albedo reflection from desert surfaces in Mexicali Valley and northern Chihuahua.
Monocrystalline holds the largest share; momentum sits with Bifacial.
Installation Type:
Cost tier stratification separates utility-scale ground arrays from commercial rooftop systems, with balance-of-system expenses and permitting complexity driving divergent capital deployment patterns.
- Ground-Mounted:Fixed-tilt and tracking structures dominate utility-scale deployment across northern Mexico's high-irradiance zones. CFE interconnection queues for these projects extend 18-24 months, compressing developer working capital cycles.
- Rooftop:Commercial and industrial building-integrated systems serve tariff relief objectives in Ciudad Juárez and Tijuana manufacturing clusters. Net metering modifications under SENER consultation could accelerate deployment in Monterrey metropolitan zones.
- Building-Integrated:Architectural photovoltaic facades and canopy structures substitute conventional construction materials while generating electricity.
- Floating:Reservoir-mounted arrays address land-use constraints for agricultural water districts and hydroelectric balancing reservoirs.
Ground-Mounted dominates installed capacity; Rooftop is expanding most quickly.
End User:
Customer type determines offtake contract structures, with utility procurement through CFE tenders diverging sharply from corporate power purchase agreements and net-metered distributed generation.
- Residential:Single-family and multi-unit rooftop systems under 30 kW capacity qualify for net metering credits under current regulatory frameworks. Clean energy certificate eligibility for these installations remains subject to CRE interpretation.
- Commercial:Mid-scale rooftop and carport installations serve retail, logistics, and light manufacturing facilities in Monterrey and Guadalajara. These offtakers seek tariff relief from CFE commercial rate schedules rather than wholesale market participation.
- Industrial:Automotive and electronics assembly verticals in Baja California contract directly with developers for dedicated clean energy supply to meet Scope 2 emissions targets.
- Utility:IPP-developed solar parks sell into CFE-controlled transmission networks or contract through long-term power purchase agreements with qualified offtakers.
Utility commands the greatest megawatt deployment; Industrial shows the steepest expansion trajectory.
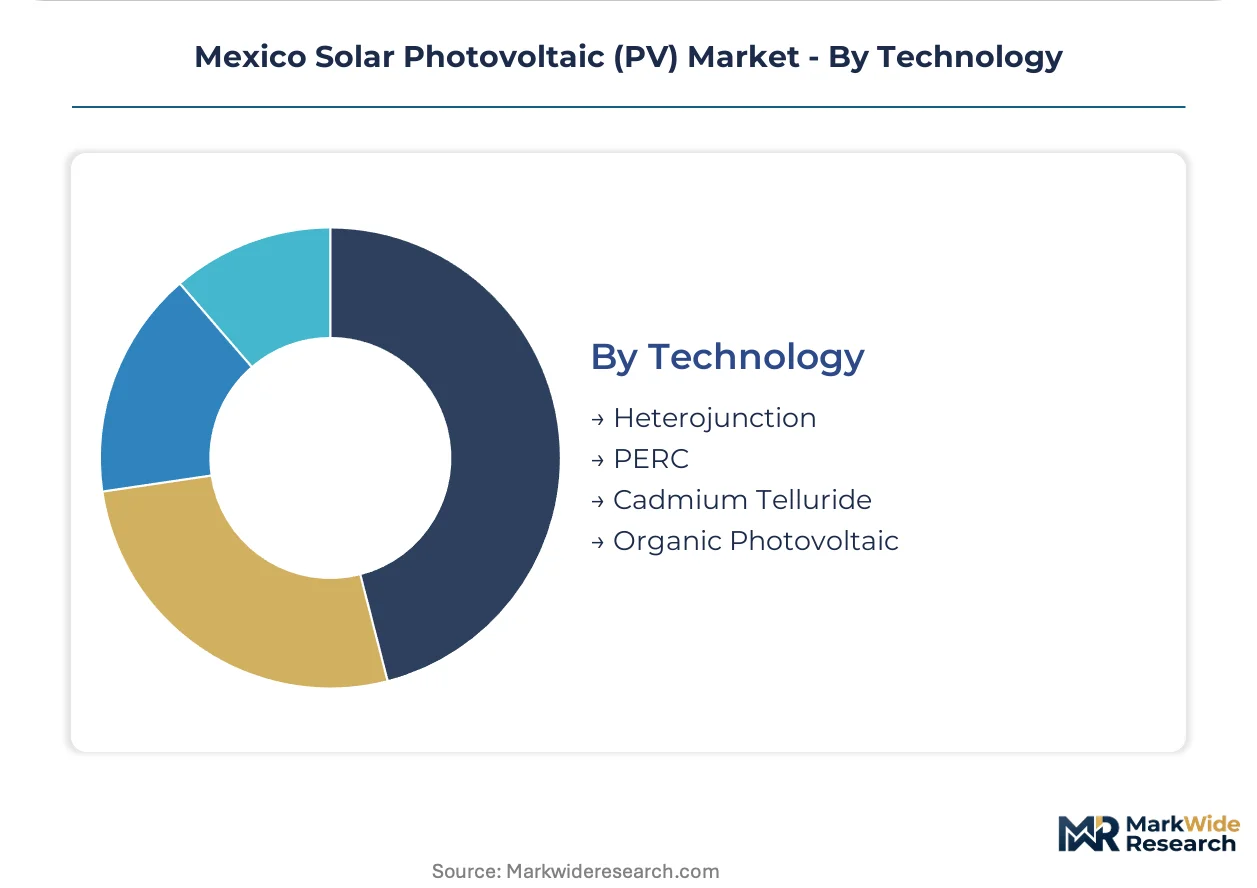
Technology:
Cell architecture maturity separates proven PERC production lines from emerging heterojunction capacity, with manufacturing yield curves and equipment depreciation schedules reshaping module cost positioning.
- Heterojunction:Amorphous silicon layers deposited on crystalline silicon wafers reduce temperature coefficient losses and enable higher bifaciality factors. Equipment capex requirements limit deployment to Tier-1 manufacturers with balance sheet capacity for production line upgrades.
- PERC:Passivated emitter and rear contact architecture dominates current crystalline silicon production with established supply chains and proven field degradation profiles.
- Cadmium Telluride:Thin-film deposition on glass substrates avoids polysilicon input volatility but requires specialized recycling infrastructure for end-of-life module recovery.
- Organic Photovoltaic:Solution-processed semiconductors enable flexible form factors and reduced manufacturing energy intensity.
PERC retains dominant production share; Heterojunction is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Module assembly capacity concentrates in northern Mexico's industrial corridor, where land availability and irradiance profiles attract utility-scale developers. State-level energy agencies and the national regulator jointly shape interconnection timelines across sub-regional markets.
Northern Border States
Sonora, Chihuahua, and Baja California host the majority of ground-mounted capacity additions. The Comisión Reguladora de Energía processes interconnection permits for projects feeding into the Comisión Federal de Electricidad transmission network. Manufacturing clusters in Ciudad Juárez and Tijuana drive corporate power purchase agreement demand from automotive and electronics assemblers.
Nuevo León
Monterrey's metropolitan zone anchors commercial rooftop deployment for tariff relief. The Secretaría de Energía's distributed generation consultation could expand net metering eligibility for mid-scale installations. Industrial parks in Apodaca and Santa Catarina specify monocrystalline systems to maximize output density on constrained warehouse roofs.
Jalisco
Guadalajara's logistics and light manufacturing base sustains steady distributed generation growth. State environmental permitting aligns with federal clean energy certificate frameworks to qualify installations for compliance credits. The El Salto industrial corridor concentrates developer activity for commercial-scale carport and rooftop arrays.
Bajío Region
Guanajuato and Querétaro assemble automotive components under renewable electricity sourcing mandates. Clean energy certificate procurement thresholds under Mexico's electricity industry law obligate large consumers to contract solar supply. Silao and Irapuato industrial zones attract independent power producer development for direct corporate offtake.
Mexico City Metro
The capital's constrained land availability limits utility-scale development to peripheral municipalities. Regulatory clarity from the Comisión Reguladora de Energía on transmission priority remains pending for projects in Estado de México and Hidalgo. Toluca and Cuautitlán industrial corridors represent emerging targets for distributed generation developers.
Mexico Solar Photovoltaic (PV) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on margin capture. The vendor base stratifies between utility-scale independent power producers with development-to-generation capabilities and module manufacturers competing on cost positioning. Two archetypes dominate: integrated energy conglomerates leveraging balance sheet scale, and pure-play solar specialists concentrating on EPC execution and technology selection. Competitive moves center on securing long-term power purchase agreements and calibrating module procurement strategies against polysilicon input volatility.
Among integrated energy groups, Enel Green Power and Iberdrola exemplify the development-to-generation archetype with multi-state operational footprints. Jinko Solar occupies a position as a module cost leader for utility-scale tender participation. These three entities represent distinct competitive vectors: integrated utility platforms, European-headquartered renewable developers, and Chinese-manufacturing-anchored module suppliers.
| Leading Market Players |
|---|
| Comisión Federal de Electricidad (CFE) |
| Enel Green Power |
| Iberdrola |
| Engie |
| Canadian Solar |
| Acciona |
| EDF Renewables |
| Jinko Solar |
| JA Solar |
| Others |
Supply & Pricing Matrix
Polysilicon input volatility from Chinese metallurgical-grade silicon suppliers compresses module assembler margins while simultaneously widening pricing spreads between Tier-1 manufacturers with long-term supply contracts and domestic assemblers exposed to spot market swings. This feedstock dependency anchors both the cost structure of crystalline silicon modules and the geographic configuration of Mexico's photovoltaic supply chain.
Pricing Analysis
Mexico's electricity industry law dictates the pricing tier structure for utility-scale solar procurement, separating premium-priced projects with secured clean energy certificate eligibility from standard-tier developments facing regulatory uncertainty and economy-tier distributed generation systems competing on pure tariff relief. Price differentiation hinges on certification grade for CFE interconnection priority and volume scale in module procurement, with industrial offtakers in Ciudad Juárez and Tijuana exhibiting highest price sensitivity due to thin manufacturing margins. Cost compression in the standard tier is intensifying because of permitting timeline extensions and transmission queue backlogs.
Supply Chain Analysis
Metallurgical-grade silicon feedstock draws primarily from China, with secondary sourcing from Germany and Norway for high-purity polysilicon used in monocrystalline wafer production. Module assembly rests on silver paste for cell metallization, aluminum frames from extrusion facilities, and tempered glass from float-glass manufacturers. Single-source vulnerability concentrates in Chinese polysilicon refining capacity, where export license restrictions or tariff escalations could disrupt input costs. Distribution runs through Enel Green Power and Iberdrola development platforms for utility-scale deployment, while commercial rooftop channels leverage regional EPC contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against combined-cycle natural gas generation, which retains dispatch priority under CFE network management and threatens to displace solar capacity additions if regulatory clarity on clean energy certificates erodes.
For Market Incumbents: Entrench interconnection queue position through advance permitting deposits with the Comisión Reguladora de Energía, securing priority access ahead of pipeline competitors. Anchor module procurement through backward integration into polysilicon offtake agreements with Chinese suppliers, insulating margin structures from spot price volatility that threatens domestic assemblers lacking contract coverage.
For New Entrants and Emerging Players: Build out distributed generation capabilities in Guadalajara and Monterrey metropolitan zones, where net metering reform under Secretaría de Energía consultation could unlock commercial rooftop deployment faster than utility-scale queue positions. Target automotive and electronics assembly verticals with direct corporate power purchase agreement structures, bypassing CFE intermediation and capturing Scope 2 emissions-driven procurement mandates.
For Investors and Strategic Acquirers: Independent power producers with advanced-stage pipelines in Baja California and Sonora present acquisition targets with de-risked permitting and secured land positions. Long-term viability hinges on regulatory clarity for clean energy certificate valuations across the projection horizon. Monitor Secretaría de Energía policy announcements as the primary inflection indicator for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Securement | Long-term offtake contracts with CFE or qualified private consumers de-risk project finance structures. |
| Backward Integration into Polysilicon | Long-term supply agreements with Chinese metallurgical-grade silicon suppliers stabilize module input costs. |
| Bifacial Technology Licensing | Dual-side yield modules from Jinko Solar and JA Solar capture albedo gains in Mexicali Valley deployments. |
| Storage Hybridization Development | Lithium-ion battery pairing with solar farms addresses evening peak demand mismatches for CFE network balancing. |
| Clean Energy Certification Program | CRE eligibility documentation qualifies installations for mandatory procurement thresholds under electricity industry law. |
Research Methodology
Desk research of EIA international energy statistics, IEA renewable energy market reports, and Secretaría de Energía regulatory filings preceded structured interviews with IPP project developers, EPC contractors, CFE interconnection planners, and corporate energy procurement officers at manufacturing facilities. Secondary validation drew from Comisión Reguladora de Energía permit databases, customs import records for photovoltaic module shipments, and developer pipeline tracking services. Bottom-up project-level capacity aggregation was cross-checked against top-down national renewable energy targets.
Fixed assumptions across the modeling period include continuation of Mexico's electricity industry law framework, stable polysilicon supply from Chinese sources, and CFE transmission expansion timelines for northern corridor capacity. Segmentation dimensions modeled encompass installation type, end-user category, cell technology architecture, and regional grid zone. CAGRs were derived from capacity deployment trajectories and module cost curve projections. Forecast inputs incorporated bifacial technology penetration rates and corporate power purchase agreement procurement shifts.
Stress conditions across polysilicon price volatility bands, regulatory reversal scenarios for clean energy certificates, and CFE dispatch priority changes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions with acknowledged sensitivity to Secretaría de Energía policy evolution. Cross-checking against IEA Mexico energy outlook benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Australia Rooftop Solar Market
Solar Power Systems
United Arab Emirates Solar Energy Market
Solar Power Systems
India Solar Inverter Market
Solar Power Systems
Solar Flower Market
Solar Power Systems
Mexico Solar Energy Market
Solar Power Systems
Solar Cell Busbar Market
Solar Power Systems
Greece Solar Energy Market
Solar Power Systems
US Solar Power Meters Market
Solar Power Systems
Solar Photovoltaic (PV) Panel Market
Solar Power Systems
US Solar Carport Market
Solar Power Systems
Solar PV Tracker Market
Solar Power Systems
Solar Power Meters Market
Solar Power Systems
Asia-Pacific Solar Blanket Market
Solar Power Systems
Bifacial Solar Panels Market
Solar Power Systems
United Kingdom Solar Power Market
Solar Power Systems
Egypt Solar Photovoltaic (PV) Market