
 DSC Solar Technologies Market | 2026-2036
DSC Solar Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
DSC Solar Technologies Market Analysis
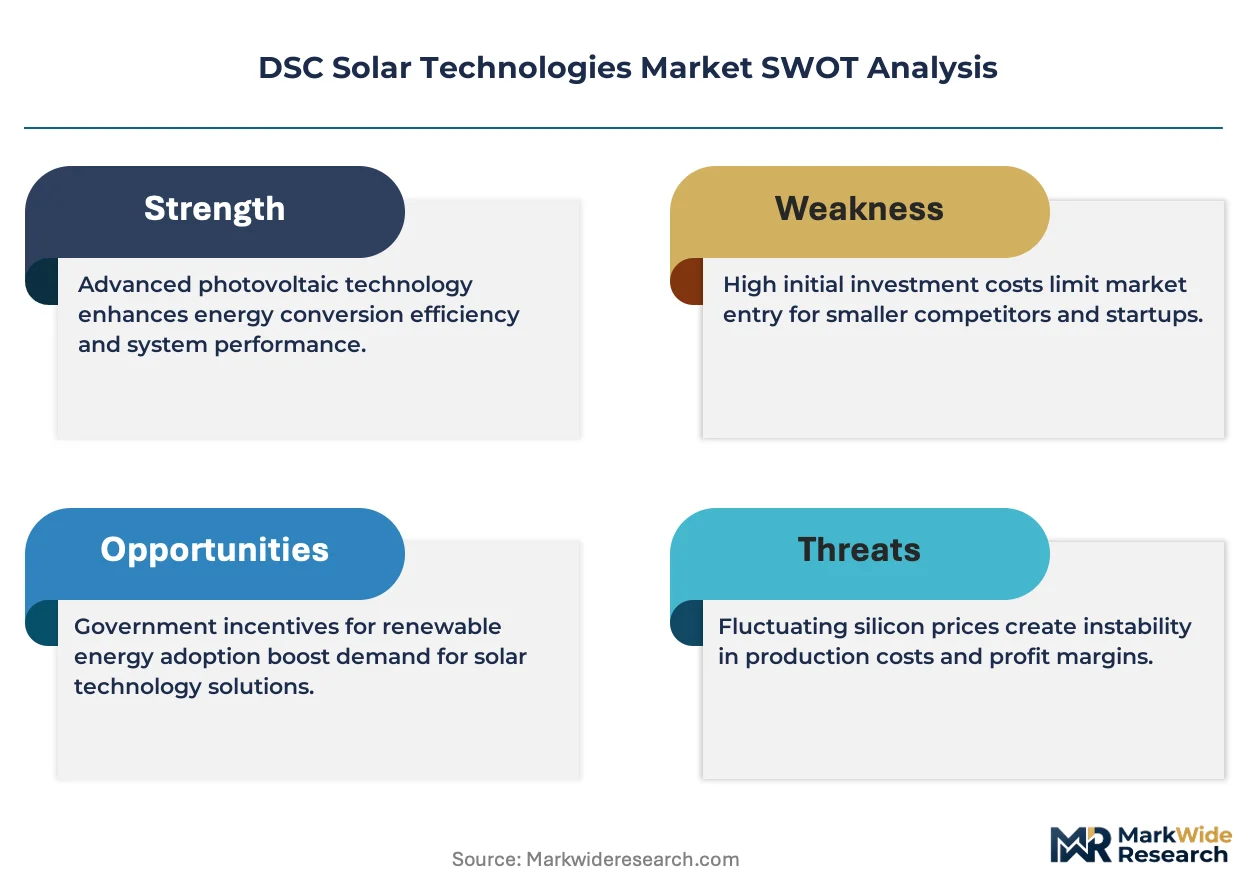
Perovskite-silicon tandem cell development is narrowing the efficiency gap between dye-sensitized solar technologies and conventional crystalline silicon modules. Prysmian Group leverages its cable and interconnection expertise to anchor utility-scale project supply chains across Southern Europe. Nexans competes through specialized high-voltage cabling systems that integrate with advanced photovoltaic arrays. Jiangsu Baosheng Photovoltaic Technology dominates domestic manufacturing scale for balance-of-system components serving Asian markets.
DSC Solar Technologies encompass photovoltaic systems utilizing dye-sensitized cells where organic dyes adsorbed onto titanium dioxide nanoparticles convert visible light into electrical current, typically achieving 10-14% laboratory efficiency through liquid or solid-state electrolyte architectures. These systems serve building-integrated photovoltaics and low-light indoor applications where conventional silicon underperforms. Bifacial technology leads commercial deployment by capturing reflected irradiance on both cell surfaces, while thin-film segments sustain margin pools through reduced material intensity and flexible substrate compatibility. Residential application growth concentrates in distributed generation markets where aesthetic integration and partial shading tolerance outweigh absolute efficiency metrics.
FERC interconnection standards in the United States shape grid-access timelines for utility-scale DSC installations, while the EU Green Deal's renewable energy directives mandate building-integrated photovoltaic adoption across member states. REACH compliance requirements from ECHA govern dye and electrolyte chemical compositions entering European markets, creating formulation barriers for non-compliant suppliers. Stakeholders must monitor evolving perovskite stability certifications and solid-state electrolyte manufacturing yields to capture emerging commercial opportunities.
Market Dynamics
Perovskite-silicon tandem architectures are compressing the efficiency penalty that historically relegated DSC systems to niche applications, forcing incumbent suppliers to reposition around building-integrated and low-light deployment scenarios where silicon underperforms.
Growth Catalysts
- Saudi Arabia's National Renewable Energy Program:Gigawatt-scale tendering creates anchor demand for utility-scale DSC installations across the Middle East, pulling supply chain investment into the region.
- EU Green Deal building mandates:Member state directives requiring photovoltaic integration on new commercial structures expand addressable surface area for aesthetic-sensitive DSC products.
- Solid-state electrolyte advances:Manufacturing yield improvements in quasi-solid architectures reduce degradation rates and unlock extended warranty terms for commercial projects.
Market Restraints
- Ruthenium dye supply concentration:Precursor chemical production clusters in a limited set of Asian refiners, exposing module assemblers to input volatility and geopolitical transit risk.
- REACH formulation barriers:ECHA compliance requirements for organic electrolyte compositions block non-certified suppliers from European procurement channels.
- Crystalline silicon cost floor:Conventional module pricing at utility scale maintains a structural cost advantage that DSC systems cannot match in high-irradiance environments.
Strategic Opportunities
- Indoor IoT power harvesting:Low-light efficiency in artificial illumination environments opens consumer electronics and warehouse automation sensor networks as untapped verticals.
- FERC interconnection standardization:Clarified grid-access timelines for distributed generation in the United States reduce project development risk and accelerate utility-scale deployment pipelines.
- Flexible substrate convergence:Roll-to-roll manufacturing compatibility with polymer backplanes enables architectural integration on curved surfaces inaccessible to rigid silicon panels.
Industry Challenges
- Perovskite stability certification timelines:Extended IEC testing protocols for tandem architectures delay product qualification and compress commercialization windows.
- Electrolyte formulation talent scarcity:Specialized organic chemistry expertise for dye-sensitized systems concentrates in academic rather than industrial labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DSC Solar Technologies Market |
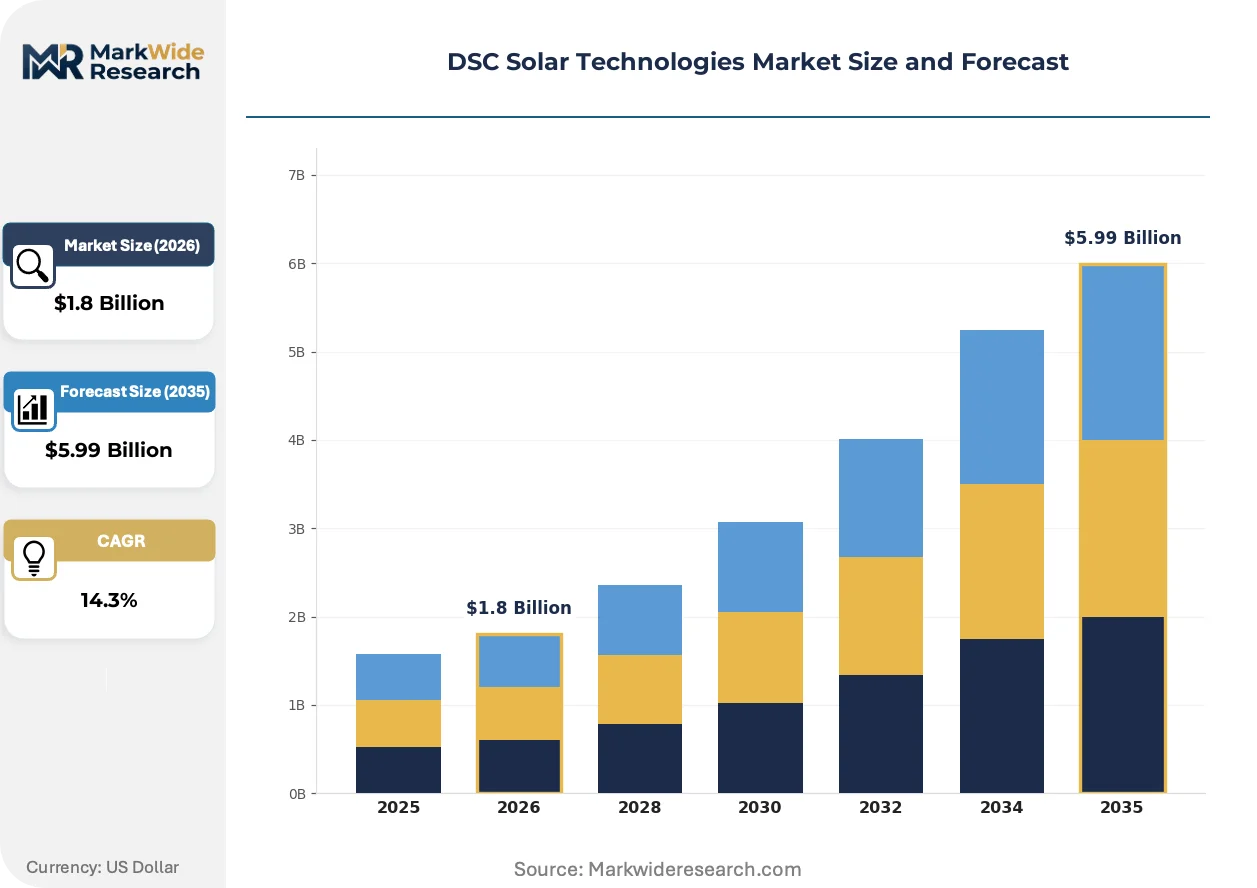
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Panels, Inverters, Storage Systems, Racking Systems Application: Residential, Commercial, Industrial, Off-grid Technology: Monocrystalline, Polycrystalline, Thin-Film, Bifacial End User: Utilities, Businesses, Homeowners, Government |
| Companies Covered | Shanghai Kuka Cable, Jiangsu Baosheng Photovoltaic Technology, Prysmian Group, Nassau National Cable, Helukabel, Nexans, Henan Safewire Cable Group, Priority Wire & Cable, SUNKEAN Cable, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DSC Solar Technologies Market Emerging Trajectories
Active materials research and regulatory harmonization are converging to expand DSC applicability beyond traditional efficiency-constrained deployment scenarios into architectural and ambient energy harvesting domains.
Perovskite-silicon tandem cell architectures combine the visible-light absorption strengths of organic dyes with silicon's infrared response to push laboratory efficiencies toward 30%. European module integrators are piloting these stacks in building-integrated facades where aesthetic constraints prohibit conventional panels. This convergence is digitizing the performance benchmarking protocols that previously separated DSC from mainstream procurement specifications.
REACH chemical registration requirements from ECHA now govern electrolyte solvent classifications and dye precursor hazard categories entering European markets. Formulators must redesign liquid electrolyte compositions to meet restricted substance thresholds or exit the region entirely. Southern European project developers are accelerating solid-state electrolyte qualification to preempt compliance-driven supply interruptions.
Building-integrated photovoltaic procurement is fragmenting across aesthetic performance tiers rather than pure cost-per-watt metrics. Architects and facade engineers in Germany and the Netherlands now specify semi-transparent DSC modules for atrium and curtainwall applications where silicon cannot compete. This specification shift is compressing traditional distributor channels as direct manufacturer-to-developer relationships displace wholesale intermediaries in premium building segments.
DSC Solar Technologies Market Segmentation
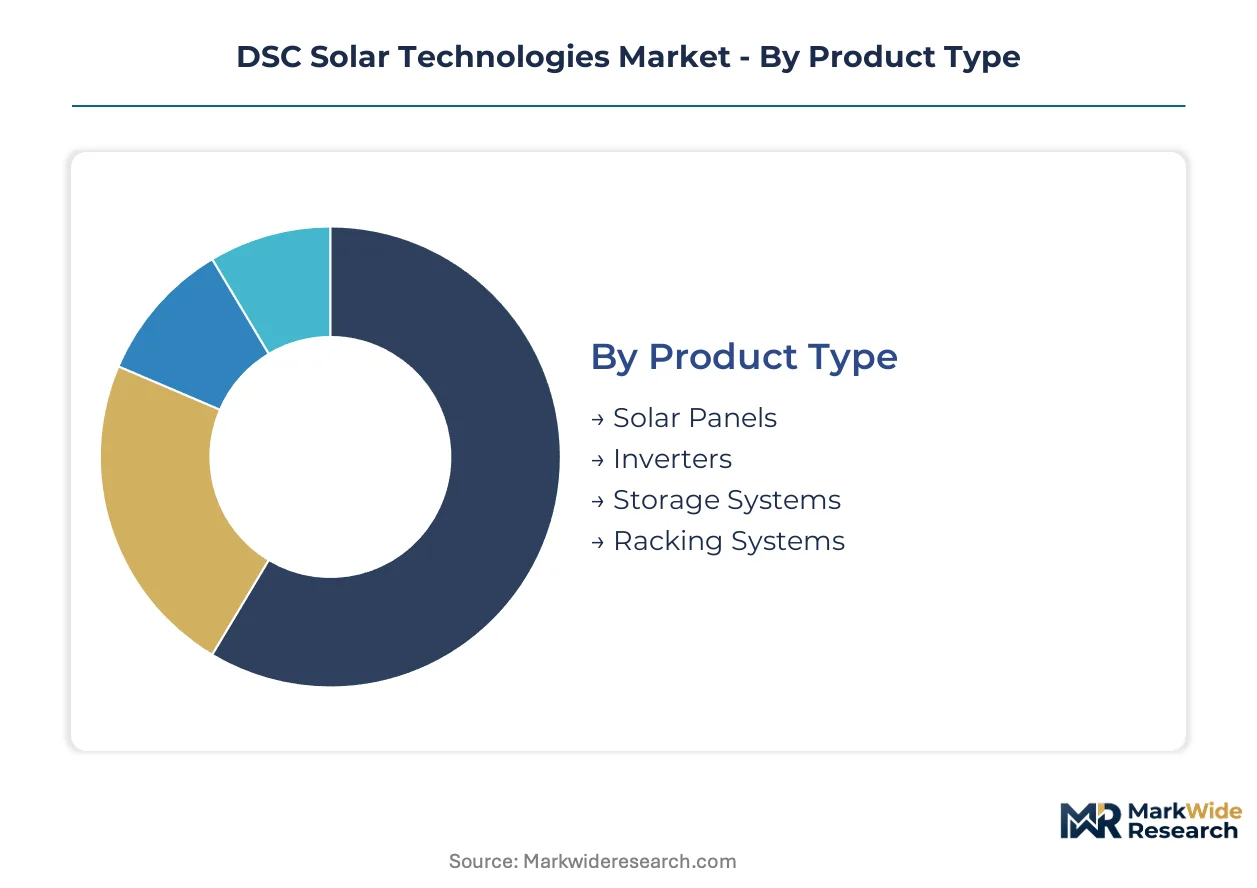
DSC Solar Technologies fragment across hardware hierarchies, deployment contexts, and customer procurement patterns. Each dimension shapes margin structures and competitive positioning differently.
Product Type:
Cost tiers separate mature commodity hardware from emerging premium components where technology differentiation commands pricing power.
- Solar Panels:DSC modules utilize titanium dioxide nanoparticle substrates with organic dye absorbers, achieving 10-14% efficiency in standard test conditions. Demand concentrates in Saudi Arabia's gigawatt-scale tenders under the national renewable energy program, where utility-scale procurement prioritizes volume availability over peak efficiency metrics.
- Inverters:Power electronics convert variable DC output from dye-sensitized arrays into grid-synchronous AC, with string architectures dominating distributed generation and central inverters anchoring utility installations. European project developers favor transformerless designs that reduce balance-of-system costs in building-integrated deployments subject to EU Green Deal mandates.
- Storage Systems:Lithium-ion battery integration addresses intermittency in off-grid DSC arrays.
- Racking Systems:Structural mounting hardware adapts to flexible polymer substrates unique to thin-film DSC architectures.
Solar panels command the established base. The steepest expansion runs through storage systems.
Application:
Deployment volume clusters around customer scale and grid connectivity requirements.
- Residential:Distributed generation installations prioritize aesthetic integration and partial shading tolerance over absolute efficiency. Demand concentrates in German and Dutch urban markets where building-integrated facades face strict architectural review, with semi-transparent DSC modules specified for atrium and curtainwall applications where silicon cannot compete.
- Commercial:Mid-scale rooftop and carport deployments balance energy yield with structural load constraints. Procurement in the United States accelerates following FERC interconnection standardization that clarifies grid-access timelines and reduces project development risk.
- Industrial:Large onsite generation for manufacturing facilities.
- Off-grid:Remote power applications leverage DSC low-light performance advantages.
Commercial applications command the established base. Residential deployment is climbing the fastest.
Technology:
Cell architecture determines efficiency ceilings and manufacturing capital intensity.
- Monocrystalline:Single-crystal silicon substrates achieve highest commercial efficiencies but compete directly with conventional PV rather than differentiated DSC positioning.
- Polycrystalline:Multi-crystal silicon offers cost advantages in high-irradiance utility environments where DSC systems face structural cost disadvantages.
- Thin-Film:Roll-to-roll manufacturing compatibility with polymer backplanes enables curved surface integration inaccessible to rigid panels. Demand concentrates in building-integrated segments across Southern Europe where architectural flexibility outweighs efficiency penalties.
- Bifacial:Dual-surface light capture captures reflected irradiance, extending yield in high-albedo environments. Saudi Arabian desert installations exploit this architecture to maximize energy density in gigawatt-scale project footprints.
Thin-film technology commands the established base. Bifacial architectures are gaining share fastest.
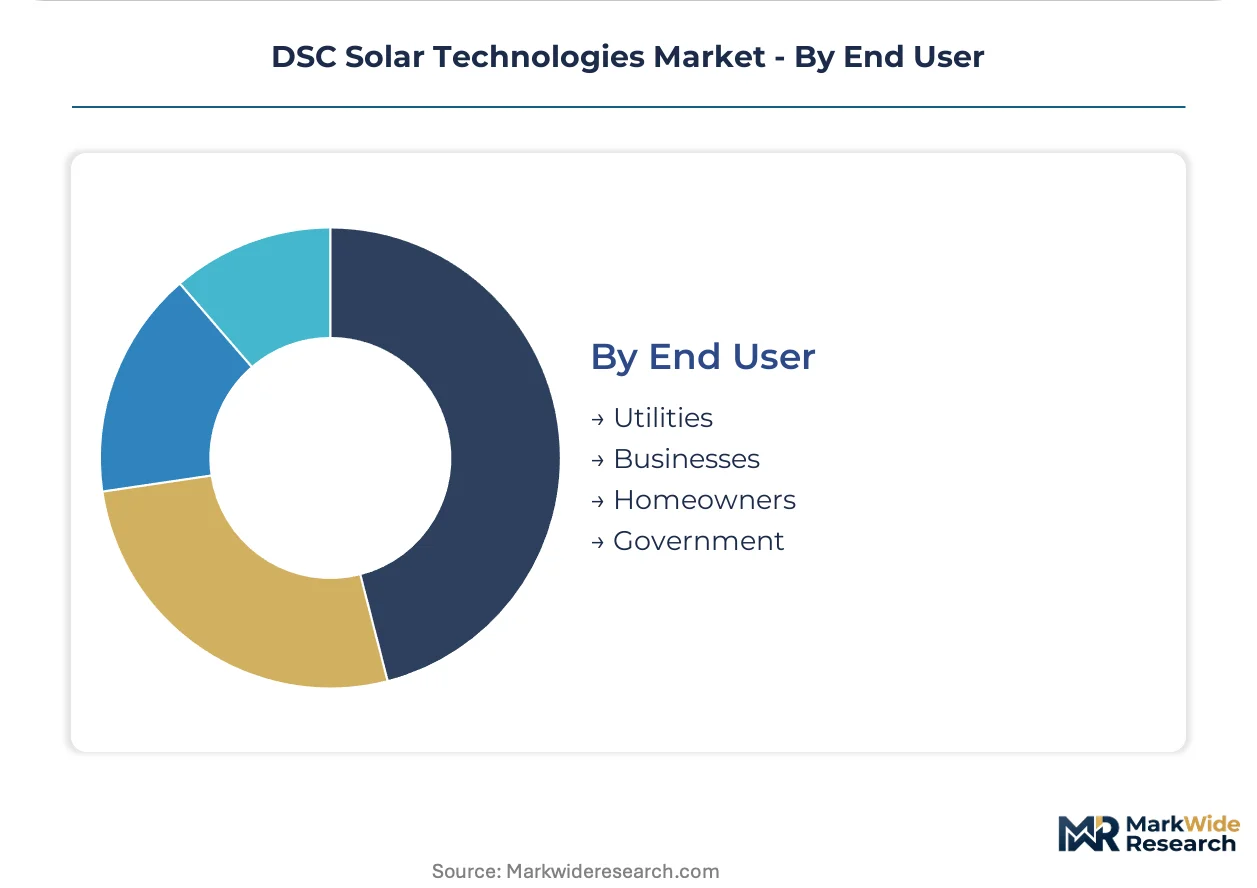
End User:
Procurement authority and capital access separate volume buyers from price-sensitive retail segments.
- Utilities:Centralized procurement of gigawatt-scale generation assets drives supply chain localization. Saudi Arabia's national renewable energy program anchors regional demand, pulling manufacturing investment into Middle Eastern production corridors.
- Businesses:Commercial and industrial offtakers prioritize corporate sustainability targets and energy cost hedging. EU Green Deal directives mandate photovoltaic integration on new commercial structures, expanding addressable surface area across member states.
- Homeowners:Distributed generation decisions balance upfront capital against aesthetic and shading constraints.
- Government:Public procurement supports demonstration projects and rural electrification programs.
Utilities command the established base. Business procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cable manufacturers export specialized high-voltage interconnection systems to Saudi Arabian gigawatt-scale solar installations, anchoring a trade corridor that pulls European supply chain investment into Middle Eastern production corridors.
Saudi Arabia
Gigawatt-scale tendering under the National Renewable Energy Program creates anchor demand for utility-scale DSC installations. The country's central renewable energy regulator mandates local content requirements that pull manufacturing investment into domestic production corridors. Riyadh-based project developers coordinate desert installations exploiting bifacial architectures to maximize energy density in high-albedo environments.
Germany
EU Green Deal building mandates require photovoltaic integration on new commercial structures, expanding addressable surface area for aesthetic-sensitive DSC products. ECHA REACH compliance requirements govern dye and electrolyte chemical compositions entering European markets. Munich and Stuttgart industrial clusters host facade engineering firms specifying semi-transparent DSC modules for atrium applications where silicon cannot compete.
United States
FERC interconnection standardization clarifies grid-access timelines for distributed generation, reducing project development risk and accelerating commercial deployment pipelines. The Federal Energy Regulatory Commission shapes utility-scale installation permitting through standardized interconnection protocols. California and Texas project developers concentrate procurement authority for mid-scale rooftop and carport deployments balancing energy yield with structural load constraints.
China
Domestic manufacturing scale for balance-of-system components serves Asian markets through roll-to-roll production compatibility with polymer backplanes. The country's national standards administration governs GB certification requirements for photovoltaic component exports. Jiangsu province industrial corridors concentrate precursor chemical production for ruthenium dye formulations, exposing module assemblers to input volatility and geopolitical transit risk.
Netherlands
Architectural procurement in Germany and Dutch urban markets specifies semi-transparent DSC modules for curtainwall applications where silicon cannot compete. The EU Green Deal's renewable energy directives mandate building-integrated photovoltaic adoption across member states. Eindhoven-based facade engineering clusters digitize performance benchmarking protocols that previously separated DSC from mainstream procurement specifications.
DSC Solar Technologies Market Vendor Landscape
On the supply side, the industry is consolidating around cable and interconnection specialists that anchor utility-scale project supply chains across multiple geographies. Tiered competitive positioning separates premium high-voltage system integrators from commodity balance-of-system component fabricators. Three strategic archetypes dominate: European cable conglomerates with project finance relationships, Chinese manufacturers with domestic scale advantages, and specialized photovoltaic interconnection firms with solid-state electrolyte formulation capabilities. Competitive moves concentrate on strategic partnerships with EPC contractors and backward integration into dye precursor chemical production.
Among European cable specialists, Prysmian Group and Nexans occupy positions as premium-tier system integrators leveraging project finance relationships across Southern European and Middle Eastern markets. Jiangsu Baosheng Photovoltaic Technology exemplifies the scale-driven Chinese manufacturing archetype, representing domestic production gravity for balance-of-system components serving Asian procurement channels. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without guaranteeing technology leadership or segment exclusivity.
| Leading Market Players |
|---|
| Shanghai Kuka Cable |
| Jiangsu Baosheng Photovoltaic Technology |
| Prysmian Group |
| Nassau National Cable |
| Helukabel |
| Nexans |
| Henan Safewire Cable Group |
| Priority Wire & Cable |
| SUNKEAN Cable |
| Others |
Supply Flow & Price Mechanics
Ruthenium dye supply concentration in Jiangsu province exposes module assemblers to input volatility that widens pricing spreads between certified European suppliers and Asian commodity producers while compressing margins for non-integrated formulators lacking captive precursor production.
Pricing Analysis
The current-generation liquid electrolyte architecture, prior-generation solid-state pilot lines, and next-generation perovskite-silicon tandem stacks each occupy distinct pricing tiers. Project-based long-term offtake contracts dominate utility-scale procurement in Saudi Arabia, while spot purchasing persists for laboratory-scale dye quantities. Price differentiation rests on ECHA REACH certification status and volume scale, with compliant European suppliers commanding premiums over uncertified Asian competitors. Pricing pressure stems from crystalline silicon cost compression in high-irradiance environments, squeezing DSC margins in utility-scale tenders. Business procurement through EPC contractors shows lowest price sensitivity, while residential distributed generation buyers prioritize aesthetic performance over per-watt economics.
Supply Chain Analysis
Contract manufacturing capacity for DSC modules clusters with Jiangsu Baosheng Photovoltaic Technology and select European facade engineering specialists serving building-integrated segments. Geographic supply concentration centers on China for titanium dioxide nanoparticle substrates and ruthenium dye precursors, Germany for high-voltage cabling and interconnection systems, and Saudi Arabia for emerging utility-scale assembly. Raw material dependencies include ruthenium metal from platinum group metal refiners, organic electrolyte solvents from petrochemical complexes, and polymer backplane substrates from specialty film producers. Single-source vulnerability in ruthenium dye precursor production creates supply chain risk. Distribution runs through direct manufacturer-to-developer relationships in premium building segments, displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized organic chemistry expertise for dye-sensitized systems concentrates in academic rather than industrial labor pools, creating a persistent talent gap that constrains formulation innovation and solid-state electrolyte manufacturing scale-up.
For Market Incumbents: Insulate core margins by securing backward integration into ruthenium dye precursor production and accelerating solid-state electrolyte qualification to preempt REACH-driven supply interruptions. Prysmian Group and Nexans should deepen project finance relationships across Middle Eastern utility-scale pipelines to anchor interconnection supply chains against emerging Chinese competitors. For New Entrants and Emerging Players: Pursue indoor IoT power harvesting applications where low-light efficiency in artificial illumination environments remains underexploited by established suppliers. Warehouse automation sensor networks and consumer electronics represent penetrable verticals lacking incumbent specialization. A go-to-market angle targeting direct partnerships with building automation integrators bypasses traditional photovoltaic distributor channels. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors acquisition targets with solid-state electrolyte formulation capabilities and existing ECHA REACH certifications. Long-term viability hinges on perovskite-silicon tandem commercialization timelines and stability certification completion. The signal to watch is IEC testing protocol acceleration for tandem architectures as an inflection indicator for product qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Electrolyte Scale-Up | Manufacturing yield improvements unlock extended warranty terms for commercial DSC projects. |
| Perovskite-Silicon Tandem Development | Laboratory efficiency gains toward 30% narrow competitive gaps with conventional silicon modules. |
| REACH Compliance Investment | ECHA certification barriers block non-compliant suppliers from European procurement channels entirely. |
| Backward Integration into Dye Precursors | Captive ruthenium supply reduces exposure to Jiangsu province production volatility and transit risk. |
| Building-Integrated Facade Partnerships | Direct manufacturer-to-developer relationships displace wholesale intermediaries in premium architectural segments. |
Methodological Framework
A spread of perspectives from EPC contractors, facade engineering firms, utility planning officers, and dye precursor chemical suppliers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with project developers in Saudi Arabia and Germany alongside secondary validation through FERC interconnection filings, ECHA REACH registration databases, and EU Green Deal directive implementation records. Bottom-up segmentation modeling triangulated against top-down market sizing from trade flow data and national renewable energy program tender announcements.
Demand-supply-balance framing anchored the forecast framework across the analysis window, modeling capacity expansion against gigawatt-scale procurement pipelines. Segmentation dimensions included technology generation, application scale, and regional regulatory framework. CAGRs were derived from slope analysis of historical deployment trajectories adjusted for policy acceleration effects. Industry-specific inputs incorporated solid-state electrolyte manufacturing yield curves and perovskite stability certification timelines.
Sensitivities concentrate around ruthenium supply disruptions, REACH formulation reclassifications, and crystalline silicon pricing floors that could compress DSC commercialization windows. Forecasts reflect documented assumptions on technology substitution rates and policy implementation cadence. Quarterly review of IEC testing protocol progress and ECHA substance restriction proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Shingles Market
Solar Power Systems
Organic PV Solar Cells Market
Solar Power Systems
Solar Cell Films Market
Solar Power Systems
Grid-Connected Solar Microinverter Market
Solar Power Systems
Indonesia Renewable Energy Market
Solar Power Systems
Solar Panel Glass Market
Solar Power Systems
Printable Solar Cells Market
Solar Power Systems
PV Array Combiner Box Sales Market
Solar Power Systems
Europe Solar Charging Station Market
Solar Power Systems
Saudi Arabia Solar PV Module Market
Solar Power Systems
North America Solar Photovoltaic (PV) Market
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
Perovskite Solar Cell Market
Solar Power Systems
Austria Solar Energy Market
Solar Power Systems
Outdoor Solar LED Market
Solar Power Systems
India Solar Energy Market