
 Solar Cells Market | 2026-2036
Solar Cells Market Size, Share, and Industry Trends Forecast 2026-2036
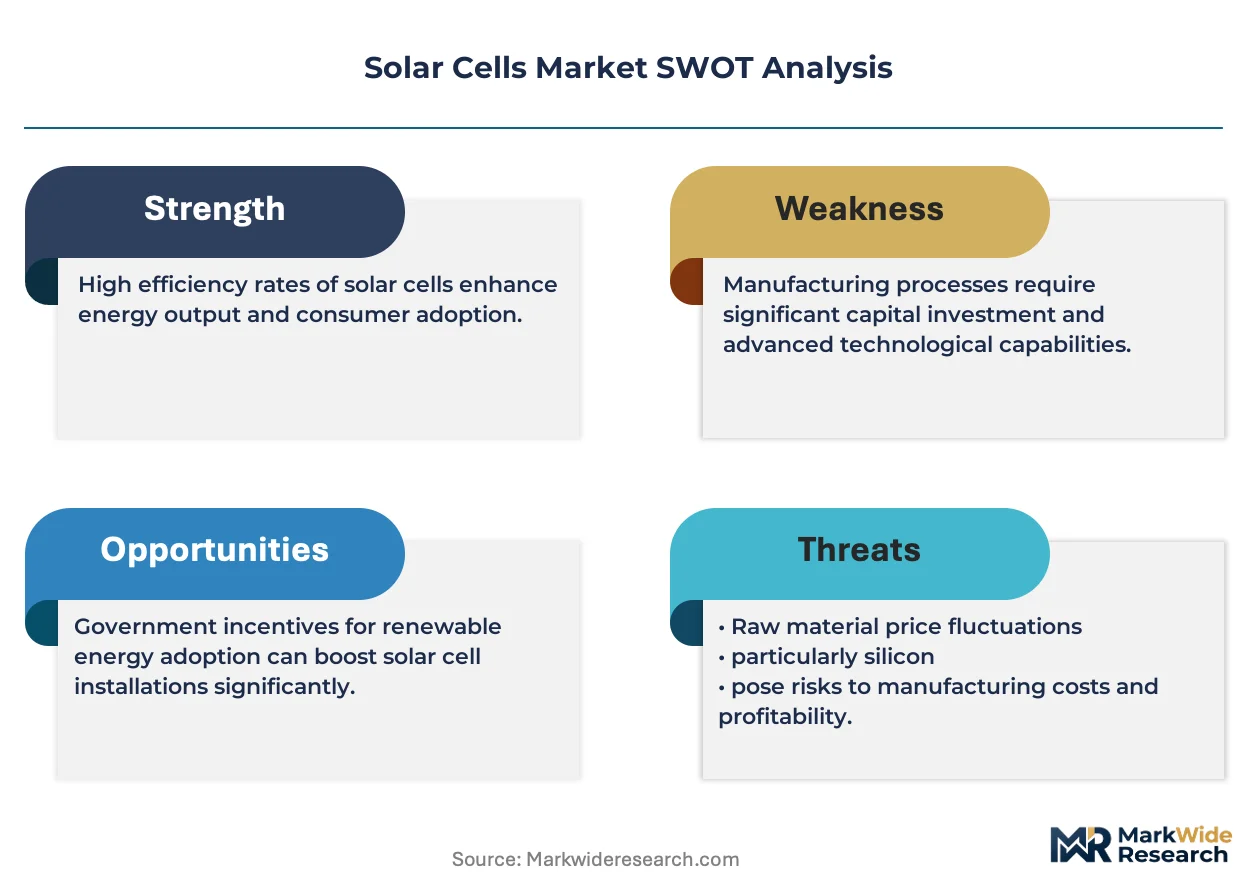
Solar Cells Market Analysis
The EU Green Deal's renewable energy targets is shifting procurement timelines across European utilities. LONGi Green Energy anchors wafer supply through in-house silicon purification and mono-crystalline pulling capacity. First Solar competes through cadmium telluride thin-film technology optimized for utility-scale deployment in arid climates. Jinko Solar dominates module shipments across emerging markets through vertically integrated cell-to-module manufacturing.
Solar cells are semiconductor devices that convert photon energy into direct-current electricity through the photovoltaic effect, typically fabricated from crystalline silicon wafers with doped p-n junctions, anti-reflective coatings, and screen-printed metal contacts. Their primary commercial purpose is generating renewable electricity for grid-connected systems, off-grid installations, and building-integrated applications. Monocrystalline silicon commands premium pricing in residential rooftop segments where space constraints prioritize efficiency over cost. Utility application volumes sustain the largest revenue pool, though bifacial module adoption in desert solar farms represents the fastest-expanding structural category. Thin-film cadmium telluride occupies a defensible niche in utility-scale projects where temperature coefficients and spectral response outperform silicon alternatives.
The US Inflation Reduction Act's domestic content bonuses shape cell and module sourcing decisions, while China's MIIT governs manufacturing standards through GB certification requirements for photovoltaic products. India's BIS mandates compulsory registration for solar modules under the CRS scheme, tightening market access for uncertified imports. Stakeholders must monitor how perovskite tandem cell efficiency certifications evolve under IEC testing protocols and whether regional content rules fragment supply chain investment across multiple jurisdictions.
Market Dynamics
Passivated contact architectures and tandem perovskite-silicon designs are compressing conventional cell efficiency ceilings while China's polysilicon refining concentration in Ningxia and Qinghai provinces concentrates upstream supply risk.
Growth Catalysts
- US IRA domestic content bonuses:Manufacturing investment is accelerating across Arizona, Ohio, and Georgia as developers secure additive credits for cells and modules meeting regional value thresholds.
- India's PLI scheme:Gujarat and Rajasthan states are anchoring module assembly capacity through production-linked incentives that offset capital intensity for greenfield fabs.
- Bifacial module deployment:Desert solar farms in Saudi Arabia, Chile, and Australia are adopting dual-glass designs that harvest albedo reflection and lift energy yield per hectare.
Market Restraints
- Polysilicon input volatility:Metallurgical-grade silicon and trichlorosilane prices swing with energy costs in Xinjiang and Inner Mongolia, compressing wafer margins unpredictably.
- Perovskite stability gaps:IEC 61215 damp-heat and thermal-cycling protocols expose rapid degradation in unencapsulated tandem layers, delaying bankability.
- EU CBAM carbon border adjustments:Embodied emissions accounting for imported cells is raising compliance costs for Chinese and Southeast Asian supply chains.
Strategic Opportunities
- Agrivoltaic integration:Elevated tracker configurations in Japan and France are enabling dual land use for shade-tolerant crops beneath panel arrays.
- Building-integrated photovoltaics:Semi-transparent perovskite glass facades in commercial construction are opening aesthetic-driven premium segments beyond rooftop.
- Green hydrogen offtake:Electrolyzer projects in Namibia, Morocco, and Australia are contracting dedicated solar parks for dedicated renewable ammonia and e-fuel production.
Industry Challenges
- Cell metallization skill scarcity:Screen-printing and laser-doping process engineers are concentrated in legacy semiconductor hubs, constraining fab ramp speeds.
- Perovskite IEC certification timelines:Accelerated aging test protocols remain unsettled, stretching product qualification cycles beyond 18 months.
- Silver paste supply reconfiguration:Photovoltaic-grade flake silver sourcing from Latin American refiners is fragmenting under conflict mineral tracing requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Cells Market |
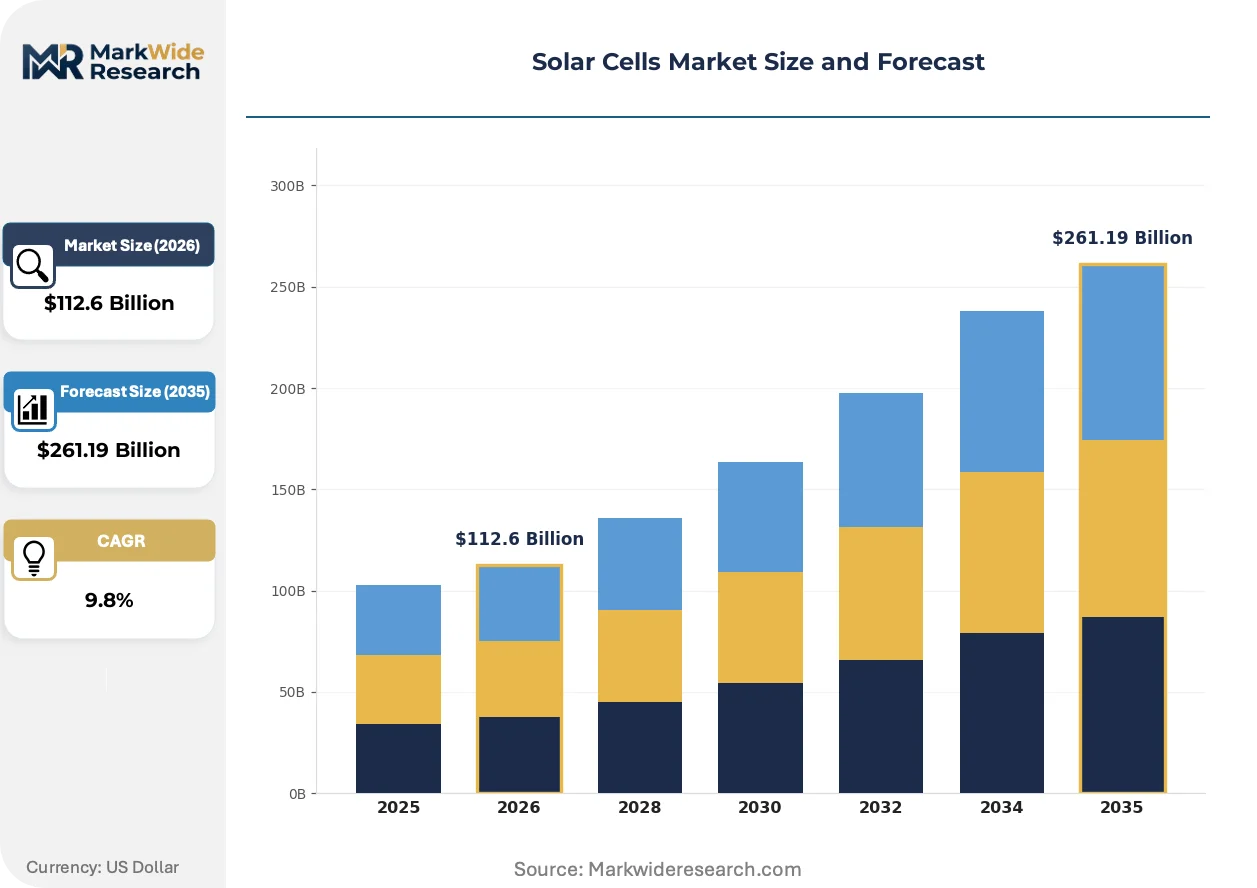
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $261.19 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Application: Residential, Commercial, Industrial, Utility Technology: Silicon-Based, Cadmium Telluride, Organic Photovoltaics, Concentrated Photovoltaics End User: Homeowners, Corporations, Government, Utilities |
| Companies Covered | Jinko Solar, LONGi Green Energy, JA Solar Technology, Tongwei Co., Ltd., Trina Solar, First Solar, Canadian Solar, Hanwha Qcells, SMA Solar Technology AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Cells Market Emerging Trajectories
Tandem cell architectures and heterojunction designs are compressing the efficiency gap between laboratory records and mass production, while regulatory carbon accounting and buyer procurement models are rewriting competitive differentiation.
Heterojunction with intrinsic thin-layer technology is rewriting cost-performance tradeoffs in cell manufacturing. LONGi Green Energy and REC Group are scaling GW-capacity lines that eliminate high-temperature diffusion steps. This architecture is rewriting the equipment supply chain as plasma-enhanced chemical vapor deposition tools displace conventional tube furnaces.
The EU Green Deal's renewable energy targets are compressing utility procurement timelines across Germany, Spain, and Poland. Member state auction designs now mandate 15-year supply contracts with escalating local content requirements. Utility-scale developers in Southern Europe are responding by pre-qualifying module suppliers against CSRD disclosure standards.
Corporate power purchase agreements are displacing traditional utility-scale offtake as the dominant demand channel. Data center operators in Virginia, Texas, and Singapore are contracting directly with solar asset owners for 24/7 carbon-free energy matching. This shift is most visible in markets where grid interconnection queues stretch beyond 36 months.
Solar Cells Market Segmentation
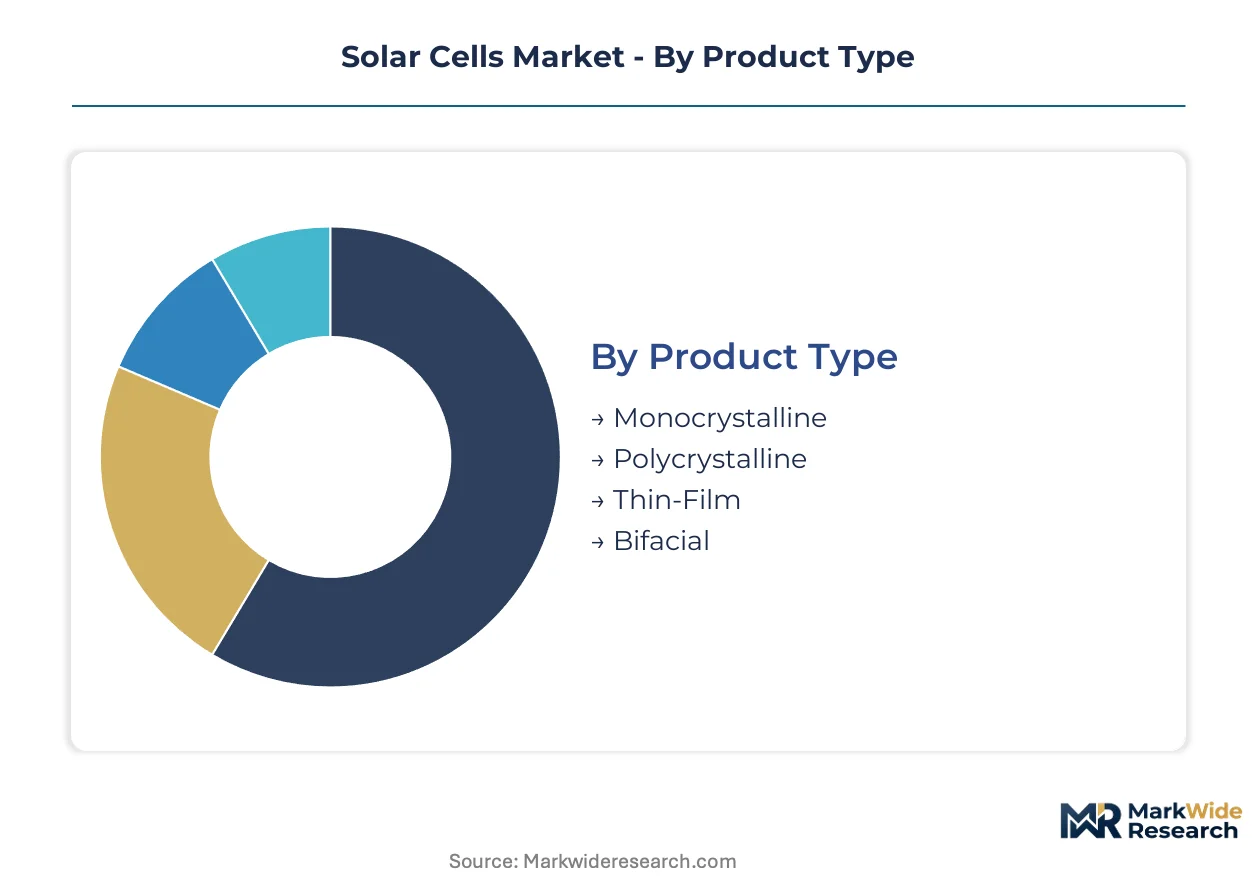
Solar cell segmentation reveals divergent capital requirements across manufacturing technologies and installation scales. Product type and technology choices determine equipment investment intensity, while application and end-user segments shape project finance structures and offtake risk profiles.
Product Type:
Capital intensity varies sharply across wafer-based and thin-film architectures, with polysilicon purification and crystal pulling demanding the heaviest upfront manufacturing investment.
- Monocrystalline:Czochralski-grown single-crystal wafers deliver the highest conversion efficiencies through uniform lattice structures. Residential rooftop installations in space-constrained urban markets absorb premium pricing for these cells despite higher module costs per watt.
- Polycrystalline:Directional solidification of silicon ingots produces multiple crystal orientations with slightly reduced efficiency but lower energy input during manufacturing. Emerging market utility procurement in India and Brazil favors this cost-optimized format where land availability offsets efficiency penalties.
- Thin-Film:Vapor-deposited semiconductor layers on glass substrates eliminate wafering steps entirely.
- Bifacial:Dual-glass encapsulation enables rear-side photon capture from ground albedo reflection.
Monocrystalline absorbs the bulk of installed capacity; bifacial is expanding most quickly.
Application:
Project scale determines development complexity, with utility-scale deployments requiring multi-year permitting and transmission interconnection timelines that dwarf residential installation cycles.
- Residential:Distributed rooftop systems under 20kW capacity serve individual homeowner demand through net metering arrangements. Germany's EEG feed-in tariffs and California's NEM 3.0 rules are restructuring compensation frameworks for these installations.
- Commercial:Behind-the-meter arrays from 100kW to 2MW offset retail electricity rates for manufacturing facilities and logistics warehouses. Corporate sustainability mandates at data center operators in Virginia and Singapore are accelerating direct procurement of these systems.
- Industrial:On-site generation for energy-intensive process loads including cement, steel, and chemical production.
- Utility:Grid-scale solar farms exceeding 50MW capacity sell power through competitive auctions and bilateral contracts.
Utility applications command the largest revenue pool; commercial installations are climbing the fastest as corporate PPA structures mature.
Technology:
Manufacturing equipment depreciation schedules and R&D amortization create divergent cost structures across incumbent silicon and emerging thin-film platforms.
- Silicon-Based:Crystalline wafers with diffused p-n junctions and screen-printed contacts dominate mass production through decades of process optimization. China's MIIT GB certification standards and India's BIS CRS registration govern quality compliance for these cells entering Asian markets.
- Cadmium Telluride:Semiconductor thin-film deposition achieves superior temperature coefficients and spectral response in high-irradiance desert conditions. First Solar's Ohio and Malaysia manufacturing bases supply utility-scale developers across the US Southwest and Middle East.
- Organic Photovoltaics:Solution-processed polymer and small-molecule absorbers enable flexible form factors and semi-transparent building integration.
- Concentrated Photovoltaics:Multi-junction III-V cells under optical concentration achieve record laboratory efficiencies above 47%.
Silicon-based technology retains overwhelming production share; cadmium telluride is gaining share fastest in arid climate utility deployments.
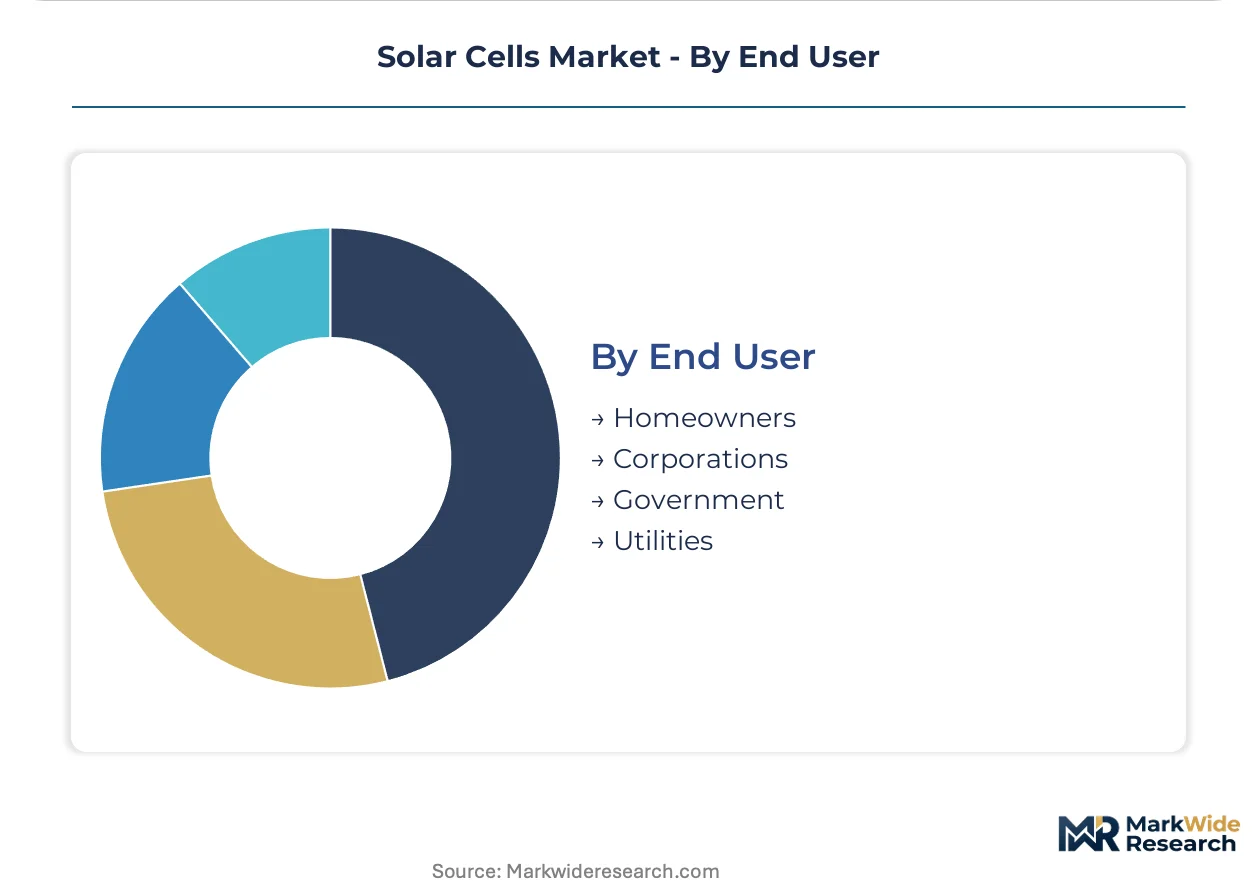
End User:
Counterparty credit quality and offtake duration differentiate financing terms across homeowner, corporate, and sovereign purchaser categories.
- Homeowners:Retail electricity rate arbitrage drives distributed adoption through third-party lease and loan products. US state-level solar property tax exemptions and accelerated depreciation schedules shape investment returns for these customers.
- Corporations:Balance-sheet-backed sustainability commitments support long-term power purchase agreements with renewable energy certificates. RE100 member companies in technology and consumer goods sectors are contracting dedicated solar capacity to meet Scope 2 emission reduction targets.
- Government:Public sector procurement through renewable energy auctions and mandated green building standards.
- Utilities:Regulated and competitive power providers integrating solar into generation portfolios for renewable portfolio standard compliance.
Utilities anchor the largest contracted volume; corporations are expanding procurement most rapidly through direct PPA structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xining anchors polysilicon refining capacity through Qinghai's low-carbon hydropower base, while Ningxia's coal-chemical corridor supplies metallurgical-grade silicon feedstock. China's western provinces concentrate upstream solar manufacturing against rising carbon border pressures from European importers.
United States
Utility-scale developers in Arizona, Ohio, and Georgia are securing domestic content bonuses under the IRA's additive credit structure. FERC interconnection queue reforms aim to compress 36-month approval timelines for solar-plus-storage projects. First Solar's Ohio manufacturing base supplies cadmium telluride modules to Southwest desert installations.
China
Ningxia and Qinghai provinces host polysilicon refining clusters powered by captive coal and hydropower respectively. MIIT GB certification standards govern photovoltaic product quality compliance for domestic and export markets. Tongwei's integrated polysilicon-to-cell operations in Sichuan leverage ultra-low electricity tariffs from the Jinsha River hydro complex.
India
Gujarat and Rajasthan states concentrate module assembly demand under the PLI scheme's production-linked incentive structure. BIS mandates compulsory registration for solar modules under the CRS scheme, tightening market access for uncertified imports. Reliance Industries' green energy complex in Jamnagar targets integrated polysilicon-to-module capacity.
Germany
Corporate PPA structures from RE100 members are compressing utility procurement timelines across Bavaria and North Rhine-Westphalia. EU Green Deal renewable energy targets mandate 15-year supply contracts with escalating local content requirements. Meyer Burger's Thalheim facility represents Europe's surviving crystalline silicon cell production.
Saudi Arabia
Desert solar farms in Al-Jouf and Tabuk provinces are adopting bifacial dual-glass designs to harvest ground albedo reflection. Vision 2030 economic diversification programs allocate sovereign capital to utility-scale renewable auctions. ACWA Power's Sudair project contracts 1.5 GW of solar capacity for green hydrogen electrolyzer offtake.
Solar Cells Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and geographic regulatory access. The vendor base stratifies into three tiers: integrated polysilicon-to-module conglomerates, pure-play cell and wafer specialists, and thin-film technology licensees. Strategic differentiation runs through backward integration into silicon purification, tandem cell R&D partnerships, and regional manufacturing footprints that satisfy domestic content rules. Competitive moves center on capacity expansion in tariff-advantaged jurisdictions and technology licensing agreements that bypass capital-intensive equipment cycles.
Within the integrated conglomerate tier, LONGi Green Energy and Tongwei Co., Ltd. exemplify upstream control strategies spanning polysilicon refining through mono-crystalline wafer pulling. Jinko Solar occupies a position among the scale-driven module specialists with vertically integrated cell-to-module manufacturing across Southeast Asian and Chinese production bases. First Solar represents the thin-film archetype through its cadmium telluride technology platform optimized for utility-scale deployment in high-irradiance desert climates. These three anchors illustrate divergent competitive vectors: silicon purity control, manufacturing scale economies, and differentiated temperature coefficient performance.
| Leading Market Players |
|---|
| Jinko Solar |
| LONGi Green Energy |
| JA Solar Technology |
| Tongwei Co., Ltd. |
| Trina Solar |
| First Solar |
| Canadian Solar |
| Hanwha Qcells |
| SMA Solar Technology AG |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between IEC 61215-certified bankable modules and uncertified commodity imports splits pricing power across divergent supply chain footprints. Premium-tier suppliers command contract premiums through guaranteed degradation curves and 25-year warranties, while commodity traders compete on spot polysilicon cost swings in Ningxia and Xinjiang refining corridors.
Pricing Analysis
Energy-yield-per-watt pricing anchors module valuation, with bifacial designs capturing 8-12% albedo-adjusted premiums over monofacial equivalents in desert utility installations. Price differentiation separates Tier-1 manufacturers with captive polysilicon from module assemblers exposed to metallurgical-grade silicon volatility. Cost compression in polycrystalline segments is intensifying as Chinese GB-certified capacity floods emerging markets. Utility-scale developers exhibit lowest price sensitivity through long-term PPA rate-locking, while distributed residential installers absorb premium pricing for space-constrained rooftop efficiency.
Supply Chain Analysis
Photovoltaic-grade polysilicon supply rests on Chinese refining clusters in Ningxia, Xinjiang, and Qinghai provinces, with Tongwei and Daqo anchoring metallurgical-grade silicon purification. Silver paste metallization draws from Latin American flake silver refiners, while quartz crucibles for Czochralski pulling hinge on high-purity semiconductor-grade sand deposits. Tariff exposure runs through US IRA domestic content thresholds and EU CBAM carbon border adjustments on embodied emissions. Distribution runs through vertically integrated conglomerates controlling wafer-to-module logistics, with regional assembly hubs in India, Vietnam, and Malaysia fragmenting final-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation is accelerating as polysilicon margin compression and IEC certification timelines force sub-scale module assemblers into distressed exit or acquisition.
For Market Incumbents: Hedge against perovskite tandem disruption through R&D partnerships with university laboratories and equipment makers scaling plasma-enhanced deposition tools. Defensive positioning requires backward integration into polysilicon refining or securing 10-year silver paste supply agreements with conflict-mineral-compliant Latin American refiners. Capacity expansion in India and the US Southwest satisfies IRA and PLI domestic content rules while insulating margins from EU carbon border adjustments. For New Entrants and Emerging Players: EPC contractors in Saudi Arabia, Morocco, and Namibia represent the most penetrable channel partners for green hydrogen electrolyzer offtake projects demanding dedicated solar park development. Agrivoltaic installations in Japan and France offer white-space entry through elevated tracker configurations enabling dual land-use revenue streams. A technology licensing model bypassing capital-intensive wafer fabs accelerates market access without competing against LONGi's scale economies. For Investors and Strategic Acquirers: Re-rating potential sits with heterojunction equipment specialists given plasma-enhanced chemical vapor deposition tool demand from LONGi and REC Group capacity expansions. Long-term viability over the next decade favors targets with proven IEC certification pathways and captive polysilicon supply. The signal to watch is perovskite tandem bankability milestones under accelerated aging protocols, which would trigger wholesale manufacturing line replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Polysilicon Refining Capacity Expansion | Captive supply in Ningxia and Qinghai insulates margins from metallurgical-grade silicon volatility. |
| Heterojunction Manufacturing Line Deployment | Plasma-enhanced chemical vapor deposition adoption by LONGi and REC Group rewrites equipment supply chains. |
| Domestic Content Compliance Certification | IRA additive credits and EU CBAM carbon accounting reshape regional manufacturing footprints. |
| Perovskite Tandem R&D Partnership | Laboratory efficiency records approaching 33% threaten incumbent silicon architectures. |
| Green Hydrogen offtake Contracting | ACWA Power's Sudair project demonstrates dedicated solar park structures for electrolyzer demand. |
Methodological Framework
Document review covered IEA renewable energy deployment statistics, EIA generation capacity databases, FERC interconnection queue filings, and MIIT GB certification registries, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and polysilicon procurement leads. Secondary validation drew from customs trade data, SEC 10-K filings of listed solar manufacturers, and auction results from India's SECI and Germany's Bundesnetzagentur. Bottom-up capacity installation tracking and top-down policy incentive modeling were triangulated against stakeholder input.
Historical deployment trajectories were cross-referenced against panel input from industry participants to construct segment-level forecasts across the projection horizon. Segmentation dimensions modeled include cell architecture type, application scale tier, technology platform, and regional regulatory framework. CAGRs were derived through polynomial trend fitting of capacity additions adjusted for policy incentive phase-out schedules and grid interconnection queue clearance rates. Forecast inputs incorporated polysilicon spot price volatility indices and silver paste supply disruption scenarios.
Caveats apply where IEC perovskite certification delays, EU CBAM carbon accounting rule changes, or US IRA domestic content threshold revisions could materially shift the outlook. Forecasts reflect documented assumptions regarding technology substitution rates and policy incentive continuity. A small set of named triggers—tandem cell bankability milestones, carbon border adjustment implementation timelines, and green hydrogen offtake contract volumes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Module Market
Solar Power Systems
Poland Solar Energy Market
Solar Power Systems
Greece Renewable Energy Market
Solar Power Systems
Solar Shed Light Market
Solar Power Systems
Indonesia Renewable Energy Market
Solar Power Systems
Solar Skin Market
Solar Power Systems
Home Solar System Market
Solar Power Systems
Off-Grid Solar Energy Market
Solar Power Systems
Global Dye-Sensitized Solar Cells (Dssc) Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
Canada Distributed Solar Power Generation Market
Solar Power Systems
Global Thin Film Solar Cells Market
Solar Power Systems
GCC Solar Photovoltaic (PV) Market
Solar Power Systems
Building Integrated Photovoltaics Module Market
Solar Power Systems
China Distributed Solar Power Generation Market
Solar Power Systems
Solar Panel Lights Market