
 Australia Solar Power Market | 2026-2036
Australia Solar Power Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Solar Power Market Outlook
The Australian Renewable Energy Target is broadening the addressable market for large-scale solar developers. SunPower leverages its premium module technology to anchor utility-scale procurement pipelines across the National Electricity Market. GEM Energy competes on integrated commercial and industrial solutions, while Solar Analytics specializes in performance monitoring platforms that sustain customer retention for distributed installers.
Australia solar power encompasses photovoltaic and concentrated solar thermal systems that convert electromagnetic radiation into electrical energy through semiconductor junctions or heat-transfer fluids, typically achieving conversion efficiencies between 18% and 22% for commercial silicon modules. The technology serves grid-connected generation, remote off-grid supply, and behind-the-meter commercial load management. Photovoltaic installations dominate current capacity additions, while bifacial modules capture expanding share in ground-mounted utility projects where albedo reflection boosts yield. Utility end users represent the fastest-growing demand pool, though residential roof-top systems retain the largest installed base and service-type revenue concentrates in maintenance contracts as aging systems require inverter replacements and performance optimization.
The Clean Energy Regulator administers Large-scale Generation Certificates under the Renewable Energy Target, directly shaping project finance structures and offtake contract pricing. State-level regulators including the Essential Services Commission of Victoria and the Independent Pricing and Regulatory Tribunal of New South Wales set feed-in tariff schedules that influence residential investment payback periods. Standards Australia and the Clean Energy Council govern module accreditation and installer certification, creating compliance thresholds that filter market participants. Stakeholders must monitor transmission constraint declarations and marginal loss factor revisions, as these network parameters increasingly determine project dispatch economics and development site selection.
Market Dynamics
Transmission constraint declarations and marginal loss factor revisions are compressing project dispatch economics across Australia's National Electricity Market, forcing developers toward grid-edge locations with firmer network access.
Growth Catalysts
- Large-scale Generation Certificates:The Clean Energy Regulator's certificate issuance under the Renewable Energy Target directly monetizes generation output, improving project finance structures and accelerating utility-scale procurement pipelines.
- Queensland solar resource concentration:Irradiance levels exceeding 5.5 kWh/m²/day in central and northern regions reduce levelized cost thresholds and attract merchant power developers seeking high-capacity-factor sites.
- Bifacial module adoption:Ground-mounted utility projects increasingly deploy double-sided photovoltaic panels that capture albedo reflection, boosting yield by 8-15% on high-reflectivity surfaces.
Market Restraints
- Polysilicon supply concentration:Australia's module procurement remains exposed to Xinjiang-sourced polysilicon, creating ESG compliance risks and supply disruption vulnerability for project developers.
- Grid connection queuing delays:The Australian Energy Market Operator's connection assessment processes extend development timelines by 18-36 months for projects in transmission-constrained zones.
- Limited domestic inverter manufacturing:Dependence on imported string and central inverters from Southeast Asian suppliers concentrates procurement risk and exposes projects to currency fluctuation impacts.
Strategic Opportunities
- Western Australia off-grid mining:Remote mineral processing operations present unmet demand for solar-plus-storage hybrid systems displacing diesel generation in the Pilbara and Goldfields regions.
- Agricultural irrigation pumping:Solar-powered water extraction systems offer untapped deployment potential across Murray-Darling Basin farming operations facing rising electricity tariffs.
- Virtual power plant aggregation:Distributed residential battery systems coordinated through aggregation platforms create new revenue streams from frequency control ancillary services markets.
Industry Challenges
- Accredited electrician scarcity:The Clean Energy Council's installer certification requirements face supply constraints as training pipeline throughput lags behind installation demand growth in Queensland and New South Wales.
- Legacy inverter replacement complexity:Aging residential systems require component swaps that trigger full system re-certification under updated AS/NZS electrical safety standards, extending service timelines.
- Network tariff reconfiguration:State-level regulators revise export pricing structures unpredictably, complicating payback period calculations for behind-the-meter commercial investors.
Report Scope
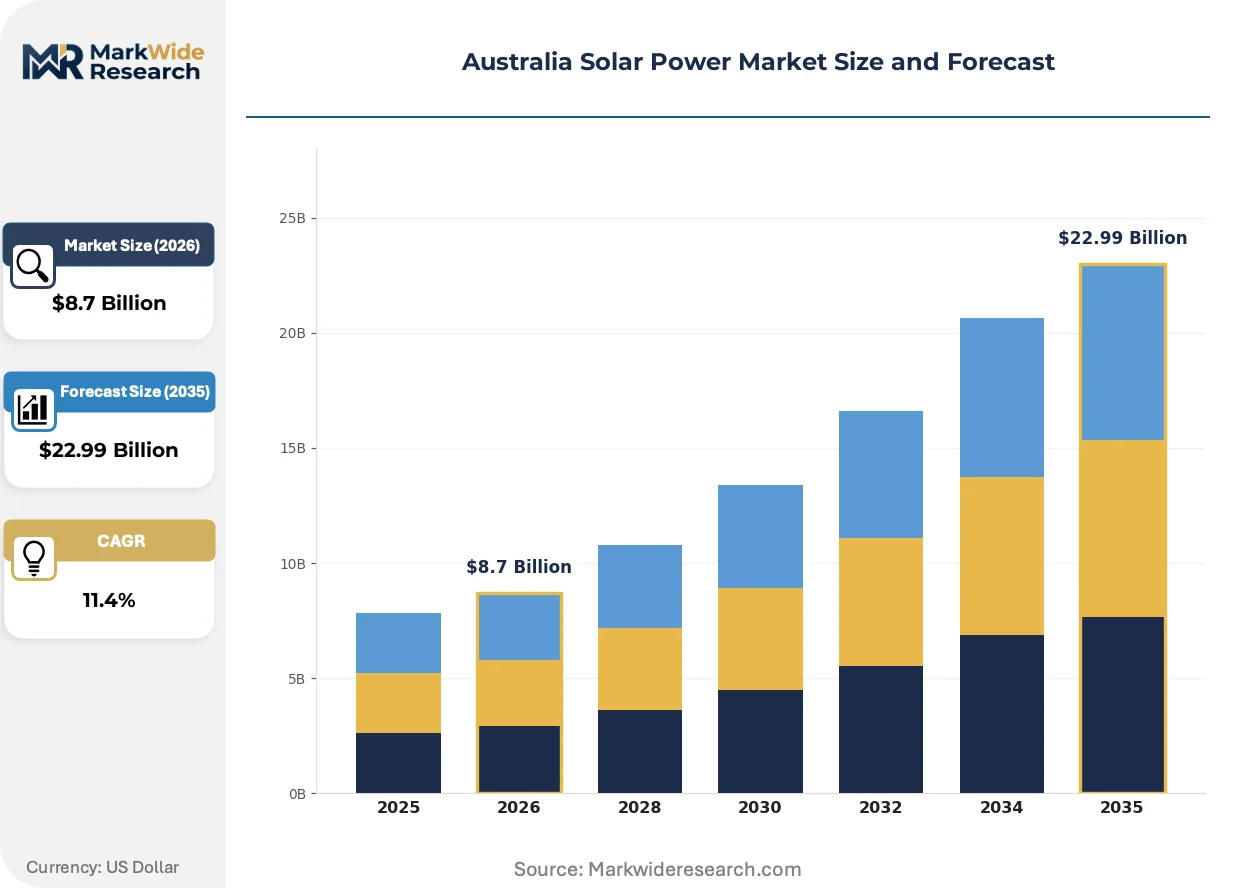
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Solar Power Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photovoltaic, Concentrated Solar Power, Bifacial Solar, Thin-Film Solar End User: Residential, Commercial, Industrial, Utility Installation: Roof-Top, Ground-Mounted, Distributed Generation, Off-Grid Service Type: Design, Installation, Maintenance, Consulting |
| Companies Covered | Sunray Power, GEM Energy, OpenSolar, Okra Solar, Solar Analytics, Sunboost, National Solar Energy Group, SunPower, SolarBright, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Solar Power Market Strategic Shifts
Module efficiency gains and grid services monetization are converging to reshape how solar assets capture value across Australia's electricity market, with technology and regulatory forces operating in parallel.
Bifacial photovoltaic technology is electrifying utility-scale project economics by capturing reflected irradiance from ground surfaces. Developers in Queensland's high-albedo clay soil regions are deploying these modules at 150% ground coverage ratios. The technology is compressing levelized energy cost benchmarks and displacing single-sided panels in new procurement tenders.
The Essential Services Commission of Victoria's time-varying feed-in tariff restructuring is altering residential investment calculus. Export price signals now peak during late afternoon demand windows rather than midday generation surpluses. Battery pairing penetration is accelerating fastest in Victoria as households seek to shift export timing toward higher-value intervals.
Corporate power purchase agreements are displacing traditional utility offtake structures for large-scale project finance. Commercial and industrial buyers in New South Wales manufacturing and data center sectors are negotiating 10-15 year fixed-price contracts directly with project developers. This procurement evolution is most visible in the Hunter-Central Coast renewable energy zone where transmission investment timelines align with corporate demand aggregation.
Australia Solar Power Market Segmentation
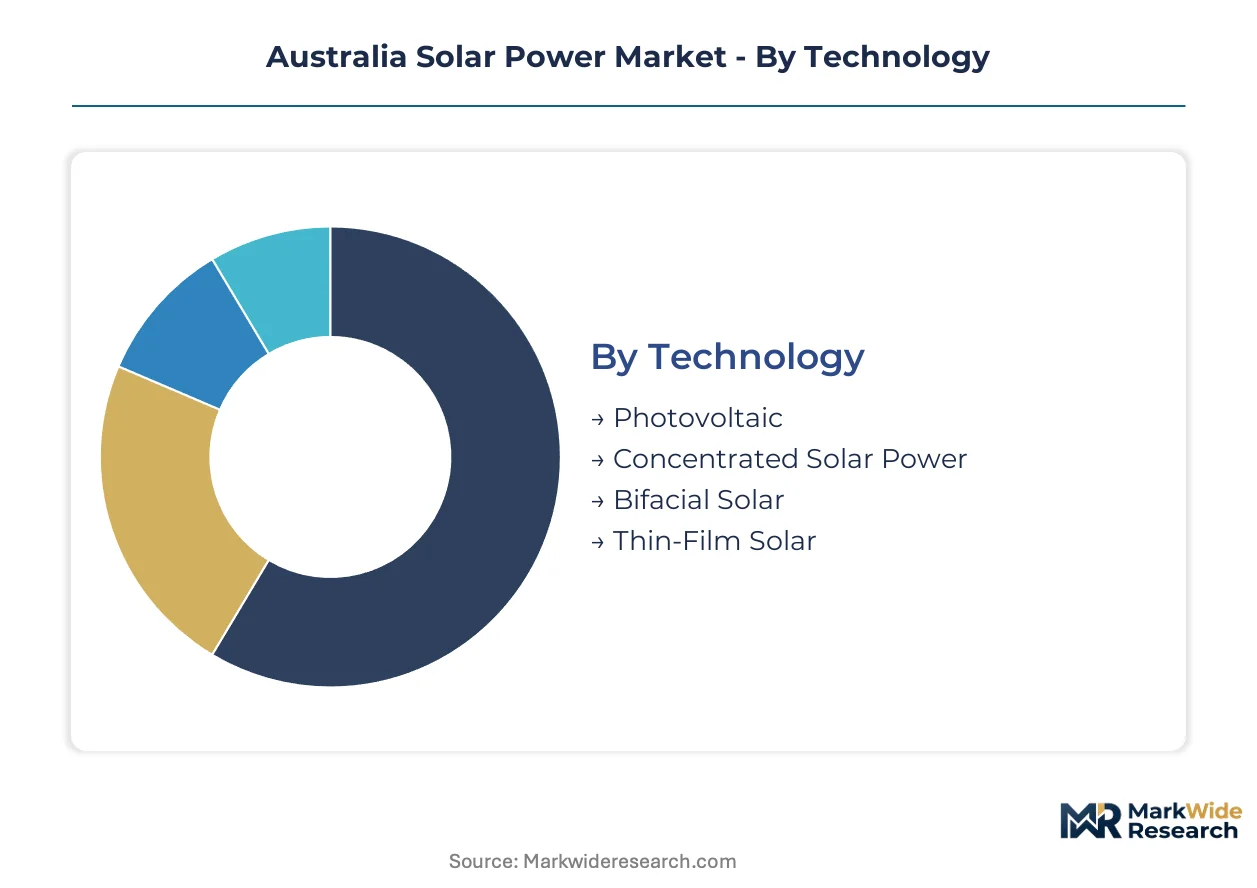
Technology and installation choices in Australia's solar market reflect upgrade cycles driven by module efficiency gains and inverter replacement timelines. End-user segments diverge sharply in procurement behavior, with utility-scale developers pursuing merchant exposure while residential buyers optimize payback periods through battery pairing.
Technology:
Module replacement cycles and efficiency upgrade pathways dominate technology selection as aging systems reach end-of-life.
- Photovoltaic:Silicon-based semiconductor junctions convert incident irradiance into direct current electricity through the photovoltaic effect. Queensland and New South Wales account for the dominant share of new capacity additions, driven by transmission zone availability and irradiance levels exceeding 5.5 kWh/m²/day. Volume placements concentrate in Photovoltaic; the faster expansion belongs to Bifacial Solar.
- Concentrated Solar Power:Parabolic trough and solar tower configurations use heat-transfer fluids to drive thermal-electric conversion cycles with integrated molten salt storage. Deployment concentrates in remote mining applications across Western Australia's Pilbara region where dispatchable output displaces diesel generation.
- Bifacial Solar:Double-sided modules capture albedo reflection from high-reflectivity ground surfaces, delivering yield premiums of 8-15% on clay soils prevalent in central Queensland.
- Thin-Film Solar:Cadmium telluride and copper indium gallium selenide absorber layers enable flexible form factors for building-integrated applications with weight constraints.
Technology cost tiers separate established silicon from emerging bifacial and thin-film alternatives.
End User:
Customer type determines financing structure, with corporate offtake agreements reshaping utility-scale procurement while residential investment responds to feed-in tariff reconfigurations.
- Utility:Grid-connected generation assets exceeding 5 MW capacity feed into the National Electricity Market through connection points assessed by the Australian Energy Market Operator. Merchant power developers in New South Wales prioritize locations with firm transmission access and favorable marginal loss factors.
- Residential:Behind-the-meter rooftop installations on single-family dwellings and multi-unit residential buildings, typically sized 3-10 kW. Victoria's time-varying feed-in tariff restructuring accelerates battery pairing as households shift export timing toward late-afternoon price peaks.
- Commercial:Small-to-medium enterprises and retail operations seeking electricity cost reduction through rooftop or carport-mounted systems with 10-100 kW nameplate capacity.
- Industrial:Energy-intensive manufacturing and mineral processing operations procuring solar through corporate power purchase agreements with 10-15 year contract tenors.
Application maturity runs deepest in Residential; Industrial procurement is climbing the fastest.
Installation:
Physical configuration dictates land use intensity, grid connection complexity, and exposure to network constraint declarations.
- Ground-Mounted:Fixed-tilt or tracking arrays installed on dedicated land parcels with dedicated electrical infrastructure and independent grid connection. Queensland's renewable energy zones attract ground-mounted development where transmission investment timelines align with project completion schedules.
- Roof-Top:Module arrays affixed to existing building structures, leveraging distributed connection points and avoiding land acquisition. Australia's residential installed base remains concentrated in roof-top configurations across suburban Sydney and Melbourne.
- Distributed Generation:Sub-utility scale systems connected at distribution voltage levels, often aggregated through virtual power plant platforms for frequency control ancillary services participation.
- Off-Grid:Standalone systems with battery storage and backup generation for locations beyond the National Electricity Market footprint, prevalent in Western Australia's remote mining camps and pastoral stations.
Installation volume clusters in Roof-Top; Ground-Mounted deployment is gaining share fastest.
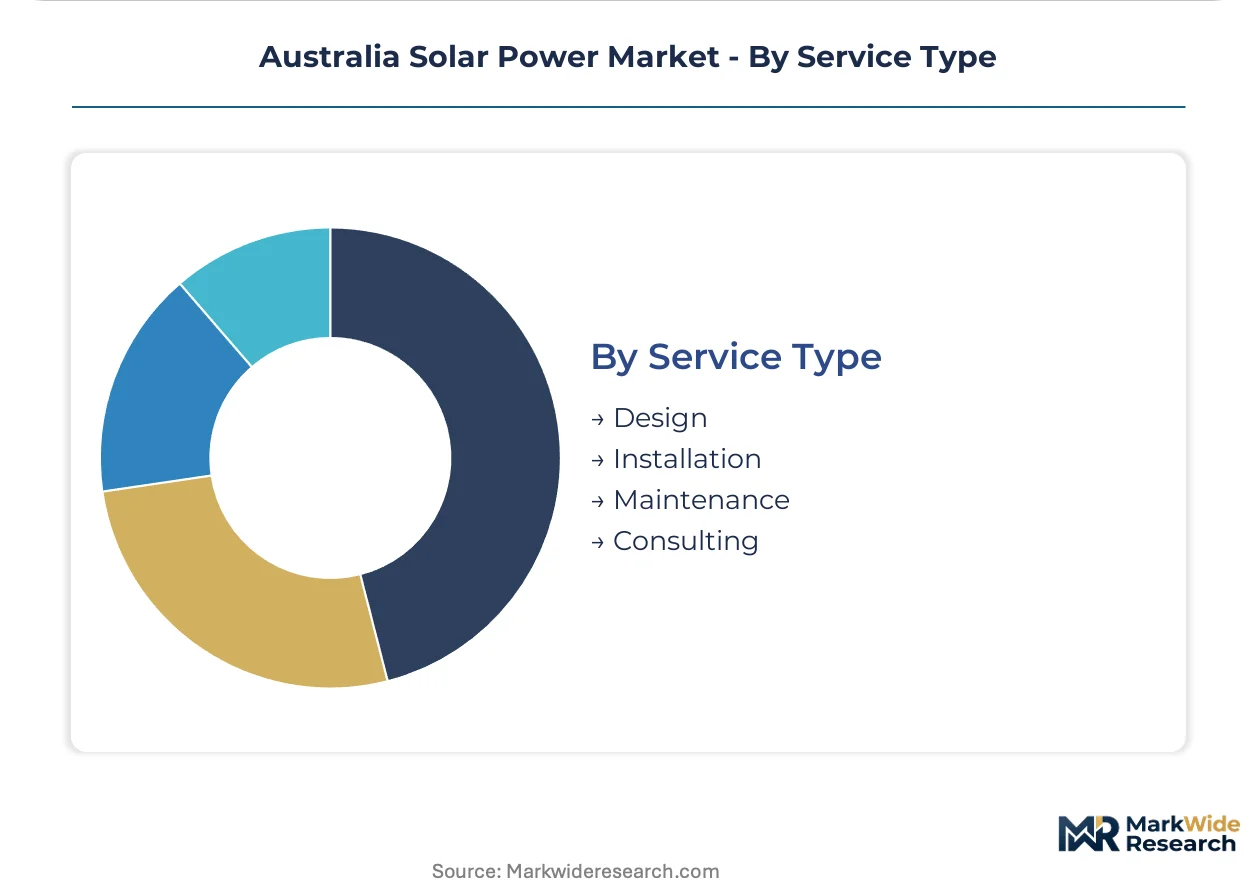
Service Type:
Service revenue correlates with installed base age, as early-vintage systems trigger replacement demand for inverters and monitoring hardware.
- Maintenance:Performance optimization, inverter replacement, and system re-certification under updated AS/NZS electrical safety standards for aging residential installations. The Essential Services Commission of Victoria's regulatory revisions extend service timelines by triggering full system re-certification requirements.
- Installation:Physical deployment of module arrays, inverters, mounting systems, and electrical balance-of-plant by Clean Energy Council accredited installers.
- Design:System sizing, shading analysis, and electrical schematic preparation preceding procurement and construction phases.
- Consulting:Grid connection application support, marginal loss factor assessment, and offtake contract structuring for utility-scale project developers.
Service margin concentrates in Maintenance; Consulting revenue is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's solar generation capacity concentrates in eastern states where transmission infrastructure and irradiance levels converge, while Western Australia develops isolated mining applications outside the National Electricity Market.
New South Wales
The Hunter-Central Coast renewable energy zone attracts corporate power purchase agreements from manufacturing and data center operators. The state's Independent Pricing and Regulatory Tribunal revises feed-in tariff schedules that reshape commercial investment payback calculations. Sydney's metropolitan solar installation base drives maintenance service demand as early-vintage residential systems require inverter replacements.
Queensland
Irradiance levels exceeding 5.5 kWh/m²/day in central and northern regions reduce levelized cost thresholds for merchant power developers. The state's renewable energy zones coordinate transmission investment timelines with project completion schedules. Brisbane and Gold Coast suburban corridors retain Australia's largest residential roof-top installed base.
Victoria
The Essential Services Commission's time-varying feed-in tariff restructuring accelerates battery pairing penetration as households shift export timing toward late-afternoon price peaks. Melbourne's commercial and industrial sector procures solar through behind-the-meter installations sized for electricity cost reduction. Regional agricultural operations deploy solar-powered irrigation pumping across the Murray-Darling Basin.
Western Australia
Remote mineral processing operations in the Pilbara and Goldfields regions present unmet demand for solar-plus-storage hybrid systems displacing diesel generation. The state's isolated grid operates outside National Electricity Market pricing mechanisms. Perth's metropolitan area concentrates distributed generation deployment with virtual power plant aggregation potential.
South Australia
High renewable penetration levels create network stability challenges that accelerate grid services monetization opportunities. The state's transmission constraint history forces developers toward grid-edge locations with firmer network access. Adelaide's industrial precincts negotiate direct corporate offtake agreements with utility-scale project developers.
Australia Solar Power Market Competitive Environment
The competitive structure tilts toward specialized service providers rather than integrated manufacturers. Market participants cluster across three tiers: premium module technology suppliers, integrated commercial and industrial solution providers, and performance monitoring platform specialists. Consolidation pressure operates through strategic partnerships between developers and offtake aggregators, while geographic expansion into Western Australia's mining regions represents a dominant competitive move.
Among the named participants, SunPower occupies a position exemplifying premium module technology anchoring utility-scale procurement pipelines. GEM Energy sits within the integrated solutions archetype targeting commercial and industrial segments. Solar Analytics represents the performance monitoring specialization that sustains customer retention for distributed installers. These three anchors illustrate how competitive positioning diverges across the value chain rather than concentrating in manufacturing scale.
| Leading Market Players |
|---|
| Sunray Power |
| GEM Energy |
| OpenSolar |
| Okra Solar |
| Solar Analytics |
| Sunboost |
| National Solar Energy Group |
| SunPower |
| SolarBright |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up installation specialists anchor Australia's solar supply base, concentrating procurement leverage among a handful of national distributors while compressing margin pools for independent retailers competing on module and inverter bundles.
Pricing Analysis
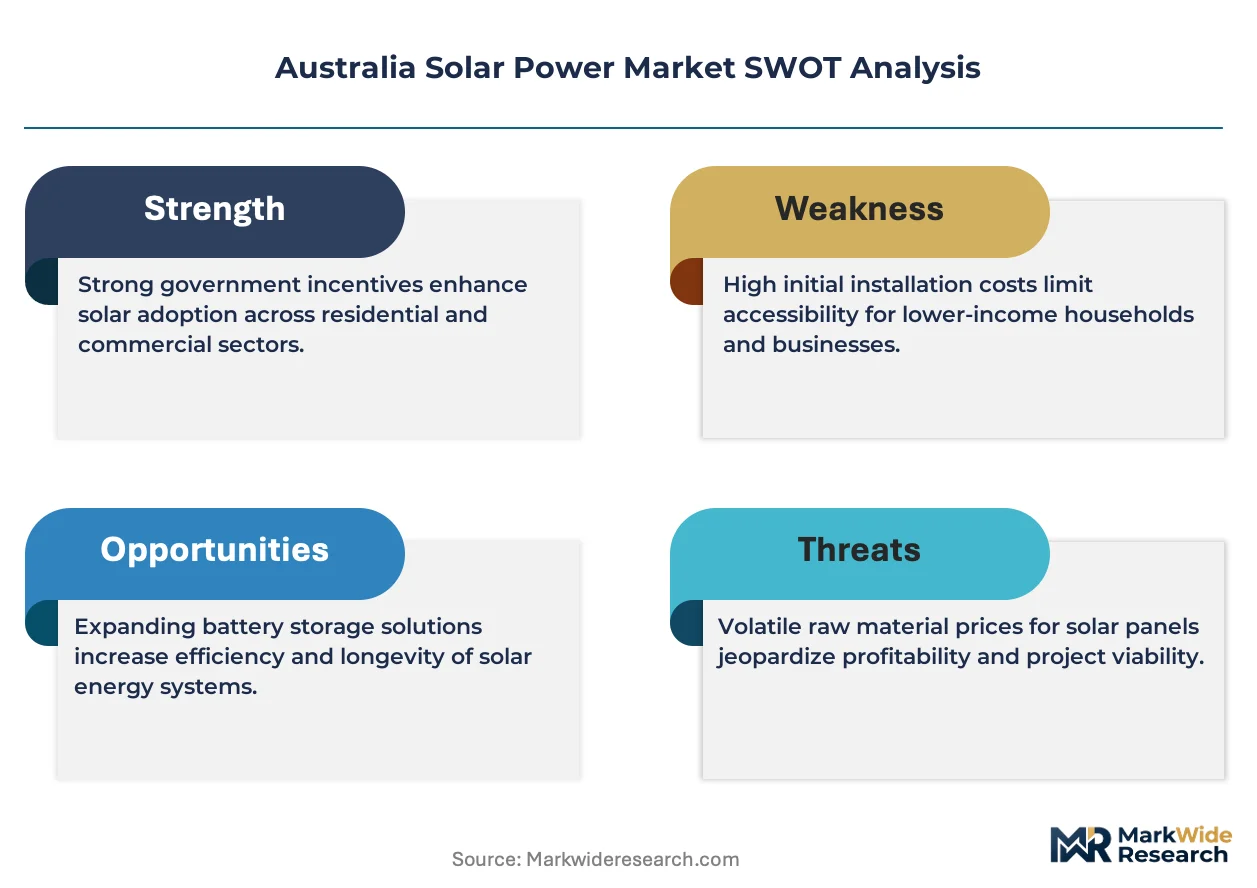
Margin tightening in residential rooftop systems reflects polysilicon cost volatility and currency fluctuation on imported inverters. Three-tier pricing structure across premium, standard, and economy levels separates SunPower's high-efficiency modules from tier-two Asian suppliers and entry-level brands. Price differentiation hinges on Clean Energy Council certification tier and after-sales service bundling. Utility-scale buyers exhibit lowest price sensitivity due to long-term offtake contract structures, while residential segment buyers face acute pressure from feed-in tariff reconfigurations.
Supply Chain Analysis
Single-source vulnerability sits with Xinjiang-sourced polysilicon and Southeast Asian inverter assembly. Module procurement draws from China, Vietnam, and Malaysia, while string and central inverter supply centers on Thailand and the Philippines. Raw material dependencies include metallurgical-grade silicon, silver paste for cell metallization, and aluminum frames. Tariff exposure on Chinese-origin components creates procurement risk. Distribution runs through Clean Energy Council-accredited wholesalers serving state-level installer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's solar market is consolidating as transmission constraint declarations and grid connection queuing delays force smaller developers into distressed exits or acquisition.
For Market Incumbents: Cement market position by securing firm transmission access in Queensland renewable energy zones and acquiring distressed development pipelines in New South Wales. Backward integration into battery storage assembly hedges inverter supply risk. Marginal loss factor volatility threatens merchant power economics; long-term corporate offtake contracts provide revenue stability. For New Entrants and Emerging Players: The price-point gap between premium SunPower modules and economy-tier Asian imports creates entry space for mid-market bifacial specialists. Western Australia's Pilbara mining region offers the most penetrable geography, with diesel displacement demand unmet by established east-coast players. Target solar-plus-storage hybrid configurations for remote mineral processing operations through direct equipment supply rather than EPC contracting. For Investors and Strategic Acquirers: Distressed-cycle entries favor utility-scale developers with approved grid connection agreements in New South Wales and Queensland. Long-term viability over the coming decade rests on transmission investment timelines aligning with project completion schedules. The signal to watch is Australian Energy Market Operator connection assessment queue movement as inflection indicator for development pipeline quality.| Strategic Initiative | Industry Significance |
|---|---|
| Transmission Access Securement | Firm grid connection in Queensland renewable energy zones underwrites merchant power dispatch economics. |
| Corporate Power Purchase Agreement | Direct offtake contracts with New South Wales manufacturing and data center operators displace traditional utility structures. |
| Battery Storage Integration | Solar-plus-storage hybrid systems capture Western Australia mining demand while hedging inverter supply concentration. |
| Virtual Power Plant Aggregation | Distributed residential battery coordination through aggregation platforms accesses frequency control ancillary services revenue. |
| Performance Monitoring Platform | Asset management software sustains installer customer retention as aging systems trigger maintenance service demand. |
Study Parameters
Independent corroboration across project developers, EPC contractors, and grid operators underwrites the qualitative findings on transmission constraint impacts. Primary interviews with Clean Energy Council accredited installers, utility planning officers, and corporate energy procurement managers combined with secondary validation from Australian Energy Market Operator connection databases, Clean Energy Regulator certificate issuance records, and state-level feed-in tariff regulatory filings. Bottom-up capacity addition tracking and top-down Renewable Energy Target compliance modeling were triangulated.
Rate-of-change decomposition across the projection horizon separates module efficiency gains, installation cost trajectories, and regulatory incentive phase-out effects. Segmentation dimensions modeled include technology type, end-user category, installation configuration, and service type alongside state-level regulatory framework clustering. CAGRs were derived from installed capacity build-up and revenue per megawatt assumptions. Forecast inputs incorporated marginal loss factor revision patterns and transmission investment commitment schedules.
Inputs from Australian Energy Market Operator and Clean Energy Regulator were available through the study window; gaps in real-time merchant power price forecasting introduce uncertainty bands. Forecasts reflect documented assumptions on certificate price trajectories and network tariff reconfiguration timing. Specific risk factors that could revise projections include accelerated Renewable Energy Target closure, unplanned transmission infrastructure delays, and polysilicon supply disruption from trade policy shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Collector Panels Market
Solar Power Systems
Single Axis Solar PV Tracker Market
Solar Power Systems
Optical Solar Reflectors Market
Solar Power Systems
North America Concentrated Solar Power (CSP) Market
Solar Power Systems
Asia Pacific Solar Backsheet Market
Solar Power Systems
Rooftop Solar PV Market
Solar Power Systems
Spain Rooftop Solar Market
Solar Power Systems
Portugal Distributed Solar Energy Market
Solar Power Systems
Solar Panel Bracket Market
Solar Power Systems
Off-Grid Solar Power Market
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
Solar Energy Market
Solar Power Systems
US Solar Power Meters Market
Solar Power Systems
Global EV Solar Modules Market
Solar Power Systems
Off-Grid Solar Generator Market
Solar Power Systems
Europe Solar Microinverter Market