
 Nigeria Petrol Station Market | 2026-2036
Nigeria Petrol Station Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Petrol Station Market Foresight
Fleet operators and logistics contractors are reorganizing fuel procurement around stations that bundle diesel bunkering with lubricant retail and vehicle maintenance bays. NNPC Retail Ltd. leverages its pipeline access and federal storage depots to sustain volume leadership across the northern corridor. TotalEnergies Marketing Nigeria Plc anchors premium positioning through branded convenience retail and loyalty programs at high-traffic Lagos locations. Oando PLC competes on downstream integration, controlling coastal import terminals that feed its owned and franchised outlets.
A petrol station constitutes a fixed retail facility designed for bulk storage, metered dispensing, and point-of-sale distribution of refined petroleum products to motor vehicles and industrial equipment, typically incorporating underground storage tanks with 20,000–60,000 litre capacity per product grade and vapor recovery systems to manage emissions. Its primary commercial purpose is to serve as the terminal node of the downstream petroleum supply chain, converting wholesale fuel deliveries into fractional retail transactions while generating ancillary revenue from convenience goods and automotive services. The fuel type dimension shows diesel commanding disproportionate margin contribution from commercial transport and generator-dependent manufacturing clusters, while the pump technology segment sees smart pumps and mobile payment integration growing fastest as cash handling costs and fraud exposure drive capital allocation toward digital infrastructure. Ownership models reveal corporate-operated stations capturing urban premium sites, whereas franchise arrangements dominate secondary cities where local capital reduces deployment risk.
The Petroleum Industry Act and its implementing regulations through the Nigerian Midstream and Downstream Petroleum Regulatory Authority reshape licensing fees, product quality standards, and retail margin structures across the sector. The Standards Organisation of Nigeria enforces specifications for pump calibration accuracy and fuel adulteration thresholds that determine market access for station operators. Stakeholders must monitor how petroleum subsidy removal timelines and foreign exchange access rules for product imports reshape working capital requirements and site-level profitability thresholds.
Market Dynamics
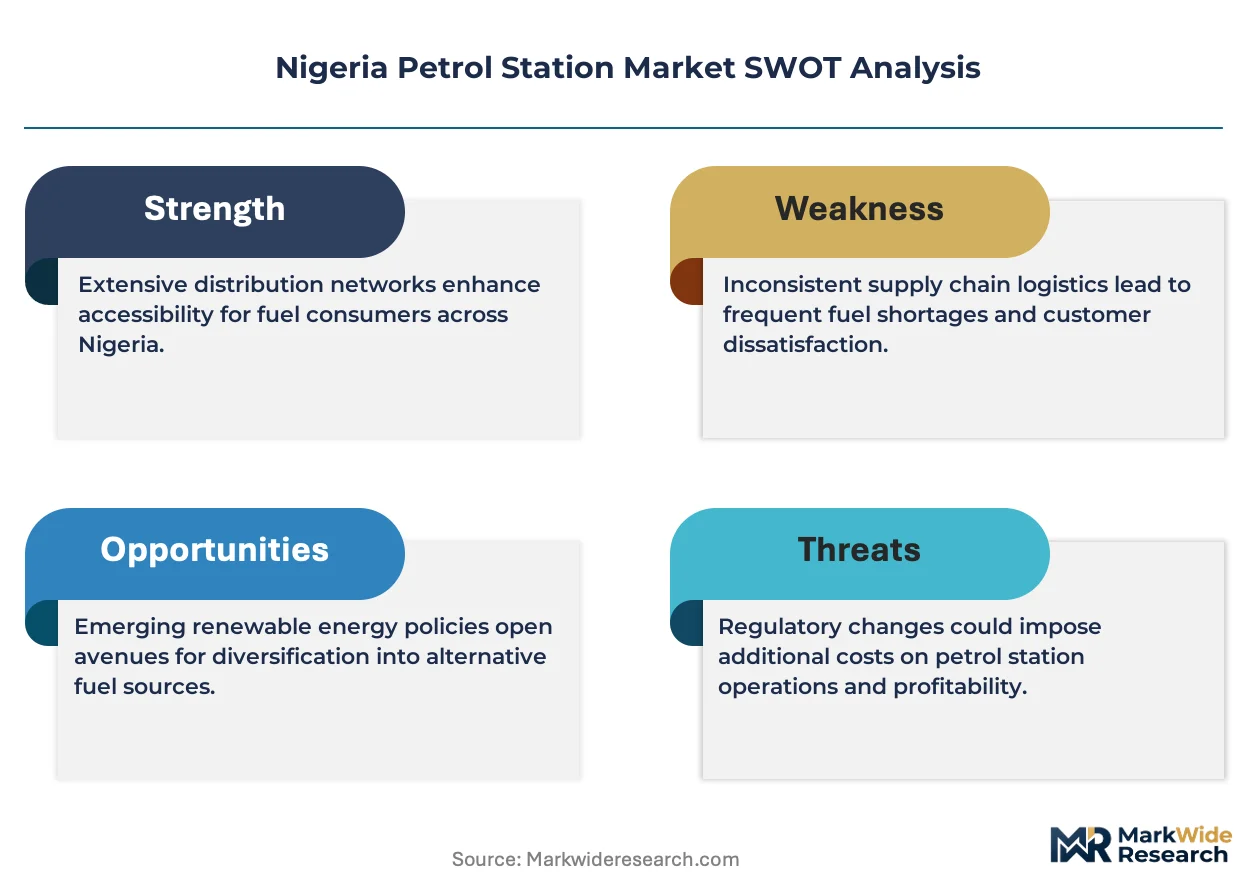
The Petroleum Industry Act is fragmenting Nigeria's petrol station landscape by forcing capital reallocation toward upgraded storage, metering infrastructure, and separate licensing for midstream versus downstream operations. This regulatory compression favors operators with balance sheet depth to absorb compliance costs while squeezing single-site independents into franchise networks or exit.
Growth Catalysts
- Diesel bunkering integration:Fleet operators now consolidate fuel procurement at stations offering on-site lubricant retail and basic maintenance bays, compressing supplier relationships into single-location contracts.
- NNPC pipeline access:Stations connected to federal storage depots through the national pipeline network secure supply continuity during import disruptions, anchoring volume throughput in the northern corridor.
- Smart pump deployment:Cashless payment infrastructure is decomposing fraud exposure and reconciliation costs, accelerating capital flow toward digital-ready sites in Lagos and Port Harcourt.
Market Restraints
- FX access constraints:Dollar-denominated product import obligations strain working capital when central bank foreign exchange windows tighten, forcing stations to absorb margin compression or ration volumes.
- Generator-dependent manufacturing clusters:Industrial diesel demand concentrates in zones with unreliable grid power, creating geographic revenue vulnerability when grid stability improves or factories relocate.
- Underground tank replacement cycles:Corrosion compliance mandates from the Nigerian Midstream and Downstream Petroleum Regulatory Authority impose capital-intensive retrofit obligations on aging station infrastructure.
Strategic Opportunities
- Rivers State corridor expansion:Port traffic through Onne and Port Harcourt sustains throughput volumes underserved by premium-format retail, opening space for mid-tier automated stations.
- LPG retail attachment:Cooking gas cylinder exchange points co-located with petrol retail capture household energy switching from kerosene and firewood.
- Petroleum Industry Act licensing windows:New downstream retail permits issued under consolidated regulatory authority create entry points for capitalized independents in secondary cities.
Industry Challenges
- Pump calibration technician scarcity:Standards Organisation of Nigeria enforcement of metering accuracy requires certified maintenance capacity that outstrips available trained labor pools.
- Legacy tank farm integration:Acquired stations with non-compliant underground storage require extended downtime for excavation and replacement, disrupting revenue during retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Petrol Station Market |
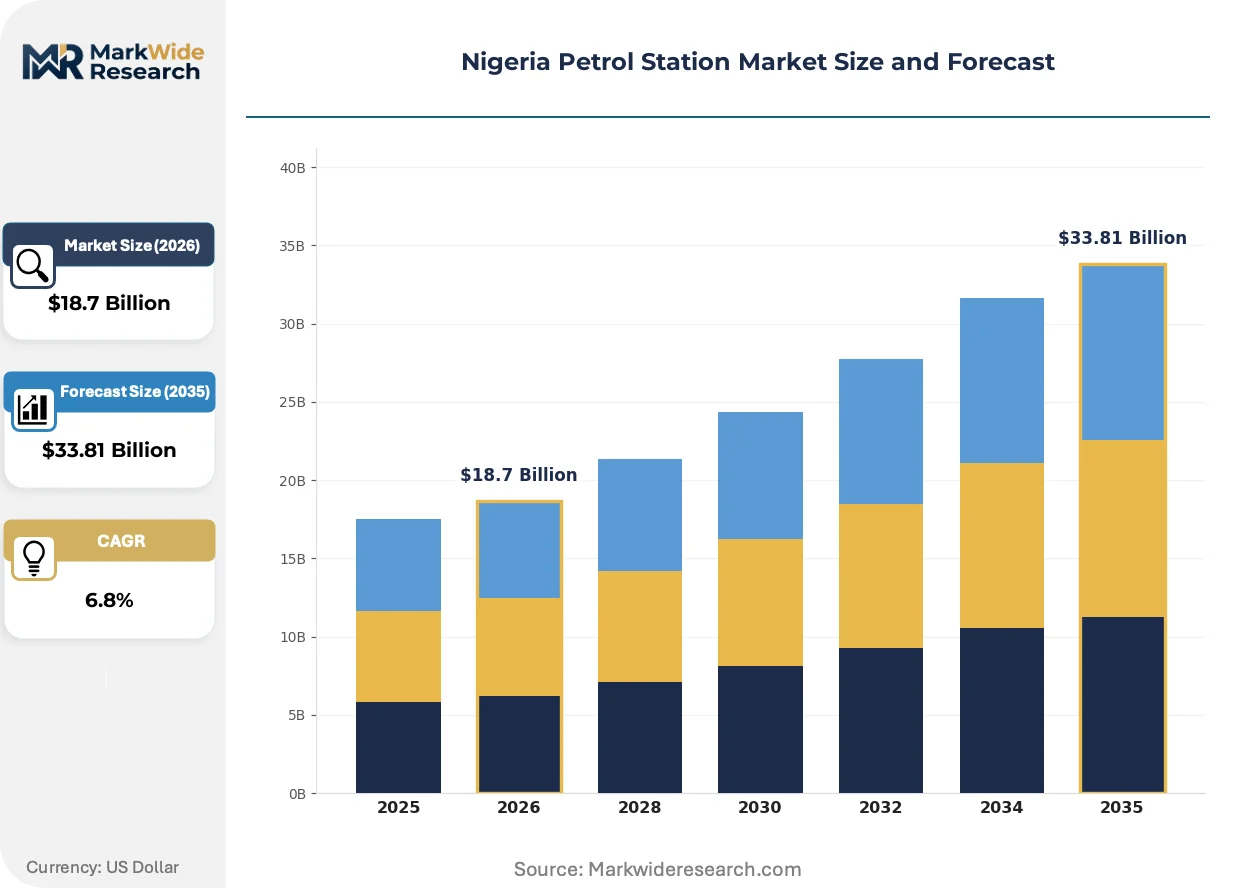
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Service, Self Service, Convenience Store, Fuel Supply Pump Technology: Conventional Pumps, Smart Pumps, Mobile Payment, Fuel Management Systems Fuel Type: Petrol, Diesel, Compressed Natural Gas, Ethanol Ownership Model: Franchise, Independent, Corporate, Consortium |
| Companies Covered | Conoil Plc, Rainoil Limited, NNPC Retail Ltd., Oando PLC, MRS Oil Nigeria Plc, TotalEnergies Marketing Nigeria Plc, 11 Plc (Ex-Mobil), Seplat Energy Plc, Ardova Plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Petrol Station Market Shifts & Advancements
Digital infrastructure is compressing cash handling costs while regulatory consolidation forces operational specialization. Three developments are restructuring competitive positioning across Nigeria's downstream retail network.
Cloud-connected dispensing hardware is decomposing manual reconciliation workflows and fuel theft vulnerabilities. Urban fleet operators and logistics contractors are adopting these systems fastest, prioritizing stations where transaction data flows directly into enterprise resource planning systems. The structural consequence is margin pressure on cash-dependent independents who cannot absorb smart pump capital costs.
The Nigerian Midstream and Downstream Petroleum Regulatory Authority's consolidated licensing framework is eliminating overlapping permit requirements that previously fragmented compliance costs across multiple agencies. Industrial consequence includes accelerated consolidation as multi-site operators spread regulatory overhead across larger station counts. Lagos-based corporate chains are absorbing independent sites to secure permit economies of scale.
Logistics contractors are unbundling fuel procurement from vehicle maintenance relationships, negotiating direct supply contracts with high-volume stations rather than routing through intermediary fleet management providers. This channel compression most visibly affects long-haul transport corridors connecting Lagos to Kano, where direct station relationships now determine contract awards. Fleet procurement officers prioritize sites with real-time inventory visibility and guaranteed diesel availability windows.
Nigeria Petrol Station Market Segmentation
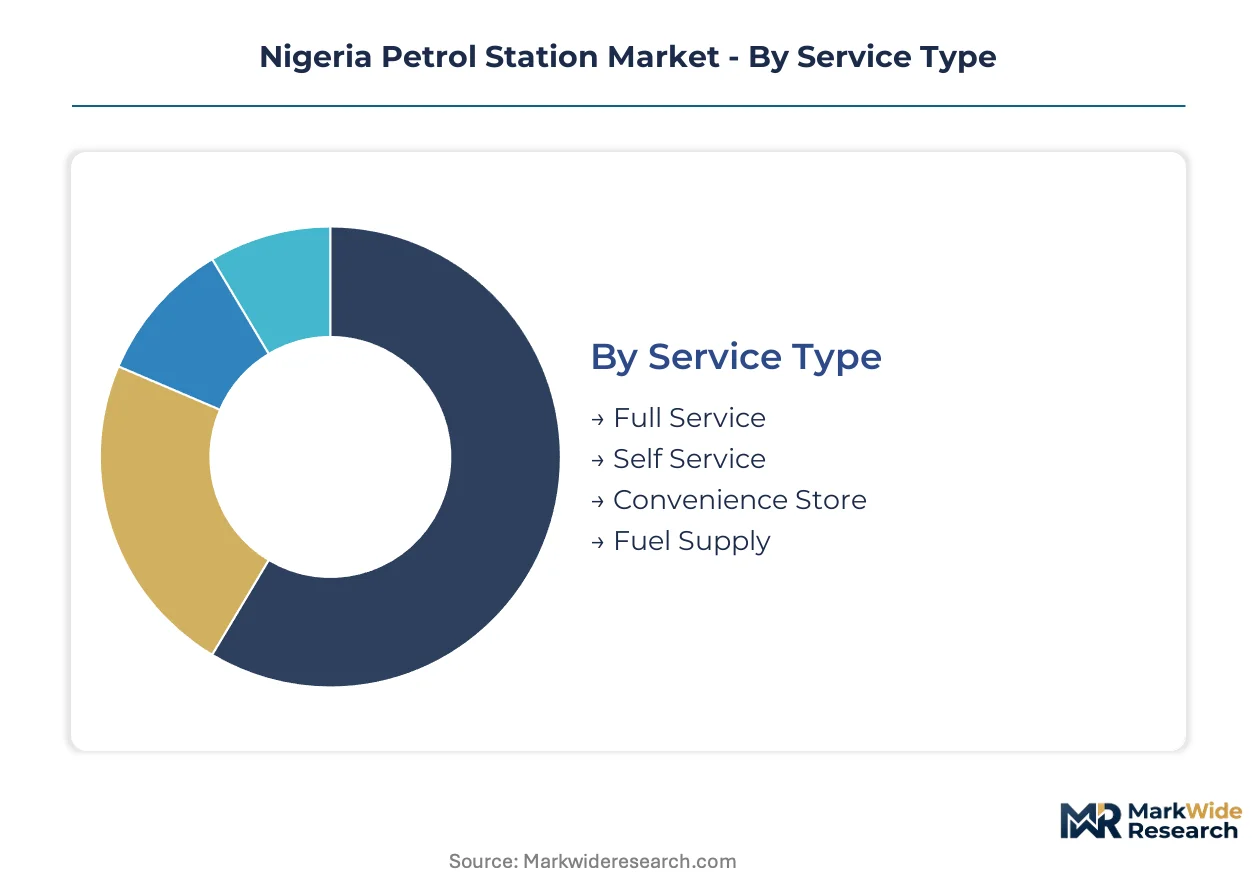
Nigeria's petrol station market fragments across four operational dimensions that determine capital intensity, regulatory exposure, and margin capture. Fleet procurement patterns and Petroleum Industry Act compliance requirements reshape which configurations attract investment.
Service Type:
Margin pools concentrate where ancillary revenue streams offset thin fuel retail spreads, particularly in high-traffic corridors where throughput justifies operational complexity.
- Full Service:Attended dispensing with windshield cleaning and fluid checks commands premium pricing at airport-adjacent stations and executive fleet terminals in Lagos Island. Demand clusters around corporate account holders seeking consolidated invoicing and guaranteed service standards.
- Self Service:Unattended dispensing infrastructure reduces labor costs and accelerates throughput during peak demand windows. Operators deploy these formats along the Lagos-Ibadan expressway where queue management determines market share.
- Convenience Store:Co-located retail captures impulse purchases from captive fuel customers, with highest basket values at stations serving long-haul truckers on the northern corridor.
- Fuel Supply:Bulk diesel delivery contracts to manufacturing estates and generator-dependent industrial parks generate predictable offtake volumes with lower per-liter handling costs.
Full Service holds installed capacity. Self Service is rotating up the share rankings.
Pump Technology:
Capital deployment flows toward configurations that compress reconciliation costs and satisfy Nigerian Midstream and Downstream Petroleum Regulatory Authority metering accuracy mandates.
- Conventional Pumps:Mechanical dispensing units with manual price setting dominate secondary cities where smart infrastructure capital exceeds station operator balance sheet capacity. These systems face escalating compliance pressure from Standards Organisation of Nigeria calibration enforcement.
- Smart Pumps:Cloud-connected dispensing hardware with real-time inventory monitoring and automated reconciliation eliminates fuel theft vulnerabilities. Fleet operators in Port Harcourt prioritize stations deploying these systems for direct ERP integration.
- Mobile Payment:QR-code and USSS-based transaction processing reduces cash handling costs and fraud exposure. Adoption concentrates in Lagos where digital banking penetration supports cashless retail.
- Fuel Management Systems:Enterprise-grade dispensing control with wet-stock management and leak detection addresses environmental compliance for multi-site corporate operators.
Conventional Pumps retains volume leadership. Smart Pumps is climbing the fastest.
Fuel Type:
Commercial transport and power generation demand profiles determine geographic placement and storage infrastructure specifications across Nigeria's downstream network.
- Petrol:Spark-ignition engine fuel for passenger vehicles and motorcycles constitutes baseline throughput at virtually all retail locations. Demand concentrates in urban centers with high private vehicle ownership.
- Diesel:Compression-ignition fuel for commercial transport, industrial equipment, and backup generators commands disproportionate margin contribution from manufacturing clusters in Ogun State and port logistics zones around Onne.
- Compressed Natural Gas:Alternative transport fuel with lower per-unit energy costs attracts fleet conversion trials in Abuja where federal vehicle procurement policies incentivize adoption.
- Ethanol:Biofuel blending component subject to import dependency and foreign exchange access constraints that limit consistent supply availability.
Petrol dominates throughput volumes. Diesel captures premium margin extraction.
Ownership Model:
Capital access and regulatory risk tolerance determine which structures proliferate across Nigeria's fragmented downstream retail landscape.
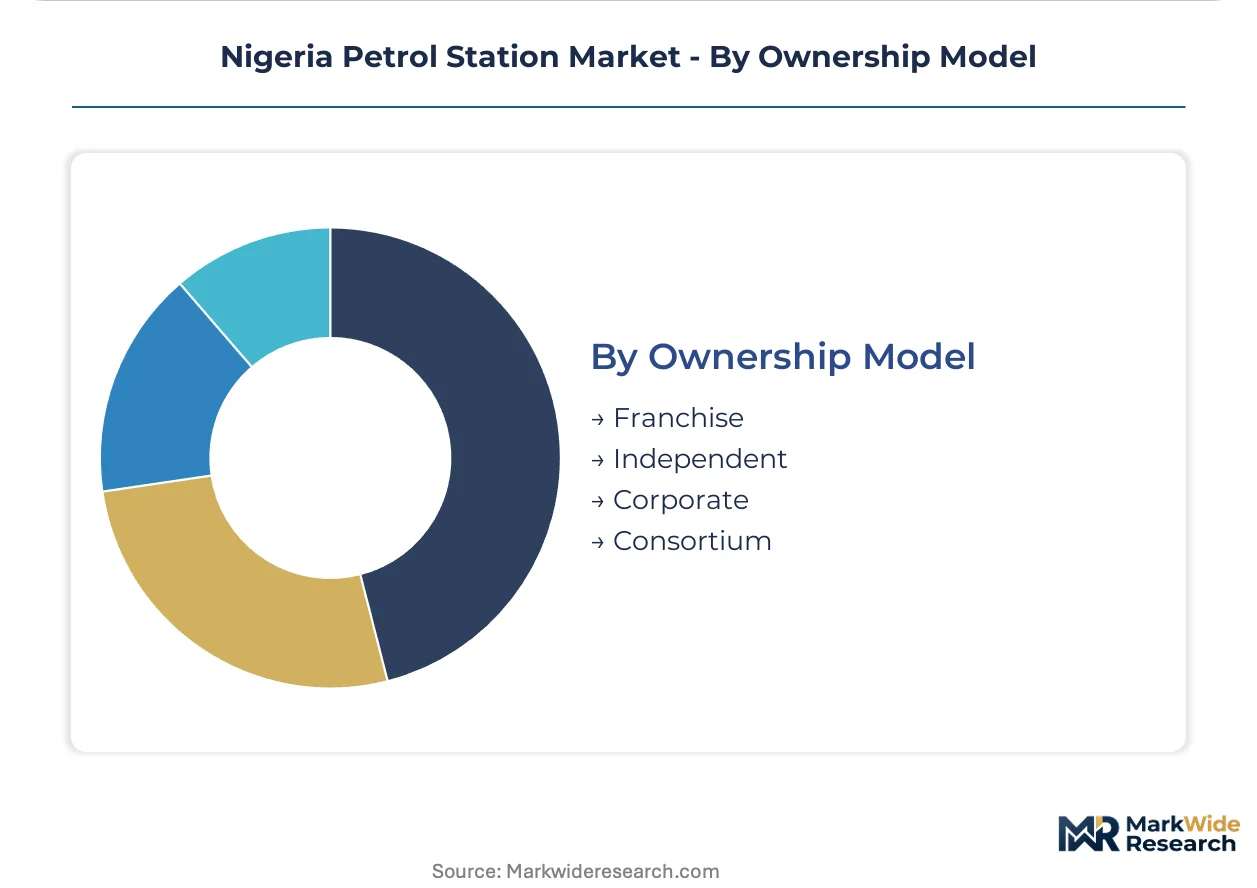
- Franchise:Branded operator agreements with national oil companies or major marketers provide supply security and marketing support. These arrangements dominate secondary cities where local capital reduces deployment risk for corporate licensors.
- Independent:Unaffiliated single-site operators retain pricing autonomy but face supply vulnerability during import disruptions and working capital strain from foreign exchange volatility.
- Corporate:Direct-operated sites with standardized formats and centralized procurement capture urban premium locations where brand consistency justifies higher capital deployment.
- Consortium:Pooled investment structures spread capital requirements across multiple local investors, common for greenfield developments in emerging corridors where individual balance sheets prove insufficient.
Franchise maintains network breadth. Corporate is gaining share fastest in premium locations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply infrastructure concentrates along the Lagos-Port Harcourt corridor, where coastal import terminals and pipeline networks anchor downstream distribution. Federal storage depots in the north sustain throughput across the Kano-Kaduna axis despite distance from marine supply points.
Lagos State
Private vehicle density and port logistics generate Nigeria's highest fuel throughput volumes. The Nigerian Midstream and Downstream Petroleum Regulatory Authority enforces retail licensing standards that favor capitalized operators with multi-site portfolios. Ikeja and Lekki host premium-format stations bundling convenience retail with fleet services.
Rivers State
Industrial diesel demand from Onne port operations and manufacturing estates drives disproportionate margin capture. Standards Organisation of Nigeria calibration mandates apply stringently here due to high-volume commercial accounts. Port Harcourt's Trans Amadi industrial cluster sustains bunkering contracts with logistics contractors.
Ogun State
Generator-dependent manufacturing clusters in Agbara and Otta generate predictable diesel offtake from industrial estates. State environmental regulations on emissions compliance intersect with federal petroleum product quality standards. The Lagos-Ibadan expressway corridor concentrates automated stations serving long-haul freight.
Kano State
NNPC pipeline connectivity from Kaduna refinery corridors secures supply continuity during marine import disruptions. The Nigerian Midstream and Downstream Petroleum Regulatory Authority's downstream licensing framework governs retail permits in this northern commercial hub. Dawanau grain market and surrounding industrial zones sustain commercial transport fuel demand.
Federal Capital Territory
Federal vehicle fleet procurement policies incentivize compressed natural gas conversion trials at selected stations. The Petroleum Industry Act's consolidated regulatory authority coordinates licensing across the Abuja municipal area. Central Business District and airport-adjacent locations command premium positioning for corporate account holders.
Nigeria Petrol Station Market Competitive Landscape
Concentration sits with integrated national marketers controlling import terminals and pipeline access. The competitive structure tiers between NNPC Retail Ltd.'s volume leadership through federal infrastructure, international majors leveraging brand equity at premium urban sites, and indigenous independents competing on price in secondary corridors. Two strategic archetypes dominate: downstream-integrated operators with captive supply chains, and franchise-network licensors deploying local capital. Consolidation accelerates through Petroleum Industry Act compliance costs, while smart pump deployment and convenience retail attachment emerge as primary differentiation vectors.
Among Nigeria-based integrated marketers, Conoil Plc and Oando PLC exemplify the downstream-integrated archetype with coastal terminal control. TotalEnergies Marketing Nigeria Plc occupies a position representing international major presence with branded convenience retail formats. NNPC Retail Ltd. anchors the state-affiliated tier through pipeline access and federal storage depot connectivity.
| Leading Market Players |
|---|
| Conoil Plc |
| Rainoil Limited |
| NNPC Retail Ltd. |
| Oando PLC |
| MRS Oil Nigeria Plc |
| TotalEnergies Marketing Nigeria Plc |
| 11 Plc (Ex-Mobil) |
| Seplat Energy Plc |
| Ardova Plc |
| Others |
Supply & Pricing Matrix
Diesel bunkering substitution for kerosene-powered industrial generators simultaneously redraws fuel procurement geography around Lagos port corridors and compresses margin capture at stations lacking integrated logistics services. This displacement dynamic concentrates pricing power with operators controlling coastal import terminals and pipeline-fed federal storage depots.
Pricing Analysis
The Petroleum Industry Act dictates the pricing tier structure across Nigeria's downstream retail network, separating corporate-operated urban premium stations from franchise-dependent secondary city outlets and price-competitive independents. Price differentiation hinges on smart pump certification grade and volume scale, with fleet operators commanding discounts against walk-up retail. Pricing pressure stems from foreign exchange access constraints on dollar-denominated product imports, forcing margin compression or volume rationing. Single-site independents exhibit highest price sensitivity, while corporate chains with captive supply chains absorb cost volatility.
Supply Chain Analysis
Strategic stockpile preferences dominate petrol station inventory management, with NNPC pipeline-connected depots maintaining buffer stocks against marine import disruptions. Supply concentrates in Belgium, the Netherlands, and the United States as source markets for refined product cargoes. Raw material dependencies include crude oil feedstocks, ethanol blending components, and lubricant base oils. Single-source vulnerability runs through the Lagos-Port Harcourt coastal terminal corridor. Distribution runs through a hub-and-spoke model anchored at federal storage depots with secondary trucking to retail sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Petroleum Industry Act compliance costs are fragmenting Nigeria's petrol station landscape, creating acquisition opportunities for capitalized operators as single-site independents face forced exit or franchise conversion.
For Market Incumbents: Secure pipeline access agreements with NNPC Retail Ltd. to anchor supply continuity during import disruptions, and accelerate smart pump deployment across northern corridor sites to capture fleet procurement contracts. Vertical integration into coastal import terminals defends margin position against foreign exchange volatility. For New Entrants and Emerging Players: Lead with automated self-service formats in Rivers State's underserved port logistics zones, where Onne and Trans Amadi industrial clusters generate diesel bunkering demand. Target consortium ownership structures in Kano State to spread Petroleum Industry Act licensing capital requirements across local investor pools. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier marketers lacking downstream terminal control. Long-term viability centers on acquisition targets with NNPC pipeline connectivity or coastal import infrastructure. Watch petroleum subsidy removal timelines as the inflection signal for working capital requirement shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Pump Infrastructure Deployment | Cloud-connected dispensing hardware eliminates fuel theft vulnerabilities and enables direct ERP integration with fleet operators. |
| LPG Retail Attachment | Cooking gas cylinder exchange points co-located with petrol retail capture household energy switching from kerosene. |
| Pipeline Access Agreement | NNPC pipeline connectivity secures supply continuity during marine import disruptions and anchors volume throughput. |
| Franchise Network Consolidation | Absorbing independent sites spreads Petroleum Industry Act compliance costs across larger station counts. |
| Diesel Bunkering Integration | On-site lubricant retail and basic maintenance bays compress fleet supplier relationships into single-location contracts. |
Research Methodology
A standing panel of petroleum retail operations managers, fleet procurement officers, Nigerian Midstream and Downstream Petroleum Regulatory Authority licensing officials, and downstream logistics contractors provided ongoing calibration. Primary fieldwork combined structured interviews with secondary validation through NNPC supply reports, Standards Organisation of Nigeria calibration enforcement records, and Petroleum Industry Act regulatory filings. Bottom-up station count modeling and top-down fuel consumption estimates were triangulated against customs import data.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation dimensions including service type, pump technology, fuel type, and ownership model alongside geographic corridor density. CAGRs were derived from throughput volume trajectories and retail margin evolution. Forecast inputs incorporated petroleum subsidy removal scenarios and foreign exchange access rule changes.
Forecasts assume regulatory continuity in Nigerian petroleum downstream licensing; material policy shifts would require re-modeling. Specific risk factors include Standards Organisation of Nigeria calibration enforcement intensity and NNPC supply allocation priority changes. Revision becomes warranted when diesel bunkering contract volumes cross thresholds indicating fleet procurement pattern shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Longitudinal Submerged-Arc Welded (LSAW) Pipes Market
Petroleum Products
East Africa Refined Petroleum Products Market
Petroleum Products
South Africa Petroleum Market
Petroleum Products
Alkylate Gasoline Market
Petroleum Products
Petcoke Market
Petroleum Products
West Africa Refined Petroleum Products Market
Petroleum Products
Crude Oil Pour Point Depressant Market
Petroleum Products
Paraffin Oil Market
Petroleum Products
Crude Oil Market
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
Green Petcoke Market
Petroleum Products
Spindle Oil Market
Petroleum Products
Very Low Sulphur Fuel Oil (VLSFO) Market
Petroleum Products
Base Oil Market
Petroleum Products
South Africa Refined Petroleum Products Market
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market