
 Natural Refrigerants Market | 2026-2036
Natural Refrigerants Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Refrigerants Market Intelligence
Revenue from integrated cooling system design and lifecycle services is reshaping the profit landscape, pulling value from commodity refrigerant sales. This shift favors engineering-led firms over pure chemical suppliers. Linde plc leverages its extensive industrial gas distribution network to supply bulk ammonia and carbon dioxide. Daikin Industries leads in developing and marketing complete CO2-based commercial refrigeration units, while Honeywell International Inc. focuses on developing ultra-low GWP alternatives to bridge the transition.
Natural refrigerants are substances found in nature that serve as heat-transfer fluids, possessing near-zero global warming potential. These compounds, including ammonia (R-717) and carbon dioxide (R-744), are deployed to replace synthetic hydrofluorocarbons (HFCs). While ammonia leads in the industrial process cooling application segment, carbon dioxide systems are expanding rapidly for commercial cooling. Hydrocarbons like propane see significant use in smaller-scale food and beverage preservation equipment.
Regulatory frameworks are the primary market accelerant, with the EU F-Gas Regulation mandating steep HFC reductions and outright bans. In the United States, the EPA's SNAP program restricts high-GWP refrigerants, while regulations in Japan and Australia also promote lower-GWP solutions. System operators must now weigh the higher initial capital cost of natural refrigerant systems against long-term operational savings and regulatory certainty.
Market Dynamics
The global phase-down of hydrofluorocarbons (HFCs) under legally binding frameworks like the EU F-Gas Regulation is the central force shaping the market, compelling a transition towards natural alternatives in commercial and industrial cooling applications.
Growth Catalysts
- Regulatory Mandates:The EU F-Gas Regulation and the US EPA's SNAP program create non-negotiable deadlines for phasing out high-GWP HFCs, directly stimulating demand for compliant ammonia, CO2, and hydrocarbon systems in new equipment and retrofits.
- End-Use Demand:Supermarkets and retail food chains are increasingly specifying natural refrigerant systems to lower operational energy costs, achieve corporate sustainability goals, and mitigate the risk of future regulatory non-compliance and refrigerant price volatility.
- Technological Maturation:Advancements in CO2 transcritical system components, such as ejectors and parallel compression, have improved energy efficiency in warmer climates, broadening the geographic applicability and economic case for CO2-based commercial refrigeration.
Market Restraints
- Capital Cost:Natural refrigerant systems, particularly industrial-scale ammonia and high-pressure transcritical CO2 installations, often carry a higher initial investment cost compared to traditional HFC-based equipment, acting as a barrier for budget-constrained operators.
- Technical Limitations:The flammability of hydrocarbons like propane and isobutane restricts their use to small charge sizes, limiting their application in larger commercial systems and requiring specialized safety measures that add complexity and cost.
- Safety Concerns:The toxicity of ammonia (R-717) and the high operating pressures of carbon dioxide (R-744) systems necessitate stringent safety protocols, specialized components, and robust technician training, which can complicate installation and maintenance.
Strategic Opportunities
- Service and Retrofit Market:A substantial opportunity exists in retrofitting the vast installed base of HFC systems in supermarkets and cold storage facilities, particularly with cascade or secondary loop systems that use a natural refrigerant.
- Emerging Geographies:Markets in Latin America and Southeast Asia, where supermarket infrastructure is expanding and environmental regulations are beginning to tighten, represent significant greenfield opportunities for natural refrigerant system deployment.
- Heat Recovery Integration:Designing CO2 refrigeration systems with integrated heat recovery capabilities allows facilities to utilize waste heat for space heating or hot water, creating an additional value proposition by improving the building's overall energy efficiency.
Industry Challenges
- Technician Skill Gap:A persistent shortage of engineers and service technicians with the requisite skills to safely design, install, and maintain high-pressure CO2 and toxic ammonia systems constrains the pace of market adoption.
- Component Standardization:A lack of full standardization for components across different natural refrigerant system types can lead to supply chain bottlenecks and complicates the maintenance and servicing of equipment from various manufacturers.
- Legacy System Integration:Integrating new natural refrigerant equipment with older, existing building management systems and controls in retrofit projects presents a significant technical challenge, often requiring custom engineering solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Refrigerants Market |
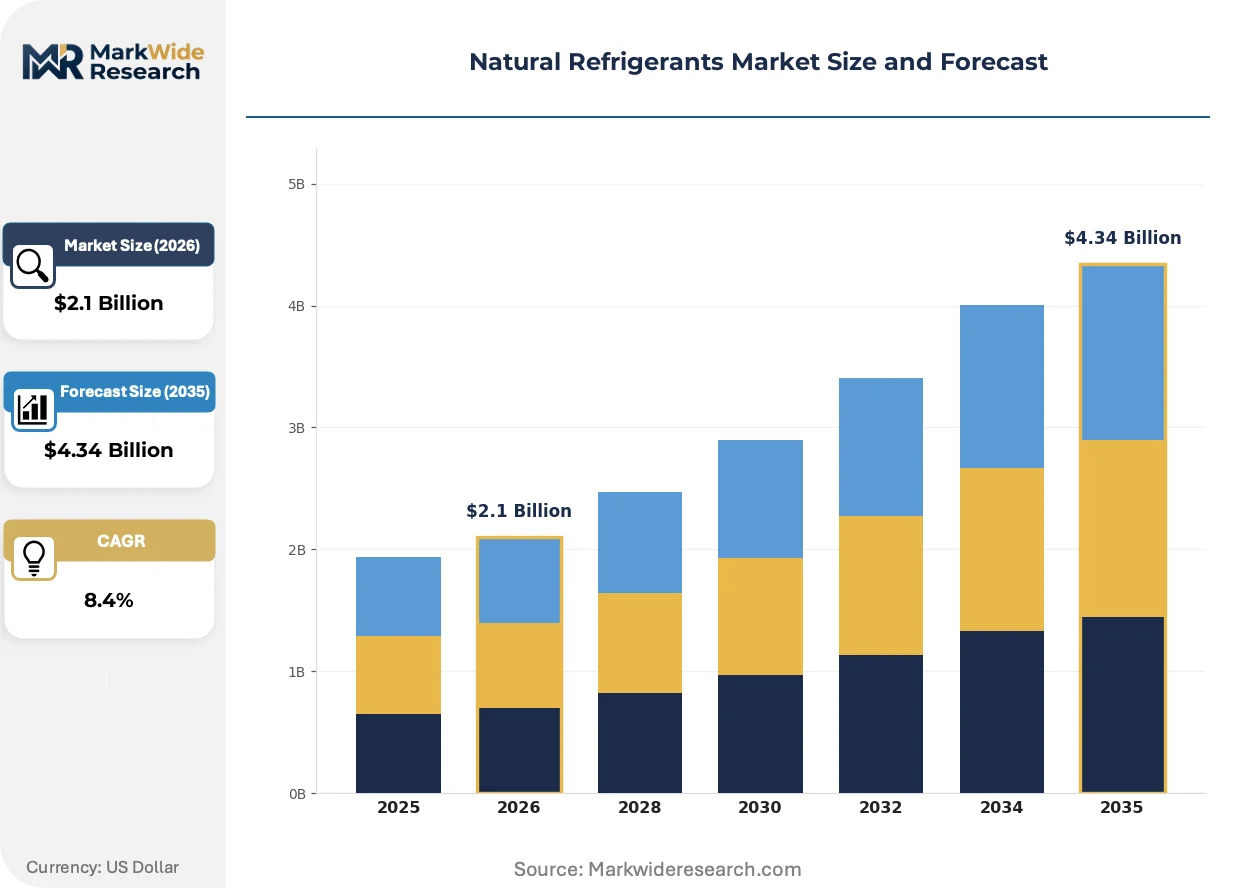
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Refrigerant Type: Ammonia, Carbon Dioxide, Hydrocarbons, Water, Air Application: Commercial Cooling, Industrial Process Cooling, Residential Air Conditioning, Food & Beverage Preservation, Pharmaceutical Storage End User Industry: Cold Storage Facilities, Food Processing Units, Beverage Manufacturers, Chemical Plants, Data Centers Distribution Channel: Direct Sales, Distributors, Online Platforms, OEM Partnerships, Aftermarket Suppliers |
| Companies Covered | AGC Inc., The Chemours Company, Air Liquide, Daikin Industries, Arkema, Linde plc, Honeywell International Inc., Güntner, Airgas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Refrigerants Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from component sales to integrated system performance. Technology and service models are converging to address total cost of ownership and energy efficiency, moving value away from the commodity refrigerant itself.
Transcritical CO2 booster systems integrate multiple temperature cooling loads into a single, efficient rack architecture. Supermarkets and distribution centers are adopting this technology to replace disparate HFC units. The incorporation of advanced components like gas ejectors is collapsing the energy efficiency gap that previously limited these systems to cooler climates, thereby expanding their global addressable market.
The United States EPA's Significant New Alternatives Policy (SNAP) program continues to delist high-GWP HFCs for use in new refrigeration equipment. This regulatory pressure forces a direct transition to alternatives like ammonia and CO2 in targeted applications. The industrial cold storage and food processing sectors are most impacted, accelerating investment in ammonia-based solutions to ensure long-term compliance.
A significant behavioral change is occurring as end-users move from simple equipment purchasing to adopting holistic lifecycle management contracts. This model displaces the traditional focus on upfront capital cost with an emphasis on total cost of ownership, including energy consumption, maintenance, and regulatory compliance. This trend is most prominent in Europe, where major food retailers partner with specialized engineering firms for complete system design and optimization.
Natural Refrigerants Market Segmentation
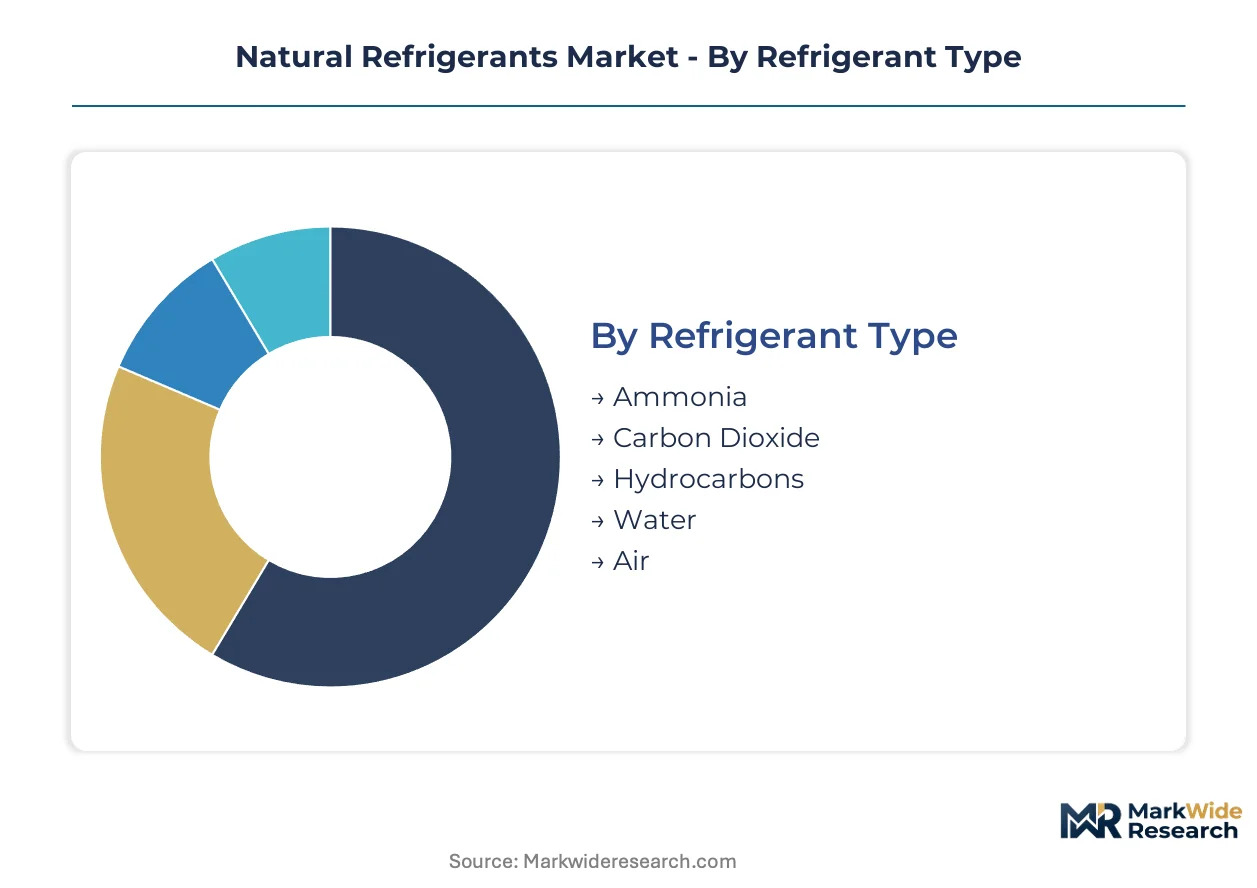
The natural refrigerants market is segmented to reflect the diverse technical requirements and regulatory pressures driving its expansion. Understanding these distinct segments helps identify specific growth pockets and technological preferences across various end-use sectors. This market analysis delineates how different refrigerant types and applications shape commercial strategies.
Refrigerant Type:
The natural refrigerant landscape spans mature, established solutions alongside emerging, innovative alternatives.
- Ammonia:Ammonia (R-717) is a highly efficient natural refrigerant with excellent thermodynamic properties, characterized by its toxicity and flammability. It dominates the industrial process cooling segment, particularly within large cold storage facilities in Germany and the United States, driven by its energy efficiency and regulatory compliance.
- Carbon Dioxide:Carbon dioxide (R-744) operates at high pressures, offering superior heat transfer and near-zero global warming potential, often used in transcritical systems. Commercial cooling applications, especially in supermarkets and retail food chains across Europe, show strong uptake, accelerated by advancements in ejector technology for warmer climates.
- Hydrocarbons:Hydrocarbons like propane and isobutane serve smaller-scale food and beverage preservation equipment due to their flammability and low GWP.
- Water:Water (R-718) acts as a natural refrigerant in absorption chillers and certain specialized industrial cooling systems, offering a non-toxic, non-flammable option.
- Air:Air (R-729) is employed in niche cryogenic and specialized refrigeration applications, valued for its abundant availability and environmental inertness.
Ammonia handles the majority of industrial throughput; carbon dioxide is the fastest mover on commercial share.
Application:
Application segments delineate where natural refrigerants deliver specific performance advantages, ranging from large-scale industrial use to precise temperature control.
- Commercial Cooling:This segment encompasses refrigeration systems for supermarkets, retail stores, and commercial buildings, requiring reliable and energy-efficient cooling for diverse product ranges. Supermarkets and food retailers in Europe and the United States are specifying these systems to meet sustainability goals and comply with HFC phase-down regulations.
- Industrial Process Cooling:Industrial process cooling involves large-scale refrigeration for manufacturing, chemical processing, and cold storage, demanding high capacity and continuous operation. Cold storage facilities and food processing units in Germany and the Netherlands represent significant demand centers, prioritizing ammonia-based systems for their efficiency.
- Residential Air Conditioning:Residential air conditioning applications are an emerging segment, with hydrocarbons seeing limited use in smaller, split-system units.
- Food & Beverage Preservation:This segment utilizes natural refrigerants in various equipment, from display cases to walk-in coolers, ensuring product integrity.
- Pharmaceutical Storage:Pharmaceutical storage requires precise temperature control, with CO2 systems gaining traction for their reliability and environmental profile in specialized facilities.
Industrial and commercial cooling applications concentrate the bulk of natural refrigerant volume; pharmaceutical storage represents a growing niche.
End User Industry:
End-user industries are distinguished by their unique operational requirements and the critical need for reliable, compliant cooling infrastructure.
- Cold Storage Facilities:These facilities demand robust, high-capacity refrigeration systems to maintain consistent low temperatures over large volumes, often integrating complex logistics. Operators in Germany and the Netherlands are investing in ammonia-based solutions to achieve significant energy savings and long-term regulatory certainty.
- Food Processing Units:Food processing environments require precise temperature control across various stages, from chilling to freezing, ensuring product safety and quality. Beverage manufacturers and meat processing plants are increasingly adopting natural refrigerants to enhance sustainability and mitigate future HFC-related operational risks.
- Beverage Manufacturers:Beverage manufacturers employ natural refrigerants for chilling, fermentation, and storage, aligning with corporate sustainability objectives.
- Chemical Plants:Chemical plants utilize industrial-scale natural refrigerant systems for process cooling, where safety and efficiency are paramount.
- Data Centers:Data centers represent an emerging application for natural refrigerants, particularly water and CO2, to manage heat loads efficiently and reduce energy consumption.
Cold storage and food processing units are strategically vital for market expansion; data centers offer significant future growth potential.
Distribution Channel:
Distribution channels reflect the varied routes to market, from direct manufacturer engagement to specialized service providers.
- Direct Sales:This channel involves manufacturers selling directly to large industrial end-users or major commercial chains, often including custom design, installation, and commissioning services. Engineering-led firms like Daikin Industries leverage direct sales for complex CO2-based commercial refrigeration units, ensuring integrated system performance and customer support.
- Distributors:Distributors offer localized sales, technical support, and inventory for a range of natural refrigerant components and pre-packaged systems, serving a broader customer base. This channel is crucial for reaching smaller commercial operators and facilitating retrofits, especially for hydrocarbon-based equipment in diverse geographic markets.
- Online Platforms:Online platforms are gaining traction for smaller components and standardized natural refrigerant equipment, offering convenience and broader accessibility.
- OEM Partnerships:Original Equipment Manufacturer (OEM) partnerships integrate natural refrigerant technology directly into new cooling appliances and industrial machinery.
- Aftermarket Suppliers:Aftermarket suppliers provide essential parts, maintenance services, and retrofit kits for existing natural refrigerant systems, supporting their lifecycle.
Direct sales ensure integrated solutions for complex projects; distributors provide efficient market reach for standardized products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for natural refrigerants exhibits varying elasticity across global markets, with industrial users in mature economies prioritizing long-term operational savings over initial capital costs. Conversely, emerging markets often weigh upfront investment more heavily against environmental mandates. Regulatory certainty significantly influences adoption rates in both segments.
Germany
Demand for ammonia-based systems in Germany stems from stringent environmental regulations and a focus on energy efficiency within cold storage. The EU F-Gas Regulation drives the transition from HFCs, compelling investment in compliant solutions. Industrial clusters in Bavaria and North Rhine-Westphalia are actively retrofitting large-scale food processing and logistics centers.
United States
The United States market sees strong uptake of ammonia and CO2 systems, particularly in industrial cold storage and food processing sectors. The EPA's SNAP program restricts high-GWP refrigerants, accelerating investment in natural alternatives. Major distribution hubs in the Midwest and California are upgrading their refrigeration infrastructure.
Netherlands
Netherlands cold storage facilities prioritize natural refrigerants due to high energy costs and strict environmental targets. EU F-Gas Regulation compliance ensures a steady shift to ammonia and CO2 solutions. Port cities like Rotterdam and Amsterdam are hubs for advanced refrigeration technology deployment in logistics centers.
Japan
Japanese regulations promote lower-GWP solutions, driving demand for CO2 systems in commercial refrigeration and heat pump applications. METI initiatives encourage the adoption of energy-efficient natural refrigerant technologies across various industries. Urban centers like Tokyo and Osaka are implementing CO2 transcritical systems in supermarkets and convenience stores.
Brazil
Brazil's expanding supermarket infrastructure creates significant greenfield opportunities for natural refrigerant systems, especially CO2. Environmental regulations, though less stringent than Europe, are gradually tightening, influencing new installations. Major metropolitan areas like São Paulo and Rio de Janeiro are seeing increased deployment of these systems in retail chains.
Natural Refrigerants Market Key Industry Players
Engineering-led firms and established chemical suppliers split the market for natural refrigerants, reflecting distinct value propositions. Engineering-led firms focus on integrated system design and lifecycle services, capturing value from total cost of ownership. Chemical suppliers leverage extensive distribution networks for bulk refrigerant sales and specialized formulations. Strategic partnerships between equipment manufacturers and chemical producers are a dominant competitive move, alongside continuous technological maturation in system components.
Leading industrial gas suppliers, such as Linde plc, exemplify companies leveraging extensive global distribution networks to supply bulk ammonia and carbon dioxide, serving large-scale industrial and commercial users. These firms benefit from established infrastructure and deep customer relationships in gas delivery. Meanwhile, Daikin Industries represents an engineering-led firm, specializing in developing and marketing complete CO2-based commercial refrigeration units, emphasizing integrated system performance. Honeywell International Inc. occupies a position among manufacturers developing ultra-low GWP alternatives, bridging the transition period for various applications requiring specific chemical properties.
| Leading Market Players |
|---|
| AGC Inc. |
| The Chemours Company |
| Air Liquide |
| Daikin Industries |
| Arkema |
| Linde plc |
| Honeywell International Inc. |
| Güntner |
| Airgas |
| Others |
Cost & Logistics Intelligence
The European cold chain logistics corridor faces cost dynamics that influence both refrigerant supply concentration and downstream price differentiation for natural systems. This market balances the higher initial investment of natural refrigerants against long-term operational savings and regulatory certainty.
Pricing Analysis
After-sales service and extended lifecycle contracts drive significant lifetime value for natural refrigerant systems. Value-based pricing dominates integrated system design, reflecting superior energy efficiency and environmental compliance. Price differentiation stems from customization level for large industrial projects and the brand premium commanded by established engineering firms. Pricing softness reflects the higher initial capital cost hurdle for natural refrigerant systems. Budget-constrained operators are most price-sensitive, while large industrial users prioritize long-term operational savings.
Supply Chain Analysis
Component manufacturing capacity for natural refrigerant systems concentrates in Germany and Japan. The supply chain draws from specialized high-pressure compressors, heat exchangers, and industrial-grade ammonia feedstock. Single-source vulnerability for specialized high-pressure components represents a structural risk. Distribution runs through direct sales channels for complex industrial projects and specialized distributors for standardized commercial equipment and smaller components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The natural refrigerants market is in a cyclical recovery phase, driven by the accelerating HFC phase-down mandates globally.
For Market Incumbents:
Entrench market share through strategic acquisitions of specialized service providers, enhancing lifecycle support capabilities. Deepen vertical integration into advanced component manufacturing to mitigate supply chain risks and control intellectual property. Invest in R&D for transcritical CO2 efficiency in warmer climates to counter the threat of commoditization in basic HFC replacements. Establish exclusive distributor agreements to maintain channel control against emerging low-cost system integrators.
For New Entrants and Emerging Players:
Underpenetration in Southeast Asian and Latin American supermarket infrastructure offers significant greenfield opportunities. Target the retrofit market for HFC systems in mid-sized North American retail, which presents a penetrable segment. Offer modular, pre-engineered CO2 systems with simplified installation requirements. Bundled energy efficiency and maintenance contracts can provide a compelling go-to-market angle for cost-conscious operators.
For Investors and Strategic Acquirers:
Specialized engineering firms with proprietary CO2 system designs or regional service and maintenance providers for ammonia systems represent attractive acquisition archetypes. The long-term viability of natural refrigerant solutions is assured over the next decade due to regulatory certainty. An inflection indicator is the acceleration of HFC phase-down schedules in emerging economies, signaling expanded market opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increasing manufacturing capacity for CO2 compressors supports market growth. |
| Backward Integration | Controlling key component supply mitigates single-source risks for system integrators. |
| Green Manufacturing Transition | Adopting sustainable production methods enhances brand reputation and compliance. |
| Long-term Supply Agreement | Securing stable bulk refrigerant supply ensures operational continuity for large users. |
| Joint Venture | Partnerships with HVAC firms expand market reach for natural refrigerant technologies. |
Research Approach
Initial hypotheses were tested against primary input from refrigeration engineers, facility managers, chemical suppliers, and regulatory compliance officers. This primary research was validated through secondary data sources, including EU F-Gas Regulation documents, EPA SNAP program reports, corporate sustainability disclosures, and industrial gas association publications. This data was triangulated using both bottom-up market sizing and top-down validation against industry forecasts.
Demand-supply balance modeling projected market evolution across the analysis window, considering technological advancements and regulatory shifts. The framework segmented the market by refrigerant type, application, end-user industry, distribution channel, and geographic region. Compound annual growth rates were derived from historical data, projected market drivers, and expert consensus, using HFC phase-down schedules and energy efficiency mandates as key inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new system integrators or chemical suppliers would shift outcomes. Unforeseen technological breakthroughs or significant policy reversals could alter market trajectories. Quarterly review of regulatory updates and new system installations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Control Solutions
Emission Control Technology Market
Environmental Control Solutions
CO2 Injector (CO2 Bubbler) Market
Environmental Control Solutions
North America Industrial Emission Control Systems Market
Environmental Control Solutions
Global Ballast Water Treatment Systems Market
Environmental Control Solutions
Gas Cleaning Technologies Market
Environmental Control Solutions
Enclosed Waste Gas Flares Market
Environmental Control Solutions
Residential Water Softening Systems Market
Environmental Control Solutions
Manufacturing Scale Electrostatic Precipitator Market
Environmental Control Solutions
Modular Energy Control System Market
Environmental Control Solutions
Scrubber System Market
Environmental Control Solutions
Sailboat Ballast Water Treatment Technology Market
Environmental Control Solutions
Global Leak Detection and Repair (LDAR) Market
Environmental Control Solutions
Electrostatic Precipitator Market
Environmental Control Solutions
Thermal Incinerator Market
Environmental Control Solutions
Global Flue Gas Desulphurization Market
Environmental Control Solutions
Ozone Generator Market