
 South America Generator Sets Market | 2026-2036
South America Generator Sets Market Size, Share, and Industry Trends Forecast 2026-2036
South America Generator Sets Market Analytics
The capital-intensity divergence between engine manufacturing and assembly-only operations is rotating competitive advantage toward integrated producers. Cummins Inc leverages in-house engine foundry capacity to anchor cost structures across Brazilian assembly lines. Caterpillar Inc sustains premium positioning through dealer network control in Chilean mining territories. Generac Holdings Inc competes via residential standby specialization in Argentine urban centers.
Generator sets are self-contained engine-alternator assemblies converting mechanical energy into electrical power, typically rated between 10 kW and 500+ kW for commercial and industrial applications. Diesel product types dominate South American installations due to fuel availability and torque characteristics for heavy-load starting. The 100-300 kW capacity band captures expanding commercial demand from Brazilian data centers and Peruvian agro-processing facilities. Industrial end users represent the deepest margin pool, with government procurement offering volume stability through ANEEL-mandated backup requirements for hospitals and utilities.
Brazil's ANEEL enforces grid interconnection standards that mandate backup power duration for critical infrastructure, directly shaping generator set sizing specifications. Argentina's Secretaría de Energía and Chile's SEC impose emissions testing protocols that filter out uncertified imports from regional markets. Stakeholders must monitor regulatory divergence between Mercosur harmonization efforts and country-specific technical barriers as the primary determinant of cross-border product strategy.
Market Dynamics
ANEEL-mandated backup power duration requirements for Brazilian critical infrastructure are compressing procurement cycles and forcing specification upgrades across the 100-300 kW capacity band. Mining electrification in Chile and Peru is simultaneously pulling heavy-duty genset demand while straining supplier lead times.
Growth Catalysts
- Grid Reliability Mandates:Brazil's ANEEL interconnection standards require hospitals and utilities to maintain minimum backup power duration, directly expanding genset sizing specifications and replacement frequency.
- Mining Expansion:Copper and lithium extraction operations in Chile's Atacama Desert and Peru's Andean highlands are procuring 500+ kW units for remote site electrification.
- Data Center Buildout:São Paulo's cloud infrastructure cluster is absorbing continuous-duty diesel gensets for tier-three facility certification compliance.
Market Restraints
- Import Tariff Volatility:Mercosur's Common External Tariff fluctuations on Chinese alternator assemblies create margin compression for Brazilian assemblers.
- Emissions Certification Friction:Chile's SEC and Argentina's Secretaría de Energía impose divergent testing protocols that block cross-border product standardization.
- Natural Gas Infrastructure Gaps:Pipeline network deficiencies in Colombia and Ecuador prevent gas genset substitution despite lower operating costs.
Strategic Opportunities
- Hybrid Microgrids:Solar-diesel hybrid configurations are penetrating Peruvian agro-processing facilities where grid extension remains uneconomical.
- Argentine Urban Standby:Buenos Aires metropolitan area shows underpenetration in residential automatic transfer switch installations versus São Paulo benchmarks.
- Biogas Feedstock Access:Brazil's sugarcane bagasse and livestock waste streams enable distributed generation projects qualifying for national renewable energy incentives.
Industry Challenges
- Technical Service Scarcity:Factory-trained technicians for electronic engine management systems remain concentrated in São Paulo and Santiago, leaving remote mining sites dependent on fly-in maintenance.
- Parts Inventory Synchronization:Long-lead turbocharger and common-rail injection components require working capital commitments that strain distributor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Generator Sets Market |
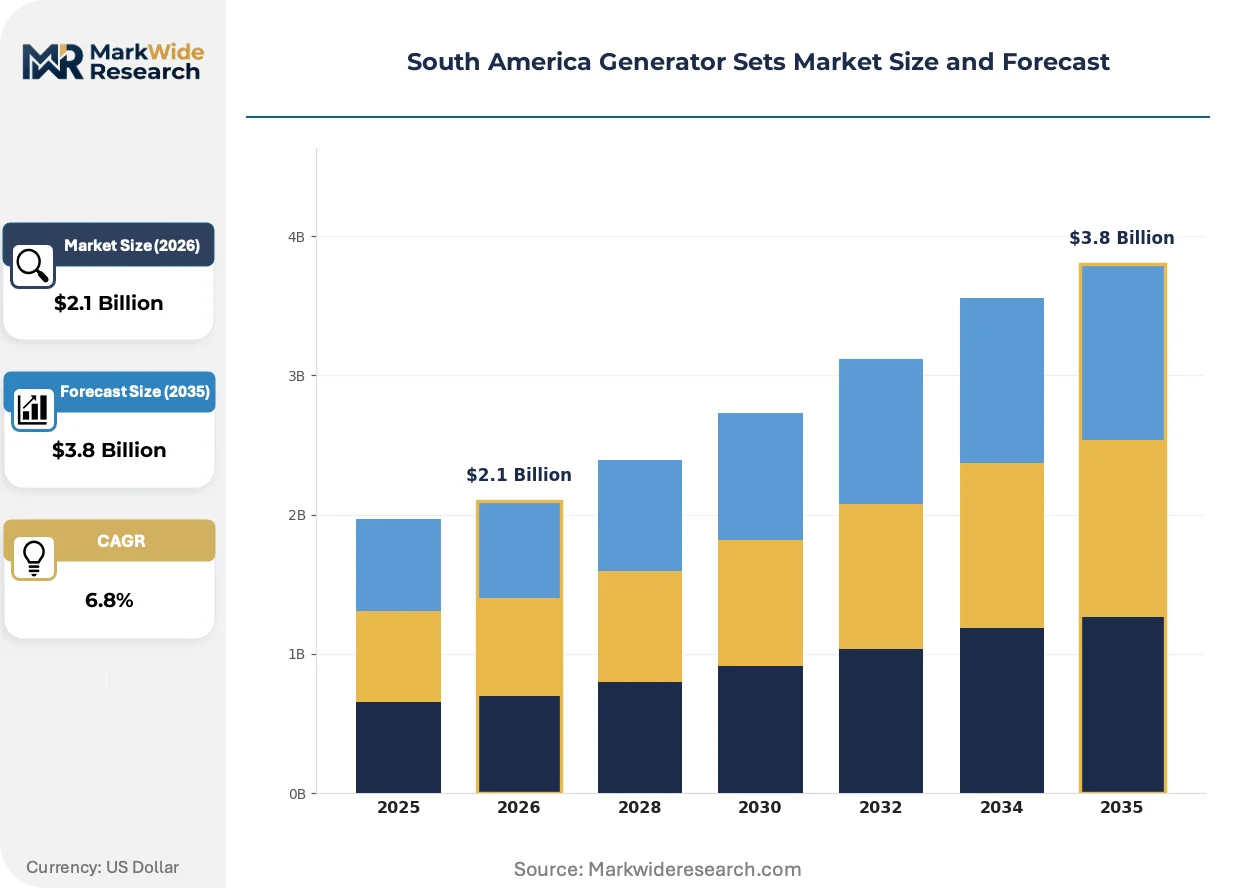
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel, Gas, Portable, Standby End User: Industrial, Commercial, Residential, Government Installation: Onsite, Remote, Mobile, Fixed Capacity: 10-100 kW, 100-300 kW, 300-500 kW, 500+ kW |
| Companies Covered | Kohler Co, Generac Holdings Inc, Caterpillar Inc, Briggs & Stratton Corporation, Deere & Company, Cummins Inc, Aggreko plc, PR INDUSTRIAL srl (PRAMAC), Atlas Copco AB, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Generator Sets Market Evolving Landscape
Digital load management and emissions compliance technologies are fragmenting product architectures across South American genset markets. Suppliers now engineer parallel-capable units with remote monitoring as baseline specifications rather than premium add-ons.
Electronic fuel injection with real-time combustion optimization is bifurcating the diesel genset landscape. Brazilian data center operators are specifying these systems for sub-5% load acceptance performance. Tier-one suppliers are compressing mechanical governor variants into price-driven construction segments only.
Chile's SEC emissions testing protocols now mirror EU Stage V particulate limits for imported engines above 130 kW. Peruvian mining contractors face equipment quarantine for non-certified power modules. Argentine distributors are pre-emptively filtering Chinese alternator imports lacking CONEAU reciprocity recognition.
Buyers in São Paulo's industrial corridor now unbundle after-sales service contracts from equipment procurement. Third-party maintenance providers with IoT-enabled predictive diagnostics are displacing manufacturer-captive service networks. This pattern is visible most acutely among Brazilian food processing facilities operating 24-hour batch cycles.
South America Generator Sets Market Segmentation
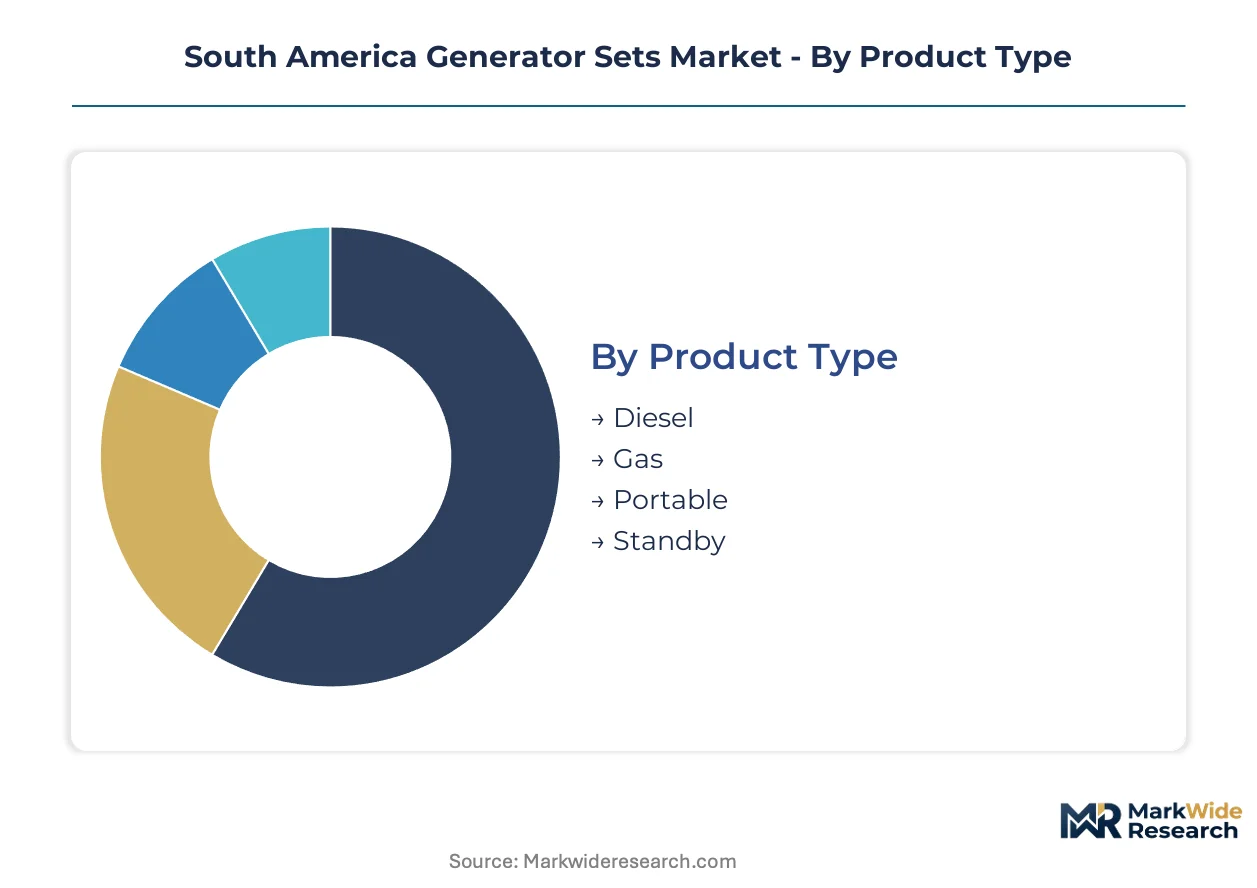
South American generator set procurement fragments sharply across fuel type, duty cycle, and grid dependency. Segment boundaries determine which suppliers capture margin versus volume, particularly where ANEEL mandates intersect with mining electrification timelines.
Product Type:
Diesel variants dominate domestic manufacturing in Brazil while gas and portable units rely heavily on import channels through Chilean and Argentine distributors.
- Diesel:Compression-ignition engines burning distillate fuel deliver superior torque for motor starting and accept sub-5% load steps without stability loss. Brazilian data centers in São Paulo's industrial corridor specify electronically governed diesel sets for continuous-duty tier-three certification compliance.
- Gas:Spark-ignited natural gas and biogas engines cut NOx emissions by 60% versus comparable diesel units but require pipeline infrastructure or compressed gas logistics. Argentine urban standby installations in Buenos Aires show underpenetration relative to diesel due to distribution network gaps.
- Portable:Trailer-mounted or wheeled gensets rated below 100 kW serve construction sites and emergency response teams requiring rapid redeployment. Peruvian mining contractors fly these into Andean highlands for exploratory drilling camp electrification.
- Standby:Automatic-start units with transfer switch integration provide backup power for hospitals, utilities, and telecommunications facilities facing ANEEL-mandated uptime requirements. Brazilian assemblers bundle these with service contracts spanning southeastern industrial states.
Diesel holds the largest share; momentum sits with gas as biogas feedstock access expands across Brazilian agro-industrial zones.
End User:
Margin concentration varies dramatically by buyer type, with industrial procurement commanding premium pricing for 500+ kW heavy-duty configurations.
- Industrial:Mining, manufacturing, and agro-processing operations require 24/7 power reliability for batch processes where interruption causes spoilage or safety hazards. Chilean copper extraction in the Atacama Desert pulls the highest-capacity units with 10,000+ hour annual runtimes.
- Commercial:Retail, hospitality, and office facilities prioritize rapid-start capability over fuel efficiency for sub-4-hour annual outage events. São Paulo's cloud infrastructure cluster absorbs continuous-duty gensets for facility certification.
- Residential:Single-family and multi-unit buildings specify automatic transfer switches for grid failure protection, with Argentine urban centers showing penetration gaps versus Brazilian benchmarks.
- Government:Hospitals, military installations, and water treatment plants face mandated backup duration requirements under ANEEL interconnection standards, creating volume stability through procurement centralization.
Industrial buyers command the deepest margins; commercial is climbing the fastest on data center buildout.
Installation:
Site configuration determines logistics complexity and service contract structure, with remote and mobile installations carrying 40% higher lifecycle costs.
- Onsite:Permanent generator installations at facilities with dedicated electrical rooms and fuel storage tanks. Brazilian food processing plants in Minas Gerais operate these with third-party maintenance providers using IoT-enabled predictive diagnostics.
- Remote:Standalone power modules for grid-extension uneconomical locations, common in Peruvian agro-processing facilities and Chilean mining camps. Factory-trained technicians for electronic engine management remain concentrated in Santiago and São Paulo, leaving these sites dependent on fly-in maintenance.
- Mobile:Skid-mounted or containerized gensets repositioned across construction phases or seasonal agricultural cycles. Colombian infrastructure projects deploy these where pipeline network deficiencies prevent gas genset substitution.
- Fixed:Anchored installations with concrete foundations and permanent fuel connections, standard for ANEEL-mandated critical infrastructure in Brazilian utilities and hospitals.
Fixed installations anchor volume; remote configurations are expanding most quickly on mining electrification.
Capacity:
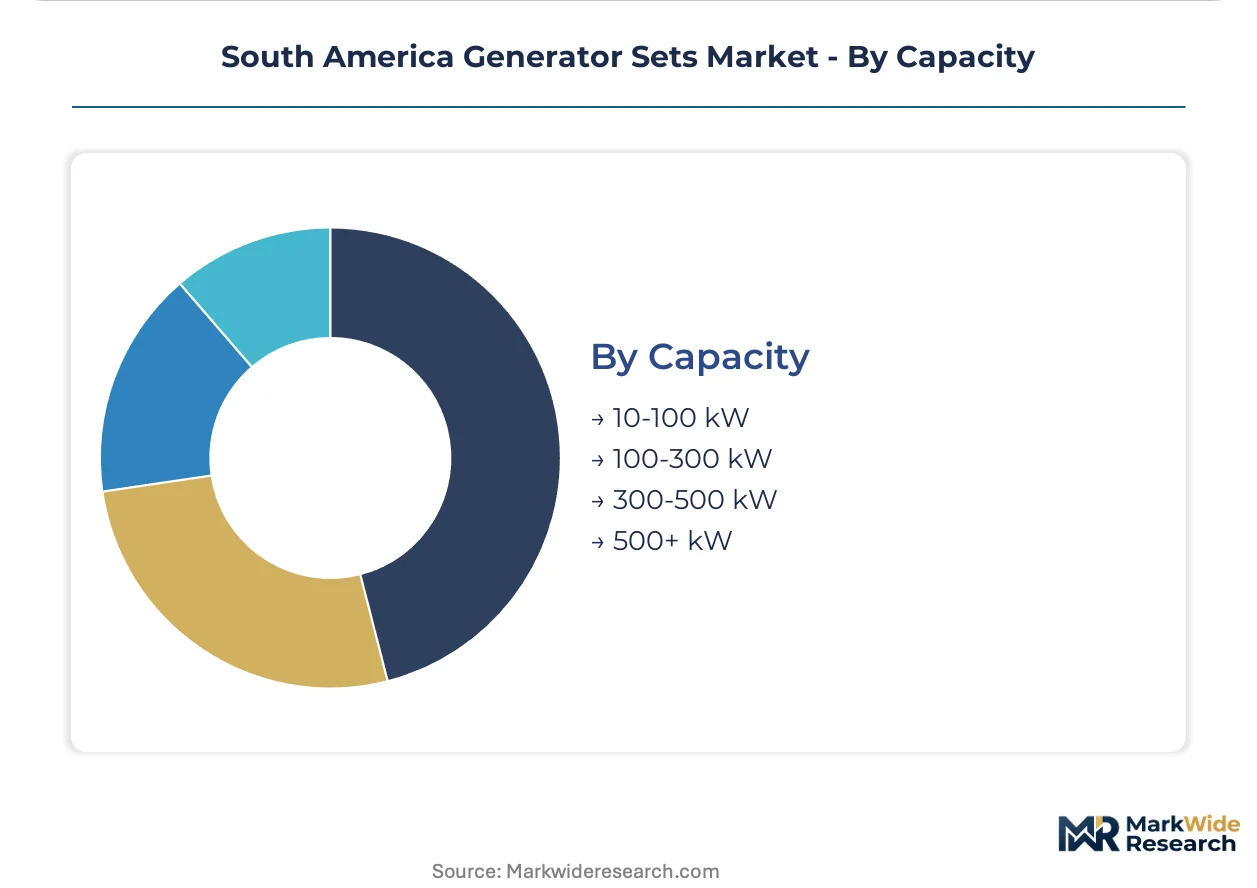
Power rating bands align with distinct competitive dynamics, with mid-range units facing the sharpest specification upgrades from grid reliability mandates.
- 10-100 kW:Compact units serving residential standby, small commercial, and auxiliary loads at larger facilities. Argentine urban centers in Buenos Aires metropolitan area show underpenetration in automatic transfer switch installations versus São Paulo.
- 100-300 kW:The commercial workhorse band capturing Brazilian data center demand and Peruvian agro-processing expansion. ANEEL-mandated backup power duration requirements are compressing procurement cycles and forcing specification upgrades across this range.
- 300-500 kW:Mid-industrial segment bridging commercial and heavy-duty applications, common in Brazilian southeastern industrial corridor manufacturing facilities.
- 500+ kW:Heavy-duty modules for mining electrification, large-scale data centers, and utility backup. Copper and lithium extraction operations in Chile's Atacama Desert and Peru's Andean highlands strain supplier lead times for these units.
100-300 kW holds the largest share; 500+ kW is gaining share fastest on mining electrification timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Brazilian assembly corridors while Chilean mining territories absorb premium markups for remote service logistics. Argentine distributors face margin compression from import tariff volatility and currency instability. Peruvian agro-processing clusters sit between these poles on cost-structure positioning.
Brazil
ANEEL grid interconnection standards mandate backup power duration for hospitals and utilities, forcing specification upgrades across the 100-300 kW band. The southeastern industrial corridor spanning São Paulo and Minas Gerais anchors domestic manufacturing capacity. Data center operators in São Paulo specify electronically governed diesel sets for tier-three certification compliance.
Chile
Copper and lithium extraction in the Atacama Desert pulls 500+ kW heavy-duty units with 10,000+ hour annual runtimes. SEC emissions testing protocols now mirror EU Stage V particulate limits for imported engines above 130 kW. Mining contractors face equipment quarantine for non-certified power modules, filtering import channels.
Argentina
Buenos Aires metropolitan area shows underpenetration in residential automatic transfer switch installations versus São Paulo benchmarks. The Secretaría de Energía imposes emissions testing protocols that block uncertified Chinese alternator imports lacking CONEAU reciprocity recognition. Urban standby demand concentrates in middle-income districts with unreliable grid supply.
Peru
Andean highland mining operations and coastal agro-processing facilities strain supplier lead times for remote site electrification. Solar-diesel hybrid configurations penetrate facilities where grid extension remains uneconomical. Factory-trained technicians for electronic engine management remain concentrated in Lima, leaving remote sites dependent on fly-in maintenance.
Colombia
Pipeline network deficiencies prevent natural gas genset substitution despite lower operating costs, locking in diesel dominance for infrastructure projects. Mobile skid-mounted units serve construction phases where permanent fuel connections prove impractical. The national renewable energy incentive framework remains underdeveloped for biogas feedstock integration.
South America Generator Sets Market Competitive Landscape
Concentration sits with integrated engine-alternator manufacturers controlling foundry capacity and assembly lines across Brazilian industrial corridors. The vendor base stratifies across three tiers: global power systems conglomerates with captive engine production, regional assemblers sourcing alternators from Chinese import channels, and rental fleet operators with service-forward positioning. Dominant competitive moves include backward integration into engine casting and turbocharger common-rail component sourcing, plus geographic expansion through dealer network control in Chilean mining territories.
Within the integrated-manufacturer tier, Cummins Inc and Caterpillar Inc exemplify archetypes of cost-structure anchoring and premium positioning respectively. Among rental-service specialists, Aggreko plc occupies a position emphasizing fly-in maintenance capabilities for remote mining electrification. Kohler Co sits within the residential standby specialization vector alongside Generac Holdings Inc, though the latter concentrates on Argentine urban centers versus Brazilian benchmarks.
| Leading Market Players |
|---|
| Kohler Co |
| Generac Holdings Inc |
| Caterpillar Inc |
| Briggs & Stratton Corporation |
| Deere & Company |
| Cummins Inc |
| Aggreko plc |
| PR INDUSTRIAL srl (PRAMAC) |
| Atlas Copco AB |
| Others |
Value Network & Pricing Analysis
Electronic fuel injection substitution for mechanical governor systems is redrawing supply geography toward Brazilian assembly corridors while compressing price premiums for electronically governed units. This technology shift simultaneously elevates working capital requirements for common-rail component inventory and fragments pricing power between integrated foundry operators and import-dependent assemblers.
Pricing Analysis
The customization-premium spread separates configured-to-order mining gensets from standard commercial units by margins reflecting fly-in service logistics and emissions certification tiers. Pricing stratifies across premium, standard, and economy tiers anchored by EU Stage V compliance status, electronic engine management inclusion, and after-sales bundling structures. Cost compression in the standard tier is intensifying because Brazilian data center operators now unbundle maintenance contracts from equipment procurement. Industrial mining buyers in Chile exhibit the lowest price sensitivity due to 10,000+ hour annual runtime requirements and remote site penalty costs.
Supply Chain Analysis
Strategic stockpile preferences dominate over just-in-time approaches for long-lead turbocharger and common-rail injection components that strain distributor balance sheets. Manufacturing concentration centers on Brazil, China, and the United States for engine castings, alternator assemblies, and electronic control modules respectively. The supply chain draws from copper and lithium extraction timelines in Chile, diesel fuel refining capacity in Brazil, and forged crankshaft sourcing from established foundry networks. Single-source vulnerability sits with Chinese alternator imports facing Mercosur Common External Tariff fluctuations. Distribution runs through manufacturer-captive dealer networks in Chilean mining territories and third-party service providers with IoT-enabled predictive diagnostics in São Paulo's industrial corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story justified by ANEEL-mandated backup power duration requirements that are compressing replacement cycles and forcing specification upgrades across Brazilian critical infrastructure.
For Market Incumbents: Consolidate dealer network control in Chilean mining territories where fly-in maintenance capabilities create switching costs against rental-service specialists. Deepen backward integration into turbocharger and common-rail component sourcing to anchor cost structures against import tariff volatility on Chinese alternator assemblies. Prioritize certification investment for EU Stage V emissions compliance to filter non-compliant imports from regional procurement channels.
For New Entrants and Emerging Players: Anchor in Argentine urban standby installations where Buenos Aires metropolitan area shows underpenetration in automatic transfer switch configurations versus São Paulo benchmarks. Target solar-diesel hybrid microgrid configurations for Peruvian agro-processing facilities where grid extension remains uneconomical and factory-trained technician scarcity creates service partnership opportunities. Pursue biogas feedstock integration in Brazil's sugarcane belt to qualify for national renewable energy incentives and differentiate from diesel-dominated competitors.
For Investors and Strategic Acquirers: ANEEL grid interconnection standard enforcement reshapes the acquisition landscape by mandating backup power duration specifications that favor integrated manufacturers with in-house engine foundry capacity over assembly-only operations. Long-term viability across the projection horizon rests on exposure to mining electrification timelines in Chile and Peru and data center buildout in São Paulo's cloud infrastructure cluster. Acquisition targets should demonstrate captive engine production, electronic fuel injection capability, and established service network density. The signal to watch is SEC emissions testing protocol stringency for imported engines above 130 kW, which determines import channel viability and competitive filtration intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Engine Casting | Cummins Inc leverages in-house foundry capacity to anchor cost structures across Brazilian assembly lines against import-dependent competitors. |
| Hybrid Microgrid Deployment | Solar-diesel configurations penetrate Peruvian agro-processing facilities where grid extension economics remain unfavorable and biogas feedstock access expands. |
| Emissions Certification Pre-Positioning | Pre-emptive EU Stage V compliance filters non-certified Chinese alternator imports from Chilean and Argentine procurement channels. |
| IoT-Enabled Predictive Maintenance | Third-party providers displace manufacturer-captive service networks among Brazilian food processing facilities operating 24-hour batch cycles. |
| Dealer Network Geographic Expansion | Caterpillar Inc sustains premium positioning through controlled distribution in Chilean mining territories with 10,000+ hour annual runtime demands. |
Research Methodology
The analysis maps diesel, gas, portable, and standby genset configurations, each validated through maintenance directors at Brazilian food processing plants, procurement leads at Chilean mining contractors, and aftermarket service heads across the southeastern industrial corridor. Primary interviews with plant engineers, OEM procurement teams, and EPC contractors specializing in remote site electrification combined with secondary validation from ANEEL regulatory filings, SEC emissions testing protocols, customs and trade data for alternator imports, and generator set registration databases. Bottom-up unit demand estimation and top-down market value triangulation cross-validated segment outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled fuel type, duty cycle, installation configuration, and capacity tier segmentation alongside regulatory compliance status as a cross-cutting dimension. CAGRs were derived from fitted growth curves applied to base-year market sizing with adjustment for mining electrification timelines, data center certification buildout, and ANEEL mandate implementation schedules as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained mining expansion in Chile and Peru, continued ANEEL enforcement stringency, and stable Mercosur tariff frameworks; material deviation would warrant model refresh. Revision becomes warranted when emissions certification reciprocity agreements between Mercosur members cross thresholds that enable or block cross-border product standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
India Portable Generator Market
Generators
South America Gas Generator Market
Generators
Onboard Marine Gensets Market
Generators
Multi Fuel Generators Market
Generators
Emergency Power Generators Sales Market
Generators
China Generator Sets Market
Generators
Middle East Portable Generator Market
Generators
Industrial Generator Sets Market
Generators
Containerized Solar Generators Market
Generators
Saudi Arabia Diesel Generator Market
Generators
Natural Gas Generator Market
Generators
Portable Inverter Generators Market
Generators
Commercial Standby Generator Sets Market
Generators
Africa Diesel Generator Market
Generators
Halogenerator Market
Generators
United States Portable Generator Market