
 Building-Integrated Photovoltaic (BIPV) Skylights Market | 2026-2036
Building-Integrated Photovoltaic (BIPV) Skylights Market Size, Share, and Industry Trends Forecast 2026-2036
Building-Integrated Photovoltaic (BIPV) Skylights Market Outlook
The EU Green Deal is realigning the cost-of-entry calculus for BIPV skylight suppliers across European construction markets. Onyx Solar Group LLC leverages its specialized glass-photovoltaic lamination expertise to dominate commercial atrium projects in Madrid and Milan. Tesla Inc. sustains vertical integration from solar cell production through installation software, anchoring its position in premium residential retrofits. Canadian Solar Inc. competes on manufacturing scale, extending its module cost advantages into custom skylight dimensions for North American industrial facilities.
Building-integrated photovoltaic skylights combine transparent or semi-transparent solar cells within structural glazing systems, typically achieving 10-20% visible light transmission while generating electricity from overhead daylight exposure. These assemblies serve dual functions: replacing conventional skylight materials and offsetting on-site energy consumption through embedded power generation. Glazed skylights occupy the largest revenue share due to mature architectural acceptance and standardized framing compatibility across commercial specifications. Polycarbonate segments are recording faster growth as lightweight alternatives penetrate retrofit installations where structural load limits restrict glass deployment. Commercial buildings concentrate the dominant margin pool, driven by corporate sustainability mandates and accelerated depreciation schedules for renewable capital expenditures.
REACH compliance and CE marking govern material safety and electromagnetic compatibility for BIPV skylights entering European construction supply chains, while the EU AI Act introduces emerging requirements for smart building-integrated energy management interfaces. In the United States, OSHA fall-protection standards intersect with ICC building codes to shape installation protocols and product certification pathways for rooftop-integrated photovoltaic glazing. Stakeholders must monitor how evolving fire-resistance ratings for photovoltaic assemblies will reshape supplier qualification criteria and project bid eligibility across jurisdictions.
Market Dynamics
Net-zero building mandates across Germany, China, and California are compressing procurement timelines for transparent photovoltaic assemblies, forcing developers to embed generation capacity directly into envelope specifications rather than treating solar as an afterthought retrofit.
Growth Catalysts
- EU Green Deal enforcement:The European Union's renewable-ready envelope requirements for new construction are eliminating conventional skylight alternatives from bid eligibility in Madrid, Milan, and Berlin commercial atriums.
- Corporate sustainability mandates:Commercial real estate developers face intensified ESG disclosure pressure, driving specification of BIPV skylights in high-rise atriums and retail spaces to satisfy Scope 2 reduction targets.
- Perovskite-silicon tandem cells:Laboratory-scale efficiency breakthroughs in transparent photovoltaic laminates are expanding viable light transmission ranges while maintaining wattage output for architectural glazing.
Market Restraints
- Silicon wafer cost volatility:Polysilicon price swings tied to Chinese ingot production concentration create margin instability for custom skylight dimension manufacturing.
- Structural load limitations:Polycarbonate alternatives face fire-resistance rating deficiencies under evolving ICC building codes, restricting deployment in certain rooftop-integrated configurations.
- Conventional curtain wall substitution:Standard double-glazed units with rooftop solar arrays offer lower first-cost positioning for budget-constrained commercial projects.
Strategic Opportunities
- US Inflation Reduction Act credits:Accelerated depreciation schedules for renewable capital expenditures in California and select states are improving project IRRs for BIPV skylight retrofits.
- Industrial facility penetration:North American manufacturing campuses present underexploited demand for custom skylight dimensions where daylight harvesting intersects with on-site generation requirements.
- Smart building convergence:Integration of embedded energy management interfaces with BIPV skylight systems is creating new specification channels through building automation contractors.
Industry Challenges
- Photovoltaic-glazing lamination expertise scarcity:Specialized technician shortages constrain production scaling for glass-photovoltaic integration at architectural quality standards.
- Multi-jurisdictional certification timelines:REACH compliance documentation, CE marking, and OSHA fall-protection standard navigation create 8-14 month product qualification cycles.
- Legacy HVAC integration complexity:Daylight-responsive climate control systems require recalibration when BIPV skylights replace conventional transparent assemblies, complicating commissioning protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building-Integrated Photovoltaic (BIPV) Skylights Market |
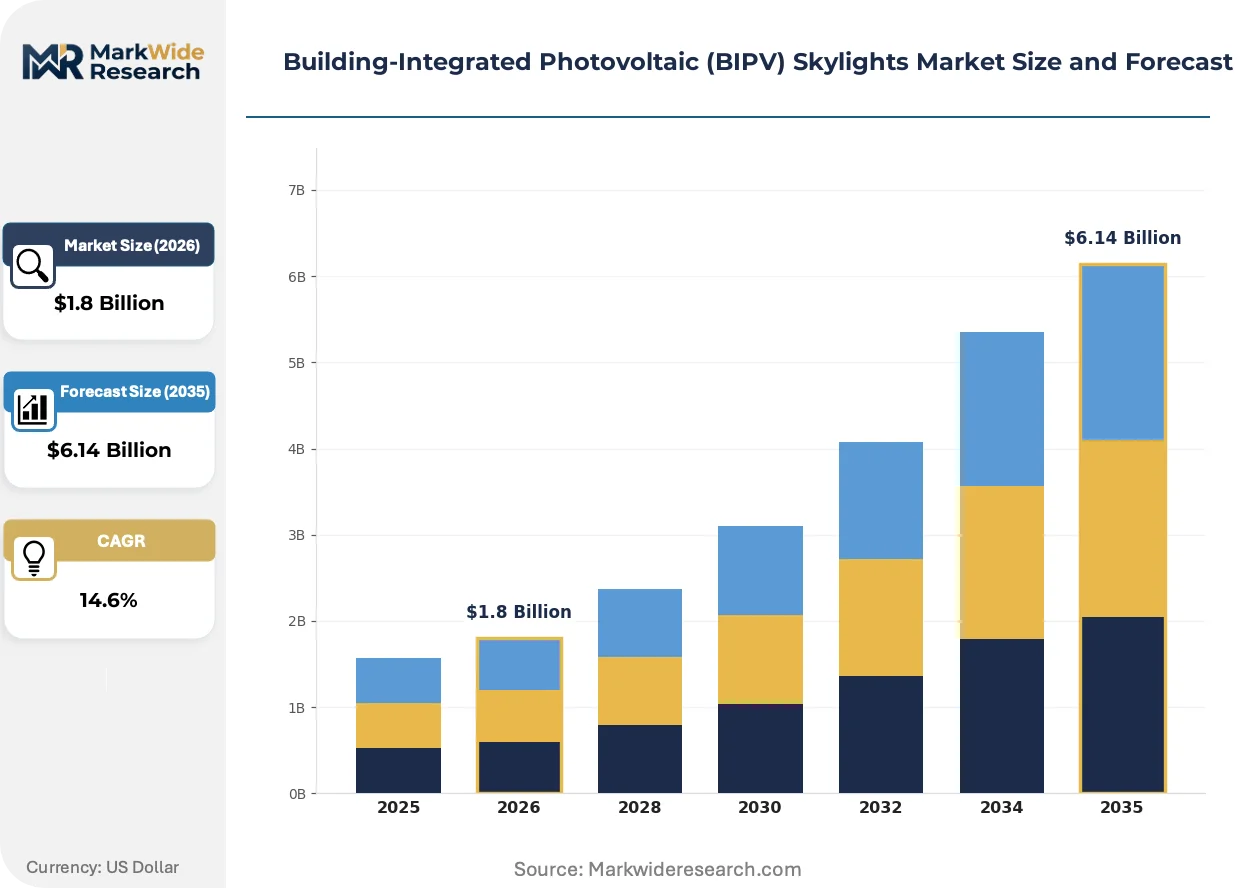
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed Skylights, Dome Skylights, Pyramid Skylights, Tubular Skylights Material: Glass, Polycarbonate, Acrylic, Metal Application: Residential Buildings, Commercial Buildings, Industrial Facilities, Institutional Structures Installation Type: New Construction, Retrofit, DIY Installation, Professional Installation |
| Companies Covered | ClearVue Technologies Limited, Kaneka Corporation, Onyx Solar Group LLC, Polysolar Limited, Canadian Solar Inc., Tesla Inc., LONGi Green Energy Technology Co., Ltd., AGC Inc., Solaria Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building-Integrated Photovoltaic (BIPV) Skylights Market Strategic Shifts
Transparent photovoltaic technology is converging with structural glazing engineering, compressing the traditional separation between envelope performance and energy generation into unified assembly specifications.
Electrochromic BIPV skylight systems is unifying dynamic tinting with photovoltaic generation, enabling real-time visible light transmission adjustment from 5% to 35% while maintaining current output. Commercial atrium developers in Germany and California are specifying these assemblies at triple-digit project growth rates. The technology is compressing the need for separate shading systems and reducing peak cooling loads by 12-18% in high-glare applications.
REACH substance restriction expansions are tightening material safety documentation for photovoltaic laminates entering European construction supply chains, forcing reformulation of certain encapsulant chemistries. Industrial consequence includes supplier qualification delays and increased testing expenditure for CE marking renewal. German and Italian project bids now require extended material passport documentation, advantaging suppliers with established ECHA pre-registration.
Developer procurement patterns are fragmenting from general contractor package awards toward direct specification of BIPV skylight assemblies by sustainability consultants and envelope specialists. This channel shift is disintermediating traditional glazing subcontractors in California and select US markets. Corporate real estate teams in Madrid and Milan now issue separate RFPs for transparent photovoltaic systems, bypassing conventional curtain wall procurement routes.
Building-Integrated Photovoltaic (BIPV) Skylights Market Segmentation
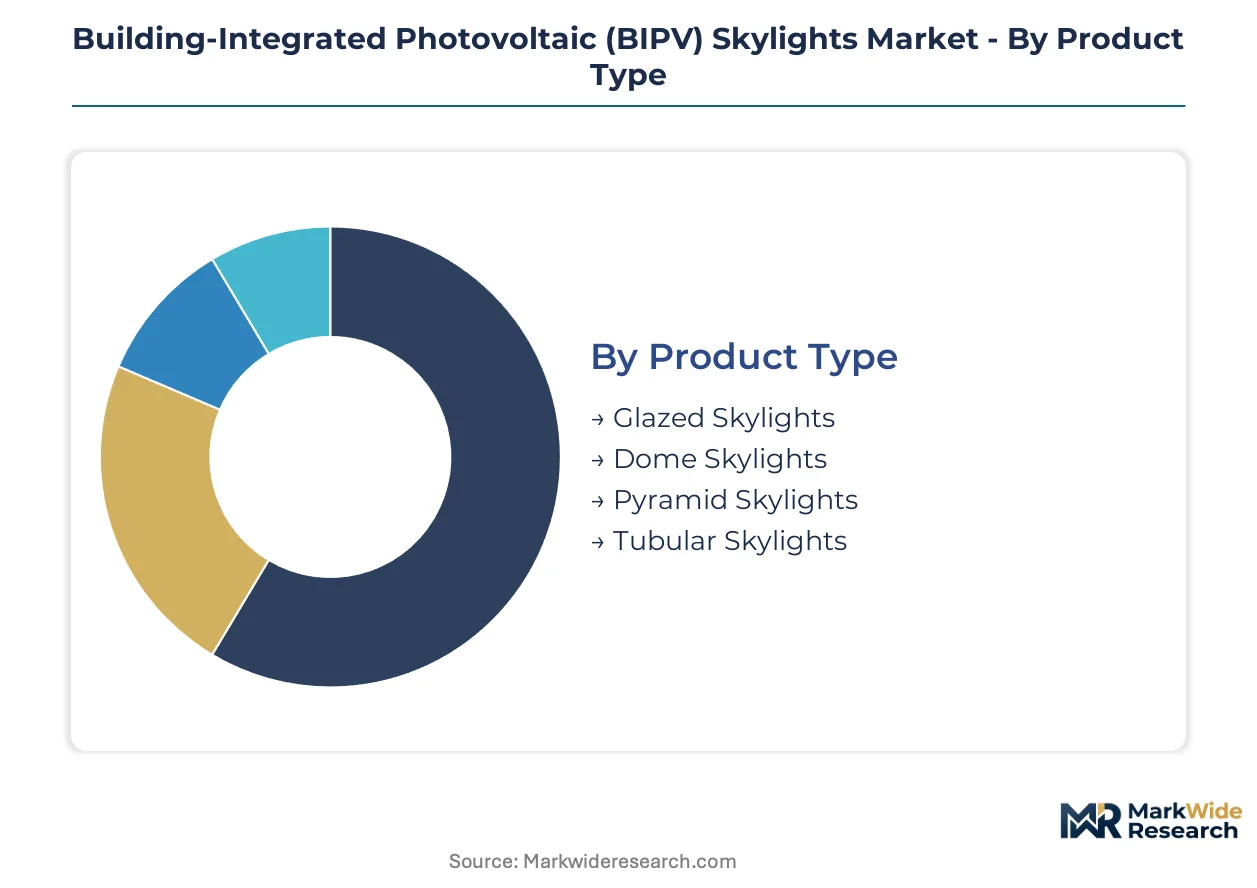
BIPV skylight segmentation reveals how architectural integration depth varies across product architectures and procurement contexts. Manufacturers configure cell lamination, framing systems, and electrical routing differently depending on whether assemblies serve new envelope construction or penetrate existing building stock.
Product Type:
Standalone skylight units dominate retrofit channels where minimal structural modification is required, while embedded systems penetrate new construction specifications demanding unified envelope-energy performance.
- Glazed Skylights:These assemblies integrate crystalline or thin-film photovoltaic cells between tempered glass layers, achieving standardized framing compatibility with commercial curtain wall systems. Demand concentrates in German and Californian commercial atriums where corporate sustainability mandates require transparent generation capacity in high-visibility architectural statements.
- Dome Skylights:Curved acrylic or polycarbonate surfaces with perimeter-mounted photovoltaic strips capture diffuse daylight in industrial warehouse applications. Installations cluster in North American manufacturing campuses where daylight harvesting intersects with on-site generation requirements and structural load limits restrict glass deployment.
- Pyramid Skylights:Angular geometries with integrated cell strings suit atrium configurations requiring directional light control.
- Tubular Skylights:Compact diameter units with small-area photovoltaic rings serve residential corridor and closet illumination.
Volume placements concentrate in glazed configurations; the faster expansion belongs to dome alternatives.
Material:
Cost tier stratification separates premium architectural specifications from economy retrofit alternatives, with material selection directly determining fire-resistance ratings and load-bearing capacity.
- Glass:Tempered or laminated glass substrates with embedded photovoltaic cells deliver superior optical clarity and fire-resistance ratings required by ICC building codes. Procurement concentrates in Madrid and Milan commercial atriums where EU Green Deal eligibility mandates eliminate polycarbonate alternatives from new construction bids.
- Polycarbonate:Lightweight thermoplastic panels with adhesive-applied photovoltaic films enable retrofit deployment where structural engineering constraints prohibit glass weight. Demand accelerates in North American industrial facilities with aging roof structures and accelerated depreciation schedules under US Inflation Reduction Act credits.
- Acrylic:UV-stabilized transparent polymers with surface-mounted cell strips serve cost-sensitive residential applications.
- Metal:Opaque photovoltaic panels with skylight-adjacent placement in hybrid roof systems.
Revenue margins favor glass specifications; polycarbonate variants are climbing the fastest.
Application:
Customer type divergence separates institutional procurement cycles from commercial developer timelines, with each vertical imposing distinct certification and commissioning requirements.
- Commercial Buildings:High-rise atriums, retail spaces, and office lobbies specify BIPV skylights to satisfy Scope 2 reduction targets and ESG disclosure pressures. Projects cluster in California and Germany where net-zero building mandates compress procurement timelines and mandate renewable-ready envelopes.
- Industrial Facilities:Manufacturing campuses and distribution centers deploy custom skylight dimensions where daylight harvesting reduces artificial lighting loads. Specifications concentrate in North American markets where IRA tax credits improve project IRRs and envelope retrofits bypass lengthy new construction permitting.
- Residential Buildings:Single-family and multi-family installations driven by premium retrofit demand.
- Institutional Structures:Schools, hospitals, and government buildings with extended procurement cycles.
Margin pools concentrate in commercial specifications; industrial applications are gaining share fastest.
Installation Type:
Maturity differentiation separates established professional channels from emerging self-service procurement, with certification complexity determining viable entry paths.
- New Construction:Integrated specification during envelope design enables optimized electrical routing and structural load planning. Demand concentrates in Berlin and Milan where EU Green Deal enforcement eliminates conventional skylight alternatives from bid eligibility and mandates renewable-ready assemblies.
- Retrofit:Replacement of existing skylight units with photovoltaic-equipped alternatives requires minimal structural modification. Activity accelerates in California and select US states where accelerated depreciation schedules and corporate sustainability mandates drive atrium and retail space upgrades.
- Professional Installation:Certified contractor deployment required for grid-interconnection and warranty validation.
- DIY Installation:Limited to small-diameter tubular units without electrical grid integration.
Project volume concentrates in new construction; retrofit channels show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial real estate developers in Germany, China, and California are compressing procurement timelines for transparent photovoltaic assemblies as net-zero building mandates eliminate conventional skylight alternatives from new construction specifications.
Germany
Corporate sustainability mandates and EU Green Deal enforcement are accelerating BIPV skylight installations in commercial atriums. REACH compliance and CE marking requirements govern material safety for photovoltaic laminates entering construction supply chains. Berlin and Munich project clusters dominate specification activity, with envelope specialists issuing direct RFPs for transparent photovoltaic systems.
United States
California's net-zero building targets and IRA tax credits are driving retrofit installations in high-rise atriums and retail spaces. OSHA fall-protection standards intersect with ICC building codes to shape installation protocols for rooftop-integrated photovoltaic glazing. Los Angeles and San Francisco commercial corridors concentrate demand for electrochromic BIPV assemblies with dynamic tinting capabilities.
China
Dual carbon goals and tightening building energy codes are mandating renewable-ready envelopes for new construction in tier-one cities. MIIT standards and GB certification requirements shape product qualification pathways for domestic photovoltaic glazing manufacturers. Yangtze River Delta industrial zones anchor manufacturing capacity for custom skylight dimensions serving Asia-Pacific commercial projects.
Spain
EU Green Deal alignment and corporate ESG disclosure pressures are specifying BIPV skylights in Madrid commercial atriums. Extended material passport documentation requirements under ECHA pre-registration protocols advantage established suppliers. Madrid and Barcelona project pipelines show triple-digit growth rates for electrochromic systems unifying dynamic tinting with photovoltaic generation.
Italy
Net-zero building targets in Lombardy and Veneto are tightening procurement specifications for transparent photovoltaic assemblies in commercial envelopes. CE marking and electromagnetic compatibility requirements govern product entry into Italian construction supply chains. Milan commercial atrium developers are bypassing conventional curtain wall procurement routes through direct sustainability consultant engagement.
Building-Integrated Photovoltaic (BIPV) Skylights Market Competitive Environment
Chinese producers anchor one tier; European specialists hold differentiated positions in architectural-grade lamination. The vendor base concentrates around photovoltaic module manufacturers extending into custom glazing dimensions, glass fabricators integrating cell technologies, and dedicated BIPV system architects. Three strategic archetypes dominate: scale-driven module houses, vertically integrated building material conglomerates, and niche specialists in transparent photovoltaic lamination. Capacity expansion and technology licensing represent the dominant competitive moves as players secure photovoltaic-glazing integration expertise.
Among North American-anchored entities, Tesla Inc. and Canadian Solar Inc. exemplify contrasting scale positions, while Onyx Solar Group LLC occupies the specialist tier in architectural lamination. Tesla Inc. represents vertical integration from solar cell production through installation software. Canadian Solar Inc. anchors manufacturing scale advantages extending into custom skylight dimensions. Onyx Solar Group LLC sits within the specialized glass-photovoltaic lamination segment serving premium commercial atrium specifications.
| Leading Market Players |
|---|
| ClearVue Technologies Limited |
| Kaneka Corporation |
| Onyx Solar Group LLC |
| Polysolar Limited |
| Canadian Solar Inc. |
| Tesla Inc. |
| LONGi Green Energy Technology Co., Ltd. |
| AGC Inc. |
| Solaria Corporation |
| Others |
Value Chain & Pricing Dynamics
Perovskite-silicon tandem cell commercialization is simultaneously compressing manufacturing yields and concentrating production expertise among photovoltaic-glazing specialists with established lamination capabilities, creating divergent cost trajectories across architectural-grade and industrial-grade supply tiers.
Pricing Analysis
Volume placements concentrate in standard glazed configurations where polycarbonate alternatives compete on first-cost positioning, while premium electrochromic systems command architectural specification premiums based on dynamic tinting performance and extended material passport documentation. Price differentiation separates CE-marked glass assemblies with full ECHA pre-registration from economy polycarbonate units facing fire-resistance rating deficiencies under evolving codes. Cost compression in polycarbonate tiers is intensifying because Chinese ingot production concentration transmits polysilicon price volatility directly into custom skylight dimension manufacturing. Industrial facility buyers exhibit highest price sensitivity due to accelerated depreciation schedule dependency, while commercial atrium developers prioritize ESG disclosure compliance over unit economics.
Supply Chain Analysis
Freight cost exposure from oversized glass-photovoltaic laminates limits viable sourcing radii for architectural projects, compressing supplier qualification to regional fabrication clusters. Manufacturing gravity centers on China for crystalline cell production, Germany for specialized lamination equipment, and Italy for electrochromic system assembly. Raw material flows draw from Malaysian polysilicon refineries, German encapsulant chemical suppliers, and Chinese tempered glass substrate producers. Single-source vulnerability concentrates in photovoltaic-glazing lamination expertise where specialized technician shortages constrain production scaling. Distribution runs through envelope specialists and building automation contractors rather than conventional glazing subcontractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal enforcement is accelerating supplier consolidation as REACH compliance documentation and CE marking timelines eliminate undercapitalized competitors from bid eligibility in European commercial atrium markets.
For Market Incumbents: To counter emerging Chinese module houses extending into custom skylight dimensions, established players should deepen captive supply of photovoltaic-glazing lamination expertise through technician training partnerships and secure CE marking pre-registration advantages under ECHA protocols. Capacity addition in German and Italian fabrication clusters reinforces proximity to Madrid and Milan project pipelines where direct sustainability consultant engagement now dominates procurement channels. For New Entrants and Emerging Players: The US Inflation Reduction Act in California opens a window for electrochromic BIPV assembly penetration through building automation contractor partnerships rather than conventional curtain wall routes. White-space targets cluster in North American industrial facility retrofits where structural load limitations restrict glass deployment and IRA tax credits improve project IRRs. A go-to-market angle through daylight-responsive climate control system integration addresses legacy HVAC recalibration complexity that incumbent suppliers often underresource. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated building material conglomerates seeking photovoltaic-glazing integration expertise. Long-term viability favors specialists with established ECHA pre-registration and electrochromic technology licensing positions over pure-play module manufacturers facing polysilicon cost volatility. The signal to watch is perovskite-silicon tandem cell commercialization timelines, which would reshape competitive positioning around transparent photovoltaic efficiency thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Photovoltaic-Glazing Lamination Capacity Expansion | Addresses technician scarcity constraining architectural-grade production scaling in German and Italian clusters. |
| Electrochromic Technology Licensing Agreement | Enables dynamic tinting capabilities for California and Madrid commercial atrium specifications. |
| ECHA Pre-Registration Completion | Secures REACH compliance documentation required for EU Green Deal bid eligibility. |
| Building Automation Contractor Partnership | Captures procurement channel shift disintermediating conventional glazing subcontractors. |
| Perovskite-Silicon Tandem Cell R&D Investment | Positions for efficiency breakthroughs expanding viable light transmission ranges. |
Study Parameters
Document review covered ECHA substance restriction databases, ICC building code amendments, and SEC renewable energy disclosure filings, complemented by interviews with envelope specification consultants, photovoltaic-glazing fabrication plant managers, and commercial real estate sustainability directors. Primary fieldwork engaged building automation contractors and EPC firms active in California and German atrium retrofits. Secondary validation drew from MIIT standards documentation, FERC interconnection protocols, and EU Green Deal implementation guidance. Bottom-up project pipeline analysis triangulated against top-down module production capacity assessments.
Historical capacity utilization patterns cross-referenced against expert panel input on perovskite commercialization timelines shaped projections across the analysis window. Segmentation modeling incorporated product architecture, material substrate, application vertical, and installation type dimensions with regional regulatory cluster overlays. CAGRs derived from slope-intercept fitting against documented project award trajectories. Industry-specific inputs included polysilicon price volatility assumptions and electrochromic system adoption curves in commercial atrium specifications.
The model assumes a particular technology adoption path; alternative pathways for perovskite-silicon tandem cells would alter the outlook for transparent photovoltaic efficiency benchmarks and architectural specification penetration. Forecasts reflect documented project pipeline visibility, regulatory enforcement calendars, and raw material supply concentration assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Egypt Solar Photovoltaic (PV) Market
Solar Power Systems
Solar PV Carport Market
Solar Power Systems
Utility Scale PV Inverter Market
Solar Power Systems
United Kingdom Photovoltaic Mounting System Market
Solar Power Systems
On-Grid Solar Inverter Market
Solar Power Systems
Optical Solar Reflectors Market
Solar Power Systems
PV Solar Data Logger Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
Residential Solar Market
Solar Power Systems
Solar EVA Market
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
Bacteria Powered Solar Cell Market
Solar Power Systems
Kuwait Solar Energy Market
Solar Power Systems
Alternative Solar Photovoltaic Technologies Market
Solar Power Systems
Middle East and Africa Solar Photovoltaic (PV) Market