
 Thin Film Photovoltaic Sales Market | 2026-2036
Thin Film Photovoltaic Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Film Photovoltaic Sales Market Insights
India is rewriting the thin film photovoltaic supply map through multi-gigawatt manufacturing commitments under its PLI scheme. First Solar anchors North American CdTe production with integrated semiconductor-to-module operations. Oxford Photovoltaics specializes in perovskite-silicon tandem architectures for building-integrated applications. Solar Frontier K.K. dominates CIS module supply for Japan's rooftop and commercial segments.
Thin film photovoltaic sales encompass photovoltaic devices manufactured by depositing one or more thin layers of photosensitive material onto substrates such as glass, plastic, or metal, with absorber layer thicknesses typically below ten micrometers. These devices convert sunlight to electricity through p-n junction formation in materials like cadmium telluride, copper indium gallium selenide, or amorphous silicon, serving applications where weight constraints, low-light performance, or building integration limit conventional crystalline silicon deployment. CdTe modules capture the dominant revenue share due to First Solar's manufacturing scale and utility-scale project economics, while perovskite and organic segments attract R&D intensity despite shorter commercial track records. Rooftop and building-integrated installations represent faster-expanding channels as architectural specifications and urban density constraints favor lightweight, flexible form factors over rigid crystalline alternatives.
The EPA regulates cadmium content and end-of-life recovery protocols for CdTe modules in the United States, while REACH governs chemical substance registration and restriction across European supply chains. India's BIS certification mandates module performance testing for grid-connected installations, and the PLI scheme ties fiscal incentives to domestic value-add thresholds. Stakeholders must monitor perovskite stability standardization progress at IEC and national levels, as commercialization timelines hinge on consensus test protocols for degradation rates and encapsulation integrity.
Market Dynamics
Utility-scale developers are prioritizing module weight reduction to cut balance-of-system costs on marginal land sites, compressing crystalline silicon's historical cost advantage in ground-mounted arrays.
Growth Catalysts
- India's PLI scheme:Production-linked incentives tie fiscal benefits to domestic value-add thresholds, attracting multi-gigawatt manufacturing commitments for cadmium-telluride and perovskite capacity.
- Building-integrated photovoltaics:Architectural firms specify lightweight thin film for curtain walls and skylights where structural load limits exclude conventional modules.
- EU Green Deal:National renewable portfolio standards mandate solar deployment on commercial rooftops, accelerating procurement of flexible form factors.
Market Restraints
- Tellurium supply concentration:Refining capacity clusters in China and Japan, exposing cadmium-telluride producers to concentrate price volatility and geopolitical disruption.
- Perovskite stability gaps:Moisture-induced degradation in unencapsulated cells exceeds utility warranty thresholds, delaying bankability for 25-year project finance.
- REACH chemical restrictions:European registration requirements for cadmium compounds add compliance costs and end-of-life recovery obligations for CdTe module suppliers.
Strategic Opportunities
- Agrivoltaics expansion:Semi-transparent perovskite modules enable dual-use land applications in Japan and France, generating revenue from crops and electricity simultaneously.
- Recycling infrastructure:Closed-loop tellurium recovery from end-of-life CdTe modules creates captive feedstock supply as installed base ages past operational life.
- Perovskite-silicon tandems:Stacked architectures push conversion efficiencies beyond single-junction limits, opening premium pricing in space-constrained commercial installations.
Industry Challenges
- IEC standardization delays:Absence of consensus test protocols for perovskite degradation rates forces manufacturers to conduct redundant certification campaigns across national markets.
- Encapsulation engineering:Developing barrier films that block moisture ingress for 25 years without adding weight or cost remains unresolved for flexible substrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Film Photovoltaic Sales Market |
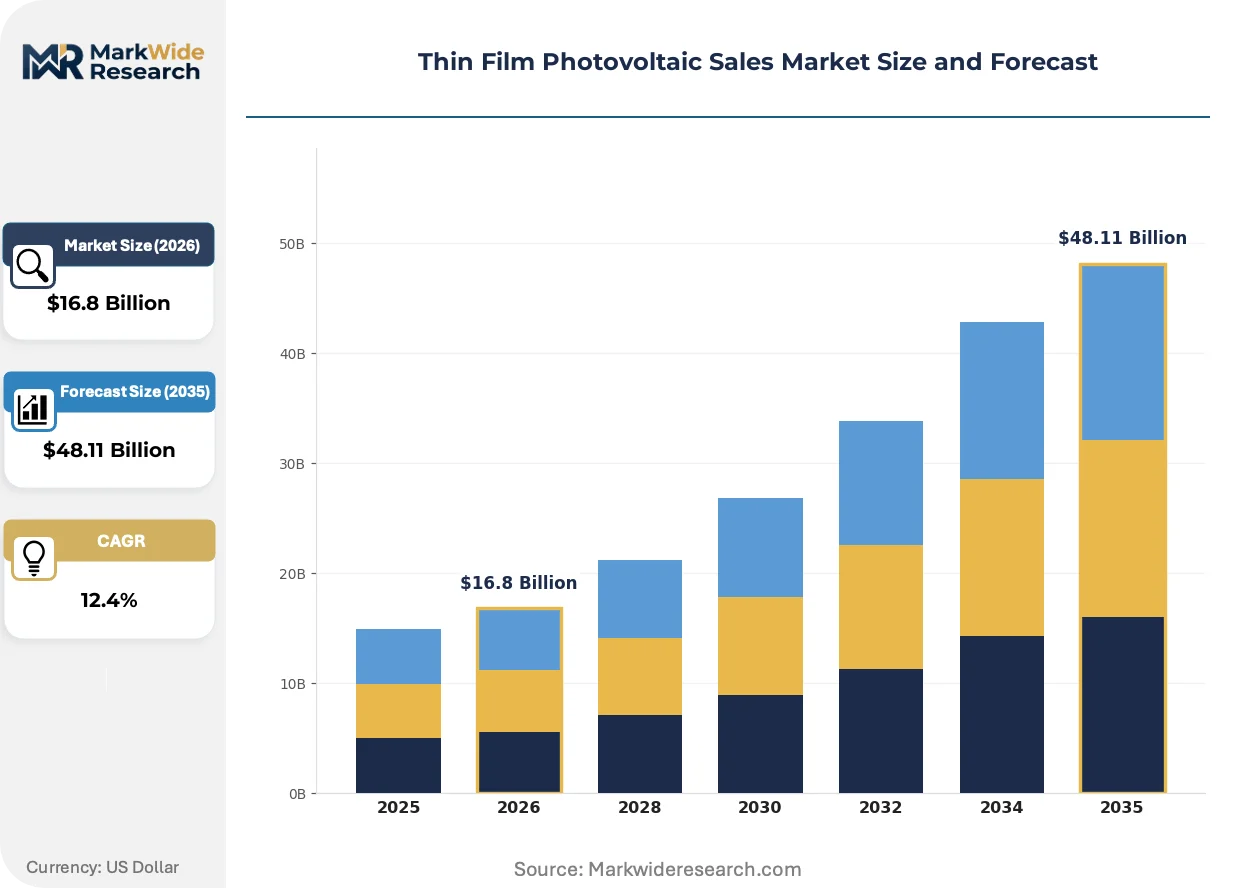
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $48.11 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CIS, CdTe, A-Si, Organic Installation Type: Ground-mounted, Rooftop, Building-integrated, Off-grid End User: Residential, Commercial, Industrial, Utility Distribution Channel: Direct Sales, Online, Retail, Distributors |
| Companies Covered | First Solar, Oxford Photovoltaics, Kaneka Corporation, Ascent Solar Technologies, MiaSole Hi-Tech Corp., Global Solar, Solar Frontier K.K., Hanergy Thin Film Power Group, Sharp Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Film Photovoltaic Sales Market Trends and Innovations
Module architecture is converging toward multi-junction designs that stack complementary absorbers, while policy frameworks increasingly embed circular economy obligations into solar deployment mandates.
Perovskite-silicon tandem cells are hybridizing laboratory efficiency records with manufacturing feasibility, attracting pilot line investments from equipment suppliers serving the display coating industry. Building-integrated project developers in Germany and South Korea specify these stacks for facades where aesthetic uniformity and power density outweigh first-cost premiums. The structural consequence is compression of amorphous silicon's addressable market in premium architectural segments.
REACH substance restriction reviews are tightening cadmium thresholds in electrical equipment, compelling CdTe manufacturers to document closed-loop recycling rates and substitution analysis for European tenders. Industrial consequence includes diverted procurement toward CIS and perovskite alternatives in public-sector projects. Germany's federal building authority now mandates third-party verified recovery plans for thin film installations on government properties.
Buyers are consolidating module procurement through engineering-procurement-construction firms that bundle installation with long-term performance guarantees, displacing direct manufacturer relationships. This channel shift concentrates pricing power with EPCs capable of underwriting multi-site portfolios. The pattern is most visible in India's utility-scale segment, where developers negotiate master supply agreements covering gigawatt-scale deployment tranches.
Thin Film Photovoltaic Sales Market Segmentation
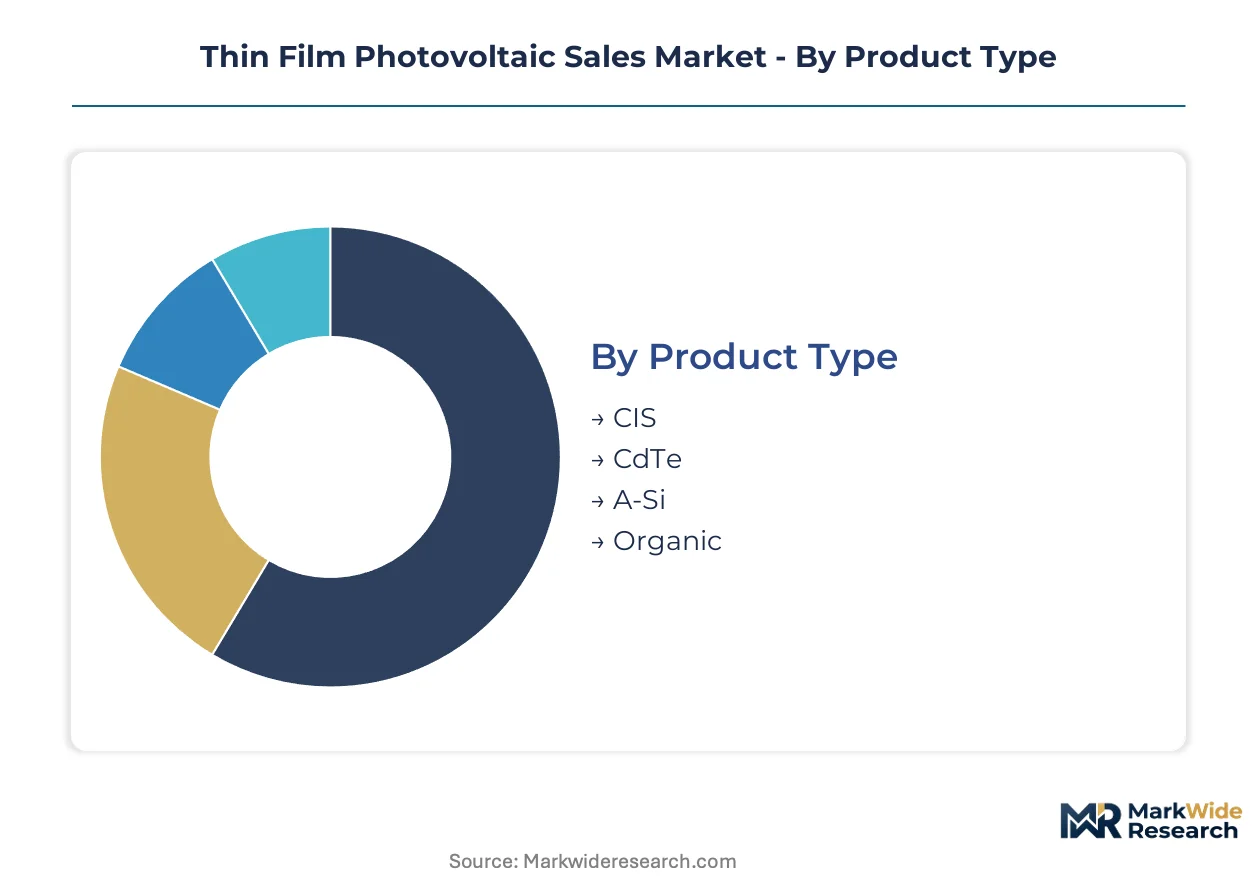
Thin film photovoltaic sales fragment across four distinct dimensions that determine procurement patterns, margin structures, and technology selection. Product type governs efficiency ceilings and material supply risks. Installation type dictates balance-of-system economics and regulatory pathways. Understanding these segment boundaries clarifies where manufacturers compete on cost versus performance differentiation.
Product Type:
Cadmium-telluride modules turn inventory fastest through utility-scale procurement cycles, while organic photovoltaics sit longest in pilot-line validation before commercial deployment.
- CdTe:Cadmium-telluride absorber layers deposited on glass substrates deliver temperature coefficients superior to crystalline silicon, making them attractive for utility-scale arrays in high-irradiance climates. First Solar's integrated manufacturing in Ohio and India concentrates procurement from independent power producers seeking bankable 25-year warranties. CdTe dominates installed base. Perovskite-silicon tandems are where expansion concentrates.
- CIS:Copper indium selenide architectures incorporate gallium to widen bandgap and boost voltage output, with Solar Frontier K.K. maintaining dedicated production for Japan's commercial rooftop segment. Japanese METI certification requirements and feed-in-tariff structures channel demand toward domestic CIS supply despite higher module costs. CIS holds established share in premium distributed installations. CdTe captures volume in utility procurement.
- A-Si:Amorphous silicon deposition on flexible substrates serves consumer electronics and portable charging applications where weight constraints override efficiency targets.
- Organic:Polymer-fullerene and non-fullerene acceptor blends enable solution-processed manufacturing at ambient temperatures, attracting R&D investment from display equipment suppliers.
CdTe commands utility-scale procurement volumes. CIS and perovskite alternatives are gaining share fastest in building-integrated and premium rooftop channels.
Installation Type:
Ground-mounted arrays absorb capital fastest through multi-hundred-megawatt project finance, while building-integrated installations stretch development timelines across architectural review and structural engineering phases.
- Ground-mounted:Fixed-tilt and tracking systems on marginal agricultural or brownfield land prioritize module cost-per-watt and degradation resistance over aesthetic constraints. Indian developers under PLI scheme procurement guidelines favor ground-mounted CdTe for gigawatt-scale solar parks in Rajasthan and Gujarat. Ground-mounted dominates annual gigawatt additions. Building-integrated photovoltaics are where margin expansion concentrates.
- Rooftop:Commercial and industrial flat-roof installations balance structural load limits with energy yield optimization, creating demand for lightweight frames and simplified mounting hardware. Germany's federal building authority mandates third-party verified recovery plans for thin film rooftop systems on government properties, tilting specification toward CdTe and CIS with established recycling infrastructure. Rooftop captures distributed generation growth. Off-grid represents niche penetration.
- Building-integrated:Curtain walls, skylights, and facade-integrated modules substitute conventional construction materials while generating electricity, requiring semi-transparent or colored finishes.
- Off-grid:Remote telecommunications, agricultural pumping, and rural electrification applications prioritize system reliability and battery compatibility over grid-connection standards.
Ground-mounted arrays anchor volume shipments. Building-integrated and rooftop segments are climbing the fastest as urban density constraints tighten.
End User:
Utility procurement cycles compress decision timelines through consolidated engineering-procurement-construction contracting, while residential purchases stretch across individual consumer research and installer scheduling.
- Utility:Independent power producers and regulated utilities procure modules through master supply agreements covering multi-year deployment tranches, concentrating pricing power with EPCs capable of underwriting portfolio-scale performance guarantees. India's National Thermal Power Corporation and Solar Energy Corporation of India negotiate directly with CdTe manufacturers for domestic content-compliant supply. Utility procurement anchors manufacturing capacity planning. Commercial segment is where technology diversification concentrates.
- Commercial:Corporate offtakers under renewable energy credit obligations and net-zero commitments specify building-integrated and rooftop systems where on-site generation displaces retail electricity rates. Amazon, Walmart, and Microsoft data center operators in the United States source thin film for carport and facade applications where structural specifications exclude conventional modules. Commercial drives premium product development. Residential lags in thin film penetration.
- Industrial:Manufacturing facilities with high baseload consumption and available roof area prioritize energy cost stabilization over maximum yield optimization.
- Residential:Single-family homeowners rarely specify thin film directly, encountering technology through installer recommendations or new construction builder programs.
Utility procurement dominates module volume. Commercial distributed generation is expanding most quickly as corporate renewable mandates proliferate.
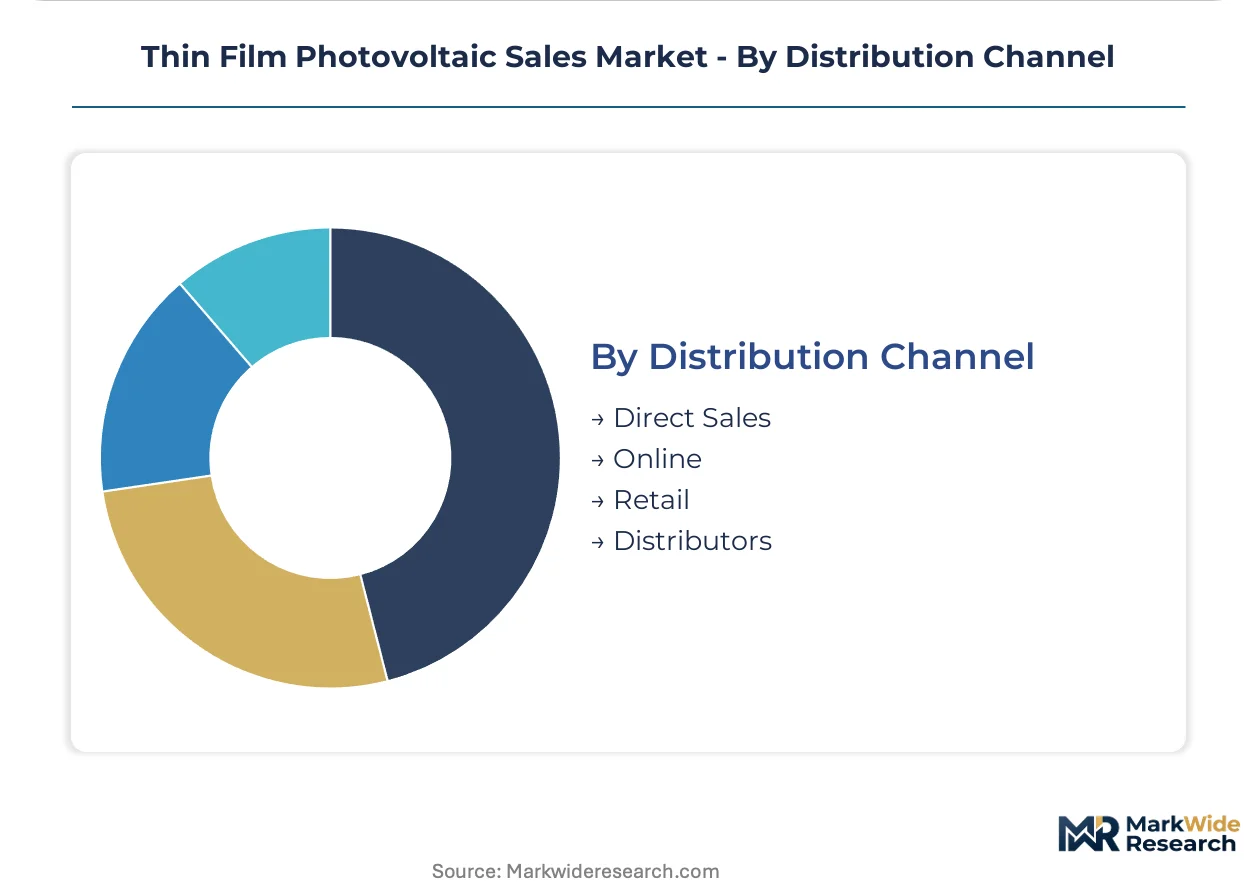
Distribution Channel:
Direct sales from manufacturers to project developers compress channel margins on large transactions, while retail and online channels stretch turnaround times through inventory holding and consumer education burdens.
- Direct Sales:Module manufacturers maintain dedicated utility and commercial account teams that negotiate specifications, warranties, and delivery schedules for project-specific procurement. First Solar's direct relationships with NextEra Energy and Duke Energy Renewables in the United States bypass distributor markups on gigawatt-scale orders. Direct sales anchor utility-scale revenue. Distributor networks are where geographic expansion concentrates.
- Distributors:Regional and national wholesale electrical distributors stock inventory for commercial and residential contractors requiring rapid fulfillment and credit terms. Rexel and WESCO in North America, and SolarWorld and Krannich Solar in Europe, maintain thin film SKUs for contractors serving building-integrated and specialized rooftop segments. Distributors bridge manufacturer scale with contractor accessibility. Online channels remain underdeveloped.
- Retail:Home improvement and electrical supply retailers serve DIY consumers and small contractors through counter sales and limited technical support.
- Online:E-commerce platforms capture minimal thin film transaction value due to shipping constraints on glass-glass modules and installation complexity requiring professional labor.
Direct sales dominate utility procurement volume. Distributor relationships are deepening fastest as manufacturers pursue commercial segment penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme anchors regional policy momentum, with BIS certification requirements and domestic value-add thresholds reshaping procurement patterns across multiple geographies.
United States
Utility-scale developers in Texas and Arizona prioritize CdTe modules for high-irradiance climates, with EPA cadmium recovery protocols governing end-of-life handling. First Solar's Ohio manufacturing cluster supplies independent power producers seeking bankable 25-year warranties under FERC interconnection standards.
India
Rajasthan and Gujarat host gigawatt-scale solar parks procuring CdTe under PLI scheme guidelines, with CEA grid codes mandating module performance testing. Domestic manufacturing commitments concentrate in these western states as developers negotiate master supply agreements with integrated semiconductor-to-module operations.
Germany
Commercial rooftop installations in Bavaria and North Rhine-Westphalia specify CIS and perovskite alternatives under federal building authority mandates for third-party verified recovery plans. REACH substance restrictions tilt public-sector procurement toward documented closed-loop recycling rates.
Japan
METI certification requirements and feed-in-tariff structures channel commercial rooftop demand toward domestic CIS supply, with Solar Frontier K.K. maintaining dedicated production for Tokyo and Osaka metropolitan areas. Kansai and Chubu regions concentrate distributed generation deployment.
China
Dual carbon goals accelerate perovskite R&D pilot lines in the Yangtze River Delta, with MIIT standards governing module efficiency benchmarks. Shanghai and Suzhou manufacturing clusters attract display coating equipment suppliers transitioning to photovoltaic deposition systems.
Thin Film Photovoltaic Sales Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around vertically integrated manufacturers with captive semiconductor production and specialized developers of tandem architectures. Three archetypes dominate: utility-scale volume suppliers, building-integrated specialists, and materials-agnostic technology licensors. Capacity expansion and strategic partnerships constitute the primary competitive moves, with manufacturers securing tellurium feedstock through offtake agreements and perovskite developers licensing deposition equipment from display industry suppliers.
Within the integrated-manufacturer tier, First Solar anchors North American supply through Ohio and India operations, while Solar Frontier K.K. occupies a position exemplifying Japan-focused CIS production. Oxford Photovoltaics represents the tandem-architecture specialist archetype, with its perovskite-silicon development program attracting building-integrated project specifications in European markets. These three entities collectively illustrate the geographic and technological segmentation governing competitive positioning.
| Leading Market Players |
|---|
| First Solar |
| Oxford Photovoltaics |
| Kaneka Corporation |
| Ascent Solar Technologies |
| MiaSole Hi-Tech Corp. |
| Global Solar |
| Solar Frontier K.K. |
| Hanergy Thin Film Power Group |
| Sharp Corporation |
| Others |
Pricing and Supply Chain Analysis
Tellurium refining capacity clustering in China and Japan concentrates upstream pricing power for cadmium-telluride manufacturers, compressing margin pools at module assembly tiers while rewarding integrated semiconductor-to-module operators with captive feedstock control.
Pricing Analysis
Geographic price spreads between Ohio-manufactured CdTe modules and Asian-imported alternatives reflect tariff exposure and logistics cost differentials. Three-tier pricing structure across premium certified, standard utility-grade, and economy project-residual tiers segments procurement by warranty length and bankability requirements. Pricing pressure stems from crystalline silicon cost compression in utility-scale tenders, with Indian PLI scheme beneficiaries absorbing margin compression to secure domestic content compliance. Utility procurement teams exhibit highest price sensitivity through consolidated EPC negotiations, while building-integrated project developers prioritize aesthetic performance over per-watt cost.
Supply Chain Analysis
Contract manufacturing concentration sits with First Solar's vertically integrated Ohio and India facilities, supplemented by Solar Frontier K.K.'s dedicated Japanese CIS lines and emerging Chinese perovskite pilot operations. Geographic supply concentration spans China for tellurium refining and glass substrates, Japan for specialized deposition equipment, and India for PLI-incentivized module assembly. Raw material dependencies include tellurium metal, cadmium compounds, indium, and gallium. Single-source vulnerability around Chinese tellurium concentrate exposes CdTe producers to geopolitical disruption and concentrate price volatility. Distribution runs through direct manufacturer relationships for utility-scale procurement and regional electrical distributors for commercial rooftop channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perovskite stability standardization at IEC represents a regulatory inflection that will separate bankable manufacturers from pilot-line operators, compressing commercialization timelines for building-integrated and tandem architectures.
For Market Incumbents: Build captive tellurium recovery infrastructure as a circular-economy moat. First Solar should expand closed-loop recycling partnerships with end-of-life module aggregators to secure feedstock supply as the installed base ages. Solar Frontier K.K. must accelerate CIS efficiency roadmaps to defend premium rooftop positioning against perovskite-silicon tandems entering commercial production.
For New Entrants and Emerging Players: Mid-market commercial building facades in Germany and South Korea represent the most penetrable entry point for perovskite-silicon tandem specialists. Agrivoltaics applications in Japan and France offer dual-revenue stream validation for semi-transparent architectures. Licensing deposition equipment from display industry suppliers accelerates pilot-to-commercial scale-up without captive capital intensity.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across perovskite manufacturing as solution-processed deposition replaces vacuum-based systems. Long-term viability over the next decade hinges on IEC certification achievement and 25-year encapsulation integrity validation. Acquisition targets should demonstrate third-party verified degradation rates under damp-heat testing protocols. The signal to watch is BIS certification progress for Indian market entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Tellurium Recovery Infrastructure | Captive feedstock supply secures margin resilience against Chinese concentrate price volatility. |
| Perovskite-Silicon Tandem Pilot Line Scale-Up | Oxford Photovoltaics validates manufacturing feasibility for building-integrated premium segments. |
| PLI Scheme Domestic Manufacturing Commitments | India's fiscal incentives attract multi-gigawatt capacity in Rajasthan and Gujarat solar parks. |
| IEC Stability Standardization Engagement | Consensus test protocols enable bankable warranties for 25-year project finance structures. |
| Agrivoltaics Dual-Use Land Development | Semi-transparent modules generate crop revenue alongside electricity in Japan and France. |
Research Methodology
Cross-validation between utility procurement databases and equipment supplier order books anchors the qualitative findings. Primary interviews with EPC contractors, IPP project developers, thin film manufacturing executives, and grid operators informed demand-side assumptions. Secondary validation drew from FERC interconnection filings, CEA grid code notifications, METI feed-in-tariff revisions, and REACH substance restriction updates. Bottom-up module shipment aggregation and top-down renewable deployment targets triangulate market sizing.
Calibration against historical CdTe and CIS deployment trajectories refined growth assumptions across the analysis window. Segmentation modeling incorporated product type, installation category, end-user archetype, and distribution channel dimensions. CAGRs derived from regression analysis of policy incentive trajectories and manufacturing capacity announcements. Industry-specific forecast inputs include PLI scheme disbursement schedules and perovskite stability certification timelines.
Practitioners should monitor IEC test protocol finalization and BIS certification batch approvals for early signals of perovskite commercialization acceleration. Forecasts reflect stated policy commitments and announced manufacturing investments, with revision triggers including tellurium supply disruptions, REACH cadmium threshold tightening, or perovskite encapsulation breakthroughs. Quarterly review of module shipment customs data and utility interconnection queues is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
US Solar Tracker Market
Solar Power Systems
Flexible Parylene-Based Solar Cells Market
Solar Power Systems
Spray-On Solar Cells Market
Solar Power Systems
Poland Solar Energy Market
Solar Power Systems
Global Solar Panel Tracking Mount Market
Solar Power Systems
Netherlands Solar Energy Market
Solar Power Systems
Greece Renewable Energy Market
Solar Power Systems
Solar Transparent Backsheet Market
Solar Power Systems
Solar Photovoltaic (PV) Market
Solar Power Systems
Kuwait Solar Energy Market
Solar Power Systems
South America Solar PV Inverters Market
Solar Power Systems
Marine Solar Panel Market
Solar Power Systems
Solar Rack Market
Solar Power Systems
United States Distributed Solar Power Generation Market
Solar Power Systems
Solar Cells Market
Solar Power Systems
China Distributed Solar Power Generation Market