
 Building-Integrated Photovoltaic (BIPV) Roofing Market | 2026-2036
Building-Integrated Photovoltaic (BIPV) Roofing Market Size, Share, and Industry Trends Forecast 2026-2036
Building-Integrated Photovoltaic (BIPV) Roofing Market Outlook
The performance gap between premium crystalline silicon systems and commodity thin-film alternatives is broadening as efficiency benchmarks diverge. Tesla leverages its integrated solar roof ecosystem to dominate the premium residential channel across North America. LONGi Green Energy Technology anchors utility-scale BIPV deployment through aggressive R&D spending on heterojunction cell architectures. Onyx Solar specializes in architectural glass-integrated photovoltaics for commercial facades and atrium roofs, sustaining margin pools in the high-design segment.
Building-integrated photovoltaic roofing refers to solar energy generating materials that replace conventional building envelope components rather than being mounted atop them, typically achieving power conversion efficiencies between 15% and 22% for crystalline variants while serving simultaneous weatherproofing and structural functions. Glass-integrated modules lead commercial new construction due to superior durability and aesthetic integration, whereas flexible thin-film systems represent the fastest-growing installation category for curved industrial roofs and heritage building retrofits where rigid panels prove impractical. Shingle-format products increasingly occupy the residential renovation channel as homeowners seek alternatives to visible rack-mounted arrays.
The EU Green Deal and Energy Performance of Buildings Directive mandate near-zero energy standards for new public and commercial structures across member states, directly expanding addressable demand for BIPV roofing systems. Germany's KBA-adjacent building codes and France's RE2020 environmental regulations further tighten thermal performance requirements that photovoltaic-integrated envelopes satisfy more readily than conventional insulation-plus-panel combinations. Stakeholders must monitor how the EU AI Act and evolving CSRD disclosure rules reshape procurement criteria for smart-building-integrated energy systems.
Market Dynamics
The EU Green Deal's near-zero energy mandates for new construction are compressing traditional roofing procurement cycles and forcing crystalline silicon BIPV systems into standard building envelopes rather than premium retrofit add-ons.
Growth Catalysts
- RE2020 Environmental Regulations:France's building performance standards mandate renewable energy integration for new commercial structures, eliminating conventional roofing from compliant designs.
- Industrial Warehouse Retrofits:Nordic logistics operators are accelerating thin-film flexible installations on curved metal roofs where rigid crystalline panels cannot mechanically conform.
- Net-Zero Compliance Deadlines:Germany's KBA-adjacent codes and Energy Performance of Buildings Directive timelines are pulling forward BIPV adoption in commercial real estate development pipelines.
Market Restraints
- Polysilicon Input Volatility:Crystalline silicon tile production remains exposed to metallurgical-grade silicon price swings concentrated in Chinese smelting capacity.
- Heritage Building Technical Constraints:Load-bearing limitations on protected structures in Italy and Spain block rigid glass-integrated modules, forcing suboptimal thin-film performance trade-offs.
- Skilled Installer Scarcity:Certified BIPV roofing technicians are concentrated in Germany and the Netherlands, creating deployment bottlenecks for residential retrofits in Southern Europe.
Strategic Opportunities
- CSRD Disclosure Requirements:The EU's Corporate Sustainability Reporting Directive is creating procurement preference for photovoltaic-integrated envelopes that simplify Scope 3 emissions accounting.
- Agricultural Building Integration:Dutch and Danish greenhouse operators are piloting semi-transparent BIPV glass that maintains crop photosynthesis while generating power.
- Digital Twin Convergence:Building information modeling platforms are unifying energy performance simulation with structural load calculations, compressing BIPV specification timelines.
Industry Challenges
- Fire Safety Certification Delays:EN 13501-1 reaction-to-fire testing protocols for integrated photovoltaic roofs are creating 8-14 month approval bottlenecks for new product variants.
- Legacy HVAC Integration Complexity:Existing building management systems in French and German commercial stock require costly middleware upgrades to coordinate BIPV generation with thermal load management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building-Integrated Photovoltaic (BIPV) Roofing Market |
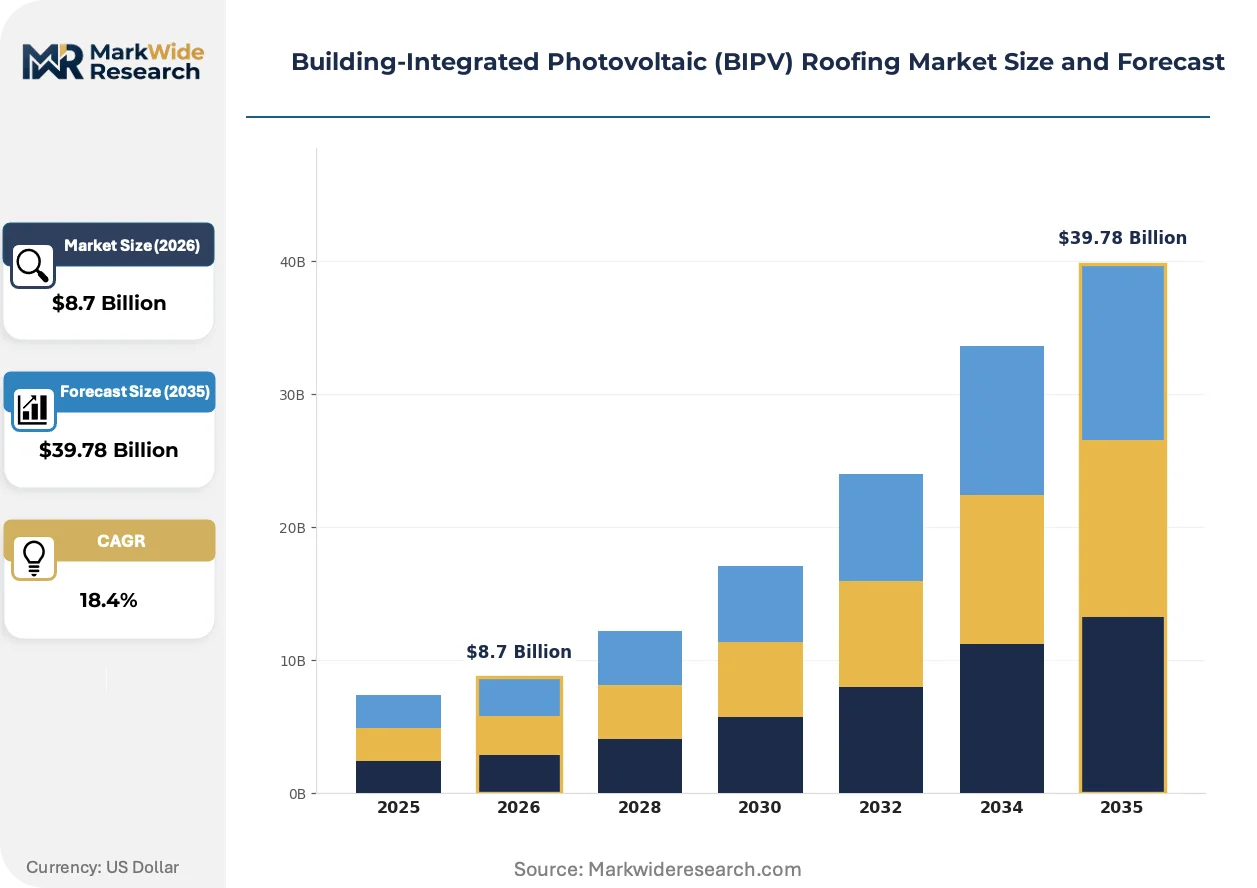
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Flexible, Shingles, Tiles Installation Type: New Construction, Retrofit, Renovation, Upgrades End User: Residential, Commercial, Industrial, Government Technology: CIGS, CdTe, Crystalline Silicon, Organic Photovoltaics |
| Companies Covered | SolarEdge Technologies, SunPower Corporation, Onyx Solar, Tesla, AGC Inc., Solaria Corporation, Ertex Solartechnik GmbH, LONGi Green Energy Technology, Mitrex Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building-Integrated Photovoltaic (BIPV) Roofing Market Strategic Shifts
Heterojunction cell architectures and building information modeling platforms are compressing the specification-to-installation timeline for integrated photovoltaic envelopes. Three developments are restructuring competitive positioning.
Perovskite-silicon tandem cell technology is unifying high conversion efficiency with flexible substrate compatibility. Dutch greenhouse developers and Nordic warehouse operators are piloting these laminates on curved structural surfaces. This convergence is collapsing the traditional segmentation between rigid crystalline premium products and thin-film commodity alternatives.
The EU AI Act's risk classification framework for smart-building energy systems is reshaping procurement documentation requirements. Automated fault detection algorithms in BIPV installations now face conformity assessment protocols previously reserved for critical infrastructure. German commercial developers are front-loading compliance costs into early design phases to avoid retrofit liability exposure.
Design-build firms are consolidating specification authority that architects and general contractors previously fragmented. French and Italian residential channels are seeing direct manufacturer-to-developer contracting displace traditional distributor networks. This concentration is visible in multi-unit housing projects near Lyon and Milan where roofing subcontractors no longer intermediate product selection.
Building-Integrated Photovoltaic (BIPV) Roofing Market Segmentation
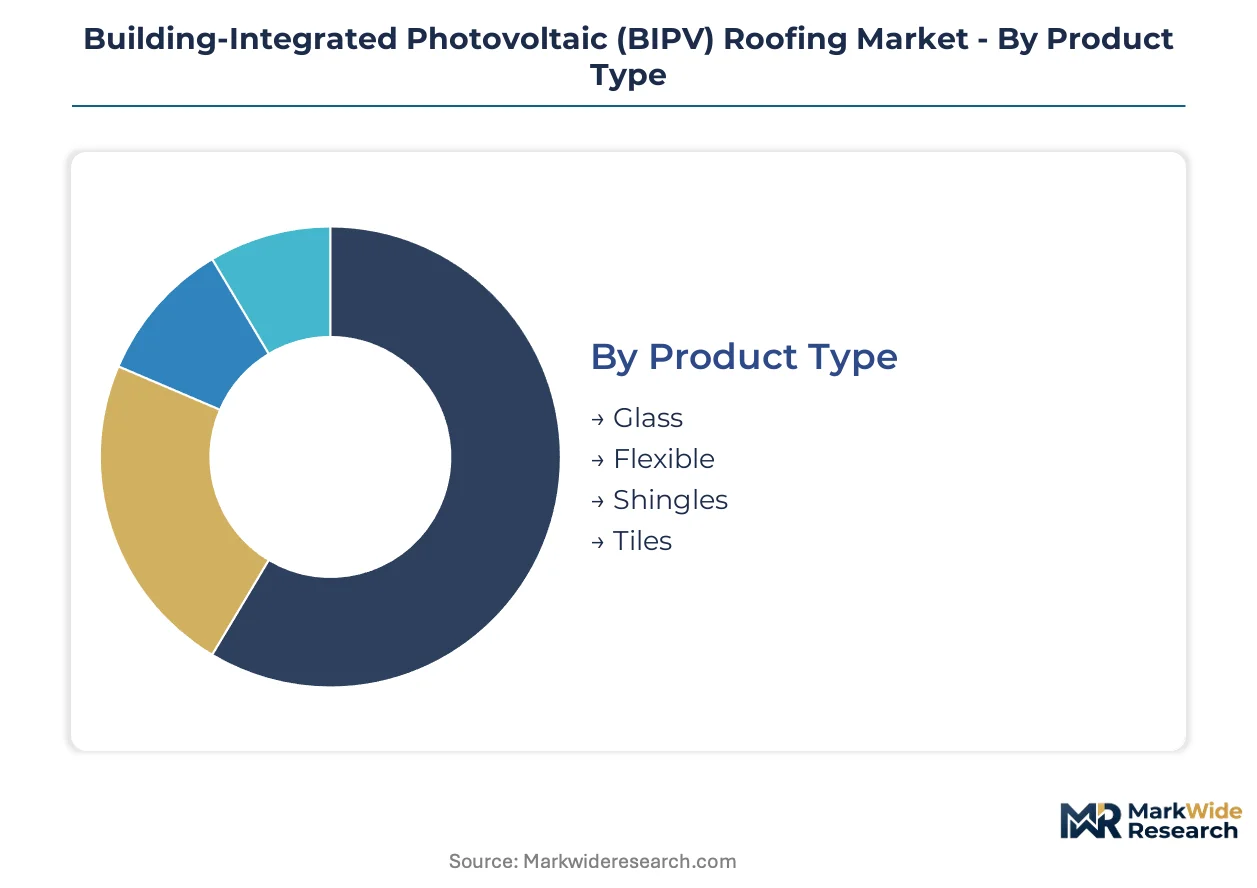
BIPV roofing procurement diverges sharply across building lifecycle stages, with new construction favoring integrated glass systems while retrofits drive flexible thin-film adoption on structurally constrained roofs. Understanding these segment boundaries clarifies where technology substitution occurs versus where architectural lock-in persists.
Product Type:
Upgrade cycles vary dramatically by material durability, with glass-integrated systems outlasting two to three roofing generations while flexible membranes align with standard commercial roof replacement intervals.
- Glass:Laminated photovoltaic glazing achieves 25-30 year service life and dominates commercial atrium and skylight specifications. German and Dutch developers specify these for net-zero office compliance under Energy Performance of Buildings Directive mandates.
- Flexible:Polymer-substrate thin-film laminates conform to curved metal decking without structural reinforcement. Nordic warehouse operators deploy these on barrel-vaulted roofs where rigid modules impose unacceptable dead loads.
- Shingles:Asphalt-replacement formats target residential renovation channels seeking concealed solar integration.
- Tiles:Ceramic and concrete-replacement systems serve Mediterranean markets with heritage aesthetic requirements.
Volume placements concentrate in Glass; the faster expansion belongs to Flexible.
Installation Type:
Cost tier separation is pronounced, with new construction embedding BIPV at marginal envelope cost premiums while retrofits bear full demolition and structural reassessment expenses.
- New Construction:Integrated specification during design phase eliminates redundant weatherproofing layers. French RE2020 compliance deadlines are pulling these into standard commercial development pro formas.
- Retrofit:Standalone replacements of functioning conventional roofs face extended payback scrutiny. Italian and Spanish residential channels show constrained uptake due to installer certification scarcity.
- Renovation:Triggered replacements during major building system overhauls reduce incremental cost barriers.
- Upgrades:Partial roof section replacements allow phased capital deployment on large commercial footprints.
Capital deployment tilts toward New Construction; Renovation captures the steepest expansion trajectory as building stock turnover accelerates.
End User:
Customer type determines performance tolerance and procurement sophistication, with industrial buyers prioritizing kilowatt-hour yield per square meter while residential purchasers weigh aesthetic concealment.
- Residential:Single-family and multi-unit housing drives shingle-format demand where homeowner associations restrict visible rack-mounted arrays. Southern European markets show particular sensitivity to tile-profile authenticity.
- Commercial:Office and retail developers specify glass-integrated systems for facade and atrium applications. CSRD disclosure requirements are shifting procurement toward photovoltaic envelopes that simplify Scope 3 emissions accounting.
- Industrial:Warehouse and logistics operators prioritize maximum roof coverage on expansive flat or curved structures.
- Government:Public building mandates under EU Green Deal directives create stable demand for high-durability installations.
Commercial leads absolute deployment; Industrial posts the fastest capacity additions as Nordic logistics construction booms.
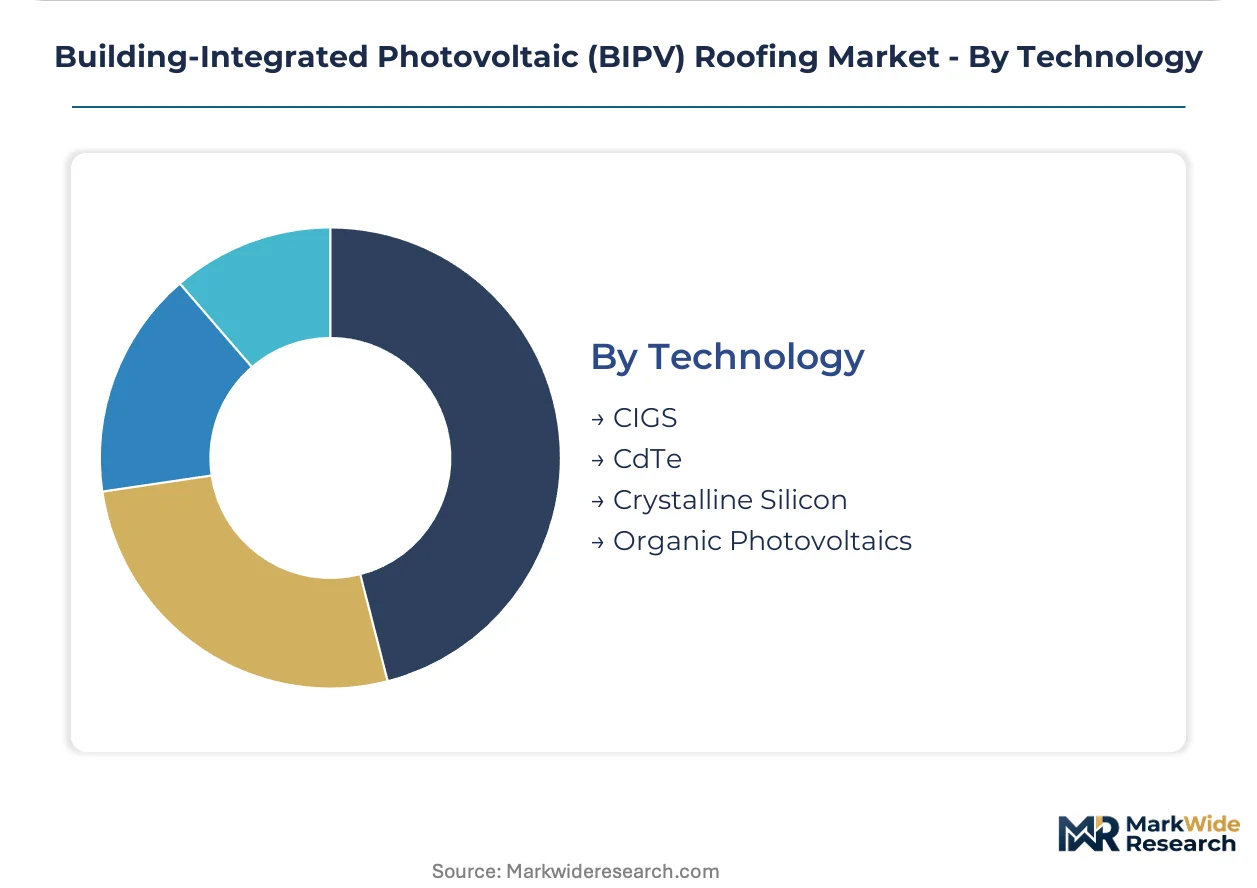
Technology:
Supply concentration in crystalline silicon processing creates cost tier separation, while thin-film alternatives occupy niches where substrate flexibility or low-light performance outweighs efficiency penalties.
- Crystalline Silicon:Monocrystalline and polycrystalline cells embedded in glass or tile formats deliver 18-22% conversion efficiency. LONGi Green Energy Technology and tier-one Chinese manufacturers anchor cost reduction through wafer scale and heterojunction R&D.
- CIGS:Copper indium gallium selenide thin-film achieves superior low-light and high-temperature performance. Dutch greenhouse developers pilot semi-transparent variants maintaining crop photosynthesis.
- CdTe:Cadmium telluride modules offer competitive manufacturing costs on rigid glass substrates.
- Organic Photovoltaics:Polymer-based cells enable ultra-lightweight and potentially transparent applications at reduced efficiency.
Crystalline Silicon commands installed capacity; CIGS gains share fastest in building-integrated applications demanding mechanical conformity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Eindhoven anchors European BIPV manufacturing density through Brainport's photovoltaic equipment cluster. The Randstad corridor concentrates Dutch commercial deployment. German KBA-adjacent building codes pull demand northward.
Germany
Net-zero commercial construction in Frankfurt and Munich drives glass-integrated system specifications. KBA-adjacent building codes tighten thermal performance thresholds for new office stock. Bavarian industrial zones host installer certification programs that supply technicians across Southern Germany.
Netherlands
Logistics warehouse construction around Rotterdam and Eindhoven accelerates thin-film flexible adoption on curved metal decking. The EU Green Deal mandates near-zero energy standards for new public structures. Dutch greenhouse operators in Westland pilot semi-transparent BIPV glass maintaining crop photosynthesis.
France
RE2020 environmental regulations eliminate conventional roofing from compliant commercial designs in Lyon and Paris. Multi-unit housing near Lyon sees direct manufacturer-to-developer contracting displace traditional distribution. Auvergne-Rhône-Alpes hosts specification authority consolidation among design-build firms.
Italy
Heritage building load constraints in Rome and Florence block rigid glass modules, forcing thin-film trade-offs. Southern European installer certification scarcity creates deployment bottlenecks for residential retrofits. Milan's multi-unit housing channels show particular tile-profile authenticity sensitivity.
Spain
Crystalline silicon tile systems dominate residential renovations in Madrid and Barcelona. Mediterranean aesthetic requirements sustain ceramic-replacement product demand. Andalusian agricultural building integration pilots test semi-transparent glazing for livestock ventilation compatibility.
Building-Integrated Photovoltaic (BIPV) Roofing Market Competitive Environment
Capital-heavy producers compete with asset-light designers across crystalline silicon and thin-film technology vectors. The vendor base separates into integrated solar roof ecosystem operators, heterojunction cell architecture specialists, and architectural glass-integrated photovoltaic fabricators. Three archetypes dominate: premium residential channel incumbents, utility-scale deployment anchors, and high-design commercial segment specialists. Competitive moves concentrate on backward integration into wafer processing and strategic partnerships with building information modeling platforms.
Among North American-integrated ecosystem operators, Tesla occupies a position exemplifying premium residential channel dominance. Within heterojunction-focused scale players, LONGi Green Energy Technology sits within the utility-scale deployment archetype. On the architectural glass specialization vector, Onyx Solar represents the high-design commercial segment. These three anchors illustrate how technology differentiation and channel focus separate competitive positions without overlapping segment territory.
| Leading Market Players |
|---|
| SolarEdge Technologies |
| SunPower Corporation |
| Onyx Solar |
| Tesla |
| AGC Inc. |
| Solaria Corporation |
| Ertex Solartechnik GmbH |
| LONGi Green Energy Technology |
| Mitrex Inc. |
| Others |
Value Chain & Pricing Dynamics
Metallurgical-grade silicon price indices cascade through crystalline silicon BIPV supply chains, compressing margins for tile manufacturers while amplifying pricing power for integrated glass-integrated system producers with captive polysilicon supply. Chinese smelting capacity concentration transmits volatility into European procurement tiers, forcing buyers to absorb cost swings or shift toward thin-film alternatives with divergent input profiles.
Pricing Analysis
Kilowatt-hour yield per square meter anchors value-based pricing for commercial glass-integrated systems, with premium crystalline silicon products commanding substantial spreads over commodity thin-film alternatives. Certification under EN 13501-1 fire safety protocols and heterojunction cell efficiency benchmarks differentiate price tiers, while volume-scale procurement by Dutch logistics operators compresses unit economics for flexible installations. Cost compression in residential shingle formats is intensifying as Chinese wafer scale feeds oversupply into Southern European renovation channels. Industrial warehouse buyers exhibit lowest price sensitivity due to net-zero compliance deadlines, whereas Italian residential retrofits face acute budget constraints from extended payback scrutiny.
Supply Chain Analysis
Dual-sourcing requirements from German commercial developers mandate qualification of both Chinese crystalline silicon suppliers and European thin-film specialists, fragmenting procurement authority across project phases. Manufacturing concentrates in China for wafer and cell processing, Germany for glass-integrated module assembly, and the Netherlands for flexible laminate production. Polysilicon ingots, tempered photovoltaic glass, and copper indium gallium selenide precursors constitute critical input dependencies. Single-source vulnerability in Chinese metallurgical-grade silicon creates structural exposure for crystalline silicon tile producers. Distribution runs through design-build firms consolidating specification authority, displacing traditional roofing distributor networks in French and Italian multi-unit housing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The BIPV roofing market functions as a vertical-integration race where control over heterojunction cell architectures and wafer processing determines margin capture. Players are pursuing backward integration into polysilicon supply to insulate against Chinese smelting volatility.
For Market Incumbents: Extend certification portfolios under EN 13501-1 and EU AI Act conformity frameworks to lock out emerging thin-film competitors. Acquire installer training capacity in Southern Europe to overcome technician scarcity blocking residential retrofit penetration. Tesla's integrated solar roof ecosystem and LONGi's heterojunction scale threaten commodity crystalline silicon producers lacking downstream integration. For New Entrants and Emerging Players: France's RE2020 environmental regulations in the Auvergne-Rhône-Alpes corridor open a window for direct manufacturer-to-developer contracting models bypassing traditional distribution. Target Nordic warehouse retrofit channels where curved metal decking excludes rigid incumbents. Pursue agricultural building integration pilots in Dutch Westland greenhouses as a beachhead for semi-transparent CIGS laminates. For Investors and Strategic Acquirers: Distressed-cycle entries favor architectural glass-integrated photovoltaic fabricators with EN 13501-1 pre-certification and established design-build firm relationships in Germany and the Netherlands. Long-term viability hinges on positioning for perovskite-silicon tandem commercialization. Watch fire safety testing approval bottlenecks as an inflection indicator for competitive consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Heterojunction Cell Architecture Investment | LONGi Green Energy Technology anchors utility-scale deployment through aggressive R&D spending on conversion efficiency gains. |
| Fire Safety Certification Acceleration | EN 13501-1 pre-approval compresses 8-14 month bottlenecks, unlocking German commercial development pipelines. |
| Installer Training Network Buildout | Bavarian certification programs supply technicians across Southern Germany, creating regional moats. |
| Direct Manufacturer Contracting | French design-build firms consolidate specification authority, displacing traditional distributor networks near Lyon. |
| Perovskite Tandem Pilot Deployment | Dutch greenhouse developers test mechanical conformity on curved structural surfaces, collapsing rigid-flexible segmentation. |
Study Parameters
Document review covered EU Green Deal implementation guidelines, Energy Performance of Buildings Directive national transposition documents, and KBA-adjacent building code amendments, complemented by interviews with commercial real estate developers, certified BIPV roofing technicians, glass-integrated module procurement managers, and greenhouse operators piloting semi-transparent systems. Secondary validation drew from EPC contractor project databases, FERC interconnection filings for building-integrated generation, and IEA distributed solar deployment reports. Bottom-up project pipeline analysis triangulated against top-down regulatory mandate modeling.
Installed capacity and revenue outputs were generated through technology-segmented deployment modeling across the projection horizon. Segmentation dimensions encompassed product type (glass, flexible, shingles, tiles), installation category (new construction, retrofit, renovation, upgrades), end-user vertical (residential, commercial, industrial, government), and cell technology (crystalline silicon, CIGS, CdTe, organic photovoltaics). CAGRs were derived from regulatory deadline pull-forward effects and building stock turnover velocity. Key inputs included RE2020 compliance timeline enforcement rates and Nordic logistics construction permit issuance patterns.
The model assumes a particular technology adoption path; alternative pathways for perovskite-silicon tandem commercialization would alter the outlook toward flexible substrate dominance. Forecasts reflect assumptions regarding EN 13501-1 approval velocity, Chinese polysilicon capacity expansion, and EU AI Act risk classification enforcement. Deviation in heritage building load-bearing regulatory interpretation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Carport Market
Solar Power Systems
Venezuela Solar Energy Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
Brazil Solar Energy Market
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
Middle East and Africa Solar Photovoltaic (PV) Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Spain Rooftop Solar Market
Solar Power Systems
Kuwait Solar Energy Market
Solar Power Systems
Polycrystalline Solar Cell Market
Solar Power Systems
Solar PV Module Market
Solar Power Systems
Slovakia Solar Energy Market
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Middle-East Solar Power Market
Solar Power Systems
Asia-Pacific Distributed Solar Power Generation Market
Solar Power Systems
Grid-Connected Solar Microinverter Market