
 Solar Pontoon Market | 2026-2036
Solar Pontoon Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Pontoon Market Analytics
Market Context
Commercial marina and resort deployment is rebalancing the solar pontoon demand mix away from purely residential lake installations. SUNGROW leverages its power electronics heritage to dominate utility-scale floating solar integration. Vikram Solar anchors its position through module specialization for humid, corrosive water environments. SCG Chemicals Co., Ltd. competes via advanced polymer formulation for UV-resistant pontoon hulls.
Technical Definition and Segment Structure
A solar pontoon is a buoyant, modular platform engineered from high-density polyethylene or fiber-reinforced polymer composites, designed to support photovoltaic arrays on static or slow-moving water bodies while withstanding wave loads, biofouling, and chemical degradation. These systems enable electricity generation on reservoirs, quarry lakes, and irrigation ponds without consuming terrestrial land area. Floating solar panels occupy the dominant revenue position due to established engineering protocols and bankability with project financiers. The modular installation category is expanding fastest as developers prioritize redeployable assets that reduce decommissioning liability. Thin film technology segments command narrower deployment share but attract niche interest where weight minimization dictates pontoon specification.
Regulatory Framework and Outlook
The EU Green Deal and F-Gas Regulation shape European product standards by restricting synthetic buoyancy foam chemistries and mandating circular material recovery. China's MEE enforces water quality preservation rules that constrain anchoring methods and anti-fouling coatings on inland reservoirs. The US EPA and state-level water quality boards jointly oversee Section 404 permitting for floating solar on jurisdictional waters. Stakeholders must monitor evolving polymer recyclability mandates and dual-use waterbody zoning decisions that will determine project pipeline viability.
Market Dynamics
The EU Green Deal's renewable waterbody mandates are compressing installation timelines while forcing polymer recyclability upgrades, creating a dual-pressure environment where marina operators must simultaneously deploy floating solar and certify circular material recovery.
Growth Catalysts
- EU Green Deal Mandates:Binding renewable energy targets for water-adjacent infrastructure are compelling commercial marina operators across Germany, the Netherlands, and Belgium to retrofit existing dock systems with floating photovoltaic arrays.
- Reservoir-Based Solar:China's MEE water quality preservation rules favor dual-use reservoir projects that generate electricity while reducing evaporation losses, accelerating procurement from state-owned irrigation authorities.
- Modular Redeployment:Fiber-reinforced polymer pontoon systems enable asset relocation between seasonal water bodies, cutting decommissioning liability for quarry lake developers in the United States.
Market Restraints
- HDPE Feedstock Volatility:High-density polyethylene resin prices fluctuate with naphtha-cracking economics, squeezing margin stability for pontoon hull fabricators concentrated in East Asian petrochemical clusters.
- Anchoring System Limitations:MEE constraints on reservoir bed penetration methods restrict installation depth and wave-load tolerance, limiting project viability on China's deeper inland water bodies.
- Terrestrial Solar Substitution:Ground-mounted photovoltaic arrays on degraded land offer lower balance-of-system costs and simpler permitting, diverting utility-scale investment from floating configurations.
Strategic Opportunities
- US Irrigation District Deployment:California's Central Valley and Arizona's CAP canal network present underpenetrated acreage where evaporation suppression creates dual-revenue streams for agricultural water managers.
- F-Gas Regulation Tailwinds:The EU F-Gas phase-down is eliminating synthetic buoyancy foam chemistries, opening market share for bio-based polymer alternatives that meet circular material recovery mandates.
- Thin Film Convergence:Cadmium telluride and CIGS module technologies are integrating with lightweight pontoon substrates, enabling deployment on smaller ponds where crystalline silicon weight loads previously prohibited installation.
Industry Challenges
- Marine Engineering Talent Scarcity:Floating solar project developers face acute shortages of professionals credentialed in both photovoltaic electrical design and hydrodynamic mooring analysis.
- Dual Certification Timelines:Pontoon systems must simultaneously satisfy IEC 61215 module standards and ISO 19901-4 offshore structural protocols, extending pre-construction approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Pontoon Market |
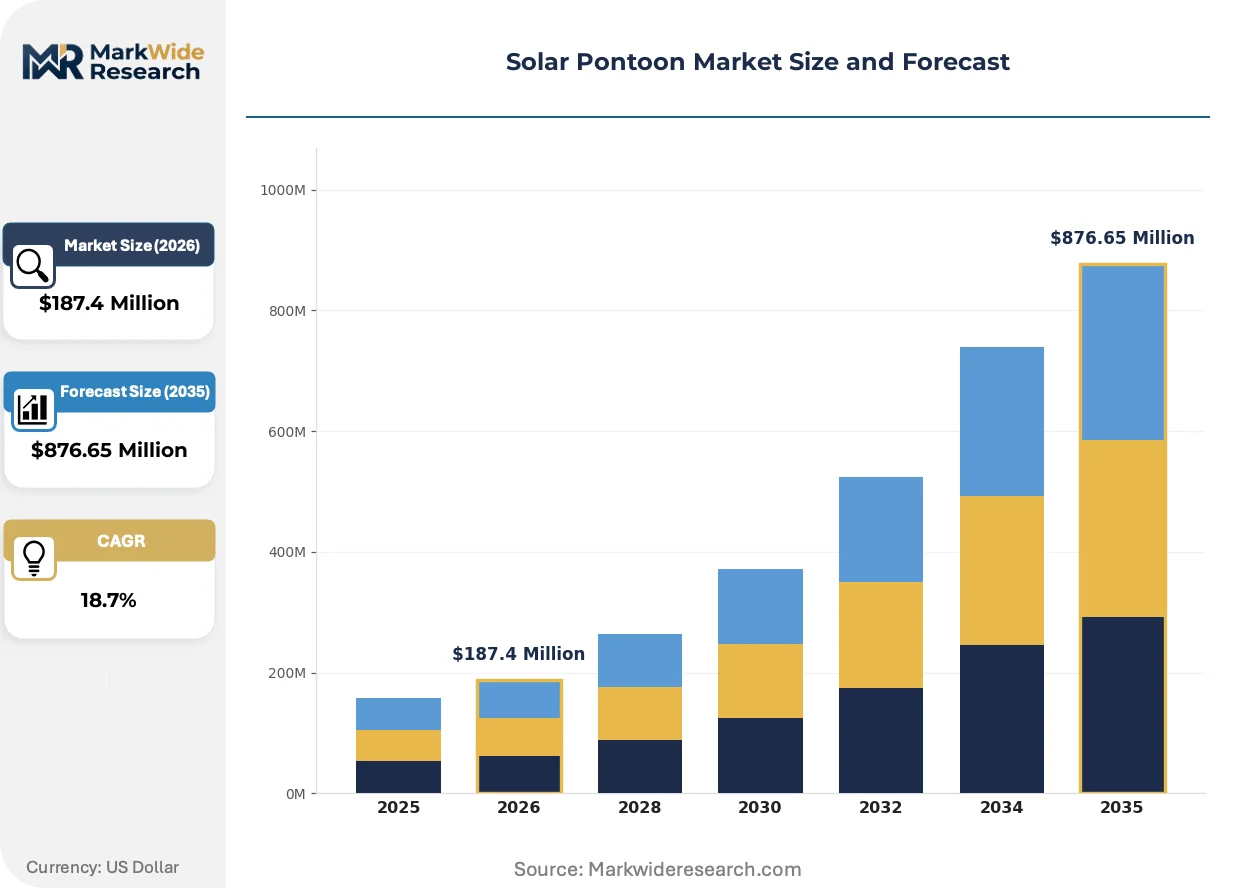
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floating Solar Panels, Solar Rafts, Solar Buoys, Solar Platforms End User: Agriculture, Commercial, Residential, Industrial Installation Type: Permanent, Semi-Permanent, Temporary, Modular Technology: Monocrystalline, Polycrystalline, Thin Film, Bifacial |
| Companies Covered | SCG Chemicals Co., Ltd., Vari Pontoons Pvt. Ltd., SUNGROW, Vikram Solar, Zhejiang Hisea Plastic Co.,Ltd, Vision Marine Technologies, Zhongshan Jintin Plastic & Hardware Products Co., Ltd., Paddle King, Mibet Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Pontoon Market Evolving Landscape
Floating solar engineering is pivoting from bespoke project design toward standardized platform architectures that reduce engineering redundancy and accelerate bankability assessments by institutional lenders.
Corrosion-resistant polymer composites are integrating anti-fouling surface treatments directly into hull extrusion processes, eliminating secondary coating application steps. Commercial marina operators in Germany and the Netherlands are specifying these integrated systems to reduce maintenance dredging cycles. The structural consequence is compressing total installed cost differentials between floating and ground-mounted solar configurations.
The EU F-Gas Regulation is phasing down hydrofluorocarbon-based buoyancy foams, forcing pontoon manufacturers to reformulate with expanded polystyrene or bio-based alternatives. Industrial consequence includes accelerated R&D spending on closed-cell polymer structures that maintain thermal insulation without synthetic blowing agents. German and Belgian fabricators are responding fastest, securing early-mover positions for circular material recovery certifications.
Utility procurement teams are consolidating vendor relationships around full-package EPC contractors capable of delivering electrical, structural, and mooring engineering under single accountability. This buyer concentration is displacing fragmented subcontractor models where marina operators previously managed separate pontoon, module, and anchoring suppliers. The shift is most visible in the United States, where reservoir project developers favor turnkey contracts to streamline Section 404 permitting risk.
Solar Pontoon Market Segmentation
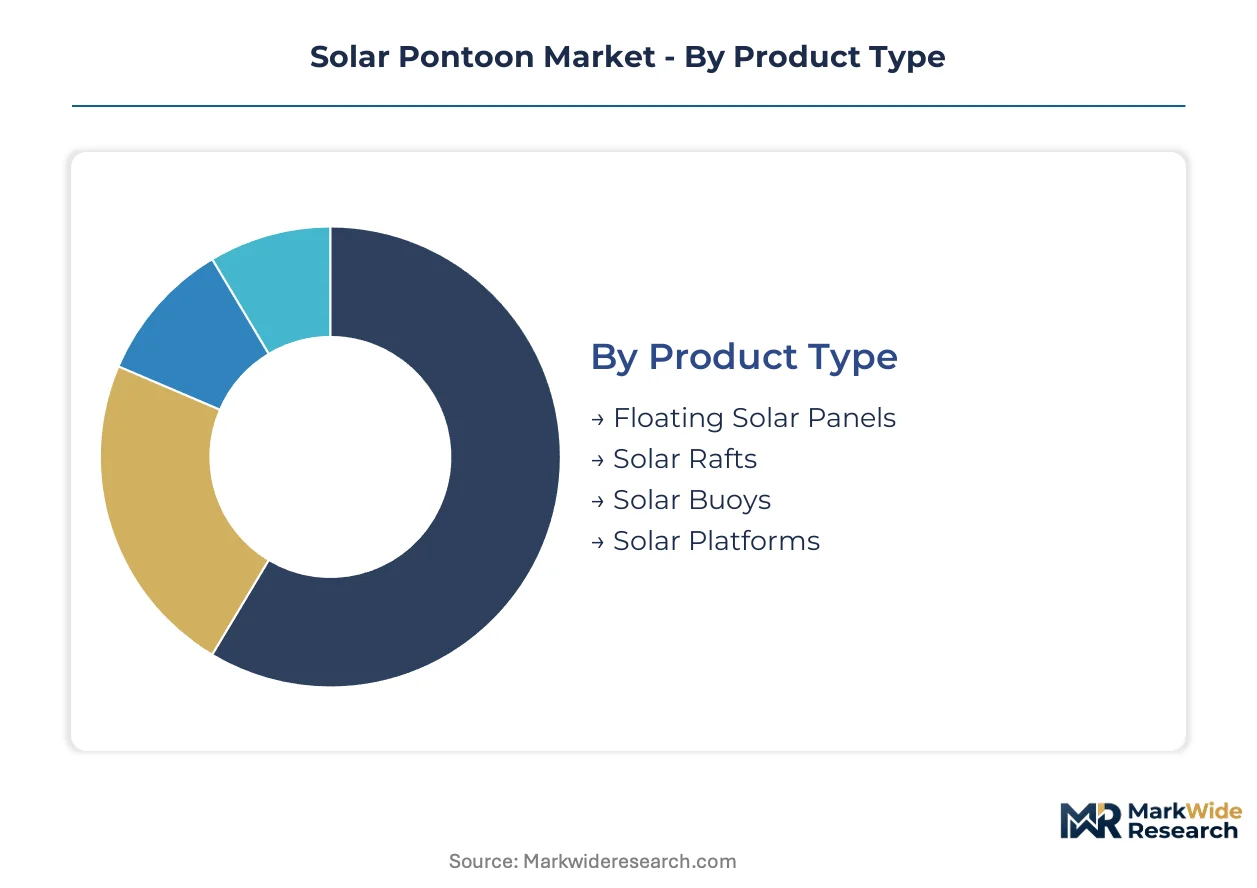
Solar pontoon procurement decisions hinge on waterbody permanence, load-bearing requirements, and regulatory decommissioning obligations. Segment differentiation determines material specification, anchoring complexity, and project financier risk assessment protocols.
Product Type:
Buyers select platform architecture based on array density requirements and wave-load tolerance specifications for specific waterbody conditions.
- Floating Solar Panels:Buoyant mounting systems engineered from high-density polyethylene or fiber-reinforced polymer composites support crystalline silicon modules on reservoirs and quarry lakes. Commercial marina operators in Germany and the Netherlands prioritize these systems for retrofitted dock installations under EU Green Deal renewable mandates.
- Solar Rafts:Low-profile pontoon arrays designed for minimal freeboard and reduced wind exposure on irrigation ponds. State-owned irrigation authorities in China procure these configurations where MEE water quality rules constrain anchoring penetration depths.
- Solar Buoys:Compact single-module platforms for distributed sensor networks and small-scale off-grid applications.
- Solar Platforms:Large-area integrated decks supporting utility-scale arrays with centralized inverter housing and maintenance walkways.
Volume sits with floating solar panels; growth tilts toward solar rafts.
End User:
Customer type dictates procurement scale, financing structure, and operational integration with existing water management infrastructure.
- Commercial:Marina operators and leisure resort developers deploy multi-megawatt arrays with integrated guest amenity power supply. Belgium and Netherlands commercial harbor authorities accelerate retrofit procurement to satisfy binding renewable targets for water-adjacent infrastructure.
- Agriculture:Irrigation district managers install evaporation-suppression systems on canals and reservoirs. California Central Valley water districts represent underpenetrated acreage where dual-revenue streams from electricity generation and water loss reduction drive procurement.
- Residential:Private lake owners and rural property developers specify small-scale systems for off-grid cabin power and dock electrification.
- Industrial:Mining companies and manufacturing facilities with on-site quarry lakes deploy self-consumption arrays to offset facility electricity demand.
Commercial deployments dominate installed capacity; agricultural applications are expanding most quickly.
Installation Type:
Project developers weigh capital commitment against regulatory decommissioning liability and site tenure security.
- Modular:Interlocking pontoon units enabling seasonal relocation and asset redeployment between water bodies. Quarry lake developers in the United States favor these systems to eliminate long-term site restoration obligations.
- Permanent:Fixed anchoring with concrete deadweight or driven pile systems for decades-long operational life. Utility-scale reservoir projects in China specify permanent installations where state ownership guarantees site tenure.
- Semi-Permanent:Seasonal removal capability with reusable anchoring hardware for irrigation ponds with fluctuating water levels.
- Temporary:Rapid-deployment configurations for disaster relief, construction site power, or pilot project validation.
Permanent installations hold the largest share; modular systems gain share fastest as decommissioning liability tightens.
Technology:
Module selection determines pontoon payload, electrical configuration, and bankability with institutional lenders.
- Monocrystalline:High-efficiency silicon cells maximizing power output per pontoon area. German utility-scale floating solar projects specify monocrystalline arrays to minimize platform material costs and mooring complexity.
- Bifacial:Dual-sided light capture leveraging albedo reflection from water surfaces. Developers on Arizona CAP canals and California irrigation reservoirs deploy bifacial modules to exploit elevated reflectivity from concrete-lined waterways.
- Polycrystalline:Cost-optimized silicon technology for price-sensitive agricultural and residential deployments.
- Thin Film:Cadmium telluride and CIGS lightweight alternatives enabling deployment on smaller ponds where crystalline silicon weight loads previously prohibited installation.
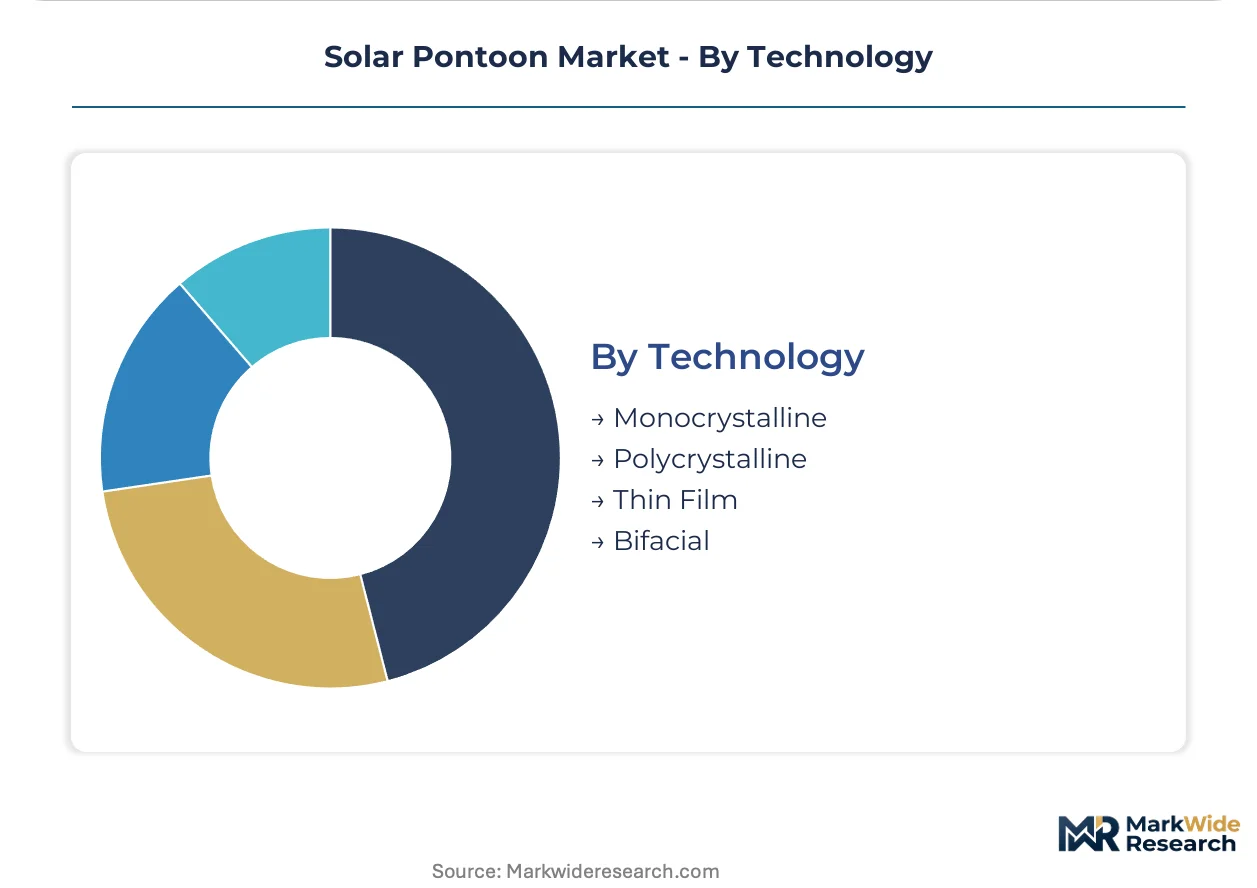
Monocrystalline technology commands the dominant position; bifacial modules show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate floating solar manufacturing clusters, while Germany's industrial heartlands anchor European demand for marina-integrated photovoltaic systems.
United States
California Central Valley irrigation districts and Arizona CAP canal authorities drive procurement for evaporation-suppression solar arrays. The EPA and state water quality boards jointly administer Section 404 permitting for floating installations on jurisdictional waters. Texas quarry lake developers in the Permian Basin specify modular redeployable systems to avoid long-term site restoration liabilities.
Germany
Commercial harbor authorities in Hamburg and Bremerhaven accelerate retrofit procurement to satisfy EU Green Deal binding renewable targets for water-adjacent infrastructure. The EU F-Gas Regulation phases down hydrofluorocarbon-based buoyancy foams, forcing polymer reformulation among North Rhine-Westphalia fabricators. Bavarian leisure resort developers on Lake Constance and Chiemsee integrate guest amenity power supply with floating photovoltaic dock systems.
China
State-owned irrigation authorities in Anhui and Jiangsu provinces procure reservoir-based solar configurations where MEE water quality preservation rules favor dual-use projects. The Ministry of Ecology and Environment constrains anchoring penetration methods on deeper inland water bodies. Zhejiang and Jiangsu manufacturing clusters supply high-density polyethylene hull components to domestic and export markets.
Netherlands
Rotterdam and Amsterdam commercial marina operators retrofit existing dock infrastructure under stringent EU Green Deal renewable mandates. The ECHA REACH framework regulates polymer recyclability certifications for circular material recovery. Randstad region engineering firms specialize in hydrodynamic mooring analysis for North Sea canal floating solar deployments.
India
Tamil Nadu and Maharashtra state irrigation departments evaluate reservoir-based floating solar for agricultural water loss reduction. The Central Electricity Authority issues technical standards for grid-connected floating photovoltaic systems. Gujarat coastal industrial zones explore salt-resistant pontoon materials for brackish water lagoon installations.
Solar Pontoon Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with utility-scale project developers consolidating procurement around full-package EPC contractors while residential lake owners source through fragmented specialty distributors. Market structure tilts toward tiered concentration at the top and geographic fragmentation below. Three archetypes dominate: power electronics heritage firms pivoting into floating integration, polymer composite specialists controlling hull material supply, and marine engineering contractors assembling turnkey mooring systems. Competitive moves center on backward integration into polymer resin production and strategic partnerships with irrigation district authorities.
Within the power electronics tier, SUNGROW anchors Chinese-origin supply for utility-scale floating solar integration, while Vikram Solar occupies a position among module specialists addressing humid, corrosive water environments. SCG Chemicals Co., Ltd. represents the polymer formulation archetype, with Thai industrial conglomerate heritage informing UV-resistant hull material development. These three exemplify how vertical specialization across electrical, structural, and material domains defines competitive positioning.
| Leading Market Players |
|---|
| SCG Chemicals Co., Ltd. |
| Vari Pontoons Pvt. Ltd. |
| SUNGROW |
| Vikram Solar |
| Zhejiang Hisea Plastic Co.,Ltd |
| Vision Marine Technologies |
| Zhongshan Jintin Plastic & Hardware Products Co., Ltd. |
| Paddle King |
| Mibet Energy |
| Others |
Value Network & Pricing Analysis
Captive polymer resin production in Zhejiang and Jiangsu manufacturing clusters anchors both hull material supply security and pricing power for Chinese fabricators serving utility-scale floating solar deployments. German and Belgian producers absorbing EU F-Gas reformulation costs face margin compression against these integrated competitors, while US quarry lake developers negotiate modular system premiums based on redeployment flexibility rather than commodity resin economics.
Pricing Analysis
Short lead-time premiums of 15-25% apply to fiber-reinforced polymer pontoon systems needed for EU Green Deal compliance deadlines in German harbor retrofits. Project-based contract structures dominate utility-scale reservoir deployments, with price differentiation resting on IEC 61215 certification tier and anchoring engineering scope. Cost compression in standard HDPE hull segments is intensifying because naphtha-cracking volatility feeds directly into resin spot markets. Agricultural irrigation districts in California exhibit highest price sensitivity, while commercial marina operators in Belgium and the Netherlands prioritize circular material recovery certifications over unit cost minimization.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and China's dual carbon enforcement are reshaping sourcing patterns for electrical components and polymer additives. HDPE resin supply concentrates in China, South Korea, and Saudi Arabia, with hull fabrication drawing from Zhejiang, Jiangsu, and North Rhine-Westphalia industrial clusters. Raw material dependencies rest on naphtha feedstock, UV stabilizer masterbatches, and corrosion-resistant mooring hardware. Single-source vulnerability in specialized anti-fouling coating chemistries creates supply chain risk as ECHA REACH restrictions tighten. Distribution runs through full-package EPC contractors in utility-scale segments and fragmented specialty distributors for residential lake applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around full-package EPC capability as fragmented subcontractor models face elimination by procurement teams seeking single-accountability contracting structures.
For Market Incumbents: Anchor market position through backward integration into polymer resin production and captive supply of UV-resistant hull formulations. Defend against terrestrial solar substitution by accelerating bankability certification with institutional lenders for standardized platform architectures. Prioritize certification investment in dual IEC 61215 and ISO 19901-4 compliance to compress pre-construction approval cycles. For New Entrants and Emerging Players: The premium-to-economy price gap in modular redeployable systems creates entry space for mid-tier competitors targeting US quarry lake developers with seasonal relocation capabilities. White-space targets include California Central Valley irrigation districts and Arizona CAP canal authorities where evaporation suppression creates dual-revenue streams. Agricultural water managers represent the most penetrable buyer segment; pursue direct engagement with irrigation district procurement officers rather than utility-scale developer channels. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to power electronics heritage firms seeking floating solar integration capabilities. Long-term viability favors specialists with polymer formulation expertise and established circular material recovery certifications under EU regulatory frameworks. Acquisition target archetypes include marine engineering contractors with hydrodynamic mooring analysis credentials and regional harbor authority relationships. Watch for inflection in dual-use waterbody zoning decisions that determine project pipeline viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin | Captive HDPE supply insulates margin stability against naphtha-cracking volatility in East Asian petrochemical clusters. |
| Circular Material Recovery Certification | ECHA REACH compliance opens procurement access to Rotterdam and Amsterdam commercial marina retrofit mandates. |
| Full-Package EPC Capability Buildout | Single-accountability contracting displaces fragmented subcontractor models in US Section 404 permitting pathways. |
| Thin Film Module Integration Partnership | Cadmium telluride convergence enables deployment on smaller ponds previously excluded by crystalline silicon weight loads. |
| Irrigation District Authority Alliance | Direct relationships with California Central Valley water districts secure underpenetrated evaporation-suppression acreage. |
Research Methodology
Independent corroboration across primary interviews with floating solar project developers, polymer composite fabricators, and commercial marina procurement officers, combined with secondary validation of MEE water quality filings, EU F-Gas regulatory texts, and EPC contractor bid documentation, underwrites the qualitative findings. Bottom-up triangulation against top-down market sizing from reservoir project databases and customs trade data for HDPE hull components ensures dimensional consistency. Stakeholder engagement spanned utility-scale developers in Anhui and Jiangsu provinces, North Rhine-Westphalia polymer formulators, and Arizona irrigation district managers.
Rate-of-change decomposition across the analysis window isolates volume drivers by product type, installation permanence, and end-user procurement scale. Segmentation dimensions modeled include platform architecture, waterbody application, technology payload, and regional regulatory framework. CAGRs derive from installed capacity buildout trajectories in reservoir, canal, and quarry lake deployments, cross-referenced against polymer feedstock cost indices and permitting velocity indicators. Industry-specific forecast inputs incorporate MEE anchoring constraint evolution and EU Green Deal mandate tightening schedules.
Inputs from state-owned irrigation authorities and commercial harbor operators were available through the study window; gaps in proprietary EPC contractor margin data introduce uncertainty bands around cost structure assumptions. Forecasts reflect documented regulatory trajectories and material science advancement assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Europe Solar Photovoltaic (PV) Market
Solar Power Systems
Residential Solar Energy Market
Solar Power Systems
Philippines Solar Energy Market
Solar Power Systems
Agriculture Solar Water Pumps Market
Solar Power Systems
Solar Powered Elevator Market
Solar Power Systems
Chile Solar Photovoltaic (PV) Market
Solar Power Systems
Global Rooftop Solar Photovoltaic Market
Solar Power Systems
Israel Solar Energy Market
Solar Power Systems
Solar EVA Market
Solar Power Systems
Floating Solar Panels Market
Solar Power Systems
US Solar Market
Solar Power Systems
Germany Distributed Solar Power Generation Market
Solar Power Systems
Solar PV Inverter Market
Solar Power Systems
Spain Solar Energy Market
Solar Power Systems
Portugal Solar Energy Market
Solar Power Systems
Solar Crimp Set Market