
 Bulgaria Solar Energy Market | 2026-2036
Bulgaria Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Bulgaria Solar Energy Market Analysis
Bulgarian photovoltaic module assembly capacity is hardening as domestic producers scale crystalline silicon output. PPC Renewables leverages its state-linked heritage to secure utility-scale auction allocations. Sunotec Group anchors distributed generation through its installer network across the Thracian Plain. Rezolv Energy competes on project development velocity for commercial rooftop portfolios.
Solar energy in Bulgaria encompasses photovoltaic systems converting sunlight into direct current electricity through semiconductor junctions, typically operating at 15-22% cell efficiency depending on silicon purity and passivation layers. The technology serves grid decarbonization, industrial self-consumption, and rural electrification objectives. Crystalline silicon panels dominate installed capacity due to proven degradation rates and local supply familiarity. Utility-scale application margins concentrate in power purchase agreement structuring, while battery storage pairing is gaining traction among energy developers seeking grid balancing revenues.
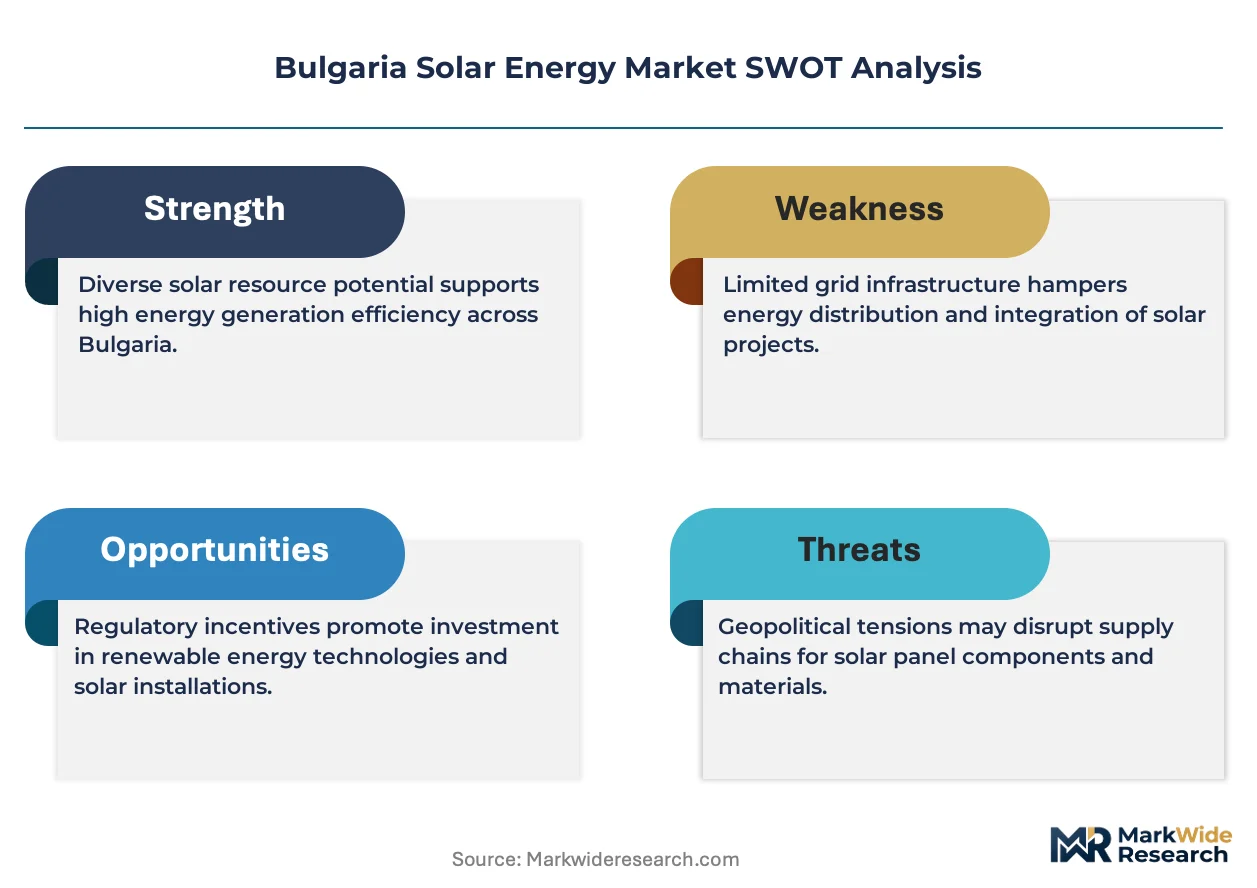
Bulgaria's State Energy and Water Regulatory Commission sets feed-in tariff ceilings, while the Ministry of Energy administers EU Modernisation Fund allocations for coal region transition. The National Recovery and Resilience Plan mandates renewable auction transparency, reshaping developer access to public land and grid connection priority. Stakeholders must monitor auction calendar density and grid reinforcement timelines to calibrate pipeline commitment.
Market Dynamics
EU Modernisation Fund allocations are redirecting capital from coal region transition into photovoltaic deployment, while grid connection priority rules under the National Recovery and Resilience Plan reshape developer competition for public land access.
Growth Catalysts
- Industrial self-consumption:Manufacturing facilities across the Thracian Plain are deploying rooftop systems to hedge volatile electricity tariffs.
- EU auction transparency mandates:The National Recovery and Resilience Plan institutionalizes competitive bidding for renewable allocations.
- Crystalline silicon cost curves:Domestic module assembly capacity expansion reduces import dependency for project developers.
Market Restraints
- Polysilicon supply concentration:Raw material sourcing remains concentrated among Asian producers, exposing Bulgarian developers to input cost volatility.
- Grid reinforcement timelines:Transmission infrastructure upgrades lag behind generation capacity additions in rural municipalities.
- Permitting density:Sofia and Plovdiv municipal authorities concentrate application volumes, creating procedural bottlenecks.
Strategic Opportunities
- Battery storage pairing:Grid balancing revenue streams are emerging as developers combine photovoltaic generation with lithium-ion systems.
- Coal region transition zones:The Maritsa basin offers brownfield sites with existing transmission access for utility-scale parks.
- Commercial rooftop aggregation:Distributed generation portfolios across small and medium industrial facilities remain underpenetrated.
Industry Challenges
- Electrical engineering talent scarcity:Grid interconnection specialists and power electronics technicians command premium compensation.
- Feed-in tariff ceiling calibration:State Energy and Water Regulatory Commission price bands require continuous monitoring for project finance viability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulgaria Solar Energy Market |
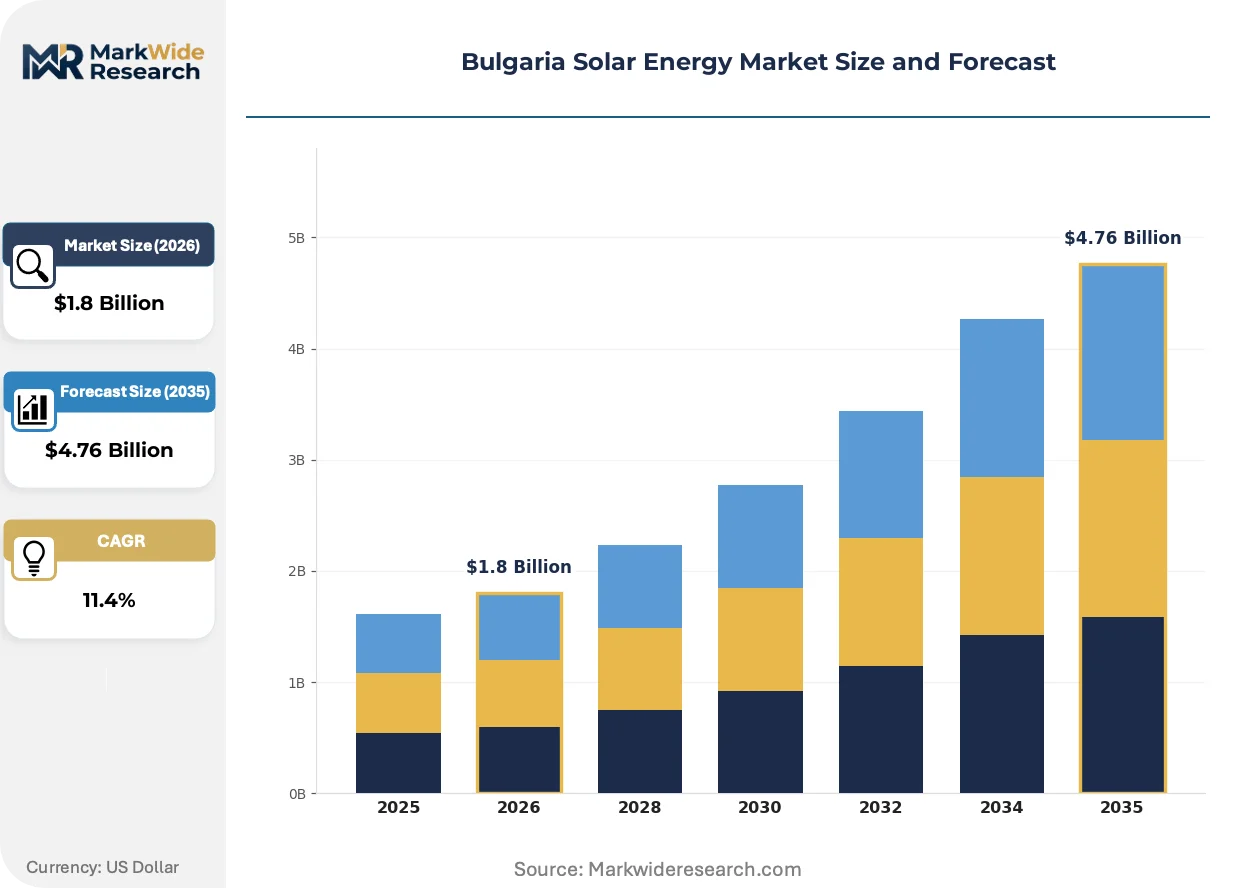
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Inverters, Mounting Systems, Battery Storage Application: Residential, Commercial, Industrial, Utility-Scale Technology: Thin-Film, Crystalline Silicon, Concentrated Solar Power, Bifacial End User: Homeowners, Businesses, Government, Energy Developers |
| Companies Covered | PPC Renewables, HEK Solar, Sunotec Group, Chint Green Energy, JinkoSolar Holding, Solarpro Holding, Rezolv Energy, Enery, PV Consult, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulgaria Solar Energy Market Emerging Trajectories
Digitalization of plant monitoring and automated fault detection is compressing operational expenditure structures. Module efficiency improvements and regulatory auction redesign are simultaneously altering competitive positioning.
String inverter technology with embedded DC-AC conversion intelligence is automating fault isolation and performance optimization across utility-scale installations. IPP operators are retrofitting existing parks with these systems to reduce truck-roll maintenance frequency. The technology is automating revenue protection by minimizing generation downtime during grid disturbances.
The National Recovery and Resilience Plan mandates renewable auction transparency, compelling the Ministry of Energy to publish connection priority criteria. This regulatory redesign accelerates developer pipeline commitment decisions. Commercial solar park applicants in Sofia and Plovdiv municipalities are restructuring land lease terms to align with auction calendar density.
Industrial offtakers are unbundling engineering-procurement-construction contracts from long-term operations and maintenance agreements. Large manufacturing facilities now tender these services separately to optimize lifetime cost structures. This procurement fragmentation is most visible among cement and metals processors seeking direct control over asset performance data.
Bulgaria Solar Energy Market Segmentation
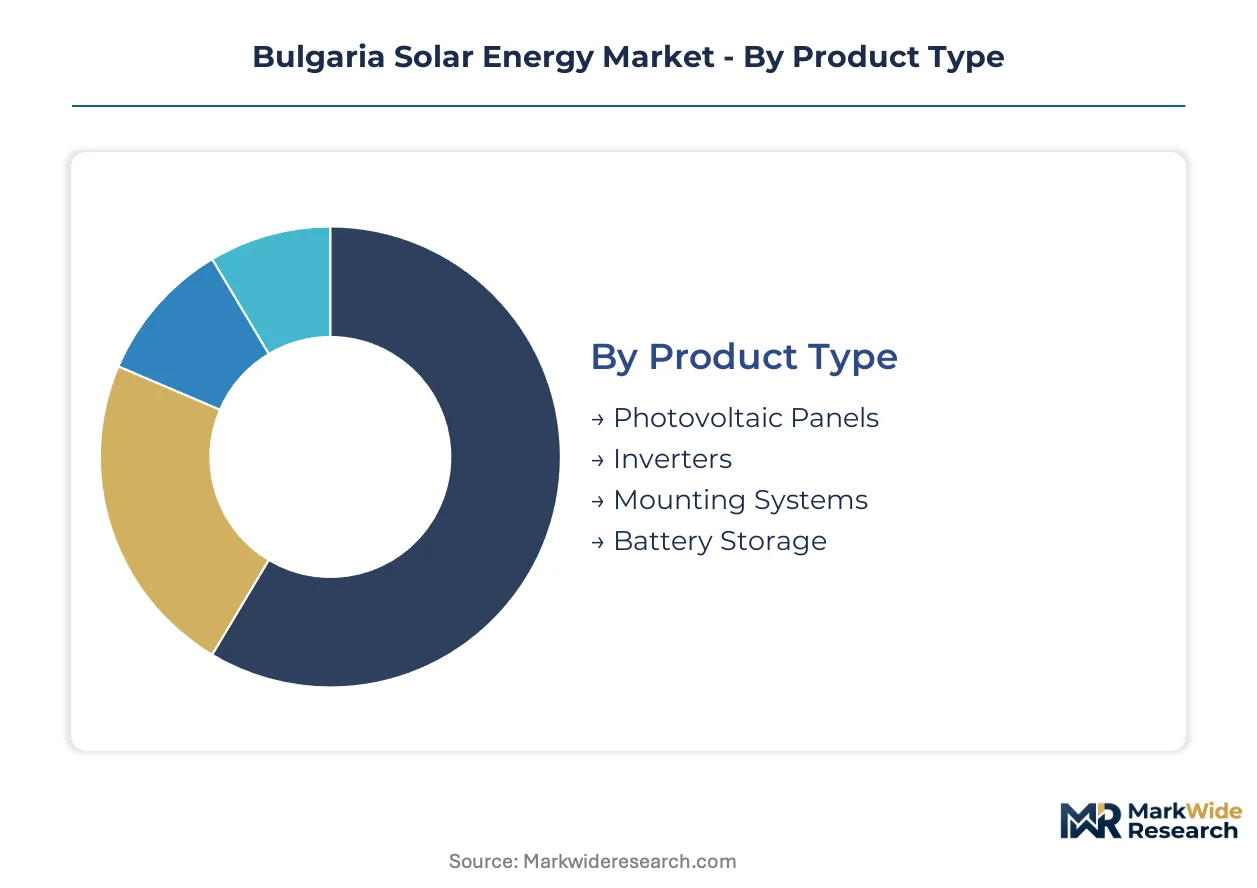
Solar energy deployment in Bulgaria fragments across hardware specifications, installation scale, and customer procurement sophistication. Understanding these divisions reveals where crystalline silicon cost curves intersect with auction-driven utility-scale development versus distributed commercial adoption.
Product Type:
Buyers differentiate primarily by capital intensity tolerance and supply chain proximity to domestic assembly capacity.
- Photovoltaic Panels:Crystalline silicon modules dominate Bulgarian procurement, with domestic producers scaling cell and wafer assembly to reduce import dependency. Thracian Plain industrial facilities prioritize rooftop deployment of these panels to hedge volatile electricity tariffs from the grid.
- Inverters:String inverter technology with embedded DC-AC conversion intelligence automates fault isolation across utility-scale installations. IPP operators retrofit existing parks with these systems to minimize generation downtime during grid disturbances and reduce truck-roll maintenance frequency.
- Mounting Systems:Fixed-tilt aluminum racking structures prevail in commercial rooftop applications across Sofia and Plovdiv municipalities.
- Battery Storage:Lithium-ion pairing with photovoltaic generation is climbing the fastest as developers seek grid balancing revenues under State Energy and Water Regulatory Commission frameworks.
Photovoltaic panels lead volumes today; battery storage is gaining share fastest.
Application:
Scale determines regulatory pathway complexity and access to EU Modernisation Fund allocations.
- Residential:Small-scale rooftop systems serve homeowners in peri-urban Sofia municipalities seeking energy independence. Permitting density in these administrative zones creates procedural bottlenecks that slow deployment velocity relative to commercial counterparts.
- Commercial:Manufacturing facilities across the Thracian Plain deploy mid-scale rooftop systems to secure direct control over electricity cost structures. Cement and metals processors increasingly unbundle engineering-procurement-construction contracts from operations and maintenance agreements.
- Industrial:Large energy consumers integrate photovoltaic generation with process heat requirements.
- Utility-Scale:Brownfield sites in the Maritsa basin leverage existing transmission access for competitive auction participation under National Recovery and Resilience Plan mandates.
Utility-scale installations anchor current capacity additions; commercial rooftops show steepest expansion trajectory.
Technology:
Cell efficiency benchmarks and degradation rates drive procurement decisions among Bulgarian developers.
- Crystalline Silicon:Proven degradation rates and local supply familiarity sustain market dominance. Passivation layer improvements push cell efficiency toward the upper bound of 15-22% operating ranges.
- Thin-Film:Cadmium telluride and copper indium gallium selenide technologies occupy niche utility-scale applications where temperature coefficient advantages outweigh efficiency penalties.
- Concentrated Solar Power:Parabolic trough and tower configurations require direct normal irradiance levels exceeding Bulgarian solar resource profiles.
- Bifacial:Dual-sided energy capture from albedo reflection is expanding most quickly in ground-mounted utility parks where terrain permits elevated installation heights.
Crystalline silicon commands installed base; bifacial modules are gaining share fastest.
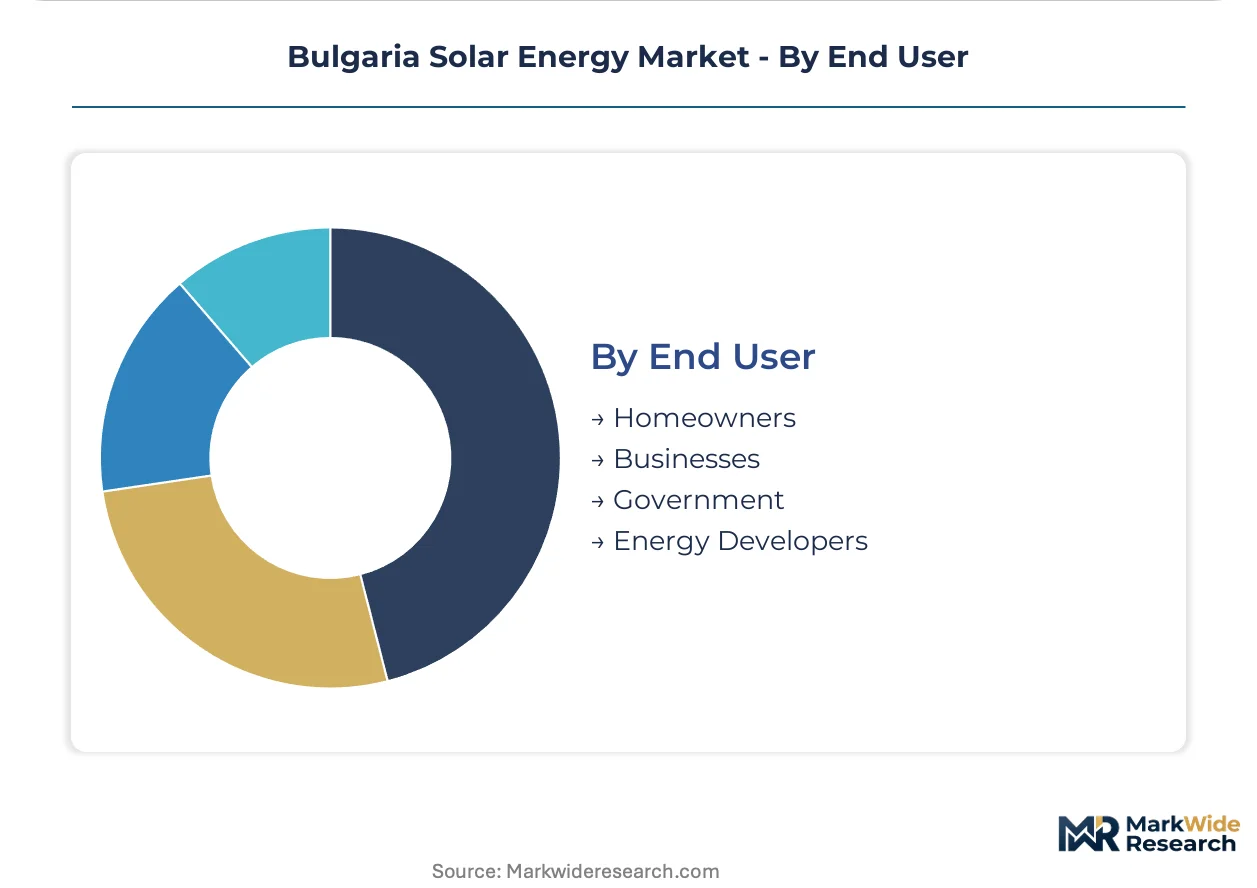
End User:
Balance sheet capacity and technical staffing determine procurement sophistication across customer categories.
- Energy Developers:Specialized firms structure power purchase agreements and grid connection priority applications under Ministry of Energy auction calendars. These entities concentrate project development velocity in coal region transition zones with existing transmission infrastructure.
- Businesses:Small and medium industrial facilities aggregate distributed generation portfolios that remain underpenetrated relative to large manufacturing counterparts. Procurement fragmentation into separate EPC and O&M tenders optimizes lifetime cost structures.
- Homeowners:Individual retail buyers navigate municipal permitting procedures in Sofia and Plovdiv administrative zones.
- Government:Public sector entities access EU fund allocations for renewable deployment on state-owned land and buildings.
Energy developers lead pipeline commitment; business aggregators are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Romania outpaces Bulgaria in utility-scale auction velocity, while Greece concentrates more commercial rooftop aggregation per capita. Both markets channel EU Modernisation Fund allocations toward coal region transition zones with existing transmission infrastructure.
Sofia City Region
Industrial facilities in the capital's peripheral municipalities deploy rooftop photovoltaic systems to hedge volatile electricity tariffs. The Ministry of Energy administers EU Recovery and Resilience Plan allocations that mandate competitive auction transparency. Municipal authorities concentrate permit applications, creating procedural bottlenecks that slow deployment velocity relative to provincial counterparts.
Plovdiv Region
Manufacturing processors across the Thracian Plain integrate mid-scale rooftop generation with process heat requirements. State Energy and Water Regulatory Commission feed-in tariff ceilings require continuous monitoring for project finance viability. The Maritsa basin offers brownfield sites with existing transmission access for utility-scale park development.
Varna Region
Coastal industrial zones leverage Black Sea port logistics for crystalline silicon module assembly supply chains. The National Recovery and Resilience Plan channels public land access toward renewable auction participants. Distributed generation portfolios remain underpenetrated among small and medium commercial facilities.
Burgas Region
Black Sea industrial clusters seek grid balancing revenues through battery storage pairing with photovoltaic generation. Grid connection priority rules reshape developer competition for transmission reinforcement timelines. Rural municipalities lag in infrastructure upgrades relative to generation capacity additions.
Bulgaria Solar Energy Market Vendor Landscape
Bulgarian state-linked utilities anchor one tier; international module manufacturers and specialized installers hold differentiated positions. The market structures around auction allocation access, domestic assembly proximity, and distributed generation network density. Three archetypes dominate: legacy energy incumbents leveraging regulatory relationships, international hardware suppliers with crystalline silicon cost curves, and regional project developers optimizing pipeline velocity. Competitive moves concentrate on securing grid connection priority and restructuring land lease terms to align with auction calendar density.
Within the state-linked incumbent tier, PPC Renewables occupies a position exemplifying utility-scale auction allocation strategies. Among specialized developers, Rezolv Energy and Sunotec Group represent contrasting archetypes—one optimizing commercial rooftop portfolio velocity, the other anchoring distributed generation networks across the Thracian Plain. These three entities illustrate how competitive positioning fragments across auction-driven utility-scale development versus commercial and industrial self-consumption aggregation.
| Leading Market Players |
|---|
| PPC Renewables |
| HEK Solar |
| Sunotec Group |
| Chint Green Energy |
| JinkoSolar Holding |
| Solarpro Holding |
| Rezolv Energy |
| Enery |
| PV Consult |
| Others |
Supply Flow & Price Mechanics
EU-linked auction participants with sovereign-backed financing access are restructuring procurement contracts to lock in crystalline silicon module pricing ahead of National Recovery and Resilience Plan allocation rounds. Their balance sheet scale compresses working capital costs for domestic assembly capacity, forcing private developers to absorb margin compression or cede grid connection priority.
Pricing Analysis
Capacity additions in Southeast Asian polysilicon refining are reshaping price floors for Bulgarian project developers dependent on imported wafers. The market runs on project-based long-term offtake structures, with price differentiation resting on module efficiency certification tiers and volume aggregation scale. Cost compression in standard-grade panels is intensifying because domestic Thracian Plain assemblers are scaling cell output. Small commercial rooftop aggregators exhibit highest price sensitivity; utility-scale IPPs with EU fund access show least.
Supply Chain Analysis
CE marking and grid code compliance certification gating restricts qualified supplier pools to Tier 1 crystalline silicon producers with Balkan distribution infrastructure. Geographic supply concentration centers on China, Vietnam, and Malaysia for cell and wafer inputs. Raw material dependencies rest on metallurgical-grade silicon, silver paste metallization, and ethylene-vinyl acetate encapsulant. Single-source vulnerability in polysilicon refining creates procurement risk. Distribution runs through Varna and Burgas port logistics clusters to Thracian Plain assembly facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Bulgaria solar energy market functions as a regulatory compounder where National Recovery and Resilience Plan auction transparency mandates are accelerating capital deployment velocity beyond neighboring Southeast European markets.
For Market Incumbents: Anticipate feed-in tariff ceiling recalibration by the State Energy and Water Regulatory Commission by securing grid connection priority allocations before auction density peaks. Defensive consolidation through backward integration into battery storage system assembly addresses emerging grid balancing revenue competition from Rezolv Energy and Sunotec Group pipeline velocity. For New Entrants and Emerging Players: Bifacial module technology with elevated albedo capture specifications offers entry wedge into ground-mounted utility parks where terrain permits dual-sided installation heights. Commercial rooftop aggregation across small and medium Thracian Plain industrial facilities remains the most penetrable white-space target. Direct EPC contracting bypassing bundled O&M structures accelerates customer acquisition among cement and metals processors. For Investors and Strategic Acquirers: Valuations sit cheapest among distributed generation specialists with installer network density but limited auction allocation track records. Long-term viability over the projection horizon rests on regulatory relationship durability with Ministry of Energy procurement officers. Acquisition target archetype: commercial rooftop aggregators with unbundled service capabilities. The signal to watch is State Energy and Water Regulatory Commission feed-in tariff band expansion announcements.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Storage Pairing | Grid balancing revenue streams under SEWRC frameworks attract lithium-ion system integration investment. |
| Backward Integration into Module Assembly | Domestic crystalline silicon cell production reduces import dependency and procurement cost volatility exposure. |
| Coal Region Brownfield Development | Maritsa basin sites with existing transmission infrastructure accelerate auction participation timelines. |
| Commercial Rooftop Aggregation | Unbundled EPC and O&M procurement structures optimize lifetime cost control for Thracian Plain manufacturers. |
| Grid Connection Priority Securement | National Recovery and Resilience Plan transparency mandates reshape developer competition for public land access. |
Methodological Framework
Multiple input streams — utility planning officers at state-linked incumbents, IPP project developers competing for auction allocations, EPC contractors with Thracian Plain installation networks, and grid operators managing transmission reinforcement timelines — were reconciled against secondary validation from Ministry of Energy auction calendars, State Energy and Water Regulatory Commission tariff filings, EU Modernisation Fund allocation disclosures, and project development database tracking. Bottom-up capacity addition modeling and top-down EU fund flow analysis were triangulated.
Historical auction allocation patterns were cross-referenced against panel input from crystalline silicon cost curve analysts and battery storage system integrators. Segmentation dimensions modeled span product type, application scale, technology efficiency tier, and end-user balance sheet capacity across the projection horizon. CAGRs were derived from auction calendar density projections and grid reinforcement timeline assumptions. Industry-specific forecast inputs include polysilicon spot price volatility bands and municipal permitting velocity differentials between Sofia-Plovdiv administrative zones and rural municipalities.
The model holds under stable EU Modernisation Fund allocation continuity and State Energy and Water Regulatory Commission tariff band predictability; deviation in auction transparency enforcement or grid connection priority rule suspension would shift developer pipeline commitment timing. Forecasts reflect these base-case assumptions with acknowledged sensitivity to polysilicon supply concentration shocks and electrical engineering talent scarcity compensation inflation. A model refresh is warranted upon material change in National Recovery and Resilience Plan renewable auction calendar density.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Southeast Asia Solar Energy Market
Solar Power Systems
Solar Photovoltaic (PV) Market
Solar Power Systems
Egypt Solar Energy Market
Solar Power Systems
Venezuela Solar Energy Market
Solar Power Systems
Ecuador Solar Energy Market
Solar Power Systems
Global Photovoltaic Market
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
Solar Panel Cleaning Equipment Market
Solar Power Systems
Solar Thermal Power Market
Solar Power Systems
North America Rooftop Solar Market
Solar Power Systems
Perovskite Solar Cell Market
Solar Power Systems
Solar Photovoltaic Modules Market
Solar Power Systems
Solar Energy Market
Solar Power Systems
Grid Connected PV Systems Market
Solar Power Systems
Solar Panel Bracket Market
Solar Power Systems
Australia Solar Power Market