
 Boat Solar Panel Market | 2026-2036
Boat Solar Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Boat Solar Panel Market Insights
Leasing and project finance for marine solar retrofits is narrowing the competitive field to firms with balance-sheet depth. SunPower leverages its high-efficiency cell architecture to command premium positioning in integrated marine energy systems. Renogy competes aggressively on modularity, offering scalable kits that reduce installer certification barriers for smaller yards. Solbian anchors the European racing and superyacht segment through custom flexible panel geometries that conform to curved deck surfaces.
Boat solar panels are photovoltaic modules engineered with saltwater-resistant encapsulants, marine-grade aluminum framing, and junction boxes rated for IP67 or higher ingress protection, designed to convert sunlight into DC electrical power for auxiliary loads, battery charging, and propulsion support aboard watercraft. Monocrystalline panels dominate installed value due to superior watt-per-square-meter density on space-constrained vessels, while flexible installation types capture the fastest growth trajectory as curved-deck compatibility becomes a purchase criterion. Thin-film variants occupy niche positions in weight-sensitive racing applications where grams translate directly to performance penalties.
IEC 61215 marine adaptations and ABYC electrical standards govern product certification and installation safety across major boating jurisdictions, with EPA vessel emissions guidelines indirectly stimulating auxiliary power electrification that expands addressable solar load. The EU Green Deal's maritime decarbonization pathways and REACH substance restrictions on hazardous encapsulants are reshaping supplier qualification requirements for panels sold in European waters. Stakeholders must monitor evolving certification reciprocity between classification societies and national regulators to anticipate which manufacturing footprints will retain market access.
Market Dynamics
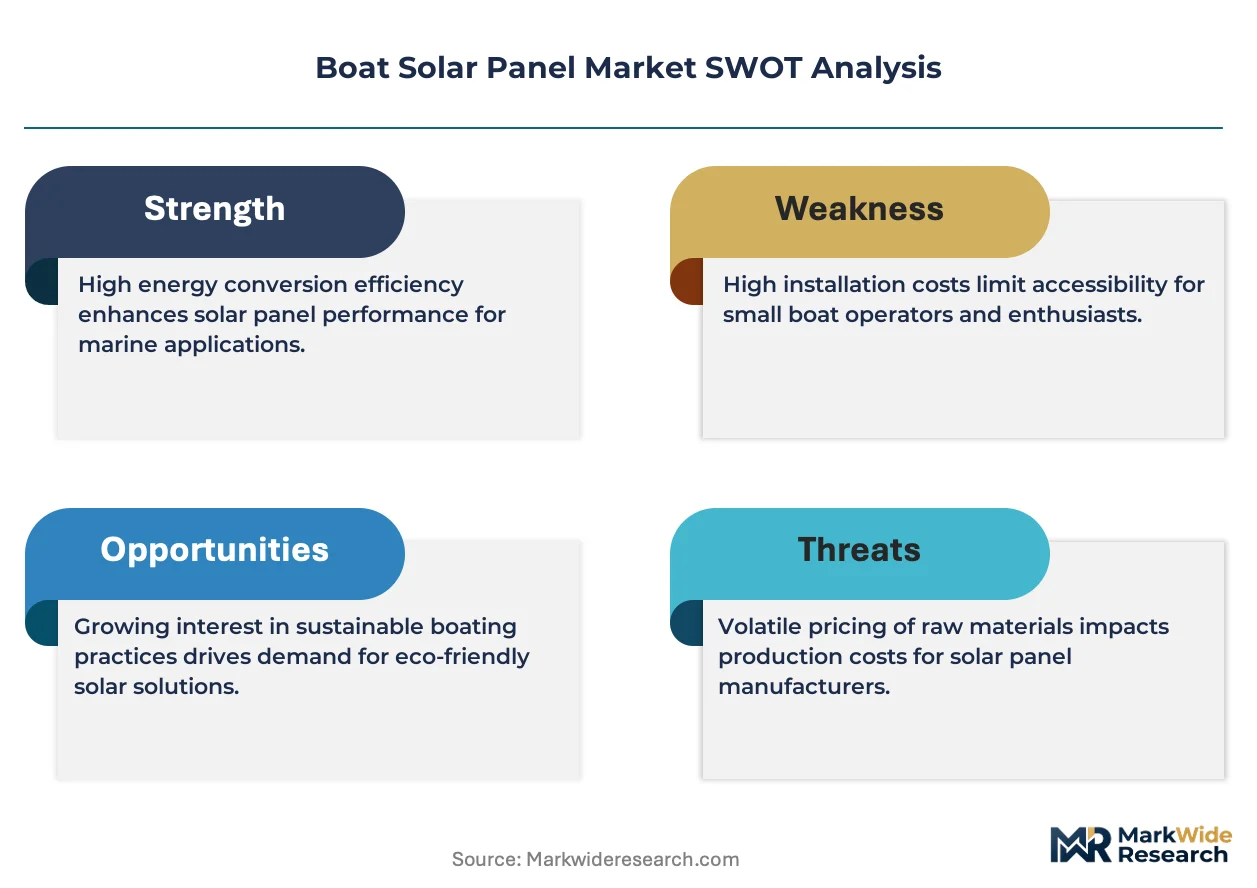
Marine-grade lithium-ion battery systems are virtualizing auxiliary power architectures across recreational and commercial fleets, compressing payback periods for solar retrofits and redrawing supplier qualification requirements around IEC 61215 marine adaptations.
Growth Catalysts
- EU Green Deal maritime pathways:Binding decarbonization targets for auxiliary power electrification are mandating shore-power alternatives that expand addressable solar load on inland and coastal vessels operating in European waters.
- Recreational boat owners:This buyer segment is expanding fastest as lithium-ion compatibility improves and integrated energy management systems reduce technical barriers to owner-installed upgrades.
- Flexible panel geometries:Curved-deck compatibility is becoming a purchase criterion in the racing and superyacht segment, pulling demand toward custom conformable modules that maximize surface utilization on complex hull shapes.
Market Restraints
- Silver and high-purity silicon input costs:Volatility in photovoltaic metallization materials is compressing module margins and forcing price pass-through negotiations with yard installers.
- East Asian cell manufacturing concentration:Supply vulnerability concentrates in Taiwan and mainland China fabrication facilities, exposing buyers to logistics disruption and tariff exposure on marine-grade cells.
- Saltwater-induced degradation rates:Accelerated encapsulant yellowing and junction box corrosion in tropical operating environments are shortening warranted lifespans below terrestrial equivalents.
Strategic Opportunities
- Nordic cruising grounds:Extended summer daylight hours and high electricity costs in Norwegian and Swedish marinas are creating favorable economics for solar-diesel hybrid auxiliary systems on liveaboard cruisers.
- Leasing and project finance:Balance-sheet-backed retrofit programs are narrowing the competitive field to firms capable of underwriting multi-vessel fleet conversions without upfront owner capital.
- AI-enabled energy management convergence:Machine learning load prediction is pairing with solar generation forecasting to optimize battery cycling and extend lithium-ion replacement intervals.
Industry Challenges
- Marine electrical certification timelines:ABYC standards compliance and classification society approvals are extending product launch cycles by eight to fourteen months for new module form factors.
- Installer skill scarcity:Qualified marine electricians capable of integrating high-voltage solar arrays with legacy 12V and 24V vessel electrical systems are concentrating in Mediterranean and Florida service clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boat Solar Panel Market |
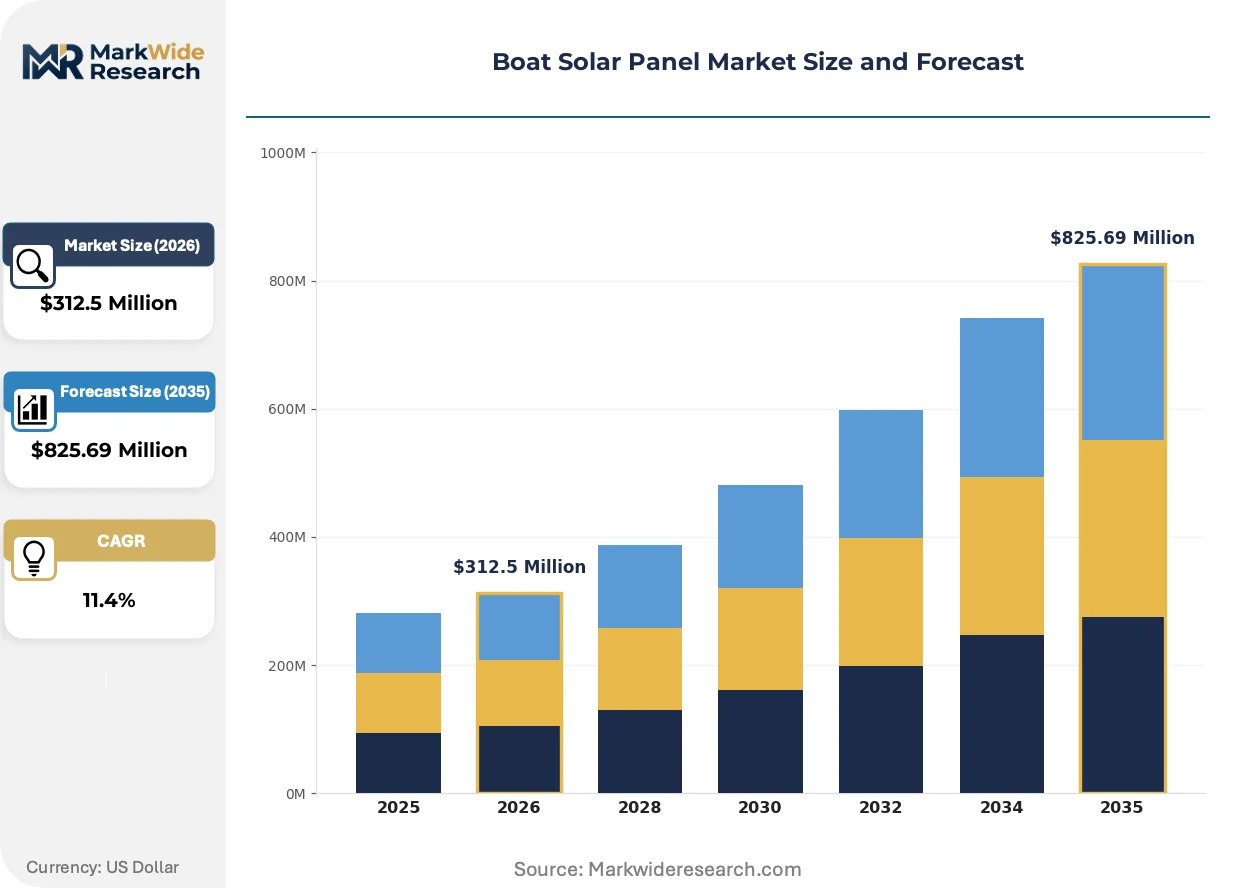
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $825.69 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial End User: Commercial Vessels, Recreational Boats, Fishing Boats, Houseboats Installation Type: On-Board, Portable, Fixed, Flexible Power Rating: 100W, 200W, 300W, 400W |
| Companies Covered | SunPower, Renogy, Solbian, HQST, Newpowa, ECO-Worthy, WindyNation, Photonic Universe, ACOPOWER, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boat Solar Panel Market Trends and Innovations
Photovoltaic technology is virtualizing traditional power generation roles aboard watercraft, with module architectures and business models compressing installation complexity and expanding addressable vessel categories.
Perovskite-silicon tandem cell architectures are virtualizing efficiency benchmarks for space-constrained marine applications. Superyacht integrators and racing teams are piloting these structures in weight-sensitive installations where watt-per-gram ratios determine competitive positioning. The technology is virtualizing the trade-off between panel area and auxiliary power autonomy that has constrained solar adoption on smaller hulls.
REACH substance restrictions on hazardous encapsulants are tightening supplier qualification requirements for panels sold in European waters. ECHA enforcement is accelerating reformulation investments by module manufacturers seeking continued market access. The regulatory pressure is compressing the supplier base toward firms with in-house polymer chemistry capabilities and EU-based testing infrastructure.
Marina-based energy-as-a-service models are displacing direct equipment sales in Mediterranean and Floridian cruising corridors. Fleet operators and charter companies are contracting for guaranteed auxiliary power availability rather than capitalizing panel assets. This procurement evolution is concentrating demand among finance-capable integrators capable of underwriting performance guarantees across multi-season operating contracts.
Boat Solar Panel Market Segmentation
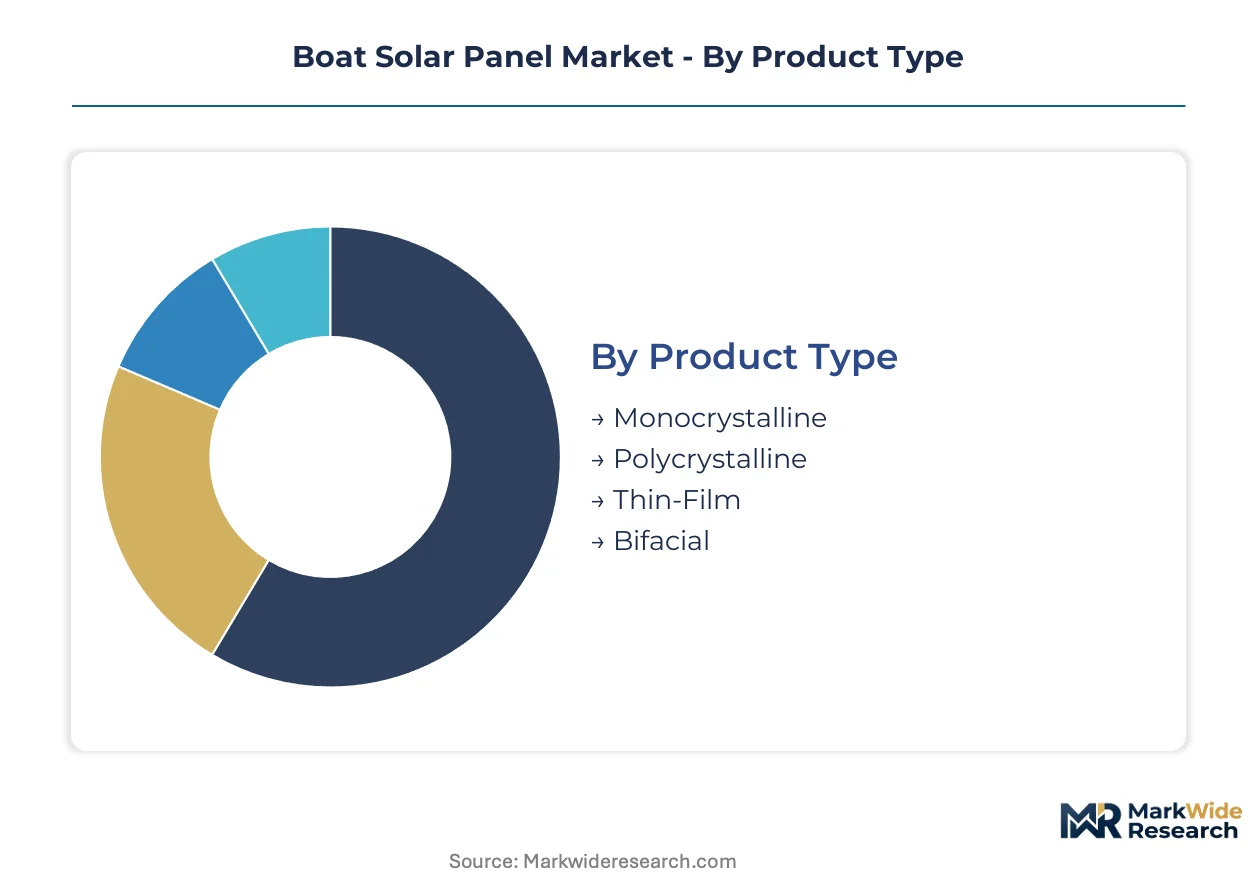
Marine photovoltaic deployment varies sharply by vessel architecture and operating profile, with saltwater exposure, deck curvature, and auxiliary load patterns dictating module selection. Segmentation reveals where technical specifications translate into commercial advantage across divergent buyer requirements.
Product Type:
After-sales service intensity concentrates around cell degradation monitoring and encapsulant integrity verification, with warranty claim rates varying significantly by crystalline structure and manufacturing chemistry.
- Monocrystalline:Single-crystal silicon construction delivers the highest watt-per-square-meter density available to space-constrained vessels. Demand concentrates in Mediterranean superyacht refit yards where deck area commands premium valuations and auxiliary load requirements are substantial. IEC 61215 marine adaptation compliance is standard among tier-one suppliers serving this segment.
- Thin-Film:Cadmium telluride or CIGS deposition on flexible substrates enables sub-3mm profiles that conform to curved deck geometries without structural reinforcement. Racing fleets in Nordic waters prioritize these modules where gram-counting directly impacts handicap ratings and competitive outcomes. ECHA REACH substance restrictions are accelerating reformulation investments by manufacturers seeking continued EU market access.
- Polycrystalline:Multi-crystal silicon cells offer cost-efficient conversion for auxiliary loads on commercial workboats with generous mounting surfaces.
- Bifacial:Dual-sided light capture architectures exploit reflected irradiance from water surfaces, gaining traction on catamarans and trimarans with elevated mounting clearance.
Monocrystalline holds the largest share; momentum sits with thin-film as curved-deck compatibility becomes a purchase criterion.
End User:
Commercial procurement cycles extend 18-24 months with classification society approvals, while recreational buyers compress decision timelines through direct-to-consumer retail channels and owner-installation pathways.
- Recreational Boats:Leisure craft owners represent the fastest-expanding buyer segment as lithium-ion battery compatibility improves and integrated energy management systems reduce technical barriers to retrofit. Coastal Mediterranean marinas and Nordic cruising grounds concentrate visible demand where shore-power alternatives command premium economics. ABYC electrical standards compliance is increasingly bundled with retail panel offerings.
- Commercial Vessels:Fleet operators and charter companies contract for guaranteed auxiliary power availability through energy-as-a-service models rather than capitalizing panel assets. Procurement concentrates among finance-capable integrators capable of underwriting performance guarantees across multi-season operating contracts in Floridian and Mediterranean corridors.
- Fishing Boats:Diesel-solar hybrid auxiliary systems address refrigeration and electronics loads on extended voyages, with Norwegian and Swedish waters showing favorable economics.
- Houseboats:Liveaboard cruisers in high-electricity-cost jurisdictions prioritize autonomy-maximizing installations with expanded battery banks and maximum panel surface utilization.
Recreational boats dominate volume; commercial vessels are climbing the fastest as leasing structures penetrate fleet procurement.
Installation Type:
Installer certification requirements and yard labor availability create geographic pockets of competitive advantage for specialized mounting hardware and integration services.
- Flexible:Conformable substrates with marine-grade ETFE encapsulation adhere directly to curved deck surfaces without structural modification. Superyacht integrators and racing teams in European waters pilot these configurations where complex hull shapes previously excluded photovoltaic deployment. Custom geometries from Italian and Spanish fabricators anchor regional supply chains.
- Fixed:Rigid aluminum-framed modules on elevated railings or hardtop structures deliver maximum durability for permanent installations on displacement hulls with predictable motion profiles.
- On-Board:Semi-permanent mounting systems allow seasonal deployment with shore-side storage during winter layup periods, common in Baltic and North Sea operating environments.
- Portable:Briefcase-style folding arrays target transient power needs on small craft without dedicated electrical infrastructure, with retail distribution through Florida and California marine chandleries.
Fixed installation retains the largest installed base; flexible configurations are gaining share fastest as hull design complexity increases.
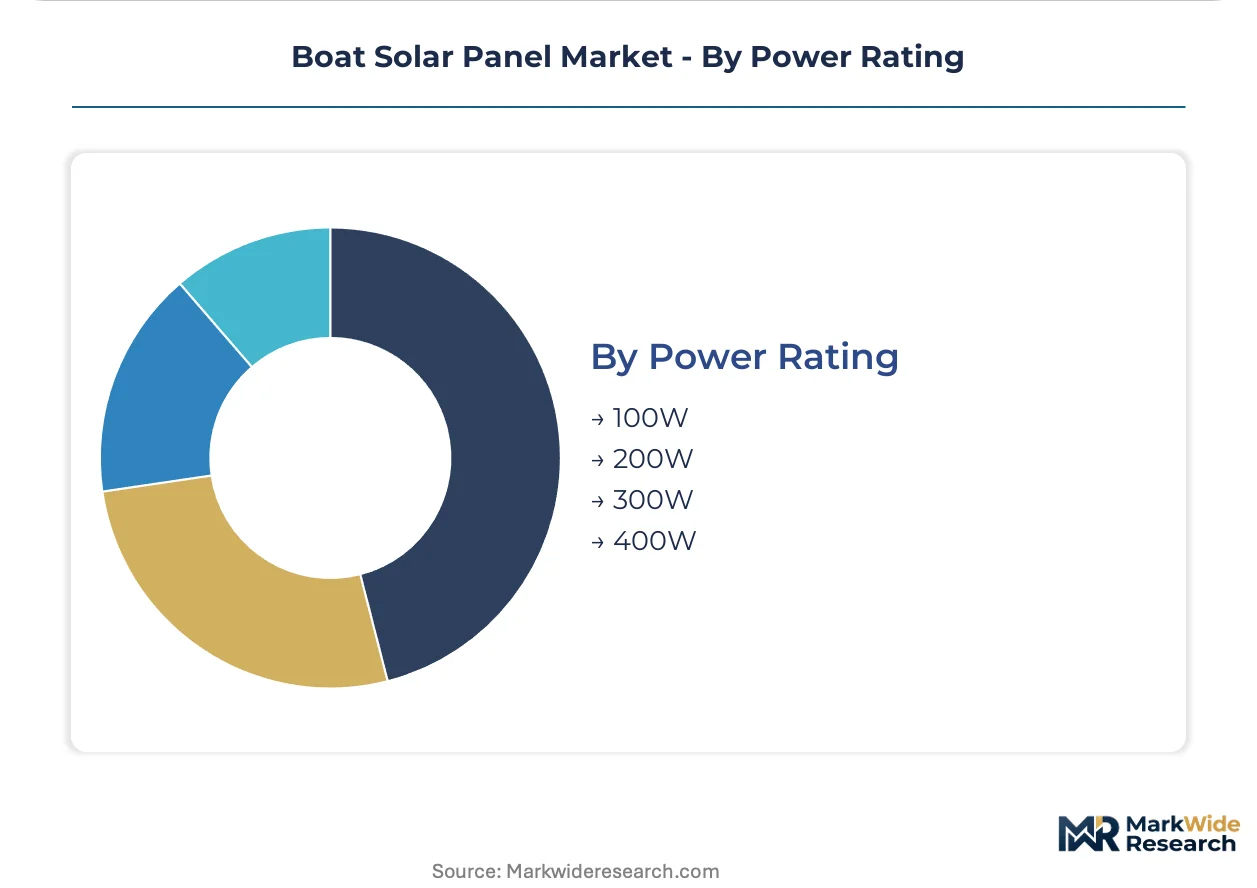
Power Rating:
Module wattage selection correlates directly with vessel displacement and auxiliary load profiles, with higher ratings requiring proportionally more sophisticated charge control and battery integration.
- 100W:Compact modules serve tender charging, navigation electronics, and bilge pump maintenance on vessels under 30 feet. Weekend cruisers in coastal US waters favor this entry point for minimal retrofit complexity.
- 200W:Mid-range output addresses refrigeration and lighting loads on coastal cruisers with moderate electrical demands.
- 300W:Higher-capacity installations support inverter-based AC loads and extended anchoring autonomy for liveaboard configurations.
- 400W:Maximum standard ratings target catamaran deck arrays and commercial vessel auxiliary electrification with substantial surface availability.
200W ratings hold the largest share; 400W modules show the steepest expansion trajectory as lithium-ion storage capacity enables meaningful load displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal maritime decarbonization pathways are mandating shore-power alternatives across European waters, while extended daylight hours in Nordic cruising grounds and high electricity costs in Mediterranean marinas are accelerating auxiliary power electrification investments.
United States
Recreational boat owners in Florida and California represent concentrated demand for owner-installed solar retrofits as lithium-ion battery compatibility improves. EPA vessel emissions guidelines indirectly stimulate auxiliary power electrification that expands addressable solar load. Marine chandleries in Fort Lauderdale and San Diego anchor retail distribution networks for portable and fixed-installation panel systems.
Germany
Norwegian and Swedish waters show favorable economics for solar-diesel hybrid auxiliary systems on liveaboard cruisers, with German yards serving as integration hubs for Nordic-bound vessels. ECHA REACH substance restrictions on hazardous encapsulants are tightening supplier qualification requirements for panels sold in European waters. Hamburg and Bremen concentrate marine electrical certification capacity for ABYC standards compliance.
Italy
Mediterranean superyacht refit yards in Genoa and Viareggio command premium valuations for deck area, driving demand for maximum watt-per-square-meter density. EU Green Deal binding decarbonization targets for auxiliary power electrification mandate shore-power alternatives on inland and coastal vessels. Italian fabricators anchor regional supply chains for custom flexible panel geometries conforming to curved deck surfaces.
China
East Asian cell manufacturing concentration in mainland China fabrication facilities exposes buyers to logistics disruption and tariff exposure on marine-grade cells. The country's national industrial standards regulator enforces GB standards for photovoltaic module safety. Manufacturing clusters in Jiangsu and Zhejiang provinces supply crystalline silicon cells for export markets.
Australia
Extended coastal cruising routes and high marina electricity costs in Queensland and New South Wales create favorable economics for autonomy-maximizing installations. The country's national electrical safety regulator mandates compliance with AS/NZS standards for marine photovoltaic deployment. Sydney and Brisbane service clusters concentrate qualified marine electricians capable of high-voltage array integration.
Boat Solar Panel Market Competitive Landscape
On the supply side, the industry is structured around three tiers differentiated by balance-sheet depth and certification breadth. High-efficiency cell architects command premium positioning in integrated marine energy systems, while modular kit specialists compete aggressively on installer certification barriers for smaller yards. Custom flexible fabricators anchor the racing and superyacht segment through conformable geometries. Dominant competitive moves include strategic partnerships with lithium-ion battery manufacturers and geographic expansion into Nordic and Mediterranean service corridors.
Among established marine photovoltaic specialists, SunPower and Solbian occupy positions at the premium-performance and custom-flexibility vectors respectively, while Renogy exemplifies the modular-scalability archetype targeting recreational owner-installers. These three companies represent distinct strategic postures: SunPower leverages high-efficiency cell architecture, Solbian delivers custom flexible panel geometries for curved-deck compatibility, and Renogy reduces installer certification barriers through scalable kit configurations. Their collective positioning illustrates how technical specialization and distribution model selection determine competitive boundaries in this market.
| Leading Market Players |
|---|
| SunPower |
| Renogy |
| Solbian |
| HQST |
| Newpowa |
| ECO-Worthy |
| WindyNation |
| Photonic Universe |
| ACOPOWER |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Jiangsu and Zhejiang crystalline silicon fabrication is compressing module margins and forcing tier-two suppliers toward aggressive price pass-through negotiations with Mediterranean and Floridian yard installers, while premium-positioned firms with IEC 61215 marine certification defend pricing power through bundled energy management integration.
Pricing Analysis
Certification level (IEC 61215 marine/ABYC electrical standards) creates the primary spread between premium and standard tiers, with tier-one suppliers commanding project-based pricing for integrated lithium-ion compatible systems while commodity crystalline panels trade on per-watt transactional terms. Price differentiation hinges on encapsulant chemistry grade and after-sales warranty bundling. Cost compression in standard-tier modules is intensifying because silver metallization input volatility feeds through to bill-of-materials pressure. Recreational owner-installers exhibit highest price sensitivity, whereas superyacht integrators prioritize watt-per-square-meter density over unit economics.
Supply Chain Analysis
Contract manufacturing concentration sits with mainland China-based cell fabricators and Taiwanese backsheet specialists, with Italian and Spanish flexible panel fabricators anchoring custom geometries for European racing applications. Geographic supply concentration centers on China, Taiwan, and Germany for crystalline cells, marine-grade aluminum framing, and polymer encapsulant formulation respectively. Raw material dependencies draw from high-purity silicon feedstock, silver paste for metallization, and ETFE fluoropolymer films. Tariff exposure on East Asian cell imports constitutes the primary structural risk. Distribution runs through marine chandleries in Fort Lauderdale and San Diego, superyacht refit yards in Genoa and Viareggio, and direct-to-consumer e-commerce channels for modular kit suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against shore-power infrastructure and hydrogen auxiliary systems as competing decarbonization pathways for vessel electrification, with incumbents needing to articulate solar's payback advantage against alternative zero-emission architectures.
For Market Incumbents: Insulate certification moats by accelerating IEC 61215 marine adaptation investments ahead of ECHA REACH substance restriction enforcement, while deepening backward integration into lithium-ion battery partnerships to capture integrated energy system margins. Shore-power infrastructure buildout in Mediterranean marinas and Nordic cruising grounds threatens standalone panel demand; counter by underwriting performance-guaranteed leasing structures that reduce owner capital barriers.
For New Entrants and Emerging Players: Australian east coast marinas and Queensland liveaboard corridors offer geographic underpenetration relative to installed vessel density and high electricity costs, with qualified marine electrician scarcity creating service-model opportunities. Target fishing boat diesel-solar hybrid retrofits in Norwegian and Swedish waters where favorable daylight economics meet unmet auxiliary electrification demand. Deploy AI-enabled energy management software as a hardware-agnostic entry wedge to bypass incumbent certification timelines.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across flexible panel manufacturing as custom geometry tooling and EU-based polymer testing infrastructure become mandatory for continued market access. Long-term viability favors integrators with balance-sheet depth to underwrite multi-vessel fleet leasing programs. Acquisition targets should demonstrate in-house encapsulant chemistry capabilities and existing ABYC certification relationships. Watch for inflection in marina energy-as-a-service contract signings as indicator of procurement model shift durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Marine Certification Acceleration | Early IEC 61215 marine adaptation completion secures yard installer preference before REACH enforcement tightens. |
| Lithium-Ion Partnership Structuring | Integrated energy system bundling with CATL or BYD cell supply locks in auxiliary electrification specification wins. |
| Flexible Panel Geometry Expansion | Custom conformable module capabilities capture superyacht and racing segment pricing premiums in European waters. |
| Leasing Program Capitalization | Balance-sheet-backed retrofit underwriting narrows competitive field to finance-capable integrators in Mediterranean corridors. |
| AI Energy Management Integration | Machine learning load prediction software differentiates hardware offerings and extends lithium-ion replacement intervals. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with superyacht refit yard managers, marine electrical contractors in Mediterranean and Nordic service clusters, lithium-ion battery system integrators, and recreational boat owner associations. Secondary validation drew from IEC certification registries, ECHA REACH substance restriction filings, ABYC standards documentation, and customs trade data for photovoltaic module imports. Bottom-up vessel fleet segmentation was triangulated against top-down marina electricity cost and daylight hour economics across the analysis window.
Calibration against historical installation volumes and lithium-ion battery deployment curves anchored the projection framework, with segmentation modeling across product type (monocrystalline/thin-film/polycrystalline/bifacial), end user category (recreational/commercial/fishing/houseboat), installation type (flexible/fixed/on-board/portable), and power rating tier. CAGRs were derived from fitted adoption curves incorporating payback period sensitivity to marina electricity tariffs and battery storage cost trajectories. Forecast inputs included EU Green Deal maritime pathway enforcement timelines and ECHA encapsulant reformulation compliance schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hydrogen auxiliary system developers or shore-power infrastructure investors would shift outcomes beyond modeled ranges. Quarterly review of marina energy-as-a-service contract signings, IEC 61215 marine adaptation approval timelines, and silver paste commodity price movements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Philippines Solar Energy Market
Solar Power Systems
Europe Concentrated Solar Power Market
Solar Power Systems
Plastic Solar Cell Market
Solar Power Systems
Chile Solar Energy Market
Solar Power Systems
Solar Photovoltaic Glass Market
Solar Power Systems
Global Photovoltaic Glass Market
Solar Power Systems
Building Integrated Photovoltaic (BIPV) Market
Solar Power Systems
Solar Phone Chargers Market
Solar Power Systems
Europe Solar Concentrator Market
Solar Power Systems
Solar Photovoltaic (PV) Panel Market
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
Off-Grid Solar Power Market
Solar Power Systems
North America Rooftop Solar Market
Solar Power Systems
3D Printed Solar Energy Trees Market
Solar Power Systems
Commercial Solar Panel Market
Solar Power Systems
High Concentration Photovoltaics Market