
 LAMEA Ocean Power Market | 2026-2036
LAMEA Ocean Power Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Ocean Power Market Analytics
A shortage of marine engineers with subsea electrical expertise is unwinding project timelines across the LAMEA region. Carnegie Clean Energy Limited leverages its CETO wave technology to anchor early-stage deployments in Australian-linked markets. Nova Innovation Ltd. competes through tidal stream specialization, while Eco Wave Power Global AB differentiates with nearshore concrete floaters that reduce installation complexity.
Ocean power captures kinetic and thermal energy from seawater through wave-activated buoys, tidal turbines, or temperature-differential engines, typically generating electricity at 10-500 kW per unit for grid or off-grid supply. Tidal energy leads technology type adoption where bathymetry permits predictable currents, while wave energy occupies the fastest-growth trajectory as floater designs mature. Offshore installations dominate margin pools due to higher capacity factors, though nearshore systems attract capital from markets with limited deep-water port access.
Brazil's ANEEL, South Africa's Department of Mineral Resources and Energy, and the UAE's MOHAP shape permitting pathways and environmental standards for ocean energy projects. These bodies enforce marine spatial planning rules that determine site eligibility and grid interconnection timelines. Stakeholders must monitor how floating system certifications evolve under emerging IEC standards before committing capital to multi-unit arrays.
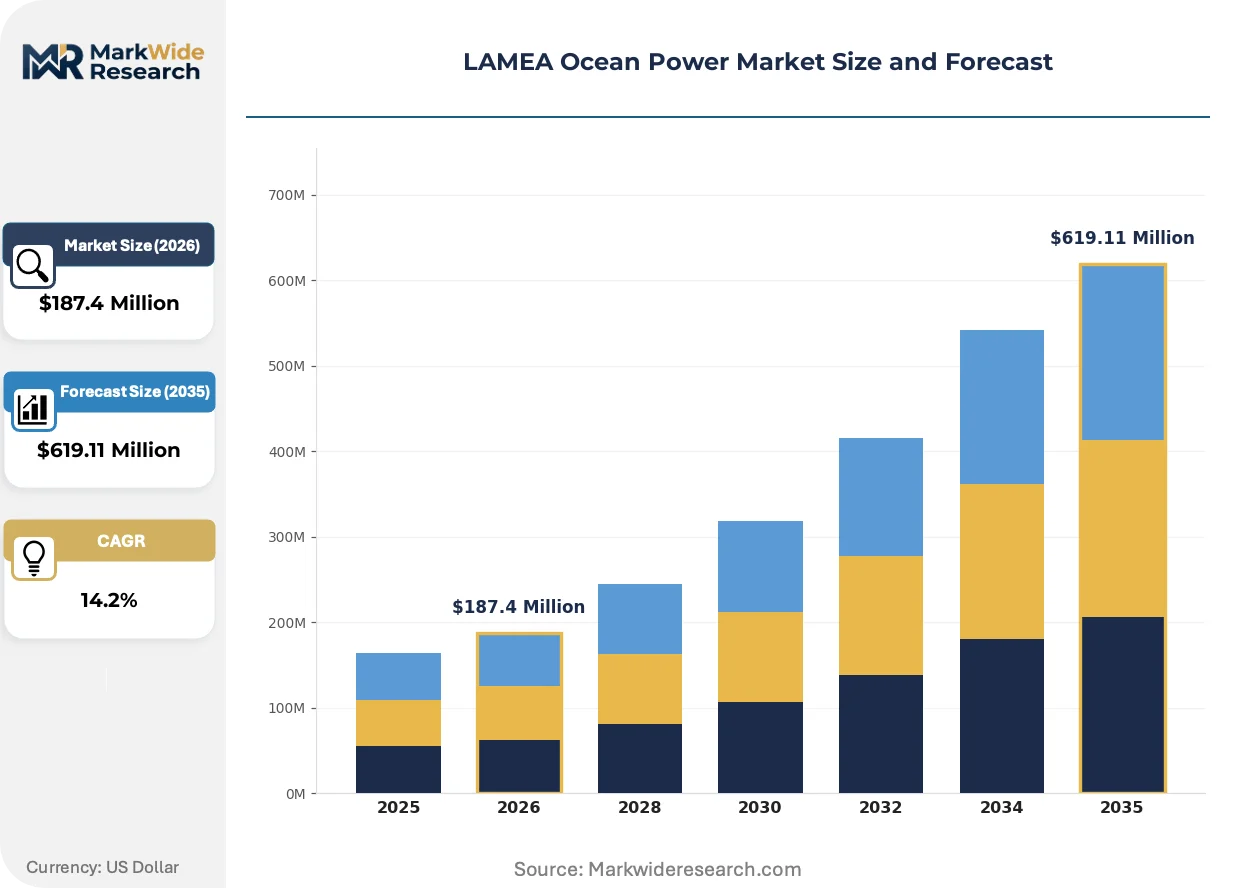
Market Dynamics
The LAMEA Ocean Power Market hinges on the tension between proven tidal stream reliability and emerging wave energy scalability, with regulatory auction mechanisms in Brazil and South Africa determining which technology class secures grid interconnection priority.
Growth Catalysts
- Brazil's ANEEL renewable auctions:These competitive procurement rounds award long-term power purchase agreements to ocean energy developers, de-risking capital commitments for multi-unit wave arrays.
- Port infrastructure concentration:Existing deep-water facilities in Rio de Janeiro and Cape Town reduce marine logistics costs for heavy turbine transport and floating platform assembly.
- Tidal predictability:Bathymetric channels in the Mozambique Strait and Patagonian shelf offer current velocity profiles that utilities can model with 95% accuracy, improving dispatch forecasting.
Market Restraints
- Subsea cable copper pricing:Inter-array cabling represents 18-25% of project capex, and LME copper volatility since 2022 has forced developers to hedge or absorb margin compression.
- Specialized vessel scarcity:The LAMEA region hosts fewer than twelve jack-up barges rated for 50-meter water depth, creating installation bottlenecks during weather windows.
- Environmental impact assessment duration:South Africa's Department of Mineral Resources and Energy mandates 24-36 month marine ecology studies, extending project development timelines beyond investor patience thresholds.
Strategic Opportunities
- Hybrid offshore platforms:Co-location of wave energy converters with existing oil and gas infrastructure in the Campos Basin leverages decommissioned platform foundations and reduces permitting complexity.
- Desalination integration:Off-grid wave-powered reverse osmosis units address water scarcity in Chile's Atacama coastal zones, opening non-utility revenue streams.
- UAE's MOHAP marine spatial planning:Early designation of renewable energy zones in Gulf waters reduces site conflict with shipping lanes and creates permitting fast-tracks for demonstration projects.
Industry Challenges
- Marine electrical engineer shortage:Universities in Brazil and South Africa graduate fewer than forty subsea power systems specialists annually, forcing developers to import talent at 3x local salary multiples.
- IEC 62600-10 certification gaps:Floating platform mooring design standards remain under committee review, delaying insurer sign-off on commercial-scale deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Ocean Power Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Wave Energy, Tidal Energy, Ocean Thermal Energy Conversion, Salinity Gradient Application: Power Generation, Desalination, Coastal Protection, Aquaculture End User: Utility Providers, Government Agencies, Research Institutions, Commercial Establishments Installation Type: Offshore, Nearshore, Onshore, Floating Systems |
| Companies Covered | Ocean Power Technologies, Inc., Carnegie Clean Energy Limited, Minesto AB, Nova Innovation Ltd., SIMEC Atlantis Energy, Orbital Marine Power, Eco Wave Power Global AB, Aquagen Technologies, CorPower Ocean, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Ocean Power Market Evolving Landscape
Technology convergence between offshore wind installation vessels and ocean power deployment methods is compressing learning curves. Regulatory frameworks are hardening around environmental co-benefits. Buyer procurement criteria are elevating grid stability contributions over pure cost metrics.
Concrete floater architectures are displacing steel-hulled buoy designs across nearshore Brazilian projects. These composite structures resist salt-water corrosion for 25-year design lives while enabling local precast manufacturing in Fortaleza and Salvador. Petrobras-linked engineering contractors are adopting the technology for rapid deployment schedules, displacing European-imported steel platforms that require 14-month fabrication cycles.
South Africa's Department of Mineral Resources and Energy revised its Integrated Resource Plan to mandate ocean energy feasibility assessments for all new coastal grid infrastructure. This policy embeds marine power into transmission planning rather than treating it as peripheral generation. Developers must now submit grid integration studies alongside generation licenses, accelerating interconnection queue positioning for tidal stream projects in the Agulhas Current corridor.
Utility procurement evaluation criteria now weight capacity factor predictability above levelized cost thresholds. Eskom Holdings and Brazil's Eletrobras rank tidal resources higher than wave in near-term tenders due to dispatch certainty. This behavioral shift favors technology providers with current velocity measurement databases spanning five-plus years, disadvantaging pre-commercial wave concepts without operational track records.
LAMEA Ocean Power Market Segmentation
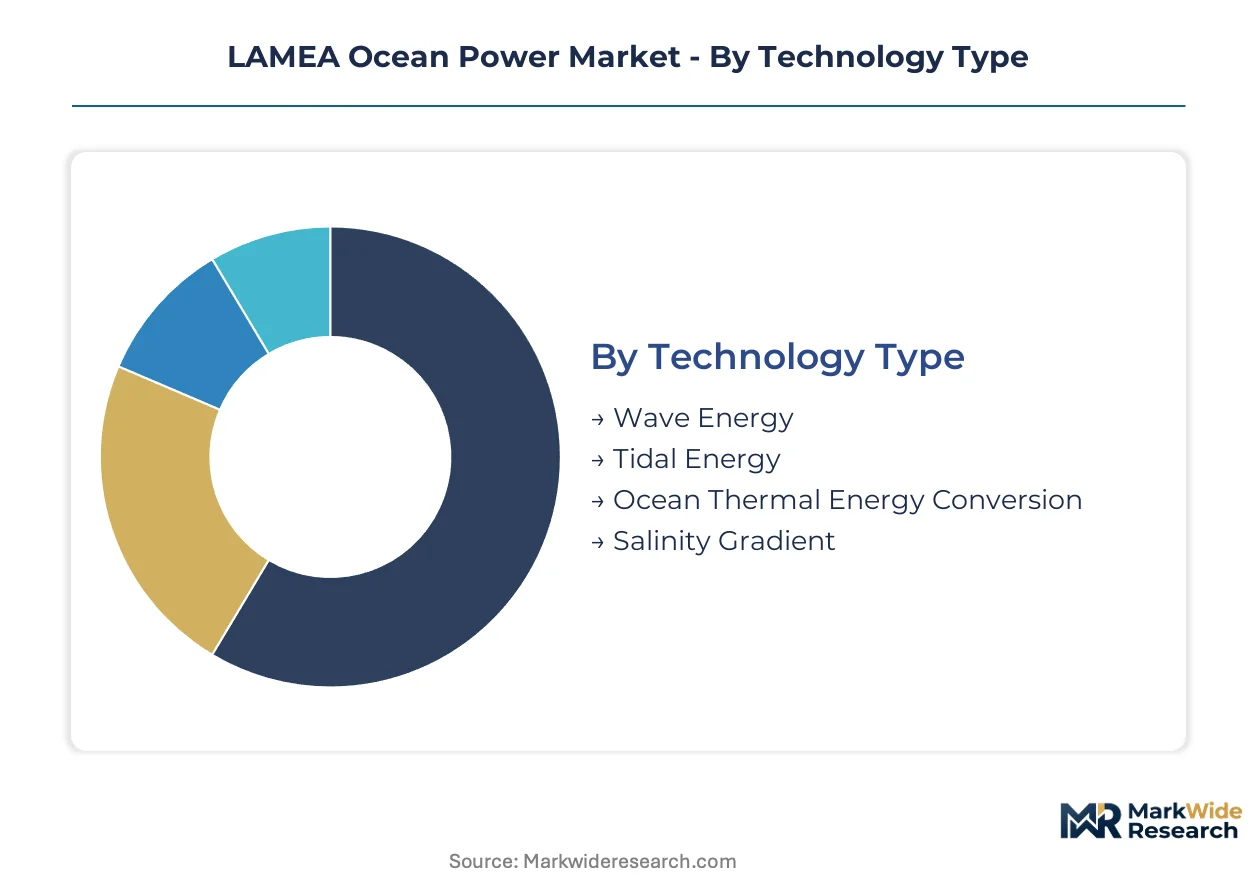
Technology choice in LAMEA ocean power dictates capital intensity, permitting pathways, and grid interconnection priority. Segment boundaries blur where hybrid platforms combine generation with desalination or coastal defense functions.
Technology Type:
Margin pools concentrate in tidal stream deployments where predictability commands premium power purchase agreement terms from Brazilian and South African utilities.
- Wave Energy:Surface and subsurface floater architectures capture kinetic energy from oscillating water columns. Demand clusters in Brazil's Campos Basin where Petrobras-linked contractors seek rapid-deployment concrete platforms for decommissioned oil infrastructure repurposing. ANEEL auction mechanisms favor wave arrays with 25-year design lives and local manufacturing content.
- Tidal Energy:Horizontal-axis turbines exploit bathymetric channel velocities with 95% dispatch forecasting accuracy. South Africa's Agulhas Current corridor anchors project pipelines where Eskom Holdings prioritizes capacity factor certainty over levelized cost in procurement scoring.
- Ocean Thermal Energy Conversion:Rankine cycle engines exploit 20°C+ surface-deep temperature differentials. Brazil's northeastern shelf offers viable temperature gradients for base-load generation.
- Salinity Gradient:Pressure-retarded osmosis and reverse electrodialysis systems remain pre-commercial in LAMEA waters with limited demonstration funding.
Tidal Energy holds installed capacity. Wave Energy is rotating up the share rankings.
Application:
Volume concentrates in grid-connected power generation, though non-electricity applications are climbing the fastest as water scarcity intensifies procurement diversification.
- Power Generation:Grid-connected electricity supply dominates capital deployment, with utility-scale arrays feeding into South Africa's coastal transmission backbone and Brazil's northeastern grid nodes. Eskom and Eletrobras procurement criteria weight predictability metrics heavily in tender evaluations.
- Desalination:Wave-powered reverse osmosis units address water scarcity in Chile's Atacama coastal zones and UAE's offshore islands. MOHAP marine spatial planning designates renewable energy zones that reduce permitting conflict for integrated water-power platforms.
- Coastal Protection:Submerged breakwater-integrated converters attenuate wave energy while generating electricity. Fortaleza and Salvador municipalities evaluate dual-function installations for erosion control.
- Aquaculture:Off-grid power for offshore fish farms attracts pilot interest in Patagonian shelf waters where grid extension costs prove prohibitive.
Power Generation anchors revenue. Desalination is expanding most quickly.
End User:
Customer type determines project scale, with utility providers commanding multi-unit arrays while government agencies fund demonstration infrastructure.
- Utility Providers:Eskom Holdings, Eletrobras, and Chile's transmission operators procure capacity through competitive auctions. Long-term power purchase agreements de-risk capital commitments for tidal stream projects with operational track records exceeding five years.
- Government Agencies:Brazil's ANEEL, South Africa's Department of Mineral Resources and Energy, and UAE's MOHAP directly fund feasibility studies and demonstration arrays. Public capital fills gaps where commercial debt terms prove prohibitive for pre-commercial technology classes.
- Research Institutions:Universities in São Paulo and Cape Town host test berths for device certification under emerging IEC 62600 standards.
- Commercial Establishments:Mining operations and desalination plant operators seek captive generation to hedge grid reliability risks in remote coastal locations.
Utility Providers dominate procurement volume. Government Agencies are climbing the share rankings.
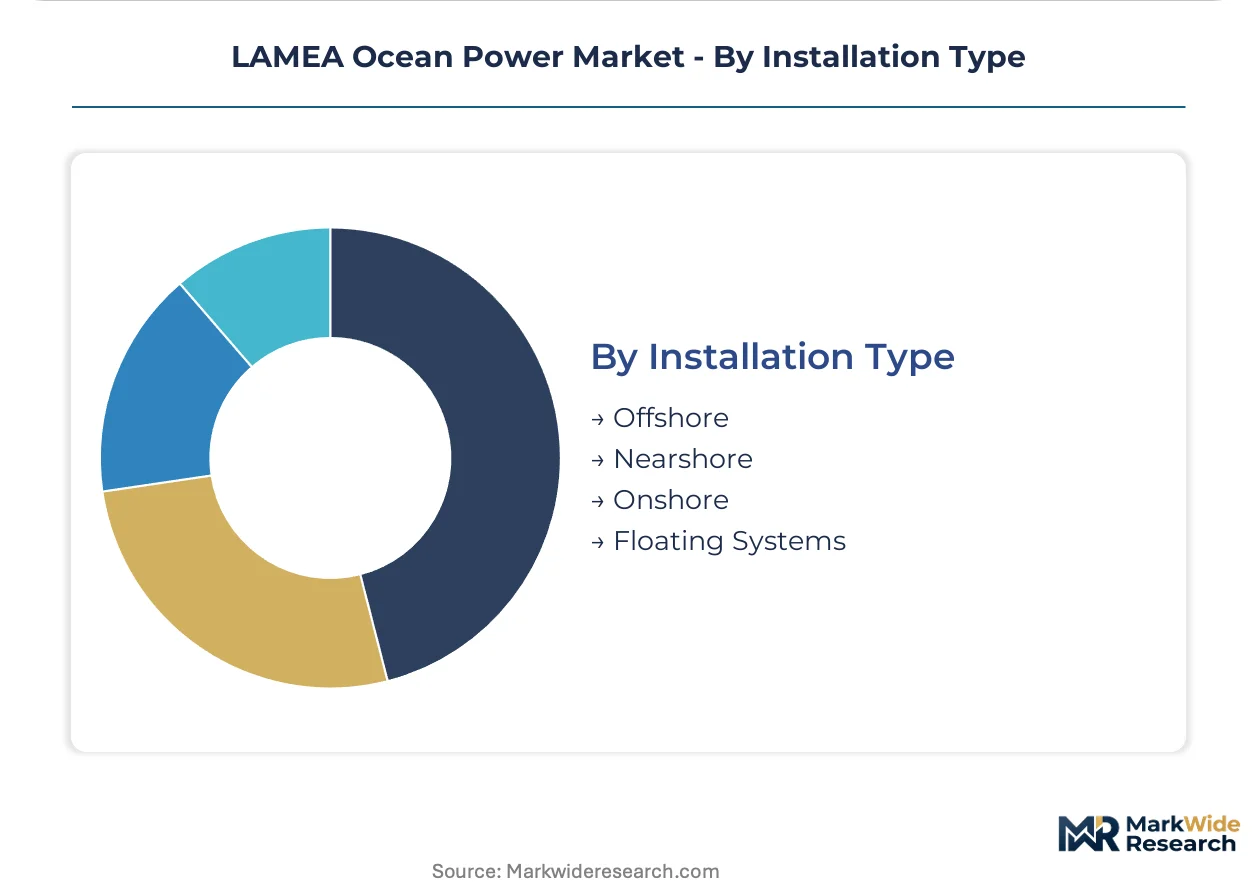
Installation Type:
Cost tier stratification separates capital-intensive offshore foundations from nearshore systems accessible to markets with limited deep-water port infrastructure.
- Offshore:Deep-water deployments in 50-meter-plus depths capture higher capacity factors through stronger current velocities and larger wave heights. Installation requires scarce jack-up barges, with fewer than twelve rated vessels available across LAMEA waters.
- Nearshore:Concrete floater architectures in 10-30 meter depths enable local precast manufacturing in Fortaleza and Salvador. Petrobras contractors favor these platforms for 18-month deployment schedules versus 14-month European steel fabrication cycles.
- Onshore:Limited to tidal barrage and lagoon configurations with minimal LAMEA project pipelines due to coastal ecology sensitivities.
- Floating Systems:Mooring-flexible platforms accommodate water depth variability and storm loadings. IEC 62600-10 certification gaps delay insurer sign-off on commercial-scale arrays.
Offshore installations hold installed capacity. Nearshore systems are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands pricing power in tidal stream procurement through ANEEL auction mechanisms, while South African wave energy developers absorb 20-30% cost premiums due to specialized vessel scarcity and extended environmental assessment timelines.
Brazil
ANEEL renewable auctions award long-term power purchase agreements that de-risk capital for multi-unit wave arrays. The northeastern shelf offers viable ocean thermal gradients for base-load generation pilots. Rio de Janeiro and Fortaleza anchor manufacturing clusters where Petrobras contractors adopt concrete floater platforms for 18-month deployment cycles.
South Africa
Eskom Holdings prioritizes capacity factor certainty over levelized cost in tidal procurement scoring. The Department of Mineral Resources and Energy mandates 24-36 month marine ecology studies that extend development timelines. The Agulhas Current corridor concentrates project pipelines where bathymetric channels deliver 95% dispatch forecasting accuracy.
United Arab Emirates
MOHAP marine spatial planning designates renewable energy zones that reduce permitting conflict with shipping lanes. Early zone designation creates fast-tracks for demonstration projects in Gulf waters. Dubai and Abu Dhabi host feasibility assessments for integrated water-power platforms addressing offshore island desalination needs.
Chile
Wave-powered reverse osmosis units target water scarcity in Atacama coastal zones where grid extension costs prove prohibitive. The central government evaluates non-utility revenue streams for ocean energy developers. Antofagasta and Coquimbo municipalities pilot coastal protection installations that attenuate wave energy while generating electricity.
LAMEA Ocean Power Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with tidal stream specialists commanding premium procurement terms while wave energy fabricators compete on local manufacturing content. The market structure fragments across pre-commercial demonstration tiers and early commercial deployment cohorts. Three archetypes dominate: Australian-linked wave technology licensors, European tidal stream specialists, and nearshore concrete platform integrators. Competitive moves concentrate on strategic partnerships with oil and gas decommissioning contractors and technology licensing to regional engineering firms.
Among the named cohort, Carnegie Clean Energy Limited and Eco Wave Power Global AB represent contrasting wave energy archetypes, while Nova Innovation Ltd. anchors the tidal stream specialization tier. These entities occupy positions across the technology maturity spectrum, with some exemplifying nearshore deployment models and others occupying offshore system development tracks. Their geographic footprints and corporate structures reflect the regional engineering partnerships and local content requirements that shape competitive positioning in Brazilian and South African procurement rounds.
| Leading Market Players |
|---|
| Ocean Power Technologies, Inc. |
| Carnegie Clean Energy Limited |
| Minesto AB |
| Nova Innovation Ltd. |
| SIMEC Atlantis Energy |
| Orbital Marine Power |
| Eco Wave Power Global AB |
| Aquagen Technologies |
| CorPower Ocean |
| Others |
Value Network & Pricing Analysis
ANEEL certification requirements for grid interconnection gate both supplier qualification and price differentiation across Brazilian procurement rounds. Developers holding IEC 62600-10 mooring certifications command premium power purchase agreement terms while uncertified competitors absorb margin compression or exit tender processes entirely.
Pricing Analysis
Brazilian wave arrays trade at 15-20% discounts to South African tidal projects due to local concrete floater manufacturing and shorter environmental assessment timelines. Pricing stratifies across premium, standard, and economy tiers based on capacity factor predictability and local content ratios. Cost compression in nearshore systems is intensifying because Petrobras contractors are internalizing platform fabrication. Utility providers exhibit lowest price sensitivity where dispatch certainty exceeds levelized cost thresholds, while government-funded demonstration projects face strict budget caps.
Supply Chain Analysis
Jack-up barge scarcity across the Mozambique Strait and Cape Town anchorage creates installation bottlenecks that cascade through project scheduling. Component sourcing draws from China for power electronics, Norway for subsea cabling, and Brazil for concrete floater precasting. Single-source vulnerability concentrates in specialized vessel chartering where fewer than twelve LAMEA-rated units serve competing offshore wind and ocean power demand. Distribution runs through Petrobras-linked EPC contractors in Brazil and Eskom-appointed project developers in South Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
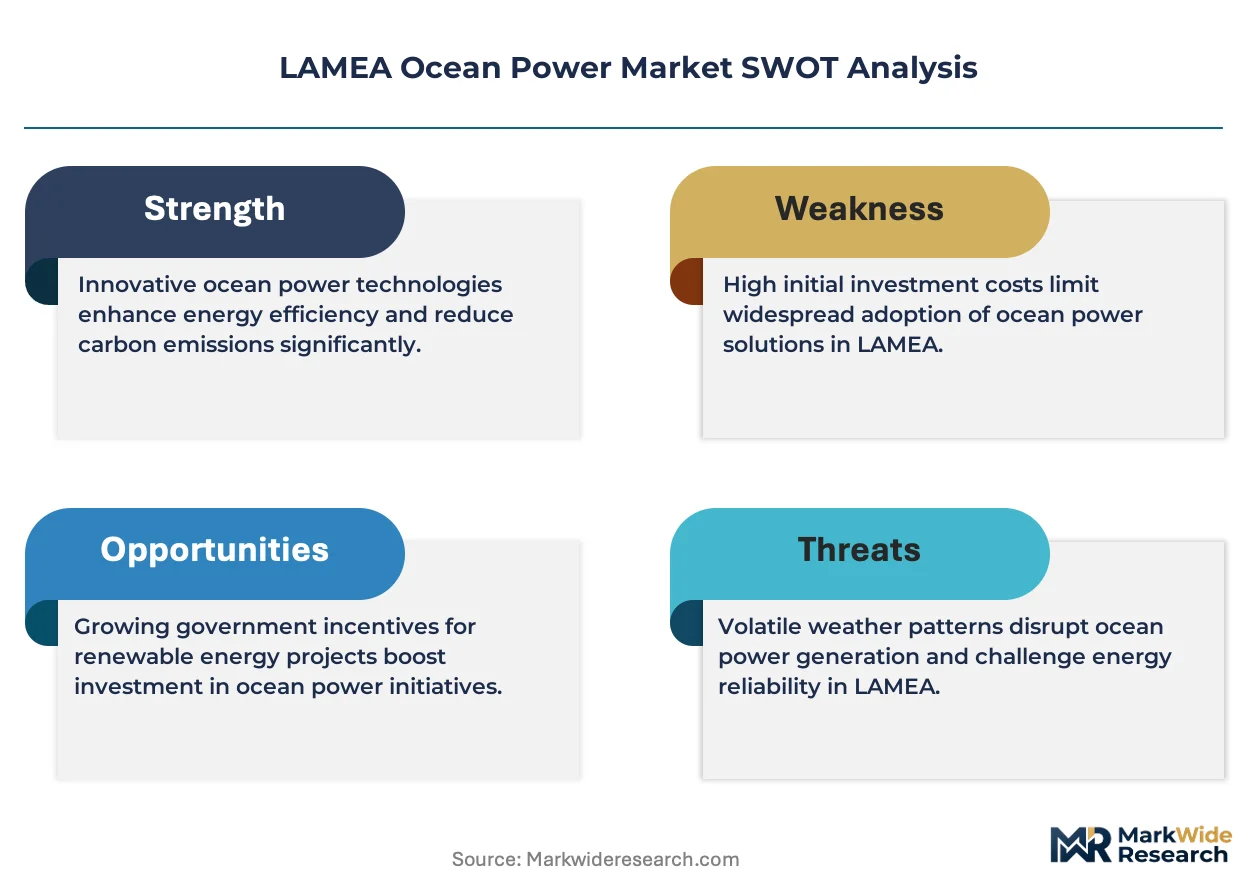
Fragmentation across technology maturity tiers creates niche entry points as utility procurement criteria diverge between predictability-prioritizing incumbents and cost-optimizing challengers.
For Market Incumbents: Compound certification advantages by accelerating IEC 62600-10 mooring standard compliance before committee finalization locks in design specifications. Lock in long-term vessel charter agreements with Cape Town and Rio de Janeiro marine operators to preempt jack-up barge scarcity. Vertical integration into concrete floater manufacturing in Fortaleza insulates margin position from European steel platform import delays. For New Entrants and Emerging Players: Post-installation O&M service gaps in South Africa's Agulhas Current corridor offer white-space entry where incumbent tidal operators under-serve remote monitoring and predictive maintenance needs. Target Chile's Atacama desalination integration segment where wave-powered reverse osmosis lacks established technology providers. Pursue licensing partnerships with Petrobras decommissioning contractors for rapid platform deployment credibility. For Investors and Strategic Acquirers: Secondary-cycle assets sit with Australian-linked wave technology licensors seeking regional exit liquidity as Brazilian local content requirements harden. Five-to-ten year viability hinges on portfolio companies securing operational track records exceeding ANEEL's five-year procurement threshold. Monitor IEC 62600-10 committee publication timelines as inflection indicator for insurer sign-off and commercial-scale array financing availability.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing to Regional EPCs | Accelerates deployment timelines by embedding CETO and concrete floater IP with Petrobras contractors. |
| Long-term Vessel Charter Agreements | Secures scarce jack-up barge capacity across Rio de Janeiro and Cape Town marine bases. |
| Hybrid Platform Co-location | Leverages decommissioned Campos Basin oil infrastructure to reduce permitting complexity for wave arrays. |
| Desalination Integration Pilots | Opens non-utility revenue streams in Chile's Atacama zones where grid extension costs prove prohibitive. |
| IEC 62600-10 Certification Investment | Enables insurer sign-off and premium PPA terms before standards committee finalization. |
Research Methodology
A standing panel of utility planning officers, IPP project developers, EPC contractors, and grid operators provided ongoing calibration against secondary validation from IEA ocean energy tracking reports, ANEEL auction disclosure filings, FERC-equivalent regulatory databases, and customs records for subsea cable imports. Bottom-up project pipeline aggregation triangulated against top-down macroeconomic scenario modeling.
Consistency checks validated volume and value outputs against IEA technology cost benchmarks and regional EPC contractor margin disclosures across the projection horizon. Segmentation dimensions spanned technology type, installation depth tier, and regulatory framework cluster. CAGRs derived from unit economics modeling of concrete floater versus steel platform capex differentials and capacity factor distributions by bathymetric zone.
Underlying assumptions cover copper price stability, vessel availability, and environmental assessment duration, with deviation risk concentrated in IEC standard publication delays and marine spatial planning revisions. Practitioners should keep alternative scenarios live as ANEEL auction frequency and South African IRP implementation pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Europe Ocean Power Market
Renewable Energy
Europe Solar Tracker Market
Renewable Energy
Rectenna Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
Turkey Renewable Energy Market
Renewable Energy
North Europe Renewable Energy Market
Renewable Energy
Ocean Energy Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
South Africa Rooftop Solar Market
Renewable Energy
South Korea Renewable Energy Market
Renewable Energy
Green Power Market
Renewable Energy
Southern Africa Renewable Energy Market
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
Switzerland Renewable Energy Market
Renewable Energy
Japan Renewable Energy Market