
 China Wind Energy Market | 2026-2036
China Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
China Wind Energy Market Analysis
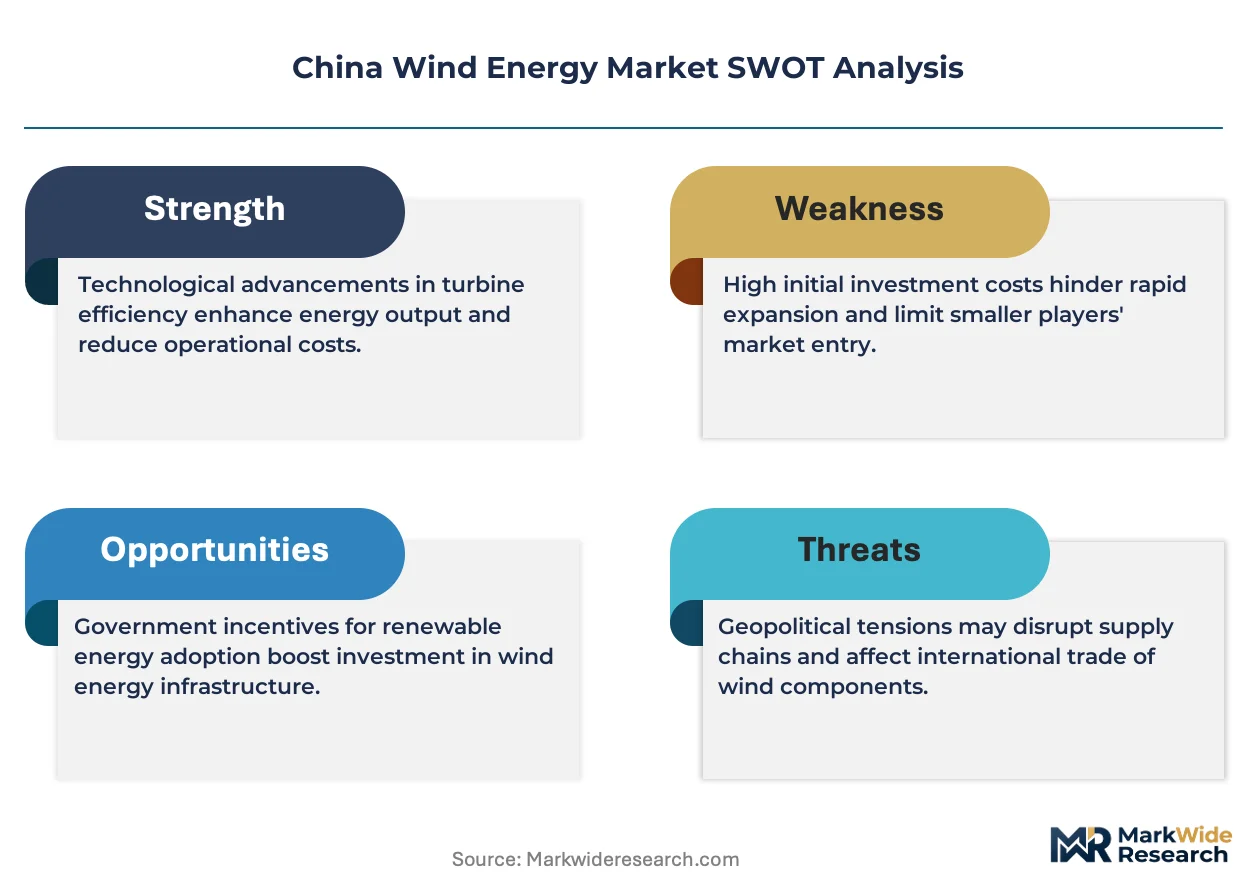
Certified wind turbine technician shortages across northern and eastern China is redrawing manufacturing location strategies for domestic OEMs. Goldwind leverages its Xinjiang training academies to sustain blade assembly throughput at its Hami and Dafeng plants. Envision anchors its Jiangsu operations near Nantong port to compete for offshore nacelle contracts without cross-province labor migration. Mingyang specializes in typhoon-resistant drivetrain designs that differentiate its Guangdong-built units for South China Sea installations.
China wind energy encompasses the conversion of kinetic airflow into electrical power through aerodynamic rotor blades coupled to synchronous or doubly-fed induction generators, with modern onshore units reaching hub heights above 160 meters and rotor diameters exceeding 200 meters to capture low-speed wind resources. The technology segment splits between onshore deployments that dominate installed capacity across Inner Mongolia and Gansu corridors, and offshore systems that command premium pricing due to foundation complexity and subsea cable integration. The component segment sees blade manufacturers pursuing longer carbon-fiber reinforced designs while gearbox suppliers face margin compression from direct-drive permanent magnet alternatives. The end user segment shows independent power producers capturing project development rights ahead of state-grid affiliated utilities in coastal provinces.
MIIT's wind turbine grid-code compliance rules and NEEA's renewable portfolio standards shape equipment procurement timelines, while GB standards for low-voltage ride-through capability determine which controllers qualify for grid connection approval. SAMR's anti-monopoly reviews of turbine supply contracts influence how developers structure equipment procurement across multi-gigawatt wind bases. Stakeholders must monitor how provincial energy bureaus allocate interconnection quotas between onshore desert bases and offshore marine zones.
Market Dynamics
MIIT's grid-code compliance mandates are forcing turbine OEMs to reengineer power electronics and grid-forming inverters, compressing equipment procurement timelines while raising technical barriers for smaller suppliers.
Growth Catalysts
- Offshore foundation engineering advances:Deep-water jacket and floating platform designs unlock gigawatt-scale development in Jiangsu and Guangdong coastal zones.
- NEEA renewable portfolio standards:Provincial energy bureaus must hit binding clean electricity quotas, accelerating interconnection approvals for desert-base and marine-zone projects.
- Carbon-fiber blade manufacturing:Longer reinforced rotors capture low-speed wind resources across Inner Mongolia and Gansu corridors previously deemed subeconomic.
Market Restraints
- Rare-earth magnet supply concentration:Direct-drive permanent magnet generators depend on dysprosium and terbium processing clusters in Jiangxi and Inner Mongolia.
- Subsea cable installation bottlenecks:Specialized vessel availability limits offshore project commissioning velocity in Fujian and Zhejiang waters.
- GB standards low-voltage ride-through:Controller certification delays disqualify imported power electronics from grid connection approval.
Strategic Opportunities
- Typhoon-resistant drivetrain specialization:South China Sea installations demand hardened gearbox and bearing designs absent in northern European offshore units.
- Inter-provincial transmission corridor expansion:Ultra-high-voltage lines from Xinjiang and Gansu to eastern load centers enable remote desert-base development.
- Technician training academy networks:Provincial labor bureaus in Xinjiang and Jiangsu are certifying blade-assembly and nacelle-installation workforces without cross-region migration.
Industry Challenges
- Grid-forming inverter integration:Converting turbine fleets from grid-following to grid-forming control architectures requires firmware revalidation across entire installed bases.
- SAMR anti-monopoly procurement reviews:Multi-gigawatt wind base developers must restructure equipment supply contracts to avoid concentration findings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Wind Energy Market |
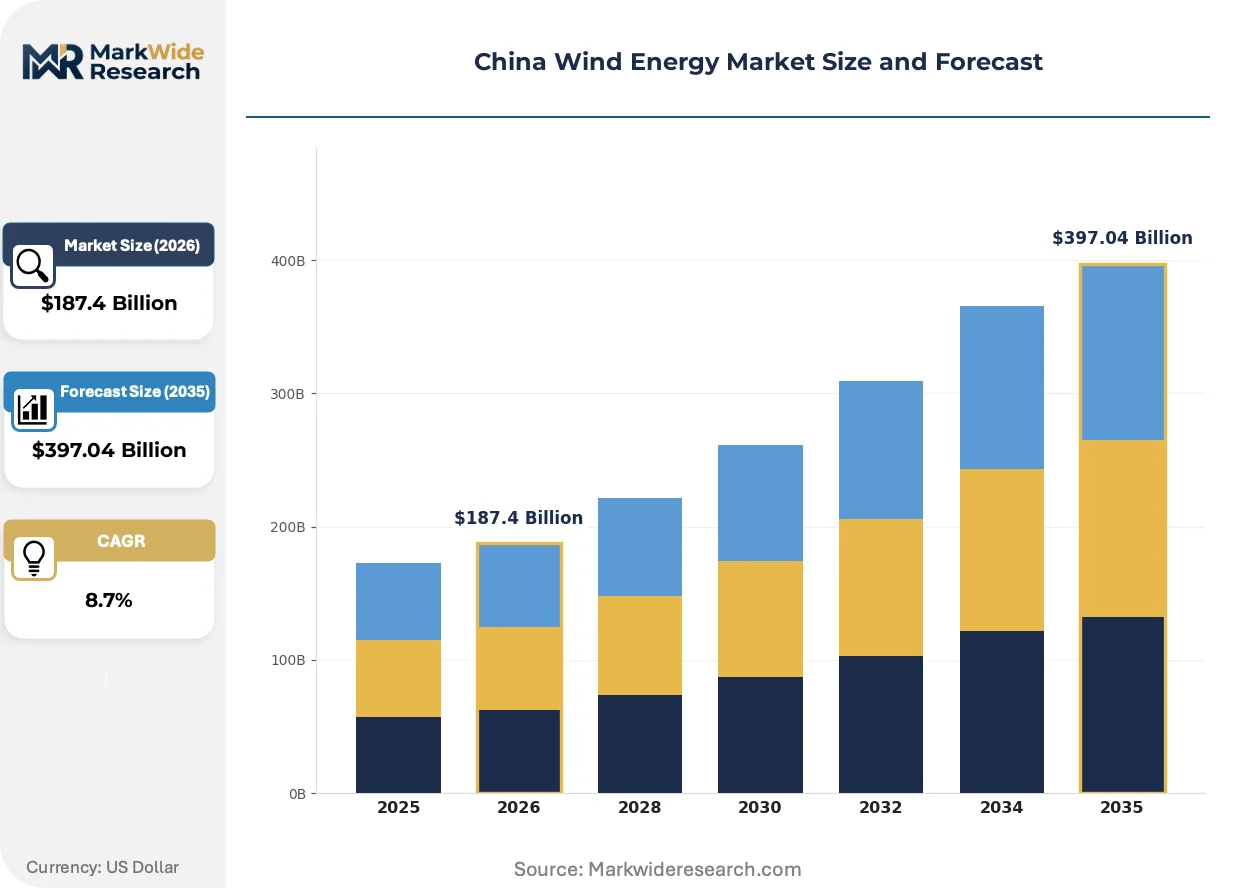
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Turbines, Blades, Gearboxes, Controllers Technology: Onshore, Offshore, Vertical Axis, Horizontal Axis End User: Utilities, IPPs, Industrial Users, Government Capacity: Below 1 MW, 1-5 MW, 5-10 MW, Above 10 MW |
| Companies Covered | Goldwind, Envision, Mingyang, Windey, Sany, Dongfang Electric, Shanghai Electric, CSIC Haizhuang, Shanghai FL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Wind Energy Market Emerging Trajectories
Power electronics architectures, foundation engineering methods, and technician deployment models are converging to reshape competitive positioning across coastal and desert-corridor development zones.
Direct-drive permanent magnet generator technology is fragmenting the drivetrain supplier landscape. Goldwind and domestic competitors are abandoning gearbox-dependent designs for simplified, higher-reliability architectures. This shift compresses margins for European and Japanese gearbox specialists while elevating rare-earth magnet procurement as a strategic chokepoint.
MIIT's updated grid connection standards now mandate grid-forming inverter capability for all new turbine installations. This regulatory friction disqualifies legacy power electronics controllers and forces OEMs to redesign converter platforms. Coastal provinces with the most aggressive offshore deployment timelines face the steepest compliance costs.
Independent power producers are unbundling engineering-procurement-construction contracts from long-term service agreements. This procurement model change disrupts state-grid affiliated utilities that historically captured both development rights and operational contracts. The pattern is most visible in Jiangsu and Guangdong, where IPPs now separately tender turbine supply, installation, and 15-year maintenance scopes.
China Wind Energy Market Segmentation
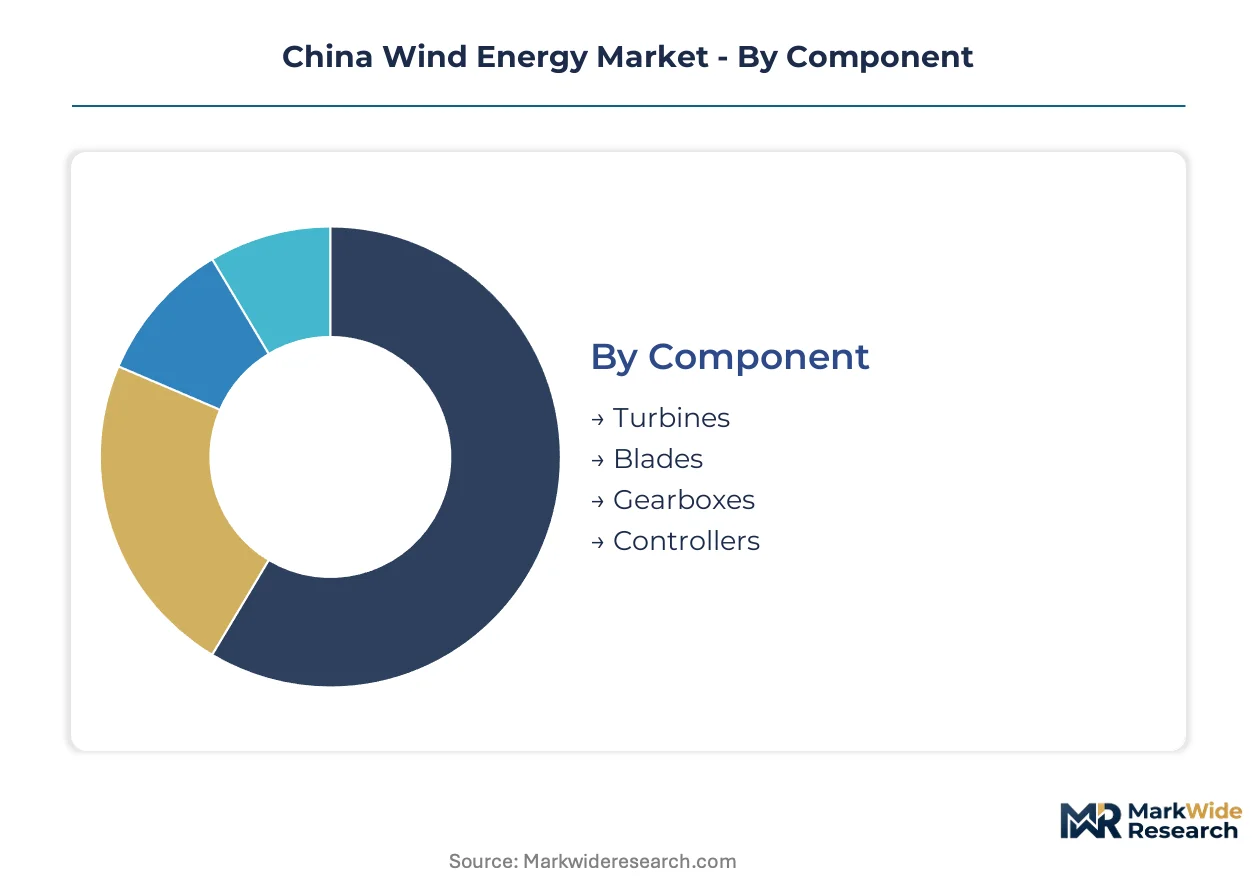
Segmentation in the China wind energy market reveals distinct procurement patterns across coastal manufacturing zones and inland desert corridors. Equipment specifications vary sharply between Jiangsu offshore clusters and Gansu onshore bases, driving divergent supplier qualification requirements.
Component:
Domestic supply chains dominate nacelle assembly and blade fabrication, while certain power electronics still rely on import substitution programs.
- Turbines:Complete nacelle assemblies integrate generators, drivetrains, and yaw systems at OEM final-assembly plants in Jiangsu and Guangdong. MIIT's grid-forming inverter mandates are forcing redesigns of converter platforms before interconnection approval.
- Blades:Carbon-fiber reinforced designs exceeding 100 meters in length capture low-speed wind resources across Inner Mongolia corridors. Goldwind's Xinjiang training academies sustain blade assembly throughput without cross-province technician migration.
- Gearboxes:European and Japanese specialists face margin compression as Goldwind and domestic OEMs abandon geared designs.
- Controllers:GB standards for low-voltage ride-through capability determine grid connection qualification, disqualifying legacy power electronics architectures.
Turbines command the established base. The steepest expansion runs through blades as longer rotors unlock previously subeconomic wind regimes.
Technology:
Cost tiers separate premium offshore foundations from standardized onshore tower configurations, with vertical-axis units occupying niche micro-grid applications.
- Onshore:Horizontal-axis units with hub heights above 160 meters dominate installed capacity across Inner Mongolia and Gansu transmission corridors. Ultra-high-voltage lines to eastern load centers enable remote desert-base development at scale.
- Offshore:Deep-water jacket and floating platform designs unlock gigawatt-scale clusters in Jiangsu and Guangdong coastal zones where inter-provincial transmission corridors and deep-water ports converge.
- Vertical Axis:Darrieus and Savonius configurations serve distributed micro-grid installations in remote agricultural counties.
- Horizontal Axis:Upwind rotor configurations with variable pitch control represent the standardized architecture for utility-scale procurement.
Onshore systems command the established base. The steepest expansion runs through offshore technology as coastal provinces accelerate marine-zone deployment.
End User:
Customer type determines contract structure, with independent power producers unbundling engineering-procurement-construction from long-term service agreements.
- Utilities:State-grid affiliated entities historically captured both development rights and operational contracts, now facing disruption from unbundled procurement models in Jiangsu and Guangdong.
- IPPs:Independent power producers separately tender turbine supply, installation, and 15-year maintenance scopes, ahead of state-grid competitors in coastal provinces.
- Industrial Users:Captive power arrangements for steel and chemical complexes in Shandong and Hebei drive behind-the-meter installations.
- Government:Provincial energy bureaus allocate interconnection quotas between desert bases and marine zones under NEEA renewable portfolio standards.
Utilities command the established base. The steepest expansion runs through IPPs as procurement unbundling accelerates in coastal development zones.
Capacity:
Volume concentration sits with multi-megawatt units for utility-scale procurement, while sub-megawatt systems serve distributed applications.
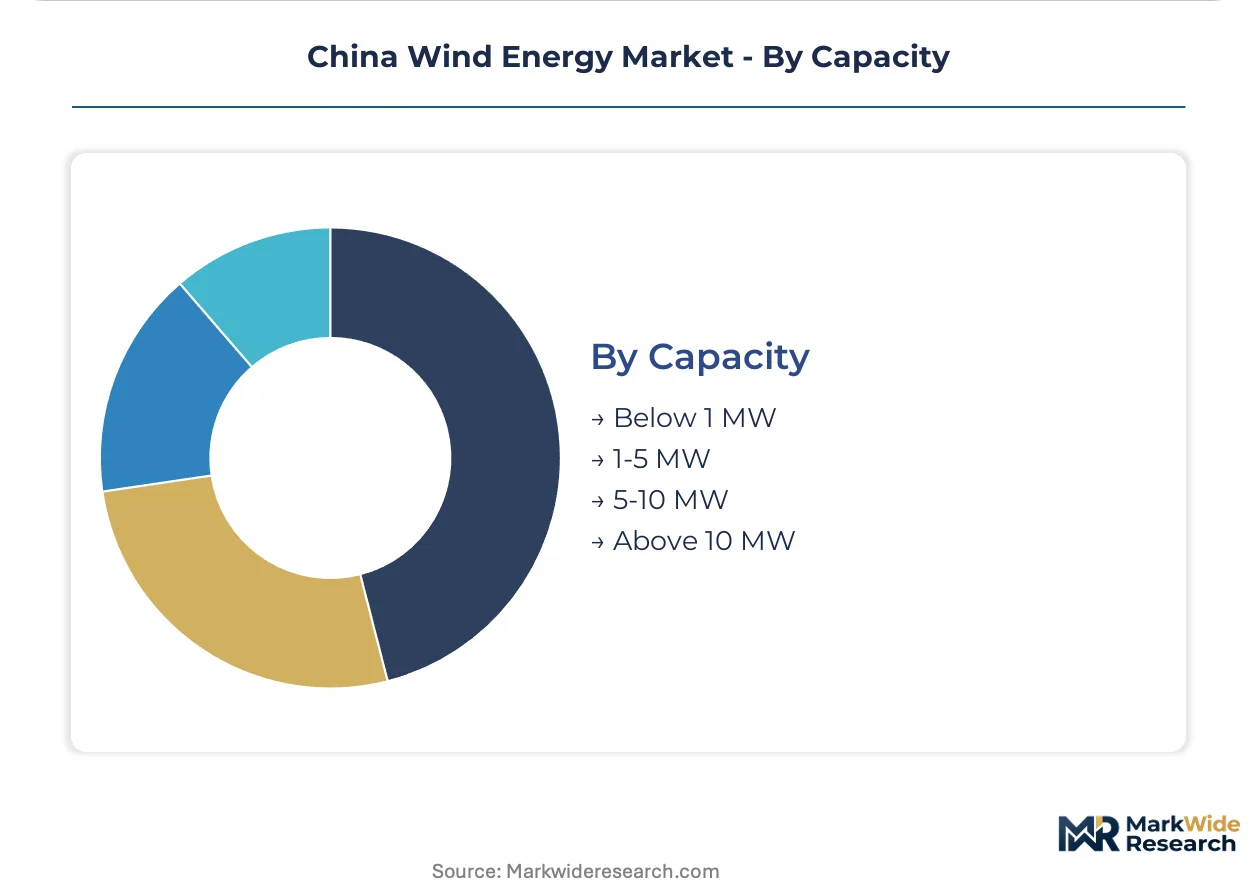
- Below 1 MW:Distributed installations for agricultural irrigation and rural electrification in western provinces.
- 1-5 MW:Early-generation onshore units undergoing repowering campaigns in northern corridor legacy wind bases.
- 5-10 MW:Current-generation onshore workhorses with 160-meter hub heights and 200-meter rotors for low-speed resource capture.
- Above 10 MW:Offshore-dedicated platforms with direct-drive permanent magnet generators and typhoon-resistant drivetrains for South China Sea installations.
5-10 MW units command the established base. The steepest expansion runs through above-10 MW platforms as offshore foundation engineering advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's wind energy deployment varies sharply by geography: coastal provinces prioritize offshore baseload capacity while inland corridors exploit desert wind resources through ultra-high-voltage transmission links.
Jiangsu
Offshore project clusters concentrate near Nantong port where deep-water access enables gigawatt-scale foundation installation. MIIT's grid-forming inverter mandates accelerate equipment procurement timelines for coastal developers. The Yangtze River Delta manufacturing belt hosts nacelle assembly plants serving both domestic and export markets.
Guangdong
South China Sea installations drive demand for typhoon-resistant drivetrain designs absent in European offshore units. Provincial energy bureaus allocate interconnection quotas aggressively under NEEA renewable portfolio standards. The Pearl River Delta anchors specialized blade fabrication for marine-zone turbine platforms.
Inner Mongolia
Desert wind bases capture low-speed resources through 160-meter hub heights and 200-meter carbon-fiber rotors. Ultra-high-voltage transmission corridors eastward enable remote generation to reach coastal load centers. Rare-earth magnet processing clusters in the region supply direct-drive permanent magnet generators for domestic OEMs.
Fujian
Subsea cable installation bottlenecks constrain commissioning velocity despite favorable wind resources. Specialized vessel availability limits project throughput compared to Jiangsu and Guangdong. The Taiwan Strait corridor remains underdeveloped relative to its technical potential due to marine construction capacity constraints.
Xinjiang
Training academies sustain blade assembly throughput without cross-province technician migration. Gansu corridor interconnections channel desert generation toward eastern demand centers. Provincial labor bureau certification programs address certified wind turbine technician shortages affecting northern manufacturing zones.
China Wind Energy Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in China's wind energy equipment market. The upper tier controls nacelle assembly, blade fabrication, and power electronics integration through captive manufacturing networks. Below them, component specialists concentrate on gearboxes, controllers, or foundation engineering. Competitive moves center on vertical integration into rare-earth magnet supply chains and geographic anchoring near coastal port infrastructure.
Within the integrated leader tier, Goldwind and Envision occupy positions defined by manufacturing scale and coastal logistics access. Goldwind leverages Xinjiang-based training infrastructure to sustain assembly throughput, while Envision anchors Jiangsu operations near Nantong port to compete for offshore contracts. Mingyang represents the specialization vector through typhoon-resistant design capabilities for South China Sea installations. These three exemplify how domestic OEMs align organizational capabilities with provincial deployment patterns.
| Leading Market Players |
|---|
| Goldwind |
| Envision |
| Mingyang |
| Windey |
| Sany |
| Dongfang Electric |
| Shanghai Electric |
| CSIC Haizhuang |
| Shanghai FL |
| Others |
Supply Flow & Price Mechanics
MIIT's grid-forming inverter certification gates both equipment qualification and price differentiation simultaneously, compressing procurement timelines for coastal developers while elevating technical compliance costs above legacy controller architectures. OEMs with captive converter production capture margin premiums against import-dependent competitors disqualified by GB standards low-voltage ride-through requirements.
Pricing Analysis
Long-term offtake contracts dominate utility-scale procurement, with 15-year service agreements bundled into turbine supply packages for state-grid affiliated buyers. Price differentiation rests on certification grade for typhoon-resistant drivetrains and geographic delivery cost to coastal port infrastructure. Cost compression in onshore tower configurations is intensifying because direct-drive permanent magnet designs displace gearbox-dependent alternatives. Independent power producers exhibit highest price sensitivity through unbundled EPC tenders, while offshore developers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Inventory lead times for rare-earth magnets extend 6-9 months from Jiangxi and Inner Mongolia processing clusters, constraining direct-drive generator output scheduling. Domestic supply chains anchor nacelle assembly in Jiangsu and Guangdong, while carbon-fiber pre-preg imports draw from Japan and South Korea for blade fabrication. Single-source vulnerability concentrates in dysprosium and terbium refining capacity. Distribution runs through provincial energy bureau interconnection quota allocations before project commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's wind energy market faces substitution pressure from photovoltaic-plus-storage hybrids in desert corridor applications, requiring incumbents to defend baseload positioning through grid-forming capabilities that solar-battery configurations cannot replicate.
For Market Incumbents: Consolidate rare-earth magnet supply through backward integration into Jiangxi processing clusters or long-term offtake agreements with Inner Mongolia refiners. Deepen technician training academy networks to sustain blade assembly throughput without cross-province labor migration. Defend against emerging drivetrain specialists by accelerating grid-forming inverter firmware revalidation across installed bases.
For New Entrants and Emerging Players: Aftermarket service gaps in legacy gearbox maintenance present white-space opportunities as Goldwind and Envision abandon geared designs. Target Fujian and Zhejiang coastal zones where subsea cable installation bottlenecks constrain incumbent project velocity. Pursue independent certification for typhoon-resistant bearing assemblies as the go-to-market angle.
For Investors and Strategic Acquirers: MIIT's renewable portfolio standard enforcement reshapes the acquisition landscape toward IPPs with secured interconnection quotas in Jiangsu and Guangdong. Long-term viability centers on vertical integration depth across converter platforms and foundation engineering capabilities. Monitor provincial energy bureau quota allocation patterns as the inflection signal for deployment velocity shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Forming Inverter Certification | MIIT mandates disqualify legacy controllers, forcing OEM platform redesigns before interconnection approval. |
| Typhoon-Resistant Drivetrain Development | South China Sea installations require hardened designs absent in European offshore units, creating regional specialization. |
| Rare-Earth Magnet Supply Integration | Backward integration into Jiangxi processing clusters secures dysprosium and terbium for direct-drive generator production. |
| Technician Training Academy Expansion | Provincial labor bureau certification programs address shortages without cross-region migration to manufacturing zones. |
| Subsea Cable Installation Capacity | Specialized vessel availability limits Fujian and Zhejiang commissioning velocity relative to Jiangsu and Guangdong. |
Methodological Framework
The analysis maps onshore desert-base, offshore marine-zone, and distributed wind segments, each validated through utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary interviews with provincial energy bureau officials and turbine OEM procurement heads combined with secondary validation from NEEA renewable portfolio filings, MIIT grid-code compliance databases, and ultra-high-voltage transmission project registries. Bottom-up project pipeline aggregation and top-down provincial quota allocation analysis provided triangulation across data sources.
Consistency checks validated volume and value outputs against interconnection approval timelines and equipment procurement disclosures from publicly traded developers. Segmentation dimensions modeled include technology type, component category, end-user archetype, and capacity tier across the projection horizon. CAGRs derived from unit deployment trajectories and capital cost curves incorporate direct-drive generator adoption rates and foundation engineering cost structures as industry-specific inputs.
Forecasts assume regulatory continuity in MIIT grid-code enforcement and NEEA renewable portfolio standards; material policy shifts in interconnection quota allocation or low-voltage ride-through requirements would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Global Renewable Energy Market
Renewable Energy
Brazil Renewable Energy Market
Renewable Energy
Europe IoT in Renewable Energy Market
Renewable Energy
India Renewable Energy Market
Renewable Energy
Renewable Energy Policy Fit Analysis Market
Renewable Energy
Renewable Naphtha Market
Renewable Energy
Asia-Pacific Renewable Energy Market
Renewable Energy
South Africa Solar Photovoltaic (PV) Market
Renewable Energy
Austria Renewable Energy Market
Renewable Energy
China Wind Power Market
Renewable Energy
South Europe Renewable Energy Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
Canada Renewable Energy Market
Renewable Energy
South Africa Rooftop Solar Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
Saudi Arabia Renewable Energy Market