
 Global Green Energy Market | 2026-2036
Global Green Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Green Energy Market Analysis
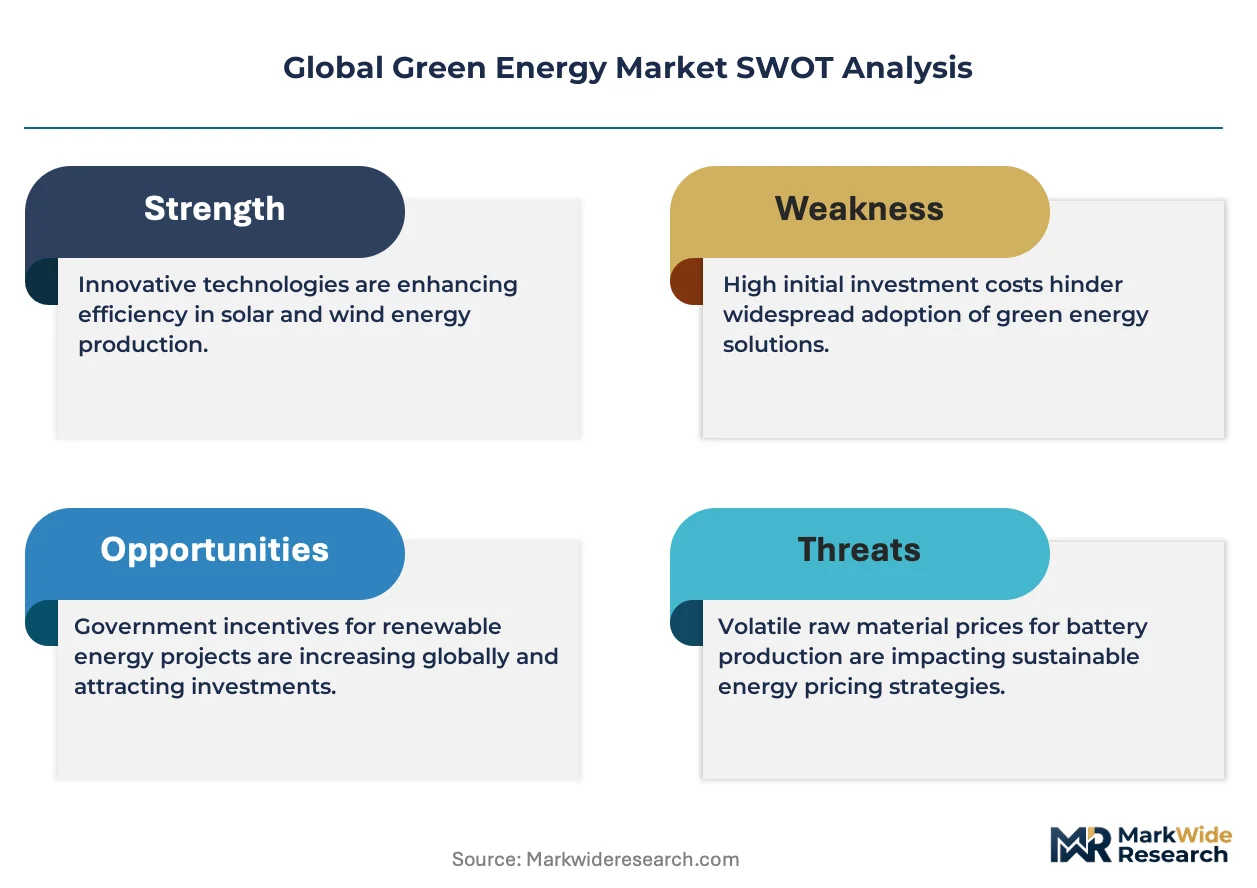
Modular solar-plus-storage bundling is hardening as the dominant procurement configuration for utility-scale buyers. NextEra Energy leverages its vertically integrated development pipeline to deliver turnkey bundled solutions across North American grids. Iberdrola anchors its competitive position through captive project development capabilities spanning offshore wind and solar hybrids. Adani Green Energy dominates India's utility-scale segment with concentrated solar park infrastructure that reduces transmission costs.
Green energy encompasses electricity, heat, and transport fuels derived from renewable sources with near-zero operational carbon emissions, typically requiring photovoltaic cells with conversion efficiencies above 20 percent or wind turbines rated at 2+ megawatts for commercial viability. Its primary purpose is displacing fossil-fuel combustion across power generation, industrial process heat, and electrified mobility. Solar technology leads installed capacity additions and captures the deepest cost-learning curve, while offshore wind within the wind segment commands premium pricing due to higher capacity factors and complex installation requirements. Hydropower remains the most mature baseload contributor with limited new large-site availability, constraining growth to small-run-of-river retrofits and pumped-storage hybrids.
The EU Green Deal and F-Gas Regulation are accelerating refrigerant-phaseout timelines that reshape heating-system electrification requirements across European markets. India's Central Electricity Authority enforces must-run status for renewable assets, altering dispatch economics and grid-integration investments. China's MIIT dual carbon goals mandate provincial renewable quotas that redirect industrial load to clean-energy clusters. Stakeholders must monitor evolving carbon-border adjustment mechanisms and their interaction with domestic content requirements to preserve project financeability and offtake competitiveness.
Market Dynamics
Modular solar-plus-storage bundling is hardening as the dominant procurement configuration for utility-scale buyers, compressing development timelines and reshaping competitive positioning around integrated delivery capabilities rather than component specialization.
Growth Catalysts
- EU Green Deal grid-connection mandates:Tightening renewable portfolio standards across Germany, Spain, and Italy are accelerating utility procurement of bundled solar-plus-storage contracts to meet dispatchability requirements.
- India's CEA must-run regulations:The Central Electricity Authority enforces priority dispatch for renewable assets, altering grid-integration investments and improving project returns for solar park developers.
- China's MIIT dual carbon quotas:Provincial renewable mandates redirect industrial load to clean-energy clusters in Inner Mongolia and Xinjiang, concentrating demand for utility-scale installations.
Market Restraints
- Polysilicon supply concentration:Refining capacity clusters in Xinjiang and Sichuan create input cost volatility and ESG compliance risks for photovoltaic module manufacturers.
- Offshore wind installation bottlenecks:Specialized vessel scarcity and port infrastructure gaps in Taiwan and Vietnam constrain project execution timelines and capital deployment.
- F-Gas Regulation phaseout timelines:The EU's accelerated refrigerant restrictions reshape heating-system electrification requirements, creating retrofit cost burdens for residential heat pump adoption.
Strategic Opportunities
- Brazil's distributed generation expansion:Net-metering reforms and rising commercial electricity tariffs open underpenetrated rooftop solar segments beyond utility-scale procurement.
- Green hydrogen offtake convergence:Electrolyzer-integrated renewable projects in Saudi Arabia and Australia create new demand sinks for curtailed solar and wind generation.
- Corporate PPA channel innovation:Virtual power purchase agreements enable technology and data center firms to bypass utility intermediaries and contract directly with developers.
Industry Challenges
- Grid interconnection queues:Transmission upgrade backlogs in California, Texas, and the UK delay project energization and strain developer working capital.
- Electrification skill shortages:Scarcity of certified technicians for heat pump installation and EV charging infrastructure deployment constrains residential and transport segment growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Green Energy Market |
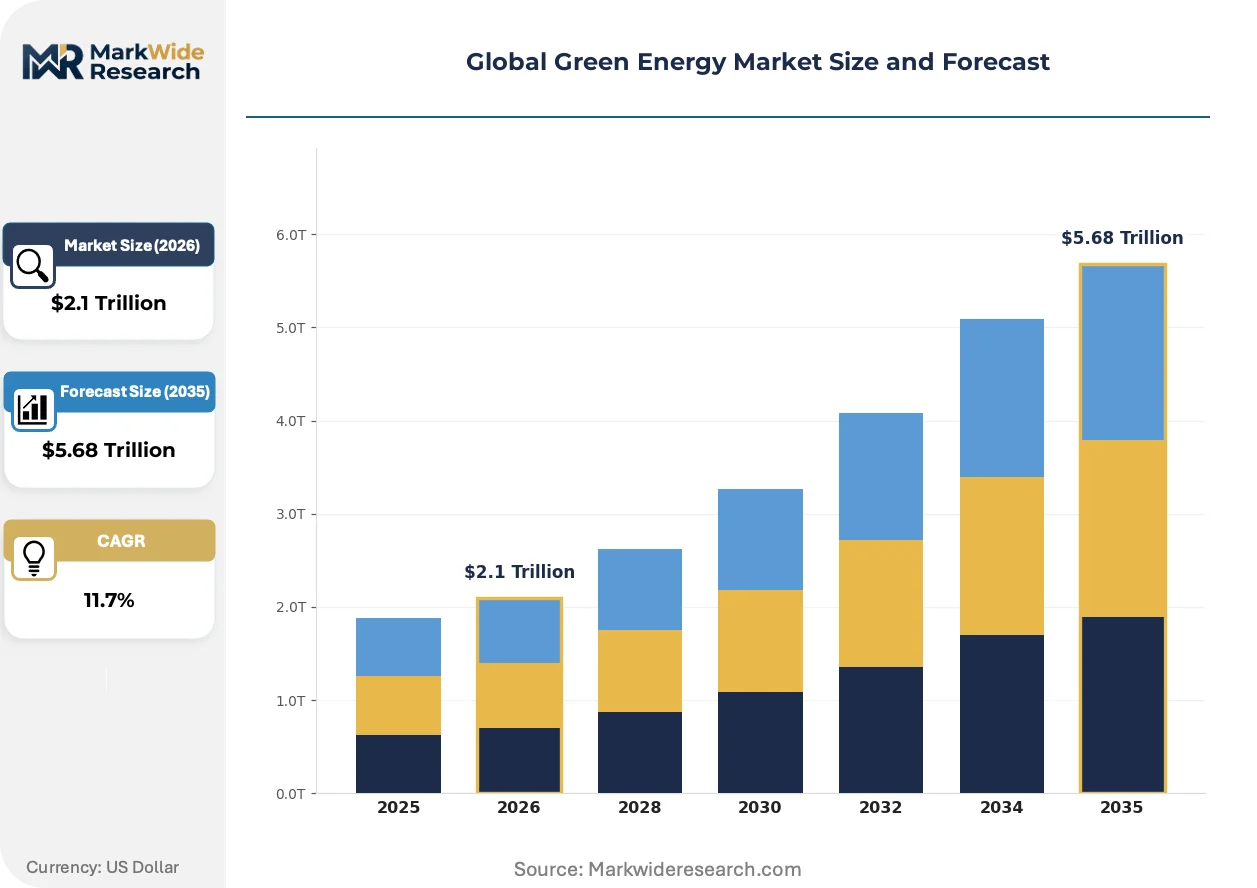
| Market Size in 2026 | $2.1 Trillion |
| Market Size in 2035 | $5.68 Trillion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Hydropower, Biomass Application: Power Generation, Heating, Transportation, Industrial Use End User: Residential, Commercial, Industrial, Utilities Distribution Channel: Direct Sales, Retail, Online, Third-Party Distributors |
| Companies Covered | NextEra Energy, Iberdrola, Enel Green Power, Adani Green Energy, Vestas, Siemens Gamesa, First Solar, Brookfield Renewable Partners, GE Vernova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Green Energy Market Emerging Trajectories
Behind-the-meter energy management systems are actively reshaping how commercial and industrial buyers optimize renewable self-consumption, creating new competitive battlegrounds around software-enabled dispatch rather than hardware procurement alone.
Containerized battery storage is decentralizing grid-scale flexibility deployment. Lithium-iron-phosphate systems with four-hour duration ratings enable commercial campuses and manufacturing facilities to arbitrage time-of-use tariffs. C&I buyers in Germany and Australia are adopting these systems faster than utility procurement cycles permit, compressing traditional centralized peaker plant economics.
The EU F-Gas Regulation is accelerating refrigerant-phaseout timelines that reshape heating-system electrification requirements. Heat pump manufacturers must redesign compressors and working fluids to comply with GWP limits below 150. Nordic and Baltic markets face the steepest compliance curves, driving equipment replacement cycles ahead of natural obsolescence.
Long-term service agreements are displacing component-only sales in utility-scale procurement. EPC contractors and independent power producers now bundle 15-20 year O&M commitments with initial construction contracts. This shift concentrates risk with developers capable of underwriting performance guarantees across multiple technology classes and geographies.
Global Green Energy Market Segmentation
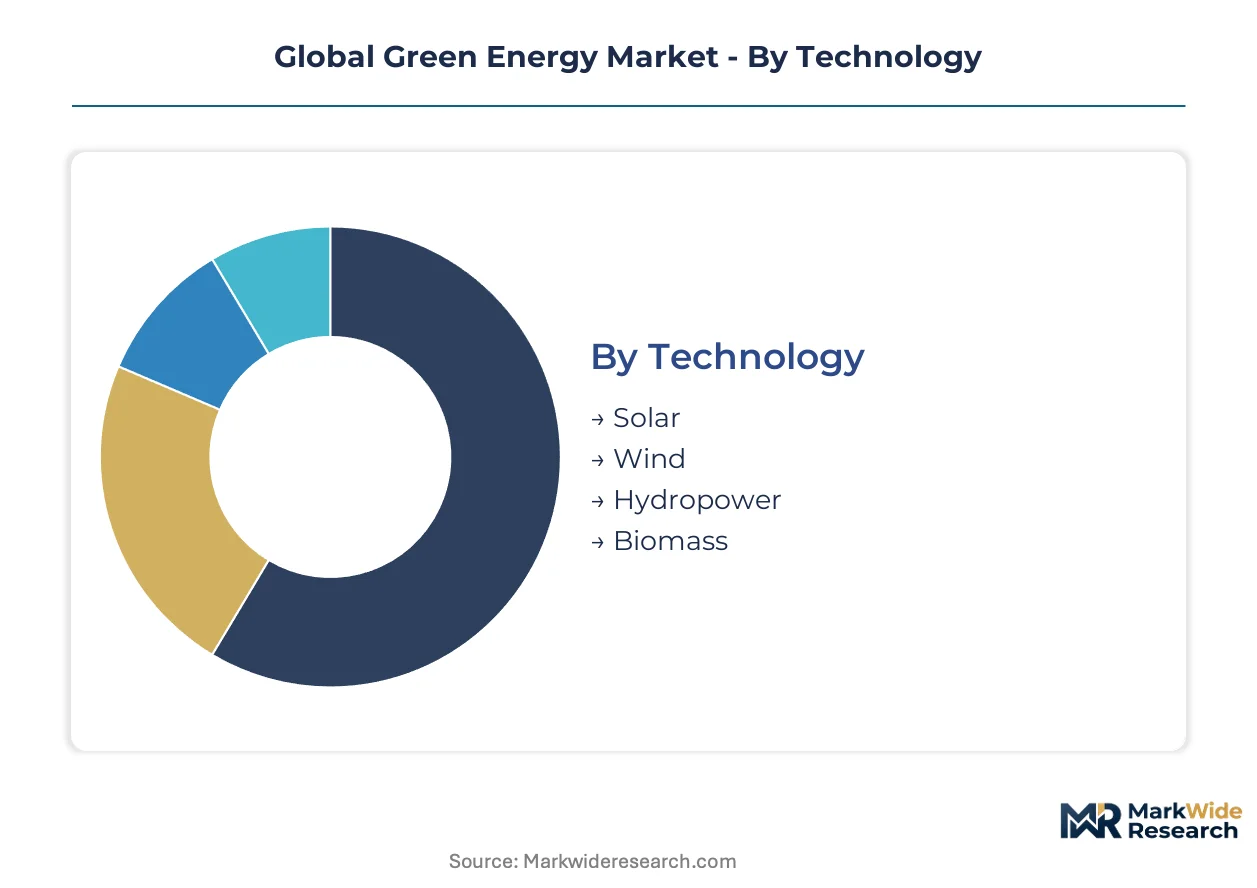
Technology choices determine capital intensity and project returns for developers across divergent grid-connection requirements. Application segmentation reveals where electrification mandates intersect with policy incentives. End-user and channel structures reflect how procurement centralization affects pricing power and delivery economics.
Technology:
Upgrade cycles for renewable assets accelerate where policy mandates force early retirement of fossil infrastructure and grid codes tighten frequency-response requirements.
- Solar:Photovoltaic systems with conversion efficiencies above 20 percent dominate capacity additions through modularity and shortest development timelines. Utility procurement in China's provincial clean-energy bases and India's solar parks concentrates demand for utility-scale installations, with bifacial panels and tracking systems commanding premium pricing for higher yield profiles.
- Wind:Turbines rated at 2+ megawatts anchor commercial viability, with offshore variants achieving higher capacity factors at complex installation cost. Taiwan and Vietnam face vessel scarcity and port infrastructure gaps that constrain execution timelines, while North Sea projects benefit from mature supply chains.
- Hydropower:Run-of-river retrofits and pumped-storage hybrids dominate new investment as large-site availability vanishes; limited growth reflects environmental permitting barriers.
- Biomass:Agricultural residue and municipal waste streams fuel combined-heat-and-power installations in rural industrial clusters; feedstock logistics constrain scaling beyond localized supply radii.
Volume placements concentrate in Solar; the faster expansion belongs to Wind.
Application:
Cost-tier differentiation separates mass-market electrification from premium industrial process heat where carbon-border mechanisms reshape competitiveness.
- Power Generation:Utility-scale procurement of bundled solar-plus-storage contracts hardens as the dominant configuration, compressing development timelines around integrated delivery capabilities. Germany, Spain, and Italy accelerate procurement to meet EU Green Deal dispatchability requirements.
- Heating:Heat pump electrification faces EU F-Gas Regulation refrigerant-phaseout timelines below 150 GWP, forcing compressor redesigns and equipment replacement cycles ahead of natural obsolescence in Nordic and Baltic markets.
- Transportation:Electrified mobility demand concentrates where charging infrastructure density and vehicle subsidy alignment create viable total-cost-of-ownership profiles; grid-integration investments strain distribution networks.
- Industrial Use:Green hydrogen offtake from electrolyzer-integrated projects in Saudi Arabia and Australia creates demand sinks for curtailed renewable generation; high-temperature process heat remains the final frontier for electrification economics.
Power Generation captures dominant placement volumes; Heating climbs fastest as building-code mandates tighten.
End User:
Customer-type concentration determines whether procurement runs through centralized tenders or fragmented retail channels with divergent working-capital requirements.
- Utilities:Vertically integrated development pipelines deliver turnkey bundled solutions across North American grids, with long-term service agreements displacing component-only sales and concentrating risk with performance-guarantee underwriters.
- Industrial:Corporate PPA channel innovation enables technology and data center firms to bypass utility intermediaries and contract directly with developers through virtual power purchase agreements.
- Commercial:Behind-the-meter energy management systems reshape self-consumption optimization; containerized lithium-iron-phosphate storage with four-hour duration enables tariff arbitrage faster than utility procurement cycles permit.
- Residential:Electrification skill shortages for heat pump installation and EV charging infrastructure constrain segment growth; net-metering reforms in Brazil open rooftop solar beyond utility-scale procurement.
Utilities anchor volume concentration; Industrial gains share fastest through direct contracting bypass.
Distribution Channel:
Supply concentration in module manufacturing and EPC capability shapes which channels can underwrite performance guarantees across multiple technology classes.
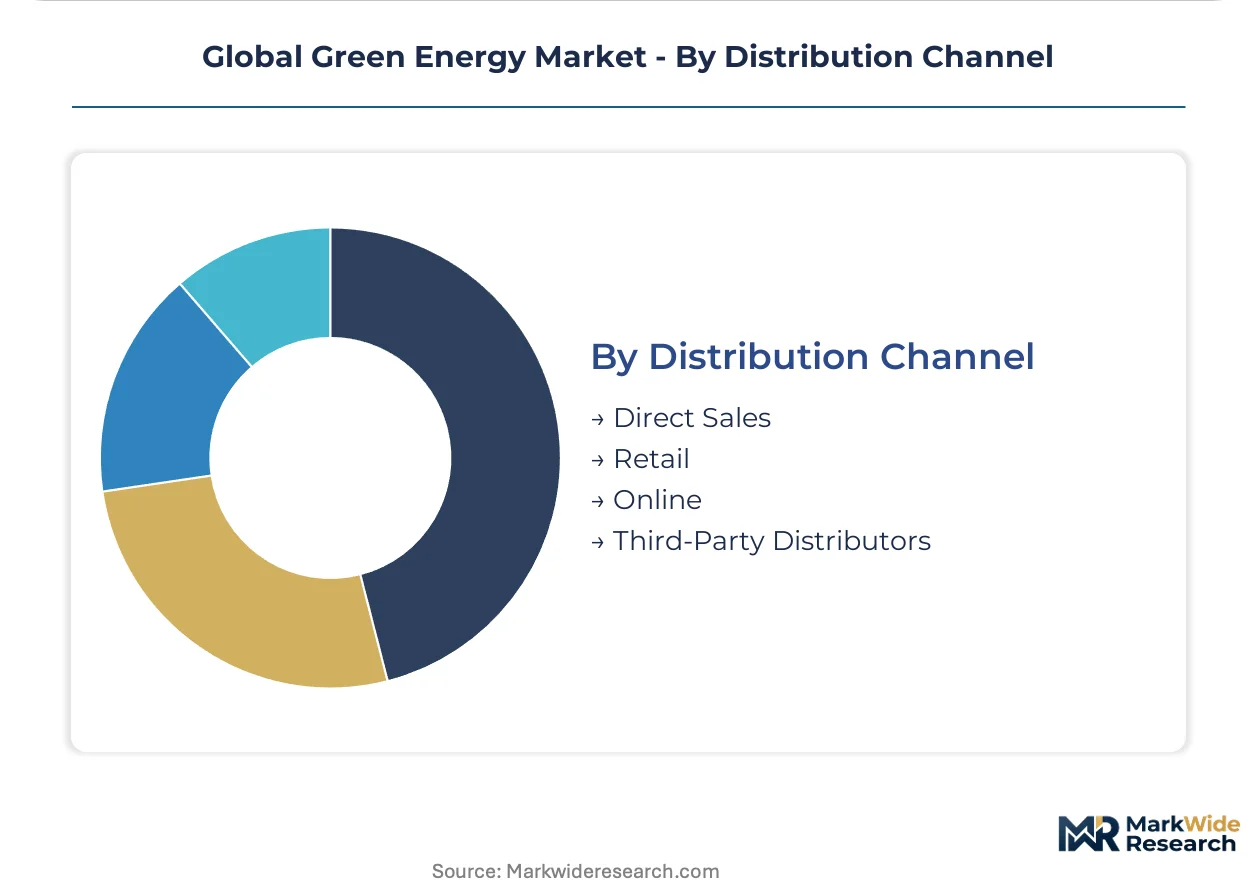
- Direct Sales:EPC contractors and independent power producers bundle 15-20 year O&M commitments with construction contracts, capturing utility-scale procurement where risk concentration demands integrated accountability.
- Third-Party Distributors:Regional logistics networks serve commercial and industrial segments where project scale falls below direct-sales thresholds but exceeds retail fragmentation.
- Retail:Hardware-focused channels dominate residential solar and heat pump equipment where installation services separate from product procurement.
- Online:Digital platforms facilitate corporate PPA origination and virtual contract execution; limited penetration for physical asset delivery due to installation complexity.
Direct Sales holds placement concentration; Third-Party Distributors expand most quickly into mid-scale commercial gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Inner Mongolia's clean-energy bases concentrate utility-scale solar and wind installations through MIIT-mandated provincial quotas that redirect industrial load from coastal manufacturing zones.
China
Xinjiang and Sichuan polysilicon refining clusters feed photovoltaic module supply chains while MIIT dual carbon goals enforce renewable procurement mandates. Provincial clean-energy bases in Inner Mongolia and Gansu host gigawatt-scale solar-wind hybrid installations serving Beijing-Tianjin-Hebei industrial demand.
United States
Texas and California interconnection queues strain developer working capital as FERC jurisdiction governs wholesale market participation. The Inflation Reduction Act's production tax credits concentrate project development in Great Plains wind corridors and Southwest solar zones.
Germany
EU Green Deal grid-connection mandates accelerate utility procurement of bundled solar-plus-storage contracts. Industrial load centers in North Rhine-Westphalia and Bavaria deploy behind-the-meter lithium-iron-phosphate systems to arbitrage time-of-use tariffs.
India
CEA must-run regulations enforce priority dispatch for renewable assets in Gujarat and Rajasthan solar parks. Adani Green Energy's concentrated infrastructure reduces transmission costs for utility-scale buyers under state-level renewable purchase obligations.
Brazil
Net-metering reforms unlock rooftop solar penetration beyond utility-scale procurement in São Paulo and Minas Gerais commercial segments. ANEEL regulatory adjustments align distributed generation expansion with rising commercial electricity tariffs.
Global Green Energy Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology classes and geographies. Market structure tilts toward consolidated developers capable of underwriting performance guarantees across solar, wind, and storage portfolios. Three archetypes dominate: vertically integrated utilities with captive project pipelines, independent power producers reliant on third-party EPC contracting, and equipment manufacturers expanding into downstream development. Competitive moves concentrate on long-term service agreement bundling and strategic partnerships for grid-scale storage integration.
Among utility-scale developers, NextEra Energy and Iberdrola exemplify the vertically integrated archetype through turnkey bundled solution delivery. Adani Green Energy occupies a position within the emerging-market pure-play tier, anchoring concentrated solar park infrastructure. These three represent divergent geographic footprints and regulatory navigation capabilities across North American, European, and South Asian markets.
| Leading Market Players |
|---|
| NextEra Energy |
| Iberdrola |
| Enel Green Power |
| Adani Green Energy |
| Vestas |
| Siemens Gamesa |
| First Solar |
| Brookfield Renewable Partners |
| GE Vernova |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers across China's provincial clean-energy bases and India's solar parks anchor supply-side discipline, translating captive financing advantages into long-term offtake pricing power that squeezes independent developers dependent on merchant market exposure.
Pricing Analysis
Margin tightening in utility-scale procurement reflects polysilicon input volatility concentrated in Xinjiang and Sichuan refining clusters. Project-based long-term offtake contracts dominate, with price differentiation hinging on conversion efficiency tiers above 20 percent and bundled storage duration guarantees. Cost-down pressure accelerates as bifacial tracking systems commoditize; commercial and industrial buyers show highest price sensitivity, while utilities under EU Green Deal mandates absorb premiums for dispatchable configurations.
Supply Chain Analysis
Domestic content requirements under India's PLI scheme and US Inflation Reduction Act local assembly mandates are reshaping module sourcing away from concentrated Chinese manufacturing. Polysilicon refining draws from Xinjiang, Sichuan, and Inner Mongolia; lithium-iron-phosphate cells rest on cathode material flows from China and nickel processing from Indonesia. Single-source vulnerability in specialized offshore wind installation vessels creates execution bottlenecks. Distribution runs through EPC contractors bundling construction with 15-20 year O&M commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid interconnection queue backlogs and working capital strain are forcing consolidation, eliminating developers lacking integrated storage capabilities or captive project pipelines.
For Market Incumbents: Lock in long-term service agreement bundling to capture utility procurement cycles and defend against pure-play storage specialists. Deepen backward integration into polysilicon or electrolyzer manufacturing to offset input cost volatility from Xinjiang supply concentration. Prioritize certification investment for EU F-Gas Regulation compliance in heat pump compressor redesigns. For New Entrants and Emerging Players: Enter via Brazil's distributed generation rooftop segment where net-metering reforms outpace utility-scale procurement saturation. Target commercial and industrial behind-the-meter storage in Germany and Australia where tariff arbitrage demand exceeds utility deployment timelines. Pursue direct corporate PPA origination with technology and data center firms bypassing traditional utility intermediaries. For Investors and Strategic Acquirers: FERC interconnection queue clearance rates are the leading indicator that developer working capital stress is peaking and distressed asset availability is expanding. Frame long-term viability around vertically integrated developers capable of underwriting performance guarantees across solar, wind, and storage portfolios. Monitor electrolyzer-integrated project announcements in Saudi Arabia and Australia as signals of green hydrogen offtake convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Expansion | Secures revenue visibility for developers under EU Green Deal dispatchability mandates. |
| Backward Integration into Polysilicon | Reduces exposure to Xinjiang refining cost volatility and ESG compliance risks. |
| Electrolyzer-Integrated Project Development | Captures green hydrogen offtake demand from Saudi Arabia and Australian industrial clusters. |
| Containerized Storage Manufacturing Scale-Up | Addresses lithium-iron-phosphate system demand from German and Australian C&I buyers. |
| Long-Term O&M Service Bundling | Concentrates risk with developers capable of multi-technology performance guarantees. |
Methodological Framework
Independent corroboration across utility planning officers, IPP project developers, EPC contractors, and grid operators underwrites the qualitative findings, validated against EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity addition tracking triangulates with top-down policy mandate analysis across the EU Green Deal, India's CEA regulations, and China's MIIT dual carbon goals.
Historical capacity deployment patterns anchor the projection horizon, with segmentation modeling across fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs derive from installed base growth rates moderated by interconnection queue clearance assumptions and polysilicon supply elasticity. Forecast inputs incorporate electrolyzer cost curves and corporate PPA origination velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tariff escalation scenarios or refrigerant-phaseout acceleration. The analytical envelope holds within boundaries defined by grid-integration investment timelines and carbon-border adjustment mechanism implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
PV Water Heater Market
Renewable Energy
Middle East Renewable Energy Market
Renewable Energy
Wind Turbine Foundation Market
Renewable Energy
China Solar Energy Market
Renewable Energy
Italy Renewable Energy Market
Renewable Energy
South Africa Distributed Solar Energy Market
Renewable Energy
Japan Renewable Energy Market
Renewable Energy
Brazil Renewable Energy Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Solar Boat Market
Renewable Energy
Norway Renewable Energy Market
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
South Asia Renewable Energy Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
Solar Panel Mounting Structure Market
Renewable Energy
Rectenna Market