
 Solar Thermal Market | 2026-2036
Solar Thermal Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Thermal Market Intelligence
A shift toward single-source procurement for critical concentrating collector components is hardening project supply chains to de-risk large-scale developments. Abengoa Solar leverages its extensive engineering expertise to construct complex solar thermal plants globally. Schott sustains its market leadership through the production of advanced glass receivers for parabolic trough systems. Heliogen positions itself with AI-powered heliostat field technology targeting high-temperature industrial heat.
Solar thermal systems capture sunlight to generate thermal energy, distinct from photovoltaic technologies that produce electricity directly. These systems use collectors and a heat transfer fluid, such as water or oil, to reach temperatures suitable for various applications. While flat plate collectors remain the standard for residential water heating, concentrating collectors are required for high-temperature industrial process heating. The commercial buildings segment increasingly utilizes evacuated tube collectors for space heating and cooling.
Incentive structures like the US Inflation Reduction Act and policies under the EU Green Deal are critical for project economics. China's dual carbon goals also provide significant policy support for renewable heat. Concurrently, ISO 9806 standards ensure collector performance and quality, facilitating market access. Navigating these diverse regional support schemes will be decisive for future investment and deployment strategies.
Market Dynamics
The central force shaping the solar thermal market is the industrial sector's strategic pivot to decarbonize process heat. This shift moves solar thermal beyond residential water heating into a critical role for manufacturing, driven by corporate sustainability goals and regulatory pressure.
Growth Catalysts
- Industrial Decarbonization Mandates:Policies under frameworks like the EU Green Deal compel manufacturers to reduce emissions, creating direct demand for renewable heat sources to replace fossil fuel-fired boilers in sectors such as food processing and chemicals.
- Policy Support in Asia:China's dual carbon goals provide substantial government support and subsidies for large-scale solar thermal installations, particularly for district heating and expansive commercial water heating projects.
- Collector Technology Advancement:Continuous improvements in the efficiency and durability of evacuated tube and concentrating collectors are expanding the viable temperature range, unlocking new applications in industrial process heat and solar cooling.
Market Restraints
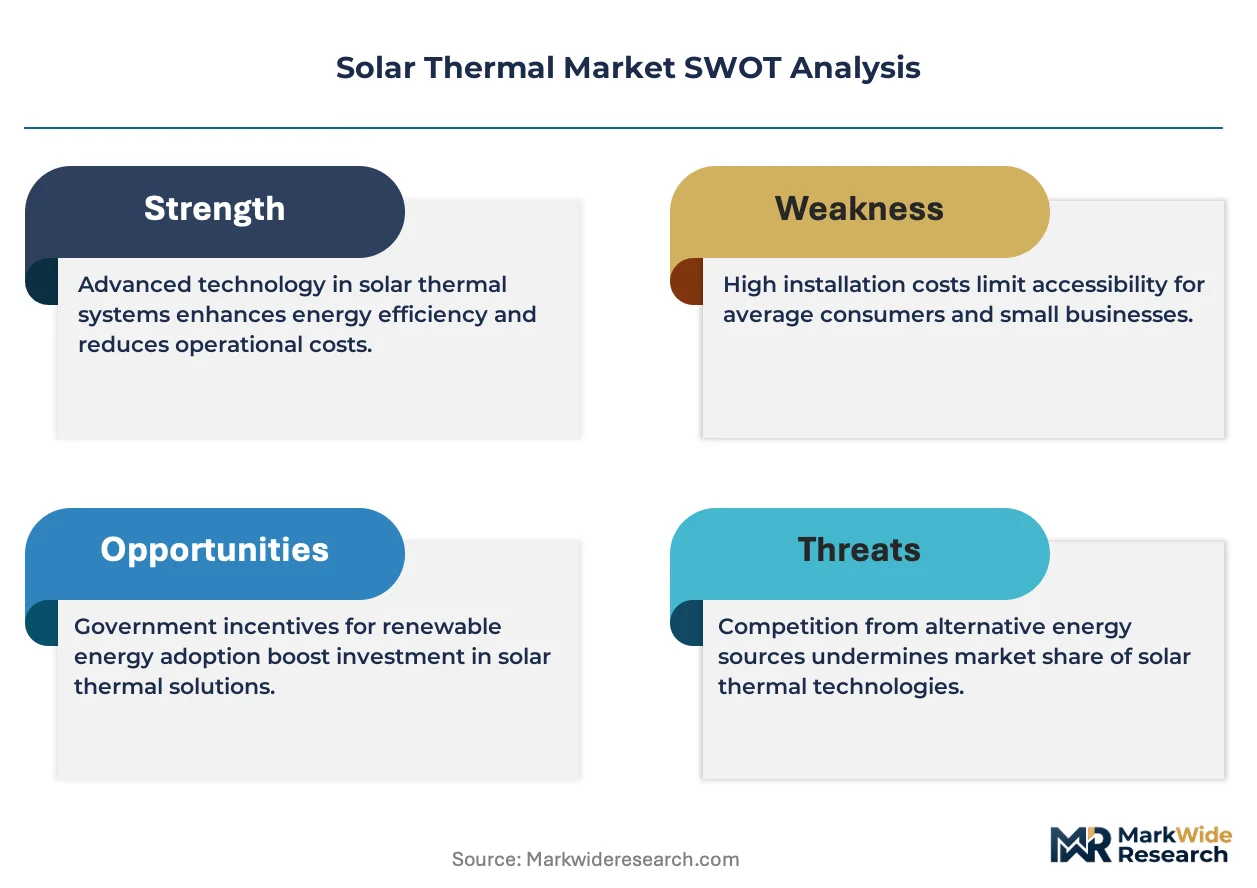
- High Initial Capital Outlay:The significant upfront investment required for large-scale concentrating solar thermal plants, including land and thermal storage, presents a major barrier compared to the lower initial cost of modular photovoltaic systems.
- Intermittency and Land Use:Solar thermal's reliance on direct sunlight creates operational intermittency, necessitating costly thermal energy storage or hybrid systems, while utility-scale projects require extensive land areas.
- Component Supply Chain Bottlenecks:The supply of critical components, such as high-performance receiver tubes for parabolic trough systems, is concentrated among a few specialized manufacturers, creating potential procurement risks and price volatility.
Strategic Opportunities
- High-Temperature Industrial Applications:Targeting energy-intensive industries like cement, steel, and mining with concentrating solar technologies offers a significant opportunity to displace fossil fuels in processes requiring temperatures above 400°C.
- Hybrid System Integration:Combining solar thermal with other energy systems, such as biomass boilers or geothermal heat pumps, creates resilient and continuous renewable heat solutions for industrial and commercial clients.
- AI-Driven Optimization:The integration of artificial intelligence and predictive analytics to control heliostat fields or optimize heat transfer fluid flow presents a clear path to boost system efficiency and lower operational costs.
Industry Challenges
- Specialized Labor Scarcity:A shortage of engineers and technicians with expertise in designing, installing, and maintaining complex concentrating solar thermal systems constrains project execution capacity and inflates labor costs.
- Grid Integration Complexity:For concentrating solar power (CSP) plants, integrating their electricity output with existing grid infrastructure, especially in regions with unstable networks, remains a significant technical and regulatory hurdle.
- Standardization and Certification:Adhering to diverse and evolving international and regional standards, such as ISO 9806 for collector performance, adds complexity and time to the product development and project certification lifecycle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Thermal Market |
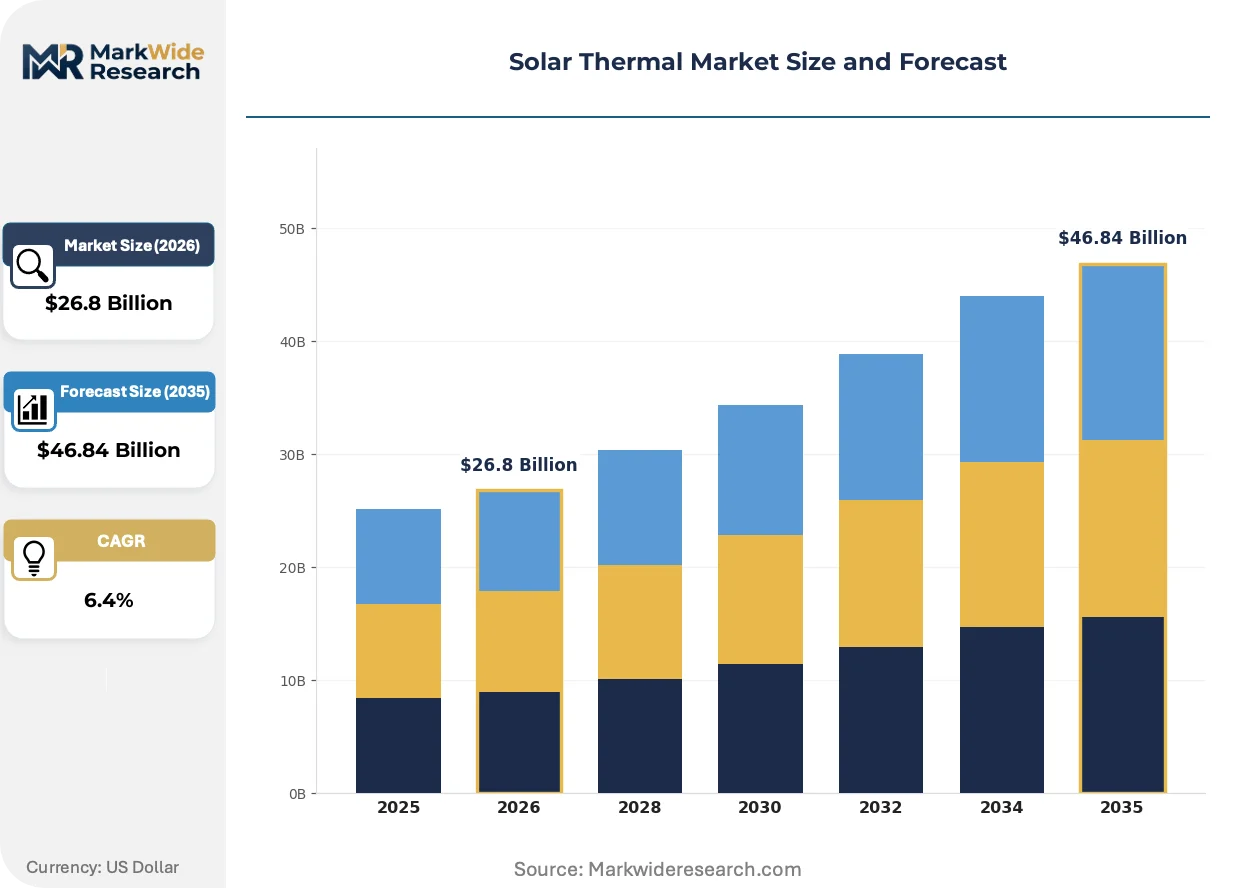
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $46.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Plate Collectors, Evacuated Tube Collectors, Concentrating Collectors, Unglazed Collectors Application: Water Heating, Space Heating, Industrial Process Heating, Solar Cooling, Desalination Installation Type: Roof-mounted Systems, Ground-mounted Systems, Building-integrated Systems, Portable Systems End User: Residential Properties, Commercial Buildings, Manufacturing Plants, Agricultural Facilities |
| Companies Covered | Acciona, Solar Millennium, Heliogen, Sener, GlassPoint, BrightSource Energy, SolarReserve, Schott, Abengoa Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Thermal Market Strategic Shifts & Innovations
The market's evolution is defined by a push toward higher temperatures and greater system intelligence. This transition is expanding solar thermal's role from a supplementary water heater to a primary energy source for complex industrial processes, supported by advanced digital controls.
AI-Powered Heliostat Fields
AI-powered heliostat field control systems use machine learning algorithms to optimize the reflection of sunlight onto a central receiver in real time. Developers of concentrating solar power plants and high-temperature industrial facilities are the primary adopters of this innovation. This technology is automating the constant, minute adjustments of the solar field, maximizing thermal efficiency and reducing reliance on manual calibration and maintenance.
Inflation Reduction Act Incentives
The US Inflation Reduction Act (IRA) establishes long-term tax credits for renewable energy projects, including solar thermal. This federal policy significantly improves project economics by lowering the effective capital cost for systems generating electricity or process heat. Industrial and commercial entities in the United States are most impacted, as the incentives make solar thermal a financially competitive alternative for decarbonizing operations.
Integrated EPC Contract Models
A transition toward single-source engineering, procurement, and construction (EPC) contracts is becoming standard for large-scale developments. This model replaces fragmented, multi-vendor procurement with a unified project delivery approach, assigning full responsibility to a single contractor. The shift is most visible in utility-scale concentrating solar power projects across the Middle East, North Africa, and China, where it de-risks complex construction schedules.
Solar Thermal Market Segmentation
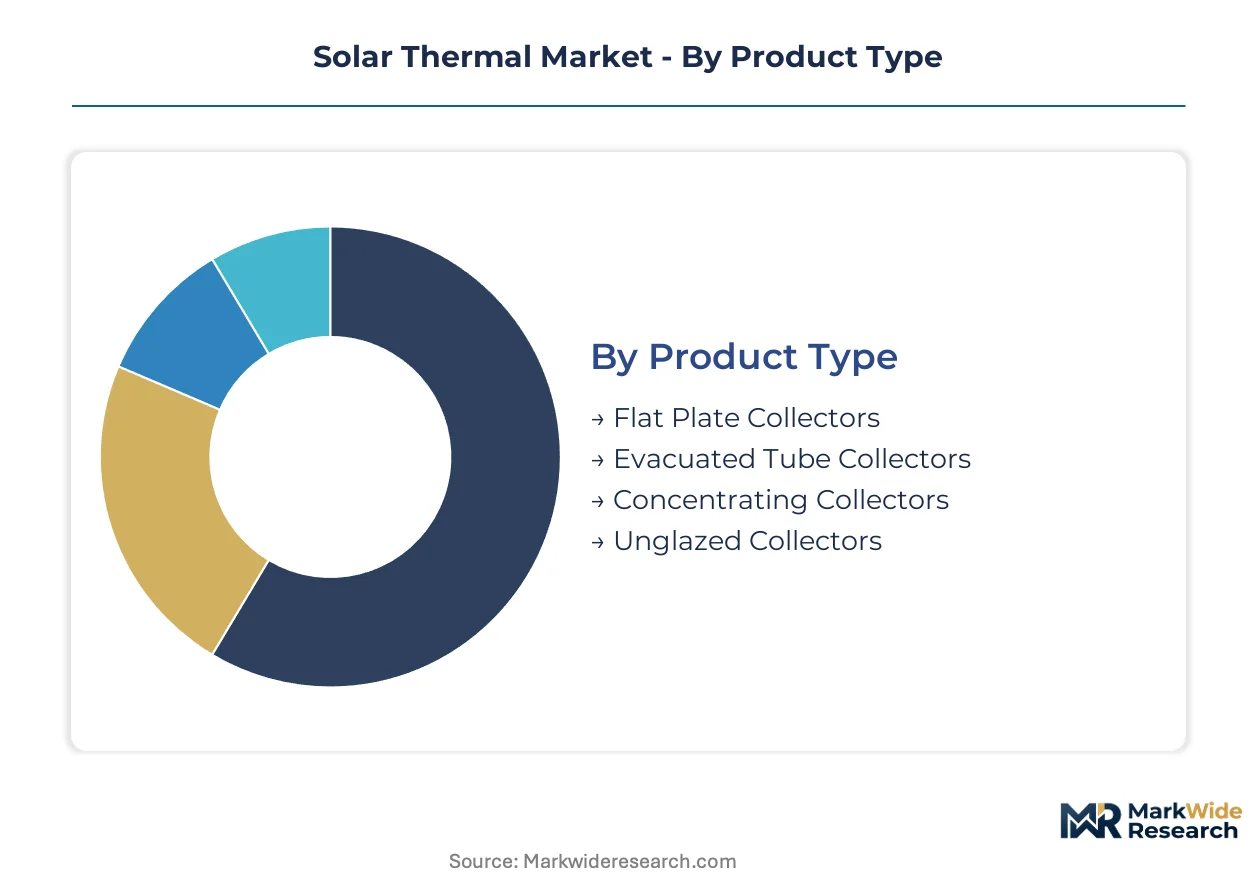
The Solar Thermal Market's segmentation reflects the diverse applications and technological requirements for harnessing solar energy to generate heat. Understanding these distinct segments is crucial for stakeholders to identify target markets, tailor product offerings, and align investment strategies with areas of highest demand and growth potential.
Product Type:
Buyers evaluate product types based on the required temperature output and system efficiency for their specific thermal energy needs.
- Concentrating Collectors:These advanced systems utilize mirrors or lenses to focus sunlight onto a small area, generating high temperatures suitable for industrial process heat and power generation. Demand for these collectors is concentrated in large-scale industrial decarbonization projects in regions like China and the Middle East, displacing fossil fuels in energy-intensive processes.
- Evacuated Tube Collectors:Featuring a series of glass tubes with a vacuum between two layers, these collectors minimize heat loss and achieve medium to high temperatures for commercial space heating, cooling, and hot water. Commercial buildings in Europe and North America increasingly adopt evacuated tube collectors for their efficiency and suitability for year-round operation.
- Flat Plate Collectors:These simple, robust collectors consist of an insulated box with a dark absorber plate and a transparent cover, primarily used for low to medium-temperature applications like residential water heating. Their cost-effectiveness makes them a standard choice for household installations.
- Unglazed Collectors:Typically made of plastic or rubber, these collectors are used for very low-temperature applications, such as swimming pool heating, where high efficiency is not the primary concern.
Flat Plate Collectors lead on installed scale for residential applications; Concentrating Collectors lead on momentum for high-temperature industrial uses.
Application:
The diverse applications of solar thermal technology dictate system design and economic viability across various sectors.
- Industrial Process Heating:This application involves using solar thermal energy to generate heat for manufacturing processes in sectors such as food and beverage, chemicals, and textiles, often requiring temperatures above 100°C. The industrial sector's strategic pivot to decarbonize process heat drives significant demand, particularly in Europe and Asia.
- Water Heating:Solar thermal systems provide hot water for residential, commercial, and institutional buildings, reducing reliance on conventional energy sources for daily needs. China exhibits strong demand for large-scale residential and commercial water heating projects, supported by national policies.
- Space Heating:Solar thermal systems contribute to heating indoor spaces in buildings, often integrated with conventional heating systems to optimize energy consumption. Commercial buildings increasingly utilize evacuated tube collectors for efficient space heating in temperate climates.
- Solar Cooling:Utilizing thermal energy to drive absorption or adsorption chillers, solar cooling systems offer an energy-efficient alternative to conventional air conditioning, particularly in regions with high solar insolation.
- Desalination:Solar thermal energy powers thermal desalination processes, converting saline water into fresh water, offering a sustainable solution for water scarcity in arid coastal regions.
Industrial Process Heating shows the steepest expansion trajectory, while Water Heating maintains consistent volume.
Installation Type:
Installation types are primarily differentiated by project scale, available land area, and integration requirements.
- Ground-mounted Systems:These large-scale installations are typically used for utility-scale concentrating solar power plants or extensive industrial process heating applications, requiring significant land area. Utility-scale projects across the Middle East and North Africa frequently employ ground-mounted systems for maximum solar exposure.
- Roof-mounted Systems:Installed on building rooftops, these systems are common for residential and commercial water heating and space heating applications, utilizing existing infrastructure. Residential properties and commercial buildings in urban areas widely adopt roof-mounted systems due to space constraints.
- Building-integrated Systems:These systems are seamlessly incorporated into the building's facade or roof structure, serving both energy generation and architectural functions. Building-integrated photovoltaics (BIPV) and thermal systems offer aesthetic and functional benefits for new constructions.
- Portable Systems:Smaller, mobile solar thermal units designed for temporary or remote applications, such as emergency hot water supply or field operations.
Ground-mounted Systems command the largest project sizes, with Roof-mounted Systems offering flexibility for urban environments.
End User:
End-user segments prioritize solar thermal solutions based on their operational energy demand and decarbonization objectives.
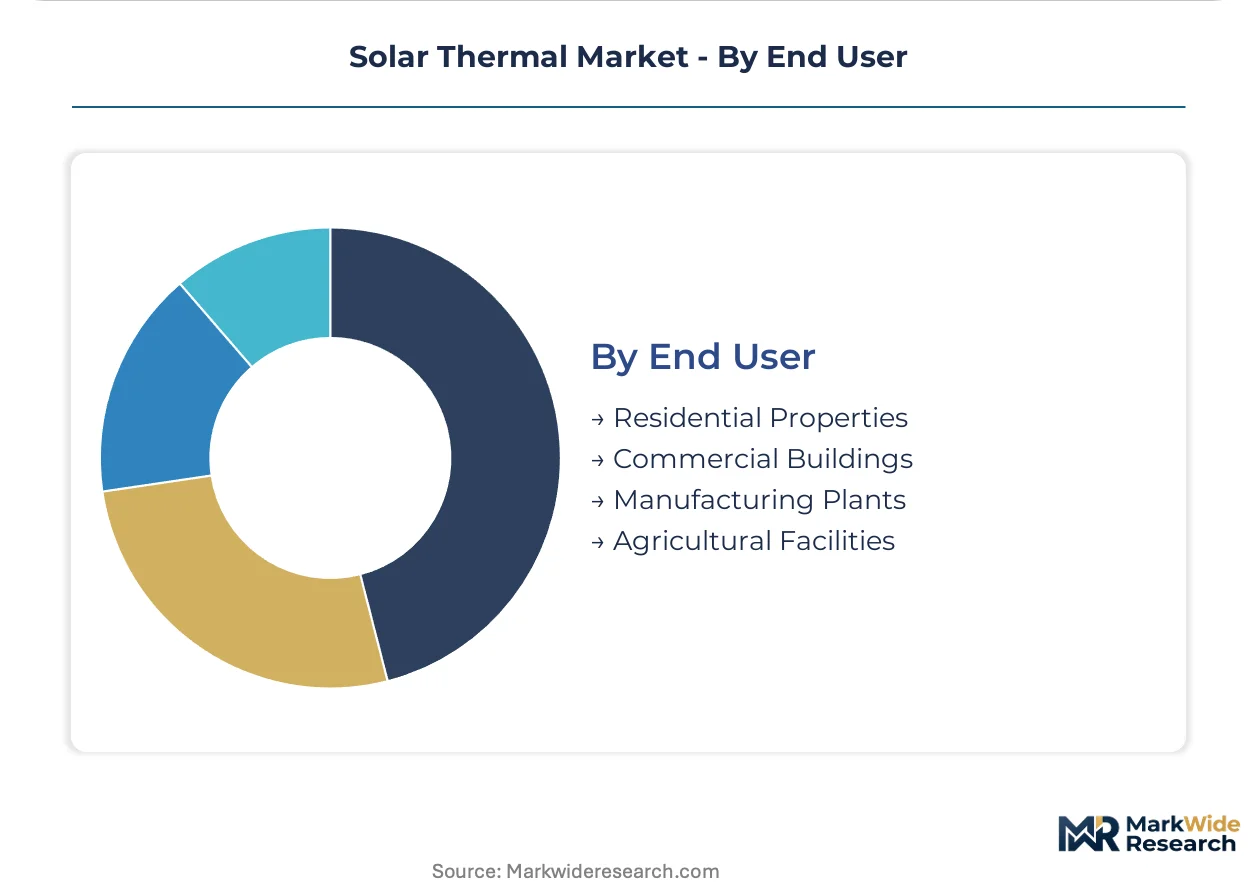
- Manufacturing Plants:Industrial facilities across various sectors, such as food processing, chemicals, and textiles, use solar thermal for process heat, driven by decarbonization mandates and corporate sustainability goals. The EU Green Deal compels manufacturers to adopt renewable heat sources.
- Commercial Buildings:Offices, hotels, hospitals, and retail spaces utilize solar thermal for water heating, space heating, and cooling, aiming to reduce operational costs and carbon footprints. The commercial buildings segment increasingly integrates evacuated tube collectors for efficient thermal management.
- Residential Properties:Individual homes and multi-family dwellings deploy solar thermal systems primarily for domestic hot water heating, driven by energy cost savings and environmental consciousness. China sees significant residential water heating projects.
- Agricultural Facilities:Farms and agricultural operations use solar thermal for applications such as greenhouse heating, crop drying, and water heating for livestock, improving energy self-sufficiency.
Manufacturing Plants exhibit significant growth potential, while Residential Properties represent a foundational consumer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta, a major industrial cluster, spearheads the global shift towards solar thermal for process heat. This momentum is supported by robust policy frameworks across diverse geographies, aiming to decarbonize energy-intensive sectors. These regional dynamics highlight distinct drivers and regulatory influences shaping solar thermal deployment worldwide.
China
Demand in China stems from extensive residential and commercial water heating projects, alongside significant industrial process heating requirements. The national dual carbon goals provide substantial government support and subsidies for large-scale solar thermal installations. Cities like Jinan and Beijing are witnessing expansive district heating initiatives powered by solar thermal technology.
Germany
Industrial decarbonization mandates drive solar thermal adoption in Germany, particularly for manufacturing process heat and commercial space heating. Policies under the EU Green Deal compel manufacturers to integrate renewable heat sources. The industrial Ruhr Valley region is increasingly deploying concentrating solar collectors to replace fossil fuel-fired boilers.
United States
Industrial and commercial entities in the United States seek solar thermal solutions to reduce operational carbon footprints and energy costs. The Inflation Reduction Act (IRA) establishes long-term tax credits, significantly improving project economics for renewable heat. California's Central Valley, with its agricultural and food processing industries, is a focal point for new solar thermal installations.
India
India's solar thermal market is propelled by the need for process heat in sectors like textiles and food processing, alongside agricultural applications. Government initiatives promoting renewable energy and energy efficiency support the deployment of these systems. Industrial corridors in Gujarat and Maharashtra are seeing increased interest in solar thermal for medium-temperature heat requirements.
Solar Thermal Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue high-temperature industrial applications and AI-driven optimization. The market exhibits a tiered structure, with specialized component manufacturers and large-scale engineering, procurement, and construction (EPC) providers. Technology advancement and strategic partnerships are dominant competitive moves among market participants.
Specialists in critical component manufacturing, such as Schott, anchor the supply chain for advanced glass receivers used in parabolic trough systems. Abengoa Solar, a Spanish-based engineering firm, exemplifies the large-scale EPC provider archetype, delivering complex solar thermal plants globally. Heliogen, an innovator in AI-powered heliostat fields, represents the technology-driven segment, targeting high-temperature industrial heat applications with advanced control systems.
| Leading Market Players |
|---|
| Acciona |
| Solar Millennium |
| Heliogen |
| Sener |
| GlassPoint |
| BrightSource Energy |
| SolarReserve |
| Schott |
| Abengoa Solar |
| Others |
Cost & Logistics Intelligence
Specialized labor concentration in advanced manufacturing hubs, particularly for high-performance glass receivers, directly influences pricing tiers for concentrating solar thermal collectors. Cost differentials in engineering expertise and component fabrication translate into varied project pricing across regions and system complexities.
Pricing Analysis
Input-cost pass-through mechanisms significantly impact project economics for solar thermal installations. Project-based pricing dominates for large-scale industrial and utility applications, reflecting custom engineering requirements. Price differentiation stems from collector efficiency (e.g., ISO 9806 certification), system integration complexity, and bundled after-sales service agreements. Pricing pressure stems from the competitive landscape with photovoltaic technologies, particularly for lower-temperature applications. Residential property owners exhibit the highest price sensitivity, while manufacturing plants prioritize long-term operational savings and decarbonization mandates over initial capital outlay.
Supply Chain Analysis
Dual-sourcing requirements for critical components are emerging as buyers seek to mitigate procurement risks for solar thermal projects. Geographic supply concentration for specialized components centers on China for basic collectors and Germany for advanced glass receiver tubes. Key dependencies include high-purity glass, specialized reflective materials, and heat transfer fluids. Single-source vulnerability for advanced receiver tubes, exemplified by manufacturers like Schott, presents a structural supply chain risk. Distribution runs primarily through integrated EPC contractors for large industrial and utility projects, complemented by regional distributors for residential and commercial systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Solar Thermal Market functions as a stable compounder, driven by the persistent global imperative to decarbonize industrial process heat. This fundamental shift underpins sustained demand across diverse applications.
For Market Incumbents: Deepen vertical integration into critical component manufacturing, especially for high-performance receiver tubes. This move mitigates supply chain bottlenecks and strengthens cost control against price volatility from specialized suppliers. Invest in advanced collector R&D to push temperature capabilities, targeting energy-intensive industries like cement and steel. Enhance EPC project delivery capabilities to de-risk complex, large-scale deployments, countering the threat of project delays and cost overruns.
For New Entrants and Emerging Players: Enter via niche high-temperature industrial applications, leveraging advanced materials or AI-powered control systems. The most penetrable segment lies in specific industrial clusters requiring heat above 400°C, where conventional solar thermal solutions are less effective. Develop specialized software solutions for AI-driven optimization of heliostat fields, offering a distinct go-to-market angle focused on efficiency gains and operational cost reduction.
For Investors and Strategic Acquirers: Industrial conglomerates and energy utility groups are the most active acquirers in this space, seeking to integrate renewable heat solutions into their portfolios. Focus on acquiring specialized component manufacturers or EPC firms with proven track records in complex industrial projects over the long term. A key signal to watch is the tightening of industrial emissions regulations in major manufacturing economies, which will accelerate adoption and drive consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand High-Temperature Collector R&D | This initiative unlocks new applications in energy-intensive sectors, displacing fossil fuels in industries like cement and steel. |
| Integrate AI for Field Optimization | AI-powered heliostat control systems boost thermal efficiency and reduce operational costs for large-scale concentrating solar plants. |
| Secure Critical Component Supply Agreements | Long-term agreements for specialized receiver tubes reduce supply chain vulnerability and stabilize project costs for developers. |
| Develop Hybrid System Solutions | Combining solar thermal with biomass or geothermal creates resilient, continuous renewable heat for diverse industrial clients. |
| Strengthen EPC Capabilities for Large Projects | Robust engineering, procurement, and construction expertise de-risks complex utility-scale and industrial solar thermal developments. |
Research Approach
Direct dialogue with industrial plant managers, EPC project developers, collector manufacturers, and renewable energy policy analysts grounded the qualitative insights. This primary research was rigorously validated through extensive secondary data analysis. Key secondary sources included IEA reports, national energy agency statistics, corporate sustainability reports, and ISO 9806 standards documentation, ensuring comprehensive market understanding through bottom-up and top-down triangulation.
Volume and value outputs were derived from an analytical framework integrating historical market trends and projected industry drivers across the analysis window. The model segmented data by product type, application, installation type, end user, and regional policy environment. Compound annual growth rates were calculated based on these projections, incorporating industry-specific forecast inputs such as industrial decarbonization targets and national renewable heat mandates.
Inputs from industry reports, government statistics, and company filings were available through the study window; gaps in specific regional deployment data introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory stability and technological progression. Deviation in major policy shifts or raw material price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar PV Panels Market
Solar Power Systems
Solar Roof Tiles Market
Solar Power Systems
India Solar Tracker Market
Solar Power Systems
Global Thin Film Solar Cells Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
Utility Solar PV EPC Market
Solar Power Systems
On-Site Photovoltaic Solar Power for Data Centers Market
Solar Power Systems
Solar Energy Market
Solar Power Systems
Greece Solar Energy Market
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
Solar Bug Zapper Market
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
Asia-Pacific Bifacial Solar Market
Solar Power Systems
Solar Vacuum Receiver Market
Solar Power Systems
US Solar Carport Market