
 Solar Home Lights Market | 2026-2036
Solar Home Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Home Lights Market Analysis
Quality-tier differentiation is bifurcating the competitive landscape as premium lithium-based systems separate from lead-acid alternatives. Signify Holding leverages its LED component supply chain to sustain cost advantages across integrated fixture production. Jinhua Sunmaster anchors volume manufacturing through direct factory relationships with East African distributors. Fonroche Lighting America competes on ruggedized housing specifications designed for tropical humidity cycles.
Solar home lights are photovoltaic-powered illumination systems typically comprising a solar panel, rechargeable battery, charge controller, and LED luminaire, engineered to deliver sustained off-grid lighting without grid connection dependency. Fixed lights and portable lights represent the dominant product configurations, with fixed systems commanding higher per-unit value due to installation permanence and larger panel wattage. Off-grid technology segments outperform hybrid alternatives in frontier markets where grid infrastructure remains absent, while LED technology dominates luminous efficacy benchmarks across all product tiers.
FCC certification governs radio-frequency components in smart-enabled solar home light systems sold in the United States, while India's BIS mandates safety testing for lithium battery packs deployed in residential solar products. The EU Green Deal and associated Ecodesign requirements shape export compliance for manufacturers targeting European markets, particularly regarding circularity mandates for battery disposal. Stakeholders must monitor evolving national subsidy eligibility criteria and local content rules that determine market access across priority deployment geographies.
Market Dynamics
Pay-as-you-go financing infrastructure is collapsing upfront capital barriers for off-grid households across sub-Saharan Africa and South Asia, fundamentally restructuring how solar home lights reach price-sensitive rural consumers.
Growth Catalysts
- Lithium iron phosphate battery chemistry:Superior cycle life and thermal stability enable longer product warranties, reducing total cost of ownership for remote installations.
- India's PLI scheme:Domestic manufacturing incentives for solar PV components accelerate localized assembly and reduce import dependency for battery packs.
- Rural electrification agencies:Kenya's Rural Electrification and Renewable Energy Corporation channels subsidized capital toward verified off-grid distributors.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings compress margin buffers for integrated battery-pack manufacturers.
- East Asian cell concentration:Cathode and electrolyte supply chains cluster in China, creating single-source vulnerability for non-integrated assemblers.
- Lead-acid substitution persistence:Price-sensitive segments in frontier markets retain cheaper flooded-cell alternatives despite inferior lifecycle economics.
Strategic Opportunities
- Nigeria's underserved northern states:Low electrification penetration and expanding mobile money infrastructure create white-space for PAYGO deployment.
- Product-service bundling:Mobile network operators bundle solar home lights with airtime credits, leveraging existing subscriber relationships.
- Ecodesign circularity mandates:EU Green Deal battery passport requirements favor modular designs enabling end-of-life material recovery.
Industry Challenges
- Field technician scarcity:Distributed repair networks require trained personnel for lithium battery diagnostics in remote territories.
- FCC certification timelines:Radio-enabled smart controllers face extended approval cycles for US market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Home Lights Market |
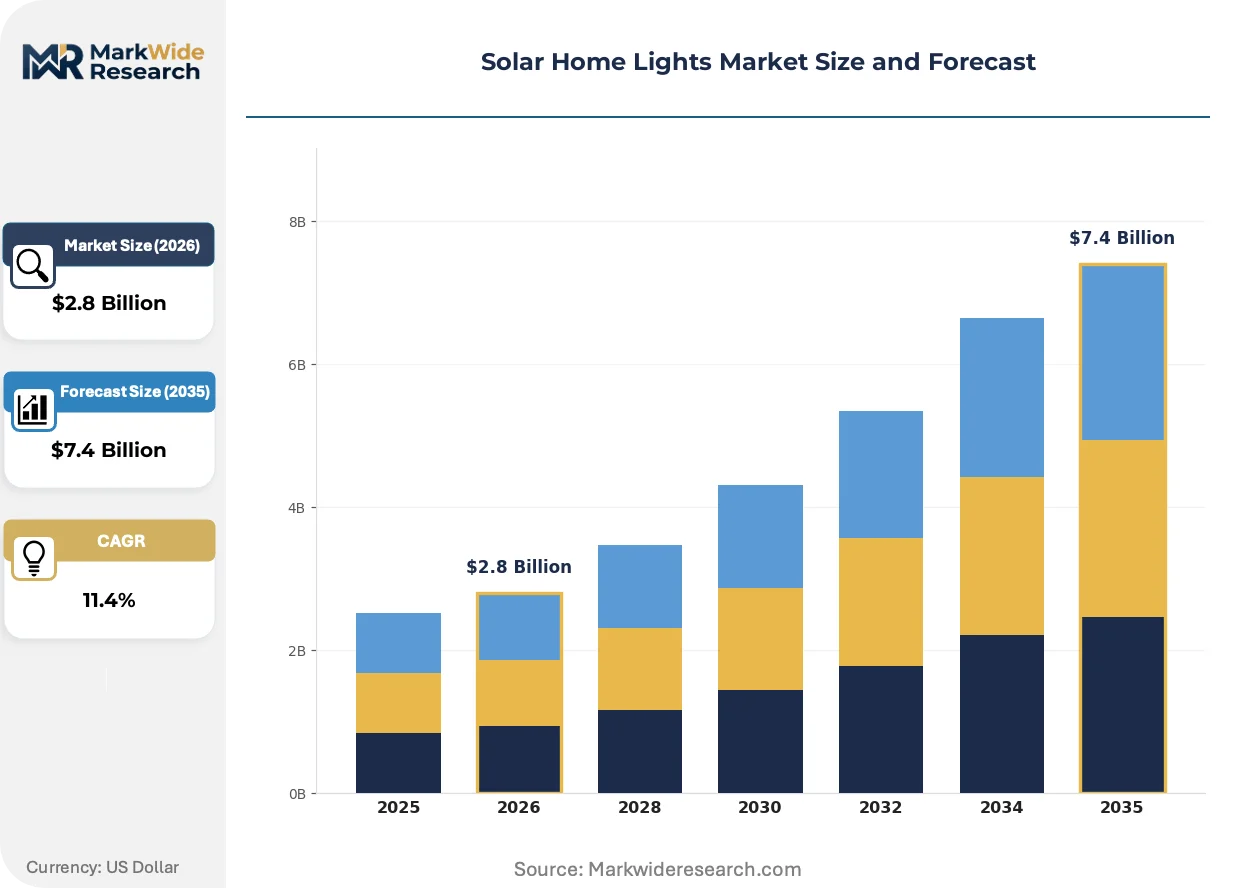
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Lights, Fixed Lights, Chandeliers, Street Lights Technology: Photovoltaic, LED, Hybrid, Off-Grid End User: Residential, Commercial, Industrial, Rural Households Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Distributors |
| Companies Covered | Signify Holding (Philips), Greenshine New Energy, Sunna Design, SEPCO (Solar Electric Power Company), Solar Street Lights USA, Gama Sonic, Jinhua Sunmaster Lighting, Fonroche Lighting America, Leadsun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Home Lights Market Emerging Trajectories
Component integration and intelligence layers are compressing system footprints while expanding remote monitoring capabilities across rural deployment contexts.
Solid-state battery prototypes are miniaturizing energy storage density for portable solar lantern configurations. Off-grid distributors in Kenya and Tanzania pilot these units for ultralight camping and emergency backup segments. The technology is miniaturizing physical battery volume by forty percent against equivalent lithium-ion capacities, enabling new wearable and handheld form factors previously uneconomical at solar-recharged price points.
India's BIS safety standards for lithium battery packs mandate thermal runaway testing and cell-balancing documentation for residential solar products. Compliance costs favor larger manufacturers with captive testing facilities, accelerating consolidation among tier-two assemblers. Export-oriented producers targeting European markets simultaneously navigate EU Green Deal circularity requirements for battery disposal and material recovery.
Rural households increasingly prioritize total-cost-of-ownership calculations over sticker price when selecting solar home light systems. PAYGO distributors respond with transparent tariff structures and warranty-backed performance guarantees. This behavioral shift concentrates most visibly in Kenya's off-grid counties where mobile money penetration enables granular usage-based billing.
Solar Home Lights Market Segmentation
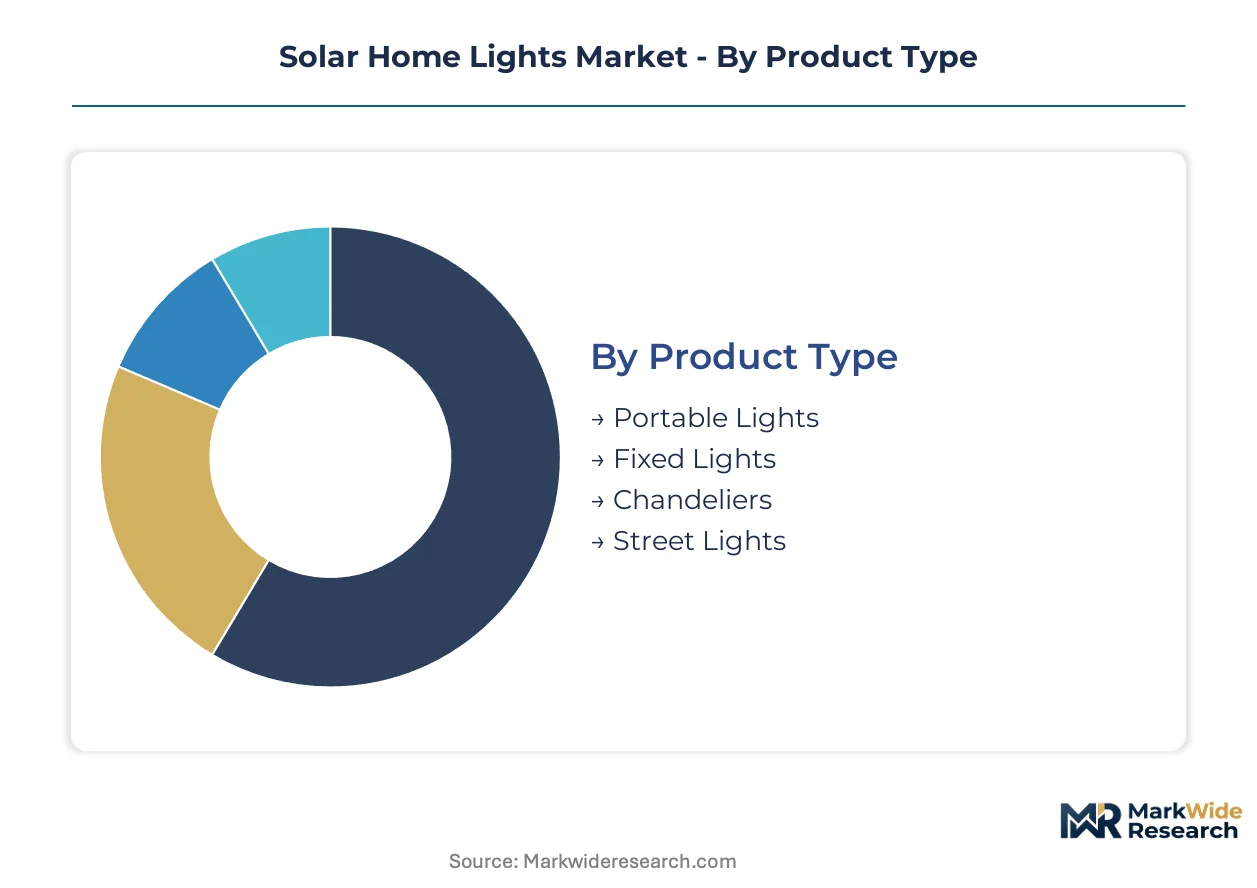
Product configuration and technology choices in solar home lights determine financing structures, installation complexity, and total cost of ownership calculations across rural electrification programs. Segment boundaries blur as distributors bundle portable units with fixed installations and hybrid systems incorporate grid-tie capabilities for peri-urban transition zones.
Product Type:
Domestic assembly lines in India and Kenya concentrate on portable and fixed configurations for regional electrification agencies, while chandelier and street light production serves export markets with stricter aesthetic and lumen-output specifications.
- Portable Lights:Self-contained units integrate collapsible solar panels with detachable LED heads for multi-room illumination. Demand clusters in Kenyan PAYGO networks where households prioritize mobility between cooking, study, and sleeping areas. Lithium iron phosphate chemistry enables warranty terms that reduce distributor risk in remote counties.
- Fixed Lights:Permanent roof-mounted panels feed wall-switched luminaires through interior wiring. Nigerian rural electrification programs channel subsidized capital toward fixed installations in northern states with lowest grid penetration. Installation permanence justifies higher panel wattage and battery capacity.
- Chandeliers:Decorative multi-point fixtures target urban off-grid villas and commercial hospitality in safari lodges.
- Street Lights:Pole-mounted systems serve communal lighting for village centers and health clinic perimeters.
Fixed lights command the established base. The steepest expansion runs through portable configurations.
Technology:
Cost tiers separate mature photovoltaic and LED stacks from emerging hybrid architectures that command price premiums in grid-adjacent territories.
- Photovoltaic:Crystalline silicon panels dominate conversion efficiency benchmarks. Indian PLI scheme recipients anchor domestic manufacturing for residential-scale modules.
- LED:Solid-state illumination delivers lumen-per-watt performance that halves battery size requirements against legacy fluorescent alternatives. Signify Holding's component supply chain sustains cost advantages for integrated fixture producers.
- Hybrid:Grid-tie capability with battery backup targets peri-urban households experiencing intermittent grid supply. Kenya's unreliable grid infrastructure creates adoption pockets in Nairobi satellite settlements.
- Off-Grid:Standalone architecture without grid connection dependency serves pure frontier markets. Sub-Saharan distributors prioritize off-grid SKUs where infrastructure absence eliminates hybrid value propositions.
Photovoltaic and LED stacks absorb the majority of current deployment. Hybrid systems are climbing the fastest as grid extension programs reach intermediate zones.
End User:
Customer type determines purchase mechanism, with rural households accessing PAYGO financing unavailable to commercial and industrial accounts.
- Residential:Urban apartment installations favor compact portable units for balcony charging. Indian metro consumers purchase through online retail with BIS-certified battery packs.
- Commercial:Retail shops and small enterprises demand extended runtime for evening operations. Nigerian market vendors represent concentrated commercial demand in off-grid northern cities.
- Industrial:Security lighting and perimeter illumination for remote facilities. Mining and agribusiness operations in Tanzania deploy ruggedized fixed systems.
- Rural Households:Price-sensitive consumers dependent on mobile money infrastructure. Kenya's off-grid counties demonstrate highest PAYGO penetration globally.
Rural households absorb volume leadership. Commercial installations are gaining share fastest as small enterprises formalize.
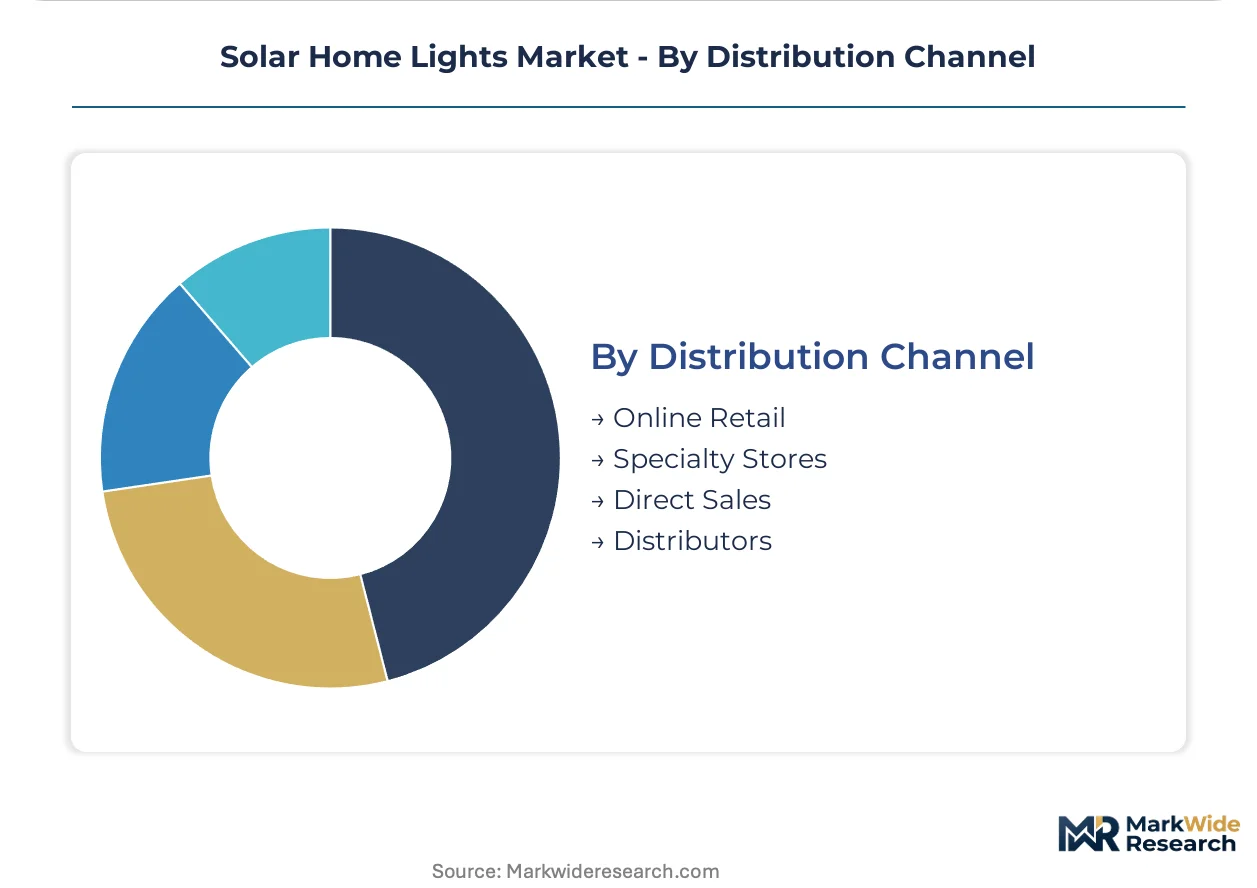
Distribution Channel:
Channel selection correlates with customer sophistication, with direct sales and distributor networks dominating low-literacy markets where product demonstration determines conversion.
- Online Retail:E-commerce platforms serve urban Indian consumers with BIS-certified product visibility. Amazon and Flipkart listings require thermal runaway documentation for lithium battery shipments.
- Specialty Stores:Dedicated solar shops provide installation services and warranty claim handling. Kenyan distributor networks embed specialty counters within agricultural supply cooperatives.
- Direct Sales:Door-to-door agents demonstrate PAYGO activation for first-time solar users. Nigerian mobile money agents double as product educators in northern states.
- Distributors:Regional wholesalers stock inventory for last-mile retailers. East African distribution concentrates through Nairobi and Dar es Salaam logistics hubs serving frontier territories.
Distributor networks handle established volume. Direct sales are expanding most quickly as PAYGO providers build dedicated agent forces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturers in China and India supply battery packs and LED modules to assembly operations across sub-Saharan Africa and South Asia. Import dependency for lithium cells creates currency exposure for distributors in frontier markets. Regional electrification agencies in Kenya, India, and Nigeria channel the majority of subsidized procurement capital.
Kenya
Rural Electrification and Renewable Energy Corporation channels subsidized capital toward verified off-grid distributors. Mobile money penetration enables granular PAYGO billing across off-grid counties. Nairobi anchors East African logistics hubs serving frontier territories through regional wholesaler networks.
India
Bureau of Indian Standards mandates thermal runaway testing and cell-balancing documentation for residential lithium battery packs. Production-Linked Incentive scheme recipients anchor domestic manufacturing for solar PV components. Tamil Nadu and Gujarat concentrate assembly operations for regional electrification agency procurement.
Nigeria
Low electrification penetration in northern states creates white-space deployment opportunities for PAYGO providers. National renewable energy agencies subsidize distributed solar installations through rural electrification programs. Kano and Kaduna represent concentrated commercial demand among off-grid market vendors.
United States
FCC certification governs radio-frequency components in smart-enabled systems sold domestically. Federal renewable energy tax credits accelerate adoption among rural households beyond grid extension zones. California and Texas lead distributed solar deployment through state-level incentive stacking.
Tanzania
Dar es Salaam logistics hubs coordinate last-mile distribution to mining and agribusiness operations. Mining sector demand drives ruggedized fixed system specifications for perimeter security lighting. Field technician scarcity constrains distributed repair network expansion in remote territories.
Solar Home Lights Market Vendor Landscape
Concentration sits with diversified lighting conglomerates and specialized solar fixture manufacturers competing across integrated versus modular system architectures. The vendor base separates between premium lithium-based system providers and lead-acid alternatives serving price-sensitive segments. Three archetypes dominate: LED component suppliers backward integrating into fixture production, volume manufacturers anchoring East African distributor relationships, and ruggedized housing specialists targeting tropical deployment conditions. Competitive moves center on strategic partnerships with PAYGO financing platforms and geographic expansion through regional logistics hub establishment.
Among diversified lighting conglomerates, Signify Holding anchors integrated fixture production through captive LED component supply chains. Jinhua Sunmaster occupies a position within the volume-manufacturing tier, exemplifying direct factory relationships with East African distributors. Fonroche Lighting America represents the ruggedized housing specialist archetype, sitting within the tropical climate deployment segment.
| Leading Market Players |
|---|
| Signify Holding (Philips) |
| Greenshine New Energy |
| Sunna Design |
| SEPCO (Solar Electric Power Company) |
| Solar Street Lights USA |
| Gama Sonic |
| Jinhua Sunmaster Lighting |
| Fonroche Lighting America |
| Leadsun |
| Others |
Supply Flow & Price Mechanics
Pay-as-you-go capacity reservations lock in supply access for East African distributors while fixing tariff visibility for rural households across Kenya and Nigeria. This contract structure binds lithium iron phosphate cell allocations to mobile money repayment schedules, tethering procurement risk to subscriber default rates rather than spot commodity swings.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium lithium-based systems command spreads over lead-acid alternatives through BIS thermal runaway certification and extended warranty terms. Cost compression in economy tiers intensifies as Kenyan PAYGO providers consolidate procurement volumes. Rural households exhibit highest price sensitivity, while safari lodge operators absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Lithium carbonate refining capacity concentration in Jiangxi province underwrites cathode material flows for battery pack assemblers in Tamil Nadu and Gujarat. East African distributors draw from Shenzhen and Ningbo logistics hubs for LED module imports. Single-source vulnerability clusters in Chinese electrolyte additive production. Distribution runs through Nairobi and Dar es Salaam wholesaler networks serving last-mile agent forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from grid extension programs and diesel generator rentals in peri-urban transition zones. Defending market position requires preemptive moves against infrastructure convergence threats.
For Market Incumbents: Fortify captive lithium iron phosphate cell sourcing through Indian PLI scheme partnerships, reducing exposure to Chinese cathode price volatility. Deepen backward integration into LED driver assembly to preserve margin buffers against Signify Holding's component dominance. Lock exclusive PAYGO platform relationships before mobile network operators bundle competing hardware. For New Entrants and Emerging Players: Differentiate on modular battery architectures enabling EU Green Deal circularity compliance, capturing export-oriented distributors serving European development finance procurement. Nigeria's northern states present the most penetrable geography given low electrification density and expanding mobile money rails. Pursue direct sales agent recruitment through agricultural cooperative networks rather than competing for established distributor shelf space. For Investors and Strategic Acquirers: Ruggedized housing specialists with tropical climate IP and Kenyan regulatory approvals represent the priority acquisition archetype. Long-term viability hinges on PAYGO financing platform viability rather than hardware margins alone. Watch Kenya's Rural Electrification and Renewable Energy Corporation subsidy allocation shifts as the inflection signal for distributor working capital stress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Cell Assembly | Indian PLI scheme recipients reduce import dependency and capture BIS certification premiums. |
| PAYGO Platform Partnership | Mobile money integration with M-Pesa and Airtel Money locks in subscriber acquisition channels. |
| EU Battery Passport Compliance | Modular designs meeting Ecodesign circularity mandates unlock European development bank procurement. |
| Ruggedized Housing R&D Investment | Tropical humidity cycle specifications differentiate Fonroche Lighting America's frontier market positioning. |
| Direct Sales Agent Network Buildout | Door-to-door demonstration capacity accelerates conversion in low-literacy Nigerian northern states. |
Methodological Framework
A standing panel of PAYGO platform executives, rural electrification agency procurement officers, lithium battery pack assemblers, and East African distributor network managers provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with factory-floor observation in Tamil Nadu and Gujarat assembly operations. Secondary sources encompassed India's BIS certification databases, Kenya's Rural Electrification and Renewable Energy Corporation subsidy disbursement records, and EU Green Deal regulatory filings. Bottom-up unit shipment estimates triangulated against top-down electrification program budget allocations.
Consistency checks validated volume and value outputs against IEA off-grid energy access tracking, World Bank development finance disbursement patterns, and mobile money transaction flow data across the analysis window. Segmentation modeling incorporated product configuration, battery chemistry tier, end-user type, and distribution channel complexity. CAGRs derived from installed base depreciation curves and replacement cycle assumptions, with lithium carbonate price scenarios stress-testing margin projections.
The analysis sits within stated boundaries; outcomes outside sustained PAYGO financing platform solvency or lithium supply chain stability would require recalibration. Forecasts reflect documented assumptions regarding rural electrification agency budget continuity and mobile money penetration trajectories. Practitioners should keep alternative scenarios live as Kenya's subsidy eligibility criteria and Nigeria's exchange rate volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Renewable Energy Certificate Market
Renewable Energy
Solar Tree Market
Renewable Energy
China Solar Photovoltaic Market
Renewable Energy
South Africa Distributed Solar Energy Market
Renewable Energy
Solar Tracker Market
Renewable Energy
Solar Ceiling Fans Market
Renewable Energy
Green Energy Lighting Market
Renewable Energy
Point Absorber Market
Renewable Energy
China Wind Power Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
Global Renewable Energy Market
Renewable Energy
Romania Power Market
Renewable Energy
Russian Federation Renewable Energy Market
Renewable Energy
Europe Solar Tracker Market
Renewable Energy
Poland Renewable Energy Market
Renewable Energy
Renewable Energy in South America Market