
 Aluminum Wire Battery Market | 2026-2036
Aluminum Wire Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Wire Battery Market Outlook
Electric vehicle battery pack architecture is rebalancing toward aluminum current collectors as OEMs pursue mass reduction targets. Constellium SE anchors European supply through its automotive rolled products division, while Novelis Inc. competes on recycling-integrated primary aluminum flow. Phinergy Ltd. differentiates through its aluminum-air technology platform, avoiding lithium-ion material constraints entirely.
Aluminum wire batteries deploy high-purity aluminum conductors, typically alloyed with magnesium or silicon, as lightweight substitutes for copper foils in cell interconnects and busbar assemblies. The conductor achieves conductivity at roughly sixty percent of copper density, enabling pack-level weight savings critical to electric vehicle range extension. Prismatic cells dominate volume shipments due to automotive pack integration efficiency, while solid-state technology segments attract premium positioning as next-generation electrolyte architectures mature. Cylindrical cells sustain industrial applications where automated winding equipment and established thermal management protocols reduce switching costs.
FDA and EPA frameworks in the United States govern battery material safety disclosures and manufacturing emissions, while China's SAMR enforces GB standards for cell performance and traceability. The EU's REACH and RoHS directives restrict hazardous substances in battery assemblies, shaping material qualification timelines for exporters. Stakeholders must monitor regulatory divergence between jurisdictions to avoid redundant certification cycles that compress development bandwidth.
Market Dynamics
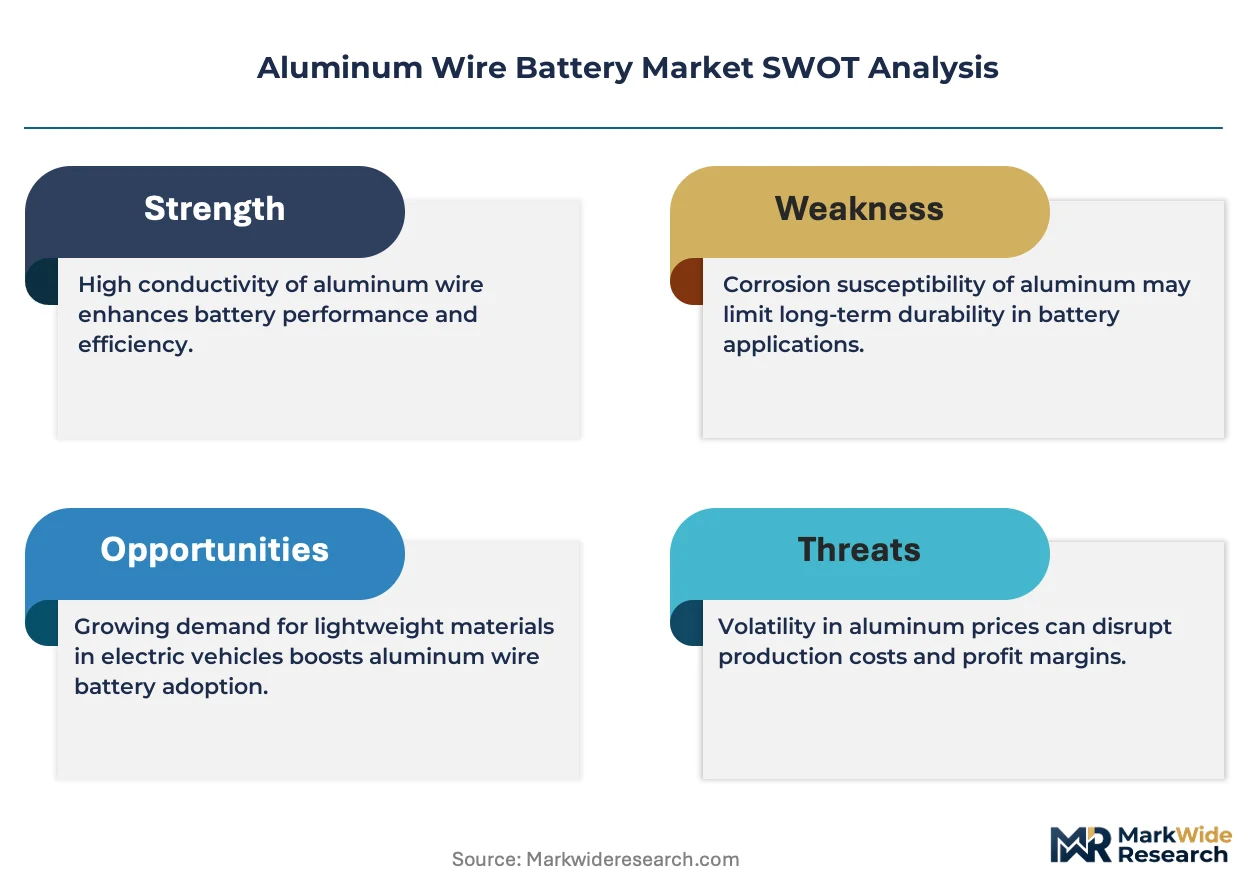
Cell-to-pack architectures are compressing copper content per kilowatt-hour, forcing battery engineers to requalify aluminum conductors across thermal cycling and weld reliability protocols. This structural shift from copper foils to aluminum wire interconnects is redrawing material procurement strategies and supplier qualification timelines.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases in battery manufacturing processes are accelerating adoption of dry electrode coating methods compatible with aluminum current collectors.
- Electric vehicle mass reduction targets:OEMs pursuing specific gravity reductions in pack architecture are qualifying aluminum wire busbars to offset cell weight concentration in floor-mounted configurations.
- South Korean cathode material clusters:Concentrated investment in high-nickel cathode production around Seoul and Ulsan is pulling compatible aluminum conductor specifications through integrated supply agreements.
Market Restraints
- Aluminum-lithium price volatility:Input cost swings for battery-grade aluminum alloys constrain long-term contracting between wire drawing facilities and cell manufacturers.
- Welding process limitations:Ultrasonic and laser welding of aluminum to dissimilar metals generates intermetallic brittleness, requiring redundant joint designs that add assembly steps.
- Copper substitution inertia:Established thermal modeling and fuse protection schemes optimized for copper conductivity create requalification friction for aluminum alternatives.
Strategic Opportunities
- Indian PLI scheme for advanced chemistry cells:Production-linked incentives for domestic battery manufacturing are opening qualification windows for aluminum conductor suppliers establishing local drawing capacity.
- Aluminum-air technology convergence:Primary aluminum-air systems for range extension applications are creating parallel demand streams for high-purity aluminum wire feedstock outside lithium-ion supply chains.
- Direct-to-OEM distribution:Bypassing traditional tiered component supply structures through technical sales engineering teams is compressing specification cycles for custom alloy formulations.
Industry Challenges
- Electrodeposition coating expertise:Thin-film ceramic coating of aluminum conductors for corrosion resistance requires specialized electrochemical engineering talent concentrated in Japanese and German industrial regions.
- GB standard compliance timelines:China's SAMR certification cycles for new aluminum alloy grades in automotive applications extend development schedules by twelve to eighteen months relative to copper equivalents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Wire Battery Market |
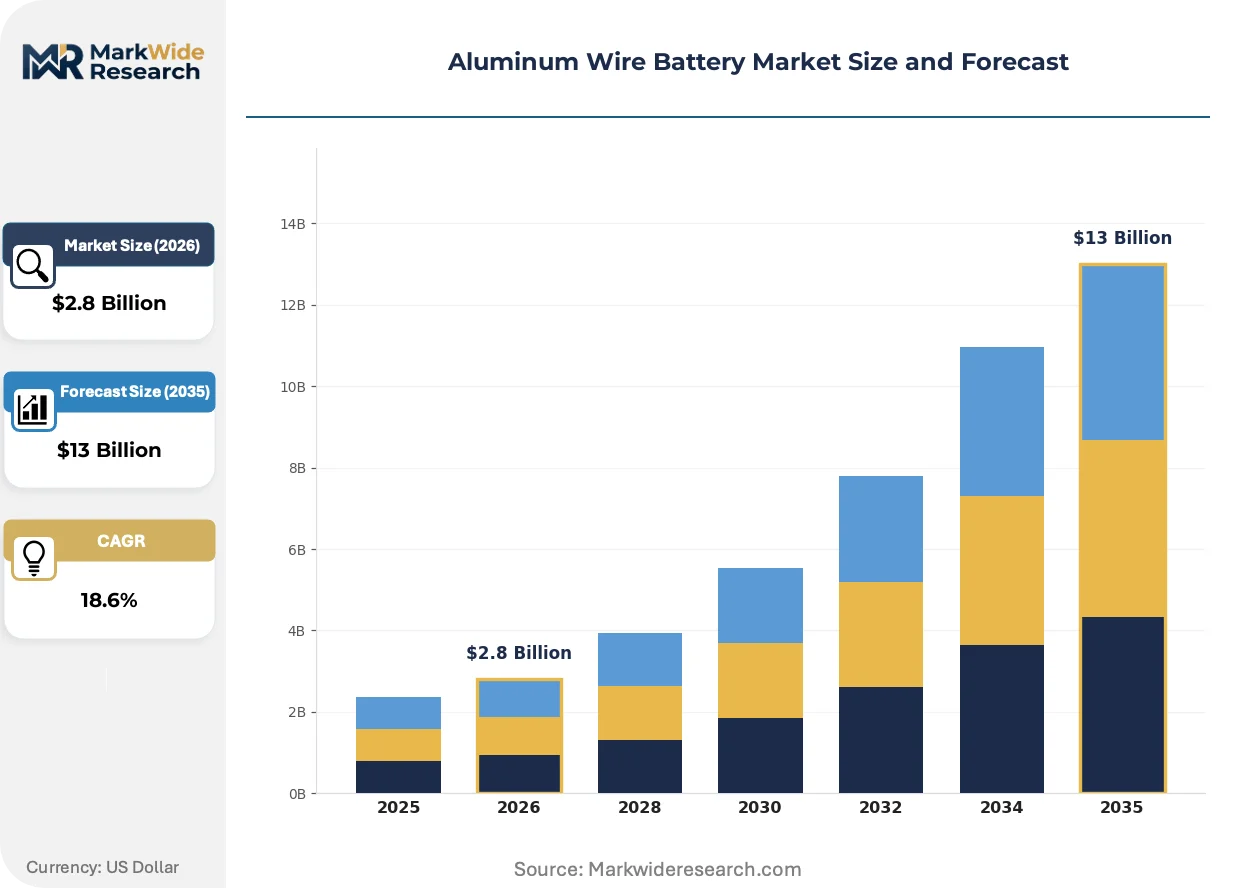
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic Cells, Cylindrical Cells, Coin Cells, Flexible Batteries End User: Consumer Electronics, Electric Vehicles, Renewable Energy, Industrial Applications Form Factor: Thin Film, Rigid, Standard Size, Custom Design Technology: Lithium-Ion, Solid-State, Hybrid, Others |
| Companies Covered | Constellium SE, Kaiser Aluminum Corporation, Alcoa Corporation, Sumitomo Light Metal Industries, Ltd., Norsk Hydro ASA, Novelis Inc., Aluminum Corporation of China Limited, Phinergy Ltd., UACJ Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Wire Battery Market Strategic Shifts
Solid-state electrolyte maturation is forcing concurrent redesign of current collector interfaces, with aluminum wire formats gaining traction as cell architectures abandon liquid electrolyte wetting requirements. Material suppliers are repositioning around thermal and electrical property bundles rather than commodity conductivity metrics.
High-purity aluminum-magnesium alloys for cell interconnects are converging with silicon-anode cell chemistries, as both technologies stress thermal expansion matching across charge cycling. Korean cell manufacturers are accelerating qualification timelines for these paired material systems in prismatic formats. The convergence is compressing supplier development cycles and forcing integrated testing protocols that validate conductor-anode-electrolyte combinations rather than isolated components.
China's GB standards for battery material traceability are mandating batch-level documentation for aluminum conductor provenance, including smelter origin and alloying additive certification. The SAMR enforcement framework is extending qualification timelines for imported materials while privileging domestic supply chain documentation. European exporters are responding by establishing captive analytical laboratories in Shanghai to pre-certify alloy compositions against GB test protocols.
Long-term cathode supply agreements are displacing spot purchasing for aluminum wire specifications, as cell manufacturers seek price stability against lithium and nickel volatility. Tier-one automotive battery divisions are locking three-to-five-year conductor supply contracts with volume-tiered pricing indexed to London Metal Exchange aluminum rather than regional premiums. This contract structure is most visible in German OEM supply chains, where pack integration responsibility has shifted from vehicle assembly plants to dedicated battery manufacturing joint ventures.
Aluminum Wire Battery Market Segmentation
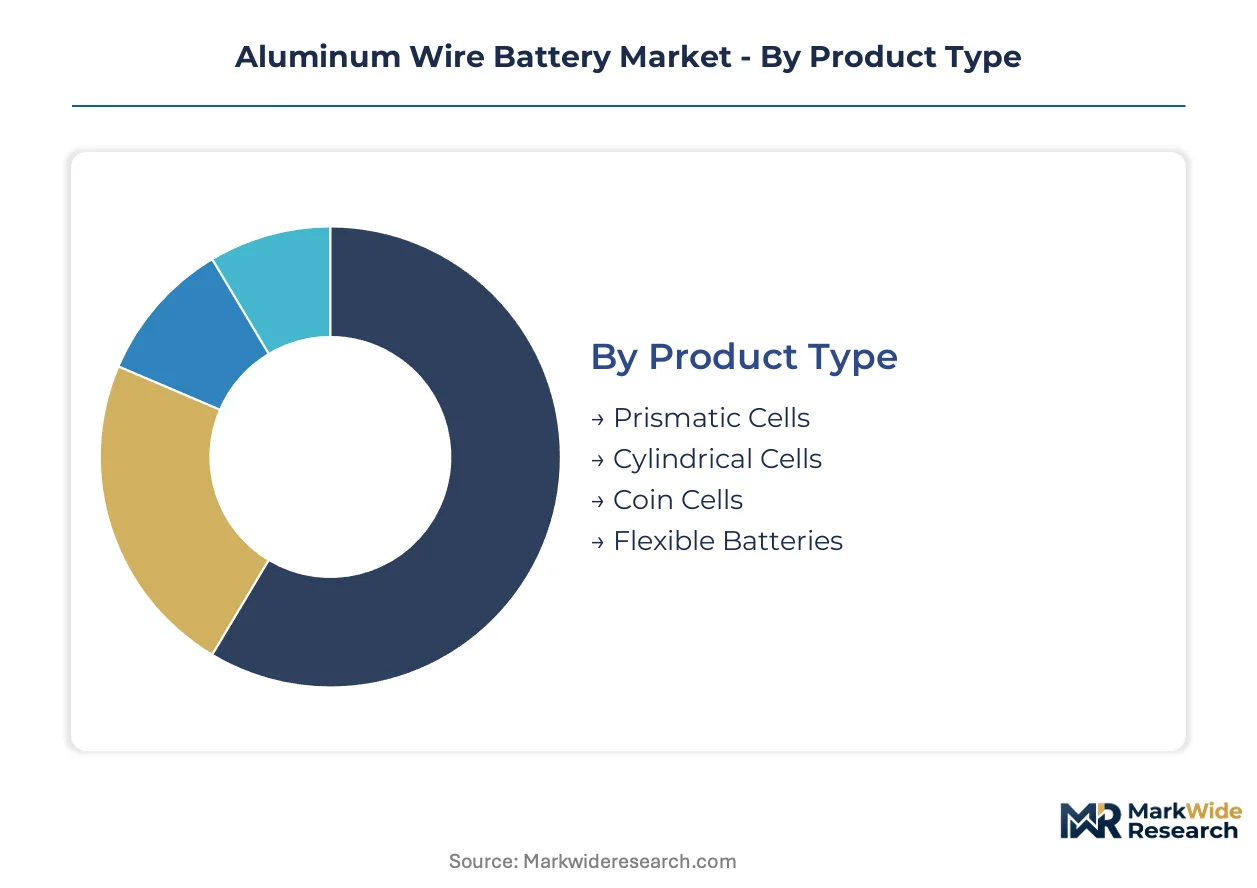
Aluminum wire battery segmentation reveals distinct capital requirements across cell geometries, with automotive-scale formats demanding fundamentally different tooling investments than consumer-grade alternatives. Procurement patterns diverge sharply between established lithium-ion supply chains and emerging solid-state qualification cycles.
Product Type:
Prismatic cell manufacturing absorbs the heaviest upfront capital, with dedicated stacking equipment and laser welding lines requiring dedicated facility investment. Cylindrical formats leverage existing winding infrastructure, lowering entry barriers for new conductor suppliers.
- Prismatic Cells:Large-format aluminum busbar integration dominates electric vehicle pack architectures, with cell-to-pack designs eliminating module-level copper interconnections. Korean and Chinese automotive battery joint ventures concentrate procurement around Seoul and Ningbo manufacturing hubs, driven by OEM mass reduction mandates for floor-mounted battery configurations.
- Cylindrical Cells:Automated winding equipment compatibility preserves established production economics, with 2170 and 4680 formats sustaining industrial tool and stationary storage applications. Tesla's Nevada and Texas facilities anchor North American demand, though welding reliability protocols for aluminum tab connections remain under refinement.
- Coin Cells:Precision micro-welding of aluminum current collectors serves hearing aid and medical device manufacturers requiring hermetic sealing.
- Flexible Batteries:Thin-gauge aluminum foil laminates enable wearable electronics form factors, with stretchable interconnects under development at Japanese materials laboratories.
Prismatic formats absorb the bulk of installed capacity; cylindrical cells are expanding most quickly through standardized automation platforms.
End User:
Customer concentration varies dramatically, with automotive OEMs consolidating procurement through joint ventures while consumer electronics maintains fragmented vendor bases.
- Electric Vehicles:Dedicated battery manufacturing subsidiaries of German and Korean OEMs lock multi-year aluminum conductor contracts indexed to LME pricing, with pack integration responsibility shifting from vehicle assembly plants to captive cell production facilities. Cell-to-pack architectures eliminate redundant copper busbar layers, directly substituting aluminum wire interconnects at gigafactory scale.
- Consumer Electronics:Smartphone and laptop manufacturers prioritize energy density over conductor material substitution, preserving copper foil dominance in premium device segments. Chinese contract manufacturers in Shenzhen and Dongguan drive spot purchasing patterns for aluminum alternatives in mid-tier product lines.
- Renewable Energy:Grid-scale battery installations prioritize cost-per-kilowatt-hour metrics, with aluminum busbar adoption accelerating in containerized storage systems.
- Industrial Applications:Forklift and automated guided vehicle fleets sustain cylindrical cell demand through established thermal management protocols and rapid charging compatibility.
Electric vehicle procurement concentrates volume commitments; renewable energy installations are gaining share fastest as utility-scale project pipelines mature.
Form Factor:
Manufacturing flexibility determines competitive positioning, with custom design capabilities commanding premium pricing against commoditized standard sizes.
- Rigid:Structural aluminum enclosures integrate current carrying functions with mechanical protection, eliminating separate housing components in prismatic automotive cells. European pack designers at BMW and Volkswagen Group facilities specify rigid aluminum frames to achieve crashworthiness targets without weight penalties.
- Thin Film:Sub-100-micron aluminum foil deposition enables flexible and curved surface applications, with roll-to-roll coating investments concentrated in Japanese and German industrial regions. Solid-state electrolyte compatibility favors thin-film current collectors by eliminating liquid wetting requirements.
- Standard Size:18650 and 2170 cylindrical formats sustain equipment reuse across product generations, preserving supplier qualification continuity.
- Custom Design:Bespoke aluminum conductor geometries serve aerospace and defense applications with specialized thermal cycling and vibration requirements.
Rigid formats dominate automotive volume; thin film configurations are climbing the fastest through solid-state battery development programs.
Technology:
Electrolyte chemistry dictates current collector interface requirements, with solid-state architectures forcing concurrent redesign of aluminum conductor surface treatments.
- Lithium-Ion:Established liquid electrolyte systems require corrosion-resistant aluminum oxide layers on current collectors, with electrodeposition coating expertise concentrated in Japanese wire drawing facilities. Chinese GB standards mandate batch-level traceability for aluminum provenance, extending qualification timelines for imported materials.
- Solid-State:Ceramic and sulfide electrolytes eliminate liquid compatibility constraints, enabling bare aluminum conductor interfaces with simplified surface preparation. Korean cell manufacturers accelerate qualification timelines for paired aluminum-silicon anode systems in prismatic formats.
- Hybrid:Semi-solid gel electrolytes bridge manufacturing compatibility, preserving existing aluminum foil supply chains while improving safety margins.
- Others:Aluminum-air primary systems bypass lithium-ion material constraints entirely, with Phinergy Ltd. and similar developers creating parallel demand streams for high-purity aluminum wire feedstock.
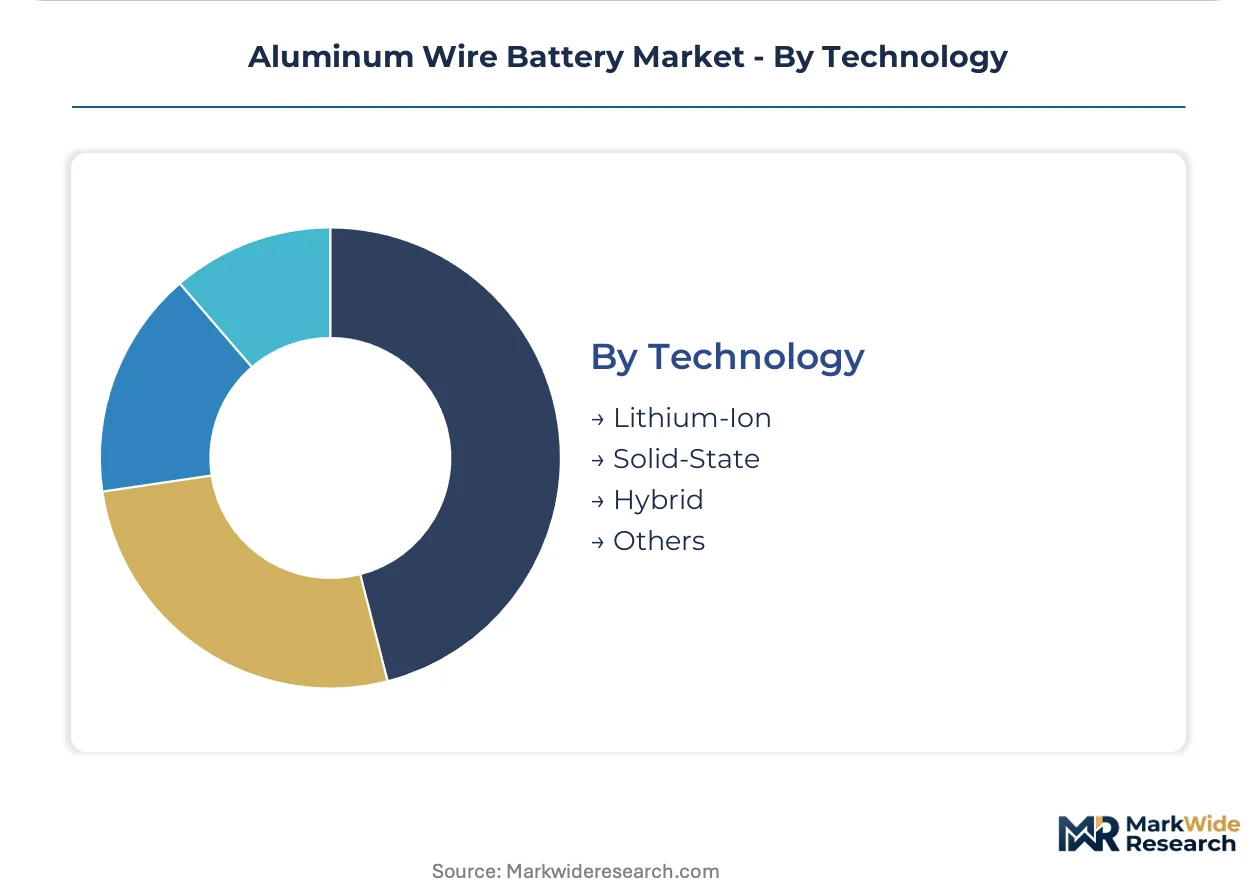
Lithium-ion retains the bulk of installed conductor capacity; solid-state technologies are expanding most quickly through integrated testing protocols validating conductor-anode-electrolyte combinations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's battery industrial parks and South Korea's cathode material clusters anchor production concentration, with specialized economic zones in each country offering tax abatements for aluminum conductor qualification facilities.
China
Cell-to-pack architecture adoption by CATL and BYD is compressing copper content per kilowatt-hour. SAMR's GB standards for battery material traceability mandate batch-level aluminum provenance documentation. Ningbo and Shenzhen manufacturing hubs concentrate wire drawing capacity serving domestic automotive battery joint ventures.
South Korea
LG Energy Solution and Samsung SDI are accelerating aluminum conductor qualification for high-nickel prismatic cells. The Ministry of Trade, Industry and Energy subsidizes domestic supply chain localization under the K-Battery strategy. Seoul and Ulsan cathode material clusters pull compatible aluminum specifications through integrated procurement agreements.
Germany
BMW and Volkswagen Group battery manufacturing subsidiaries lock multi-year aluminum conductor contracts indexed to LME pricing. The EU F-Gas Regulation restricts fluorinated gases in coating processes, favoring dry electrode methods compatible with aluminum current collectors. Bavarian and Lower Saxony pack integration facilities specify rigid aluminum frames for crashworthiness targets.
Japan
Precision wire drawing expertise for sub-100-micron aluminum foils concentrates in Nagoya and Kansai industrial regions. METI's battery supply chain resilience programs fund domestic conductor capacity expansion. Japanese materials laboratories develop stretchable aluminum interconnects for flexible battery form factors.
United States
Tesla's Nevada and Texas gigafactories anchor North American cylindrical cell demand for 2170 and 4680 formats. EPA frameworks govern manufacturing emissions disclosures for battery material facilities. The Inflation Reduction Act's domestic content bonuses incentivize localized aluminum conductor supply qualification.
Aluminum Wire Battery Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with automotive-scale procurement consolidating around qualified tier-one suppliers while industrial applications sustain fragmented vendor bases. The supplier landscape organizes around three archetypes: integrated aluminum producers with captive wire drawing capacity, specialized conductor manufacturers serving battery-specific specifications, and technology developers pursuing alternative aluminum-air chemistries. Competitive positioning depends on qualification timelines against OEM thermal cycling protocols and backward integration into primary aluminum smelting.
Within the integrated producer tier, Constellium SE and Novelis Inc. represent European and North American rolled products specialists respectively, each anchoring regional supply through automotive-qualified alloy portfolios. Phinergy Ltd. occupies a distinct technology development position, exemplifying the aluminum-air archetype that bypasses lithium-ion material constraints entirely. These three entities illustrate the strategic divergence between incumbent conductor suppliers and alternative chemistry disruptors.
| Leading Market Players |
|---|
| Constellium SE |
| Kaiser Aluminum Corporation |
| Alcoa Corporation |
| Sumitomo Light Metal Industries, Ltd. |
| Norsk Hydro ASA |
| Novelis Inc. |
| Aluminum Corporation of China Limited |
| Phinergy Ltd. |
| UACJ Corporation |
| Others |
Value Chain & Pricing Dynamics
Dry electrode coating adoption is compressing processing costs for aluminum current collectors while simultaneously concentrating qualified supply among Japanese and German wire drawing facilities with electrochemical engineering depth. This dual effect tightens procurement timelines for automotive battery joint ventures seeking GB-compliant conductor documentation.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to automotive-scale aluminum-magnesium alloy orders against standard eight-week delivery windows. Three-tier pricing structure across automotive-qualified, industrial-grade, and spot-inventory tiers reflects certification investment recovery and volume commitment depth. Cost compression in industrial-grade cylindrical cell conductors is intensifying because Chinese wire drawing capacity expansion outpaces qualification velocity. Renewable energy storage integrators exhibit highest price sensitivity due to project-financed procurement models, while German OEM battery subsidiaries prioritize thermal cycling reliability over unit cost.
Supply Chain Analysis
GB standard certification and SAMR traceability documentation gate qualified supply, extending development schedules for imported aluminum alloys by twelve to eighteen months relative to domestic Chinese equivalents. Production gravity centers on China, South Korea, and Japan, with Ningbo and Ulsan manufacturing hubs feeding automotive battery joint ventures. High-purity primary aluminum and magnesium alloying additives draw from smelter networks in Australia and the Middle East. Single-source vulnerability concentrates in Japanese precision wire drawing for sub-100-micron foil specifications. Distribution runs through tiered component structures toward direct-to-OEM technical sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into primary aluminum smelting and captive wire drawing capacity anchors competitive positioning as cell manufacturers consolidate procurement through multi-year offtake agreements.
For Market Incumbents: Lock in long-term cathode supply agreements that bundle aluminum conductor specifications, defending against emerging solid-state battery developers with simplified current collector requirements. Add dedicated drawing capacity in South Korea's Seoul-Ulsan corridor to capture K-Battery strategy subsidies and compress logistics lead times for LG Energy Solution and Samsung SDI procurement teams. For New Entrants and Emerging Players: Aluminum-air technology platforms offer a technology-first wedge into range-extension applications for commercial fleets, bypassing lithium-ion qualification cycles entirely. Target Indian PLI scheme qualification windows for advanced chemistry cell manufacturing, where domestic aluminum conductor capacity remains underdeveloped. Deploy direct-to-OEM technical sales engineering to compress specification cycles against established tiered supply structures. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated aluminum producers seeking automotive-qualified conductor capabilities. Long-term viability hinges on qualification velocity against OEM thermal cycling protocols rather than commodity scale. Watch Korean cell manufacturer announcements on silicon-anode aluminum conductor pairing as inflection indicator for solid-state technology convergence timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Smelting | Captive aluminum supply secures GB traceability documentation for CATL and BYD procurement. |
| Direct-to-OEM Technical Sales Deployment | Custom alloy specification cycles compress from eighteen months to nine months against tiered channels. |
| Solid-State Electrolyte Compatibility Investment | Bare aluminum conductor interfaces align with Samsung SDI and LG Energy Solution development programs. |
| Indian PLI Scheme Qualification | Domestic drawing capacity captures production-linked incentives under advanced chemistry cell policy. |
| Aluminum-Air Technology Platform Development | Primary metal systems bypass lithium-ion material constraints for commercial fleet range extension. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with wire drawing facility technical directors, automotive battery joint venture procurement leads, cathode material supplier R&D heads, and SAMR certification consultants. Secondary sources included GB standard documentation, EU F-Gas Regulation implementation guidance, London Metal Exchange aluminum pricing archives, and Korean Ministry of Trade battery supply chain reports. Bottom-up cell shipment estimates by format and top-down automotive battery pack value aggregation were triangulated against disclosed OEM supply agreements.
Granularity-level modeling addressed prismatic, cylindrical, and solid-state technology segments separately, with aluminum conductor content per kilowatt-hour calibrated against disclosed cell-to-pack architecture adoption rates. End-use segmentation captured electric vehicle, consumer electronics, renewable energy storage, and industrial application demand pools. CAGRs were derived from fitted adoption curves for solid-state technology maturation and aluminum-lithium price ratio trajectories. Forecast inputs included Korean cathode cluster expansion timelines and German OEM battery subsidiary production ramp schedules.
Several conditions sit outside the modeled scope, including unannounced solid-state electrolyte breakthroughs, abrupt aluminum tariff regime changes, and disruptive aluminum-air technology commercialization. Forecasts reflect assumptions on GB standard enforcement consistency and SAMR certification timeline stability. A model refresh is warranted upon material change in Korean cell manufacturer aluminum conductor qualification velocity or EU F-Gas Regulation coating process restrictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Zinc-Manganese Oxide Printed Battery Market
Batteries
Drone Power Sources Market
Batteries
Inverter Battery Market
Batteries
Smart Diagnostic Battery Charger Market
Batteries
Global Bio Compatible Battery Market
Batteries
Carbon Black in Lead-Acid Battery Market
Batteries
Primary Battery Market
Batteries
Middle-East and Africa Battery Cell Market
Batteries
India Alkaline Battery Market
Batteries
Sodium-Air Battery Market
Batteries
Advanced Batteries Market
Batteries
Aluminum-Air Battery Market
Batteries
Battery Coolant-Antifreeze Refractometer Market
Batteries
Battery Cases Market
Batteries
Utility Battery Market
Batteries
Military Battery Market