
 Point Absorber Market | 2026-2036
Point Absorber Market Size, Share, and Industry Trends Forecast 2026-2036
Point Absorber Market Analytics
Offshore operator procurement is shifting toward integrated wave-to-grid platforms that reduce cable-laying costs and platform downtime. Ocean Power Technologies sustains technology leadership through its autonomous PowerBuoy systems for remote marine applications. Carnegie Corporation anchors development activity in Australia through its CETO submerged pressure differential technology. AWS Ocean Energy competes in the European demonstration pipeline with multi-unit array architectures designed for Orkney waters.
A point absorber is a floating or submerged wave energy converter that captures kinetic energy from heave motion via a buoyant surface element coupled to a power take-off mechanism, typically rated between 10 kW and 500 kW per unit depending on wave climate. These systems convert oscillating water particle motion into mechanical or direct electrical output for grid injection or islanded marine loads. Floating configurations currently lead deployment counts due to simpler mooring logistics and surface-accessible maintenance protocols, while submerged variants attract capital for reduced storm damage exposure and lower visual impact. Linear generator technology dominates the power take-off segment because it eliminates intermediate hydraulic stages and improves conversion efficiency in irregular seas.
Marine energy developers navigate permitting under the EU Marine Strategy Framework Directive, the US Federal Energy Regulatory Commission's pilot project licensing, and the UK's Marine Management Organisation leasing rounds. These frameworks shape device certification requirements, environmental impact thresholds, and grid connection timelines that directly affect project financeability. Stakeholders must monitor how streamlined consenting reforms in Portugal, Scotland, and the US Pacific Northwest alter competitive positioning for first-commercial arrays.
Market Dynamics
Linear generator power take-off systems are compressing hydraulic intermediate stages, cutting maintenance intervals and raising conversion efficiency in irregular Atlantic wave climates. This hardware transition is reshaping capital allocation across demonstration pipelines.
Growth Catalysts
- EU Marine Strategy Framework Directive:Streamlined environmental consenting in Portuguese and Scottish waters accelerates array deployment timelines.
- Near-shore platform electrification:Offshore operators in the North Sea are procuring integrated wave-to-grid systems to displace diesel generator sets on unmanned platforms.
- Aguçadoura test zone infrastructure:Grid-connected berths and shared mooring systems reduce developer capex burdens for scaled trials.
Market Restraints
- Neodymium supply concentration:Rare-earth magnet dependency for linear generators concentrates in Chinese processing facilities, exposing bill-of-materials volatility.
- FERC pilot licensing duration:US Federal Energy Regulatory Commission environmental review timelines extend 18-36 months, freezing early-stage project finance.
- Subsea cable cost structure:Dynamic power export cables account for 35-45 percent of installed system cost in deep-water configurations.
Strategic Opportunities
- Orkney Islands leasing rounds:The UK's Marine Management Organisation is releasing consented seabed parcels with pre-approved grid capacity for multi-unit arrays.
- Desalination co-location:Islanded coastal municipalities in the Azores are evaluating wave-powered reverse osmosis to displace diesel-electric desalination.
- EU Green Deal innovation procurement:Pre-commercial purchase agreements for marine energy are qualifying under the European Commission's strategic technology auction mechanisms.
Industry Challenges
- Marine structural engineering talent scarcity:Specialized mooring design and fatigue analysis capabilities concentrate in Norwegian and Scottish consultancies, constraining project team scaling.
- Device certification timeline compression:IEC 62600-1 certification for ocean energy converters requires 24-48 months of structured sea trials, delaying revenue recognition.
- Power quality grid integration:Variable wave-to-wire output requires advanced inverter control systems to meet national transmission operator frequency response standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point Absorber Market |
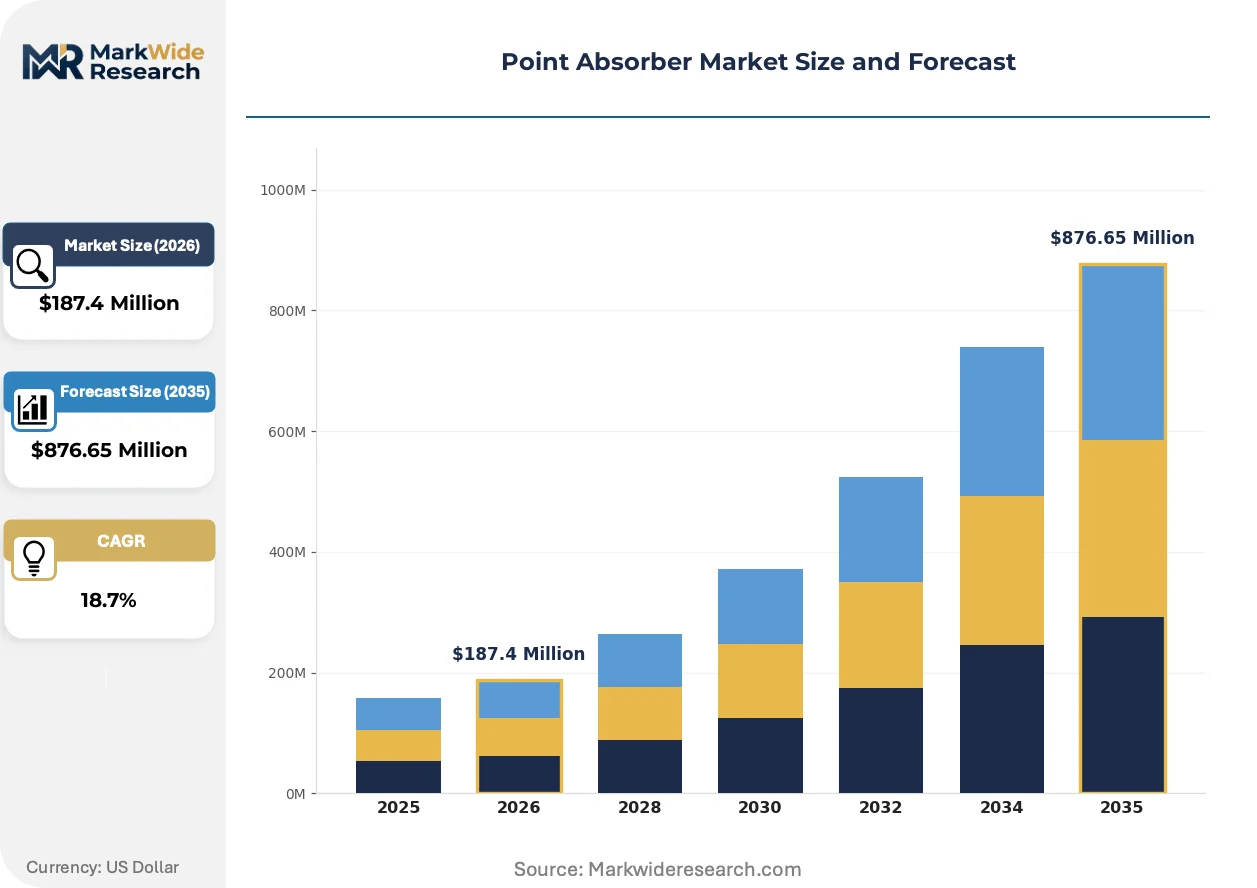
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floating, Fixed, Submerged, Hybrid End User: Utilities, Offshore Operators, Research Institutions, Government Technology: Linear Generators, Pendulum Systems, Oscillating Water Columns, Turbine Systems Application: Electricity Generation, Environmental Monitoring, Wave Energy Conversion, Research & Development |
| Companies Covered | Wavestar, Ocean Navitas, Ocean Power Technologies, Wave Bob, Carnegie Corporation, AWS Ocean Energy, Pelamis Wave Power, Aquamarine Power, The European Energy Centre, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point Absorber Market Evolving Landscape
Hardware miniaturization and predictive maintenance architectures are converging to reshape competitive economics across the demonstration-to-commercial transition. These shifts favor developers with integrated system control capabilities.
Direct-drive linear generators is overtaking hydraulic power take-off systems in new deployments. Carnegie Corporation and AWS Ocean Energy are specifying permanent-magnet linear architectures for their next-generation arrays. This transition eliminates seal failure points and compresses operational expenditure forecasts for 25-year asset lifetimes.
REACH substance restrictions on marine coatings are forcing reformulation of antifouling systems used on buoyant hull structures. ECHA candidate list scrutiny of zinc-based compounds is accelerating silicone and fluoropolymer alternative adoption. Portuguese and Spanish developers are qualifying ceramic-composite surface treatments to maintain biofouling resistance without toxic release.
Utility offtake contracting is compressing from 15-year power purchase agreements toward 5-7 year tenor structures with merchant price exposure. European distribution system operators are reluctant to underwrite long-term wave energy tariffs without production track records. This shift concentrates development activity in markets with capacity payment mechanisms or green certificate premiums, notably the UK and Portugal.
Point Absorber Market Segmentation
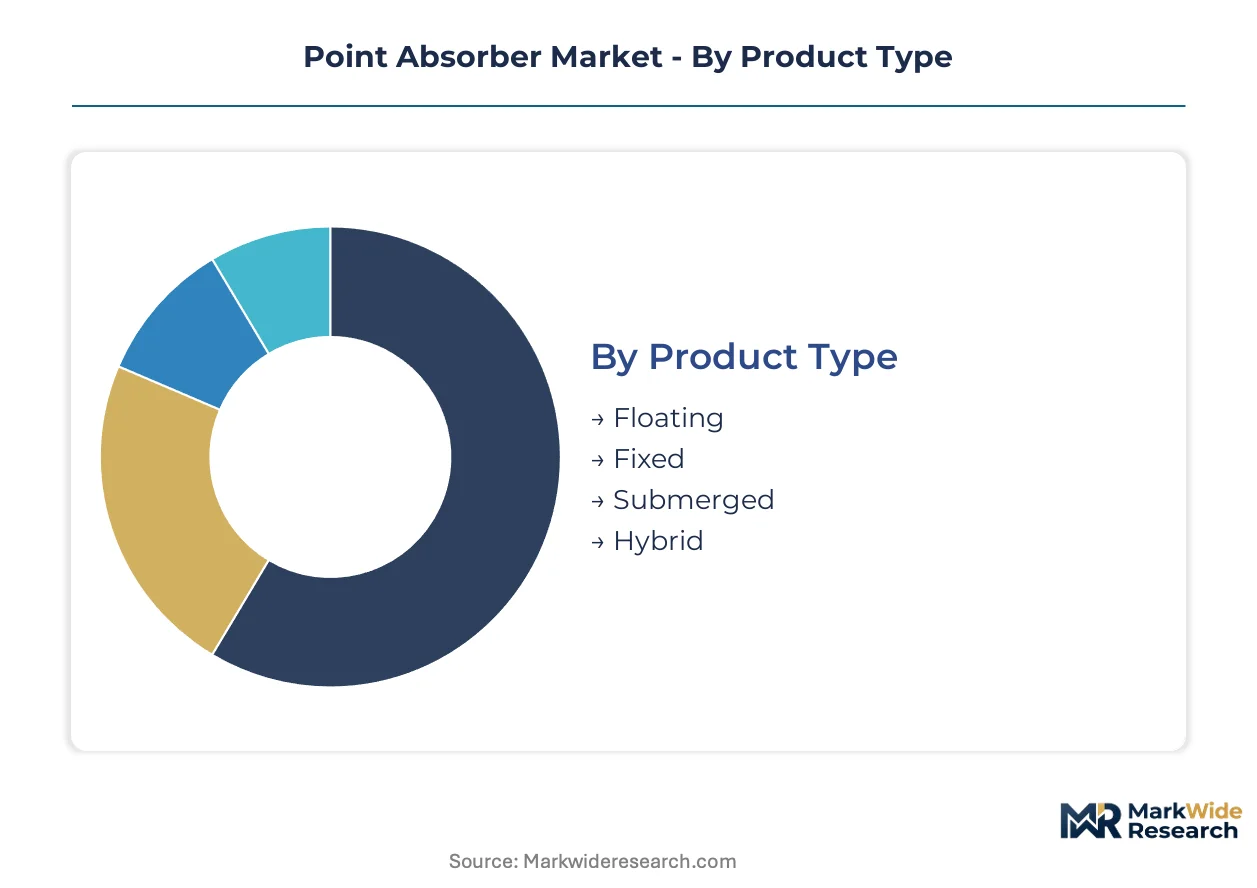
Segmentation in the point absorber market reveals how capital allocation, technical risk tolerance, and regulatory exposure vary across deployment configurations and customer archetypes. Developers must match product architecture to end-user procurement criteria and site-specific wave climates.
Product Type:
Floating systems demand the highest upfront capital commitment due to surface mooring complexity and dynamic cable infrastructure, while submerged variants concentrate engineering spend on pressure-rated hull structures and subsea power export.
- Floating:Surface-accessible buoyant hulls coupled to taut-leg mooring arrays enable crane-based maintenance without subsea intervention. North Sea offshore operators favor this architecture for unmanned platform electrification, though storm survivability drives steel-to-composite hull cost premiums.
- Submerged:Pressure-differential devices operate below wave action to reduce fatigue loading and visual impact. Portuguese developers at the Aguçadoura test zone prioritize this configuration for streamlined environmental consenting under the EU Marine Strategy Framework Directive.
- Fixed:Bottom-mounted structures eliminate active mooring systems but require seabed penetration and scour protection. Deployments concentrate in shallow near-shore zones with sandy substrates.
- Hybrid:Configurations combine surface and submerged elements to optimize power capture across wave height spectra. Early-stage arrays in Scottish waters test this architecture for multi-mode energy extraction.
Floating configurations absorb the bulk of installed capacity; submerged variants are expanding most quickly as consenting frameworks tighten visual impact thresholds.
End User:
Procurement scale and contracting sophistication separate utility offtakers from islanded marine operators, with research institutions anchoring pre-commercial demonstration pipelines.
- Utilities:Grid-connected power purchase agreements drive volume procurement for coastal distribution networks. Iberian utilities leverage EU Green Deal innovation procurement mechanisms to underwrite first-commercial arrays in Portuguese waters.
- Offshore Operators:Oil and gas platform electrification displaces diesel generator sets with integrated wave-to-grid systems. North Sea operators specify autonomous PowerBuoy-class devices for unmanned installation power.
- Research Institutions:Universities and national laboratories validate device performance for IEC 62600-1 certification. European Marine Energy Centre berths in Orkney host multi-developer testing campaigns.
- Government:Defense and coastal management agencies procure environmental monitoring payloads integrated with point absorber platforms. Azores regional government evaluates wave-powered desalination co-location.
Offshore operators absorb the bulk of installed capacity; utilities are climbing the fastest as power purchase agreement tenors compress toward merchant exposure tolerance.
Technology:
Power take-off architecture determines maintenance intervals, conversion efficiency in irregular seas, and rare-earth material exposure.
- Linear Generators:Direct-drive permanent-magnet architectures eliminate hydraulic intermediate stages and seal failure points. Carnegie Corporation specifies this technology for CETO submerged pressure differential systems in Australian deployments.
- Pendulum Systems:Internal mass oscillation drives mechanical power take-off through gear trains. Reduced magnet dependency attracts developers seeking supply chain decoupling from Chinese rare-earth processing.
- Oscillating Water Columns:Air turbine systems capture wave energy via entrained air compression in partially submerged chambers. Simpler rotating machinery reduces specialized maintenance requirements.
- Turbine Systems:Direct water flow through ducted turbines suits high-velocity near-shore zones. Deployments concentrate in channel geographies with consistent current-wave interaction.
Linear generators absorb the bulk of installed capacity; pendulum systems are gaining share fastest as neodymium price volatility reshapes bill-of-materials risk.
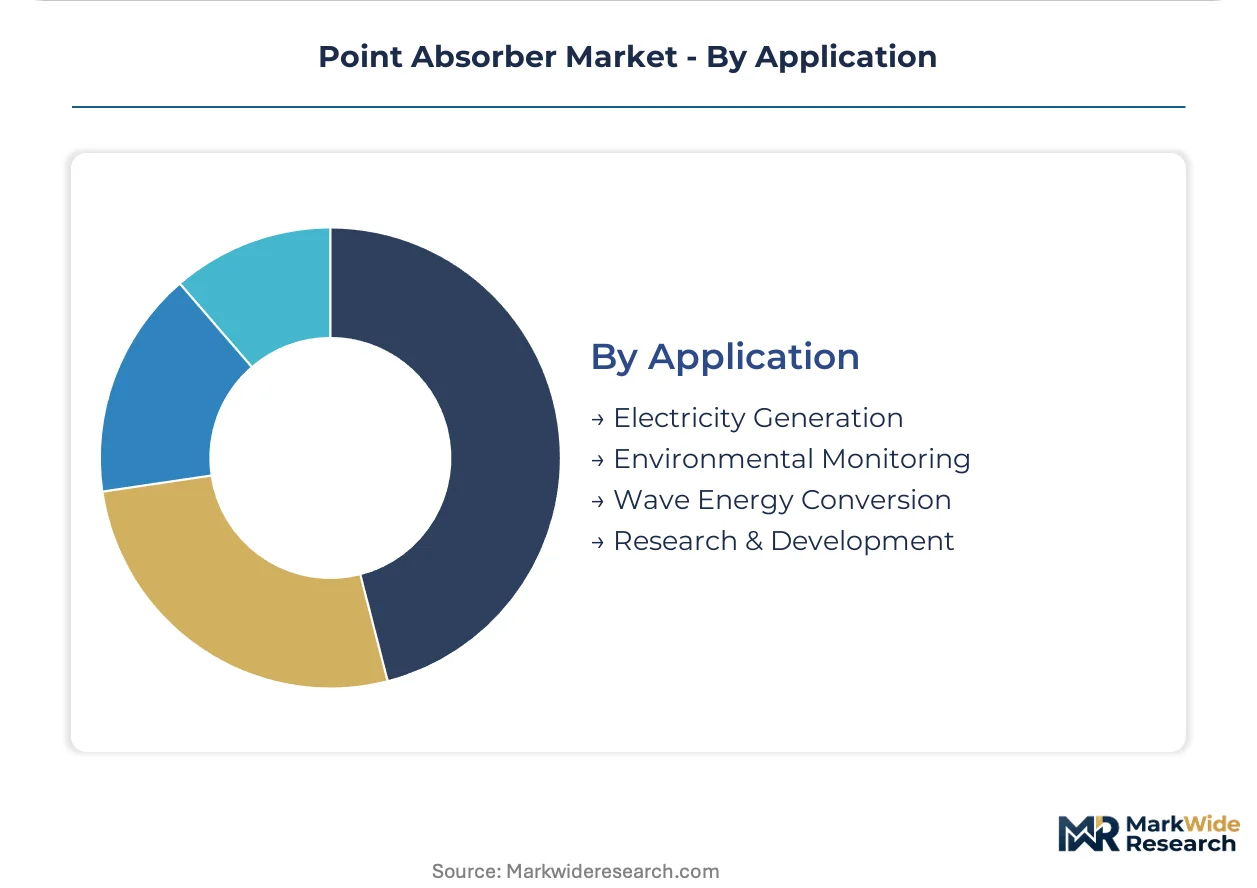
Application:
Revenue model differentiation separates grid-connected electricity sales from contracted research services and environmental data subscriptions.
- Electricity Generation:Grid injection and islanded microgrids constitute the primary commercialization pathway. UK and Portuguese markets lead due to capacity payment mechanisms and green certificate premiums.
- Environmental Monitoring:Sensor payload hosting for oceanographic and meteorological data generates recurring revenue. Defense and climate research agencies fund integrated platform deployments.
- Wave Energy Conversion:Dedicated power take-off testing and certification services support device developer pipelines. Shared test infrastructure at Aguçadoura and Orkney reduces per-developer capex burdens.
- Research & Development:Structured sea trials for IEC 62600-1 certification require 24-48 month commissioning timelines. Revenue concentrates in engineering consultancies with marine structural fatigue expertise.
Electricity generation absorbs the bulk of installed capacity; environmental monitoring is expanding most quickly as sensor miniaturization enables payload integration at marginal cost.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aguçadoura test zone tax incentives and shared infrastructure berths are concentrating Portuguese developer investment. Scottish Orkney waters attract multi-unit array trials through pre-approved grid capacity. Australian demonstration pipelines anchor Pacific commercialization pathways.
Portugal
Aguçadoura test zone infrastructure reduces developer capex through grid-connected berths and shared mooring systems. EU Marine Strategy Framework Directive streamlined consenting accelerates array deployment timelines. WaveRoller demonstration sites in northern Portuguese waters validate submerged pressure-differential architectures for utility-scale procurement.
United Kingdom
Orkney Islands leasing rounds from the Marine Management Organisation release consented seabed parcels with pre-approved grid capacity. Capacity payment mechanisms under UK energy market reforms underwrite wave energy tariff structures. Scottish waters host multi-developer testing campaigns at European Marine Energy Centre berths.
Australia
CETO submerged pressure-differential technology development anchors national demonstration activity in Western Australian waters. Commonwealth renewable energy agency funding supports structured sea trials for IEC 62600-1 certification. Perth-based engineering consultancies concentrate marine structural fatigue analysis capabilities for project team scaling.
United States
FERC pilot licensing timelines extending 18-36 months freeze early-stage project finance for Pacific Northwest developers. Bureau of Ocean Energy Management lease rounds in Oregon and California waters advance environmental review coordination. Ocean Power Technologies sustains autonomous PowerBuoy deployment for remote marine applications off California and Hawaii coasts.
Norway
North Sea offshore operators procure integrated wave-to-grid systems to displace diesel generator sets on unmanned platforms. Norwegian consultancies concentrate specialized mooring design capabilities constraining project team scaling across European pipelines. Bergen and Stavanger engineering clusters anchor marine structural engineering talent for Atlantic wave climate deployments.
Point Absorber Market Competitive Landscape
Top-tier vendors anchor integrated system control capabilities, while mid-tier developers concentrate on single-device demonstration pipelines. The vendor base stratifies across autonomous platform specialists, submerged pressure-differential technologists, and multi-unit array architects. Strategic archetypes include technology licensors seeking partnership revenue, vertically integrated developers capturing full project value, and component suppliers feeding OEM pipelines. Competitive moves concentrate on demonstration-to-commercial transition financing and certification timeline compression.
Among autonomous platform specialists, Ocean Power Technologies occupies a position exemplifying remote marine application focus. Carnegie Corporation and AWS Ocean Energy represent the submerged pressure-differential archetype with permanent-magnet linear generator specifications. Wavestar and Pelamis Wave Power sit within the European demonstration pipeline tier, reflecting multi-unit array architecture development in Orkney and Portuguese waters.
| Leading Market Players |
|---|
| Wavestar |
| Ocean Navitas |
| Ocean Power Technologies |
| Wave Bob |
| Carnegie Corporation |
| AWS Ocean Energy |
| Pelamis Wave Power |
| Aquamarine Power |
| The European Energy Centre |
| Others |
Value Network & Pricing Analysis
North Sea offshore operator procurement of integrated wave-to-grid platforms for unmanned platform electrification is compressing supplier margins and forcing tier-one vendors to absorb dynamic cable cost inflation through bundled service contracts.
Pricing Analysis
Lead-time premiums dominate point absorber commercial negotiations, with developers paying 15-20 percent markups for accelerated IEC 62600-1 certification timelines. Project-based contract structures with milestone payments predominate, differentiated by certification grade and mooring complexity. Price erosion runs through floating configurations as Portuguese and Scottish test zones saturate with demonstration units. Research institutions exhibit highest price sensitivity due to grant-funded procurement constraints.
Supply Chain Analysis
Dual-sourcing mandates from European utilities require developers to qualify redundant suppliers for permanent-magnet linear generators and subsea cable assemblies. Manufacturing concentrates in Norway, Germany, and China. Neodymium magnets, high-voltage marine cables, and composite hull laminates constitute critical input dependencies. Single-source vulnerability in Chinese rare-earth processing exposes bill-of-materials volatility. Distribution runs through EPC contractors with marine installation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point absorber market consolidation is accelerating as FERC pilot licensing timelines and IEC 62600-1 certification requirements force capital-constrained developers toward partnership or exit.
For Market Incumbents: Extend certification timeline compression capabilities through captive marine structural engineering talent in Bergen and Stavanger clusters. Secure backward integration into permanent-magnet supply chains to hedge Chinese neodymium concentration. Carnegie Corporation and Ocean Power Technologies anchor this defensive posture through integrated system control architectures that emerging entrants cannot replicate without 24-48 month sea trial investments. For New Entrants and Emerging Players: EU Marine Strategy Framework Directive streamlined consenting in Portuguese waters opens a window for submerged pressure-differential specialization at Aguçadoura test zone. Target Azores regional government desalination co-location procurement before utility offtake markets mature. Pursue technology licensing revenue from Norwegian offshore operators seeking autonomous platform electrification without in-house wave energy development. For Investors and Strategic Acquirers: The window for entry favors developers with pre-approved grid capacity at Orkney Islands leasing rounds and completed IEC 62600-1 sea trials. Long-term viability hinges on power purchase agreement tenor compression tolerance and merchant price exposure management. Watch for UK capacity payment mechanism reforms as the inflection signal for utility-scale deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Timeline Compression | Reduces 24-48 month IEC 62600-1 sea trial burden through parallel testing protocols at European Marine Energy Centre berths. |
| Permanent-Magnet Supply Agreement | Locks neodymium pricing through multi-year contracts with German and Japanese magnet processors outside Chinese concentration. |
| Test Zone Infrastructure Partnership | Secures grid-connected berths at Aguçadoura or Orkney with shared mooring systems reducing per-unit capex. |
| Desalination Co-location Development | Captures Azores municipal procurement for wave-powered reverse osmosis displacing diesel-electric alternatives. |
| Autonomous Platform Specialization | Serves North Sea offshore operator demand for unmanned installation power through PowerBuoy-class device architectures. |
Research Methodology
Document review covered FERC pilot project licensing databases, EU Marine Strategy Framework Directive implementation reports, and IEC 62600 certification records, complemented by interviews with wave energy developers, marine structural engineering consultancies, offshore operator procurement officers, and European distribution system operators. Secondary validation drew from Bureau of Ocean Energy Management lease round filings, ECHA REACH substance restriction updates, and national renewable energy agency funding disclosures. Bottom-up deployment pipeline tracking triangulated against top-down market sizing from utility procurement announcements and test zone infrastructure investments.
Segmentation outputs reflect product type, end user archetype, power take-off technology, and application across the projection horizon. CAGRs derive from deployment timeline probability weighting and learning curve cost reduction assumptions. Forecast inputs incorporate wave climate resource assessments for Portuguese, Scottish, and Australian waters alongside grid connection queue data from UK and Iberian system operators.
The model assumes a particular technology adoption path; alternative pathways for pendulum power take-off systems would alter the outlook if neodymium price volatility accelerates magnet-to-mechanical substitution. Deviation in FERC licensing reform timing or EU innovation procurement auction mechanics would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Biogas Plant Market
Renewable Energy
Solar Street Lighting Market
Renewable Energy
Solar Chimney Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
Europe Renewable Energy Market
Renewable Energy
Solar Floating Pool Lights Market
Renewable Energy
Solar District Heating Market
Renewable Energy
LAMEA Wave and Tidal Energy Market
Renewable Energy
Venezuela Renewable Energy Market
Renewable Energy
Solar Panel Mounting Structure Market
Renewable Energy
Tunisia Renewable Energy Market
Renewable Energy
Wave Energy Market
Renewable Energy
China Solar Energy Market
Renewable Energy
Hybrid Solar Wind Diesel Market
Renewable Energy
Biomethane Certificate Trading Platform Market
Renewable Energy
Drones in Renewable Energy Market