
 Europe Single-Axis Solar Tracker Market | 2026-2036
Europe Single-Axis Solar Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Single-Axis Solar Tracker Market Foresight
Backtracking algorithms paired with IoT-enabled sensor arrays is tilting tracker control architectures toward predictive rather than reactive positioning. Soltec Power Holdings SA anchors its European presence through manufacturing scale in Spain and dedicated R&D centers serving Mediterranean project pipelines. Array Technologies Inc. competes on structural engineering heritage, leveraging decades of utility-scale deployment experience to secure contracts in high-wind zones across Southern Europe. Nextracker Inc. differentiates through distributed drive architectures that reduce steel content and simplify foundation requirements on uneven terrain.
A single-axis solar tracker rotates photovoltaic modules along one horizontal axis to follow the sun's daily path, typically achieving 20-35% additional energy capture versus fixed-tilt systems through east-west tracking movement. Steel torque tubes, bearing assemblies, and linear actuators constitute the primary mechanical stack, with control systems processing irradiance and wind-load data to optimize angular positioning. Active trackers command the largest installed base among product type categories, though smart trackers integrating machine-learning-based predictive algorithms are gaining fastest traction in new procurement cycles. Ground-mounted installations dominate the installation type landscape, while bifacial installation configurations are emerging as a margin-rich sub-segment where tracker geometry directly influences rear-side gain capture.
EMA certification requirements for mechanical durability and the EU Green Deal's binding renewable targets are reshaping procurement criteria toward equipment with verified 25-year operational life documentation. CE marking obligations under the Machinery Directive enforce specific safety and interoperability standards that non-compliant suppliers cannot bypass in European project tenders. Stakeholders must monitor evolving F-Gas Regulation implications on tracker motor cooling systems and anticipate how CSRD sustainability disclosure mandates will cascade through supply chain qualification protocols.
Market Dynamics
Tracker control architectures are pivoting from reactive positioning to predictive algorithms powered by IoT sensor arrays, compressing commissioning timelines and reshaping supplier qualification criteria across European utility-scale procurement.
Growth Catalysts
- EU Green Deal binding targets:National renewable energy mandates under the revised Renewable Energy Directive are accelerating utility-scale solar park approvals in Spain and Germany, creating immediate demand pull for yield-enhancing tracker systems.
- Bifacial module pairing:Rear-side gain capture from bifacial photovoltaic configurations depends critically on tracker geometry optimization, driving specification upgrades in new Iberian Peninsula installations.
- Steel torque tube standardization:Modular foundation designs reducing civil works complexity are expanding addressable terrain categories for tracker deployment across uneven Mediterranean topography.
Market Restraints
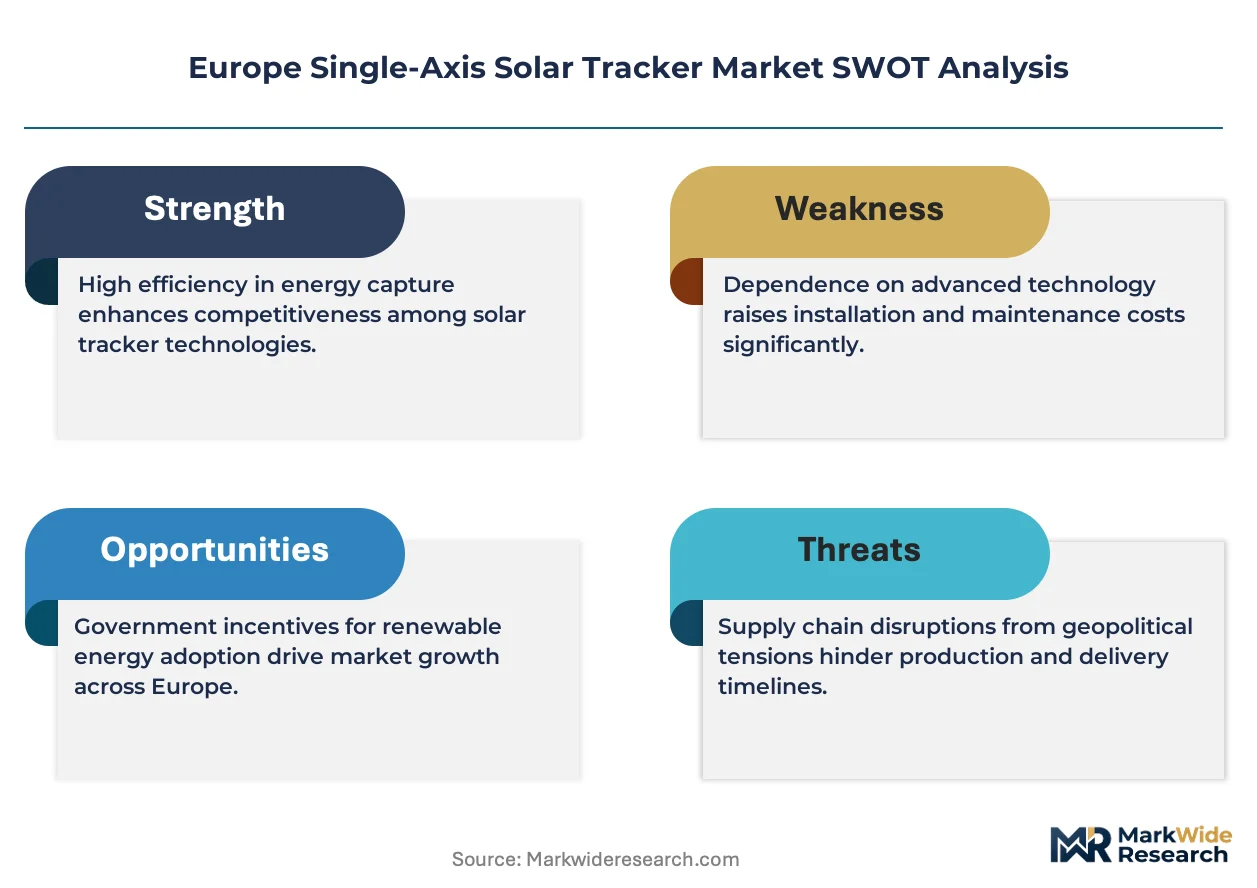
- Steel price volatility:Torque tubes and bearing assemblies constitute substantial bill-of-materials exposure, with input cost swings compressing project developer margins during procurement cycles.
- Wind load engineering constraints:Southern European high-wind zones impose structural certification requirements that limit supplier qualification pools and extend technical due diligence timelines.
- F-Gas Regulation compliance:Motor cooling system refrigerant restrictions under evolving EU rules are forcing redesign cycles for electromechanical drive architectures.
Strategic Opportunities
- Eastern European solar pipelines:Poland and Romania are scaling utility-scale capacity auctions with land availability profiles suited to tracker-equipped installations.
- Predictive control convergence:Machine learning algorithms integrated with satellite irradiance forecasting are enabling anticipatory positioning that outperforms sensor-reactive systems.
- CSRD supply chain disclosure:Sustainability reporting mandates are creating competitive differentiation for tracker manufacturers with verified 25-year operational life documentation and carbon footprint transparency.
Industry Challenges
- Electromechanical commissioning expertise:Shortages of technicians qualified to integrate linear actuator systems with IoT control networks are extending project handover timelines.
- CE marking documentation burden:Machinery Directive compliance requirements for interoperability and safety testing are lengthening product certification cycles for new tracker platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Single-Axis Solar Tracker Market |
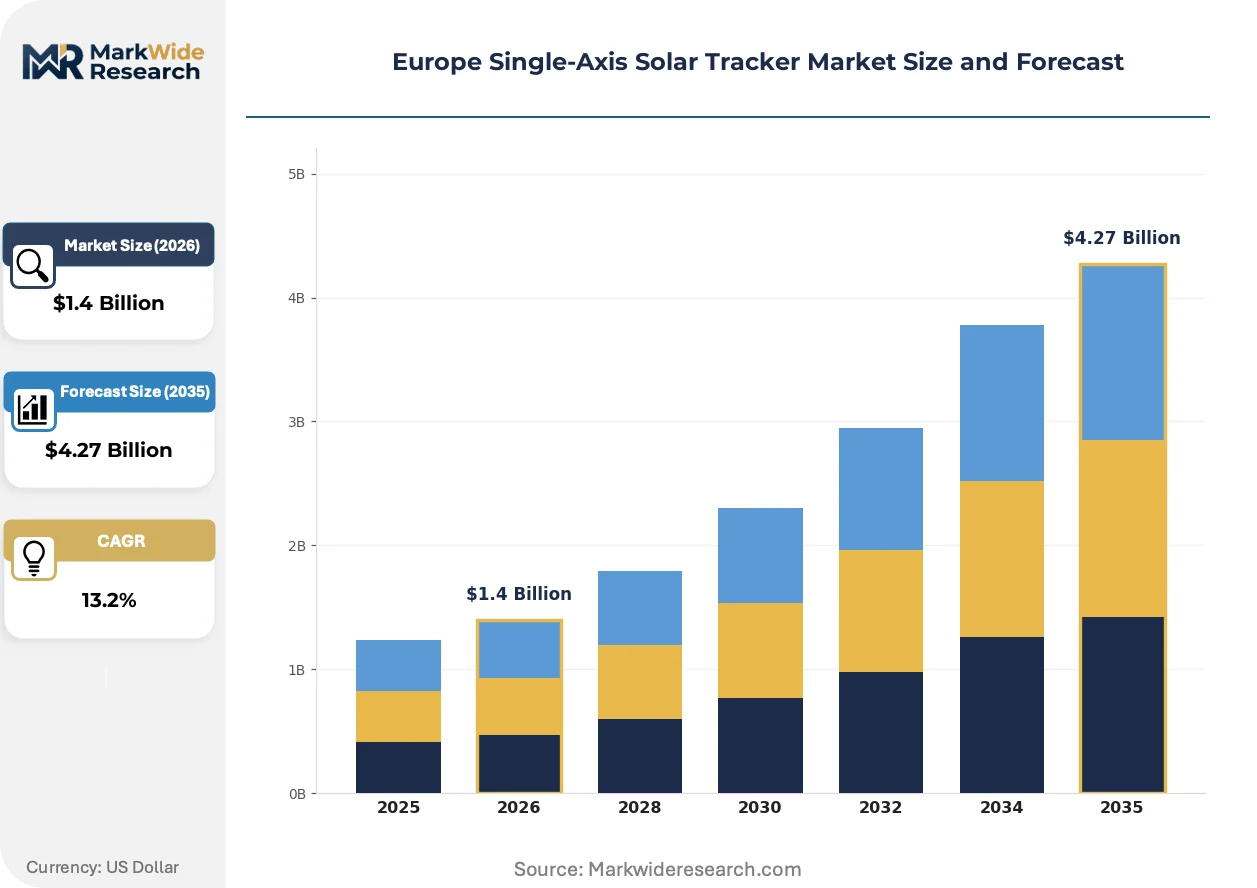
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.27 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Trackers, Passive Trackers, Hybrid Trackers, Smart Trackers Installation Type: Ground Mounted, Roof Mounted, Bifacial Installation, Utility Scale End User: Commercial, Residential, Utility, Government Control System: Open Loop, Closed Loop, GPS Controlled, Manual Control |
| Companies Covered | MecaSolar, Arctech Solar Holding Co. Ltd, Soltec Power Holdings SA, Valmont Industries Inc., DCE Solar, Ideematec Deutschland GmbH, Array Technologies Inc., P V Hardware, Nextracker Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Single-Axis Solar Tracker Market Shifts & Advancements
Tracker technology trajectories center on control intelligence advancement, regulatory compliance integration, and procurement model transformation that collectively redefine supplier value propositions.
Distributed drive architectures are hybridizing centralized motor systems with modular electromechanical units that reduce steel content and simplify foundation engineering on irregular terrain. Spanish and German utility developers are specifying these configurations for projects with geotechnical complexity. The structural consequence is compressing supplier differentiation around mechanical hardware toward software-enabled predictive performance guarantees.
CSRD sustainability disclosure mandates are cascading through European supply chain qualification protocols, requiring tracker manufacturers to document embodied carbon and end-of-life recyclability. Industrial consequence includes procurement teams embedding lifecycle assessment scores alongside price-technical evaluations. Southern European project developers are most affected, with EPC contracts now specifying CSRD-aligned supplier certification as a gate to bid participation.
Performance-based service contracts are displacing traditional equipment-only sales in utility-scale tracker procurement, with developers transferring operational risk to manufacturers through energy yield guarantees. Array Technologies and Nextracker are restructuring European go-to-market organizations around long-term service revenue streams. This shift is most visible in Spain, where 25-year power purchase agreement structures align with extended manufacturer service obligations.
Europe Single-Axis Solar Tracker Market Segmentation
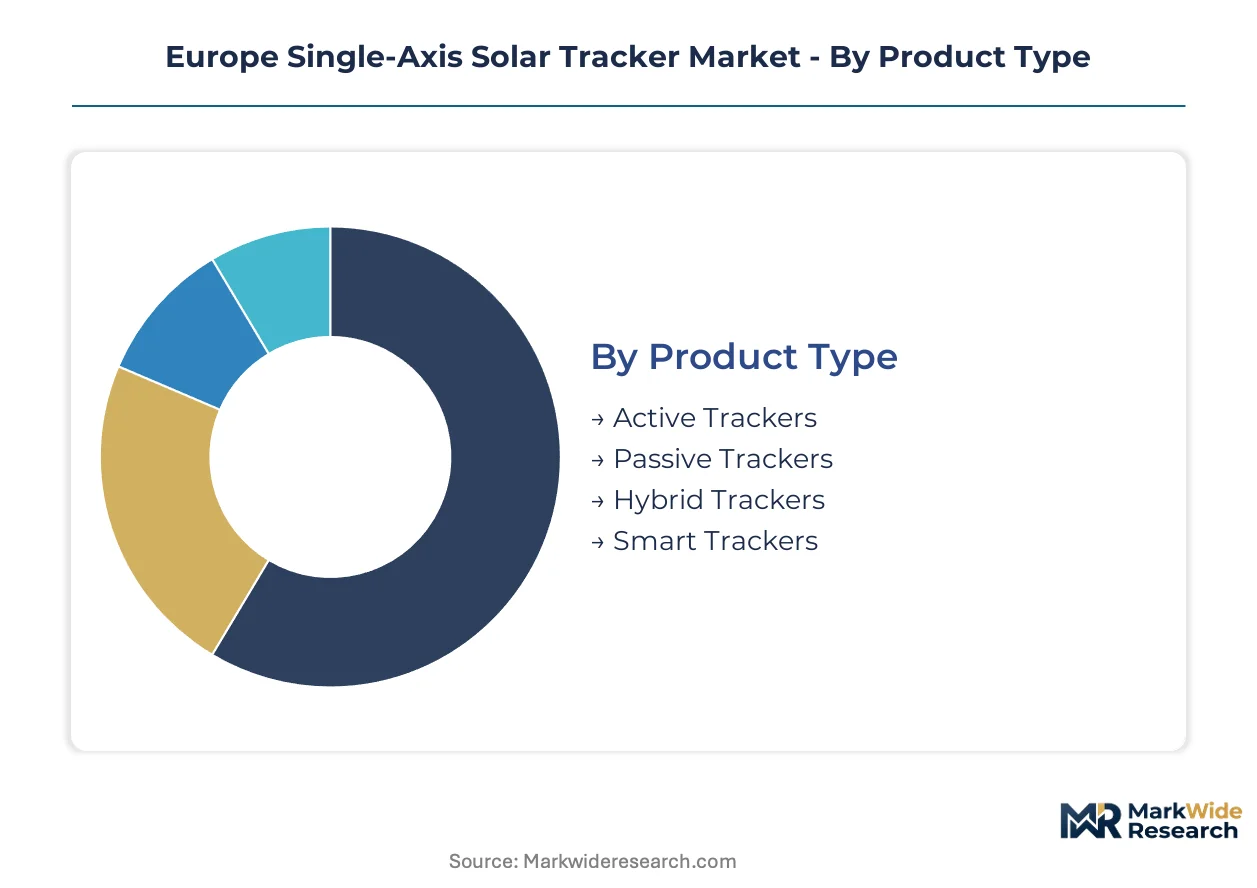
Tracker deployment patterns across Europe fragment sharply by technical architecture, mounting configuration, and procurement authority. Each segmentation dimension carries distinct margin profiles and regulatory exposure that reshape supplier positioning strategies.
Product Type:
Active electromechanical systems dominate utility-scale deployment, while intelligence integration separates premium from commodity tiers.
- Active Trackers:Motor-driven arrays with real-time sensor feedback command the largest installed base across Spanish and German solar parks. Iberian Peninsula developers favor these systems for proven reliability in high-irradiance conditions where downtime carries steep revenue penalties.
- Smart Trackers:Machine-learning control layers process satellite weather feeds and historical performance data to pre-position modules before cloud fronts arrive. These configurations are climbing the fastest in new procurement cycles across Southern Europe as energy yield guarantees tighten.
- Passive Trackers:Thermal expansion actuators eliminate motor maintenance but sacrifice precision in variable weather. These units concentrate in off-grid and remote installations where technician access is constrained.
- Hybrid Trackers:Dual-mode architectures combine passive thermal response with electromechanical override capabilities. Polish and Romanian project pipelines specify these for transitional climate zones with erratic irradiance patterns.
Established volume favors active configurations; emerging adoption favors smart tracker integration.
Installation Type:
Foundation engineering requirements and land access constraints create four distinct deployment archetypes across European markets.
- Ground Mounted:Steel-pile or concrete-ballasted foundations support row-based tracker arrays across open terrain. This configuration absorbs the majority of capacity additions in Spain and Portugal where agricultural land conversion faces fewer restrictions than in Northern Europe.
- Bifacial Installation:Elevated tracker geometry with reflective ground cover captures rear-side generation gains. Southern European EPC contracts increasingly mandate bifacial compatibility as module prices for dual-sided cells compress.
- Utility Scale:Centralized inverter integration and standardized row spacing optimize levelized cost of energy at installations exceeding 50 MW. German grid connection queues favor these configurations for streamlined permitting.
- Roof Mounted:Structural load constraints and wind exposure limit tracker deployment on commercial and industrial rooftops. Italian agricultural building retrofits represent a narrow niche where lightweight tracker designs gain traction.
Ground-mounted systems anchor current procurement volumes; bifacial specifications drive margin expansion in new tenders.
End User:
Procurement sophistication and contract duration vary dramatically across customer categories, fragmenting supplier go-to-market requirements.
- Utility:Long-term power purchase agreements and integrated EPC contracting dominate procurement. These customers demand 25-year performance warranties and CSRD-aligned sustainability documentation.
- Commercial:Behind-the-meter installations for manufacturing and logistics facilities prioritize rapid payback periods over extended warranties. Energy service company financing structures shape specification decisions.
- Government:Public tender processes impose strict CE marking and Machinery Directive compliance thresholds. Romanian and Polish auction mechanisms favor domestic content requirements that filter supplier pools.
- Residential:Single-axis trackers remain rare in rooftop applications due to structural complexity and maintenance access challenges. Off-grid rural properties in Mediterranean regions represent isolated demand pockets.
Utility procurement commands volume concentration; commercial segment expansion depends on financing innovation.
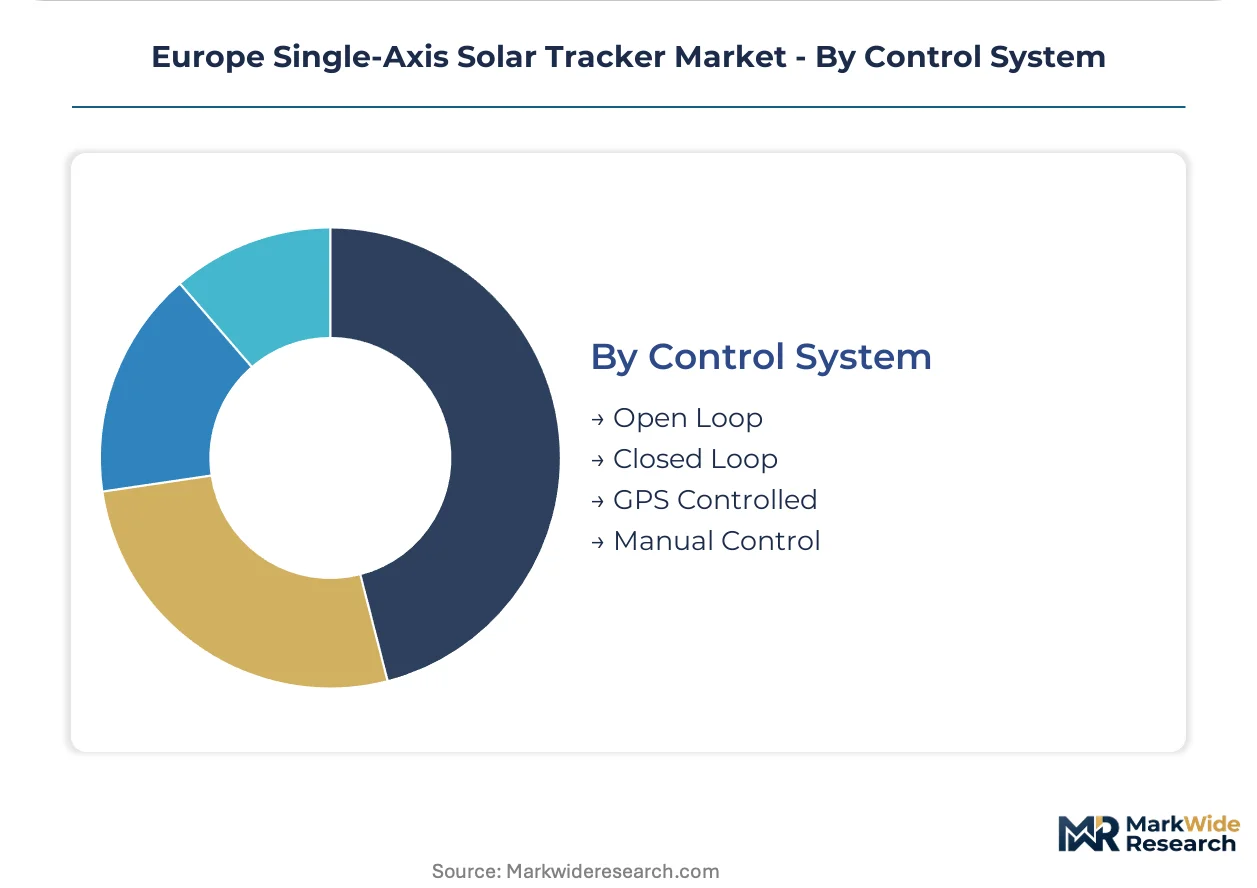
Control System:
Positioning intelligence architectures determine commissioning complexity and long-term operational expenditure profiles.
- Closed Loop:Feedback sensors continuously correct angular positioning against actual sun location. These systems dominate high-value installations where tracking precision directly affects revenue.
- GPS Controlled:Satellite-derived ephemeris data eliminates on-site sensor calibration requirements. Nextracker and Array Technologies deploy these architectures for rapid commissioning across uneven Mediterranean terrain.
- Open Loop:Pre-programmed astronomical tables drive positioning without environmental feedback. Cost-sensitive installations in Eastern Europe accept reduced precision for lower hardware expenditure.
- Manual Control:Seasonal or monthly adjustment protocols persist in legacy installations and off-grid applications. These systems face obsolescence pressure from declining electromechanical component costs.
Closed-loop architectures defend premium positioning; GPS integration enables fastest deployment velocity in new markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's single-axis solar tracker market operates with a modest trade surplus in finished systems, though steel torque tubes and linear actuators draw heavily on imported mill products from Turkey and Ukraine. Spain and Germany anchor domestic manufacturing capacity, while Eastern European project pipelines increasingly source from regional fabrication clusters to compress logistics expenditure.
Spain
Andalusia and Extremadura host the continent's densest concentration of tracker-equipped solar parks, where irradiance levels above 1,800 kWh/m² annually justify premium tracking investments. The EU Green Deal's binding renewable targets have accelerated environmental permitting reforms under the revised Renewable Energy Directive. Soltec Power Holdings SA maintains manufacturing scale in Murcia, supplying Mediterranean project pipelines with regionally fabricated torque tube assemblies.
Germany
Brandenburg and Saxony-Anhalt dominate utility-scale deployment, with grid connection queues favoring standardized tracker configurations for streamlined permitting. CE marking obligations under the Machinery Directive enforce interoperability standards that filter non-compliant suppliers from federal auction participation. Array Technologies Inc. has secured structural engineering contracts across high-wind zones in the northern plains.
Poland
The country's national renewable energy regulator has scaled capacity auctions with land availability profiles suited to tracker-equipped installations, particularly in the central Mazovia and Łódź regions. Domestic content requirements in Polish auction mechanisms favor regional fabrication over imports. Hybrid tracker configurations gain specification traction for transitional climate zones with erratic irradiance patterns.
Italy
Puglia and Sicily concentrate ground-mounted tracker deployment where agricultural land conversion faces fewer restrictions than in Northern Italy. The F-Gas Regulation imposes refrigerant restrictions on motor cooling systems, forcing redesign cycles for electromechanical drive architectures. Agricultural building retrofits in Lombardy represent a narrow niche where lightweight tracker designs gain traction.
Romania
The Dobrogea plateau and Banat region present favorable project economics for tracker-equipped installations given flat topography and high solar resource. The country's national renewable energy regulator has aligned auction mechanisms with EU Green Deal targets, tightening installation standards. Eastern European EPC contractors increasingly specify distributed drive architectures to reduce steel content on uneven terrain.
Europe Single-Axis Solar Tracker Market Competitive Landscape
On the supply side, the industry is moderately consolidated around a handful of vertically integrated manufacturers with European manufacturing footprints, while specialist component suppliers occupy fragmented niches in bearing assemblies and sensor modules. Two strategic archetypes dominate: integrated system houses controlling full mechanical and control stacks, and modular component specialists supplying torque tubes or drive units to third-party integrators. Competitive moves center on capacity expansion in Iberian Peninsula manufacturing clusters and technology licensing partnerships for predictive control algorithms.
Within the integrated system house tier, Soltec Power Holdings SA and Array Technologies Inc. exemplify divergent technical approaches to tracker architecture, while Nextracker Inc. occupies a position emphasizing distributed drive configurations. Ideematec Deutschland GmbH anchors German-speaking market presence through regional engineering capabilities. These three companies represent distinct competitive postures: Mediterranean manufacturing scale, structural engineering heritage, and terrain-adaptive mechanical design respectively.
| Leading Market Players |
|---|
| MecaSolar |
| Arctech Solar Holding Co. Ltd |
| Soltec Power Holdings SA |
| Valmont Industries Inc. |
| DCE Solar |
| Ideematec Deutschland GmbH |
| Array Technologies Inc. |
| P V Hardware |
| Nextracker Inc. |
| Others |
Supply & Pricing Matrix
Steel price volatility in Turkish and Ukrainian mill supply channels compresses project developer margins while simultaneously widening spreads between active tracker configurations and smart tracker premiums across European procurement cycles.
Pricing Analysis
Current-generation active electromechanical systems, prior-generation open-loop architectures, and next-generation machine-learning-enabled smart trackers stratify across premium, standard, and economy tiers. Price differentiation centers on CE marking certification grade and volume scale in utility-scale tenders. Cost compression in economy-tier open-loop systems is intensifying because Eastern European EPC contractors prioritize rapid payback over extended warranties. Commercial behind-the-meter installations exhibit highest price sensitivity; utility procurement with 25-year power purchase agreements shows lowest.
Supply Chain Analysis
Tariff exposure between Turkey and European Union member states dominates supply chain risk calculus for steel torque tube sourcing. Manufacturing concentrates in Spain, Germany, and emerging fabrication clusters in Poland and Romania. Raw material dependencies draw from Turkish steel mills, Ukrainian bearing assemblies, and Chinese linear actuator components. Distribution runs through EPC contractor integration with regional project developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's single-axis solar tracker market sits in early-cycle expansion as EU Green Deal binding targets trigger utility-scale capacity auction waves across Iberian and Eastern European markets.
For Market Incumbents: Harden predictive control algorithm portfolios against emerging software-native entrants through dedicated R&D center expansion in Mediterranean clusters. Deepen backward integration into steel torque tube production to offset Turkish mill price volatility. Secure EMA durability certification documentation ahead of CSRD supply chain disclosure mandates tightening qualification gates. For New Entrants and Emerging Players: Distributed drive architectures for uneven terrain in Romanian and Polish project pipelines represent the most penetrable entry point. Hybrid tracker configurations for transitional climate zones offer specification differentiation where incumbent portfolios concentrate on active systems. Partner with Eastern European EPC contractors for rapid commissioning credibility. For Investors and Strategic Acquirers: The market sits at a capacity-buildout phase that favors integrated system houses with captive manufacturing footprints. Long-term viability over the next decade rests on service revenue transformation from equipment-only sales toward performance-based yield guarantees. Watch F-Gas Regulation motor cooling redesign cycles as inflection signal for electromechanical drive architecture consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Control Algorithm Development | Machine-learning positioning layers outperform sensor-reactive systems in Spanish high-irradiance installations. |
| Backward Integration into Steel Fabrication | Captive torque tube production insulates margins from Turkish mill price volatility. |
| CSRD-Aligned Sustainability Certification | Verified 25-year operational life documentation gates bid participation in German federal auctions. |
| Performance-Based Service Contract Restructuring | Energy yield guarantees transfer operational risk from EPC contractors to tracker manufacturers. |
| Eastern European EPC Partnership Expansion | Polish and Romanian auction mechanisms favor regional fabrication over imports. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators; and secondary validation through IEA deployment databases, EU auction registry filings, FERC-equivalent grid connection queues, and customs trade records. Bottom-up project pipeline aggregation and top-down regulatory target triangulation anchored volume estimates.
Forecast inputs span tracker architecture type, installation configuration, procurement authority tier, and control system intelligence level across the projection horizon. CAGRs derive from segmented growth rate blending against policy milestone timing. Steel price trajectory assumptions and renewable energy auction schedule phasing constitute critical industry-specific variables.
Macroeconomic conditions sit as an overlay; deviation in eurozone industrial construction indices or Turkish steel export pricing would shift the trajectory. Forecasts embed assumptions around EU Green Deal target continuity and Machinery Directive enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar EPC Market
Renewable Energy
Wind Turbine Inspection Services Market
Renewable Energy
China Solar Photovoltaic Market
Renewable Energy
Global Solar Home Lighting Market
Renewable Energy
Global BIPV Glass Market
Renewable Energy
China Wind Power Market
Renewable Energy
Renewable Energy Consulting Market
Renewable Energy
Tunisia Renewable Energy Market
Renewable Energy
Asia-Pacific Renewable Energy Market
Renewable Energy
Solar Traffic Light Market
Renewable Energy
Middle East Renewable Energy Market
Renewable Energy
Wave Energy Converter Market
Renewable Energy
Renewable Energy Policy Fit Analysis Market
Renewable Energy
Renewable Energy Certificate Market
Renewable Energy
Ethiopia Renewable Energy Market
Renewable Energy
West Africa Renewable Energy Market