
 Global Renewable Energy Market | 2026-2036
Global Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Renewable Energy Market Outlook
Integrated solar-plus-storage bundling is consolidating buyer preference across utility procurement programs. NextEra Energy leverages its vertically integrated development model to capture full-project margins from origination through grid connection. Vestas Wind Systems anchors its competitive position through advanced blade manufacturing scale and offshore platform specialization. JinkoSolar Holding extends its reach via module efficiency leadership and distributed generation channel control.
Renewable energy encompasses power generation systems that harness naturally replenishing flows—solar irradiance, wind kinetic energy, biomass organic matter, and hydrological gradients—to produce electricity or thermal output with near-zero operational emissions. Photovoltaic cells convert sunlight directly into direct-current electricity through semiconductor junctions, while concentrated solar power deploys mirrors to focus thermal energy for steam turbine drives. Solar photovoltaic dominates installed capacity globally due to precipitous module cost declines and manufacturing scale concentration. Offshore wind represents the fastest-expanding technology segment as floating foundation designs unlock deeper-water sites with superior capacity factors. Industrial end users command the largest margin pool through long-term power purchase agreements that hedge volatile fossil fuel exposure.
The EU Green Deal and F-Gas Regulation constrain fluorinated gas use in grid infrastructure, compelling utilities to specify SF6-free switchgear in renewable interconnection projects. China's MIIT enforces GB standards for photovoltaic module efficiency and recycling obligations that shape manufacturing compliance costs for exporters. India's CEA mandates renewable purchase obligations that obligate discoms to source specified shares from solar, wind, and biomass categories. Stakeholders must monitor evolving carbon border adjustment mechanisms and domestic content requirements that threaten to fragment equipment sourcing strategies.
Market Dynamics
Integrated solar-plus-storage procurement packages are consolidating utility buyer preferences across Asia-Pacific markets, compressing standalone module margins while elevating full-system integrators. China's MIIT efficiency mandates and the EU F-Gas Regulation are simultaneously tightening equipment specifications and forcing switchgear substitutions.
Growth Catalysts
- EU Green Deal binding targets:Germany, Spain, and Poland must accelerate offshore wind auctions and green hydrogen electrolyzer deployments to meet 2030 milestones.
- Industrial offtake hedging:Data center operators in Virginia and semiconductor fabs in Taiwan are signing 15-20 year power purchase agreements to lock in price certainty against volatile natural gas futures.
- Floating foundation maturation:Norwegian and Japanese engineering consortia have validated semi-submersible platforms for 60+ meter water depths, unlocking capacity factors above 50%.
Market Restraints
- Polysilicon supply concentration:Xinjiang-based producers control 45% of global metallurgical-grade silicon refining, exposing module assemblers to forced labor due diligence risks and input cost volatility.
- SF6 switchgear phase-out:The EU F-Gas Regulation mandates fluorinated gas reductions in grid infrastructure, compelling utilities to absorb 30-40% cost premiums for vacuum interrupter alternatives during renewable interconnection projects.
- Interconnection queue congestion:ERCOT and CAISO interconnection backlogs now exceed 1,000 GW of solar and wind capacity, delaying project energization by 3-5 years regardless of permitting status.
Strategic Opportunities
- Green hydrogen offtake:The EU's Carbon Border Adjustment Mechanism will impose embodied carbon tariffs on imported steel and ammonia from 2026, creating premium demand for electrolyzer-produced hydrogen in Rotterdam and Hamburg industrial clusters.
- Distributed generation channel control:Residential solar installers in Australia and the Netherlands are bundling rooftop PV with home battery systems and virtual power plant enrollment, capturing recurring software revenue streams.
- Agrivoltaics convergence:German and Japanese pilot projects demonstrate dual-use solar arrays elevated above crops, generating electricity while maintaining agricultural output and qualifying for rural development subsidies.
Industry Challenges
- Grid-forming inverter engineering scarcity:Utility-scale battery projects require power electronics specialists capable of programming synthetic inertia and black-start capability, with fewer than 200 qualified engineers available across major EPC firms.
- Module recycling compliance:China's MIIT GB standards mandate photovoltaic recycling obligations that exporters must certify through third-party auditors, adding 2-4 months to customs clearance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Renewable Energy Market |
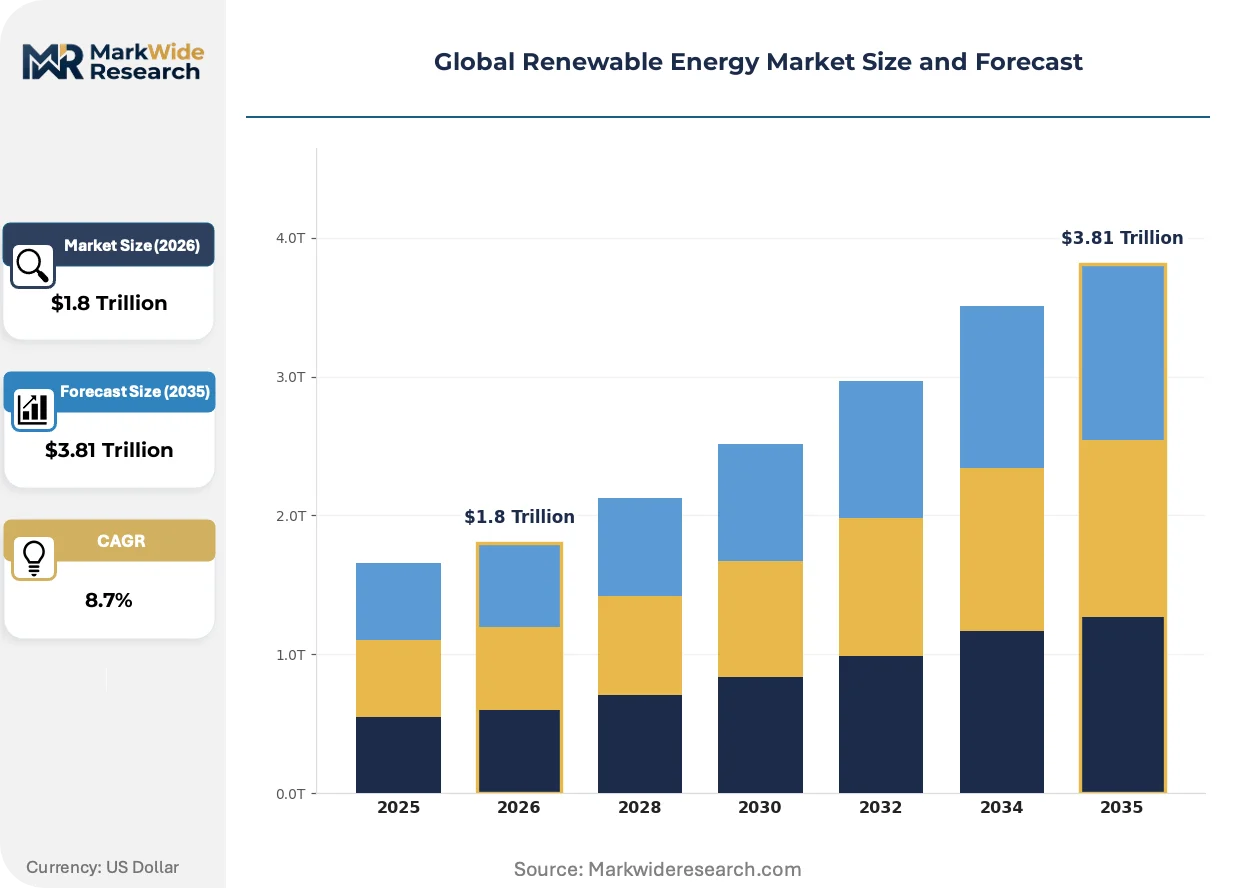
| Market Size in 2026 | $1.8 Trillion |
| Market Size in 2035 | $3.81 Trillion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Solar, Wind, Biomass, Hydro Technology: Photovoltaic, Concentrated Solar Power, Offshore Wind, Geothermal End User: Residential, Commercial, Industrial, Utilities Application: Electricity Generation, Heating, Transportation, Cooling |
| Companies Covered | NextEra Energy, Sungrow Power Supply, ACWA Power Company, GE Vernova, Vestas Wind Systems, LONGi Green Energy, Adani Green Energy, JinkoSolar Holding, Iberdrola, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Renewable Energy Market Strategic Shifts
Technology convergence between power generation and storage hardware is collapsing project development timelines. Regulatory pressure on embodied carbon and grid stability is forcing equipment redesigns. Buyer sophistication is shifting procurement evaluation criteria from component cost to lifetime system value.
Perovskite tandem cell architectures are absorbing incremental research investment from crystalline silicon incumbents. LONGi Solar and Oxford PV pilot lines in China and Germany are targeting 30%+ conversion efficiency by stacking thin-film layers atop conventional wafers. Utility procurement committees in Saudi Arabia and India are now requiring bankability guarantees for unproven cell chemistries, compressing technology adoption windows for unvalidated suppliers.
The EU F-Gas Regulation is prohibiting sulfur hexafluoride in new medium-voltage switchgear from 2026. Siemens Energy and ABB have accelerated vacuum interrupter and clean air insulation R&D to maintain European grid infrastructure market access. Offshore wind developers in the North Sea and Baltic Sea are specifying SF6-free substations to preempt construction-phase regulatory rejection.
Corporate renewable energy buyers are consolidating procurement through aggregated virtual power purchase agreements. Technology firms in Silicon Valley and pharmaceutical manufacturers in Basel are pooling demand to access utility-scale projects below 100 MW that would otherwise fail minimum offtake thresholds. This buyer aggregation model is most visible in Texas ERCOT and the Nordic Nord Pool markets where merchant price exposure can be syndicated across multiple creditworthy counterparties.
Global Renewable Energy Market Segmentation
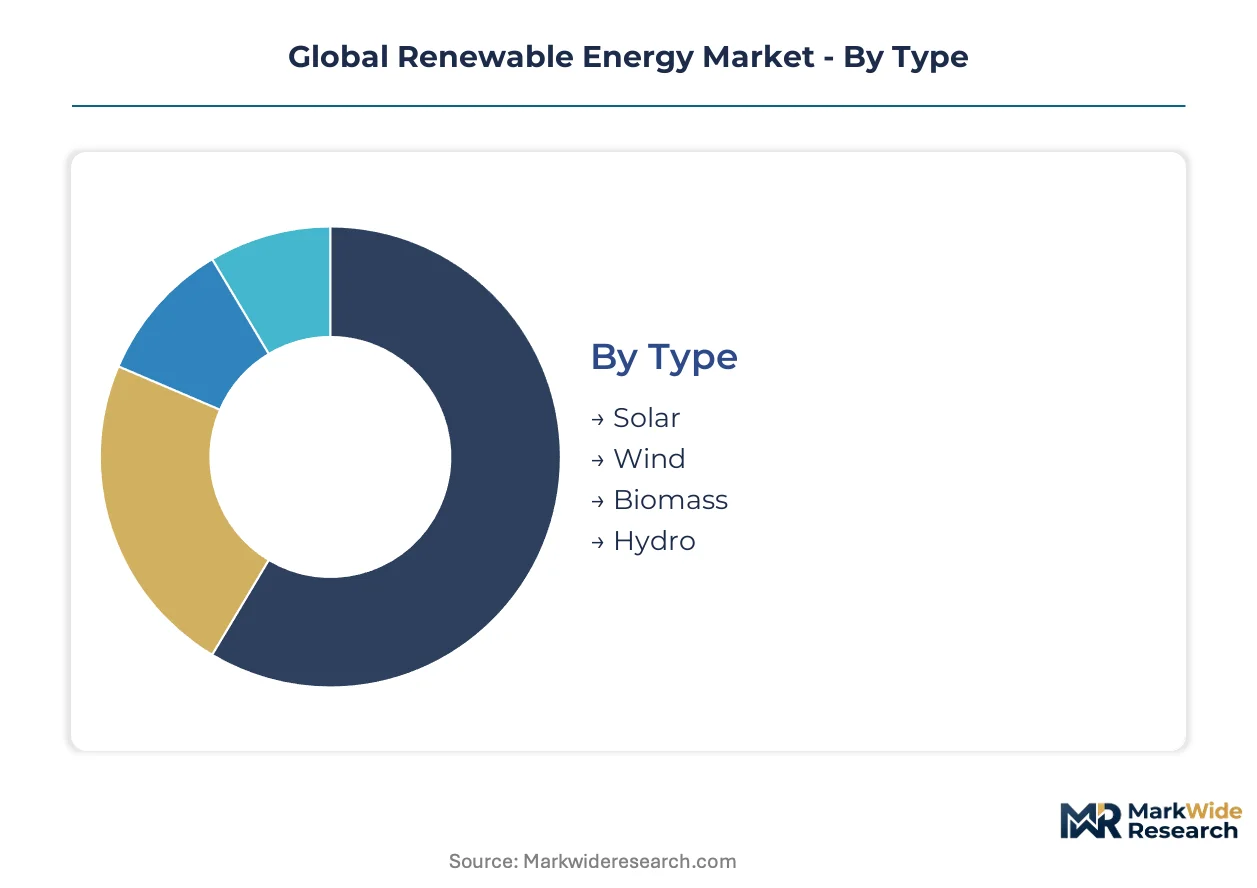
Technology heterogeneity across renewable energy systems creates divergent capital requirements, operational profiles, and customer access strategies. Equipment manufacturers and project developers must align R&D portfolios and channel investments against segment-specific margin structures and regulatory exposure.
Type:
Solar and wind deployments command the steepest upfront capital commitments due to manufacturing scale requirements and grid interconnection infrastructure.
- Solar:Photovoltaic arrays convert sunlight through semiconductor junctions, with crystalline silicon modules dominating utility-scale installations. China's MIIT efficiency mandates and India's CEA renewable purchase obligations are concentrating procurement in India, China, and Germany as these markets expand auction programs and grid modernization.
- Wind:Horizontal-axis turbines extract kinetic energy through aerodynamic blade rotation, with offshore platforms requiring floating foundation engineering. Norwegian and Japanese consortia are validating semi-submersible designs for 60+ meter depths, unlocking capacity factors above 50% in North Sea and Baltic Sea clusters.
- Biomass:Organic matter combustion and anaerobic digestion systems generate thermal and electrical output from agricultural residues and municipal waste. Feedstock logistics constraints limit deployment to rural industrial zones with established collection infrastructure.
- Hydro:Run-of-river and pumped-storage configurations harness gravitational water flow for baseload generation and grid balancing services. Environmental permitting complexity restricts greenfield development to retrofit and efficiency upgrade projects.
Solar absorbs the bulk of installed capacity; offshore wind is expanding most quickly.
Technology:
Technology selection determines project bankability timelines, with mature platforms offering construction certainty against emerging architectures promising efficiency breakthroughs.
- Photovoltaic:Crystalline silicon cells dominate manufacturing throughput, while perovskite tandem architectures from LONGi Solar and Oxford PV pilot lines target 30%+ conversion efficiency. Procurement committees in Saudi Arabia and India now require bankability guarantees for unproven chemistries.
- Concentrated Solar Power:Mirror arrays focus thermal energy onto heat transfer fluids for steam turbine drives, enabling molten salt storage integration. Deployment concentrates in Spain, Morocco, and South Africa where direct normal irradiance exceeds 2,000 kWh per square meter annually.
- Offshore Wind:Fixed-bottom foundations serve depths below 50 meters while floating platforms unlock deeper sites with superior wind resource consistency. Germany, Spain, and Poland must accelerate auctions to meet EU Green Deal 2030 milestones.
- Geothermal:Binary cycle and flash steam plants extract subsurface heat for electricity generation and direct-use heating. Reservoir characterization costs and drilling risk limit development to volcanic regions in Iceland, Kenya, and the Philippines.
Photovoltaic technology captures the greatest installed base; offshore wind platforms are climbing the fastest.
End User:
Customer scale determines contracting structures, with large offtakers securing long-term price certainty through power purchase agreements while smaller users prioritize capital accessibility.
- Residential:Distributed rooftop installations paired with battery storage and virtual power plant enrollment. Installers in Australia and the Netherlands are capturing recurring software revenue through bundled home energy management systems.
- Commercial:On-site generation serving retail, hospitality, and office facilities with behind-the-meter consumption and net metering arrangements. Aggregated virtual power purchase agreements are consolidating demand from technology firms in Silicon Valley and pharmaceutical manufacturers in Basel.
- Industrial:Process heat and electricity for manufacturing facilities with 15-20 year contracts hedging volatile fossil fuel exposure. Data center operators in Virginia and semiconductor fabs in Taiwan are locking in price certainty against natural gas futures volatility.
- Utilities:Centralized generation assets dispatching into transmission networks under regulated cost recovery or merchant market structures. Integrated solar-plus-storage packages are consolidating procurement preferences across Asia-Pacific utility programs.
Utility-scale projects absorb the bulk of capital deployment; commercial aggregated procurement is gaining share fastest.
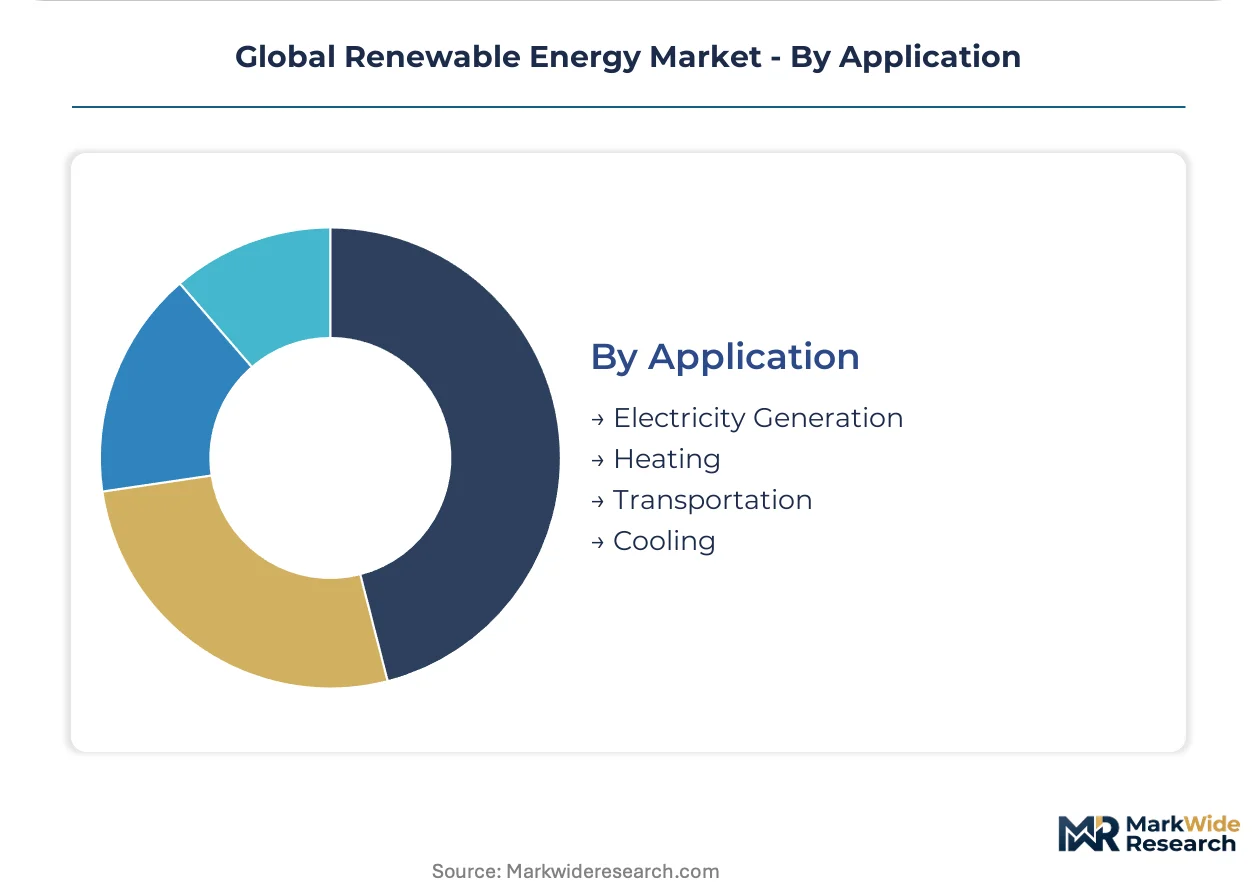
Application:
Application focus shapes equipment specifications, with electricity generation commanding manufacturing scale and thermal applications requiring site-specific engineering.
- Electricity Generation:Grid-connected renewable assets feeding transmission and distribution networks under dispatch protocols. Interconnection queue congestion at ERCOT and CAISO now exceeds 1,000 GW of delayed capacity regardless of permitting status.
- Heating:Solar thermal collectors and geothermal heat pumps serving residential and commercial thermal loads. EU F-Gas Regulation constraints on fluorinated gases are compelling SF6-free switchgear specifications in renewable interconnection projects.
- Transportation:Electrolyzer-produced hydrogen for fuel cell vehicles and maritime bunkering. The EU Carbon Border Adjustment Mechanism will impose embodied carbon tariffs on imported steel and ammonia from 2026, creating premium demand in Rotterdam and Hamburg industrial clusters.
- Cooling:Absorption chillers and solar-driven desiccant systems for commercial air conditioning. Deployment concentrates in Middle Eastern and South Asian markets with high cooling degree-days and constrained grid capacity.
Electricity generation absorbs the bulk of renewable output; green hydrogen for transportation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Fujian and Guangdong provinces are concentrating photovoltaic manufacturing investment through China's MIIT-backed efficiency mandates and export processing incentives.
China
Provincial governments in Jiangsu and Anhui are expanding utility-scale solar auctions under MIIT GB standards that enforce module recycling obligations. The Yangtze River Delta cluster anchors crystalline silicon wafer production, with pilot perovskite tandem lines from LONGi Solar targeting 30% conversion efficiency in Xian and Hefei manufacturing parks.
United States
Data center operators in Virginia and hyperscale cloud campuses in Nevada are executing 15-20 year power purchase agreements to hedge ERCOT and CAISO price volatility. FERC interconnection queue reforms face legislative deadlock while Texas and California backlogs exceed 1,000 GW of delayed renewable capacity regardless of permitting completion.
Germany
Industrial hydrogen demand from steelmakers in Duisburg and chemical producers in Ludwigshafen is accelerating electrolyzer deployments to meet EU Green Deal 2030 milestones. The EU F-Gas Regulation mandates SF6-free switchgear specifications, compelling Siemens Energy and ABB to deploy vacuum interrupter substations across North Sea offshore wind clusters.
India
Discoms in Gujarat and Rajasthan are procuring integrated solar-plus-storage packages under CEA renewable purchase obligations that specify solar, wind, and biomass sourcing shares. The Mundra and Kutch industrial zones are concentrating module assembly capacity to serve Middle East and African export markets.
Saudi Arabia
ACWA Power and sovereign development funds are commissioning gigawatt-scale solar and green hydrogen complexes in NEOM and Al-Jouf under long-term offtake arrangements with European industrial buyers. The kingdom's procurement committees now require bankability guarantees for unproven cell chemistries, compressing technology validation windows for emerging suppliers.
Global Renewable Energy Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology segments, with market structure tilting toward scale-driven consolidation in photovoltaic manufacturing and project development. Equipment vendors fragment across regional certification requirements while utility-scale developers concentrate through vertical integration into origination, construction, and grid interconnection. Three archetypes dominate: integrated technology conglomerates spanning generation and grid infrastructure, pure-play renewable developers with captive project pipelines, and specialist component manufacturers with channel control in distributed generation. Competitive dynamics center on manufacturing capacity expansion in Southeast Asia and strategic partnerships for floating offshore wind foundation engineering.
Within the integrated conglomerate tier, GE Vernova and Iberdrola occupy positions spanning turbine manufacturing through utility ownership and merchant power marketing. Among pure-play renewable developers, NextEra Energy exemplifies the vertically integrated model with control from project origination through grid connection, while Vestas Wind Systems anchors the specialist manufacturer archetype through blade manufacturing scale and offshore platform engineering concentration.
| Leading Market Players |
|---|
| NextEra Energy |
| Sungrow Power Supply |
| ACWA Power Company |
| GE Vernova |
| Vestas Wind Systems |
| LONGi Green Energy |
| Adani Green Energy |
| JinkoSolar Holding |
| Iberdrola |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers in China's Yangtze River Delta cluster anchor polysilicon refining capacity, translating concentrated ownership into pricing discipline that module assemblers absorb through long-term offtake contracts or vertical integration into wafer manufacturing.
Pricing Analysis
Margin tightening in crystalline silicon modules reflects Xinjiang-based metallurgical-grade silicon concentration and forced labor due diligence costs. Three-tier pricing structure across premium efficiency, standard utility-grade, and economy distributed-generation tiers separates bankable manufacturers from unproven entrants. Cost-down pressure accelerates as China's MIIT efficiency mandates compel R&D pass-through. Utility procurement committees exhibit lowest price sensitivity; residential installers face highest margin compression.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns for module delivery to project sites. Manufacturing concentrates in China, Vietnam, and Malaysia as Southeast Asian capacity expands to circumvent tariff exposure. Polysilicon, silver paste, and aluminum frames constitute critical input dependencies. Single-source vulnerability in Xinjiang polysilicon refining creates supply disruption risk. Distribution runs through EPC contractor networks with direct-to-utility channels for gigawatt-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
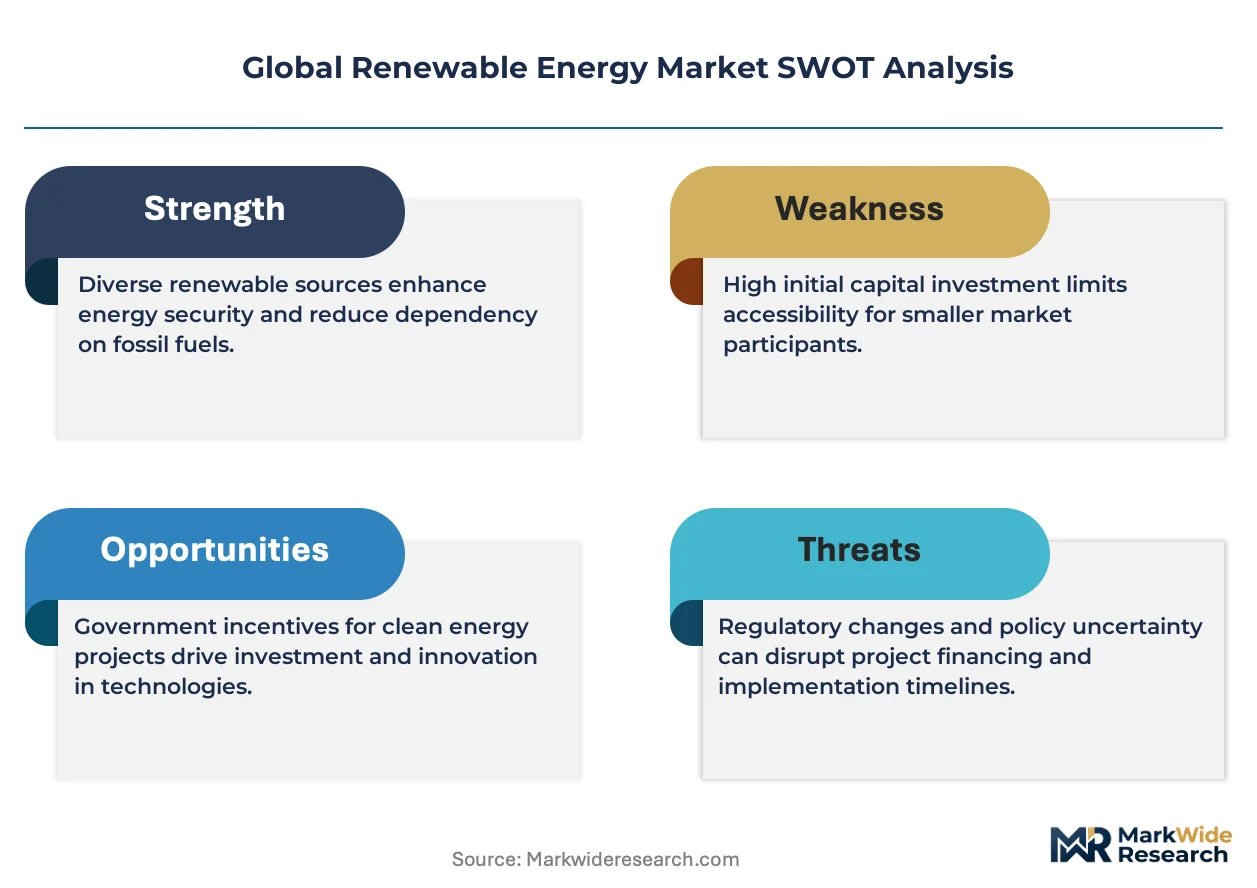
The EU F-Gas Regulation erects a compliance moat around SF6-free switchgear suppliers, fragmenting procurement access for non-compliant equipment vendors and rewarding early vacuum interrupter adopters with locked-in utility relationships.
For Market Incumbents: Hedge against polysilicon cost volatility through backward integration into wafer production or captive long-term supply agreements with Xinjiang-alternative producers. Accelerate perovskite tandem pilot lines to maintain efficiency leadership against LONGi Solar and Oxford PV. Defensive patent filings around floating foundation engineering preserve offshore wind positioning against Norwegian and Japanese consortia. For New Entrants and Emerging Players: The EU Carbon Border Adjustment Mechanism in Germany and the Netherlands opens a window for electrolyzer-integrated green hydrogen developers serving Rotterdam and Hamburg industrial clusters. Target agrivoltaics pilots in Japan and Germany where dual-use solar arrays qualify for rural development subsidies with lower land-cost barriers. Go-to-market through virtual power plant software platforms captures recurring revenue from residential battery aggregation in Australia. For Investors and Strategic Acquirers: FERC interconnection queue reform legislative movement is the leading indicator that ERCOT and CAISO backlog clearance will unlock delayed project energization. Five-to-ten year viability favors developers with permitted-but-unenergized capacity positions. Acquisition targets include grid-forming inverter engineering specialists with black-start programming capability. Watch floating offshore wind foundation certification milestones as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Solar-Plus-Storage Packaging | Captures full-system margins from Chinese and Indian utility procurement committees. |
| SF6-Free Switchgear Certification | Secures Siemens Energy and ABB access to EU offshore wind interconnection projects. |
| Perovskite Tandem Pilot Scale-Up | Validates 30% efficiency claims for Saudi Arabian and Indian bankability committees. |
| Floating Foundation Engineering Partnership | Unlocks 60-meter depth sites in North Sea and Baltic Sea clusters for Vestas. |
| Green Hydrogen Offtake Contracting | Positions ACWA Power and NEOM developers for EU Carbon Border Adjustment Mechanism premiums. |
Study Parameters
Document review covered IEA renewable deployment databases, FERC interconnection queue filings, and EU Green Deal regulatory texts, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from EIA capacity data, MIIT GB standard publications, and CEA renewable purchase obligation circulars. Bottom-up project pipeline aggregation and top-down policy target reconciliation enabled triangulation.
Installed capacity and revenue trajectories across the projection horizon reflect technology-specific learning curve assumptions and regulatory mandate enforcement timelines. Segmentation dimensions modeled include generation source, project capacity tier, end-use customer scale, and regional grid interconnection framework. CAGRs derive from compound application of technology cost reduction rates and policy-driven deployment floors. Forecast inputs incorporate polysilicon supply concentration risk and floating offshore wind foundation certification progress.
The model assumes a particular technology adoption path; alternative pathways for perovskite tandem commercialization or solid-state battery integration would alter the outlook. Forecasts reflect documented assumptions regarding EU F-Gas Regulation enforcement timing and China's MIIT recycling obligation implementation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Boat Market
Renewable Energy
Global BIPV Glass Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Azerbaijan Renewable Energy Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
Turkey Renewable Energy Market
Renewable Energy
Renewable Energy Policy Fit Analysis Market
Renewable Energy
China Renewable Energy Market
Renewable Energy
Israel Renewable Energy Market
Renewable Energy
Poland Renewable Energy Market
Renewable Energy
Mexico Renewable Energy Market
Renewable Energy
Venezuela Renewable Energy Market
Renewable Energy
Southeast Asia Renewable Energy Market
Renewable Energy
Green Energy Lighting Market
Renewable Energy
North Africa Renewable Energy Market
Renewable Energy
Wind Turbine Foundation Market