
 South Africa Renewable Energy Market | 2026-2036
South Africa Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Renewable Energy Market Analytics
Buyer concentration among South African mining houses and large industrial off-takers is restructuring procurement channels for renewable energy, shifting volume away from traditional utility-tied models toward bilateral contracts. Mainstream Renewable Power leverages its early-mover position in the Northern Cape to sustain pipeline dominance across utility-scale wind and solar assets. Enel Green Power competes through technology transfer partnerships that anchor its engineering presence in the Western Cape. SolarAfrica specializes in commercial and industrial rooftop deployments, occupying a differentiated niche below the utility-scale threshold.
South Africa renewable energy encompasses electricity generation from solar PV, wind, biomass, and hydropower resources, typically deployed through centralized plants above 1 MW or distributed systems integrated at medium-voltage substations, with modern installations incorporating grid-forming inverters and lithium-ion storage buffers to manage frequency response. The primary purpose is displacing coal-fired baseload while stabilizing a transmission network constrained by aging infrastructure and spatial mismatches between generation and demand centers. Solar PV leads technology deployment due to modularity and declining module costs, though wind commands higher capacity factors in the Eastern Cape corridor. Grid integration services carry premium margins as Eskom's network constraints force developers to fund dedicated transmission upgrades. Energy storage applications represent the fastest-growing segment as regulatory reforms enable merchant revenue stacking through ancillary services.
The National Energy Regulator of South Africa (NERSA) governs generation licensing and tariff approvals, while the Department of Mineral Resources and Energy administers the Integrated Resource Plan and bid window schedules that determine annual procurement caps. BIS certification requirements for imported solar modules and the South African Revenue Service's customs enforcement shape equipment sourcing strategies and local assembly economics. Stakeholders must monitor NERSA's pending distributed generation frameworks and the timeline for municipal wheeling regulations that would unlock commercial-industrial demand outside metropolitan supply areas.
Market Dynamics
The Integrated Resource Plan revision and declining battery storage costs are redirecting capital toward hybrid solar-wind installations, compressing project development timelines and reshaping procurement channels for mining houses and industrial off-takers.
Growth Catalysts
- Integrated Resource Plan procurement windows:The Department of Mineral Resources and Energy schedules annual bid windows that create predictable demand pipelines for utility-scale developers.
- Northern Cape mining corridor electrification:Mining houses accelerate direct power purchase agreements with independent producers to secure baseload supply and hedge against Eskom tariff volatility.
- Lithium-ion cost curves:Declining battery storage costs enable merchant revenue stacking through ancillary services, improving project economics for hybrid installations.
Market Restraints
- Transmission infrastructure deficit:Eskom's aging network and spatial mismatches between generation and demand centers force developers to fund dedicated transmission upgrades, inflating capex requirements.
- BIS certification bottlenecks:Bureau of Indian Standards requirements for imported solar modules and South African Revenue Service customs enforcement create equipment sourcing delays and local assembly cost premiums.
- Grid integration complexity:Grid-forming inverter deployment and frequency response management require specialized engineering capabilities scarce in the domestic labor market.
Strategic Opportunities
- Municipal wheeling frameworks:Pending NERSA regulations would unlock commercial-industrial demand outside metropolitan supply areas, expanding addressable market for distributed generators.
- Western Cape industrial corridor expansion:The Atlantis Special Economic Zone and surrounding areas concentrate manufacturing demand underserved by current utility-tied models.
- Hybrid technology convergence:Solar-wind-battery configurations optimize capacity factors and reduce curtailment risk, attracting capital from risk-averse institutional investors.
Industry Challenges
- Grid code compliance timelines:NERSA licensing and tariff approval processes extend project development cycles, compressing developer margins and delaying revenue recognition.
- Specialized construction labor scarcity:Medium-voltage substation integration and high-voltage cabling installation require certified technicians in short supply across the Eastern Cape and Northern Cape provinces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Renewable Energy Market |
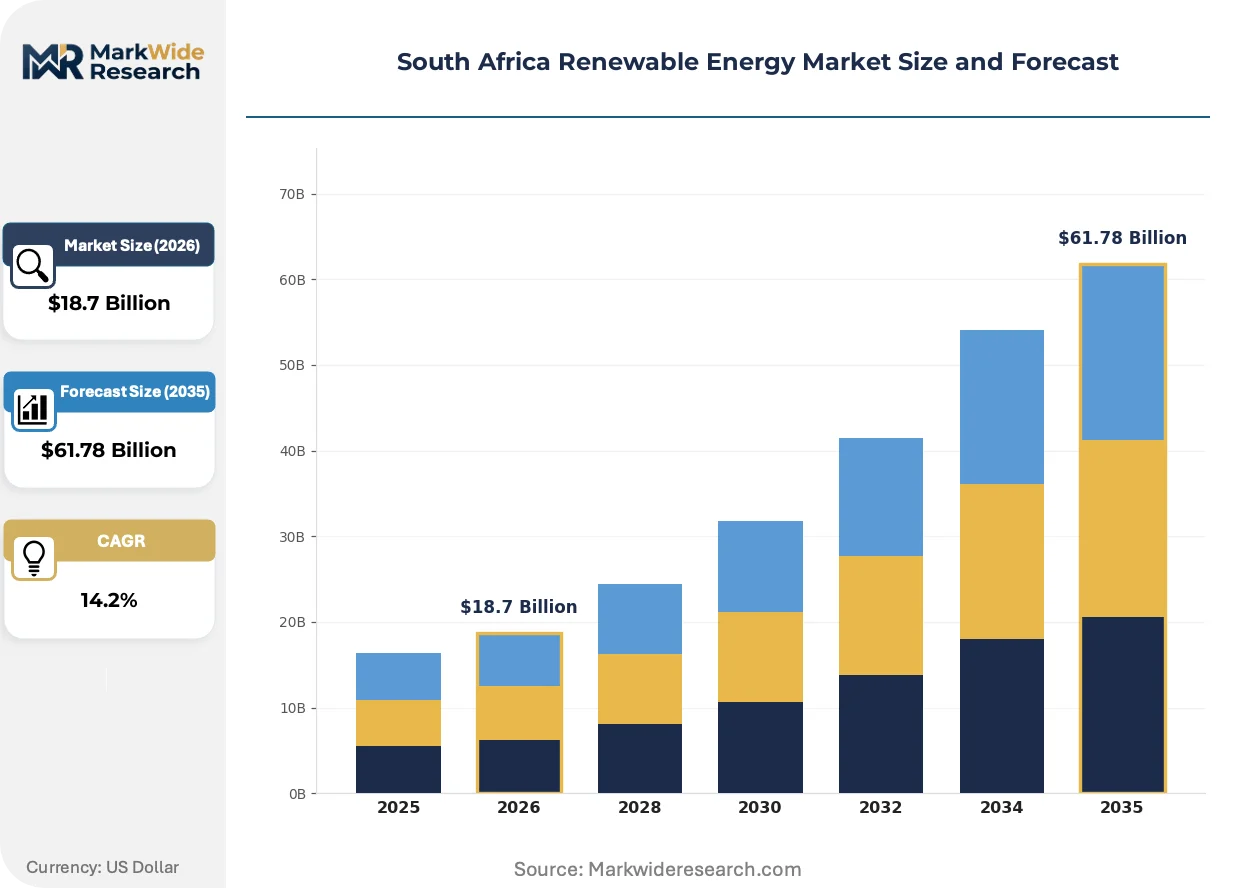
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar PV, Wind, Biomass, Hydropower Service Type: Installation, Maintenance, Consultancy, Financing End User: Residential, Commercial, Industrial, Government Application: Power Generation, Off-Grid Solutions, Grid Integration, Energy Storage |
| Companies Covered | Mainstream Renewable Power, Enel Green Power, Anthem, SolarAfrica, Open Access Energy, Sustainable Power Solutions, Etana Energy, SolarTurtle, Standard Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Renewable Energy Market Evolving Landscape
Technology convergence and regulatory experimentation are compressing traditional utility-tied procurement models while elevating merchant and bilateral contracting structures. These shifts redistribute value capture across the value chain.
Grid-forming inverter technology is integrating lithium-ion storage buffers to manage frequency response and provide synthetic inertia services previously delivered by coal-fired turbines. Mining houses in the Northern Cape are deploying these configurations at utility-scale wind and solar assets to reduce dependence on Eskom's constrained transmission network. This integration is enabling bilateral power purchase agreements that bypass traditional utility intermediation, compressing procurement channel margins and accelerating capital deployment timelines.
NERSA's pending distributed generation frameworks and municipal wheeling regulations represent the most significant regulatory experiment in South Africa's electricity sector since the Renewable Energy Independent Power Producer Procurement Programme. These reforms would permit commercial and industrial consumers to contract directly with generators outside their licensed distribution areas, fundamentally restructuring supply relationships. The Western Cape's Atlantis Special Economic Zone stands to benefit earliest, as municipal infrastructure and industrial load concentration create favorable conditions for regulatory pilot implementation.
Buyer concentration among mining houses and large industrial off-takers is fragmenting procurement authority away from centralized utility procurement toward bilateral negotiations with independent power producers. This concentration compresses developer sales cycles but intensifies price negotiation leverage, squeezing margins on standardized equipment packages. The shift is most visible in the Northern Cape, where De Beers, Anglo American, and Kumba Iron Ore operations have established direct contracting precedents that neighboring mining operations now replicate.
South Africa Renewable Energy Market Segmentation
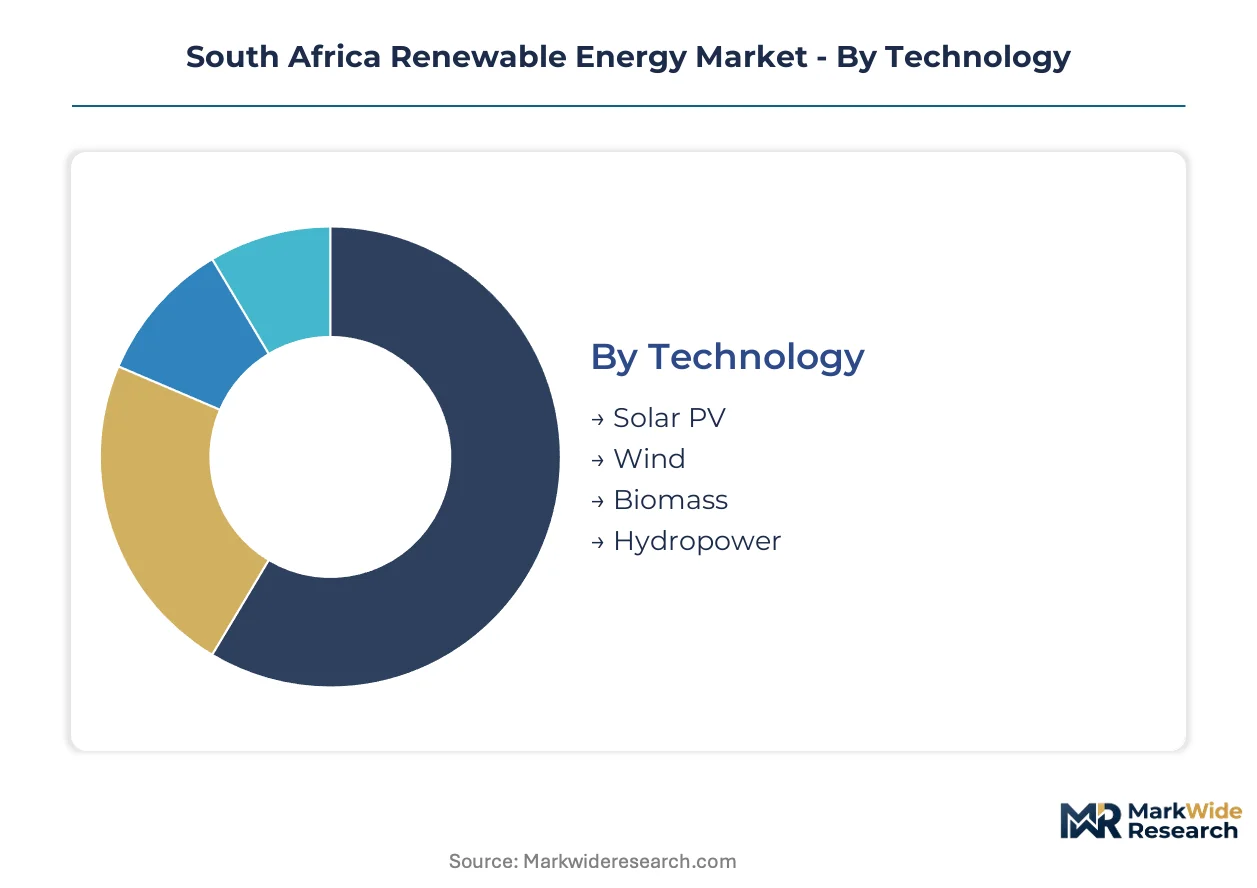
South Africa's renewable energy market segments along technology, service, end-user, and application dimensions, each carrying distinct certification burdens from NERSA and BIS that shape procurement economics. Understanding these divides clarifies where capital concentrates and which regulatory pathways govern market entry.
Technology:
BIS certification requirements and NERSA licensing protocols apply differentially across generation technologies, with module standards and grid code compliance timelines varying by equipment type.
- Solar PV:Modular crystalline silicon and thin-film configurations dominate procurement volumes. Atlantis Special Economic Zone manufacturers and Northern Cape mining houses drive demand for utility-scale and distributed rooftop arrays respectively, with BIS module certification creating sourcing bottlenecks for imported equipment.
- Wind:Horizontal-axis turbines with capacity factors exceeding solar in the Eastern Cape corridor. Grid-forming inverter integration and synthetic inertia services attract institutional capital seeking merchant revenue streams, though specialized construction labor scarcity inflates installation costs.
- Biomass:Organic waste-to-energy systems utilizing agricultural residues. Feedstock supply agreements and environmental impact assessments govern project viability in KwaZulu-Natal sugar belt regions.
- Hydropower:Run-of-river and small-scale pumped storage configurations. Water use licensing from the Department of Water and Sanitation constrains development timelines.
Solar PV sits at the top of the volume ranking, with Energy Storage climbing the fastest through hybrid installation convergence.
Service Type:
Margin structures across the service stack reflect capital intensity and technical specialization, with financing and grid integration commanding premium returns relative to commoditized installation labor.
- Installation:Medium-voltage substation integration and high-voltage cabling deployment. Certified technician scarcity across Eastern Cape and Northern Cape provinces compresses execution timelines and inflates labor rates.
- Maintenance:Preventive and corrective servicing of inverters, transformers, and storage systems. Long-term service agreements anchor recurring revenue for independent power producers.
- Consultancy:Feasibility studies, environmental impact assessments, and grid code compliance documentation. NERSA licensing support and tariff structuring expertise differentiate premium providers.
- Financing:Project debt, tax equity, and merchant offtake structuring. Mining house bilateral PPA templates and development finance institution participation reshape capital stack composition.
Financing captures the steepest margin expansion trajectory, with Installation facing the most acute price compression from labor supply constraints.
End User:
Procurement authority fragmentation distinguishes centralized utility-tied demand from bilateral contracting patterns emerging among large off-takers.
- Residential:Distributed rooftop systems below 1 MW threshold. Municipal wheeling framework uncertainty limits addressable market to metropolitan supply areas with favorable net metering policies.
- Commercial:Medium-scale installations for retail, hospitality, and office complexes. Atlantis Special Economic Zone concentration creates cluster economies for shared infrastructure and maintenance services.
- Industrial:Mining houses and manufacturing facilities pursuing baseload security. Northern Cape platinum and iron ore operations establish direct PPA precedents that neighboring sites replicate.
- Government:Public sector procurement through Department of Mineral Resources and Energy bid windows. Integrated Resource Plan scheduling creates predictable but lumpy demand pipelines.
Industrial off-takers anchor current volume leadership, with Commercial segments expanding most quickly pending municipal wheeling regulatory clarity.
Application:
Revenue model differentiation separates regulated utility-tied generation from merchant and bilateral structures enabled by storage and grid services.
- Power Generation:Utility-scale solar and wind feeding Eskom's transmission network. Spatial mismatches between Northern Cape resource abundance and Gauteng demand centers force developer-funded transmission upgrades.
- Off-Grid Solutions:Mini-grids and captive power for remote mining and rural communities. Diesel displacement economics drive payback calculations in areas with unreliable grid access.
- Grid Integration:Dedicated transmission infrastructure and grid-forming inverter deployment. Synthetic inertia and frequency response services unlock ancillary revenue streams.
- Energy Storage:Lithium-ion buffers for arbitrage, backup, and grid stabilization. Declining battery cost curves and merchant revenue stacking improve project economics for hybrid solar-wind configurations.
Power Generation retains dominant volume share, with Grid Integration gaining share fastest as network constraints force premium infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's renewable energy expansion outpaces neighboring markets in installed capacity growth, while Namibia and Botswana accelerate regulatory reforms to capture spillover investment from the Southern African Power Pool.
Northern Cape
Platinum and iron ore mining houses drive direct power purchase agreement demand across the Kalahari manganese field. The Department of Mineral Resources and Energy's Integrated Resource Plan bid windows channel utility-scale solar and wind procurement toward Upington and Springbok industrial corridors. De Beers and Anglo American operations establish bilateral contracting templates that neighboring extraction sites replicate.
Western Cape
The Atlantis Special Economic Zone concentrates manufacturing load seeking distributed generation alternatives to municipal supply constraints. NERSA's pending municipal wheeling regulations would unlock cross-boundary energy trading for Cape Town industrial parks. Stellenbosch and Paarl wine processing facilities pilot commercial rooftop solar aggregations.
Eastern Cape
Wind capacity factors exceed solar generation profiles along the Wild Coast and Amathole district corridors. Grid-forming inverter deployment and synthetic inertia services attract merchant revenue-seeking developers to East London industrial zones. Specialized high-voltage cabling technicians remain scarce, inflating construction timelines.
KwaZulu-Natal
Sugar belt biomass-to-energy projects leverage agricultural residue feedstock agreements in the Umfolozi and Midlands regions. Water use licensing from the Department of Water and Sanitation constrains run-of-river hydropower development timelines. Richards Bay mineral processing facilities evaluate captive power to offset grid reliability risks.
Gauteng
Spatial mismatches between Northern Cape generation abundance and Johannesburg-Pretoria demand centers force transmission upgrade investments. Eskom's constrained network prioritizes grid integration services with premium margin structures. Tshwane and Ekurhuleni municipalities pilot distributed generation frameworks ahead of national regulatory finalization.
South Africa Renewable Energy Market Competitive Landscape
Northern Cape project developers anchor one competitive tier; Western Cape engineering specialists hold differentiated positions in grid integration and commercial rooftop deployment. Market structure fragments across utility-scale independent power producers, commercial-industrial distributed generators, and financial institutions structuring mining house bilateral power purchase agreements. Three archetypes dominate: early-mover pipeline developers with established land positions, technology-transfer joint ventures leveraging foreign engineering expertise, and captive finance arms of commercial banks. Capacity expansion and strategic partnerships constitute the dominant competitive moves as developers secure construction labor and transmission access ahead of regulatory window openings.
Within the utility-scale developer tier, Mainstream Renewable Power and Enel Green Power occupy positions shaped by geographic concentration and partnership structures. Mainstream Renewable Power exemplifies early-mover pipeline dominance across Northern Cape wind and solar assets. Enel Green Power represents technology-transfer joint ventures that anchor engineering presence in Western Cape industrial corridors. SolarAfrica sits within the commercial-industrial distributed generation segment, specializing in rooftop deployments below utility-scale thresholds.
| Leading Market Players |
|---|
| Mainstream Renewable Power |
| Enel Green Power |
| Anthem |
| SolarAfrica |
| Open Access Energy |
| Sustainable Power Solutions |
| Etana Energy |
| SolarTurtle |
| Standard Bank |
| Others |
Value Network & Pricing Analysis
Mining house procurement consolidation across the Northern Cape platinum and iron ore corridors is compressing developer margins and forcing equipment suppliers to absorb cost pressure through volume commitments and extended payment terms. This buyer-side concentration reshapes how module manufacturers and EPC contractors structure pricing, with BIS certification requirements for imported solar equipment adding compliance premiums that suppliers must either pass through or offset through local assembly partnerships.
Pricing Analysis
Capacity additions in the Eastern Cape wind corridor are reshaping price floors for grid-connected generation, intensifying competition among independent power producers bidding into Department of Mineral Resources and Energy procurement windows. Three-tier pricing structure across premium, standard, and economy levels separates grid-forming inverter packages with synthetic inertia services from basic frequency-compliant configurations. Cost compression in standardized module supply runs through aggressive procurement by mining houses leveraging bilateral PPA templates. Commercial and industrial rooftop segments exhibit highest price sensitivity due to municipal wheeling framework uncertainty, while utility-scale developers with secured transmission access demonstrate lowest sensitivity.
Supply Chain Analysis
Domestic-content mandates under South Africa's Renewable Energy Independent Power Producer Procurement Programme localisation requirements are reshaping sourcing strategies, compelling developers to establish module assembly partnerships within special economic zones. Equipment supply draws from China, India, and Vietnam for crystalline silicon modules, with lithium-ion battery cells predominantly sourced from South Korea and China. Raw material dependencies span polysilicon feedstock, lithium carbonate, and high-grade steel for turbine towers. Single-source vulnerability concentrates in grid-forming inverter power electronics where qualified suppliers remain limited. Distribution runs through port-of-entry logistics at Durban and Cape Town, with inland rail and road corridors serving Northern Cape and Eastern Cape project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's renewable energy market functions as a stable compounder anchored by the Integrated Resource Plan's scheduled procurement windows, which institutionalise predictable demand pipelines across multi-year horizons.
For Market Incumbents: Extend transmission access portfolios through early land positioning and grid connection queue priority ahead of NERSA licensing reforms, while deepening backward integration into module assembly to neutralise BIS certification bottlenecks. Defensive consolidation should target certified construction labour pools in the Eastern Cape where technician scarcity inflates project timelines. The emerging threat of municipal wheeling regulatory delays compressing commercial segment margins demands proactive channel control through direct industrial off-taker relationships. For New Entrants and Emerging Players: Commercial wine processing facilities in the Western Cape Stellenbosch-Paarl corridor represent an underserved buyer archetype with aggregatable rooftop load and limited incumbent penetration. This segment offers white-space access through shared infrastructure models that reduce per-site development costs. Grid integration services for hybrid solar-wind-battery configurations present a second penetrable entry point, leveraging scarce engineering capabilities as differentiation. A go-to-market angle anchored on merchant revenue stacking through ancillary services bypasses utility-tied procurement complexity. For Investors and Strategic Acquirers: Asymmetric upside sits with early-mover pipeline developers holding secured land positions and grid connection agreements across Northern Cape wind and solar zones. Long-term viability across the projection horizon rests on regulatory execution consistency rather than technology disruption risk. Acquisition targets should prioritise developers with established mining house bilateral PPA relationships. The signal to watch is NERSA's final distributed generation framework release, which would unlock commercial-industrial demand outside metropolitan supply areas and re-rate distributed generation portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Technology Licensing | Enables merchant revenue stacking through synthetic inertia services at Eastern Cape wind assets. |
| Municipal Wheeling Partnership | Unlocks cross-boundary energy trading for Atlantis Special Economic Zone manufacturing load. |
| Backward Integration into Storage | Captures lithium-ion cost curve benefits and secures supply for hybrid installation pipelines. |
| Certified Labour Pool Acquisition | Neutralises construction timeline inflation from high-voltage cabling technician scarcity. |
| Grid Connection Queue Priority | Secures transmission access ahead of Integrated Resource Plan bid window allocations. |
Research Methodology
Multiple input streams — developer project pipeline disclosures, Eskom transmission planning documents, and mining house procurement announcements — were reconciled against NERSA licensing records and Department of Mineral Resources and Energy bid window awards. Primary interviews with IPP project developers, EPC contractors, grid operators, and mining house energy procurement officers were validated through secondary sources including IEA country reports, EIA international energy data, and project finance database tracking. Bottom-up capacity addition modelling and top-down macroeconomic demand projections were triangulated to establish market sizing.
Data-stream reconciliation across technology, service type, end-user, and application dimensions anchored the analytical framework over the projection horizon. Segmentation modelling incorporated generation capacity tier, regulatory framework, and regional grid type as core dimensions. CAGRs were derived from weighted average growth trajectories across these segments. Key forecast inputs included lithium-ion battery cost curve assumptions and municipal wheeling regulatory implementation timelines.
Underlying measurement precision varies by segment; utility-scale power generation carries tighter precision than emerging energy storage applications due to disclosed project-level data availability. Forecasts reflect assumptions regarding NERSA licensing throughput and Eskom transmission upgrade execution. Regulatory delay risk, commodity price volatility in module supply chains, and construction labour availability constraints warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
North America Ocean Power Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
Solar Street Lighting Market
Renewable Energy
Nigeria Renewable Energy Market
Renewable Energy
Solar PV and Wind Energy Market
Renewable Energy
Solar Chair Market
Renewable Energy
Egypt Renewable Energy Market
Renewable Energy
Philippines Renewable Energy Market
Renewable Energy
Wind Turbine Inspection Drones Market
Renewable Energy
Hybrid Solar Wind Diesel Market
Renewable Energy
Kazakhstan Renewable Energy Market
Renewable Energy
Azerbaijan Renewable Energy Market
Renewable Energy
Green Energy Lighting Market
Renewable Energy
Renewable Energy Enclosures Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
China Wind Energy Market