
 Offshore Wind Energy Infrastructure Market | 2026-2036
Offshore Wind Energy Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Wind Energy Infrastructure Market Analytics
Aftermarket service revenue is fragmenting across turbine OEMs and independent service providers as fleet ages expand. Siemens Gamesa Renewable Energy leverages its installed base to capture long-term service contracts across European waters. Vestas Wind Systems anchors its competitiveness through predictive maintenance platforms that reduce vessel dispatch costs. Ørsted controls project development margins by integrating in-house installation capabilities with external foundation suppliers.
Offshore wind energy infrastructure encompasses the engineered systems required to capture, convert, and transmit wind-generated electricity from marine environments, including monopile and jacket foundations rated for water depths exceeding 60 meters, inter-array cables carrying 33-66 kV, and turbine generators scaled beyond 12 MW. Fixed Structures dominate current capital deployment due to proven installation economics in shallow continental shelves. Floating Systems attract the fastest-growing engineering investment as developers target deeper basins off Portugal and Japan where seabed-fixed solutions prove impractical. Subsea Cables concentrate margin pools with specialized manufacturers holding IEC 62288 certification barriers.
The EU Green Deal and national maritime spatial planning directives in Germany and Denmark shape site allocation and environmental permitting timelines. The International Electrotechnical Commission maintains IEC 61400-3-1 standards governing turbine design conditions for offshore mechanical loads. Stakeholders must monitor evolving auction design mechanisms that increasingly tie seabed leases to domestic content requirements and grid connection timelines.
Market Dynamics
The transition from monopile to floating foundation systems is compressing installation windows and redrawing competitive boundaries as developers target water depths beyond 60 meters. This structural shift demands new vessel capabilities and specialized port infrastructure.
Growth Catalysts
- EU Green Deal auction mechanisms:Germany and Denmark tie seabed leases to accelerated grid connection timelines, pulling forward project commitments.
- Floating foundation engineering:Semi-submersible and tension-leg platforms unlock development in Portugal's deep Atlantic basins.
- Power purchase agreements:Corporate offtakers in the Netherlands secure long-term contracts that de-risk capital deployment for developers.
Market Restraints
- Steel input cost volatility:Monopile and jacket fabrication depends on heavy plate supply concentrated in East Asian mills.
- Installation vessel scarcity:Specialized jack-up fleets number fewer than fifteen units capable of handling 15 MW+ turbines.
- Grid interconnection queues:Onshore substation upgrades in Germany face permitting delays stretching 36-48 months.
Strategic Opportunities
- Japanese deepwater zones:METI feed-in tariff revisions target 4 GW of floating capacity off Kyushu and Hokkaido coastlines.
- Green hydrogen integration:Electrolyzer co-location at offshore substations creates captive demand for curtailed generation.
- Digital twin convergence:Predictive maintenance platforms fused with SCADA systems reduce vessel dispatch frequency.
Industry Challenges
- Marine electrical technician shortage:High-voltage cable jointing and turbine commissioning require certifications held by fewer than 2,000 specialists across European waters.
- IEC 61400-3-1 type certification timelines:New turbine platforms face 18-24 month validation cycles before commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Wind Energy Infrastructure Market |
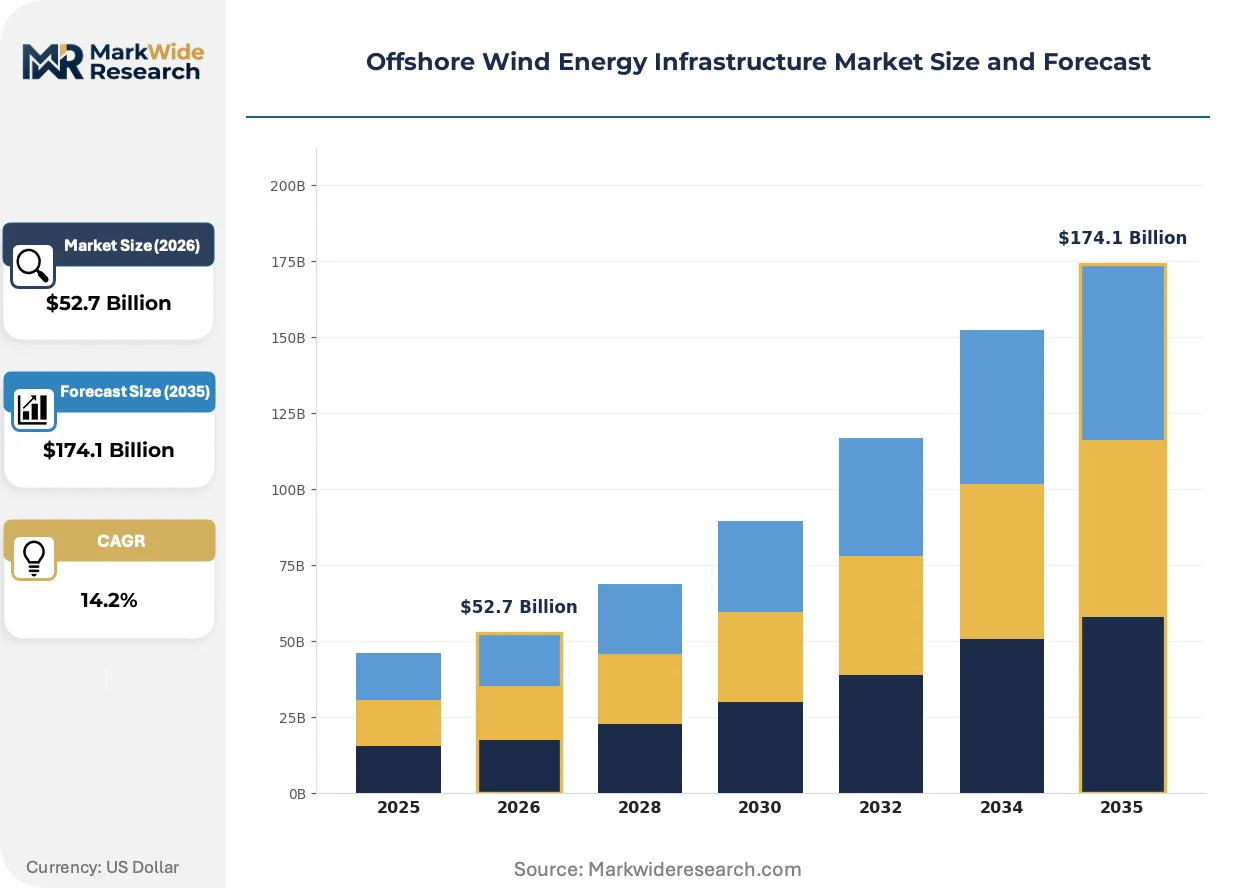
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $174.1 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fixed Structures, Floating Systems, Subsea Cables, Wind Turbines Component: Transformers, Foundations, Generators, Switchgear End User: Utilities, Private Developers, Governments, Energy Cooperatives Service Type: Installation, Maintenance, Operation, Consulting |
| Companies Covered | Siemens Gamesa Renewable Energy, Vestas Wind Systems, Ørsted, GE Vernova, MHI Vestas Offshore Wind, Xinjiang Goldwind Science & Technology, Ming Yang Smart Energy, Nordex, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Wind Energy Infrastructure Market Evolving Landscape
Digitalization is compressing operational expenditure curves while foundation technology unlocks previously inaccessible seabed territories. These shifts are reconfiguring asset ownership structures and service delivery models.
Digital twin platforms for turbine drivetrain monitoring aggregate sensor data from gearbox bearings, generators, and power converters into unified degradation models. Ørsted and RWE deploy these systems across North Sea fleets to schedule component replacement before failure. The technology is virtualizing traditional time-based maintenance schedules into condition-triggered interventions.
The EU Green Deal's revised Renewable Energy Directive tightens domestic content thresholds for auction eligibility, requiring 40% European-manufactured components by project completion. Developers in Germany and the Netherlands now pre-qualify foundation suppliers based on mill location and fabrication yard proximity. This policy is forcing Asian steel producers to establish European rolling capacity or lose market access.
Utility procurement teams unbundle long-term service agreements into discrete work packages covering blade repair, drivetrain overhaul, and cable maintenance. Independent service providers capture scope previously held by turbine OEMs through specialized vessel charters and technician pools. This fragmentation is most advanced in Danish waters where Ørsted's fleet scale supports multi-vendor contracting strategies.
Offshore Wind Energy Infrastructure Market Segmentation
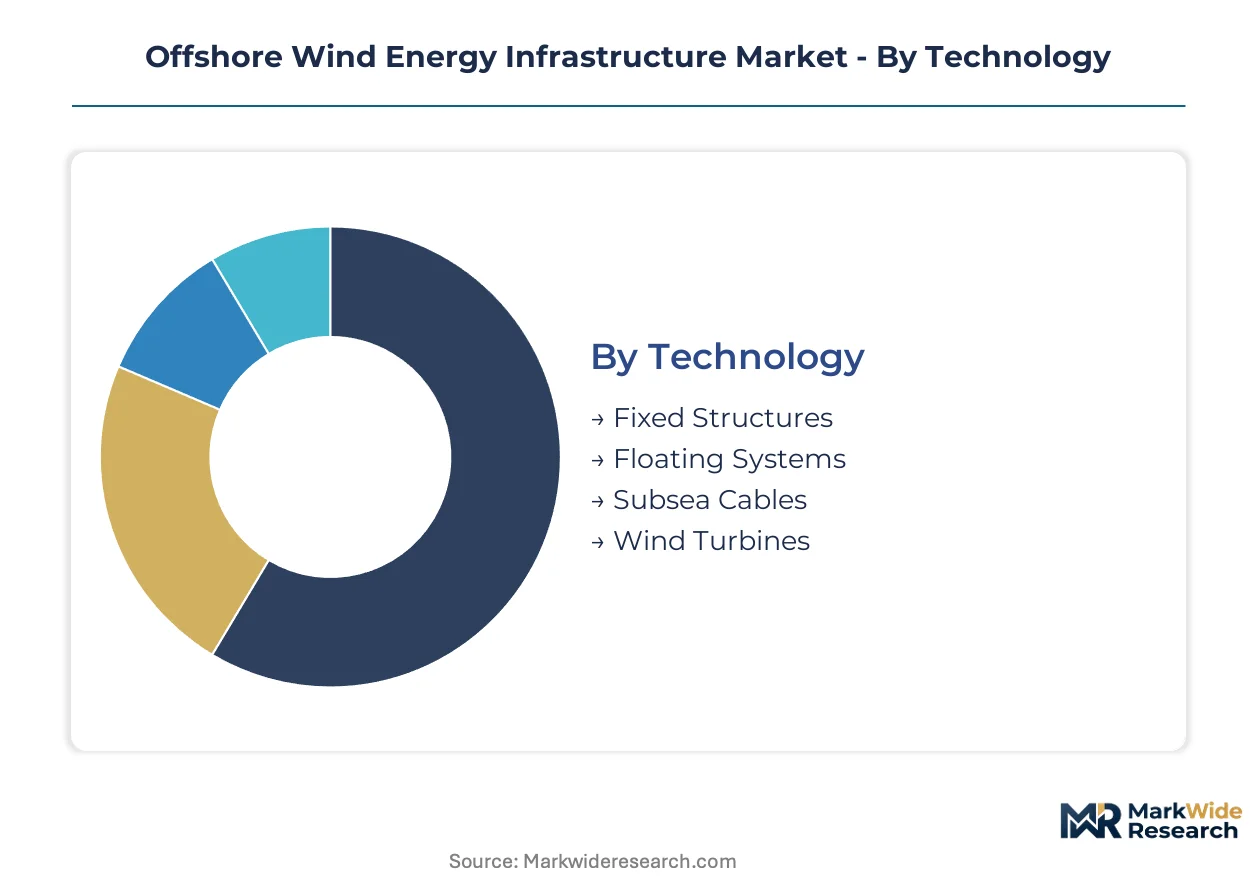
Offshore wind infrastructure segmentation reveals distinct technology maturities, capital intensity profiles, and contracting structures that shape procurement strategies. Each dimension—technology, component, end user, and service type—carries unique margin dynamics and vendor qualification barriers.
Technology:
Technology segmentation spans the full deployment spectrum from shallow-water proven systems to deep-water emerging platforms.
- Fixed Structures:Monopile and jacket foundations dominate capital deployment in water depths below 60 meters. North Sea developers in Germany and Denmark concentrate procurement here due to established installation economics and vessel availability.
- Floating Systems:Semi-submersible and tension-leg platforms target depths exceeding 60 meters where seabed fixation proves impractical. Portugal's Atlantic basins and Japan's Kyushu coastline drive engineering investment as METI feed-in tariffs and EU Green Deal funding unlock project pipelines.
- Subsea Cables:Inter-array cables rated 33-66 kV and export cables carry margin concentration with IEC 62288 certification barriers limiting supplier pools.
- Wind Turbines:Generators scaled beyond 12 MW face 18-24 month IEC 61400-3-1 type certification cycles before commercial deployment.
The dominant share belongs to Fixed Structures, while Floating Systems is closing the gap fastest.
Component:
Component segmentation reflects capital stack allocation across electrical and structural systems.
- Foundations:Steel monopiles and concrete gravity bases absorb 20-35% of project capital expenditure. Fabrication yards in Denmark and the Netherlands face EU Green Deal domestic content thresholds requiring 40% European-manufactured steel.
- Generators:Direct-drive permanent magnet and geared doubly-fed induction units above 12 MW define turbine platform competitiveness. Vestas and Siemens Gamesa anchor supply through vertical integration of nacelle assembly.
- Transformers:Offshore substation step-up units handle voltage elevation from 33-66 kV to transmission-level 220 kV+.
- Switchgear:Gas-insulated and air-insulated medium-voltage assemblies protect array circuits from fault conditions.
Foundations capture the largest capital share, though Generators is expanding most quickly as turbine ratings climb.
End User:
End user segmentation distinguishes balance-sheet capacity and risk tolerance across contracting structures.
- Utilities:Ørsted, RWE, and Iberdrola deploy corporate balance sheets to self-develop and retain long-term ownership. German and Dutch utilities leverage auction mechanisms tying seabed leases to accelerated grid connection timelines.
- Private Developers:Independent sponsors secure power purchase agreements with corporate offtakers in the Netherlands to de-risk capital deployment before financial close.
- Governments:State-owned enterprises in France and Taiwan direct strategic capacity buildout through tender programs.
- Energy Cooperatives:Danish community ownership models aggregate retail investor capital for minority stakes in Ørsted-led projects.
Utilities hold the dominant development share, while Private Developers are gaining ground fastest through PPA-backed project finance.
Service Type:
Service type segmentation tracks value migration from installation to operational phases as fleet ages expand.
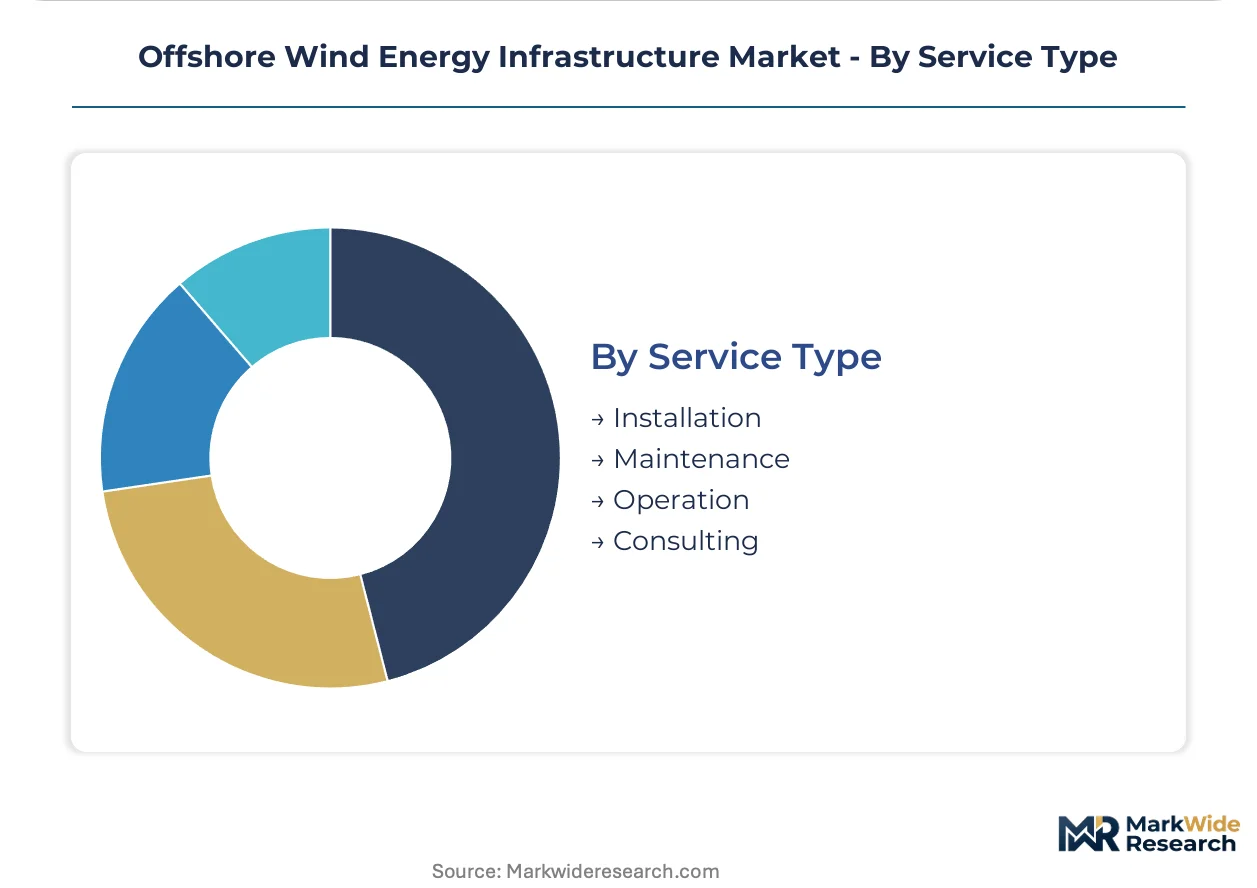
- Installation:Foundation piling, turbine erection, and cable laying demand specialized jack-up vessels numbering fewer than fifteen units capable of handling 15 MW+ turbines.
- Maintenance:Predictive platforms fused with SCADA systems reduce vessel dispatch frequency. Independent service providers capture scope through blade repair and drivetrain overhaul contracts.
- Operation:Long-term service agreements unbundle into discrete work packages across turbine OEMs and third-party providers.
- Consulting:Maritime spatial planning and environmental permitting support faces 36-48 month grid interconnection queues in Germany.
Installation commands the upfront revenue concentration, though Maintenance is climbing the fastest as operational expenditure curves steepen with fleet maturity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes offshore wind infrastructure through auction-tied grid acceleration, while Japan deploys floating systems in deep Atlantic basins—each geography engineering around distinct seabed constraints and policy architectures.
Germany
North Sea lease rounds and 36-month grid connection mandates pull forward foundation procurement. The EU Green Deal's domestic content rules require 40% European-manufactured steel for auction eligibility. Bremerhaven and Cuxhaven anchor fabrication clusters where heavy plate rolling capacity is expanding.
Denmark
Energy cooperatives aggregate retail capital for minority stakes in utility-led developments. National maritime spatial planning compresses environmental permitting timelines against EU Green Deal benchmarks. Esbjerg concentrates jack-up vessel marshalling and turbine pre-assembly yards.
Netherlands
Corporate power purchase agreements from Rotterdam industrial offtakers de-risk capital deployment for private developers. The EU Green Deal's seabed lease conditions tie grid timelines to accelerated commissioning. Eemshaven and Rotterdam Maasvlakte host cable storage and foundation staging facilities.
Japan
METI feed-in tariff revisions target floating capacity off Kyushu and Hokkaido where seabed-fixed solutions prove impractical. The regulator's 4 GW procurement mandate unlocks tension-leg platform engineering investment. Nagasaki and Yokohama clusters specialize in semi-submersible hull fabrication.
United Kingdom
Round 4 and Round 5 auction mechanisms allocate seabed leases with supply chain commitment requirements. The Contracts for Difference regime guarantees strike prices that underwrite project finance. Humberside and Aberdeen harbor expansion programs target next-generation installation vessel homeporting.
Offshore Wind Energy Infrastructure Market Competitive Landscape
Capability concentration sits with turbine OEMs holding IEC 61400-3-1 certification authority; scale advantage sits with utilities commanding multi-gigawatt development pipelines. The structure tiers between integrated energy majors and specialized component fabricators. Three archetypes dominate: vertically integrated developers, independent foundation suppliers, and predictive maintenance platform operators. Competitive moves center on backward integration into steel rolling capacity and strategic port infrastructure concessions.
Among European turbine specialists, Siemens Gamesa Renewable Energy and Vestas Wind Systems occupy positions anchoring the premium-tier equipment supply segment. Ørsted exemplifies the integrated developer archetype, controlling project margins through in-house installation capabilities paired with external foundation sourcing. These three entities represent the dominant competitive anchors across the North Sea basin development corridor.
| Leading Market Players |
|---|
| Siemens Gamesa Renewable Energy |
| Vestas Wind Systems |
| Ørsted |
| GE Vernova |
| MHI Vestas Offshore Wind |
| Xinjiang Goldwind Science & Technology |
| Ming Yang Smart Energy |
| Nordex |
| ABB |
| Others |
Value Network & Pricing Analysis
Bremerhaven's heavy plate rolling expansion directly shapes foundation pricing power across North Sea project pipelines. The cluster's capacity additions feed into monopile and jacket fabrication economics that absorb 20-35% of project capital expenditure.
Pricing Analysis
Long-term offtake contracts dominate procurement structures, with corporate power purchase agreements from Rotterdam industrial buyers de-risking capital deployment for developers. Price differentiation hinges on IEC 62288 certification tier and fabrication yard proximity to EU Green Deal domestic content thresholds. Cost compression in standard-grade monopile supply is intensifying as Asian mills establish European rolling capacity. Private developers exhibit highest price sensitivity due to project finance leverage constraints, while integrated utilities anchor premium-tier procurement through balance-sheet capacity.
Supply Chain Analysis
Tariff exposure between East Asian steel producers and European fabrication yards dominates supply chain risk assessment for foundation components. Manufacturing concentrates in China, South Korea, and domestic European mills for heavy plate supply. Raw material dependencies rest on seabed-fixed steel grades, permanent magnet rare earth elements, and high-voltage cable copper. Single-source vulnerability concentrates in specialized jack-up vessel fleets numbering fewer than fifteen units capable of handling 15 MW+ turbines. Distribution runs through port infrastructure concessions at Esbjerg, Bremerhaven, and Nagasaki marshalling yards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin platform interoperability is reshaping asset ownership economics as predictive maintenance data streams fuse with SCADA systems across turbine fleets.
For Market Incumbents: Build certification authority moats by accelerating IEC 61400-3-1 type validation cycles for next-generation floating platforms. Siemens Gamesa and Vestas should deepen backward integration into permanent magnet supply chains to offset rare earth price volatility. Ørsted must secure exclusive jack-up vessel charter agreements before independent service providers capture installation margin pools. For New Entrants and Emerging Players: Establish a beachhead in Japanese floating foundation engineering where METI feed-in tariffs unlock 4 GW of tension-leg platform demand off Kyushu and Hokkaido. Independent service providers should target blade repair and drivetrain overhaul work packages in Danish waters where Ørsted's fleet scale supports multi-vendor contracting. Green hydrogen electrolyzer co-location at offshore substations offers the most penetrable application white-space. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among predictive maintenance platform operators with SCADA integration capabilities. Long-term viability over the next decade hinges on exposure to operational expenditure curves as fleet ages expand across European waters. Acquisition targets should display IEC 62288 certification barriers and specialized technician pools. The signal to watch is unbundling velocity of long-term service agreements into discrete work packages.| Strategic Initiative | Industry Significance |
|---|---|
| Floating Foundation Engineering Investment | Unlocks deep Atlantic basins off Portugal and Japan where seabed-fixed solutions prove impractical. |
| Predictive Maintenance Platform Deployment | Fuses SCADA data streams to reduce vessel dispatch frequency across Ørsted and RWE fleets. |
| Domestic Content Compliance Program | Secures EU Green Deal auction eligibility through 40% European-manufactured steel thresholds. |
| Installation Vessel Charter Consolidation | Captures scarce jack-up capacity capable of handling 15 MW+ turbine generations. |
| Green Hydrogen Co-location Partnership | Creates captive demand for curtailed generation at offshore substation platforms. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, EPC contractors, and turbine OEM procurement leads; and secondary validation through IEA offshore wind deployment databases, FERC interconnection filings, and project development registries. Bottom-up triangulation across foundation fabrication yard capacity and top-down validation against national auction pipeline announcements anchored volume estimates.
Forecast inputs span technology segmentation across fixed and floating foundation systems, water depth deployment tiers, and regional regulatory frameworks. CAGRs were derived from project pipeline aggregation across the analysis window, incorporating grid interconnection queue timelines and domestic content phase-in schedules. Modeled variables include steel input cost trajectories, vessel availability constraints, and marine electrical technician supply elasticity.
Stress conditions across steel price volatility, installation vessel scarcity, and grid permitting duration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal implementation velocity and METI feed-in tariff revision timing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Poland Renewable Energy Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
Hybrid Solar Wind System Market
Renewable Energy
Botswana Renewable Energy Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
Ethiopia Renewable Energy Market
Renewable Energy
Indonesia Renewable Energy CAPEX Market
Renewable Energy
Singapore Renewable Energy Market
Renewable Energy
China Wind Energy Market
Renewable Energy
Wave Energy Converter Market
Renewable Energy
Hungary Renewable Energy Market
Renewable Energy
Middle East Renewable Energy Market
Renewable Energy
Renewable Energy Consulting Market
Renewable Energy
Netherlands Renewable Energy Market
Renewable Energy
Point Absorber Market
Renewable Energy
Solar Ceiling Fans Market