
 Japan Renewable Energy Market | 2026-2036
Japan Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Renewable Energy Market Outlook
Utility-scale certification tiers for grid stability and frequency response is redrawing competitive boundaries in Japanese power procurement. JERA Co., Inc. leverages its combined-cycle expertise to anchor offshore wind-to-hydrogen integration projects. Eurus Energy Holdings Corporation specializes in onshore wind development across rural prefectures. Mitsubishi Heavy Industries Ltd. dominates turbine manufacturing and domestic supply chain verticality for large-scale installations.
Japan renewable energy encompasses solar PV, wind power, biomass, and geothermal systems that convert natural flux into grid-compliant electricity through inverters, transformers, and interconnection infrastructure rated for 50 Hz eastern and 60 Hz western grid zones. Solar PV retains the largest installed base though offshore wind claims the fastest expansion trajectory under revised maritime leasing rules. Utility-scale deployment captures dominant capital allocation while distributed generation segments serve commercial and industrial end users seeking behind-the-meter supply security.
METI enforces grid codes through the Organization for Cross-regional Coordination of Transmission Operators while the Ministry of the Environment administers environmental impact assessments for offshore wind zones. These frameworks mandate battery co-location for frequency regulation and constrain project timelines through layered permitting. Stakeholders must monitor feed-in tariff phase-out schedules and regional grid reinforcement commitments to calibrate capital deployment timing.
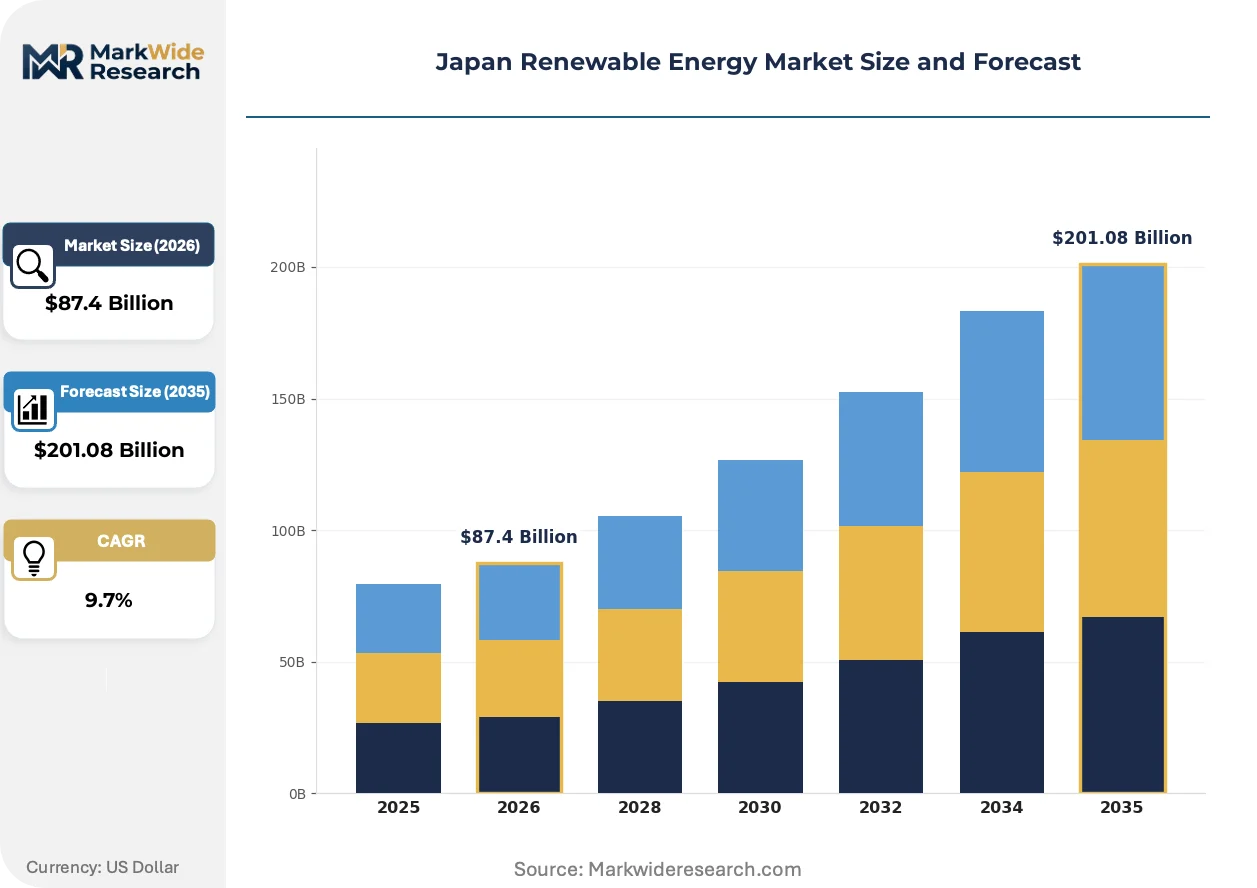
Market Dynamics
Japan's renewable energy sector is undergoing a fundamental reconfiguration as METI's feed-in tariff phase-out forces developers to pivot from subsidized procurement to merchant power contracting and corporate PPAs. This shift compresses project returns while elevating grid-scale storage co-location requirements.
Growth Catalysts
- Offshore Wind Maritime Leasing:Revised seabed lease frameworks from the Ministry of Land, Infrastructure, Transport and Tourism unlock deeper water sites for floating turbine platforms. Developers gain access to higher-capacity factor wind corridors off Kyushu and Tohoku.
- Corporate PPA Demand:Data center operators and semiconductor fabs in Osaka and Nagoya seek 24/7 carbon-free power, driving direct contracting with solar and wind asset owners outside traditional utility channels.
- Green Hydrogen Export Mandates:METI's hydrogen roadmap positions Hokkaido wind-to-hydrogen clusters for ammonia co-firing and maritime fuel bunkering at Yokohama and Kobe ports.
Market Restraints
- Grid Interconnection Queues:Organization for Cross-regional Coordination of Transmission Operators approval timelines stretch 18-36 months for utility-scale projects in Kyushu and Hokkaido where renewable saturation strains 66kV and 154kV lines.
- Domestic Turbine Supply Concentration:Mitsubishi Heavy Industries and Hitachi Zosen control nacelle and monopile fabrication, creating single-source dependency for 8MW-plus offshore units.
- Land Acquisition Friction:Agricultural land conversion restrictions under the Basic Act on Food, Agriculture and Rural Areas block utility-scale solar siting in Chubu and Kanto prefectures with superior irradiance profiles.
Strategic Opportunities
- Hokkaido Wind-to-Ammonia:Untapped onshore wind resource in northern Hokkaido supports integrated ammonia production for coal plant co-firing and export to Southeast Asian power markets.
- Agrivoltaics Deployment:Dual-use solar installations on rice paddies and tea plantations in Shizuoka and Fukuoka prefectures unlock land-constrained capacity while qualifying for agricultural preservation incentives.
- Grid-Scale Battery Arbitrage:Frequency regulation markets and capacity payments create merchant revenue streams for lithium-ion co-location at existing solar farms in Kyushu.
Industry Challenges
- Offshore Installation Vessel Scarcity:Japan lacks heavy-lift jack-up vessels capable of 12MW-plus turbine installation, forcing reliance on European contractors with 24-month charter backlogs.
- Grid Code Compliance Costs:OCCTO-mandated fault ride-through and reactive power requirements add 8-12% to inverter and transformer capex for projects above 50MW.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Renewable Energy Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $201.08 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar PV, Wind Power, Biomass, Geothermal End User: Residential, Commercial, Industrial, Government Application: Electricity Generation, Heating, Transportation, Off-Grid Solutions Deployment: Onshore, Offshore, Distributed, Utility-Scale |
| Companies Covered | JERA Co., Inc., Eurus Energy Holdings Corporation, RENOVA, Inc., TEPCO Renewable Power Inc., Mitsubishi Heavy Industries Ltd., Ørsted Japan K.K., Japan Renewable Energy Co. Ltd., Renewable Energy Investment Japan, Kobe Steel, Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Renewable Energy Market Strategic Shifts
Floating offshore wind technology and grid-forming inverters are redefining project economics as Japan's renewable sector matures beyond FIT dependency. Developers now optimize for merchant revenue streams and industrial offtake rather than subsidized feed-in tariffs.
Perovskite-silicon tandem solar cell technology is decomposing the cost-performance tradeoff that has constrained Japanese PV deployment. Residential and commercial installers in Kansai and Chubu are piloting these modules for rooftop applications where space constraints favor higher efficiency. The technology is decomposing incumbent crystalline silicon supply chains by enabling thinner wafers and lower-temperature processing.
METI's 2023 revision to the Feed-in Tariff Act introduces competitive auction mechanisms for solar and wind capacity above 250kW. Industrial developers must now bid against each other for grid connection rights, compressing allowable returns and favoring sponsors with balance sheet capacity to absorb merchant price risk. Large-scale solar in Kyushu faces the steepest competitive pressure as irradiance advantages attract multiple bidders per substation zone.
Corporate buyers in Japan's automotive and electronics sectors are contracting directly with renewable developers through virtual and sleeved PPAs rather than purchasing green certificates from utilities. This bypasses regional utility monopolies and locks in decade-long price certainty. The shift is most pronounced among semiconductor fabs in Kumamoto and Hiroshima prefectures where 24/7 clean power supports supply chain decarbonization mandates from overseas parent companies.
Japan Renewable Energy Market Segmentation
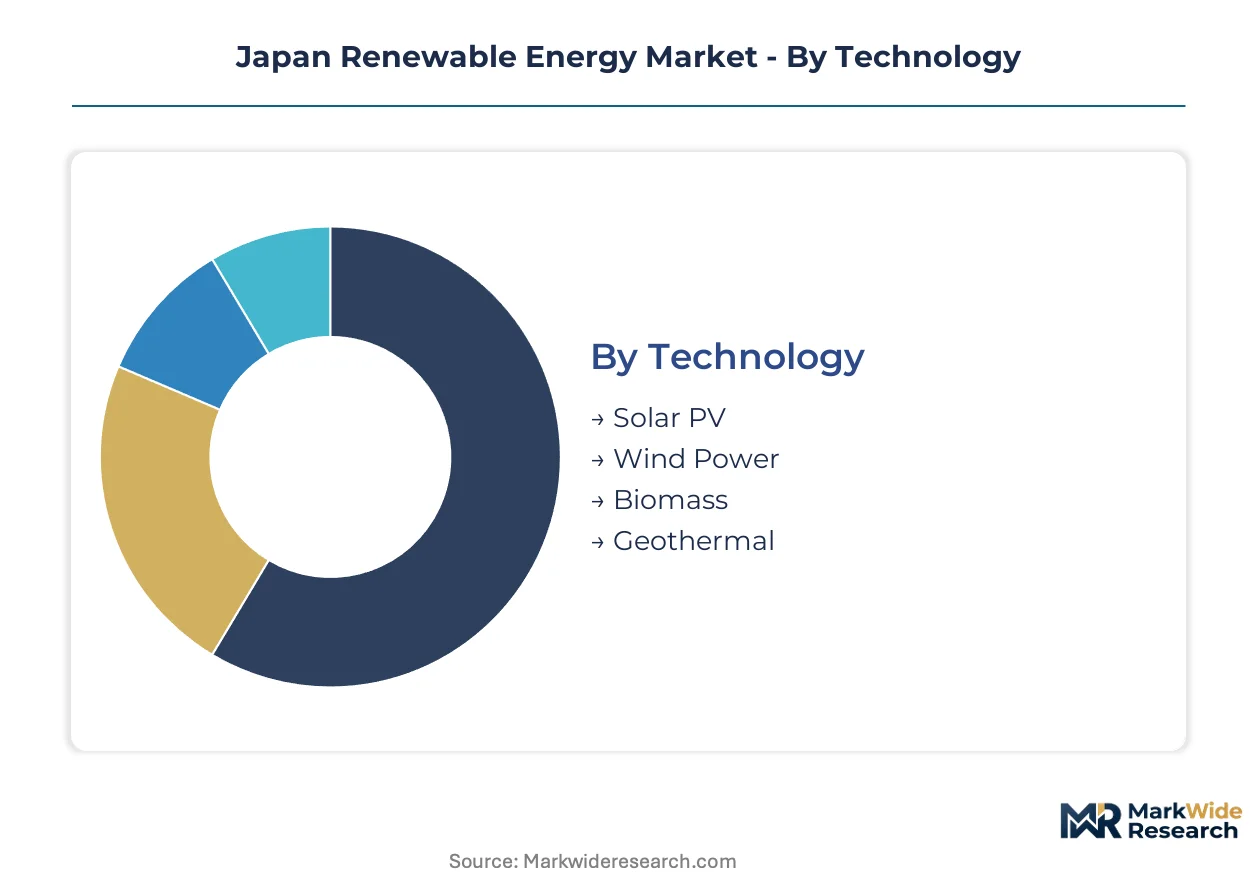
Technology choices in Japan's renewable sector channel capital toward distinct procurement pathways, with METI auction mechanisms and corporate PPA structures filtering project economics differently across each segment. Deployment scale and grid connection voltage tier determine whether developers pursue subsidized feed-in tariffs or merchant contracting models.
Technology:
Solar PV modules flow through residential installers and utility-scale EPC contractors, while offshore wind turbines move via maritime construction consortia and heavy-lift vessel operators.
- Solar PV:Crystalline silicon and emerging perovskite-tandem configurations dominate rooftop and ground-mount installations. Residential demand clusters in Kansai and Chubu where irradiance profiles support distributed generation economics, though land conversion restrictions in Kanto constrain utility-scale siting.
- Wind Power:Onshore turbines serve rural prefectures through regional utility offtake, while floating offshore platforms target deeper water leases off Kyushu and Tohoku. Grid interconnection queues at OCCTO stretch 18-36 months for projects above 50MW.
- Biomass:Woody pellet and agricultural residue combustion units supply baseload power under FIT schedules. Industrial facilities in pulp and paper regions leverage captive feedstock for behind-the-meter generation.
- Geothermal:Binary-cycle plants exploit volcanic zones in Hokkaido and Tohoku. Onsen tourism opposition and environmental review timelines limit expansion beyond existing concession areas.
By volume, Solar PV leads. By growth pace, Wind Power is ahead.
End User:
Customer type segments the market into distinct financing structures, with industrial offtakers commanding bilateral negotiation leverage unavailable to residential segments.
- Residential:Rooftop solar deployments under 10kW capacity qualify for residual FIT rates or net metering. Installation volumes concentrate in suburban Osaka and Nagoya corridors where housing stock permits south-facing array orientation.
- Commercial:Office buildings and retail chains in Tokyo and Yokohama procure sleeved PPAs to meet RE100 commitments. Behind-the-meter battery co-location is accelerating for demand charge management.
- Industrial:Semiconductor fabs and automotive assembly plants in Kumamoto and Hiroshima contract directly for 24/7 carbon-free power. Virtual PPAs bypass regional utility monopolies and lock in decade-long price certainty.
- Government:Municipal buildings and defense installations procure through centralized agency tenders. Public-sector procurement prioritizes domestic content requirements under METI industrial policy.
Industrial offtakers command the steepest contract discounts through volume aggregation. Residential installations retain the broadest installer network access.
Application:
Use-case differentiation separates power-sector revenue streams from thermal and mobility applications with distinct regulatory treatment.
- Electricity Generation:Grid-connected solar, wind, and geothermal plants supply wholesale markets and utility portfolios. Frequency regulation markets create ancillary revenue for battery-co-located assets.
- Heating:Biomass boilers and geothermal district heating serve industrial process load and municipal networks. Hokkaido pulp mills integrate biomass thermal with power generation.
- Transportation:Electrolyzer installations convert Hokkaido wind power to hydrogen for ammonia production and maritime bunkering. Yokohama and Kobe ports anchor fuel supply chains.
- Off-Grid Solutions:Remote island microgrids in Okinawa and isolated mountain communities deploy solar-plus-storage configurations. Diesel displacement economics drive procurement where grid extension is uneconomic.
Electricity Generation captures dominant capital allocation. Transportation applications are climbing the fastest on hydrogen export mandate tailwinds.
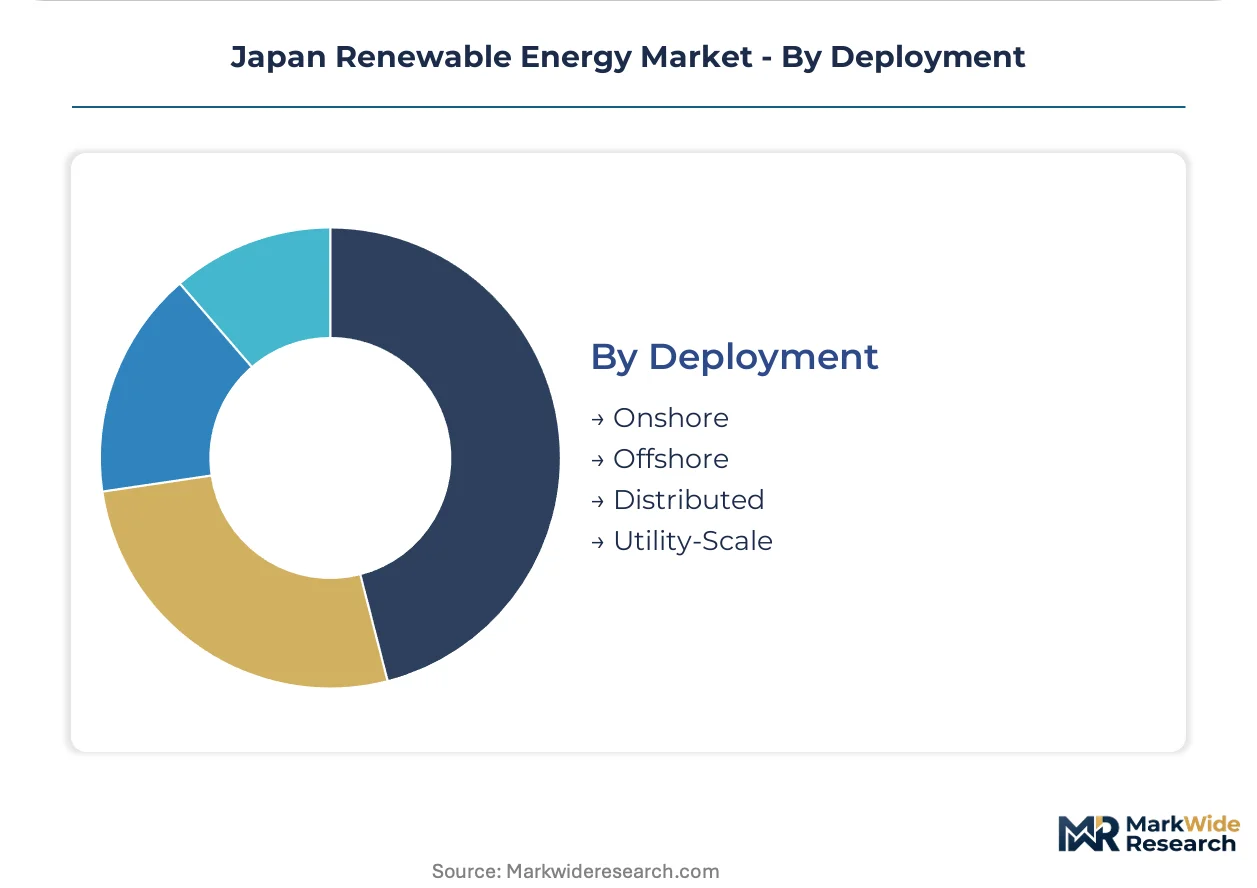
Deployment:
Scale and siting configuration determine grid code compliance burden and permitting pathway complexity.
- Onshore:Wind and solar installations on agricultural and forested land face conversion restrictions under the Basic Act on Food, Agriculture and Rural Areas. Agrivoltaics pilots in Shizuoka and Fukuoka unlock dual-use capacity.
- Offshore:Floating turbine platforms access higher-capacity factor wind corridors in deeper waters. Japan lacks heavy-lift jack-up vessels for 12MW-plus installation, forcing European contractor reliance.
- Distributed:Sub-250kW solar and storage systems serve commercial and industrial behind-the-meter demand. METI auction thresholds exclude these from competitive bidding requirements.
- Utility-Scale:Projects above 50MW face OCCTO-mandated fault ride-through and reactive power compliance adding 8-12% to inverter and transformer capex. Kyushu and Hokkaido substation zones attract the densest development interest.
Utility-Scale deployment leads by megawatt contribution. Offshore configurations are gaining share fastest on maritime leasing rule revisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive industrial buyers in Kyushu and Hokkaido drive procurement volume, while Tokyo-based corporate offtakers absorb premium pricing for supply security. Regional disparities in grid infrastructure and resource quality fragment deployment economics across Japan's archipelago.
Kyushu
Utility-scale solar developers crowd substation zones in Kagoshima and Miyazaki prefectures where irradiance peaks exceed national averages. METI's competitive auction mechanisms for projects above 250kW compress developer margins as multiple bidders target limited interconnection capacity. Semiconductor fabs in Kumamoto contract directly for sleeved PPAs, bypassing Kyushu Electric Power's regional monopoly.
Hokkaido
Onshore wind clusters in northern Hokkaido supply wind-to-ammonia conversion for coal plant co-firing and Southeast Asian export markets. The prefecture's isolation from the 50 Hz eastern grid forces standalone project economics and captive hydrogen production pathways. Pulp mills in Tomakomai integrate biomass thermal with power generation under FIT baseload schedules.
Kansai
Osaka-based data center operators and automotive suppliers command steepest contract discounts through volume aggregation of 24/7 carbon-free power. Sleeved PPAs bypass Kansai Electric Power's retail channels. Perovskite-silicon tandem pilots on commercial rooftops in Kyoto and Osaka test higher-efficiency configurations for space-constrained urban deployment.
Chubu
Nagoya's automotive assembly plants and precision manufacturing clusters drive corporate PPA demand with price certainty requirements spanning decade-long horizons. Agricultural land conversion restrictions under the Basic Act on Food, Agriculture and Rural Areas block utility-scale solar siting despite superior irradiance profiles. Agrivoltaics pilots on Shizuoka tea plantations unlock dual-use capacity under agricultural preservation incentives.
Tohoku
Floating offshore wind platforms target deeper water leases off Aomori and Iwate coastlines under revised maritime leasing frameworks from the Ministry of Land, Infrastructure, Transport and Tourism. Binary-cycle geothermal plants exploit volcanic zones in Akita and Yamagata, though onsen tourism opposition constrains expansion beyond existing concession areas. Grid interconnection queues at OCCTO stretch 18-36 months for utility-scale projects.
Japan Renewable Energy Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with turbine manufacturers and maritime construction specialists occupying distinct competitive tiers. The market structures around consolidated equipment supply and fragmented project development, creating dependency relationships between sponsors and fabricators. Three archetypes dominate: integrated energy conglomerates with balance sheet capacity, specialized renewable developers with siting expertise, and heavy industrial manufacturers with domestic supply chain control. Competitive moves concentrate on strategic partnerships for floating platform deployment and co-location agreements for grid-scale battery arbitrage.
Within the integrated energy tier, JERA Co., Inc. and TEPCO Renewable Power Inc. exemplify sponsors with utility heritage and merchant risk absorption capacity. Among specialized developers, Eurus Energy Holdings Corporation and RENOVA, Inc. occupy positions anchored in rural prefecture relationships and environmental permitting velocity. Mitsubishi Heavy Industries Ltd. represents the equipment-manufacturing archetype with captive nacelle and monopile fabrication capabilities.
| Leading Market Players |
|---|
| JERA Co., Inc. |
| Eurus Energy Holdings Corporation |
| RENOVA, Inc. |
| TEPCO Renewable Power Inc. |
| Mitsubishi Heavy Industries Ltd. |
| Ørsted Japan K.K. |
| Japan Renewable Energy Co. Ltd. |
| Renewable Energy Investment Japan |
| Kobe Steel, Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term corporate offtake agreements lock in supply access for turbine nacelles and monopiles while anchoring price visibility across METI's auction-driven procurement cycles. These contract structures tether developer margins to domestic fabrication capacity and maritime logistics availability.
Pricing Analysis
METI's competitive auction mechanisms dictate the pricing tier structure for utility-scale solar and wind capacity above 250kW. Three-tier pricing structure across premium certification-grade, standard compliance, and economy merchant-exposed levels segments developer returns. Price differentiation rests on grid-code compliance burden and battery co-location requirements. Cost compression in the economy tier is intensifying because multiple bidders crowd Kyushu substation zones. Industrial offtakers in semiconductor and automotive sectors command steepest contract discounts through volume aggregation, while residential installers retain broadest network access with highest per-watt price sensitivity.
Supply Chain Analysis
Strategic stockpiling of nacelle components and monopile steel precedes heavy-lift vessel charter windows, as just-in-time delivery proves incompatible with 24-month European contractor backlogs. Manufacturing concentrates in Japan, South Korea, and Denmark for turbine fabrication. Raw material dependencies span rare-earth magnets from China, high-grade steel from South Korea, and composite blade resins from Germany. Single-source vulnerability concentrates in Mitsubishi Heavy Industries and Hitachi Zosen for 8MW-plus offshore units. Distribution runs through maritime construction consortia and regional EPC contractors to utility offtakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's renewable energy sector is accelerating through METI's feed-in tariff phase-out, forcing a wholesale pivot from subsidized procurement to merchant contracting and corporate PPA structures.
For Market Incumbents: Secure captive fabrication capacity for floating platform components before European vessel charter rates escalate further. Anchor balance sheet capacity to absorb merchant price risk in OCCTO interconnection queues stretching 18-36 months. Prioritize certification investment for grid-forming inverter compliance to defend positioning against emerging entrants with weaker utility relationships. For New Entrants and Emerging Players: Anchor in agrivoltaics deployment across Shizuoka tea plantations and Fukuoka rice paddies, where agricultural preservation incentives unlock land-constrained capacity outside utility-scale auction competition. Target Hokkaido wind-to-ammonia clusters for integrated production serving Southeast Asian export markets. Pursue sleeved PPA origination with Osaka data center operators as the most penetrable offtaker segment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized developers with established rural prefecture relationships and environmental permitting velocity. Long-term viability over the five-to-ten year window favors sponsors with demonstrated OCCTO approval track records and captive hydrogen offtake agreements. Monitor floating offshore wind maritime leasing rule revisions as the signal to watch for capacity expansion inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Origination | Direct contracting with semiconductor fabs in Kumamoto bypasses regional utility monopolies. |
| Vertical Integration into Grid-Scale Storage | Battery co-location at Kyushu solar farms captures frequency regulation arbitrage revenue. |
| Technology Licensing for Floating Platforms | European turbine design partnerships address Japan's heavy-lift vessel scarcity constraints. |
| Green Certification Program | RE100 compliance for automotive suppliers in Nagoya locks in decade-long offtake security. |
| Capacity Buildout in Hokkaido | Wind-to-ammonia clusters exploit captive hydrogen production for coal plant co-firing. |
Study Parameters
A standing panel of utility planning officers, IPP project developers, EPC contractors, and grid operators provided ongoing calibration across primary fieldwork and secondary validation. METI auction records, OCCTO interconnection databases, IEA renewable deployment reports, and corporate PPA disclosure filings anchored data triangulation. Bottom-up project economics modeling and top-down capacity aggregation were cross-checked for consistency.
Consistency checks validated volume and value outputs against IEA benchmark trajectories and regional utility procurement disclosures across the projection horizon. Segmentation dimensions spanned technology type, deployment scale, end-user category, and regional grid infrastructure maturity. CAGRs were derived from installed capacity buildout curves and capital expenditure flows. Forecast inputs incorporated maritime leasing rule revision timelines and heavy-lift vessel charter availability.
Decision-makers should treat outputs as directional under base assumptions of sustained METI auction participation and corporate PPA demand growth; material deviation in interconnection approval velocity would warrant model refresh. Practitioners should keep alternative scenarios live as floating platform technology maturation and hydrogen export mandate implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Europe Power to Gas Market
Renewable Energy
Solar Drying System Market
Renewable Energy
Wind Turbine Inspection Drones Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Solar Watch Market
Renewable Energy
Renewable Energy in South America Market
Renewable Energy
Green Energy Lighting Market
Renewable Energy
Egypt Renewable Energy Market
Renewable Energy
Romania Wind Energy Market
Renewable Energy
Norway Renewable Energy Market
Renewable Energy
China Wind Energy Market
Renewable Energy
India Renewable Energy Market
Renewable Energy
South Africa Distributed Solar Energy Market
Renewable Energy
LAMEA Wave and Tidal Energy Market
Renewable Energy
Ocean Power Market
Renewable Energy
United States Renewable Energy Market