
 Wind and Solar Hybrid Monitoring Systems Market | 2026-2036
Wind and Solar Hybrid Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Wind and Solar Hybrid Monitoring Systems Market Insights
The pricing architecture for wind and solar hybrid monitoring systems is rebalancing as premium predictive analytics tiers separate from basic SCADA commodity packages. Vestas Wind Systems A/S leverages its turbine data heritage to anchor high-margin software subscriptions. SMA Solar Technology AG competes through inverter-integrated monitoring that sustains hardware-software bundling power.
Wind and solar hybrid monitoring systems comprise sensor networks, data acquisition hardware, and analytics platforms that measure irradiance, wind speed, turbine vibration, and inverter performance in unified dashboards. These systems synchronize generation profiles across variable renewable assets to optimize dispatch and curtailment decisions. IoT-enabled sensor deployments now dominate new installations as edge computing architectures reduce latency for real-time turbine pitch and solar tracking coordination. AI-driven predictive maintenance applications capture the fastest expansion within the technology stack as asset operators prioritize uptime over reactive servicing. Control systems retain the deepest margin pools where proprietary algorithms govern hybrid plant output.
FERC Order 2023 interconnection reforms in the United States compel hybrid project developers to demonstrate grid stability capabilities that monitoring systems must certify. India's CEA mandates centralized renewable energy management centers that standardize data protocols for hybrid parks above 50 MW capacity. China's GB standards for wind-solar complementary power stations enforce sensor calibration frequencies that shape replacement cycles. Stakeholders must weigh regulatory compliance automation against modular upgrade paths as jurisdictions layer new data sovereignty requirements onto operational technology stacks.
Market Dynamics
Hybrid renewable asset operators now demand unified visibility across generation sources, collapsing the historical separation between wind SCADA and solar monitoring stacks into integrated platforms that synchronize dispatch decisions.
Growth Catalysts
- India's PLI scheme for solar-wind parks:Production-linked incentives for hybrid renewable parks above 50 MW mandate centralized monitoring infrastructure, accelerating procurement of integrated sensor networks and analytics platforms.
- Edge computing architectures:IoT-enabled sensor deployments with localized processing reduce latency for real-time turbine pitch and solar tracking coordination, enabling sub-second dispatch optimization that standalone systems cannot match.
- Utility-scale renewable developers:East Asia's manufacturing corridors where turbine and module production clusters co-locate generate concentrated demand for hybrid monitoring systems that manage co-sited generation assets.
Market Restraints
- Proprietary algorithm lock-in:Control systems with embedded intellectual property create switching costs that prevent asset operators from migrating between monitoring vendors without full plant recertification.
- Sensor calibration mandates:China's GB standards for wind-solar complementary power stations enforce replacement cycles that accelerate hardware refresh spending beyond typical depreciation schedules.
- Data sovereignty layering:Jurisdictions are adding operational technology data localization requirements that fragment cloud architectures and multiply compliance engineering overhead.
Strategic Opportunities
- AI-driven predictive maintenance:Asset operators prioritize uptime over reactive servicing, creating expansion space for machine learning applications that forecast turbine bearing failure and inverter degradation before operational impact.
- FERC Order 2023 interconnection reforms:United States hybrid project developers must demonstrate grid stability capabilities that monitoring systems certify, opening consultative service revenue streams around compliance automation.
- India's CEA centralized management mandate:Renewable energy management centers for hybrid parks above 50 MW standardize data protocols, enabling platform vendors to capture recurring software subscription revenue.
Industry Challenges
- Cyber-physical security integration:Converging IT and OT networks in hybrid plants expands attack surfaces that asset operators struggle to harden without operational disruption.
- Legacy SCADA migration:Brownfield wind farms with decade-old turbine control systems require expensive protocol translation layers to synchronize with modern solar inverter monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind and Solar Hybrid Monitoring Systems Market |
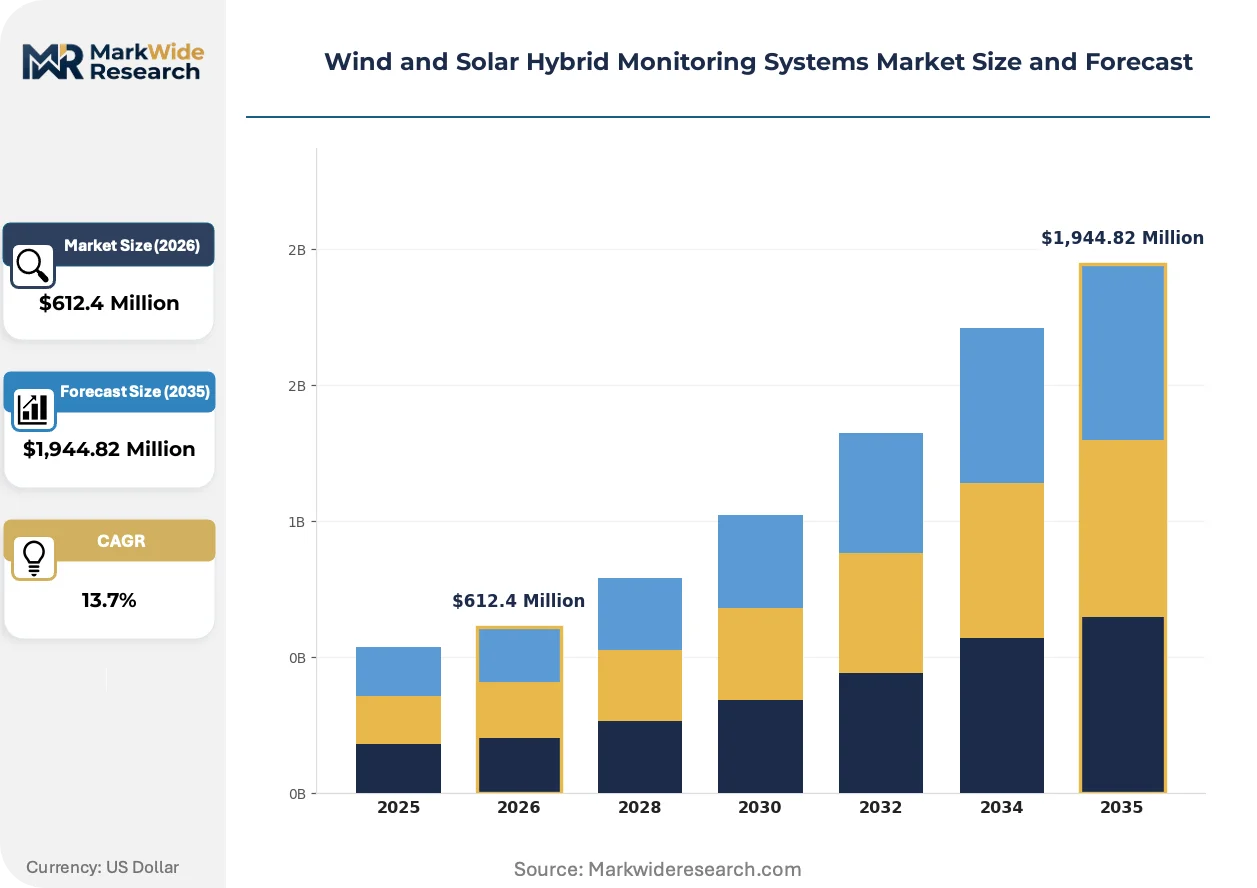
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,944.82 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitoring Software, Control Systems, Sensors, Data Loggers Technology: IoT, AI, Cloud Computing, Edge Computing End User: Utilities, Renewable Energy Providers, Research Institutions, Industrial Users Application: Energy Management, Performance Monitoring, Predictive Maintenance, Grid Integration |
| Companies Covered | Vestas Wind Systems A/S, Siemens Gamesa Renewable Energy, GE Vernova, SMA Solar Technology AG, Sungrow Power Supply, SolarEdge Technologies, Suzlon Energy Ltd., Enphase Energy, NextEra Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind and Solar Hybrid Monitoring Systems Market Trends and Innovations
Digital twin architectures are absorbing capital allocation previously directed toward physical redundancy, compressing commissioning timelines while expanding simulation-based optimization capabilities across hybrid renewable fleets.
Digital twin platforms for hybrid renewable plants is absorbing engineering validation workflows that previously required physical commissioning tests. Vestas and SMA are deploying virtual turbine and inverter models that simulate five-year operational degradation in compressed timeframes. This technology is absorbing upfront engineering costs while accelerating project finance approval cycles.
China's GB standards for wind-solar complementary power stations now mandate sensor calibration frequencies and data interoperability protocols that shape replacement cycles. Equipment vendors must redesign hardware modules for field-serviceability rather than sealed-unit replacement. The standardization push most affects control system manufacturers supplying the multi-gigawatt hybrid parks proliferating across Inner Mongolia and Gansu.
Asset operators now unbundle monitoring software subscriptions from hardware procurement, compressing vendor switching cycles from decade-long SCADA contracts to annual SaaS renewals. This procurement pattern shift disrupts inverter-integrated monitoring bundling that historically locked customers into single-vendor ecosystems. The unbundling is most visible among independent power producers in India managing diversified renewable portfolios across multiple equipment OEMs.
Wind and Solar Hybrid Monitoring Systems Market Segmentation
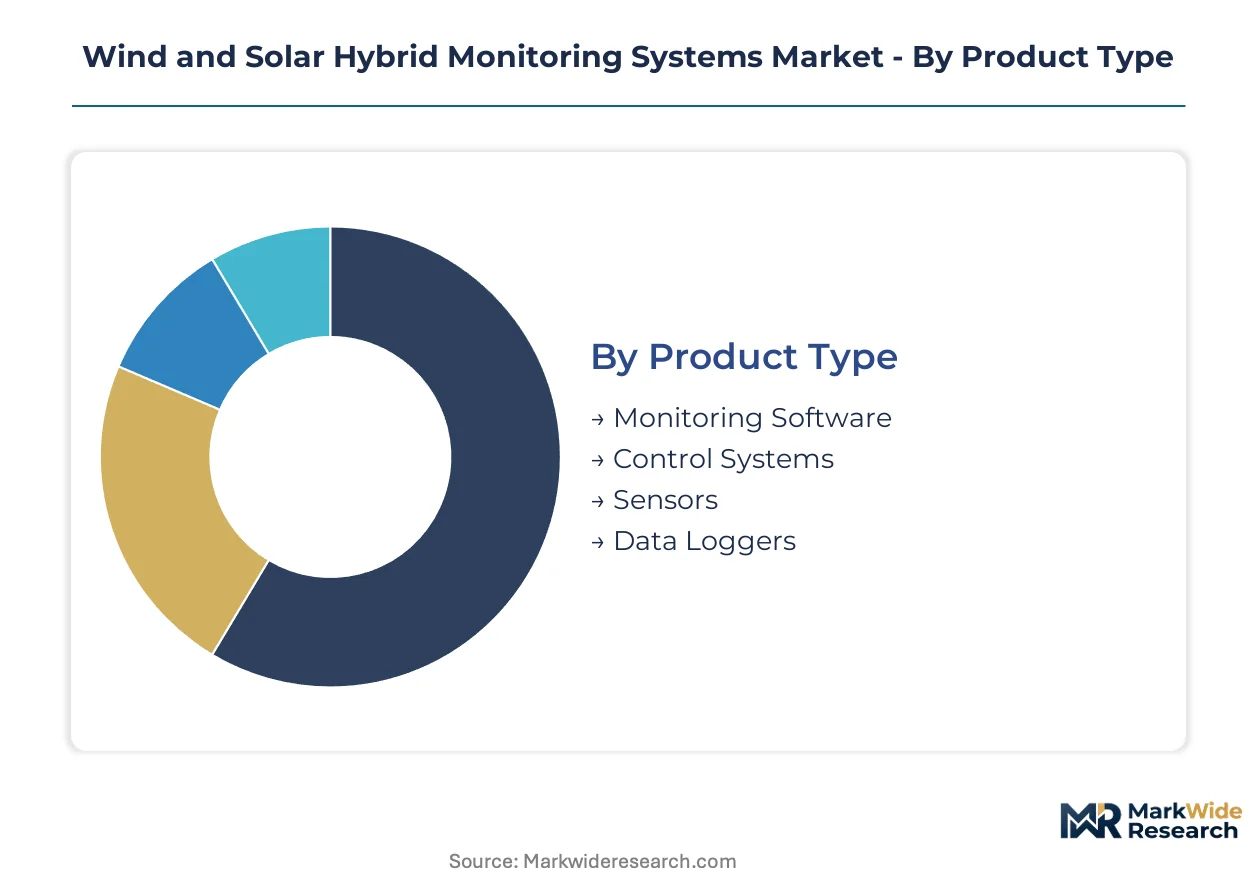
Hybrid renewable operators select monitoring architectures based on generation scale, grid connection complexity, and regulatory certification requirements. Segmentation reveals how procurement priorities diverge between utility-scale developers seeking unified dispatch platforms and industrial users prioritizing localized performance visibility.
Product Type:
Procurement decisions in this category hinge on whether operators prioritize upfront capital control or recurring operational intelligence subscriptions.
- Monitoring Software:Unified dashboards aggregate irradiance, wind speed, and inverter telemetry into single-pane visibility for hybrid plant operators. India's CEA-mandated renewable energy management centers for parks above 50 MW standardize procurement of these platforms, creating recurring SaaS revenue streams for vendors.
- Control Systems:Embedded algorithms govern turbine pitch coordination with solar tracking systems in sub-second dispatch cycles. Proprietary intellectual property in these systems creates switching costs that prevent migration between vendors without full plant recertification under FERC Order 2023.
- Sensors:IoT-enabled networks measure vibration, temperature, and electrical parameters across hybrid assets.
- Data Loggers:Edge-located acquisition hardware buffers telemetry before cloud transmission.
Control systems lead volumes today; monitoring software is gaining share fastest.
Technology:
Technology selection tracks the latency requirements of specific hybrid coordination tasks, with edge architectures displacing cloud-only stacks for time-critical control loops.
- IoT:Sensor networks with standardized communication protocols enable plug-and-play expansion across multi-vendor hybrid installations. China's GB standards for wind-solar complementary power stations mandate interoperability protocols that accelerate replacement cycles for non-compliant legacy deployments.
- AI:Machine learning models forecast turbine bearing degradation and inverter thermal stress before operational impact. Asset operators in India prioritize these applications over reactive maintenance, expanding the addressable market for predictive analytics subscriptions.
- Cloud Computing:Centralized data lakes support long-term performance benchmarking across hybrid fleets.
- Edge Computing:Localized processing architectures reduce latency for real-time coordination decisions.
IoT deployments dominate installed base; AI applications show the steepest expansion trajectory.
End User:
End user segmentation reflects divergent procurement authority structures, from centralized utility engineering teams to distributed industrial facility managers.
- Utilities:Vertically integrated grid operators mandate hybrid monitoring platforms that certify grid stability capabilities under interconnection reform requirements. These buyers consolidate procurement across generation portfolios, favoring vendors with consultative compliance automation services.
- Renewable Energy Providers:Independent power producers with diversified equipment fleets drive unbundling of software subscriptions from hardware procurement. India's PLI scheme beneficiaries managing multi-OEM solar-wind parks exemplify this procurement pattern shift.
- Research Institutions:Academic and national laboratory users prioritize open data formats for algorithm development.
- Industrial Users:Cogeneration facilities with captive hybrid assets emphasize localized performance optimization over grid-scale dispatch coordination.
Utilities anchor current demand; renewable energy providers are expanding most quickly.
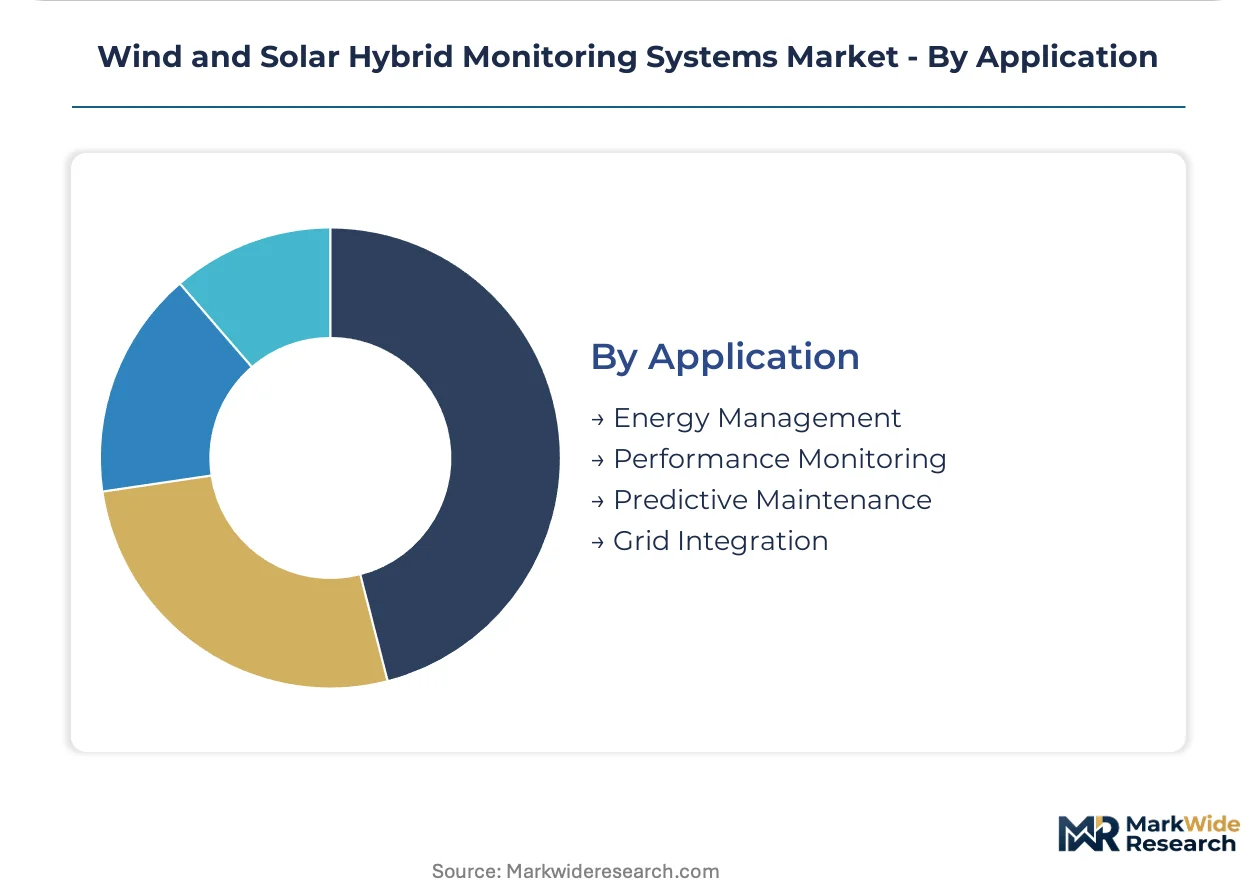
Application:
Application prioritization varies with asset maturity, with greenfield developments emphasizing grid integration certification and brownfield retrofits targeting performance gap identification.
- Energy Management:Dispatch optimization algorithms synchronize variable renewable output with demand patterns and storage state-of-charge. East Asia's manufacturing corridors with co-located turbine and module production clusters generate concentrated demand for these coordination capabilities.
- Performance Monitoring:Real-time dashboards track capacity factor degradation and availability metrics across hybrid portfolios. Brownfield wind farms with decade-old SCADA systems require expensive protocol translation layers to achieve unified visibility.
- Predictive Maintenance:Condition-based servicing schedules replace calendar-driven interventions.
- Grid Integration:Stability certification documentation supports interconnection queue positioning.
Energy management commands the largest deployment share; predictive maintenance is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools concentrated in Denmark, Germany, and China's coastal provinces anchor the technology development for hybrid monitoring systems. These workforce clusters feed directly into the control algorithm and sensor calibration capabilities that differentiate competitive offerings.
United States
Utility-scale hybrid developers in Texas and California drive procurement of grid stability certification platforms. FERC Order 2023 interconnection reforms compel these operators to demonstrate dispatch coordination capabilities that monitoring systems must validate. The ERCOT and CAISO grid regions concentrate deployment of edge-computing architectures for sub-second turbine-solar coordination.
China
Multi-gigawatt hybrid parks across Inner Mongolia and Gansu generate concentrated demand for sensor networks compliant with GB standards. MEE dual carbon goals accelerate procurement of integrated monitoring infrastructure. Turbine and module manufacturing clusters in Jiangsu and Zhejiang co-locate with system integrators refining calibration protocols for wind-solar complementary stations.
India
Independent power producers in Gujarat and Rajasthan manage diversified renewable portfolios across multiple equipment OEMs. CEA mandates for renewable energy management centers above 50 MW standardize data protocols and accelerate SaaS procurement. PLI scheme beneficiaries in Tamil Nadu and Karnataka deploy unified monitoring platforms for solar-wind parks.
Germany
Industrial automation specialists in Bavaria and Baden-Württemberg supply control system components for European hybrid installations. EU Green Deal implementation drives demand for predictive maintenance platforms that optimize asset uptime. The Ruhr industrial corridor hosts engineering consultancies advising on brownfield SCADA migration for aging wind fleets.
Denmark
Turbine data heritage concentrated in Copenhagen and Aarhus feeds high-margin software subscription development. Vestas Wind Systems A/S anchors predictive analytics tier differentiation through proprietary algorithm portfolios. Danish engineering clusters specialize in digital twin architectures that compress commissioning timelines for hybrid renewable projects.
Wind and Solar Hybrid Monitoring Systems Market Competitive Landscape
Top-tier vendors anchor premium predictive analytics tiers, while mid-market players compete on hardware-software bundling power. The vendor base stratifies across three tiers: turbine OEMs with data heritage, inverter manufacturers with integrated monitoring stacks, and independent software specialists. Two strategic archetypes dominate: heritage equipment vendors leveraging installed base lock-in, and modular platform vendors capitalizing on procurement unbundling. Competitive moves center on M&A for algorithm portfolios and capacity expansion in edge computing hardware.
Among European heritage equipment vendors, Vestas Wind Systems A/S and Siemens Gamesa Renewable Energy exemplify the turbine-data-anchored archetype that sustains premium software subscriptions. SMA Solar Technology AG occupies a position within the inverter-integrated tier that historically captured customers through hardware-software bundling. GE Vernova represents the diversified industrial conglomerate model applying cross-sector digital capabilities to renewable asset monitoring.
| Leading Market Players |
|---|
| Vestas Wind Systems A/S |
| Siemens Gamesa Renewable Energy |
| GE Vernova |
| SMA Solar Technology AG |
| Sungrow Power Supply |
| SolarEdge Technologies |
| Suzlon Energy Ltd. |
| Enphase Energy |
| NextEra Energy |
| Others |
Pricing and Supply Chain Analysis
Silicon wafer and rare earth magnet costs cascade through sensor module fabrication into tiered software subscription pricing, with edge computing hardware margins compressing as Chinese GB standard compliance mandates accelerate replacement cycles for calibration-dependent components.
Pricing Analysis
Bundled hardware-software packages are unbundling into separate SaaS tiers and commodity sensor procurement, with predictive analytics subscriptions commanding premium positioning against basic SCADA dashboards. Price differentiation rests on AI-enabled failure forecasting depth and FERC Order 2023 certification automation rather than raw hardware specifications. Pricing pressure stems from Indian independent power producers forcing annual renewal cycles against decade-long legacy contracts. Renewable energy providers with multi-OEM portfolios exhibit highest price sensitivity; utilities with consolidated procurement authority show lowest.
Supply Chain Analysis
Regional distribution centers in Denmark, Germany, and China's coastal provinces anchor hub-and-spoke fulfillment for control system algorithms and sensor calibration protocols. Manufacturing concentrates in China, Germany, and India. Component sourcing draws from Taiwanese semiconductor foundries, German precision sensor suppliers, and Chinese rare earth processors. Supply chain risk centers on single-source vulnerability for edge computing chipsets. Distribution runs through direct OEM channels for utility-scale deployments and systems integrator networks for industrial users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FERC Order 2023 interconnection reforms in the United States create mandatory demand for grid stability certification platforms that monitoring vendors must supply.
For Market Incumbents: Hedge proprietary algorithm exposure by embedding open protocol translation layers that reduce customer switching costs without sacrificing core control system margins. Capacity expansion in India's Tamil Nadu and Karnataka manufacturing corridors captures PLI scheme procurement waves. Certification investment in CEA-mandated renewable energy management center compliance defends against modular platform vendors capitalizing on procurement unbundling. For New Entrants and Emerging Players: Begin with brownfield SCADA migration services for decade-old European wind fleets where protocol translation complexity blocks heritage OEM incumbents from cost-effective retrofit pricing. India's renewable energy providers managing diversified equipment portfolios represent the most penetrable buyer segment. Go-to-market execution should anchor on annual SaaS renewal models that compress vendor switching cycles. For Investors and Strategic Acquirers: Roll-up economics work for independent software specialists because CEA and FERC mandates standardize data protocols that reduce platform integration complexity across acquired targets. Five-to-ten year viability hinges on AI predictive maintenance algorithm portfolios displacing reactive service revenue. Acquisition targets should demonstrate embedded edge computing hardware capabilities. The signal to watch is unbundling penetration rates among Indian independent power producers as inflection indicator for modular platform vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies wind SCADA and solar monitoring stacks into single-pane dashboards for hybrid dispatch optimization. |
| Acquisition of Specialist Firm | Adds AI predictive maintenance algorithms that forecast turbine bearing failure before operational impact. |
| Geographic Expansion | Establishes calibration protocol capabilities in Inner Mongolia and Gansu to serve multi-gigawatt hybrid parks. |
| Strategic Partnership | Links inverter manufacturers with turbine OEMs to preserve hardware-software bundling power against unbundling pressure. |
| Product Launch | Introduces digital twin architectures that compress commissioning timelines for greenfield hybrid renewable projects. |
Research Methodology
Bottom-up utility and renewable energy provider modeling reconciled against top-down sensor network and control system manufacturing tracking forms the analytical core of this study. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Triangulation across stakeholder inputs and published regulatory mandates ensures segmentation integrity.
Historical trendline analysis of deployment volumes and software subscription revenues establishes baseline trajectory patterns across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end user procurement authority, and application priority. CAGRs derive from regression analysis of correlated drivers including regulatory mandate implementation timelines, hybrid park commissioning schedules, and edge computing hardware cost curves. Forecast inputs incorporate India's PLI scheme capacity additions and China's MEE dual carbon goal enforcement intensity.
Several conditions sit outside the modeled scope, including cyber-physical security breach impacts on operational technology adoption, trade policy disruptions affecting semiconductor supply, and breakthrough battery storage technologies that could reduce hybrid coordination complexity. Forecasts reflect documented assumptions around regulatory implementation pacing and technology cost reduction trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Biogas Plant Market
Renewable Energy
Argentina Renewable Energy Market
Renewable Energy
Global Solar Home Lighting Market
Renewable Energy
Wave Energy Converter Market
Renewable Energy
Hydroelectric Cells Market
Renewable Energy
Philippines Renewable Energy Market
Renewable Energy
Renewable Energy in South America Market
Renewable Energy
Global Organic Rankine Cycle Market
Renewable Energy
Republic of Congo Renewable Energy Market
Renewable Energy
Kazakhstan Renewable Energy Market
Renewable Energy
Solar Drying System Market
Renewable Energy
Finland Renewable Energy Market
Renewable Energy
Austria Renewable Energy Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
Sweden Renewable Energy Market
Renewable Energy
United States Renewable Energy Market