
 Solar Thermal Collector Market | 2026-2036
Solar Thermal Collector Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Thermal Collector Market Analysis
Aftermarket service revenue is narrowing as a margin pool as original equipment manufacturers pull maintenance contracts in-house. Bosch Thermotechnology leverages its European service network to retain captive aftermarket income. Viessmann Werke anchors its position through backward integration into heat storage and control systems. GREENoneTEC Solarindustrie GmbH specializes in large-scale collector arrays for district heating operators.
A solar thermal collector is a device that absorbs incident solar radiation and transfers thermal energy to a heat transfer fluid, typically achieving stagnation temperatures between 150°C and 300°C depending on design geometry and selective coating emissivity. Its primary commercial purpose is to displace fossil-fuel combustion in low-to-medium temperature heating applications across buildings and industrial processes. Evacuated tube collectors capture premium pricing in cold-climate installations where thermal losses must be minimized. Flat plate collectors dominate residential water heating volumes due to simpler manufacturing and lower installed cost per square meter. Concentrated solar collectors occupy the process heat segment where temperatures above 250°C are required.
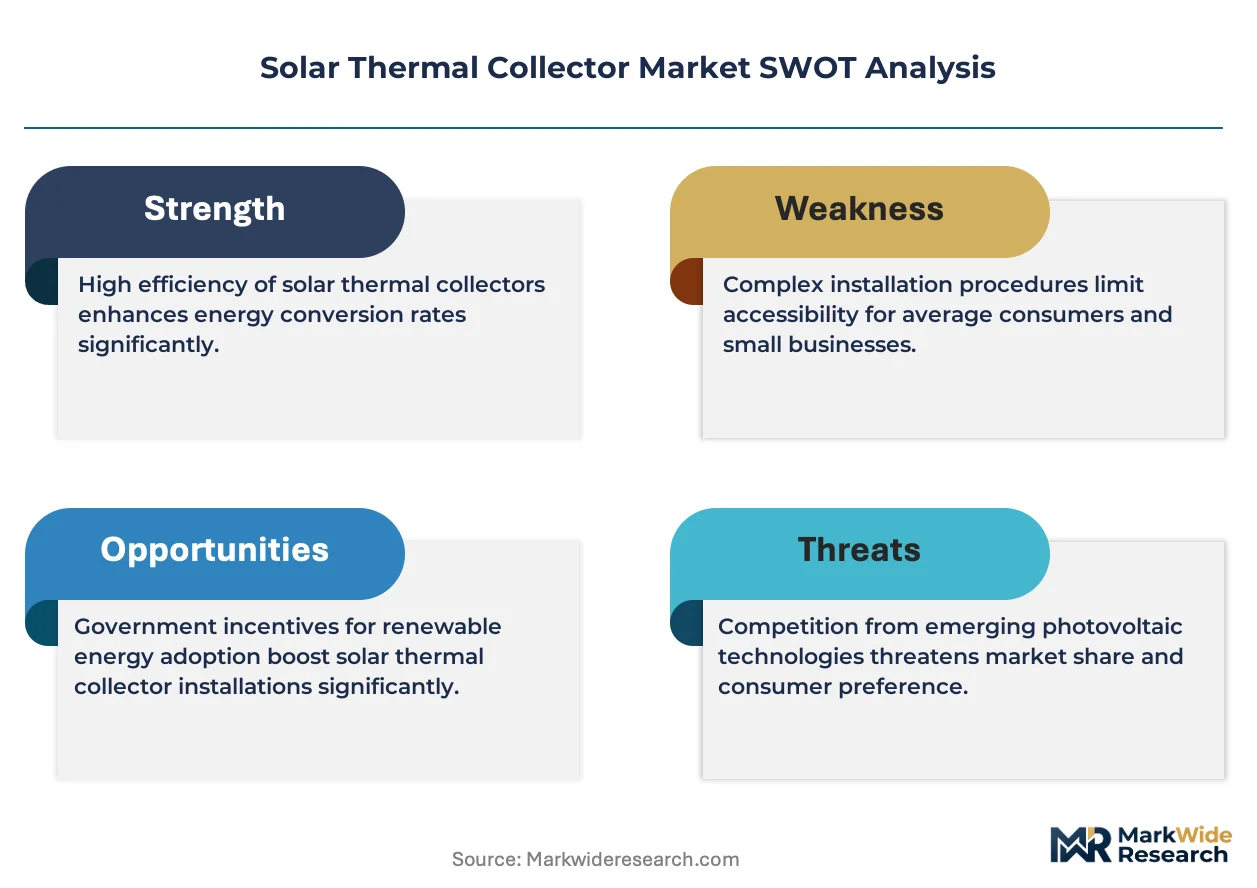
The EU Green Deal and F-Gas Regulation are accelerating collector efficiency benchmarks and restricting high-global-warming-potential working fluids in hybrid heat pump systems. Germany's KBA and federal building codes mandate minimum renewable heat shares in new commercial construction, directly expanding addressable collector surface area. Stakeholders must monitor whether updated CE marking requirements under the EU Solar Thermal Standard will exclude non-compliant imports from Eastern European supply channels.
Market Dynamics
The solar thermal collector market is undergoing a fundamental restructuring as industrial process heat buyers displace fossil-fuel combustion with renewable thermal systems, driven by tightening efficiency mandates and carbon pricing mechanisms across manufacturing corridors.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on high-global-warming-potential working fluids in hybrid heat pump systems are accelerating collector efficiency benchmarks and expanding addressable surface area for evacuated tube and flat plate technologies.
- China's dual carbon goals:Updated GB standards for renewable thermal systems are tightening efficiency mandates and creating mandatory replacement cycles for legacy industrial heating infrastructure.
- Food processing sector:Low-to-medium temperature heat requirements in dairy, brewing, and canning operations are scaling collector installations as natural gas price volatility compresses payback periods.
Market Restraints
- Copper and aluminum input volatility:Selective coating substrates and absorber plate materials face commodity price swings that compress manufacturing margins and destabilize project financing.
- German manufacturing corridor concentration:Collector production gravity in Baden-Württemberg and Austria's R&D cluster creates geographic supply risk and logistics bottlenecks for non-European project developers.
- Heat pump substitution:Electric vapor-compression systems with improving coefficient-of-performance ratings are capturing residential water heating volumes that collectors previously dominated.
Strategic Opportunities
- District heating networks:Large-scale collector arrays for centralized thermal distribution represent underpenetrated white space as municipal operators seek renewable heat shares.
- CE marking exclusion risk:Updated EU Solar Thermal Standard creates competitive moat for compliant manufacturers against non-compliant Eastern European imports.
- Industrial process heat above 250°C:Concentrated solar collectors for chemical, textile, and paper manufacturing represent emerging application expansion beyond traditional building services.
Industry Challenges
- Stagnation temperature certification:Testing protocols for 150°C to 300°C operating ranges create extended compliance timelines that delay product commercialization.
- Heat storage integration:Sizing and control system compatibility with legacy boiler infrastructure requires specialized engineering capacity that installer networks often lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Thermal Collector Market |
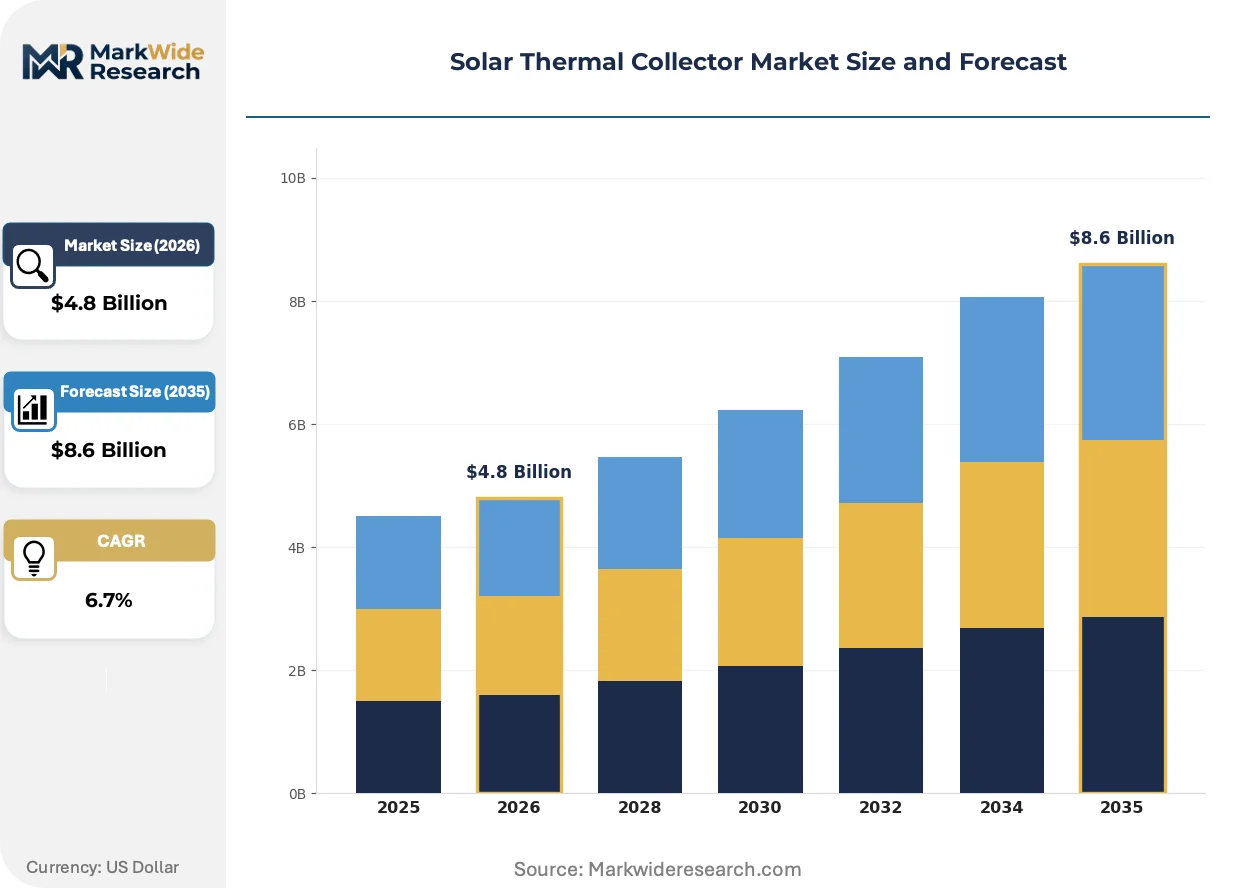
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Plate Collectors, Evacuated Tube Collectors, Concentrated Solar Collectors, Integrated Collector Storage Installation Type: Residential, Commercial, Industrial, Utility Scale End Use: Pool Heating, Water Heating, Space Heating, Process Heat System Configuration: Active Systems, Passive Systems, Hybrid Systems, Thermosiphon Systems |
| Companies Covered | Bosch Thermotechnology, Viessmann Werke, GREENoneTEC Solarindustrie GmbH, TVP Solar, Sunrain Group, Solimpeks, Absolicon Solar Collector AB, SunEarth, Heliodyne, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Thermal Collector Market Emerging Trajectories
Selective coating chemistry and vacuum insulation engineering are compressing thermal loss coefficients while stagnation temperature ratings climb, reshaping competitive differentiation between collector geometries.
Selective absorber coatings with low emissivity values are migrating from sputtered metal-ceramic composites to atomic layer deposition processes. District heating operators in Denmark and Germany are piloting these surfaces for large-scale arrays. The technology is migrating from premium cold-climate positioning toward cost-engineered flat plate variants that challenge evacuated tube economics in temperate zones.
The EU Green Deal's renewable heat share mandates are cascading into national building codes. Germany's KBA and federal construction standards now prescribe minimum collector surface area for new commercial builds. Industrial process heat buyers in Baden-Württemberg's manufacturing corridor are responding by pre-specifying certified systems in procurement tenders.
Aftermarket service contracts are unbundling from equipment supply as original equipment manufacturers pull maintenance revenue in-house. District heating operators and large industrial thermal buyers are encountering revised commercial terms that shift lifecycle service risk. This pattern is most visible in Germany and Austria where captive service networks anchor supplier relationships.
Solar Thermal Collector Market Segmentation
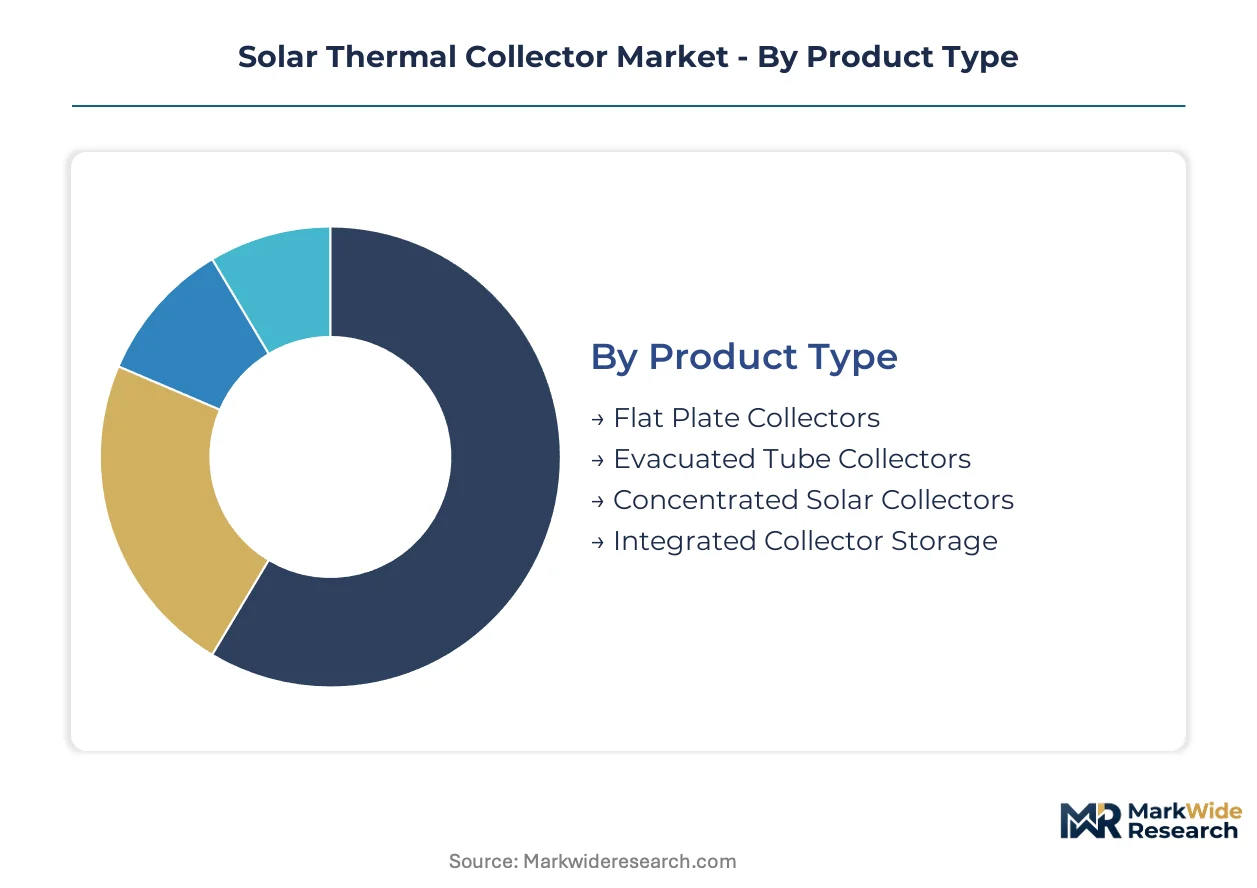
Solar thermal collector segmentation reveals how technology geometry, installation scale, and thermal application intersect to determine project economics and regulatory compliance. Understanding these dimensions exposes where efficiency mandates and carbon pricing mechanisms concentrate commercial opportunity.
Product Type:
Cost tier separates collector geometries by manufacturing complexity, selective coating chemistry, and stagnation temperature ratings.
- Flat Plate Collectors:Aluminum or copper absorber plates with tempered glass glazing and insulated backing achieve stagnation temperatures around 150°C. Demand concentrates in Germany's residential water heating retrofits where KBA building codes mandate minimum renewable heat shares and simpler installation keeps payback periods competitive against natural gas boilers.
- Evacuated Tube Collectors:Borosilicate glass tubes with vacuum insulation and selective absorber coatings minimize radiative heat losses, enabling 250°C stagnation ratings in sub-zero ambient conditions. Installations scale across Austria's alpine districts and China's northern industrial zones where cold-climate performance justifies premium pricing over flat plate alternatives.
- Concentrated Solar Collectors:Parabolic trough and Fresnel lens geometries focus direct normal irradiance onto linear receivers for process heat above 300°C.
- Integrated Collector Storage:Combined absorber and tank units eliminate separate storage vessels for low-volume residential applications.
Flat plate collectors command the established base. The steepest expansion runs through concentrated solar collectors.
Installation Type:
Application scale determines collector array sizing, thermal storage integration, and whether procurement flows through distributor networks or direct OEM contracting.
- Residential:Individual rooftop systems from 2-4 square meters serve domestic hot water loads. Installations cluster in Germany's Baden-Württemberg manufacturing corridor where Viessmann Werke and Bosch Thermotechnology maintain captive service networks that lock in aftermarket revenue.
- Commercial:Mid-scale arrays from 50-500 square meters address hotels, hospitals, and multi-family housing. GREENoneTEC Solarindustrie GmbH specializes in these configurations for Austrian and German municipal building tenders.
- Industrial:Process heat systems from 1,000+ square meters displace fossil combustion in food processing and textile manufacturing.
- Utility Scale:Centralized solar thermal plants feed district heating networks or industrial steam headers.
Residential installations anchor volume. Industrial arrays are climbing the fastest as carbon pricing compresses fossil fuel economics.
End Use:
Customer type and thermal temperature requirements segment demand by regulatory treatment and equipment specification intensity.
- Water Heating:Low-temperature applications from 40-60°C dominate collector deployment volumes. EU F-Gas Regulation restrictions on hybrid heat pump working fluids are expanding addressable surface area for dedicated solar thermal in German and Austrian new construction.
- Process Heat:Medium-to-high temperature loads from 80-400°C in dairy pasteurization, brewing, and chemical processing command system premiums. China's updated GB standards for renewable thermal systems are tightening efficiency mandates and triggering mandatory replacement cycles for legacy industrial boilers.
- Pool Heating:Seasonal low-temperature loads utilize unglazed polymer collectors.
- Space Heating:Seasonal thermal storage requirements complicate system sizing and control integration.
Water heating retains the volume base. Process heat is gaining share fastest as industrial decarbonization timelines accelerate.
System Configuration:
Supply concentration in German and Austrian engineering clusters shapes which configuration types achieve certification and installer network penetration.
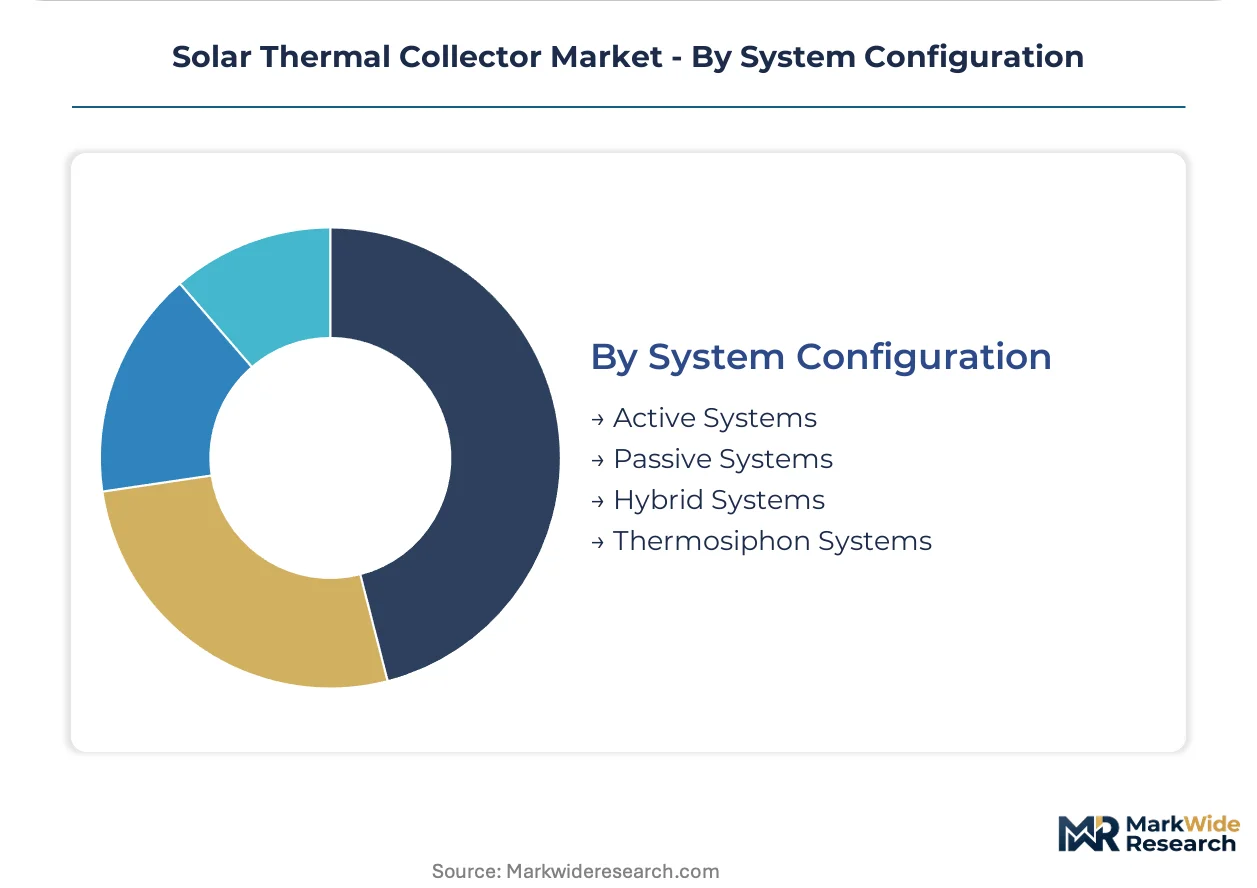
- Active Systems:Pump-circulated heat transfer fluid with differential temperature controllers enables precise thermal management and freeze protection. CE marking requirements under the EU Solar Thermal Standard favor these configurations for commercial and industrial compliance.
- Thermosiphon Systems:Natural convection eliminates pumping energy and control complexity. Passive circulation suits residential applications in China's solar-rich regions where cost minimization outweighs efficiency optimization.
- Passive Systems:Direct thermosiphon or integral collector-storage designs without mechanical components.
- Hybrid Systems:Solar thermal paired with heat pumps or auxiliary boilers for load-following.
Active systems command the certified commercial base. Thermosiphon configurations are expanding most quickly in cost-sensitive emerging installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys solar thermal collectors for industrial process heat at volumes unmatched elsewhere, while Germany concentrates on building-integrated residential systems and Austria specializes in cold-climate evacuated tube engineering.
Germany
Residential water heating retrofits and commercial construction mandates drive collector demand across the country. The KBA and federal building codes enforce minimum renewable heat shares in new commercial buildings. Production clusters in Baden-Württemberg host captive service networks that lock in aftermarket revenue for major suppliers.
China
Industrial decarbonization timelines and food processing sector expansion scale collector installations for medium-temperature process heat. Updated GB standards for renewable thermal systems mandate efficiency benchmarks and trigger replacement cycles for legacy boilers. Northern industrial zones deploy evacuated tube arrays for sub-zero climate performance.
Austria
Alpine climate conditions and district heating network expansion sustain premium evacuated tube demand. EU Green Deal renewable heat mandates cascade into national building codes that specify collector surface minima. The country's solar thermal R&D cluster advances selective coating chemistry and vacuum insulation engineering.
Denmark
District heating operators pilot large-scale collector arrays for centralized renewable thermal distribution. EU F-Gas Regulation restrictions on hybrid heat pump working fluids expand addressable surface area for dedicated solar thermal. Municipal procurement tenders increasingly pre-specify certified active systems.
United States
Commercial and industrial process heat buyers respond to natural gas price volatility by evaluating collector payback periods. The EPA and state-level renewable thermal incentives shape project economics in manufacturing corridors. Southwestern states with high direct normal irradiance concentrate concentrated solar collector interest for high-temperature applications.
Solar Thermal Collector Market Vendor Landscape
Capability concentration sits with European engineering specialists; scale advantage sits with integrated heating equipment conglomerates. The vendor base separates into three tiers: full-service heating system providers with captive distribution, selective coating and absorber technology specialists, and regional fabrication houses serving municipal tenders. Consolidation pressure runs through backward integration into heat storage and control systems, plus in-house production of selective absorber coatings.
Among Germany-based heating equipment conglomerates, Bosch Thermotechnology and Viessmann Werke exemplify the full-service tier with European service networks that retain lifecycle revenue. GREENoneTEC Solarindustrie GmbH occupies a specialist position in large-scale collector arrays for district heating operators. These three anchors illustrate how geographic proximity to Baden-Württemberg's manufacturing corridor and Austria's R&D cluster shapes competitive positioning.
| Leading Market Players |
|---|
| Bosch Thermotechnology |
| Viessmann Werke |
| GREENoneTEC Solarindustrie GmbH |
| TVP Solar |
| Sunrain Group |
| Solimpeks |
| Absolicon Solar Collector AB |
| SunEarth |
| Heliodyne |
| Others |
Supply Flow & Price Mechanics
Baden-Württemberg's manufacturing corridor concentrates collector production capacity, and its captive service networks translate geographic clustering into sustained pricing power for incumbent suppliers. Copper and aluminum input volatility feeds downstream cost compression that selectively erodes margins in flat plate segments while evacuated tube specialists preserve premium positioning through selective coating differentiation.
Pricing Analysis
Long-term offtake contracts dominate procurement for district heating operators and industrial process heat buyers, while residential retrofits flow through spot-market distributor channels. Three-tier pricing structure across premium evacuated tube, standard flat plate, and economy unglazed polymer levels separates certification-grade systems from commodity imports. Pricing pressure stems from heat pump substitution in residential water heating, compressing collector payback competitiveness. Municipal tenders exhibit lowest price sensitivity due to EU Green Deal renewable heat mandates, while residential retrofits face acute cost consciousness.
Supply Chain Analysis
Tariff exposure between China and the European Union threatens evacuated tube import economics for cold-climate installations. Manufacturing gravity centers on Germany, Austria, and China, with selective coating chemistry and vacuum insulation engineering anchored in Alpine R&D clusters. Supply chains draw from copper and aluminum substrate markets, borosilicate glass tubing, and sputtered metal-ceramic deposition equipment. Single-source vulnerability concentrates in advanced selective absorber coating production. Distribution runs through OEM captive service networks in Germany and Austria, with project-based direct contracting for industrial arrays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar thermal collector market sits in early-cycle expansion as industrial decarbonization timelines accelerate process heat adoption beyond traditional building services penetration. EU F-Gas Regulation restrictions on hybrid heat pump working fluids expand dedicated solar thermal addressable surface area.
For Market Incumbents: Harden certification moats through accelerated CE marking compliance under updated EU Solar Thermal Standards, excluding non-compliant Eastern European imports from procurement tenders. Deepen backward integration into heat storage and control systems to capture lifecycle service revenue that aftermarket unbundling threatens. Anchor capacity in Baden-Württemberg's manufacturing corridor to exploit logistics proximity for German and Austrian municipal tenders. For New Entrants and Emerging Players: Establish a beachhead in concentrated solar collectors for industrial process heat above 250°C, where chemical and textile manufacturing demand outpaces established supply. Target China's northern industrial zones for evacuated tube deployment under updated GB standards mandating efficiency benchmarks. Lead with thermosiphon configurations in cost-sensitive emerging installations where passive circulation minimizes control complexity. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated heating equipment conglomerates spinning non-core solar thermal divisions as heat pump portfolios absorb capital allocation. Favor specialists with captive selective coating production and district heating operator relationships over pure-play fabricators. Watch industrial carbon pricing trajectory as the signal for process heat segment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Storage | Captures lifecycle service revenue streams that OEMs are pulling in-house from distributor networks. |
| CE Marking Certification Investment | Creates competitive exclusion against non-compliant imports under updated EU Solar Thermal Standards. |
| District Heating Network Partnership | Locks in large-scale collector array procurement through municipal renewable heat share mandates. |
| Selective Coating Chemistry R&D | Enables stagnation temperature ratings that differentiate evacuated tubes in sub-zero Alpine installations. |
| Industrial Process Heat System Integration | Captures food processing and textile manufacturing demand as carbon pricing compresses fossil economics. |
Methodological Framework
Desk research of customs trade databases, EU regulatory filings, and national building code repositories preceded structured interviews with district heating procurement officers, industrial plant engineers, OEM aftermarket service heads, and selective coating R&D directors. Primary fieldwork with EPC contractors and municipal tender administrators was cross-validated against secondary sources including KBA construction statistics, CE marking certification databases, and GB standards documentation. Bottom-up project pipeline aggregation was triangulated against top-down equipment production estimates.
Fixed assumptions across the analysis window held carbon pricing trajectories, copper and aluminum commodity bands, and EU F-Gas Regulation enforcement timelines constant while varying industrial heat demand growth and residential retrofit incentive levels. Segmentation modeling spanned collector geometry, installation scale, end-use temperature requirements, and system configuration complexity. CAGRs were derived from installed surface area projections calibrated to efficiency mandate compliance deadlines and replacement cycle triggers.
Stress conditions across copper price volatility, CE marking compliance timeline delays, and heat pump coefficient-of-performance advancement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and industrial decarbonization commitment durability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Spray-On Solar Cells Market
Solar Power Systems
Mexico Solar Energy Market
Solar Power Systems
Solar Phone Chargers Market
Solar Power Systems
Off-Grid Solar Power Market
Solar Power Systems
Asia-Pacific Bifacial Solar Market
Solar Power Systems
Non-Concentrating Solar Collector Market
Solar Power Systems
Tubular Solar Collector Market
Solar Power Systems
Portable Solar Charger Market
Solar Power Systems
US Residential Solar PV Market
Solar Power Systems
Portugal Distributed Solar Energy Market
Solar Power Systems
APAC Solar Micro Inverters Market
Solar Power Systems
Solar Tracker for Power Generation Market
Solar Power Systems
Thin Film Photovoltaic Sales Market
Solar Power Systems
Solar Photovoltaic (PV) Market
Solar Power Systems
Middle East and Africa Solar Photovoltaic (PV) Market
Solar Power Systems
India Solar Photovoltaic (PV) Market