
 Insulation Flanges Market | 2026-2036
Insulation Flanges Market Size, Share, and Industry Trends Forecast 2026-2036
Insulation Flanges Market Analytics
Chinese stainless steel forging capacity is shifting toward specialty flange grades suited for high-pressure hydrocarbon service. Octal Flange leverages integrated forging and machining operations to control lead times on custom dimensions. Texas Flange anchors its position through Gulf Coast distribution proximity to Permian Basin pipeline projects. Minamisakai Flange Manufacturing Co., Ltd. competes on JIS-certified precision for Asian LNG terminal specifications.
Insulation flanges are bolted or welded pipeline components engineered with dielectric inserts—typically phenolic, neoprene, or high-density polyethylene—that electrically isolate adjoining pipe sections to prevent galvanic corrosion in cathodic protection systems. They must withstand design pressures commonly ranging from 150 to 2,500 psi and temperatures from minus 50 to plus 200 degrees Celsius depending on gasket and core material selection. Metal product types dominate current volume owing to structural load requirements in transmission pipelines, while composite formulations represent the fastest-expanding category as operators seek weight reduction in offshore platform and subsea tieback applications. The welded installation method leads in large-diameter transmission contracts, though bolted configurations command margin premiums in turnaround and maintenance environments where hot-work restrictions apply.
The US PHMSA and DOT pipeline safety regulations mandate insulating joints where dissimilar metals intersect or cathodic protection zones require electrical segmentation. API 6FB and ISO 15589-1 testing protocols govern fire-safe and dielectric performance qualifications, respectively. ASTM material specifications and NACE SP0286 corrosion standards further constrain supplier qualification pathways. Stakeholders must monitor evolving methane emission regulations and hydrogen blending trials, as both trends will recast material compatibility requirements and flange sealing performance thresholds.
Market Dynamics
Pipeline operators face escalating cathodic protection mandates that require electrical isolation at every metallic transition point, forcing procurement departments to pre-qualify flange suppliers against fire-safe and dielectric testing protocols before contract award.
Growth Catalysts
- API 6FB fire-safe certification:Transmission pipeline contractors in Texas and Louisiana now specify API 6FB-qualified insulating joints as a baseline bid requirement, expanding addressable demand for tested assemblies.
- Permian Basin midstream buildout:Crude oil gathering system expansions across West Texas and southeastern New Mexico are consuming record volumes of welded insulation flanges in 20-inch and larger diameters.
- Hydrogen blending trials:Utility-scale hydrogen injection into natural gas pipelines is recasting material compatibility specifications, creating replacement cycles for existing flange installations.
Market Restraints
- Stainless steel forging concentration:Specialty 316L and duplex stainless feedstock for high-pressure flanges concentrates among a limited set of Chinese and Indian forging houses, exposing lead times to export control volatility.
- NACE SP0286 qualification timelines:Corrosion-resistant material certification under NACE standards extends supplier onboarding to 18-24 months, freezing out newer entrants from major operator approved-vendor lists.
- Composite substitution ceiling:Phenolic and HDPE core materials face temperature and pressure limitations above 150 psi and 120°C that metal-cored flanges continue to dominate.
Strategic Opportunities
- Offshore platform weight reduction:Composite insulation flanges are penetrating North Sea and Gulf of Mexico subsea tieback projects where topside load constraints favor density reduction.
- Turnaround maintenance channel:Bolted flange configurations command premium positioning in refinery shutdown cycles where hot-work permitting delays favor mechanical assembly over welding.
- EU methane emission regulations:The EU's methane emission performance standards are accelerating leak-tight sealing requirements that favor precision-machined insulating joint designs over field-fabricated alternatives.
Industry Challenges
- ASME Section IX welder certification scarcity:Qualified pressure vessel welders capable of executing code-compliant insulation flange installation remain concentrated along the Gulf Coast, constraining nationwide deployment velocity.
- Legacy cathodic protection integration:Retrofitting insulating joints into operational pipelines requires electrical continuity interruption planning that conflicts with corrosion protection uptime requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulation Flanges Market |
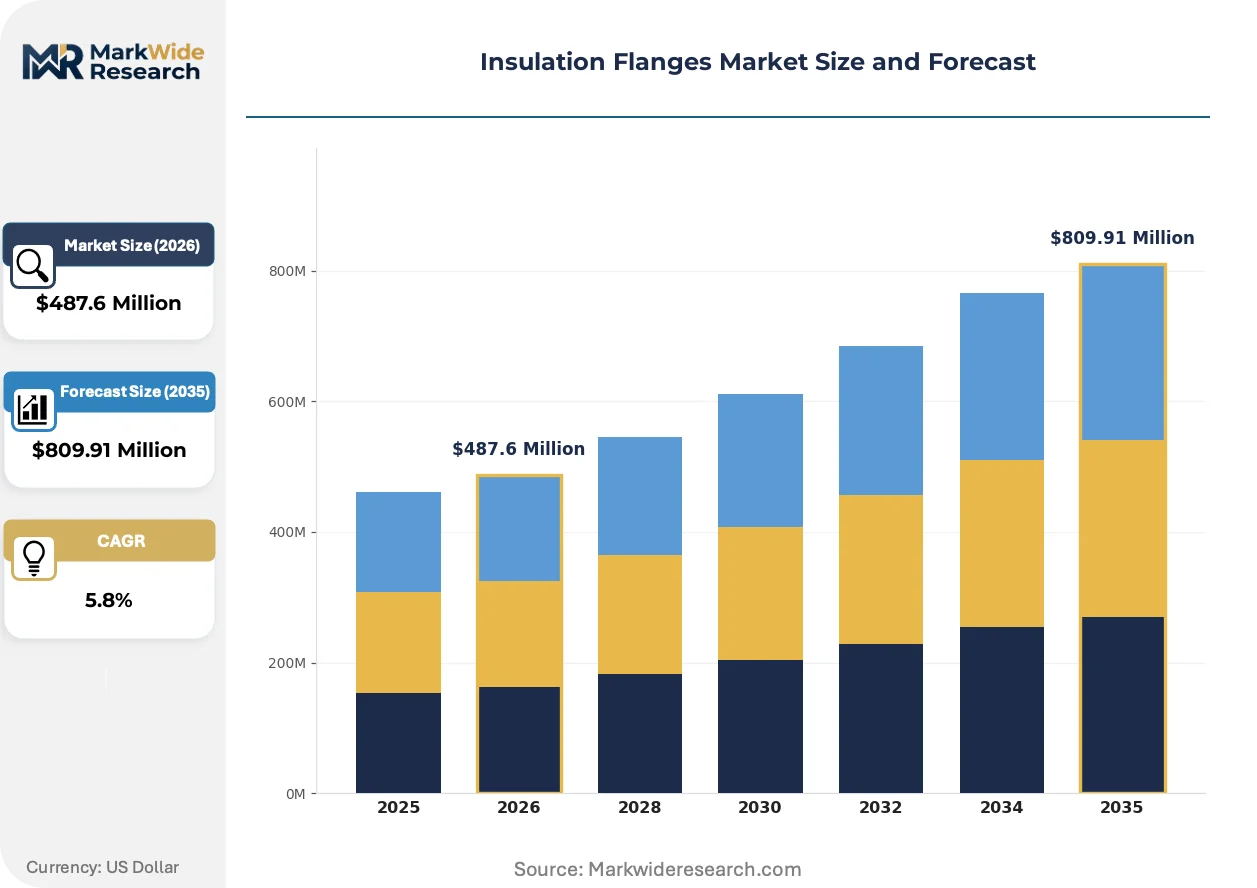
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal, Plastic, Composite, Fiberglass End User: Manufacturing, Oil & Gas, Energy, Construction Form: Flat, Round, Custom Shape, Standard Shape Installation Method: Welded, Bolted, Adhesive Bonding, Mechanical Fixing |
| Companies Covered | Octal Flange, Minamisakai Flange Manufacturing Co., Ltd., Texas Flange, Aoyama Kogyo Co., Ltd., Tokki Co., Ltd., Shaw Stainless & Alloy, Pirped International, Consus Co., Ltd., Martin Sprocket & Gear, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulation Flanges Market Evolving Landscape
Material science advances and regulatory tightening are compressing product development cycles while fragmenting buyer specifications across hydrogen service, subsea pressure ratings, and fire-safe performance tiers.
Modular composite core assemblies are modularizing field installation by enabling pre-tested dielectric inserts to ship separately from forged metal housings, reducing freight costs and damage rates. Offshore engineering contractors in the Gulf of Mexico are specifying these split-shipment configurations for platform projects with crane-limited logistics. The approach is modularizing supply chain risk by decoupling machining lead times from composite fabrication schedules.
REACH substance restrictions on phenolic resin precursors are forcing European flange manufacturers to reformulate core materials around halogen-free epoxy alternatives that maintain dielectric properties. The industrial consequence is a 12-18 month qualification gap as suppliers resubmit to ISO 15589-1 testing protocols. German transmission system operators are absorbing these compliance costs fastest, while Mediterranean contractors lag in specification updates.
Buyer consolidation among supermajor oil companies is compressing approved-vendor lists from thirty-plus suppliers to fewer than ten qualified fabricators per region. Engineering-procurement firms are responding by demanding turnkey cathodic protection compatibility packages that bundle insulating joints with monitoring hardware. This concentration is most visible in Texas, where Occidental, ExxonMobil, and Chevron have harmonized their technical specifications across Permian and Gulf Coast operations.
Insulation Flanges Market Segmentation
Insulation flange procurement varies sharply across pressure ratings, dielectric requirements, and installation constraints. Specification diversity forces suppliers to maintain parallel production lines for commodity and engineered-to-order outputs.
Product Type:
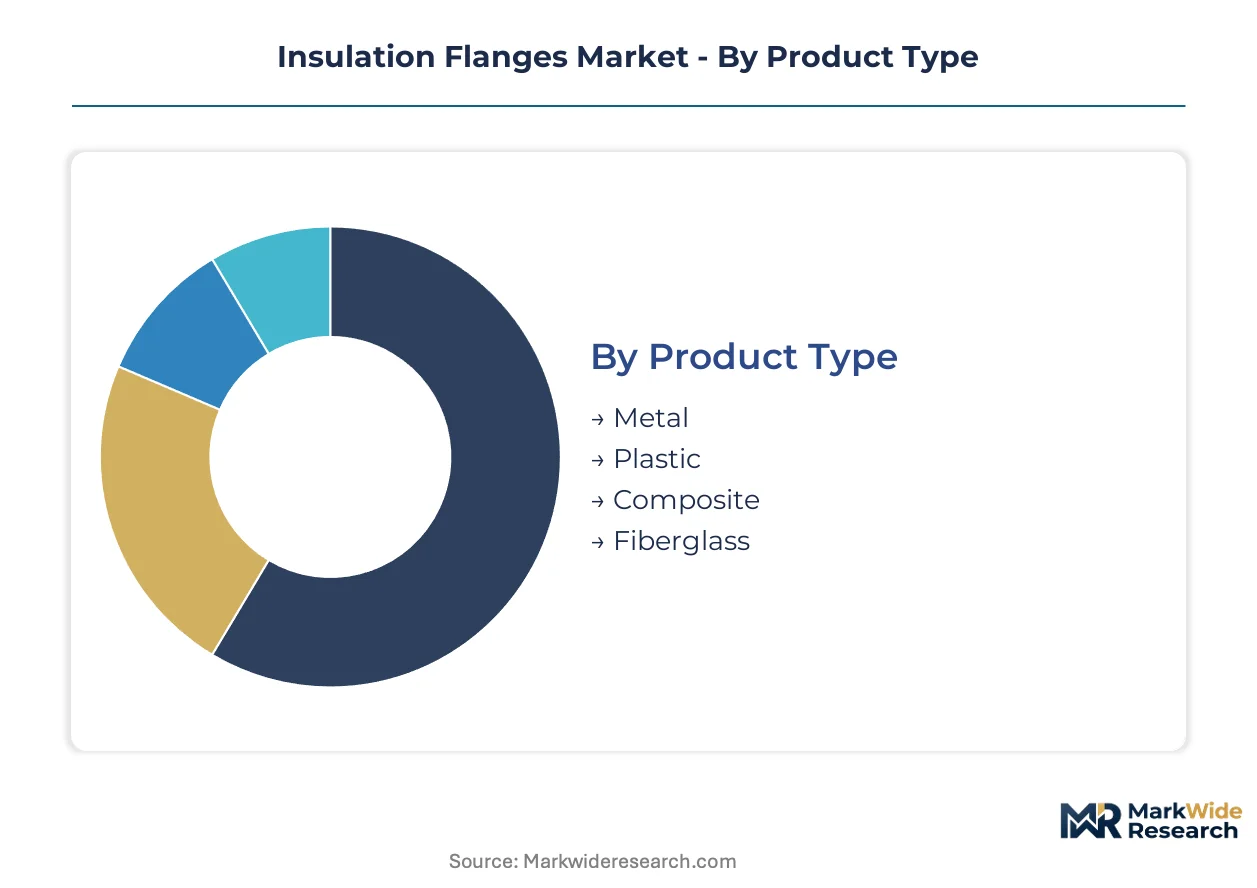
Standardization dominates high-volume pipeline contracts while specialty alloys and composites command customization premiums for corrosive or weight-critical service.
- Metal:Forged carbon steel, stainless steel, and duplex alloy housings withstand 150–2,500 psi design pressures and temperatures exceeding 200°C. PHMSA-mandated cathodic protection systems across Texas and Louisiana transmission corridors consume welded metal configurations in 20-inch and larger diameters.
- Composite:Phenolic, epoxy, or HDPE-cored assemblies reduce weight by 60–70% versus all-metal equivalents while maintaining dielectric isolation. North Sea and Gulf of Mexico subsea tieback projects specify these for topside load constraints, though temperature ceilings at 120°C limit downstream process applications.
- Plastic:Injection-molded polymer flanges serve low-pressure utility and water distribution networks where structural loads remain minimal.
- Fiberglass:Glass-reinforced thermoset configurations resist galvanic corrosion in coastal and chemical exposure environments.
Leading the category by volume: Metal. Growing fastest: Composite.
End User:
Capital intensity and regulatory exposure create divergent procurement patterns across industrial sectors.
- Oil & Gas:Midstream operators face API 6FB fire-safe and ISO 15589-1 dielectric qualification mandates that pre-qualify suppliers before contract award. Permian Basin gathering system expansions drive welded insulation flange consumption in record volumes.
- Energy:Utility-scale hydrogen blending trials recast material compatibility specifications, forcing replacement cycles for existing flange installations as embrittlement risks emerge at elevated partial pressures.
- Manufacturing:Process industries deploy bolted configurations during turnaround maintenance cycles where hot-work permitting delays favor mechanical assembly.
- Construction:Commercial and institutional building systems specify lower-pressure plastic and fiberglass variants for HVAC and water service isolation.
Dominant demand source: Oil & Gas. Steepest expansion trajectory: Energy.
Form:
Geometric complexity directly correlates with machining cost and lead time extension.
- Round:Symmetrical geometries enable CNC turning efficiencies and standard gasket compatibility across ANSI and API dimensional catalogs. Off-the-shelf availability compresses procurement cycles for maintenance, repair, and operations inventories.
- Custom Shape:Non-standard bolt circle patterns, raised face modifications, and integral instrumentation ports serve platform-specific piping configurations. Gulf of Mexico engineering contractors specify these for crane-limited logistics where modular pre-assembly reduces offshore man-hours.
- Flat:Compact face-to-face dimensions suit space-constrained skid packages and packaged equipment enclosures.
- Standard Shape:Catalog square, oval, or rectangular configurations address niche architectural and structural penetration applications.
Highest shipment volumes: Round. Fastest specification growth: Custom Shape.
Installation Method:
Field execution constraints and code compliance requirements segment procurement between permanent and serviceable attachment modes.
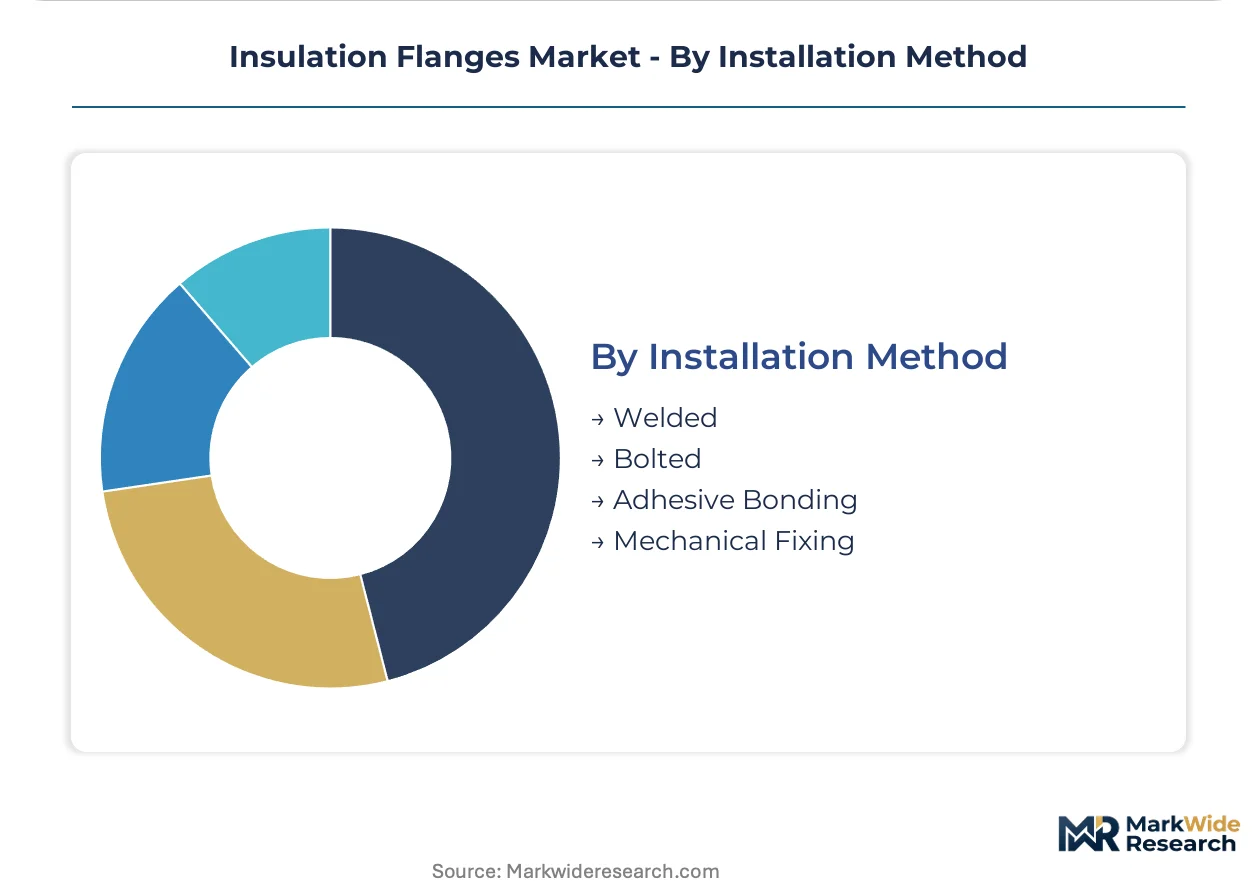
- Welded:ASME Section IX-qualified procedures deliver pressure-boundary integrity for transmission pipelines and process piping. Gulf Coast welder certification scarcity constrains nationwide deployment velocity despite dominant specification in large-diameter contracts.
- Bolted:Mechanical assembly permits electrical isolation verification and future replacement without cutting and re-welding. Refinery turnaround contractors in Texas and Louisiana pay 15–25% premiums to avoid hot-work permitting delays.
- Adhesive Bonding:Specialized epoxy systems enable dielectric isolation in non-metallic piping and repair scenarios where welding is impossible.
- Mechanical Fixing:Compression and clamp-style attachments serve temporary bypass and commissioning applications.
Prevalent in new construction: Welded. Margin premium capture: Bolted.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty stainless steel forging capacity clusters in China's Jiangsu and Zhejiang provinces, supplying precision-machined housings for high-pressure hydrocarbon service worldwide. This feedstock concentration shapes procurement patterns across North American and Asian terminal projects.
United States
PHMSA corrosion control mandates drive cathodic protection-compatible flange procurement across Texas and Louisiana transmission corridors. The Pipeline and Hazardous Materials Safety Administration requires insulating joints at every metallic transition point in interstate pipelines. Permian Basin gathering system expansions in West Texas and southeastern New Mexico consume welded configurations in 20-inch and larger diameters.
China
Jiangsu and Zhejiang forging houses supply 316L and duplex stainless feedstock for high-pressure flange assemblies serving Asian LNG terminals. GB standards and MIIT industrial policy guide domestic certification pathways for pressure-boundary components. Yangtze River Delta fabricators leverage integrated forging and machining operations to compress lead times on custom dimensions.
Japan
JIS-certified precision flanges serve Tokyo Bay and Osaka Bay LNG terminal specifications with tight dimensional tolerances. METI energy security policy prioritizes domestic sourcing for critical pipeline infrastructure. Minamisakai Flange Manufacturing anchors Kansai-region supply for Asian export markets.
Germany
REACH substance restrictions on phenolic resin precursors force core material reformulation toward halogen-free epoxy alternatives. ECHA compliance timelines create 12-18 month qualification gaps as suppliers resubmit to ISO 15589-1 testing protocols. Ruhr industrial corridor transmission operators absorb these compliance costs fastest among European buyers.
Saudi Arabia
Eastern Province petrochemical complexes specify fire-safe insulating joints for high-temperature process streams in refinery expansion cycles. The country's national oil company procurement standards harmonize with API 6FB qualification requirements. Jubail Industrial City demand concentrates in turnaround maintenance channels where bolted configurations avoid hot-work permitting delays.
Insulation Flanges Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue composite specialization and modular assembly configurations. Market structure tilts toward regional concentration, with Gulf Coast proximity, Asian forging integration, and European regulatory compliance each anchoring distinct competitive positions. Three archetypes dominate: integrated forging-to-machining operators, precision-certified specialists, and regional distributors with inventory depth. Capacity expansion and approved-vendor list pre-qualification represent the dominant competitive moves as operator consolidation compresses supplier pools.
Among Asian fabricators, Minamisakai Flange Manufacturing Co., Ltd. and Aoyama Kogyo Co., Ltd. exemplify the precision-certified specialist archetype with JIS-standard positioning. Texas Flange anchors the regional distributor model through Gulf Coast inventory proximity to Permian Basin projects. Octal Flange represents the integrated forging-to-machining operator with Chinese capacity backing custom dimension control.
| Leading Market Players |
|---|
| Octal Flange |
| Minamisakai Flange Manufacturing Co., Ltd. |
| Texas Flange |
| Aoyama Kogyo Co., Ltd. |
| Tokki Co., Ltd. |
| Shaw Stainless & Alloy |
| Pirped International |
| Consus Co., Ltd. |
| Martin Sprocket & Gear, Inc. |
| Others |
Value Network & Pricing Analysis
Specialty 316L and duplex stainless steel feedstock costs cascade through three distinct pricing tiers as forged housings move from Jiangsu and Zhejiang forging houses through precision machining to cathodic protection system integrators. API 6FB fire-safe certification and NACE SP0286 corrosion-resistant material qualification create service-bundling premiums that separate approved-vendor list holders from commodity fabricators.
Pricing Analysis
Warranty-backed dielectric performance guarantees and ISO 15589-1 testing documentation separate premium-tier suppliers from unbundled commodity offerings. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth, with API 6FB-qualified assemblies commanding 15-25% premiums over untested equivalents. Cost compression in standard-tier welded configurations is intensifying because buyer consolidation among Permian Basin operators concentrates volume leverage. Turnaround maintenance contractors in Texas and Louisiana show least price sensitivity, absorbing bolted-configuration premiums to avoid hot-work permitting delays.
Supply Chain Analysis
Refurbishment flows for dielectric insert replacement and flange housing re-machining create reverse-logistics channels that extend asset life in operational pipelines. Supply concentrates in China's Jiangsu and Zhejiang provinces for specialty stainless forging, India's forging houses for duplex alloy feedstock, and Japan's Kansai region for JIS-certified precision machining. The supply chain draws from phenolic resin precursors, high-density polyethylene cores, and halogen-free epoxy alternatives as REACH restrictions force material transitions. Single-source vulnerability in Chinese forging capacity exposes lead times to export control volatility. Distribution runs through Gulf Coast stocking distributors with proximity to Permian Basin pipeline projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insulation flanges market functions as a cost-of-compliance arena where PHMSA cathodic protection mandates and API 6FB fire-safe certification requirements erect 18-24 month supplier qualification barriers that protect incumbents with approved-vendor status.
For Market Incumbents: Anchor market position by deepening backward integration into specialty stainless forging capacity to insulate against Chinese export control volatility. Defend against composite flange specialists by accelerating halogen-free epoxy core qualification ahead of REACH compliance deadlines. Prioritize capacity expansion along the Gulf Coast to capture Permian Basin gathering system buildout demand. For New Entrants and Emerging Players: Engineering-procurement firms represent the most accessible channel partners for modular composite core assemblies with split-shipment configurations. Target North Sea and Gulf of Mexico subsea tieback projects where topside weight constraints favor density reduction and crane-limited logistics reward pre-tested dielectric inserts. Pursue white-space in European methane emission compliance markets where leak-tight sealing requirements displace field-fabricated alternatives. For Investors and Strategic Acquirers: Hydrogen blending trial announcements at utility-scale natural gas pipeline operators are the leading indicator that material compatibility replacement cycles are accelerating. Position for 5-10 year viability by acquiring precision-certified specialists with JIS or API 6FB qualification assets rather than undifferentiated commodity fabricators. Monitor NACE SP0286 certification pipeline velocity as the signal for supplier pool consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| API 6FB Fire-Safe Certification Investment | PHMSA-mandated corrosion control standards require tested assemblies for interstate pipeline contracts. |
| Backward Integration into Specialty Forging | Captive 316L and duplex stainless feedstock supply insulates against Chinese export control disruptions. |
| Halogen-Free Epoxy Core Qualification | REACH substance restrictions on phenolic resins force 12-18 month reformulation timelines. |
| Gulf Coast Distribution Expansion | Proximity to Permian Basin and Louisiana petrochemical corridors compresses procurement cycles. |
| Modular Composite Assembly Development | Split-shipment configurations reduce freight costs and damage rates for offshore platform logistics. |
Research Methodology
Multi-period observation of cathodic protection system procurement volumes, API 6FB certification pipeline velocity, and NACE SP0286 qualification timelines anchored the trend analysis, supplemented by interviews with pipeline engineering directors, cathodic protection specialists, EPC procurement managers, refinery maintenance planners, and specialty forging house operations heads. Secondary validation drew from PHMSA incident reports, API standards documentation, customs trade data for stainless steel flange imports, and SEC filings from midstream infrastructure operators. Bottom-up project tracking across Permian Basin gathering systems and top-down operator capex analysis were triangulated against regional welding certification capacity constraints.
Input-output matrix modeling connected specialty stainless feedstock availability, ASME Section IX welder certification scarcity, and approved-vendor list concentration to flange procurement velocity across the analysis window. Segmentation dimensions included product type (metal, composite, plastic, fiberglass), installation method (welded, bolted, adhesive, mechanical), end-use sector (oil and gas transmission, hydrogen blending infrastructure, refinery turnaround, subsea tieback), and pressure-temperature rating tiers. CAGRs were derived from pipeline mileage expansion forecasts and cathodic protection system replacement cycles. Hydrogen embrittlement risk curves and fire-safe testing protocol adoption rates served as industry-specific forecast modifiers.
Caveats apply where REACH substance restriction enforcement delays, hydrogen blending trial acceleration, or Chinese forging export control expansion could materially shift the outlook. Forecasts embed assumptions about PHMSA regulatory continuity and API standards adoption without anticipating structural revision. Practitioners should monitor NACE SP0286 certification backlog durations and Permian Basin welder training pipeline throughput for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
North America Irrigation Valves Market
Valves
Sand Control System Market
Valves
Penstock Market
Valves
Pneumatic Positioner Market
Valves
Orifice Reducers Market
Valves
Gate Impellers Market
Valves
Valve Manifold Box (VMB) Market
Valves
Portable Valve Actuator Market
Valves
Cryogenic Valve Market
Valves
United States Valves Market
Valves
Battery Pack Cooling Valve Actuator Systems Market
Valves
Asia-Pacific Medium Voltage Switchgear Market
Valves
Transmission Overload Protectors Market
Valves
Servo Valves Market
Valves
Global Gas Pressure Regulator Market
Valves
North America Valves Market