
 Radiant Cooling Systems Market | 2026-2036
Radiant Cooling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Radiant Cooling Systems Market Analytics
Buyer concentration in the commercial real estate sector is shifting as institutional landlords and sovereign wealth funds consolidate their sustainability procurement standards across multi-building portfolios. REHAU leverages its polymer extrusion expertise to supply cross-linked polyethylene piping networks for large-scale radiant cooling installations. Danfoss Group anchors the controls layer with variable-speed circulators and zone-valve assemblies that integrate with building automation systems. Uponor Corporation competes through its pre-insulated piping systems and prefabricated manifold stations that reduce on-site labor hours.
Radiant cooling systems distribute chilled water, electricity, or conditioned air through surface-embedded circuits to absorb sensible heat loads at temperatures between 14°C and 18°C, eliminating the energy penalty of forced-air dehumidification and ductwork fan power. Hydronic technology dominates installed capacity in commercial and healthcare applications where thermal mass and humidity control are critical, while smart controls represent the fastest-expanding segment as IoT-enabled actuators and predictive algorithms reduce commissioning time and operating energy. Electric radiant panels occupy a narrower niche in residential retrofit markets where structural access to ceiling slabs is limited.
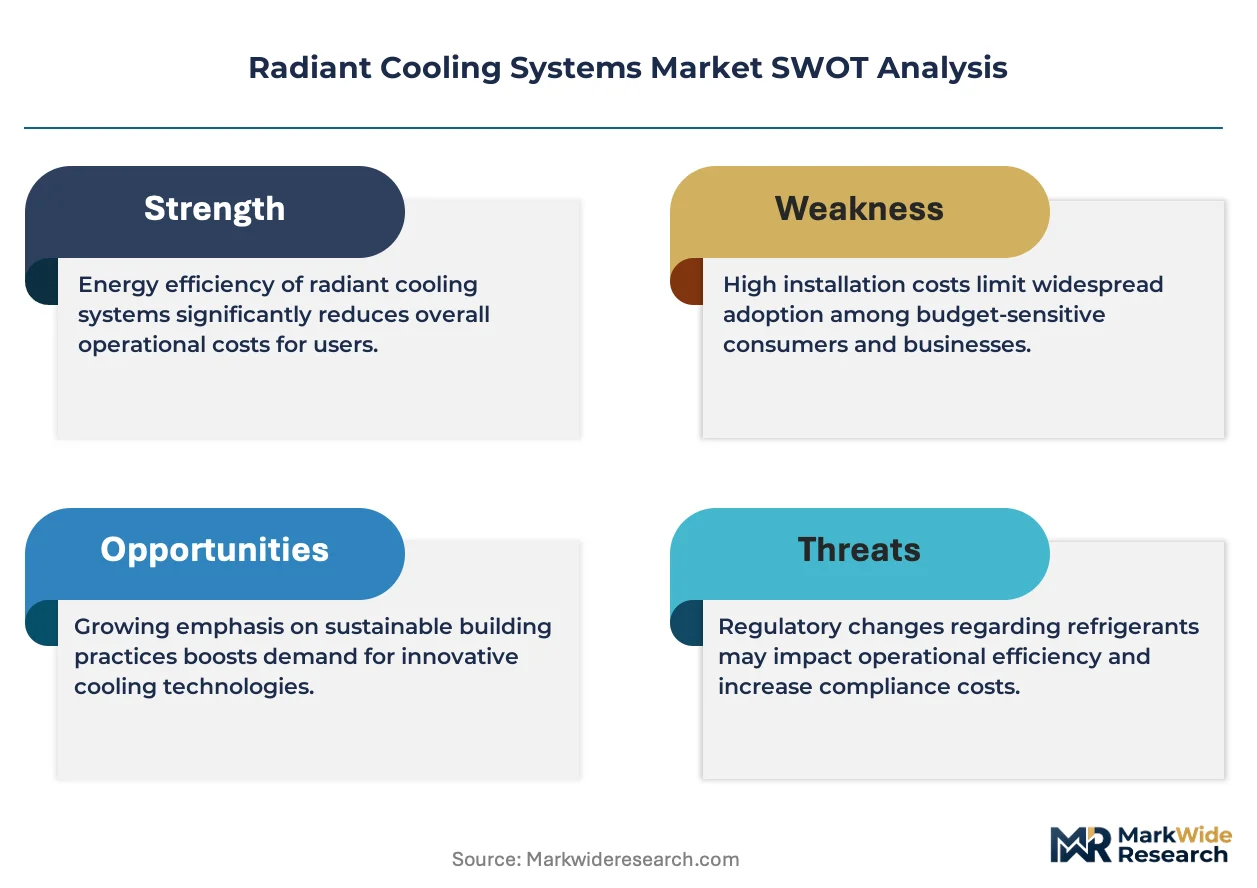
Europe's F-Gas Regulation and the EU Green Deal's building performance standards are tightening refrigerant restrictions and mandating embodied-carbon disclosures for HVAC replacements, directly favoring water-based radiant architectures. In the United States, ASHRAE Standard 55 and the EPA's Energy Star certification programs shape thermal comfort benchmarking and equipment eligibility for federal tax incentives. China's GB standards for building energy efficiency and its dual carbon goals are accelerating municipal adoption of radiant systems in public infrastructure projects. Stakeholders must monitor how evolving humidity-control integration requirements and local water-quality standards affect system specification and maintenance protocols across jurisdictions.
Market Dynamics
Hydronic radiant cooling architectures are displacing conventional variable refrigerant flow systems as Europe's F-Gas Regulation compresses fluorinated gas availability and building codes tighten embodied-carbon thresholds for HVAC retrofits.
Growth Catalysts
- EU Green Deal building performance standards:Mandated energy efficiency disclosures for commercial retrofits are redirecting capital toward water-based surface cooling systems in Germany and France.
- Net-zero commercial office construction:Institutional landlords in Singapore and Dubai are specifying ceiling-embedded hydronic panels to meet portfolio-level carbon targets.
- Cross-linked polyethylene piping networks:Advances in polymer extrusion durability are extending system lifespans and reducing maintenance intervals in healthcare facilities.
Market Restraints
- Copper and polymer feedstock volatility:Hydronic distribution networks face input cost pressure from commodity price swings in piping materials.
- Technical limitation in humidity control:Surface temperatures must stay above dew point thresholds, requiring dedicated dehumidification equipment in tropical climates.
- Substitution threat from magnetic-bearing chillers:High-efficiency forced-air systems retain specification advantage in existing buildings with intact ductwork infrastructure.
Strategic Opportunities
- China's Yangtze River Delta megacity cluster:Municipal infrastructure projects under dual carbon goals are specifying radiant systems for public transit hubs and government buildings.
- IoT-enabled predictive control convergence:Integration of zone-level actuators with building automation systems is opening performance-contracting revenue streams.
- Residential retrofit channel innovation:Electric radiant panels are penetrating ceiling-restricted housing stock through surface-mounted installation kits.
Industry Challenges
- Commissioning skill scarcity:Hydronic balancing and controls integration require specialized technicians in short supply across construction labor markets.
- Legacy system interoperability:Integration with existing building management protocols demands protocol translation hardware and extended project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiant Cooling Systems Market |
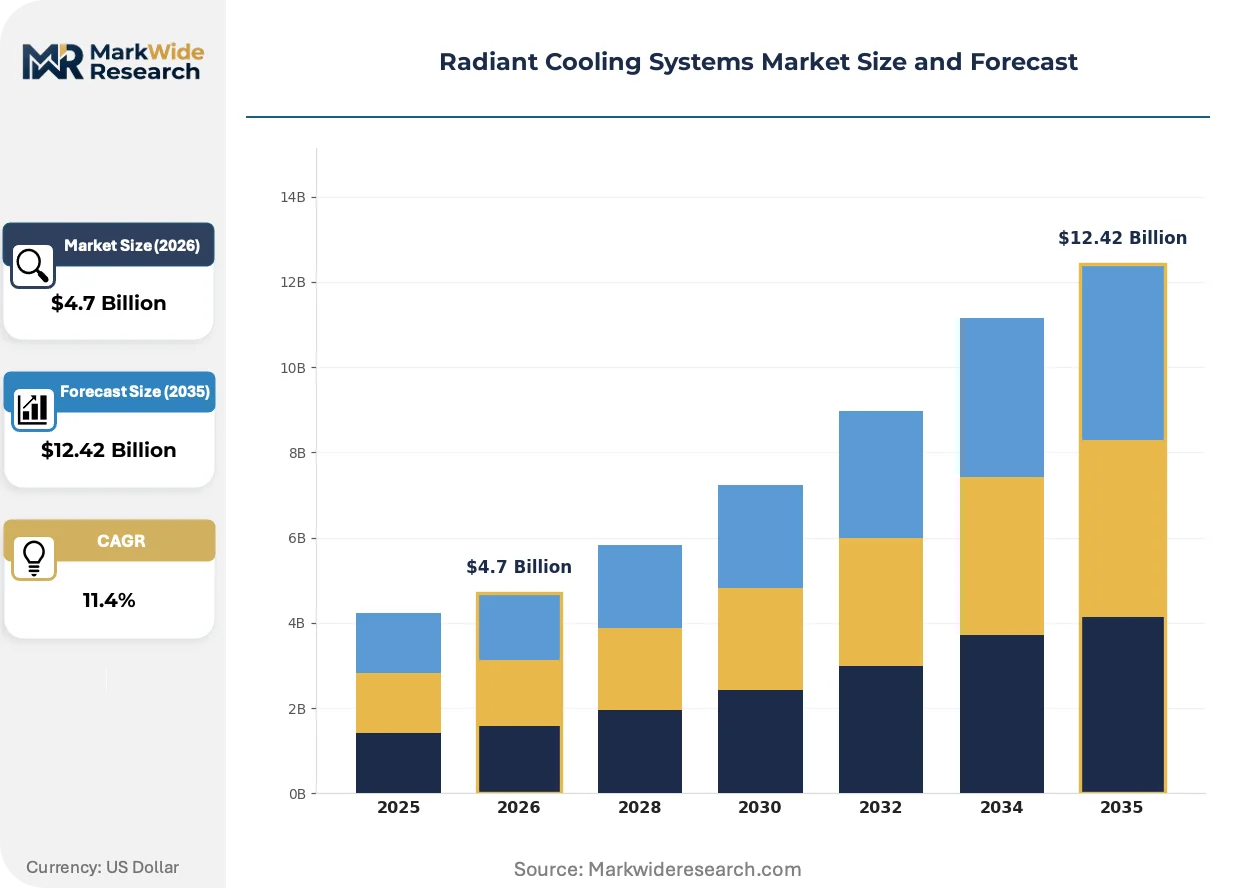
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.42 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydronic, Electric, Air-Based, Phase Change Material Application: Residential, Commercial, Industrial, Healthcare Control Method: Manual, Automatic, Smart Controls, Integrated Systems Installation Type: New Construction, Retrofitting, Modular Units, Centralized Systems |
| Companies Covered | Jardine Engineering Corporation (JEC), Giacomini Spa, Danfoss Group, Emerson Electric Co., REHAU, Messana Inc., Uponor Corporation, Zehnder Group, MrPEX Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiant Cooling Systems Market Evolving Landscape
Machine-learning control algorithms and prefabricated manifold assemblies are compressing installation timelines and operating energy simultaneously. Three developments are restructuring competitive advantage.
Machine-learning predictive control is automating zone-level thermal response by anticipating occupancy patterns and weather shifts. Large commercial landlords are deploying these systems across multi-building portfolios to reduce commissioning overhead. The technology is automating the traditional manual balancing process that previously consumed weeks of specialist labor.
Europe's F-Gas Regulation is accelerating refrigerant-phaseout timelines and redirecting specification toward water-based alternatives. The industrial consequence is a supply squeeze on certified HVAC contractors capable of handling legacy refrigerant recovery. Commercial new-build segments in Germany and the Netherlands are responding by eliminating compressor-based cooling from initial designs.
Performance-based energy service contracts are displacing equipment-only procurement in institutional real estate. Facility management providers are bundling installation with guaranteed thermal comfort outcomes and absorbing operational risk. This shift is most visible in Singapore's sovereign wealth fund commercial portfolios and Dubai's free-zone developments.
Radiant Cooling Systems Market Segmentation
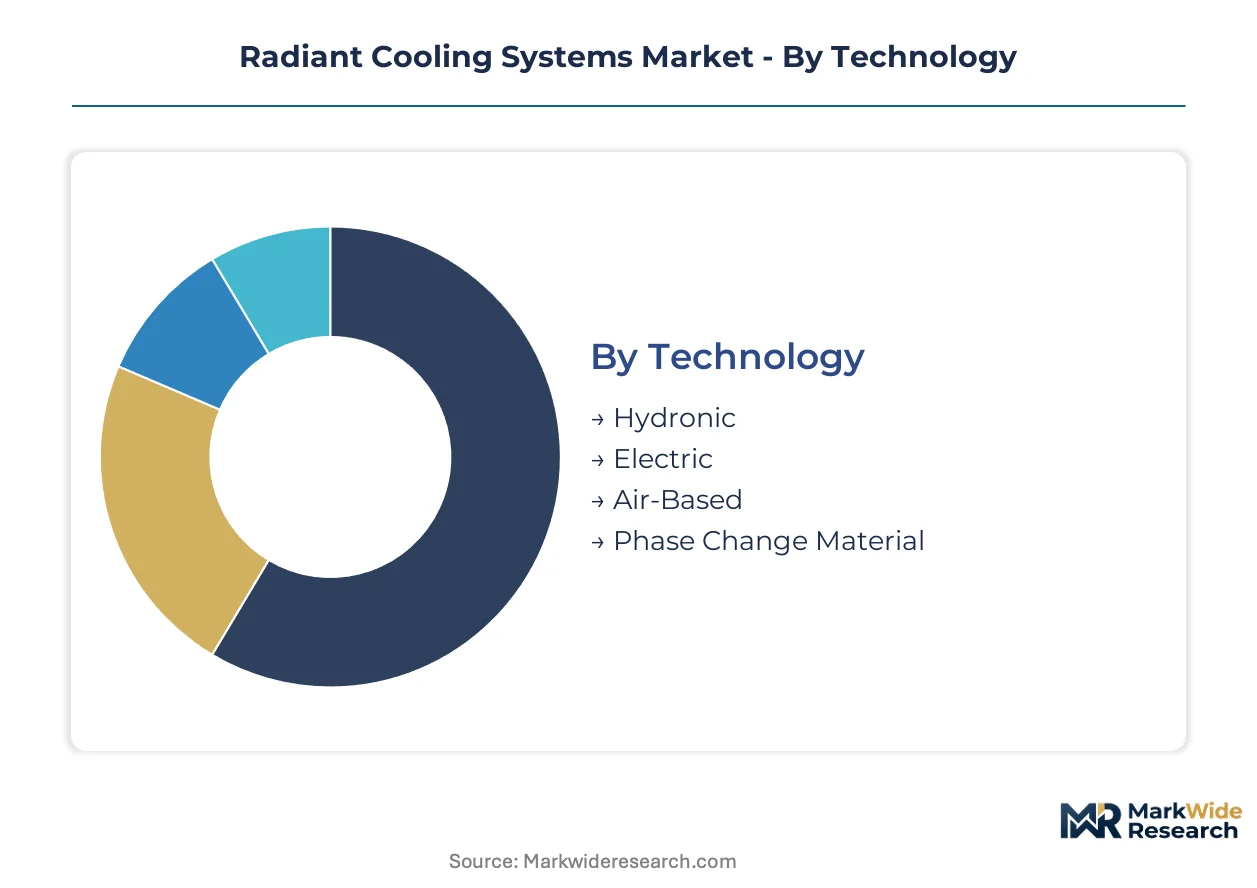
Radiant cooling architectures diverge sharply in their integration depth, from standalone electric panels to building-embedded hydronic networks. Understanding these structural distinctions clarifies where capital concentrates and which technologies capture specification momentum across construction cycles.
Technology:
Integration depth separates surface-embedded hydronic circuits from standalone electric installations, with material science advances reshaping competitive boundaries.
- Hydronic:Chilled water circulates through cross-linked polyethylene or copper tubing embedded in ceiling slabs and floor structures. Germany's Passivhaus construction corridor and Singapore's net-zero commercial towers specify these systems for thermal mass advantages and humidity stability.
- Electric:Resistance-heating elements or thermoelectric modules mount directly to surfaces without plumbing infrastructure. Demand concentrates in residential retrofit channels across Spain and Italy where structural ceiling access is restricted and installation speed outweighs operating efficiency.
- Air-Based:Conditioned air passes through radiant panels with minimal ductwork; compact units serve temporary structures.
- Phase Change Material:Salt hydrates or paraffin waxes store and release thermal energy passively; niche deployment in passive house prototypes.
Hydronic systems lead volumes today; smart controls integration is gaining share fastest across specification portfolios.
Application:
End-use economics drive divergent performance requirements, with healthcare and commercial segments prioritizing precision over first-cost minimization.
- Commercial:Ceiling-embedded hydronic panels serve open-plan offices, retail atriums, and hospitality lobbies where thermal uniformity reduces absenteeism claims. Dubai's sovereign wealth fund developments and Amsterdam's EDGE-certified towers mandate these systems for portfolio-level carbon accounting.
- Healthcare:Operating theaters and patient wards demand tight temperature and humidity bands with minimal air movement. China's Yangtze River Delta hospital construction program specifies radiant cooling to reduce airborne pathogen circulation.
- Residential:Single-family homes and multifamily units balance upfront cost against comfort; electric panels penetrate renovation markets.
- Industrial:Manufacturing floors with high latent loads require hybrid approaches; limited pure radiant deployment.
Commercial applications dominate current specification; healthcare is climbing fastest as infection-control protocols tighten.
Control Method:
Automation sophistication determines commissioning labor and ongoing operating efficiency, with predictive algorithms compressing payback periods.
- Smart Controls:IoT-enabled sensors and machine-learning algorithms anticipate occupancy patterns and weather shifts. Large commercial landlords in Singapore deploy these across multi-building portfolios to automate zone-level thermal response.
- Integrated Systems:Native connectivity with building automation protocols eliminates protocol translation hardware. Germany's F-Gas Regulation compliance projects favor these for streamlined refrigerant-phaseout documentation.
- Automatic:Programmable thermostats with fixed schedules; mid-market commercial standard.
- Manual:Occupant-adjusted valves or switches; residual presence in legacy residential stock.
Integrated systems anchor current deployment; smart controls show steepest expansion trajectory as performance contracting spreads.
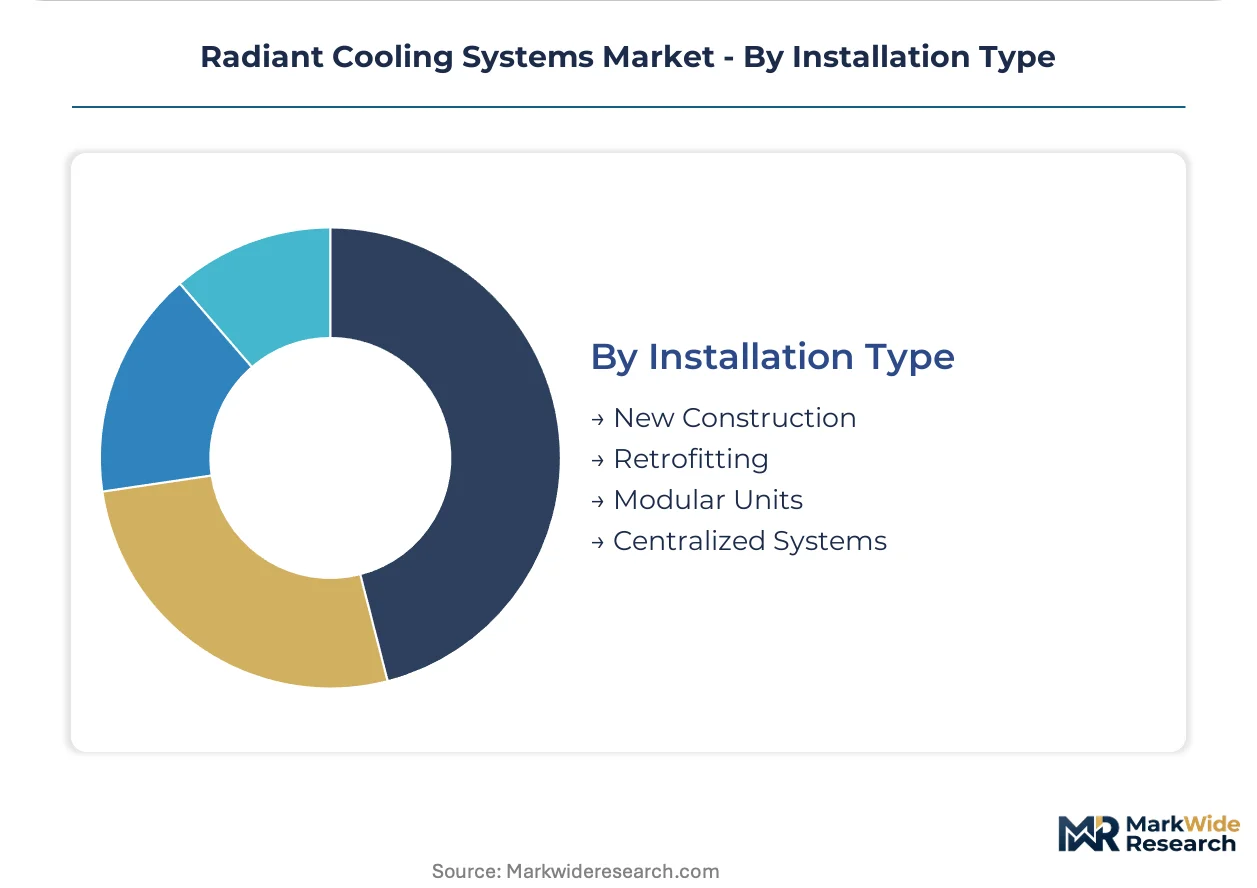
Installation Type:
Project delivery mode shapes supplier margin structure and customer acquisition costs, with prefabrication disrupting traditional on-site labor models.
- New Construction:Hydronic tubing embeds directly into concrete slabs during pouring, enabling optimal thermal mass integration. China's municipal infrastructure projects under dual carbon goals specify these for government buildings and transit hubs.
- Modular Units:Factory-assembled manifold stations and pre-insulated piping reduce on-site skilled labor hours. Netherlands-based contractors deploy these for ASHRAE Standard 55 compliance in commercial retrofits.
- Retrofitting:Surface-mounted electric panels or slim hydronic modules attach to existing ceilings; higher unit costs limit scale.
- Centralized Systems:District-scale chilled water plants serve multiple buildings; utility-managed infrastructure in Nordic urban districts.
New construction commands volume leadership today; modular units are expanding most quickly as labor scarcity bites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Passivhaus corridor commands specification density for hydronic ceiling panels, while Singapore's sovereign wealth funds consolidate procurement standards across commercial portfolios at roughly triple the per-square-meter investment intensity.
Germany
Commercial developers in Berlin and Frankfurt specify hydronic systems for net-zero retrofits under the EU Green Deal's building performance standards. The F-Gas Regulation accelerates refrigerant-phaseout timelines, redirecting capital toward water-based alternatives. The Passivhaus construction corridor concentrates manufacturing demand for cross-linked polyethylene piping networks.
China
Municipal infrastructure projects under dual carbon goals specify radiant cooling for transit hubs and government buildings. GB standards for building energy efficiency mandate disclosure thresholds that favor surface-embedded systems. The Yangtze River Delta megacity cluster anchors hospital construction programs prioritizing infection-control through reduced air circulation.
Singapore
Institutional landlords specify ceiling-embedded hydronic panels to meet portfolio-level carbon targets across commercial office towers. The Building and Construction Authority's Green Mark certification shapes equipment eligibility for public tenders. Marina Bay and Jurong Lake District developments mandate radiant systems for thermal uniformity in open-plan atriums.
United Arab Emirates
Dubai's free-zone developers integrate radiant cooling to attract multinational tenants with sustainability mandates. MOHAP efficiency guidelines for healthcare facilities encourage surface cooling to minimize airborne pathogen circulation. Jumeirah Lakes Towers and Dubai Design District concentrate specification activity for net-zero commercial towers.
United States
ASHRAE Standard 55 thermal comfort benchmarking redirects commercial retrofit specifications toward radiant alternatives. The EPA's Energy Star certification programs determine equipment eligibility for federal tax incentives. California's Title 24 building codes and New York City's Local Law 97 carbon caps concentrate adoption in high-performance commercial corridors.
Radiant Cooling Systems Market Competitive Landscape
German and Swiss producers anchor the premium hydronic tier; Danish and Finnish specialists hold the controls and pre-fabrication segments. The vendor base fragments across polymer extrusion, circulator manufacturing, and system integration layers, with no single participant commanding double-digit share. Three archetypes dominate: materials-science-led piping suppliers, automation-centric controls providers, and turnkey system integrators. Capacity expansion and strategic partnerships represent the dominant competitive vectors as firms address commissioning skill scarcity.
Within the materials-science tier, REHAU exemplifies polymer extrusion specialization, while Uponor Corporation occupies a position in pre-insulated piping systems. Danfoss Group anchors the controls layer among Danish industrial participants. These three entities represent distinct strategic postures: backward integration into raw polymer supply, modular assembly standardization, and building automation protocol convergence respectively.
| Leading Market Players |
|---|
| Jardine Engineering Corporation (JEC) |
| Giacomini Spa |
| Danfoss Group |
| Emerson Electric Co. |
| REHAU |
| Messana Inc. |
| Uponor Corporation |
| Zehnder Group |
| MrPEX Systems |
| Others |
Value Network & Pricing Analysis
Cross-linked polyethylene resin costs transmit from German petrochemical complexes through polymer extrusion tiers to hydronic piping networks, compressing margins at the standard-grade level while premium-certified systems retain pricing power through F-Gas Regulation compliance bundling.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for copper tubing and polymer piping components. Three-tier pricing structure across premium, standard, and economy levels separates Passivhaus-certified hydronic systems from basic commercial specifications. Pricing pressure stems from copper feedstock volatility and commissioning skill scarcity. Residential retrofit buyers exhibit highest price sensitivity; sovereign wealth fund commercial portfolios show lowest.
Supply Chain Analysis
Local-content rules in China's dual carbon infrastructure projects are reshaping sourcing toward domestic cross-linked polyethylene producers. Manufacturing concentrates in Germany, China, and Finland. Raw material flows draw from copper concentrate, polymer resin, and rare-earth magnet inputs. Single-source vulnerability runs through German precision circulator supply. Distribution feeds from factory-direct specification for large commercial projects and specialized HVAC distributor networks for retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in radiant cooling systems rests on prefabricated manifold standardization reducing on-site labor intensity and smart controls premiumization capturing performance-contracting value pools.
For Market Incumbents: Acquire predictive control algorithm capabilities to defend against magnetic-bearing chiller substitution in existing building retrofits. Backward integration into polymer compounding secures cross-linked polyethylene supply continuity. Channel control through certified contractor networks addresses commissioning skill scarcity threatening project timelines.
For New Entrants and Emerging Players: Begin with electric radiant panel surface-mount kits targeting Spain and Italy residential renovation channels where structural ceiling access is restricted. The penetrable white-space sits in mid-market healthcare facility retrofits requiring humidity-stable cooling without full hydronic infrastructure. Go-to-market through facility management performance-contracting partnerships absorbs operational risk for institutional landlords.
For Investors and Strategic Acquirers: Consolidation pressure builds where controls-layer specialization fragments across Danish automation specialists and German system integrators. Long-term viability favors participants with captive smart controls development and established specification relationships with sovereign wealth fund procurement desks. The signal to watch is municipal infrastructure tender volume under China's dual carbon goals as inflection indicator for hydronic system demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Prefabricated Manifold Standardization | Factory-assembled stations reduce German and Dutch contractor on-site labor hours by half. |
| Predictive Control Algorithm Development | Machine-learning zone automation captures Singapore sovereign wealth fund performance-contracting mandates. |
| Cross-linked Polymer Compounding Integration | Captive resin supply insulates REHAU and Uponor from petrochemical price volatility. |
| Certified Contractor Network Expansion | Addresses F-Gas Regulation compliance documentation requirements across EU Green Deal retrofits. |
| Healthcare Infection-Control Specification | Yangtze River Delta hospital construction prioritizes radiant cooling for reduced airborne pathogen circulation. |
Research Methodology
Bottom-up commercial real estate modeling reconciled against top-down hydronic equipment production tracking forms the analytical core of this study. Primary interviews with building automation system integrators, MEP contractors, sovereign wealth fund sustainability officers, polymer extrusion plant managers, and healthcare facility engineering directors combined with secondary validation from SEC filings of listed HVAC participants, EU F-Gas Regulation compliance databases, China's GB standard certification registries, and ASHRAE Standard 55 thermal comfort benchmarking studies. Triangulation across these sources ensures cross-verification of specification trends and procurement volume estimates.
Input-output matrices map technology penetration rates across installation type and control method segments throughout the projection horizon. Modeled dimensions span hydronic versus electric versus air-based architectures, new construction versus retrofit versus modular delivery modes, and smart versus integrated versus automatic control tiers. CAGRs derive from installed base growth rates, replacement cycle analysis, and regulatory compliance deadline clustering. Forecast inputs incorporate EU Green Deal building performance standard enforcement calendars and China's dual carbon municipal infrastructure commitment schedules.
Caveats apply where copper and polymer commodity price spikes, F-Gas Regulation phaseout timeline adjustments, or humidity-control technical limitations in tropical climates could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Global Secondary Refrigerants Market
Cooling Systems
North America Evaporative Cooling Market
Cooling Systems
Industrial Cooling System Market
Cooling Systems
Global Condensing Unit Market
Cooling Systems
Adaptive Cooling Fan Market
Cooling Systems
Thawing System Market
Cooling Systems
Aftercoolers Market
Cooling Systems
Solar Air Conditioning Market
Cooling Systems
Battery Cooling Plate Market
Cooling Systems
Cold Climate Air Source Heat Pump Market
Cooling Systems
Solar Cooling Market
Cooling Systems
Horizontal Air Flow Condensers Market
Cooling Systems
Microchannel Heat Exchanger Market
Cooling Systems
Global Evaporative Cooling Market
Cooling Systems
Global Energy Efficient HVAC Systems Market
Cooling Systems
Water Cooling Corona Discharge Ozone Generator Market