
 Circulating Fluid Bed Boilers Market | 2026-2036
Circulating Fluid Bed Boilers Market Size, Share, and Industry Trends Forecast 2026-2036
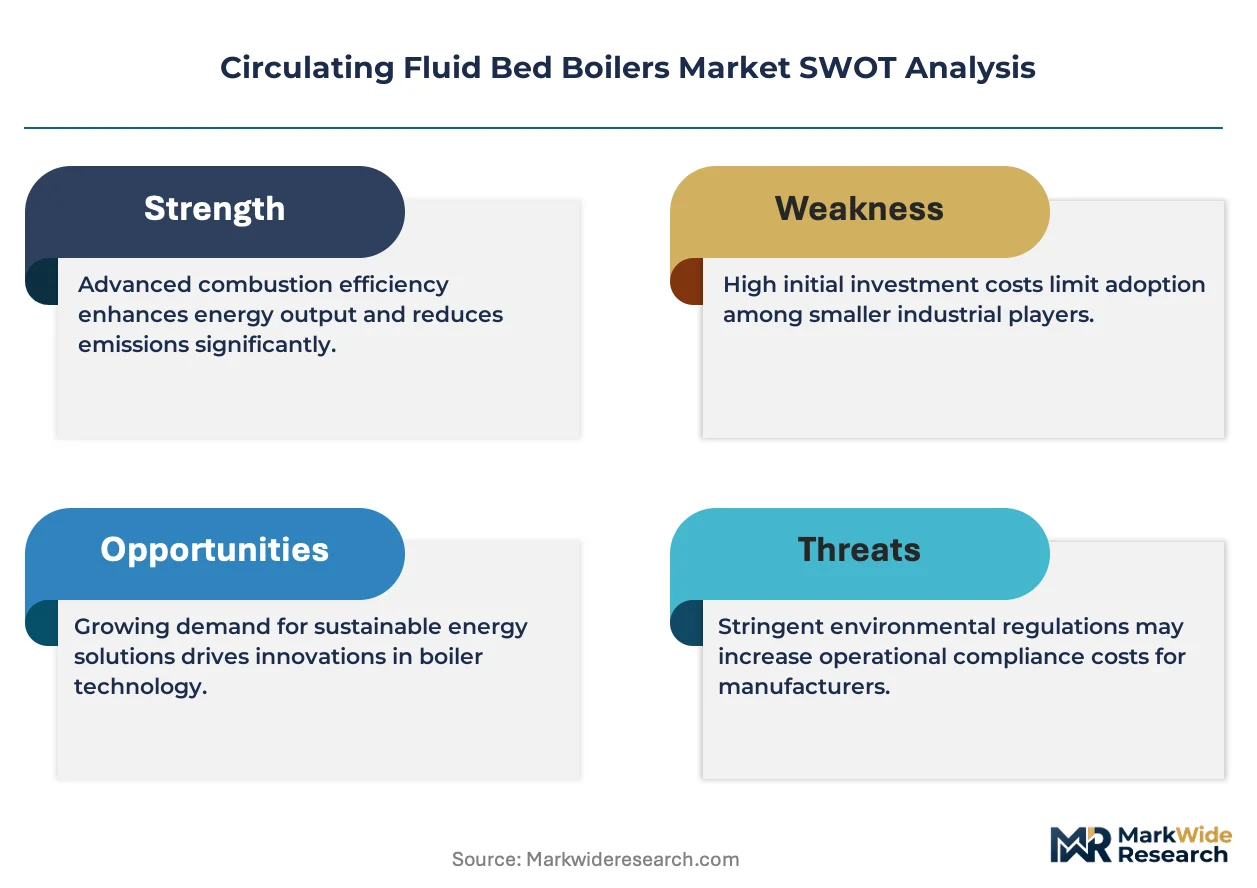
Circulating Fluid Bed Boilers Market Analysis
Multi-source procurement for critical components is repositioning how original equipment manufacturers manage fabrication risk and cost exposure. ANDRITZ leverages its Austrian engineering base to dominate high-efficiency biomass CFB systems across European retrofit projects. Thermax anchors its competitive stance through deep backward integration into boiler auxiliaries and emission control skids for Indian power utilities. Babcock & Wilcox sustains its technology leadership in supercritical CFB designs for North American independent power producers.
Circulating fluid bed boilers achieve combustion temperatures of 800–900°C through high-velocity gas streams that suspend and circulate fuel particles with limestone sorbents, enabling single-vessel sulfur capture and low-NOx operation without post-combustion scrubbers. Coal fired configurations still occupy the largest installed base, though biomass segments are registering the fastest capacity additions as utilities phase out unabated coal under carbon pricing mechanisms. Emission control technology represents the highest-margin attach category, with selective catalytic reduction and fabric filter retrofits commanding premium pricing on aging CFB fleets.
EPA Mercury and Air Toxics Standards enforce stringent particulate and heavy metal limits that compel US operators to upgrade legacy units or retire them. The EU Green Deal and associated Industrial Emissions Directive are accelerating CFB replacements across Polish and German lignite districts. China's MEE enforces ultra-low emission standards that push domestic boiler makers toward integrated gasification-combustion hybrids. Stakeholders must monitor how carbon border adjustment mechanisms reshape the cost calculus for imported CFB equipment versus localized manufacturing.
Market Dynamics
Retrofit mandates on aging coal fleets across India, China, and the United States are compressing procurement timelines and forcing boiler operators toward integrated emission control packages rather than standalone equipment purchases.
Growth Catalysts
- EPA Mercury and Air Toxics Standards:US power utilities face binding particulate and heavy metal limits that compel CFB upgrades or forced retirements, creating replacement demand for supercritical units with integrated sulfur capture.
- Biomass fuel flexibility:Carbon pricing mechanisms in the European Union and United Kingdom are accelerating coal-to-biomass conversions, with CFB designs uniquely accommodating variable feedstock calorific values without combustion instability.
- Ultra-low emission zones:China's MEE enforcement of emission ceilings below 50 mg per cubic meter for particulates is driving domestic utilities toward oxy-fuel CFB hybrids that achieve near-zero NOx without selective catalytic reduction.
Market Restraints
- Refractory material cost volatility:High-alumina castables and silicon carbide tiles essential for CFB combustor linings face supply concentration among Chinese producers, exposing project budgets to raw material price swings.
- Specialized welding labor scarcity:Thick-wall pressure vessel fabrication for supercritical CFB drums requires ASME-certified welders, with training pipelines failing to match North American and European project backlogs.
- Competing gas turbine economics:Combined-cycle natural gas plants achieve faster permitting and lower capital intensity in markets with pipeline infrastructure, diverting utility capex from solid-fuel boilers.
Strategic Opportunities
- Waste-to-energy applications:Municipal solid waste incineration regulations in Japan and South Korea are opening CFB deployments for refuse-derived fuel, with lower corrosion rates than grate-fired alternatives.
- Carbon capture readiness:EU Innovation Fund and US Department of Energy demonstration grants are subsidizing CFB retrofits with amine scrubber tie-ins, positioning the technology for post-combustion CCS integration.
- Industrial steam decentralization:Chemical and pulp processing clusters in Brazil and Indonesia are shifting from centralized grid steam to captive CFB cogeneration, escaping transmission tariff escalations.
Industry Challenges
- Control systems integration complexity:Legacy distributed control systems from the 1990s lack cybersecurity hardening and digital twin compatibility, forcing costly rip-and-replace during CFB automation upgrades.
- Extended commissioning timelines:Cold flow modeling, refractory curing, and load bank testing for large CFB units routinely exceed 18 months, straining project finance covenants and contractor liquidity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Circulating Fluid Bed Boilers Market |
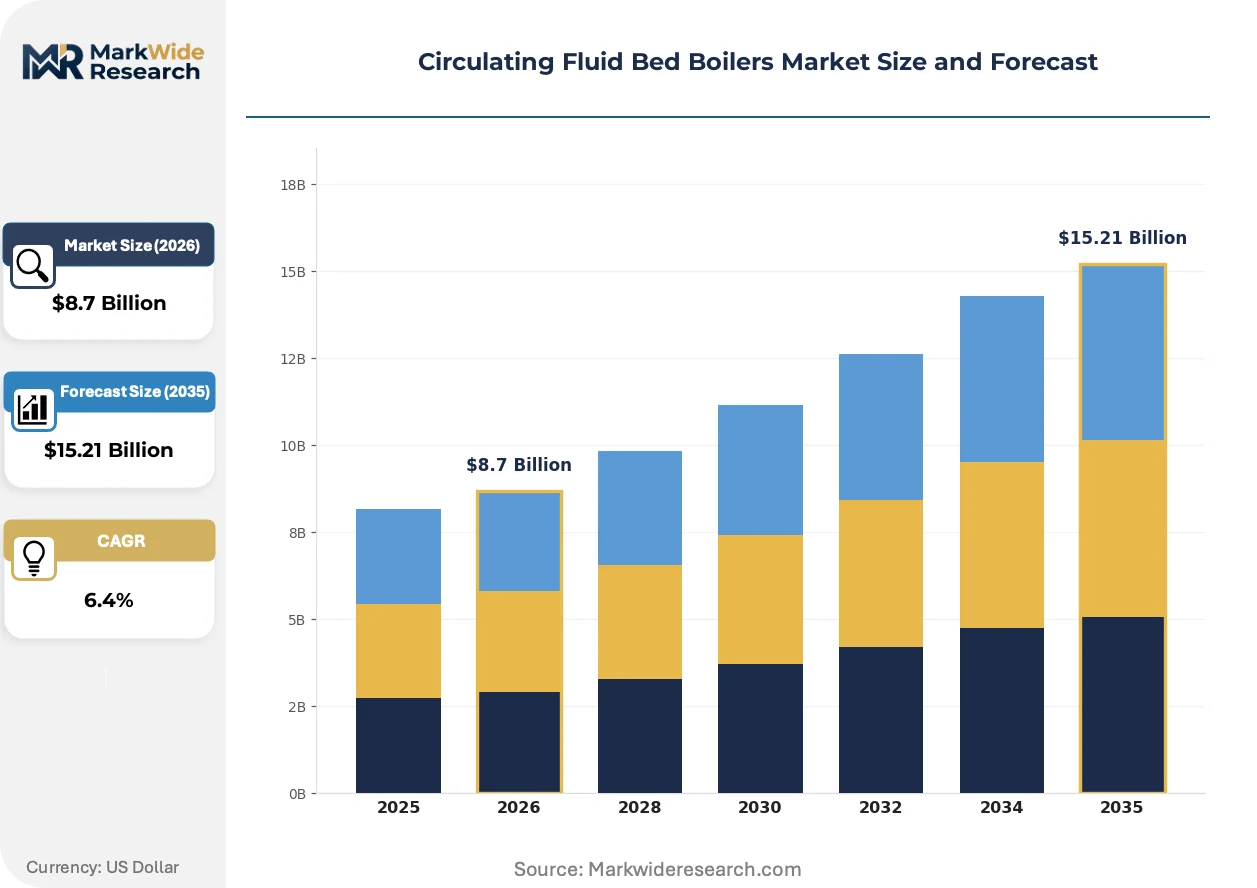
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coal Fired, Oil Fired, Gas Fired, Biomass End User: Power Generation, Cement Industry, Chemical Processing, Pulp & Paper Installation Type: Onshore, Offshore, Industrial, Commercial Technology: Gasification, Combustion, Heat Recovery, Emission Control |
| Companies Covered | ANDRITZ, Thermax, Mitsubishi Heavy Industries Ltd, Industrial Boilers America Inc., General Electric, Babcock & Wilcox, Valmet, Alstom Power Inc., Sumitomo Heavy Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Circulating Fluid Bed Boilers Market Emerging Trajectories
Artificial intelligence-based combustion optimization and modular fabrication methods are compressing project delivery schedules while expanding CFB applicability beyond traditional utility scale into industrial distributed generation.
Oxy-fuel combustion retrofit kits are decentralizing carbon capture economics for existing CFB assets. Cement and steel producers with process CO2 streams are piloting these systems to generate pipeline-ready carbon dioxide without amine separation. The technology is compressing the cost gap between post-combustion capture and pre-combustion gasification alternatives.
The EU F-Gas Regulation phase-down of hydrofluorocarbon refrigerants is indirectly tightening thermal efficiency standards for power plant auxiliary cooling systems. CFB operators in Germany and Poland are responding by specifying air-cooled condensers and dry cooling towers, adding 8-12 percent to project capital cost but eliminating regulatory exposure.
Asset performance guarantees are displacing traditional equipment-only procurement in Indian and Chinese utility tenders. State-owned power developers now require energy availability contracts and fuel-flexibility warranties, transferring operational risk to OEMs and compressing margins for vendors unable to demonstrate fleet-wide reliability data.
Circulating Fluid Bed Boilers Market Segmentation
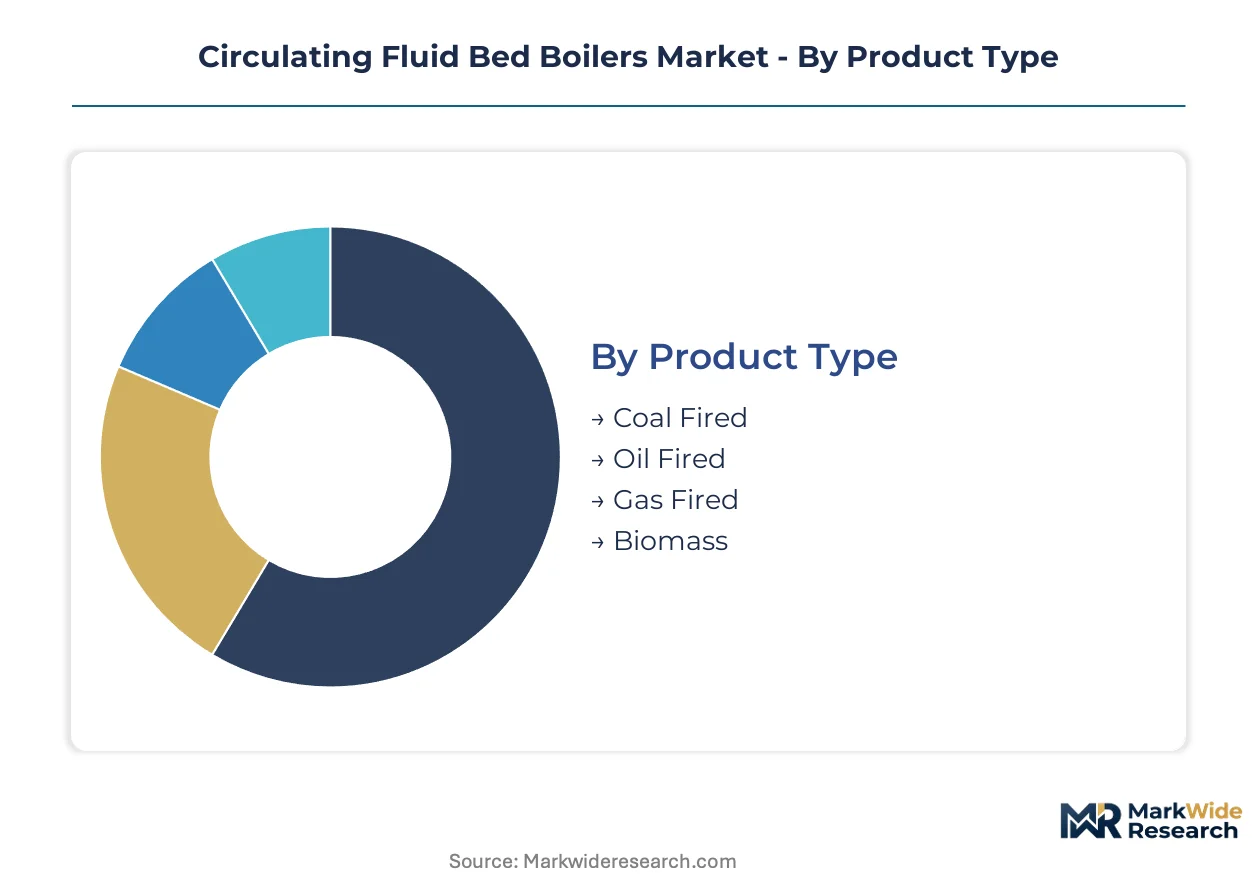
Product configuration choices in circulating fluid bed boilers determine fuel flexibility boundaries, emission control integration depth, and project lifecycle economics. Segmentation reveals where technology specialization commands premium positioning versus where modular standardization drives procurement efficiency.
Product Type:
Standardized combustion cores accommodate multiple fuel inputs through configurable feed systems, while specialized designs optimize for single-fuel performance at higher thermal efficiency.
- Coal Fired:High-ash bituminous and sub-bituminous coals dominate feedstock specifications, with limestone injection systems integrated for in-bed sulfur capture. Indian and Chinese utilities retrofit aging pulverized coal units with CFB architectures to meet MEE and CEA emission mandates without external scrubbers.
- Biomass:Agricultural residues, wood pellets, and energy crops with moisture content ranging 10-50% require enlarged fuel handling systems and modified bed material chemistry. United Kingdom and Danish power producers convert former coal sites to biomass CFB under carbon pricing mechanisms, with fuel flexibility warranties becoming standard tender requirements.
- Oil Fired:Heavy fuel oil and refinery residue applications concentrate in Middle Eastern industrial zones where liquid fuel infrastructure predates gas grid expansion.
- Gas Fired:Natural gas and syngas configurations serve chemical processing clusters requiring process steam with rapid load modulation capabilities.
Leading the category by volume: Coal Fired. Growing fastest: Biomass.
End User:
Volume concentration follows industrial electrification intensity, with process heat requirements determining boiler scale and steam parameter specifications.
- Power Generation:Utilities deploy utility-scale supercritical CFB units rated 300-600 MW for baseload and mid-merit operation. Independent power producers in Poland and Germany replace lignite-fired subcritical units ahead of EU Industrial Emissions Directive deadlines.
- Chemical Processing:Ammonia, methanol, and ethylene crackers require high-pressure steam at 100-150 bar with guaranteed availability above 95%. Captive cogeneration installations in Louisiana and Texas Gulf Coast clusters escape transmission congestion charges through on-site CFB deployment.
- Cement Industry:Preheater exhaust heat integration drives waste heat recovery CFB configurations for clinker production facilities.
- Pulp & Paper:Black liquor recovery boilers and bark-fired CFB systems close chemical loops in integrated mills across Sweden and Finland.
Dominant by installed megawatts: Power Generation. Expanding most quickly: Chemical Processing.
Installation Type:
Site constraints and grid interconnection economics determine whether projects proceed as greenfield developments or brownfield retrofits.
- Industrial:Captive power and steam installations within manufacturing fences prioritize compact footprints and quick-start capability. Brazilian sugar-ethanol mills and Indonesian palm oil processors adopt medium-pressure CFB cogeneration to displace diesel gensets and grid imports.
- Commercial:District heating networks in Nordic cities specify biomass CFB with flue gas condensation for seasonal efficiency peaks above 100% on lower heating value basis.
- Onshore:Greenfield utility projects concentrate in coal-dependent regions with available cooling water and transmission access.
- Offshore:Platform-based CFB systems serve remote oil production facilities requiring process heat and power isolation from mainland grids.
Highest project count: Industrial. Steepest expansion trajectory: Commercial.
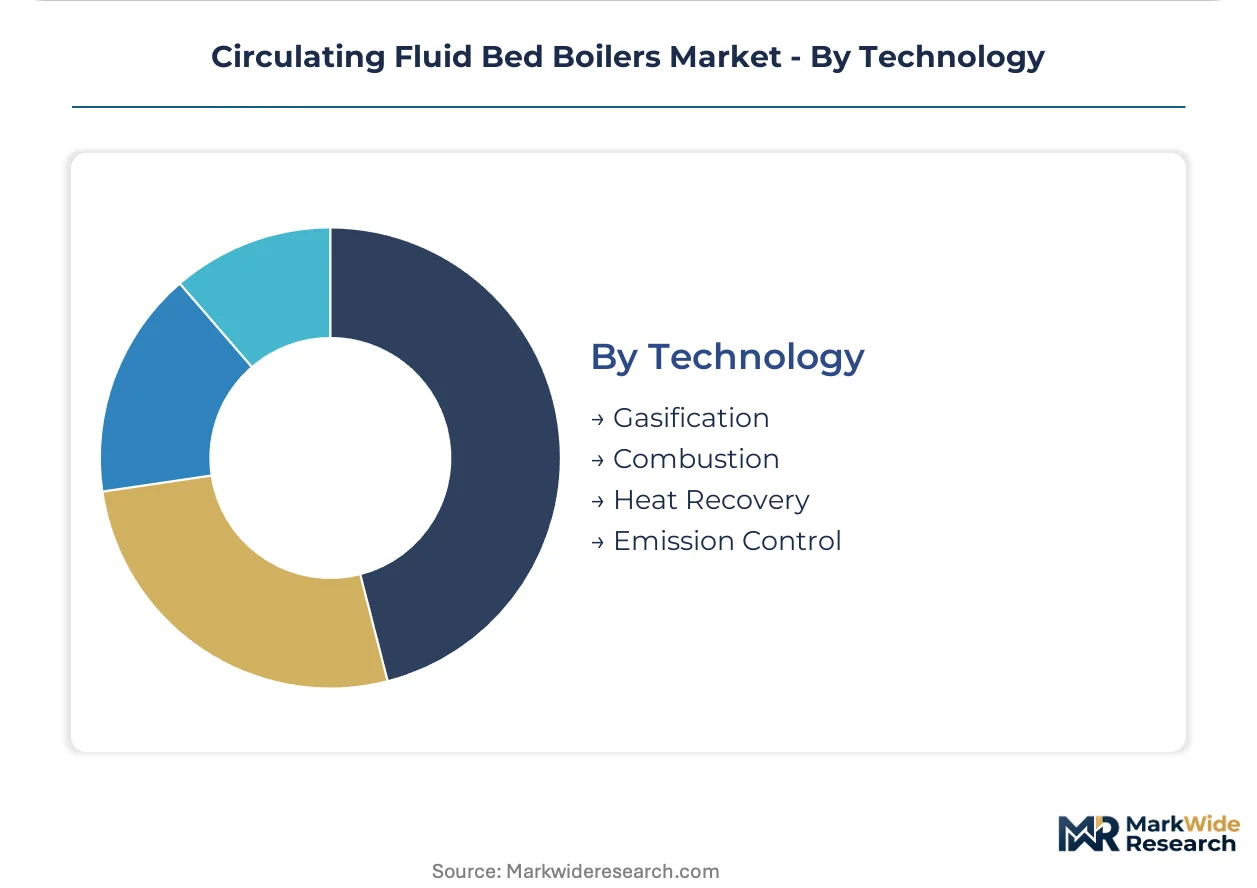
Technology:
Process integration depth separates basic combustion packages from advanced systems with embedded emission control and energy recovery.
- Combustion:Core CFB technology with staged air injection achieves 800-900°C bed temperatures for low-NOx formation without post-combustion reduction. Standard configurations dominate developing market procurement where capital constraints limit technology stacking.
- Emission Control:Selective catalytic reduction, fabric filters, and activated carbon injection retrofits command premium pricing on aging CFB fleets. EPA enforcement of Mercury and Air Toxics Standards compels US operators to upgrade legacy units with integrated multi-pollutant control trains.
- Gasification:Dual fluid bed configurations produce syngas for chemical synthesis while capturing CO2 in concentrated streams for sequestration.
- Heat Recovery:Economizers, air preheaters, and feedwater heaters extract residual energy from flue gas streams to boost cycle efficiency.
Widest deployment base: Combustion. Gaining share fastest: Emission Control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-ash coal deposits in eastern India and lignite belts across Poland and Germany anchor regional CFB deployment patterns. Limestone sorbent availability and cooling water access shape project economics in each market. Regulatory enforcement timelines compress procurement windows differently across jurisdictions.
United States
Independent power producers in Texas and the PJM interconnection retrofit aging coal units ahead of EPA Mercury and Air Toxics Standards deadlines. FERC interconnection queue reforms accelerate project timelines for supercritical CFB replacements. The Ohio River Valley and Powder River Basin host concentrated brownfield activity as utilities phase out subcritical pulverized coal.
China
Provincial grid companies in Shandong and Shanxi provinces deploy ultra-low emission CFB systems under MEE enforcement below 50 mg per cubic meter particulate limits. The Yangtze River Delta industrial corridor drives captive cogeneration installations for chemical processing clusters. Domestic boiler makers integrate gasification-combustion hybrids to meet dual carbon goals.
India
NTPC and state gencos in Maharashtra and Gujarat retrofit 210 MW and 500 MW subcritical units under CEA emission mandates. High-ash domestic coal specifications favor CFB sulfur capture over external flue gas desulfurization. The Singrauli and Korba super thermal power stations anchor replacement demand for supercritical configurations.
Germany
RWE and LEAG accelerate lignite-fired CFB replacements in the Lusatian and Rhineland mining districts ahead of EU Industrial Emissions Directive deadlines. The EU Green Deal carbon pricing mechanism renders unabated coal uneconomic by 2030. Hamburg and Berlin district heating networks specify biomass CFB with flue gas condensation.
Poland
PGE and Tauron deploy CFB systems for Bełchatów and Turów lignite complexes under EU F-Gas Regulation phase-down pressures. The Silesian coal basin drives hard coal CFB retrofits with integrated selective catalytic reduction. Katowice and Łódź municipal utilities specify biomass conversions for district heating decarbonization.
Circulating Fluid Bed Boilers Market Vendor Landscape
Global majors compete with regional champions across engineering depth and fabrication proximity. The vendor base stratifies between full-scope OEMs with captive boiler auxiliary production and specialized fabricators focused on pressure vessel supply. Three archetypes dominate: European-Austrian engineering houses with biomass specialization, Indian integrated boiler-emission control providers, and North American supercritical technology licensors. Competitive intensity centers on M&A for refractory and control system capabilities, plus geographic expansion through local fabrication joint ventures.
Among European-Austrian engineering specialists, ANDRITZ exemplifies the high-efficiency biomass retrofit archetype across Central European utility tenders. Thermax represents the backward-integrated Indian model with captive emission control skid production for domestic power gencos. Babcock & Wilcox anchors North American positioning in supercritical CFB technology licensing for independent power producers. These three occupy distinct competitive spaces without direct overlap in core offerings.
| Leading Market Players |
|---|
| ANDRITZ |
| Thermax |
| Mitsubishi Heavy Industries Ltd |
| Industrial Boilers America Inc. |
| General Electric |
| Babcock & Wilcox |
| Valmet |
| Alstom Power Inc. |
| Sumitomo Heavy Industries Ltd |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed boiler fabricators in China and family-owned refractory specialists in Austria anchor supply-side ownership patterns that compress margin flexibility for project developers. Asset performance guarantees now bundled into Indian and Chinese utility tenders transfer operational risk downstream, forcing OEMs to price warranties into long-term service contracts rather than equipment-only transactions.
Pricing Analysis
Warranty bundling separates premium OEMs from commodity fabricators, with energy availability contracts and fuel-flexibility warranties commanding substantial premiums in state-owned utility tenders. Price differentiation hinges on ASME certification tier and integrated emission control depth, with supercritical designs certified for ultra-low emission zones pricing above subcritical alternatives. Cost compression in standard combustion packages is intensifying as Chinese domestic makers expand export capacity. Independent power producers in North America exhibit highest price sensitivity due to merchant power exposure, while European district heating utilities prioritize efficiency guarantees over capital cost.
Supply Chain Analysis
ASME Section I and ISO 9001 certification gating restricts pressure vessel fabrication to qualified shops, concentrating high-specification supply among certified facilities in the United States, Germany, and Japan. Raw material dependencies center on high-alumina refractory castables, silicon carbide tiles, and thick-wall alloy steel plate. Single-source vulnerability in Chinese refractory supply exposes project budgets to export restriction risk. Distribution runs through EPC contractors and direct OEM relationships with utility procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Mercury and Air Toxics Standards enforcement and EU Industrial Emissions Directive deadlines are accelerating replacement cycles, squeezing subscale fabricators unable to warranty integrated emission performance.
For Market Incumbents: Anticipate margin compression from Chinese OEMs expanding into Southeast Asian and African markets by deepening captive production of selective catalytic reduction skids and fabric filter systems. Secure ASME-certified welding capacity through apprenticeship pipelines in Texas and Louisiana to address labor scarcity threatening project delivery timelines. For New Entrants and Emerging Players: Begin with refuse-derived fuel CFB configurations for Japanese and South Korean municipal waste incineration markets, where corrosion-resistant designs command premium positioning against grate-fired alternatives. Target Brazilian sugar-ethanol and Indonesian palm oil processing clusters for captive cogeneration deployments escaping grid transmission tariffs. For Investors and Strategic Acquirers: FERC interconnection queue reform acceleration is the leading indicator that North American brownfield retrofit activity is entering a sustained expansion phase. Position for 5-10 year horizon consolidation by targeting mid-cap specialists with demonstrated oxy-fuel combustion pilot experience and established relationships with chemical processing off-takers seeking carbon capture readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Emission Control Skids | Captive SCR and fabric filter production protects margin from external supplier price volatility. |
| Oxy-Fuel Combustion Retrofit Development | Positions existing CFB assets for post-combustion carbon capture without amine separation systems. |
| ASME-Certified Welding Pipeline Investment | Addresses specialized labor scarcity constraining North American supercritical project execution. |
| Biomass Fuel Flexibility Certification | Unlocks UK and Danish coal-to-biomass conversion tenders under carbon pricing mechanisms. |
| Digital Twin and Cybersecurity Hardening | Replaces legacy DCS systems from the 1990s during automation upgrade cycles. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with utility planning officers, EPC project developers, OEM procurement teams, and aftermarket service heads. EPA enforcement timelines, MEE ultra-low emission standards, and EU F-Gas Regulation phase-down schedules provided policy calibration points. Bottom-up unit deployment tracking across India, China, and the United States triangulated against top-down market sizing from boiler manufacturer capacity disclosures.
Segment-level modeling addressed fuel source, generation capacity tier, technology integration depth, and regional regulatory framework across the projection horizon. CAGRs derived from fitted growth curves incorporating retrofit mandate enforcement schedules and carbon pricing mechanism expansion. Forecast inputs included limestone sorbent cost trajectories, ASME-certified welder supply elasticity, and interconnection queue reform implementation pace.
Refractory material cost volatility, specialized welding labor scarcity, and competing gas turbine economics are the dominant revision risks to deployment assumptions. A model refresh is warranted upon material change in EPA enforcement intensity or EU carbon border adjustment mechanism implementation scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Utility Boiler Market
Boilers
Fuel Operated Heaters Market
Boilers
North America Commercial Boiler Market
Boilers
Watertube Boilers Market
Boilers
Europe Power Plant Boiler Market
Boilers
Commercial Boiler Market
Boilers
Advanced Utility Boilers Market
Boilers
Global Domestic Boilers Market
Boilers
GCC Electric Water Heater Market
Boilers
Brazil Combined Heat and Power Market
Boilers
US Commercial Boiler Market
Boilers
US Boiler Market
Boilers
Fire Tube Industrial Boiler Market
Boilers
Space Heating Boilers Market
Boilers
Boiler Control Market
Boilers
North America Residential Boiler Market