

Renewable Energy Consulting Service Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Energy Consulting Service Market Insights
European engineering consultancies is decoupling from pure advisory models by building in-house technical certification labs. Deloitte leverages its climate risk analytics platform to anchor long-term contracts with offshore wind developers. McKinsey & Company differentiates through proprietary LCOE benchmarking tools that shape capital allocation decisions for institutional investors. Accenture competes by embedding digital twin capabilities into grid integration planning for utility clients.
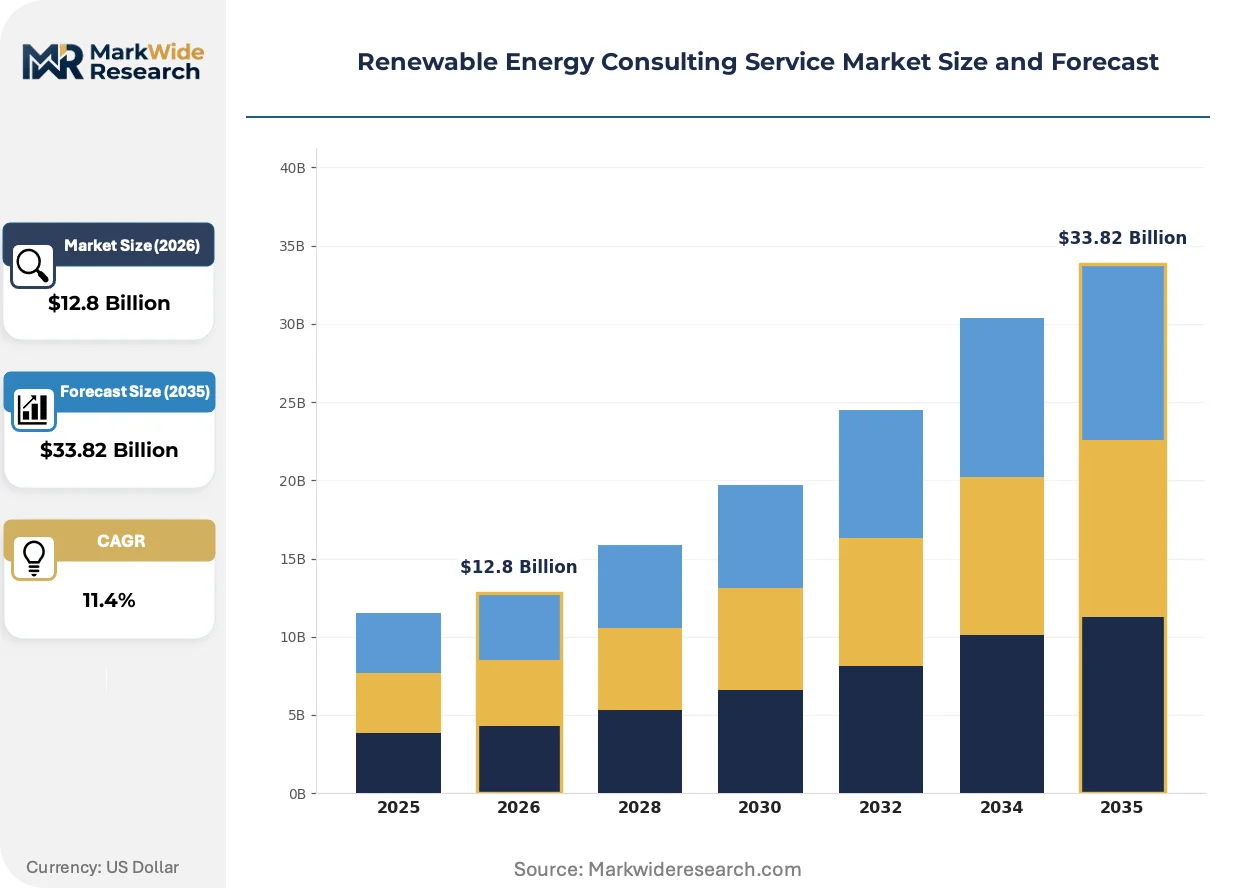
Renewable energy consulting services encompass technical, regulatory, and financial advisory functions that optimize the development, financing, and operation of clean energy assets, typically delivered through multi-disciplinary teams combining engineering, policy, and capital markets expertise. The primary purpose is to reduce project risk, accelerate permitting timelines, and improve returns on renewable infrastructure investments across solar, wind, storage, and emerging technologies. Project feasibility and regulatory compliance segments command premium pricing due to their direct impact on financial close and offtake security. Technology advisory around energy storage solutions and grid interconnection represents the fastest-expanding margin pool as hybrid project structures proliferate.
The EU Green Deal and REACH frameworks mandate stricter lifecycle carbon accounting for renewable project finance, while India's CEA and BIS enforce evolving grid code standards that consultants must navigate for market access. Germany's KBA and the country's federal network regulator shape permitting timelines that directly determine advisory engagement duration and cost structures. Stakeholders should monitor how carbon border adjustment mechanisms and domestic content requirements in key markets redefine the regulatory compliance burden for cross-border renewable investments.
Market Dynamics
Hybrid renewable project structures are compressing traditional advisory boundaries as developers demand unified technical-financial-regulatory guidance rather than siloed specialist inputs. This convergence pressure is elevating consultants who can certify grid interconnection, structure project finance, and navigate carbon accounting within single engagement frameworks.
Growth Catalysts
- EU Green Deal lifecycle mandates:Stricter carbon accounting requirements for project finance are extending advisory engagement duration and expanding scope into supply chain due diligence.
- Utility-scale solar deployment in India:Central Electricity Authority grid code revisions are forcing foreign developers to retain local regulatory specialists for market access.
- Energy storage integration:Battery-hybrid project proliferation is creating specialized demand for consultants who can model stacked revenue streams and interconnection queuing strategies.
Market Restraints
- Specialized talent scarcity:Deep expertise spanning power systems engineering, structured finance, and environmental permitting concentrates among senior practitioners at top-tier firms.
- Permitting timeline volatility:Germany's Federal Network Agency and KBA processes create unpredictable advisory cost structures that strain fixed-fee contract viability.
- Input cost inflation:Specialized technical certification lab equipment and software licensing for grid modeling tools are elevating consultant overhead bases.
Strategic Opportunities
- Brazil distributed generation acceleration:ANEEL regulatory reforms for prosumer solar are opening advisory markets previously dominated by utility-scale incumbents.
- Digital twin convergence:Integration of real-time asset performance data with predictive maintenance algorithms is enabling new recurring revenue advisory models.
- Carbon border adjustment preparation:EU CBAM implementation timelines are creating compliance advisory demand for exporters in India and Brazil targeting European offtake.
Industry Challenges
- Cross-functional talent acquisition:Firms struggle to recruit professionals combining power engineering credentials with capital markets structuring experience.
- Certification timeline compression:Accelerated project finance close deadlines are squeezing the window for completing technical due diligence and grid impact studies.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Energy Consulting Service Market Trends and Innovations
Advisory delivery models are fragmenting as specialized boutiques capture niche technical certification work while integrated platforms consolidate multi-jurisdiction regulatory strategy. This bifurcation is reshaping hiring patterns and technology investment priorities across the competitive landscape.
Artificial intelligence-powered permitting document analysis is integrating natural language processing trained on historical approval decisions to predict regulatory pathway outcomes. Major developers in Germany and India are adopting these tools to compress pre-application timelines. The technology is integrating probabilistic risk scoring into early-stage site selection, reducing abortive engineering expenditure.
EU CSRD disclosure requirements are mandating granular Scope 3 emissions reporting for renewable asset portfolios. Project sponsors must now document construction-phase embodied carbon and component supply chain provenance. Offshore wind developers in the North Sea basin are most affected, with several consortia establishing dedicated sustainability verification functions.
Buyers are unbundling advisory services from EPC and O&M contracts to retain independent technical representation. Institutional investors in utility-scale Indian solar are driving this shift, seeking separate engineering due diligence from construction management. Brazil's distributed generation segment exhibits similar patterns as commercial and industrial offtakers demand owner-engineer roles distinct from installer relationships.
Renewable Energy Consulting Service Market Segmentation
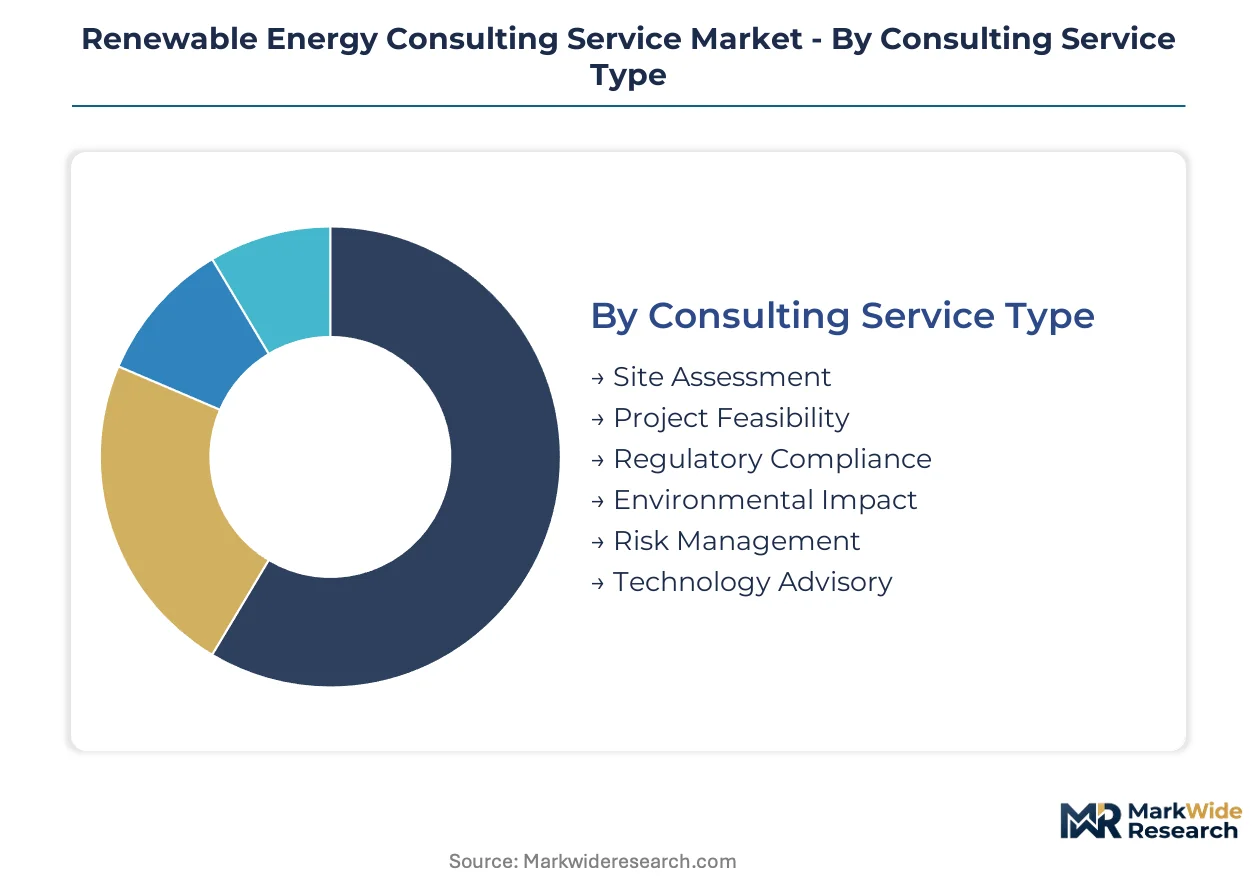
Advisory scope and delivery models in renewable energy consulting vary sharply by project phase, client sophistication, and technology maturity. Segmentation reveals where premium pricing concentrates and which service bundles capture recurring revenue.
Consulting Service Type:
Customization intensity spans from standardized site screening to bespoke regulatory navigation, with pricing power correlating to project risk exposure.
- Project Feasibility:Comprehensive technical-economic modeling determines resource assessment accuracy, technology selection, and financial return projections. Power generation firms in Germany commission these studies to satisfy KBA permitting prerequisites and secure offtake agreements. Demand concentrates where grid interconnection queues are longest.
- Regulatory Compliance:Multi-jurisdiction permit application management, environmental licensing, and grid code adherence documentation. India's CEA mandates foreign developers retain local specialists to navigate evolving standards. Engagement duration extends as EU Green Deal lifecycle requirements tighten.
- Site Assessment:Meteorological data collection, geotechnical surveys, and grid proximity evaluation for greenfield development.
- Environmental Impact:Biodiversity baseline studies, noise modeling, and cumulative effects analysis for permitting authorities.
- Risk Management:Insurance placement support, political risk assessment, and construction-phase contingency planning.
- Technology Advisory:Equipment specification, vendor qualification, and emerging technology due diligence.
Leading the category by volume: Project Feasibility. Expanding most quickly: Regulatory Compliance.
End User Industry:
Procurement sophistication ranges from transactional project-based buying to embedded strategic advisory relationships.
- Power Generation Firms:Integrated utilities and IPPs seeking unified technical-financial-regulatory guidance across solar, wind, and storage portfolios. These buyers compress traditional advisory boundaries by demanding single-engagement frameworks covering certification, finance structuring, and carbon accounting.
- Independent Producers:Non-utility developers requiring capital-raising support, offtake negotiation, and independent engineering for project finance. Brazil's ANEEL distributed generation reforms are opening this segment to new entrants previously locked out of utility-scale markets.
- Energy Traders:Merchant power and renewable certificate market participants.
- Government Agencies:Policy design, auction mechanism development, and grid planning mandates.
- Research Institutions:Demonstration project commercialization and technology transfer advisory.
- Public Utilities:Grid modernization planning and distributed resource integration.
Dominant by contract value: Power Generation Firms. Fastest client acquisition: Independent Producers.
Technology Focus:
Advisory complexity escalates with system integration challenges and revenue stack multiplicity.
- Energy Storage Solutions:Battery-hybrid project structuring, stacked revenue stream modeling, and interconnection queuing strategy. Consultants must navigate frequency regulation, capacity markets, and energy arbitrage value capture simultaneously. India's grid code revisions for storage mandate specialized technical certification.
- Solar Photovoltaic:Utility-scale and distributed generation project development, module technology selection, and performance guarantee structuring. Germany's KBA permitting timelines directly determine advisory engagement cost structures for large ground-mount installations.
- Wind Turbine:Onshore and offshore resource assessment, wake modeling, and foundation design review.
- Biomass Energy:Feedstock supply chain verification and emissions accounting for EU Green Deal compliance.
- Geothermal Systems:Exploration risk assessment and reservoir engineering support.
- Hydroelectric Power:Run-of-river and pumped storage licensing and environmental mitigation planning.
Highest advisory margins: Energy Storage Solutions. Steepest expansion trajectory: Solar Photovoltaic.
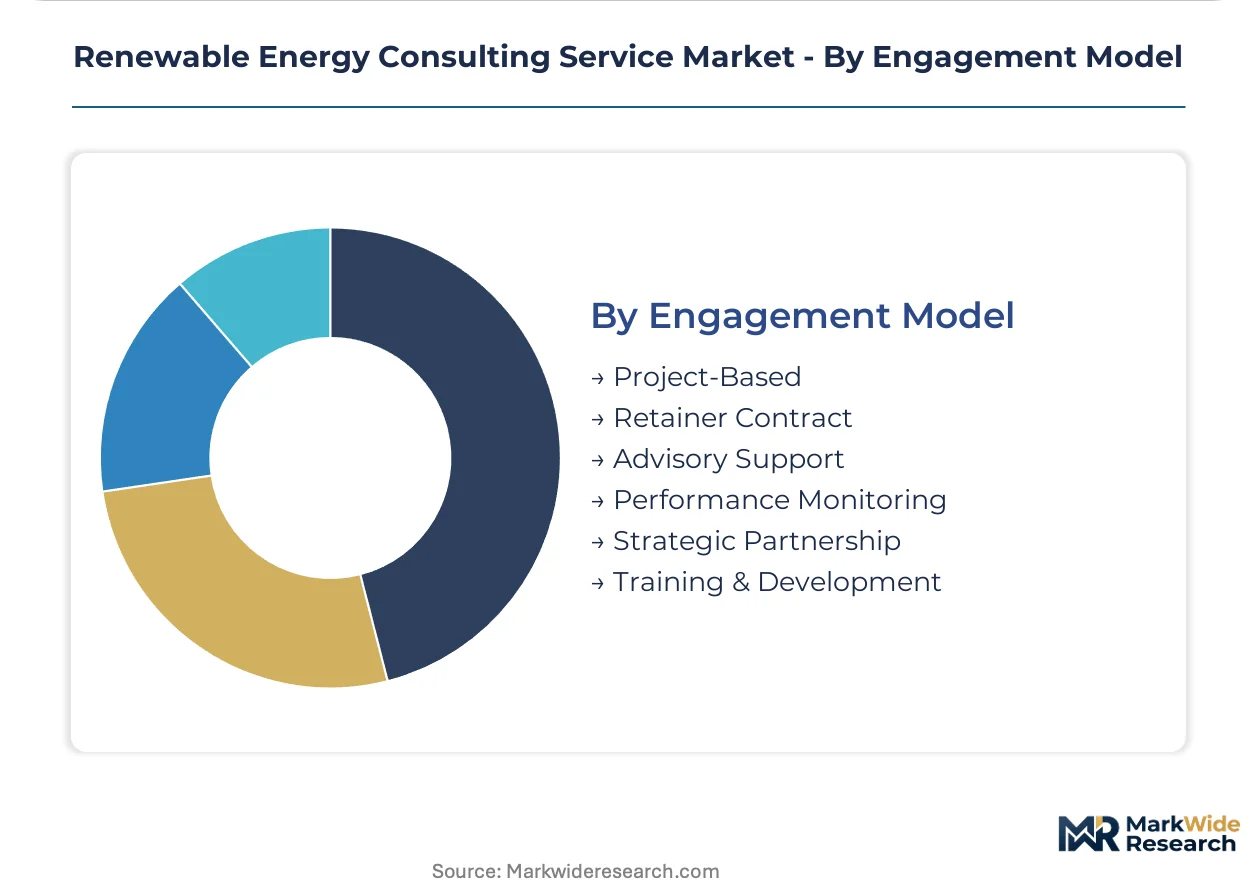
Engagement Model:
Revenue predictability increases as advisory relationships shift from transactional to embedded.
- Project-Based:Discrete scope delivery tied to specific development milestones such as feasibility completion, permitting submission, or financial close. Fixed-fee structures dominate, though permitting timeline volatility in Germany strains contract viability.
- Retainer Contract:Ongoing advisory access with monthly or annual fee structures covering regulatory monitoring, technical hotline support, and priority staffing. Accenture's digital twin capabilities for utility clients exemplify this recurring revenue model.
- Advisory Support:On-call expertise for discrete decisions without continuous engagement.
- Performance Monitoring:Asset-level data analytics and operational optimization recommendations.
- Strategic Partnership:Multi-year alliances covering pipeline development and capability building.
- Training & Development:Knowledge transfer programs and certification course delivery.
Most common structure: Project-Based. Gaining share fastest: Retainer Contract.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wind resource corridors in northern Germany anchor European advisory demand, while solar irradiance zones in western India and Brazil's northeastern highlands concentrate project development activity. These geographies shape where technical certification labs cluster and regulatory specialists concentrate.
Germany
Offshore wind deployment in the North Sea basin drives demand for integrated technical-financial advisory services. The Federal Network Agency and KBA permitting processes create extended engagement timelines that favor retainer-based consulting relationships. Hamburg hosts specialized engineering consultancies building in-house certification capabilities for grid interconnection studies.
India
Utility-scale solar parks in Rajasthan and Gujarat require local regulatory specialists to navigate CEA grid code revisions for foreign developers. The Central Electricity Authority mandates technical certification that extends advisory scope into construction-phase oversight. Hyderabad and Bengaluru clusters concentrate engineering talent for hybrid storage-solar project structuring.
Brazil
ANEEL reforms for distributed generation prosumer solar open advisory markets beyond utility-scale incumbents. The northeastern states of Pernambuco and Ceará attract commercial and industrial offtakers seeking independent owner-engineer representation. São Paulo hosts financial structuring specialists serving capital-raising mandates for independent producers.
United States
IRA production tax credit extensions accelerate utility-scale wind and solar development across Texas and the Great Plains. FERC interconnection queue reforms create demand for consultants modeling transmission upgrade cost allocation. Denver and Austin clusters concentrate technical teams specializing in energy storage integration and stacked revenue stream optimization.
United Kingdom
Offshore wind auction rounds in the Celtic Sea and North Sea drive demand for lifecycle carbon accounting advisory. The Environment Agency and Marine Management Organisation shape permitting timelines that determine engagement cost structures. London anchors project finance structuring capabilities serving institutional investors in utility-scale renewable portfolios.
Renewable Energy Consulting Service Market Competitive Landscape
Global majors compete with regional champions across technical certification depth and regulatory jurisdiction coverage. The market structures around three tiers: integrated professional services networks, specialized energy boutiques, and engineering consultancies building in-house labs. Strategic moves concentrate on M&A for technical talent acquisition and partnerships for digital twin capability integration.
Within the integrated advisory tier, Deloitte, Accenture, and McKinsey & Company exemplify divergent specialization vectors. Deloitte represents the climate risk analytics anchor position for long-term offshore wind contracts. Accenture occupies the digital twin integration position for utility grid modernization advisory. McKinsey & Company sits within the capital markets structuring archetype, serving institutional investor LCOE benchmarking mandates.
| Leading Market Players |
|---|
| McKinsey & Company |
| Boston Consulting Group |
| Bain & Company |
| Deloitte |
| PwC |
| Ernst & Young |
| KPMG |
| Accenture |
| Guidehouse |
| Others |
Pricing and Supply Chain Analysis
Power generation firms unbundling advisory services from EPC contracts forces consultants to absorb technical certification lab overhead while competing on standalone engineering due diligence fees. This procurement shift compresses margins on traditional project-based scopes while elevating retainer pricing for embedded grid integration advisory.
Pricing Analysis
Service bundling separates warranty-backed technical certification from pure advisory hours, with premium tiers anchoring on in-house lab capabilities and economy tiers competing on standardized site screening speed. Price differentiation rests on certification grade for grid interconnection studies and geographic delivery cost for multi-jurisdiction regulatory navigation. Cost compression in feasibility studies is intensifying because AI-powered permitting tools commoditize early-stage document analysis. Independent producers in Brazil exhibit highest price sensitivity, while offshore wind developers in Germany accept premium positioning for lifecycle carbon accounting integration.
Supply Chain Analysis
Dual-sourcing requirements for specialized engineering talent mandate that advisory firms qualify multiple power systems experts and capital markets specialists for each engagement geography. Supply concentrates in Germany, India, and Brazil as regulatory specialists cluster around Hamburg, Hyderabad, and São Paulo. Raw material dependencies include meteorological data licensing, geotechnical survey equipment, and grid modeling software. Single-source vulnerability concentrates in senior practitioners spanning engineering and structured finance expertise. Distribution runs through direct partner relationships with IPPs and institutional investors rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advisory firms face a vertical-integration race to capture in-house technical certification capabilities, with downstream control over grid interconnection labs emerging as the decisive margin lever.
For Market Incumbents: To counter boutique specialists capturing niche technical certification work, integrated platforms must acquire power engineering talent in Hyderabad and Bengaluru clusters while embedding digital twin capabilities into utility retainer contracts. Backward integration into proprietary LCOE benchmarking databases creates switching costs for institutional investor clients. For New Entrants and Emerging Players: Enter via Brazil's ANEEL distributed generation reforms, where commercial and industrial offtakers seek independent owner-engineer representation distinct from installer relationships. Target energy storage integration advisory as battery-hybrid projects proliferate, using stacked revenue stream modeling as the differentiated entry proposition. For Investors and Strategic Acquirers: The window for entry favors specialized boutiques with captive technical certification labs and CEA grid code navigation capabilities in India. Acquisition candidates combine power engineering credentials with capital markets structuring experience. Watch for permitting timeline compression in Germany's Federal Network Agency processes as the inflection signal for advisory cost structure viability.| Strategic Initiative | Industry Significance |
|---|---|
| Technical Certification Lab Acquisition | In-house grid interconnection capabilities capture premium pricing from offshore wind developers facing KBA mandates. |
| Digital Twin Platform Integration | Real-time asset performance data enables recurring retainer revenue models with utility clients. |
| Regulatory Specialist Expansion in India | CEA grid code expertise secures foreign developer mandates for utility-scale solar park development. |
| Carbon Accounting Capability Buildout | EU CSRD Scope 3 disclosure compliance creates advisory demand from North Sea offshore wind consortia. |
| Hybrid Project Structuring Practice | Battery-solar integration expertise captures fastest-expanding margin pool as stacked revenue models proliferate. |
Research Methodology
Document review covered EIA generation data, IEA renewable investment reports, FERC interconnection queue filings, and national regulatory databases, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary fieldwork validated secondary estimates through bottom-up project pipeline assessment and top-down market sizing triangulation.
Market value and volume outputs derive from segment-level modeling across consulting service type, end user industry, technology focus, and engagement model dimensions throughout the forecast period. CAGRs emerge from regression analysis against historical advisory spend patterns and project development velocity indicators, incorporating EU Green Deal compliance cost trajectories and India CEA regulatory revision timelines as structural inputs.
Revisions become necessary when carbon border adjustment implementation timelines accelerate, permitting agency processing capacity contracts, or energy storage technology cost curves steepen beyond modeled assumptions. Deviation in Germany's Federal Network Agency queue clearance rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.