
 Solar Thermal Water Heater Market | 2026-2036
Solar Thermal Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Thermal Water Heater Market Intelligence
Chinese manufacturers' dominance in evacuated tube collector production is realigning the supply chain for residential systems. Himin Solar Energy Group leverages its massive scale to influence component pricing for these systems. In contrast, European specialists like Bosch Thermotechnology and GREENoneTEC Solarindustrie differentiate through high-efficiency flat plate collector technology and system integration for commercial applications, serving a different market tier.
A solar thermal water heater is a system that uses solar collectors to absorb solar radiation and transfer the heat to water. These collectors, often containing a heat transfer fluid like a glycol-water mixture, circulate the heated medium to an insulated storage tank for later use. Evacuated tube collectors command a significant market share due to their superior performance in colder climates. The residential application segment remains the largest volume driver, while commercial installations in hotels and sports facilities represent a high-margin growth opportunity.
Global standards like ISO 9806 provide a framework for collector performance testing, ensuring product quality and enabling international trade. In parallel, national incentives such as the US federal tax credits and India's Production Linked Incentive (PLI) scheme directly stimulate consumer and commercial purchases. System integrators must now decide whether to compete on price with commoditized components or focus on specialized, high-performance systems for niche applications.
Market Dynamics
The solar thermal water heater market is defined by a fundamental split between commoditized residential systems driven by cost and high-performance commercial systems driven by efficiency. This bifurcation is a direct result of Chinese manufacturing scale in evacuated tube collectors realigning supply chain economics.
Growth Catalysts
- Government Incentives:National subsidies and tax credits in countries like India and Brazil directly stimulate consumer demand by lowering the initial investment barrier for residential installations.
- Regulatory Mandates:The EU Green Deal creates significant momentum by promoting energy-efficient building retrofits, positioning solar thermal as a key technology for decarbonizing domestic hot water production.
- Residential Utility Costs:Homeowners are increasingly adopting solar thermal systems as a long-term strategy to hedge against rising electricity and gas prices, seeking greater energy independence and lower utility bills.
Market Restraints
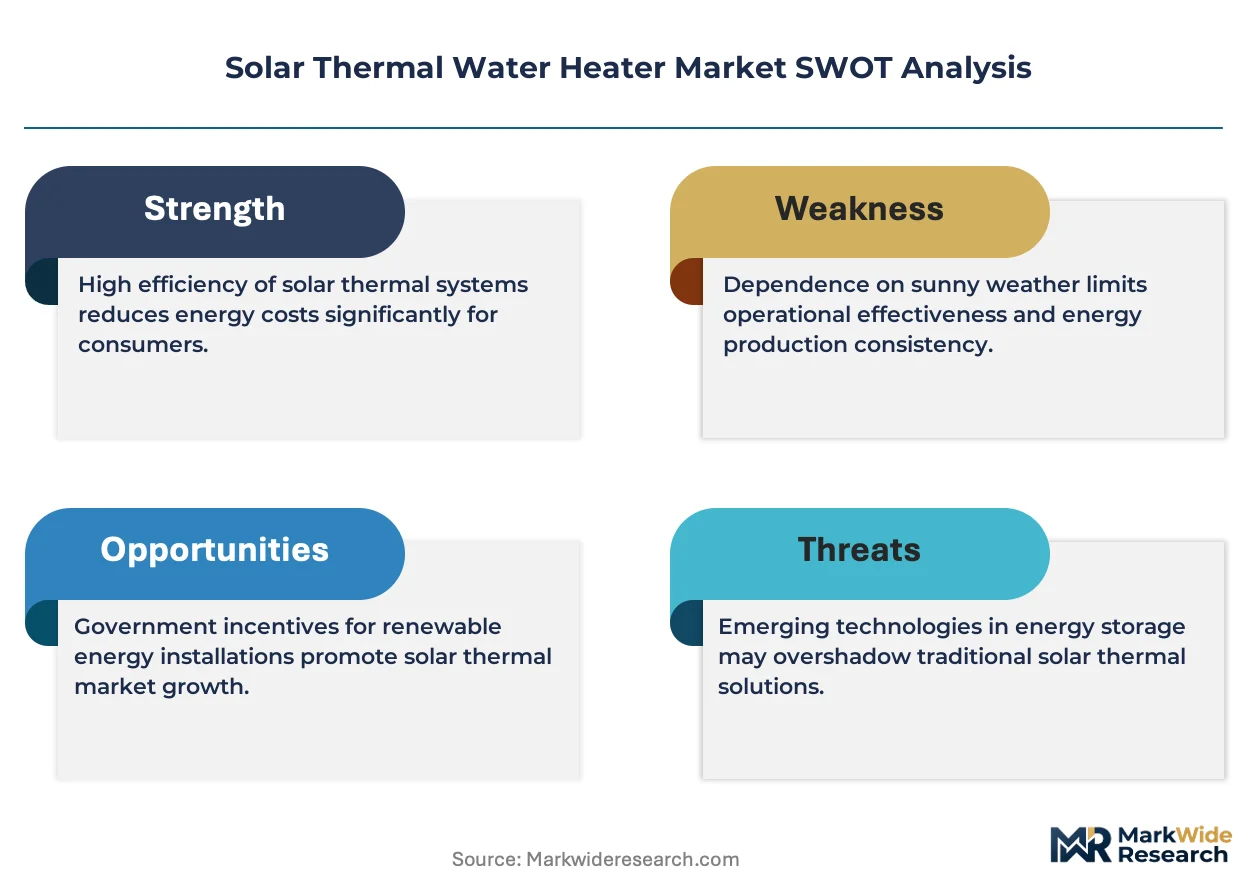
- High Initial Capital Outlay:The upfront cost of purchasing and installing a solar thermal system remains significantly higher than for conventional gas or electric water heaters, deterring price-sensitive consumers.
- Substitution by Solar PV:The falling cost and rising efficiency of solar photovoltaic (PV) panels present a strong substitution threat, as consumers may opt for a PV-plus-electric-heater combination.
- Performance Variability:System output is inherently dependent on local weather conditions and solar irradiation levels, leading to inconsistent performance in regions with frequent cloud cover or long winters.
Strategic Opportunities
- Commercial Sector Expansion:High-margin growth exists in commercial applications for hotels, hospitals, and sports facilities, which have large, consistent hot water demands and can realize faster payback periods.
- Hybrid System Integration:Combining solar thermal collectors with electric heat pumps or other heating systems offers an opportunity to create highly efficient, reliable hybrid solutions for year-round performance.
- Service and Maintenance Contracts:Developing long-term service agreements for commercial and industrial clients provides a recurring revenue stream and ensures optimal system performance and longevity.
Industry Challenges
- Skilled Labor Scarcity:A shortage of technicians trained in the proper installation, commissioning, and maintenance of solar thermal systems can lead to suboptimal performance and damage brand reputation.
- Regulatory Compliance Complexity:System integrators face challenges navigating the diverse landscape of national certifications, such as ISO 9806, and varying local building codes, which can delay projects.
- Legacy System Integration:Retrofitting solar thermal systems into older buildings with existing complex plumbing and heating infrastructure poses significant technical and logistical hurdles for installers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Thermal Water Heater Market |
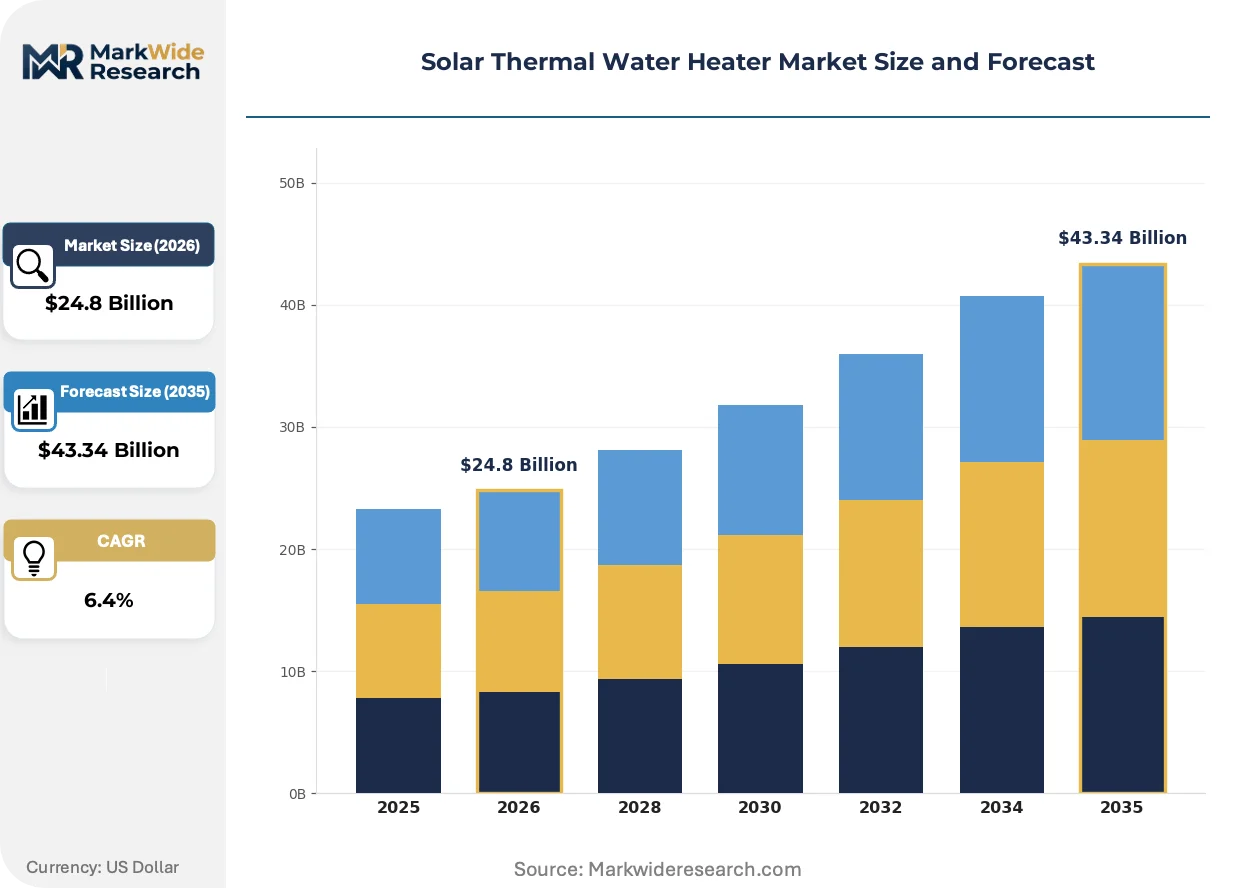
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Plate Collectors, Evacuated Tube Collectors, Integral Collector Storage, Concentrating Collectors Installation Type: Rooftop, Ground Mounted, Wall Mounted, Integrated Building Systems Application: Residential, Commercial, Institutional, Agricultural End User: Hotels, Manufacturing Units, Educational Establishments, Sports Facilities |
| Companies Covered | A. O. Smith, Rheem Manufacturing, Bosch Thermotechnology, SunEarth, Ariston Thermo, Himin Solar Energy Group, V-Guard Industries, Stiebel Eltron, GREENoneTEC Solarindustrie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Thermal Water Heater Market Strategic Shifts & Innovations
The market's evolution is marked by a technological divergence between collector types and a demand-side shift toward performance-based solutions. This reflects a maturing industry where buyers are becoming more sophisticated, moving beyond simple component selection to demanding integrated, guaranteed outcomes.
High-efficiency flat plate collectors incorporate advanced selective coatings and anti-reflective glass to maximize solar energy absorption and minimize heat loss. Commercial clients in Europe are adopting these systems for their superior durability and performance in moderate climates. This premium technology is expanding into high-end residential projects where aesthetic integration and maximum energy output per square meter are critical design requirements.
Building energy codes and regulations are becoming more stringent, directly benefiting the solar thermal market. For example, the EU Green Deal's mandates for nearly zero-energy buildings (NZEB) compel developers and architects to incorporate renewable heating sources. The commercial new-build segment is most affected, as solar thermal systems provide a compliant and cost-effective path to meeting hot water-related energy performance targets.
A notable behavioral shift is occurring in how commercial systems are specified and purchased. End-users are moving from procuring individual components to demanding turnkey solutions with guaranteed thermal output and energy savings from specialized system integrators. This trend is most prominent in the hospitality sector in North America and Europe, where predictable operational cost savings are a primary driver for capital investment.
Solar Thermal Water Heater Market Segmentation
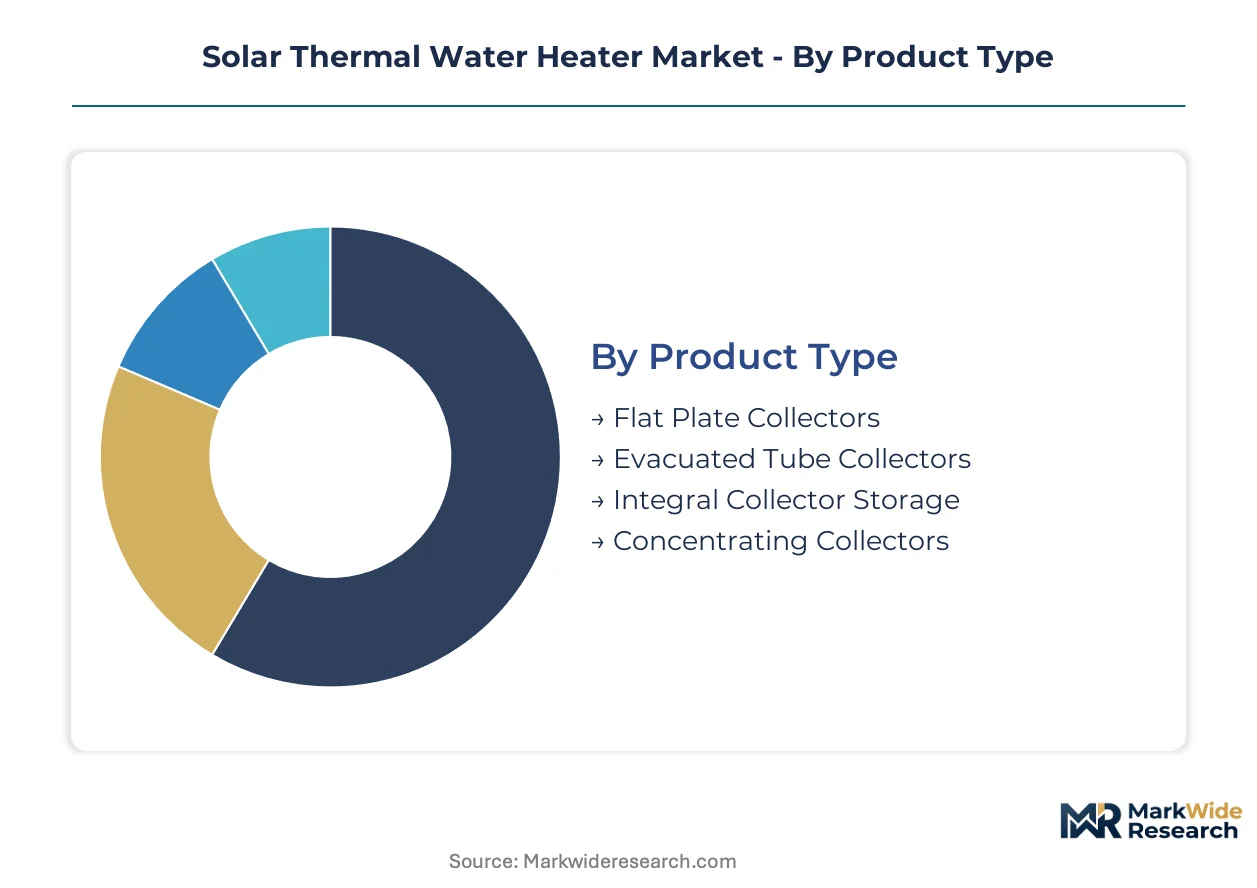
Understanding the solar thermal water heater market's segmentation is critical for manufacturers and integrators to align product development and market strategies. This analysis reveals the distinct requirements and commercial dynamics across different product types, installation methods, applications, and end-user groups. Each segment presents unique challenges and opportunities for market participants.
Product Type:
Navigating the product type landscape requires adherence to specific global and national certifications, such as ISO 9806, which provides a framework for collector performance testing and product quality assurance.
- Evacuated Tube Collectors:These collectors offer superior performance in colder climates due to their vacuum insulation, minimizing heat loss. Chinese manufacturers like Himin Solar Energy Group dominate production, influencing global component pricing for residential systems.
- Flat Plate Collectors:Featuring advanced selective coatings and anti-reflective glass, these collectors maximize solar energy absorption and minimize heat loss. European specialists like Bosch Thermotechnology differentiate through high efficiency and durability, particularly for commercial applications in moderate climates.
- Integral Collector Storage:These systems combine the collector and storage tank into a single unit, simplifying installation and reducing plumbing requirements. They are often favored for their compact design in smaller residential settings.
- Concentrating Collectors:These collectors use mirrors or lenses to focus sunlight onto a smaller absorber area, achieving higher temperatures. They find niche applications in industrial processes requiring high-temperature hot water or steam generation.
Leading the category by volume: Evacuated Tube Collectors. Expanding most quickly: Flat Plate Collectors.
Installation Type:
Installation methods vary significantly based on building structure, available space, and aesthetic considerations, directly impacting project complexity and cost.
- Rooftop:This is the most common installation method, leveraging unused roof space for solar exposure. Residential and smaller commercial buildings frequently adopt rooftop systems due to ease of access and optimal sun exposure.
- Integrated Building Systems:These systems are seamlessly incorporated into the building's architecture, often replacing conventional roofing materials. Commercial new-build projects are increasingly adopting integrated solutions to meet stringent EU Green Deal mandates for nearly zero-energy buildings (NZEB).
- Ground Mounted:When roof space is limited or unsuitable, ground-mounted systems provide flexibility in orientation and tilt for optimal solar capture. Large-scale commercial or institutional installations often utilize ground arrays for greater capacity.
- Wall Mounted:Less common, wall-mounted collectors can be used where roof access is impractical or for specific architectural integration. These installations often serve smaller domestic hot water needs.
The choice of installation type is primarily driven by the building's existing infrastructure and the desired system capacity.
Application:
The market bifurcates across applications, driven by differing demands for hot water volume, temperature, and payback period expectations from various customer types.
- Residential:Homeowners represent the largest volume driver, adopting solar thermal systems to reduce utility costs and hedge against rising electricity and gas prices. Government incentives in countries like India and Brazil directly stimulate these consumer purchases.
- Commercial:This segment includes hotels, hospitals, and sports facilities, which have large and consistent hot water demands. Commercial installations represent a high-margin growth opportunity, with end-users demanding turnkey solutions and guaranteed thermal output.
- Institutional:Educational establishments and government buildings utilize solar thermal for domestic hot water and space heating. These applications often prioritize long-term operational savings and adherence to public sector sustainability goals.
- Agricultural:Farms use solar thermal for various processes, including livestock watering, greenhouse heating, and crop drying. The demand here is often for robust, low-maintenance systems capable of operating in diverse rural environments.
Residential applications remain strategically important for market volume, while the commercial sector offers significant high-margin growth potential.
End User:
Specific end-user segments demonstrate distinct procurement patterns and hot water requirements, influencing system design and service expectations.
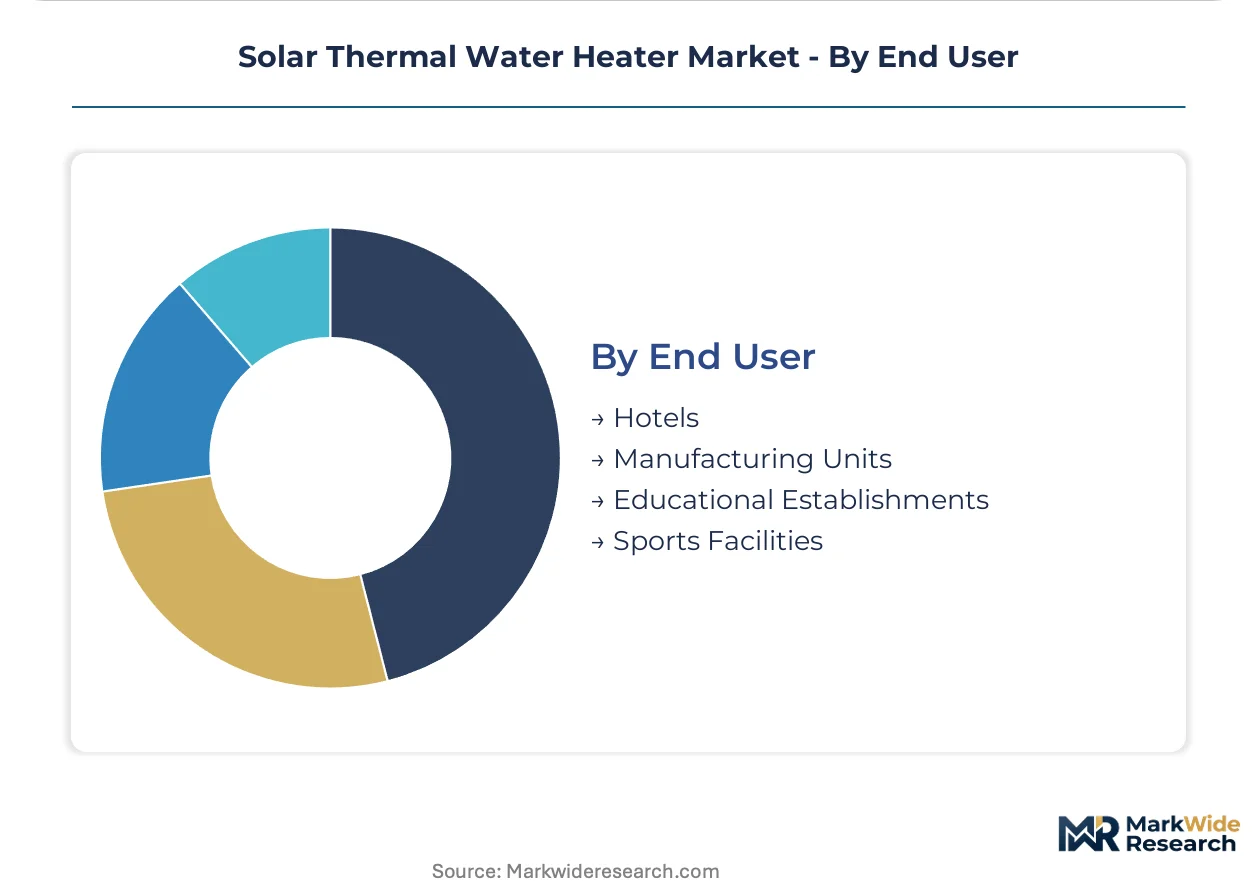
- Hotels:The hospitality sector in North America and Europe is shifting towards demanding turnkey solutions with guaranteed energy savings. Hotels require consistent, high-volume hot water for guest services, making solar thermal an attractive operational cost-saving measure.
- Sports Facilities:These establishments, including gyms and swimming pools, have substantial and predictable hot water needs. They represent a high-margin growth opportunity where system efficiency and reliability are paramount for continuous operation.
- Manufacturing Units:Industrial facilities utilize solar thermal for process heat, pre-heating boiler feed water, and domestic hot water for staff. Their demand often focuses on large-scale, robust systems that can integrate with existing industrial infrastructure.
- Educational Establishments:Schools and universities implement solar thermal systems to reduce operational expenses and demonstrate environmental commitment. These institutions typically require reliable systems for dormitories, cafeterias, and athletic facilities.
End-user segments with high, consistent hot water demand, such as hotels and sports facilities, demonstrate the most promising future potential for solar thermal adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturing dominance in evacuated tube collectors anchors the global supply chain, influencing component pricing for residential systems worldwide. This manufacturing scale creates a cost-competitive environment for solar thermal technologies. Demand centers in countries like India and Brazil benefit from high solar irradiation and targeted government initiatives, stimulating market expansion.
China
The Chinese market is driven by vast domestic manufacturing capacity and strong government support for renewable energy deployment. China's dual carbon goals promote solar thermal as a key technology for reducing emissions in heating. Production hubs in provinces like Shandong and Jiangsu actively develop and export evacuated tube collectors to global markets.
India
India's solar thermal market benefits from significant government subsidies and high solar irradiation levels across most regions. The Production Linked Incentive (PLI) scheme encourages domestic manufacturing and adoption of solar water heaters. Cities such as Bengaluru and Chennai are seeing increased residential and commercial installations due to rising energy costs.
Brazil
Government incentives and the abundant solar potential across the country stimulate demand for solar thermal systems in Brazil. Programs like the National Energy Efficiency Program promote energy-saving technologies in buildings. The southeastern states, including São Paulo and Minas Gerais, lead in residential adoption due to favorable climate and economic conditions.
Germany
Germany's market for solar thermal systems is shaped by stringent regulatory mandates, particularly the EU Green Deal's focus on energy-efficient building retrofits. High-efficiency flat plate collectors are favored for commercial applications and premium residential projects. Cities like Freiburg and Munich are centers for advanced solar thermal research and high-quality system integration.
United States
The United States market is influenced by federal tax credits and state-level renewable energy mandates that reduce the initial investment for consumers. Homeowners increasingly adopt solar thermal to mitigate rising utility costs and achieve greater energy independence. California and Arizona demonstrate strong market activity, driven by high solar insolation and supportive policies.
Solar Thermal Water Heater Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized, high-performance system integration. This market bifurcates between commoditized residential systems and high-efficiency commercial solutions. Strategic archetypes include large-scale component manufacturers, specialized system integrators, and technology-focused developers. Dominant competitive moves involve capacity expansion for cost leadership and product differentiation through advanced collector technology.
At the scale-driven end, Himin Solar Energy Group exemplifies the influence of Chinese manufacturing on global component pricing for evacuated tube collectors. European specialists like Bosch Thermotechnology and GREENoneTEC Solarindustrie occupy a position in the high-efficiency segment. These companies differentiate through advanced flat plate collector technology and comprehensive system integration for commercial and high-end residential applications.
| Leading Market Players |
|---|
| A. O. Smith |
| Rheem Manufacturing |
| Bosch Thermotechnology |
| SunEarth |
| Ariston Thermo |
| Himin Solar Energy Group |
| V-Guard Industries |
| Stiebel Eltron |
| GREENoneTEC Solarindustrie |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's mandates for energy-efficient buildings compel developers to source compliant solar thermal systems, influencing component pricing and supply chain integration. This demand-side pressure forces manufacturers to adapt production and pricing strategies.
Pricing Analysis
Warranty and service contracts bundled with solar thermal systems significantly influence pricing, especially for commercial clients. The market primarily operates on a project-based pricing model, where system integrators offer turnkey solutions. Price differentiation stems from collector technology and after-sales service agreements. Pricing pressure stems from cost-competitive Chinese-made evacuated tube collectors, while residential homeowners remain the most price-sensitive segment.
Supply Chain Analysis
Logistics and freight costs significantly impact the landed price of solar thermal components, particularly for international shipments. Supply concentration for evacuated tube collectors centers in China, with Germany and other European countries specializing in flat plate collectors. Raw material dependencies include copper, glass, and aluminum for collector manufacturing. A structural risk is the single-source vulnerability for specialized components from dominant manufacturers. Distribution runs through a network of regional distributors and system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar thermal market is becoming a vertical-integration race, as companies pursue upstream control over component manufacturing to manage costs and ensure supply. This strategic move aims to enhance competitive positioning and product quality.
For Market Incumbents:Hedge against the growing substitution threat from solar photovoltaic (PV) by integrating hybrid system solutions. Incumbents should invest in R&D for advanced flat plate collectors, enhancing performance in moderate climates. Acquire specialized system integrators to deepen vertical integration into high-margin commercial applications. Strengthen channel partnerships to improve installation quality and after-sales service.
For New Entrants and Emerging Players:Small and medium-sized enterprises (SMEs) in the institutional and agricultural sectors represent an underserved buyer archetype for solar thermal systems. New entrants should target these segments with robust, low-maintenance systems tailored for specific process heat or water demands. A focused go-to-market angle involves offering bundled solutions that include financing and long-term service contracts. This approach leverages specialized knowledge to penetrate niche applications.
For Investors and Strategic Acquirers:The window for entry favors specialized system integrators with strong commercial client relationships and technical expertise. Long-term viability across the next decade rests on companies that can deliver guaranteed thermal output and reliable service. Acquisition targets should be mid-sized firms proficient in complex system integration and regulatory compliance. The signal to watch is the increasing demand for outcome-based performance contracts in the commercial sector.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Integration | Combines solar thermal with heat pumps, offering year-round energy efficiency. |
| Commercial Sector Expansion | Captures high-margin projects in hospitality and sports facilities with large hot water demands. |
| Advanced Collector R&D | Differentiates products through superior performance and durability in varied climates. |
| Skilled Workforce Development | Addresses labor scarcity, ensuring proper installation and system maintenance. |
| Service Contract Bundling | Secures recurring revenue streams and enhances customer lifetime value. |
Research Approach
Document review covered academic journals, industry association reports, and government publications, complemented by interviews with manufacturers, system integrators, and commercial end-users. Primary research involved discussions with R&D directors, procurement managers, and installation technicians across key geographies. Secondary data sources included national energy agency reports, trade statistics, and company financial disclosures. This approach ensured bottom-up market sizing and top-down validation of segment projections.
Historical market data was cross-referenced against expert panel input to establish a robust forecast framework across the analysis window. The analytical framework modeled segmentation dimensions including product type, installation type, application, and regional adoption patterns. Compound annual growth rates were derived from a multi-variable regression analysis, incorporating economic indicators and regulatory changes. Key forecast inputs included projected utility cost trends and government incentive program durations.
Revisions become necessary when significant shifts in energy policy or raw material prices materialize, impacting market dynamics. Forecasts reflect assumptions regarding technological advancements and incentive program continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Renewable Energy Contractor Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
Solar Showers Market
Renewable Energy
China Wind Power Market
Renewable Energy
Austria Renewable Energy Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
Solar Ceiling Fans Market
Renewable Energy
Republic of Ireland Renewable Energy Market
Renewable Energy
Renewable Energy Consulting Market
Renewable Energy
Europe Renewable Energy Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
Solar Highway Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
West Africa Renewable Energy Market