
 Soft Touch Lamination Film Market | 2026-2036
Soft Touch Lamination Film Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Touch Lamination Film Market Intelligence
Value-added surface treatments, such as anti-fingerprint and scuff-resistant coatings, is reshaping competitive positioning from pure film supply to specialized finishing services. Taghleef Industries SLU leverages its scale in BOPP production to offer a wide range of base films for these applications. Cosmo Films Ltd. specializes in developing films with unique tactile properties for premium packaging. Amcor Limited integrates these specialized films into its broader flexible packaging solutions portfolio for global consumer brands.
Soft touch lamination film is a biaxially-oriented polypropylene (BOPP) or polyester (PET) film treated with a specialized coating to create a distinct, velvety texture. Its primary function is to enhance the tactile and visual appeal of printed materials and packaging while providing surface protection. Within applications, demand from luxury packaging and high-end magazine covers outpaces that from standard business cards. The material segment shows a clear preference for BOPP due to its cost-effectiveness and excellent printability.
Material composition and safety are governed by regulations such as the FDA's requirements for food-contact materials in the United States. In Europe, compliance with REACH and RoHS directives is critical for films used in consumer goods and electronics packaging. These rules influence polymer and additive choices. Producers must now decide whether to invest in developing bio-based and recyclable film variants to meet rising sustainability mandates.
Market Dynamics
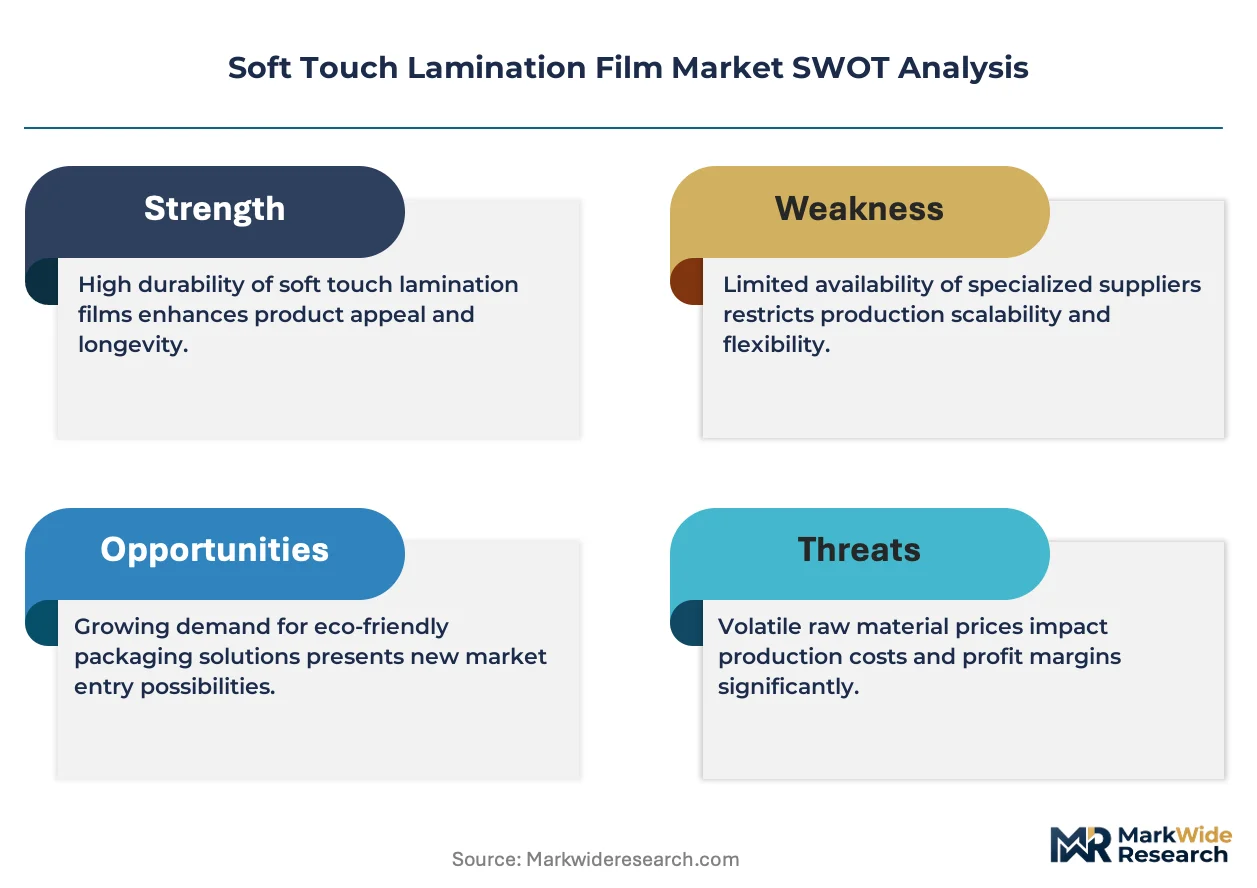
The imperative to reconcile luxury aesthetics with environmental sustainability defines the soft touch lamination film market. This structural tension is forcing innovation in polymer science and coating technology to meet both premium branding demands and stricter recycling regulations.
Growth Catalysts
- Luxury Goods Expansion:Demand from high-end electronics and cosmetics packaging, particularly within China's advanced manufacturing hubs, requires premium finishing materials to enhance consumer perception and product value.
- Value-Added Coatings:The development of functional surfaces, such as anti-scuff and fingerprint-resistant coatings, creates new application possibilities and allows film suppliers to offer specialized, higher-margin services.
- Recyclable Film Innovations:Advances in recyclable BOPP film technology are enabling brands to meet sustainability mandates like the EU Green Deal without sacrificing the tactile qualities of their packaging.
Market Restraints
- Input Cost Volatility:The market's profitability is sensitive to fluctuations in the price of key raw materials, specifically polypropylene and polyethylene terephthalate (PET) resins, which are tied to global petrochemical markets.
- Recycling Infrastructure Gaps:Laminated materials, even those designed for recyclability, face challenges in collection and sorting systems that are not equipped to handle them, limiting the realization of circular economy goals. *Substitution by Digital Media: A shift towards digital marketing and minimalist packaging designs in some sectors reduces the overall addressable market for printed materials requiring high-end lamination finishes.
Strategic Opportunities
- Bio-Based Polymers:Developing and scaling soft touch films derived from bio-based sources like polylactic acid (PLA) offers a path to meet corporate sustainability goals and appeal to environmentally conscious consumers.
- Automotive Interior Surfaces:The unique tactile properties of soft touch films present an opportunity for application on interior car components, such as dashboards and touch panels, to enhance perceived quality and durability.
- Emerging Luxury Markets:Penetrating high-growth consumer markets in Southeast Asia and Latin America, where a rising middle class is driving demand for premium packaged goods, presents a significant geographic expansion path.
Industry Challenges
- Regulatory Compliance Complexity:Manufacturers must navigate a fragmented and evolving landscape of food-contact and chemical safety regulations, such as FDA requirements in the U.S. and REACH directives in Europe, which impacts material selection.
- Process Control Consistency:Achieving a uniform velvety texture across large-scale production runs is technically demanding, requiring significant investment in advanced coating machinery and stringent quality control protocols to avoid defects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Touch Lamination Film Market |
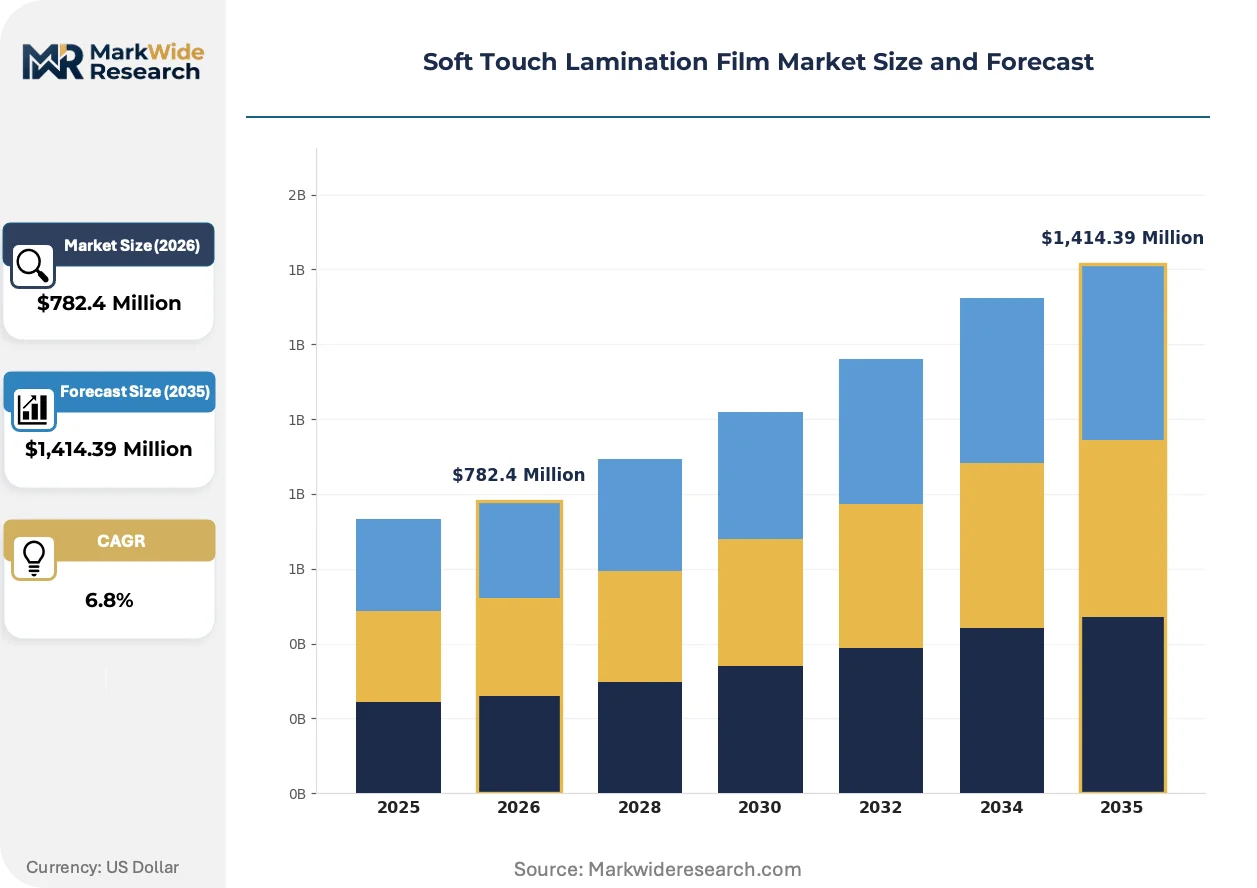
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,414.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Matte, Gloss, Satin, Textured Application: Packaging, Labels, Business Cards, Magazines End User: Retail, Publishing, Electronics, Food & Beverage Material: Polyethylene, Polyester, BOPP, PVC |
| Companies Covered | Taghleef Industries SLU, DUNMORE Corporation, Amcor Limited, Monotech Systems Ltd., Flex film Limited, Avery Dennison Corporation, Dow Chemical Co., Jet Technologies, Cosmo Films Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Touch Lamination Film Market Strategic Shifts & Innovations
Material science advancements are steering the market toward solutions that balance premium tactile experience with circular economy principles. This evolution is driven by regulatory pressure and a decisive shift in brand owner priorities toward verifiable sustainability claims for packaging materials.
Advanced mono-material BOPP films offer a sustainable alternative to traditional multi-layer products that hinder recycling. High-end consumer goods brands, especially in cosmetics, are rapidly adopting these solutions to align with corporate ESG commitments. The market's material foundation is migrating from conventional, difficult-to-recycle laminates toward single-polymer structures that are compatible with established polyethylene and polypropylene recycling streams.
Europe's Green Deal, through its Packaging and Packaging Waste Regulation (PPWR), establishes stringent targets for recyclability and recycled content in packaging. This policy directly impacts producers of luxury goods, forcing investment in film technologies that will not contaminate post-consumer waste streams. The high-end electronics packaging sector is particularly affected, now funding R&D for compliant films to preserve access to the European market.
Brand owners are altering their specification criteria, prioritizing materials with formal sustainability certifications over selections based solely on cost or aesthetics. This change transforms the procurement process from a simple transaction for film into a strategic partnership aimed at meeting corporate sustainability reporting goals. This behavioral shift is most pronounced in the North American and European consumer goods verticals.
Soft Touch Lamination Film Market Segmentation
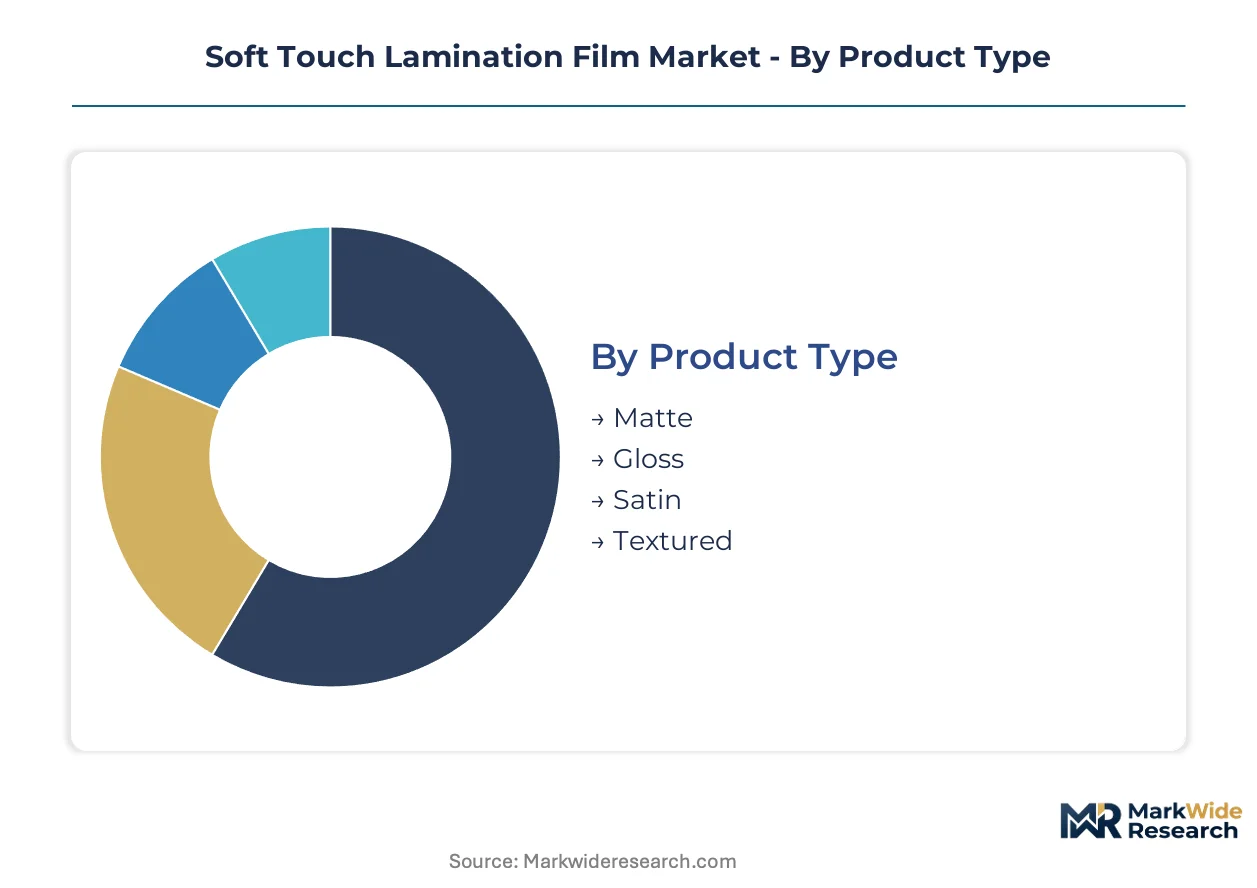
The soft touch lamination film market segments across several critical dimensions, each influencing product development and market penetration. Understanding these categories helps manufacturers align their offerings with specific end-user demands and regulatory frameworks. This granular analysis reveals where innovation delivers the most significant commercial impact for film producers.
Product Type:
The product type segmentation reflects the diverse aesthetic and functional finishes demanded by brand owners, ranging from understated elegance to striking visual effects.
- Matte:This film type provides a non-reflective, sophisticated finish that diffuses light, reducing glare and enhancing perceived quality. Demand concentrates in luxury packaging for cosmetics and high-end electronics, particularly within the German and Japanese consumer markets, where premium aesthetics are paramount.
- Textured:Textured films incorporate embossed patterns or specialized coatings to create a distinct haptic experience, mimicking materials like leather or fabric. High-end product launches in the United States and China leverage textured finishes to differentiate products and elevate brand perception.
- Gloss:Gloss films deliver a high-shine, reflective surface that intensifies color and visual vibrancy. This finish remains popular for promotional materials and book covers seeking maximum visual impact.
- Satin:Satin finishes offer a subtle sheen, falling between matte and gloss, providing a balanced aesthetic with good scuff resistance. Packaging for artisanal goods and specialty food products often utilizes satin lamination.
Matte films retain volume leadership; Textured films hold the steepest expansion curve.
Application:
Application segments highlight the primary end-uses for soft touch films, with varying requirements for durability, tactile properties, and cost-effectiveness across different printed materials.
- Packaging:Soft touch films are extensively used in luxury packaging for consumer goods, protecting surfaces while adding a premium tactile experience. The electronics and cosmetics sectors in South Korea and France drive significant demand for sophisticated packaging solutions.
- Magazines:High-end magazine covers and editorial inserts utilize soft touch lamination to enhance visual appeal and tactile quality, differentiating premium publications. Publishers in the United Kingdom and Italy specifically seek these finishes for art and fashion magazines.
- Labels:Soft touch films applied to product labels improve durability and provide a distinctive feel, particularly for wine, spirits, and gourmet food products. Craft beverage producers in Australia and Canada value the enhanced shelf presence.
- Business Cards:Laminated business cards with a soft touch finish convey professionalism and a premium brand image. Small businesses and corporate clients in urban centers globally specify these enhanced cards.
Packaging applications command the largest market share; Magazines exhibit strong growth in niche segments.
End User:
The end-user segmentation categorizes the industries that integrate soft touch lamination films into their products, each with unique purchasing criteria and regulatory considerations.
- Electronics:Manufacturers of high-end electronics, including smartphones, laptops, and gaming consoles, use soft touch films for packaging and sometimes for device surfaces. Companies in Taiwan and the United States prioritize films with anti-fingerprint and scuff-resistant properties for their products.
- Food & Beverage:The food and beverage industry utilizes soft touch films for premium product packaging, enhancing shelf appeal and providing a protective barrier. Compliance with FDA food-contact regulations in the United States and EFSA directives in Europe is critical for these applications.
- Retail:The broader retail sector employs soft touch films for point-of-sale displays, shopping bags, and branded collateral to create a luxurious brand experience. Fashion brands in France and Italy frequently specify these materials for their marketing efforts.
- Publishing:Publishing houses apply soft touch films to book covers, brochures, and promotional materials, especially for art books and limited editions. Academic and trade publishers in Germany and the Netherlands value the enhanced durability and aesthetic.
Electronics companies represent a significant end-user segment; Food & Beverage is expanding quickly due to premiumization trends.
Material:
The material segment details the polymer types used as the base for soft touch lamination films, with each offering distinct properties regarding cost, performance, and recyclability.
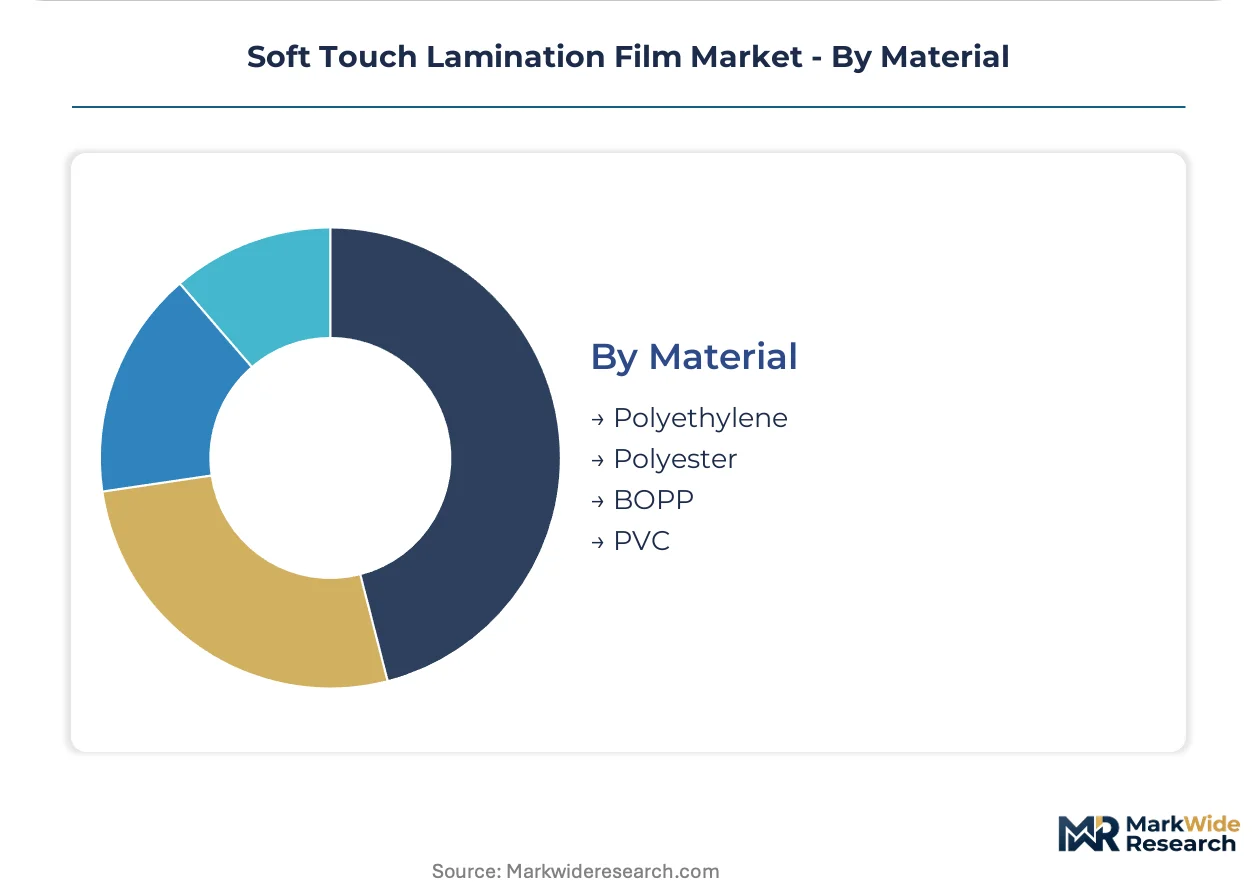
- BOPP:Biaxially-oriented polypropylene films are highly favored due to their cost-effectiveness, excellent printability, and good mechanical properties. Innovations in recyclable BOPP variants are aligning products with EU Green Deal objectives, especially for packaging in Germany and the Netherlands.
- Polyester:Polyester (PET) films offer superior heat resistance, dimensional stability, and stiffness compared to BOPP, making them suitable for demanding applications. High-end graphic arts and industrial applications in Japan and Switzerland often specify PET for its robust performance.
- Polyethylene:Polyethylene films provide flexibility and good sealing properties, often used in multi-layer laminates where a soft touch effect is desired. The material's use is evolving with advancements in mono-material structures for improved recyclability in North America.
- PVC:Polyvinyl chloride films offer durability and chemical resistance, historically used for certain lamination applications. Environmental concerns and regulatory pressures, particularly in Europe, are leading to a decline in its adoption for new soft touch film developments.
BOPP maintains its market dominance; Polyester films are gaining share in specialized, high-performance applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The soft touch lamination film market exhibits varied consumption patterns across different geographies, with Asia-Pacific markets often prioritizing functional benefits alongside aesthetics, while European nations emphasize sustainability mandates. North America balances premiumization trends with regulatory compliance for food contact materials. Each region presents unique demand drivers and regulatory landscapes for film producers.
China
Luxury goods expansion and high-end electronics packaging drive significant demand for premium soft touch films. China's dual carbon goals promote investment in sustainable packaging solutions across various industries. Advanced manufacturing clusters like the Pearl River Delta actively integrate these films into new product designs for global export.
United States
High-end product launches and electronics packaging, particularly for consumer devices, fuel the need for advanced soft touch films. FDA requirements for food-contact materials critically influence material selection for food and beverage packaging. Urban centers such as New York City and Los Angeles specify enhanced films for sophisticated branding and tactile appeal.
Germany
Premium aesthetics in consumer markets and demand from academic and trade publishing sectors sustain the market for soft touch films. The EU Green Deal objectives and REACH directives heavily influence material choices, pushing for recyclable and compliant solutions. The Rhine-Ruhr region and Bavaria actively develop sustainable packaging applications for diverse industries.
South Korea
Sophisticated electronics and cosmetics packaging propel demand for visually appealing and tactile films. The Ministry of Food and Drug Safety (MFDS) regulates packaging materials, ensuring safety and compliance for consumer goods. The Seoul Capital Area's technology and beauty industries continually seek innovative tactile film solutions for product differentiation.
France
Luxury packaging for cosmetics and fashion brands, alongside high-end magazines, requires distinctive soft touch finishes. ANSM (national agency for the safety of medicines and health products) directives guide material selection for cosmetics packaging. Paris and Lyon's luxury goods sectors prioritize films that enhance the perceived quality and brand experience.
Soft Touch Lamination Film Market Key Industry Players
Capability concentration sits with one tier of specialized film innovators; scale advantage sits with another tier of integrated packaging solution providers. The market structure thus exhibits a tiered competition, with pure-play film suppliers, specialized coating companies, and diversified packaging conglomerates. Strategic archetypes include large-scale BOPP producers, niche tactile film developers, and full-service flexible packaging companies. Dominant competitive moves involve portfolio diversification into value-added coatings and strategic partnerships to integrate specialized films into broader packaging solutions.
Specialized film innovators like Cosmo Films Ltd. exemplify companies focused on unique tactile properties for premium packaging applications. Taghleef Industries SLU, a European-based entity, leverages its extensive scale in BOPP production to offer a broad range of base films for these applications. Amcor Limited, a global leader in flexible packaging, integrates these specialized films into its comprehensive packaging solutions portfolio for international consumer brands, representing the integrated solution provider archetype.
| Leading Market Players |
|---|
| Taghleef Industries SLU |
| DUNMORE Corporation |
| Amcor Limited |
| Monotech Systems Ltd. |
| Flex film Limited |
| Avery Dennison Corporation |
| Dow Chemical Co. |
| Jet Technologies |
| Cosmo Films Ltd. |
| Others |
Cost & Logistics Intelligence
Commodity volatility in polypropylene and PET resins critically determines pricing tier spreads and influences the structural resilience of the soft touch lamination film supply chain. This input cost fluctuation compels manufacturers to adjust pricing models and sourcing strategies.
Pricing Analysis
Long-term offtake agreements characterize pricing for large-volume soft touch lamination film procurements. Price differentiation stems from specialized tactile properties and customization levels, such as anti-fingerprint or scuff-resistant coatings. Pricing softness affects standard BOPP films due to raw material volatility, while premium segments like luxury packaging sustain higher margins. Business card applications exhibit the highest price sensitivity, contrasting with the low sensitivity seen in high-end electronics and cosmetics packaging.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities often underpin relationships between film producers and large converters. Supply concentration centers on China's advanced manufacturing clusters and European hubs like Germany for sustainable variants, alongside the United States for high-end electronics. The market relies on polypropylene and PET resins, plus specialized coating chemicals. A structural risk involves evolving regulatory restrictions, particularly the EU Green Deal, impacting material choices. Distribution runs through direct sales channels to integrated packaging companies and specialized film distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soft touch lamination film market represents a high-growth disruption, driven by the imperative to reconcile luxury aesthetics with environmental sustainability. Recyclable film innovations, particularly in BOPP technology, are fundamentally reshaping product development and market access.
For Market Incumbents: Harden process control consistency by investing in advanced coating machinery to ensure uniform texture across large-scale production runs. Diversify film portfolios with bio-based and recyclable variants to preempt regulatory shifts like the EU Green Deal. Pursue formal sustainability certifications to meet evolving brand owner priorities, mitigating the threat of market access restrictions. Develop specialized finishing services beyond pure film supply to enhance competitive positioning.
For New Entrants and Emerging Players: Build out specialized textured film offerings for high-end electronics packaging in China's advanced manufacturing hubs. Focus on mono-material BOPP solutions to align with circular economy principles and gain market entry in sustainability-conscious regions. Forge strategic partnerships with packaging converters and brand owners to integrate innovative films into their product lines, leveraging compliance with regulations like REACH. Target niche applications requiring unique tactile properties and verifiable sustainability claims.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized film innovators capable of balancing luxury aesthetics with sustainability mandates. Long-term viability remains strong, driven by premiumization trends and stringent environmental regulations over the next decade. Target acquisition profiles include companies with proprietary coating technologies or advanced recyclable BOPP film R&D. The signal to watch is the accelerated adoption of mono-material packaging structures by leading global consumer brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Polymer Development | Scales production of sustainable soft touch films, aligning with EU Green Deal objectives for packaging materials. |
| Advanced Coating Technology Investment | Enhances film durability and tactile properties, offering anti-fingerprint and scuff-resistant solutions for electronics. |
| Mono-material BOPP Transition | Facilitates recyclability of luxury packaging, meeting brand owner ESG commitments in North America. |
| Strategic Partnerships with Luxury Brands | Secures long-term contracts and co-develops tailored film solutions for high-end cosmetics and consumer goods. |
| Geographic Expansion into Southeast Asia | Captures demand from a rising middle class and growing premium packaged goods market in emerging economies. |
Research Approach
Demand-side practitioners and supply-side operators were consulted, combining primary interviews with extensive secondary validation. Engagements included film manufacturers, packaging converters, brand managers from luxury goods, and regulatory compliance officers. Secondary data sources encompassed industry association reports, government environmental regulations, company annual reports, and trade publications. This approach ensured robust bottom-up and top-down triangulation of market insights.
The calibration approach involved modeling market dynamics across the analysis window, integrating historical trends with future projections. Segmentation dimensions modeled included product type, application, end user, material, and key regional regulatory clusters. Compound annual growth rates were derived from a weighted average of segment-specific growth rates. Key forecast inputs included anticipated shifts in packaging material preferences and the impact of sustainability mandates.
Stress conditions across raw material price volatility and evolving regulatory landscapes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding market adoption and technological advancements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polyolefin (POF) Shrink Film Market
Poly film
Bopet Films Market
Poly film
PVC Films Market
Poly film
Polylaminate Capsules Market
Poly film
Anti Fog Polycarbonate Films and Sheets Market
Poly film
Italy Plastic Packaging Films Market
Poly film
Global Fluoropolymer Films Market
Poly film
Poly Coated Kraft Paper Market
Poly film
Thermoforming Films Market
Poly film
PET Lidding Films Market
Poly film
Polyethylene Film Market
Poly film
Poly Coated Paper Market
Poly film
Shrink Bundling Films Market
Poly film
Japan Plastic Packaging Film Market
Poly film
Middle East and Africa Plastic Packaging Films Market
Poly film
PP Laminating Films Market