
 PP Laminating Films Market | 2026-2036
PP Laminating Films Market Size, Share, and Industry Trends Forecast 2026-2036
PP Laminating Films Market Analytics
Aftermarket technical service revenue for film converting equipment is rewriting margin capture across the value chain. Amcor plc leverages its global converting footprint to sustain premium positioning in high-barrier laminates. Cosmo Films anchors South Asian supply through integrated BOPP film and metallization capabilities. UFLEX Limited competes on cost-optimized rollstock for flexible packaging export markets.
PP laminating films are biaxially oriented polypropylene substrates bonded to paper, board, or other films via thermal or adhesive lamination, typically operating at line speeds of 200–400 meters per minute in commercial converting. Their primary purpose is to impart moisture resistance, gloss enhancement, and structural rigidity to printed packaging and graphic arts materials. Gloss films dominate volume in publishing applications where visual impact commands shelf attention, while matte finishes are gaining share in premium cosmetics packaging where tactile differentiation supports brand positioning. The 75 micron thickness band occupies the broadest applicability across food and non-food flexible packaging, though 100 micron grades are displacing legacy PET constructions in certain frozen food pouch formats.
REACH substance restrictions and the EU Packaging and Packaging Waste Regulation are forcing substrate recyclability redesigns across European converting operations. FDA food-contact notification requirements and state-level extended producer responsibility laws in California and New York are elevating compliance costs for North American laminate suppliers. Stakeholders must monitor mechanical recycling compatibility standards and chemical recycling infrastructure buildout to preserve market access as circularity mandates harden.
Market Dynamics
REACH substance restrictions and the EU Packaging and Packaging Waste Regulation are forcing substrate recyclability redesigns across European converting operations, compressing legacy multilayer constructions while elevating mono-material PP laminates.
Growth Catalysts
- Flexible food packaging expansion:Southeast Asian converting lines are absorbing disproportionate capacity additions as regional food processors adopt laminated pouches for shelf-stable products.
- EU circularity mandates:The EU Packaging and Packaging Waste Regulation is accelerating demand for mechanically recyclable mono-PP constructions that simplify post-consumer sorting streams.
- Metallization technology maturation:Vacuum-deposited aluminum barriers on BOPP substrates now match legacy metallized PET performance at lower grammage, driving adoption in snack and confectionery segments.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking economics and regional refinery maintenance cycles inject margin instability into film extrusion operations.
- Chinese BOPP overcapacity:State-subsidized capacity additions in Shandong and Zhejiang provinces have compressed export pricing power for non-integrated converters.
- Multilayer incompatibility:Legacy PET/PE/PP adhesive laminates face mechanical recycling rejection at European sorting facilities, stranding installed converting assets.
Strategic Opportunities
- Chemical recycling infrastructure:Pyrolysis and dissolution facilities under construction in the Netherlands and Germany will create offtake pathways for contaminated or degraded PP laminates.
- Frozen food pouch conversion:100 micron PP grades are displacing legacy PET constructions in North American frozen vegetable and ready-meal formats where low-temperature flexibility matters.
- Digital print compatibility:Corona-treated BOPP films engineered for water-based ink adhesion are capturing share from solvent-coated competitors in short-run label applications.
Industry Challenges
- Adhesive formulation expertise:Solventless polyurethane systems require precise viscosity control and nip pressure calibration that legacy hot-melt operators struggle to master.
- Food-contact notification timelines:FDA 21 CFR compliance documentation for novel coextrusion layers stretches 18-24 months, delaying commercialization of improved barrier constructions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PP Laminating Films Market |
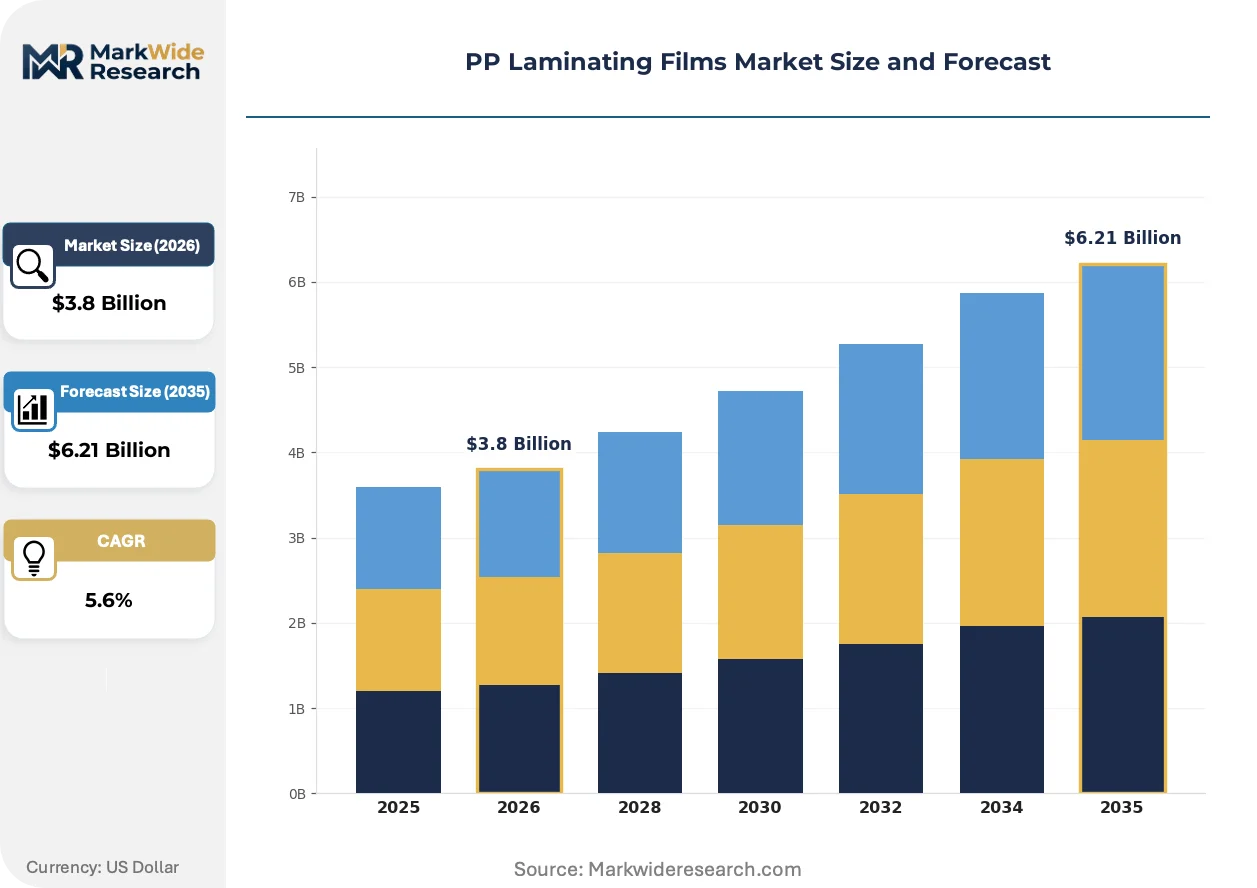
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gloss, Matte, Textured, Transparent End User: Packaging, Publishing, Retail, Textile Thickness: 50 Micron, 75 Micron, 100 Micron, 125 Micron Form: Roll, Sheet, Pouch, Bag |
| Companies Covered | Amcor plc, Cosmo Films, Mondi plc, UFLEX Limited, Taghleef Industries, Polyplex Corporation, Constantia Flexibles, Berry Global Group, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PP Laminating Films Market Evolving Landscape
Active developments across material science, regulatory compliance, and procurement models are compressing traditional competitive advantages while opening white space for specialized converters.
Water-based barrier coatings on BOPP substrates are collapsing the historical performance gap between extrusion-coated and metallized films. Premium cosmetics brands in France and Germany are specifying these constructions for matte-finish folding cartons where haptic differentiation commands shelf attention. The elimination of aluminum deposition steps compresses converting lead times from weeks to days.
REACH SVHC candidate list expansions are forcing reformulation of slip agents and antiblock additives across European film extrusion operations. ECHA evaluations of microplastic release from synthetic polymer films are elevating scrutiny of fragmentation behavior in marine environments. Converters serving German publishing houses are pre-certifying products to Blue Angel standards to secure long-term supply contracts.
Consolidated food processors are unbundling technical service contracts from film supply agreements, creating standalone revenue streams for equipment optimization and line-speed auditing. This procurement pattern is most visible in Vietnam and India where multinational CPG subsidiaries are centralizing flexible packaging specifications. Regional converters must now compete on aftermarket technical capability rather than rollstock pricing alone.
PP Laminating Films Market Segmentation
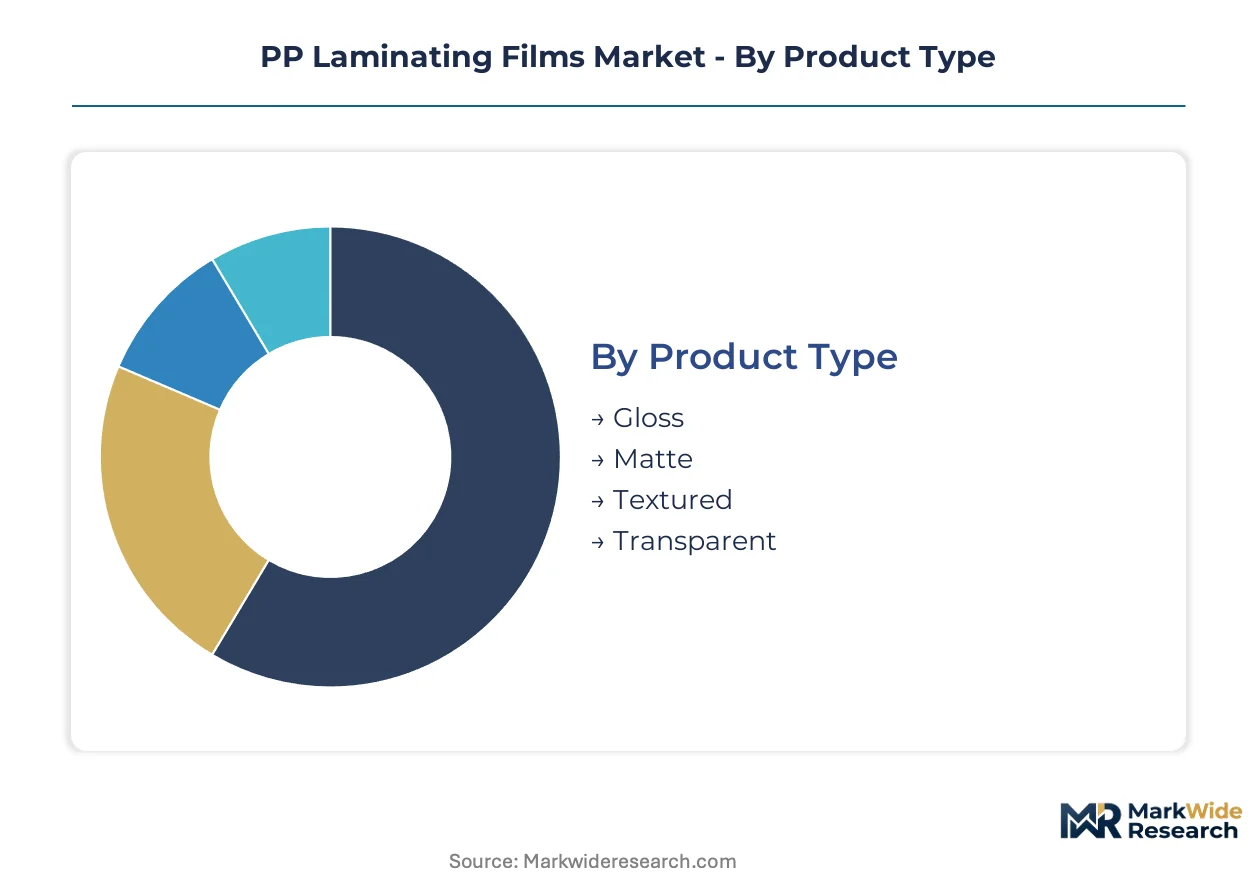
PP laminating films serve divergent technical requirements across food protection, visual communication, and industrial applications. Segment boundaries reflect trade-offs between barrier performance, optical properties, and converting economics that reshape procurement priorities.
Product Type:
Cost tier differentiation separates commodity gloss volumes from specialty matte and textured premiums.
- Gloss:High-clarity biaxially oriented surfaces maximize light reflectance for retail shelf impact. Frozen food processors in Vietnam and Thailand specify gloss laminates for vegetable pouches where moisture resistance and visual appeal converge.
- Matte:Diffused surface treatment reduces glare and enables tactile brand differentiation. Premium cosmetics houses in France and Germany are migrating folding cartons to matte PP constructions that satisfy Blue Angel pre-certification requirements.
- Textured:Embossed surface patterns deliver haptic engagement for luxury packaging segments.
- Transparent:Unmodified optical clarity serves windowed packaging and overlay applications.
Gloss holds installed capacity. Matte is rotating up the share rankings.
End User:
Application maturity spans established food protection to emerging textile lamination niches.
- Packaging:Flexible food pouches, folding cartons, and blister packs constitute the dominant demand pool. Southeast Asian converting lines are absorbing disproportionate capacity additions as regional processors adopt laminated structures for shelf-stable products.
- Publishing:Book covers, magazines, and educational materials require durability and handling resistance.
- Retail:Point-of-sale displays and promotional materials demand short-run flexibility with visual impact.
- Textile:Fabric backing and interlining applications exploit PP moisture barriers for outdoor and performance apparel.
Packaging commands the largest equipment footprint. Textile is climbing the fastest as technical textile investments accelerate.
Thickness:
Volume concentration centers on mid-range specifications that balance material cost with functional performance.
- 75 Micron:The broadest applicability across food and non-food flexible packaging. This specification dominates frozen food pouch formats where puncture resistance and low-temperature flexibility matter.
- 100 Micron:Displacing legacy PET constructions in North American frozen vegetable and ready-meal segments. Heavier gauge PP delivers equivalent barrier performance at improved recyclability under emerging extended producer responsibility frameworks.
- 50 Micron:Lightweight option for cost-sensitive publishing and label applications.
- 125 Micron:Maximum rigidity for heavy-duty industrial and export packaging requirements.
75 micron anchors current converting assets. 100 micron is expanding most quickly as mono-material designs gain regulatory preference.
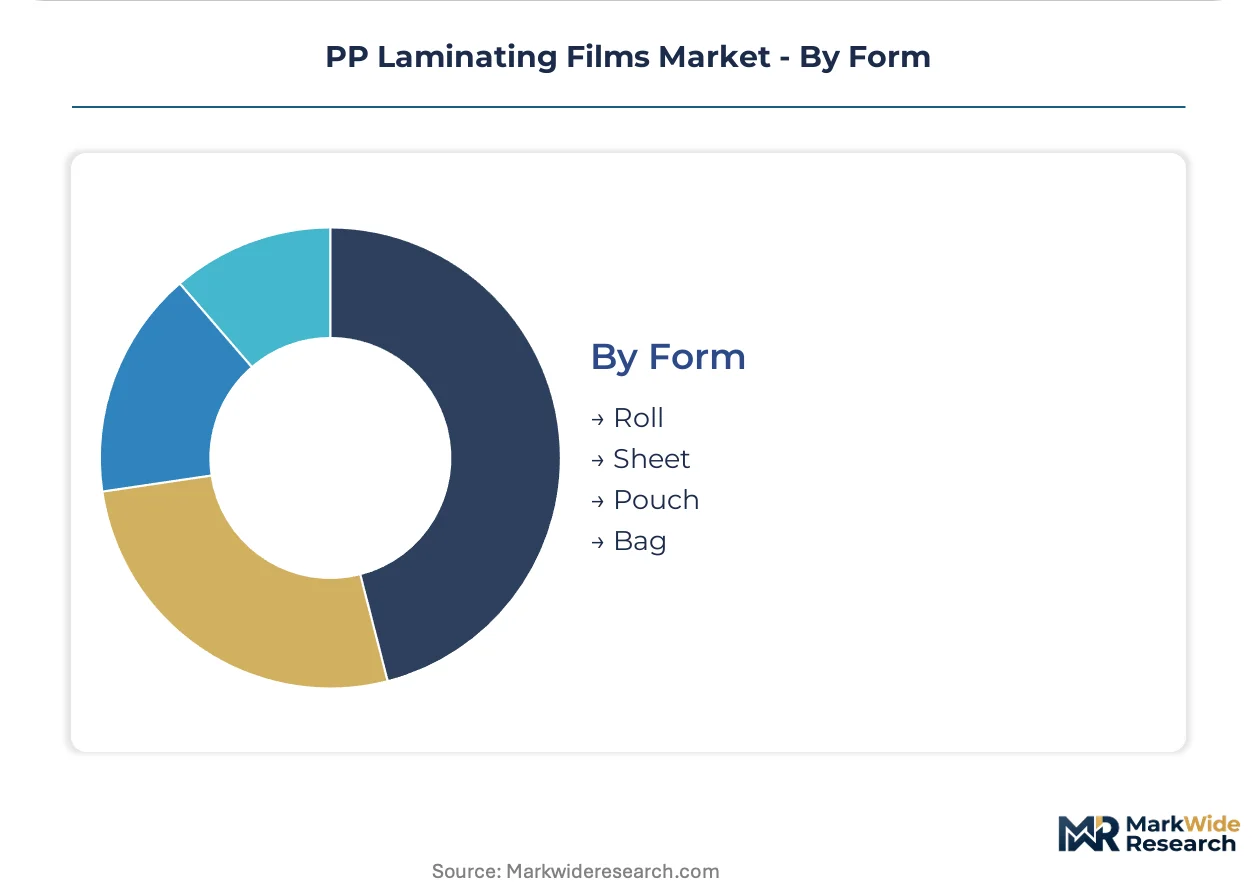
Form:
Supply chain configuration reflects downstream converting automation and handling requirements.
- Roll:Continuous web format enables high-speed lamination at 200–400 meters per minute on commercial converting lines. Roll supply dominates flexible packaging operations in India where integrated extrusion and metallization facilities cluster.
- Sheet:Cut-size formats serve sheet-fed offset and digital print workflows.
- Pouch:Pre-formed three-side-seal and stand-up configurations reduce downstream converting steps.
- Bag:Side-gusseted and flat-bottom constructions target bulk food and industrial powder containment.
Roll maintains the deepest installed base. Pouch is gaining share fastest as brand owners consolidate supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for PP laminating films varies sharply across geographies. Indian and Vietnamese converters absorb capacity on price-sensitive rollstock contracts, while German and French buyers prioritize certified mono-material constructions despite 15-20% premiums.
India
Flexible food packaging expansion in Gujarat and Maharashtra drives disproportionate capacity absorption. The Bureau of Indian Standards enforces stricter food-contact substrate rules under FSSAI alignment. Integrated BOPP extrusion and metallization clusters in Vapi and Silvassa capture export orders to Middle Eastern markets.
Germany
Cosmetics houses specify Blue Angel pre-certified matte laminates for folding cartons. ECHA REACH SVHC expansions force slip-agent reformulations across film extrusion operations. The Rhine-Ruhr industrial corridor hosts chemical recycling pilot plants processing contaminated PP laminates via pyrolysis.
Vietnam
Multinational CPG subsidiaries centralize flexible packaging specifications for shelf-stable seafood and instant noodle pouches. The Ministry of Industry and Trade implements extended producer responsibility pilots in Ho Chi Minh City. Converting lines in Binh Duong province absorb technical service contracts unbundled from film supply agreements.
United States
Frozen food processors in Wisconsin and California displace legacy PET with 100 micron PP grades for low-temperature flexibility. FDA 21 CFR food-contact notification timelines stretch 18-24 months for novel coextrusion layers. State-level EPR laws in California and New York elevate compliance documentation burdens for laminate suppliers.
China
State-subsidized BOPP capacity additions in Shandong and Zhejiang provinces compress export pricing power for non-integrated converters. The Ministry of Ecology and Environment tightens emissions standards for solvent-based adhesive lamination. Yangtze River Delta clusters pivot toward water-based barrier coatings for domestic cosmetics brands.
PP Laminating Films Market Competitive Landscape
Capability concentration sits with integrated film-and-converting specialists; scale advantage sits with diversified packaging conglomerates. The vendor base separates into three tiers: global converters with captive resin positions, regional rollstock specialists with metallization depth, and equipment-anchored service providers. Dominant competitive moves include backward integration into BOPP extrusion and unbundling of technical service contracts from commodity supply agreements.
Within the integrated specialist tier, Cosmo Films and UFLEX Limited exemplify geographic anchoring strategies. Cosmo Films occupies a position as a South Asian supply anchor through combined BOPP film and metallization capabilities. UFLEX Limited represents the cost-optimized rollstock archetype targeting flexible packaging export markets. Amcor plc sits within the global diversified tier, leveraging worldwide converting footprints to sustain premium positioning in high-barrier laminates.
| Leading Market Players |
|---|
| Amcor plc |
| Cosmo Films |
| Mondi plc |
| UFLEX Limited |
| Taghleef Industries |
| Polyplex Corporation |
| Constantia Flexibles |
| Berry Global Group |
| DuPont |
| Others |
Value Network & Pricing Analysis
Chinese state-subsidized BOPP capacity additions in Shandong and Zhejiang provinces feed directly into margin compression for non-integrated converters in India and Vietnam. This upstream concentration shifts value capture toward aftermarket technical service contracts and metallization capabilities rather than commodity rollstock.
Pricing Analysis
Aftermarket technical service revenue for film converting equipment now drives lifetime value more than initial rollstock sales. Three-tier pricing structure across premium certified mono-materials, standard multilayer laminates, and economy gloss films separates buyers by compliance requirements. Cost compression in standard grades is intensifying because Chinese export pricing power limits regional converter margins. Brand owners in Germany and France show least price sensitivity, absorbing 15-20% premiums for Blue Angel pre-certified matte constructions.
Supply Chain Analysis
Tariff exposure between China and Southeast Asian converting hubs dominates supply chain risk calculus for non-integrated buyers. Propylene feedstock draws from naphtha-cracking operations in China, South Korea, and Singapore, with film extrusion clustered in Shandong province, Vapi-Silvassa corridor, and Binh Duong province. Single-source vulnerability sits with vacuum metallization equipment suppliers serving barrier coating operations. Distribution runs through integrated converter-direct contracts for multinational CPG subsidiaries, bypassing traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU circularity mandates are accelerating mono-material PP displacement of legacy multilayer constructions, creating a high-growth disruption window for certified converters. This regulatory inflection compresses incumbent asset values while elevating specialized metallization and chemical recycling capabilities.
For Market Incumbents: Build certification moats around Blue Angel and FDA food-contact notification expertise to defend against commodity rollstock erosion. Anchor capacity additions in Gujarat and Maharashtra to capture Indian flexible packaging expansion. Prioritize solventless adhesive lamination R&D to meet REACH SVHC restrictions.
For New Entrants and Emerging Players: Build out water-based barrier coating capabilities for French and German cosmetics brands seeking matte-finish alternatives to metallized films. Target Vietnam's unbundled technical service contracts as the most penetrable entry point. Lead with line-speed auditing and equipment optimization expertise rather than price-competitive rollstock.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional converters lacking integrated BOPP extrusion. Five-to-ten-year viability hinges on chemical recycling offtake agreements with Netherlands and Germany pyrolysis facilities. Watch for FDA 21 CFR notification backlog clearance as signal for improved barrier construction commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into BOPP Extrusion | Captures propylene margin and insulates against Chinese overcapacity pricing. |
| Blue Angel Pre-Certification Investment | Locks in German cosmetics house supply contracts ahead of REACH SVHC expansions. |
| Chemical Recycling Offtake Agreement | Creates disposal pathway for contaminated laminates under EU Packaging Waste Regulation. |
| Water-Based Barrier Coating Scale-Up | Eliminates aluminum deposition steps for French matte-finish folding carton demand. |
| Technical Service Contract Unbundling | Captures standalone revenue from Vietnam-based multinational CPG subsidiaries. |
Research Methodology
A standing panel of film extrusion plant managers, flexible packaging procurement leads at multinational CPG subsidiaries, metallization equipment specialists, and aftermarket service technicians provided ongoing calibration. Primary interview insights combined with secondary validation from customs trade data, Bureau of Indian Standards filings, ECHA REACH substance restriction updates, and SEC disclosures from listed packaging conglomerates. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Scenario-bracketing anchored projections across low, base, and high cases reflecting propylene feedstock volatility and circularity mandate enforcement intensity. Segmentation dimensions modeled include product finish type, end-use application, thickness specification, supply form, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating frozen food pouch conversion rates and metallization technology maturation curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-subsidized producers or accelerated chemical recycling buildout in the Rhine-Ruhr corridor would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Tube Laminating Films Market
Poly film
Global Reclosable Films Market
Poly film
Peelable and Resealable Films Market
Poly film
Wrap Around Label Films Market
Poly film
United Kingdom Plastic Packaging Films Market
Poly film
Latin America Plastic Packaging Films Market
Poly film
Indonesia Plastic Packaging Films Market
Poly film
Stretch Films Packs Market
Poly film
Poly Coated Kraft Paper Market
Poly film
France Plastic Packaging Films Market
Poly film
Polyethylene Furanoate Films Market
Poly film
Canada Plastic Packaging Films Market
Poly film
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Lidding Films Market
Poly film
Easy Peel Film Packaging Market
Poly film
Japan Polypropylene Packaging Films Market