
 Middle East and Africa Plastic Packaging Films Market | 2026-2036
Middle East and Africa Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Plastic Packaging Films Market Insights
Project finance tied to petrochemical downstream integration is fragmenting competitive access across the Middle East and Africa Plastic Packaging Films Market. Amcor Group GmbH leverages its regional converting footprint to sustain long-term supply agreements with Gulf-based resin producers. Berry Global Inc. anchors its position through backward integration into polyethylene resin streams. Aalmir Plastic Industries competes on specialized shrink film formulations for ambient temperature distribution networks.
Middle East and Africa plastic packaging films are multilayer polymer constructions, typically 12 to 150 microns in caliper, manufactured through blown or cast extrusion processes to provide moisture vapor transmission control, oxygen barrier, and mechanical protection for packaged goods. Stretch film dominates volume throughput across regional logistics hubs where palletized unitization drives consumption. Barrier film commands premium positioning in pharmaceutical end-use applications where moisture and gas permeability specifications determine product shelf stability. Shrink film occupies growing share in consumer goods retail presentation formats across North African markets.
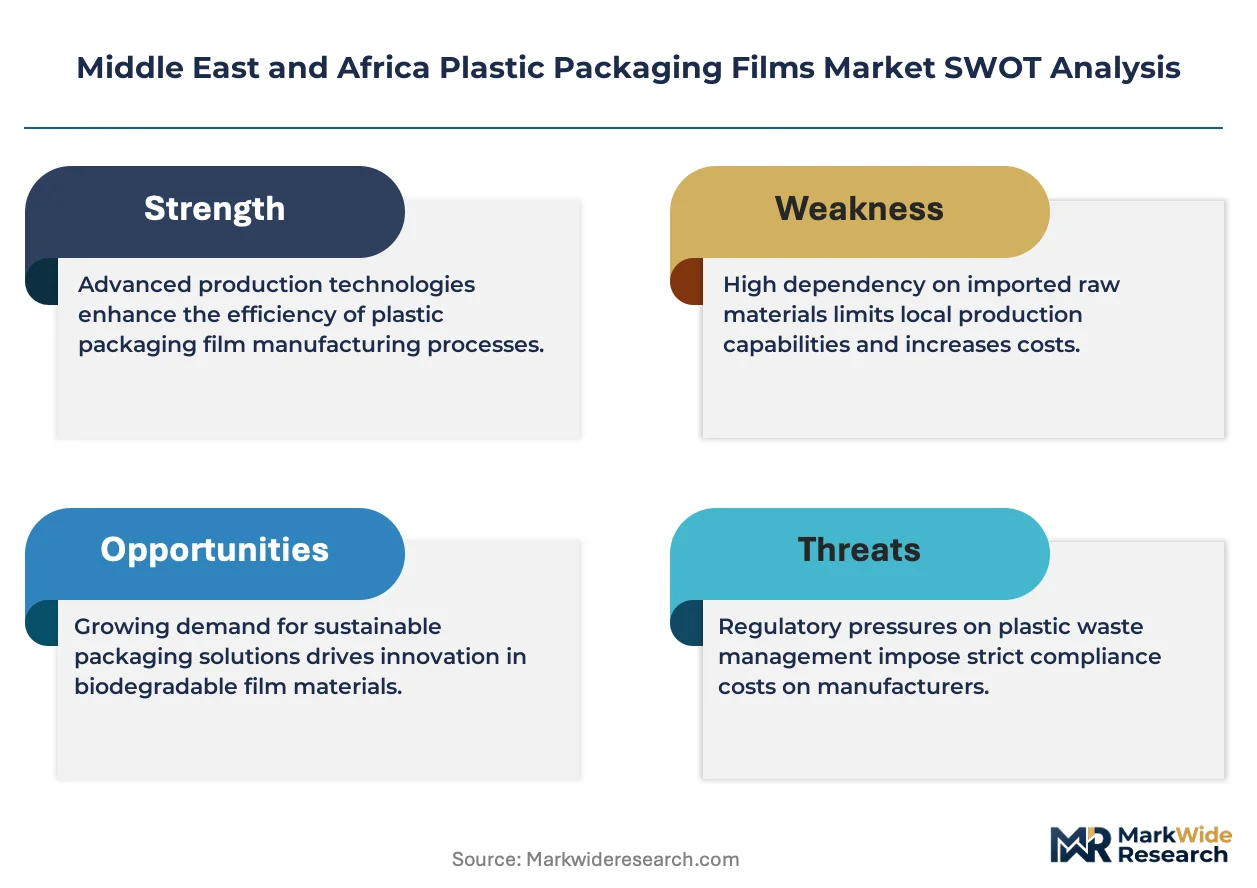
SASO in Saudi Arabia, ESMA in the United Arab Emirates, and NAFDAC in Nigeria collectively shape compliance architecture for food-contact and pharmaceutical-grade films through divergent testing protocols and migration limit standards. The EU Green Deal's extraterritorial reach into export-oriented African converters is forcing material formulation shifts away from certain additive packages. Stakeholders must monitor regulatory misalignment between Gulf harmonization initiatives and sub-Saharan national standards as a determinant of cross-border manufacturing investment viability.
Market Dynamics
Project finance tied to petrochemical downstream integration is fragmenting competitive access across the Middle East and Africa Plastic Packaging Films Market. Gulf-based resin producers are leveraging captive feedstock positions to dictate long-term supply terms, while sub-Saharan converters face working capital constraints that limit participation in premium barrier film segments.
Growth Catalysts
- Cold-chain packaging programs:Food and beverage producers across the Gulf Cooperation Council are expanding refrigerated distribution networks, driving multilayer barrier film specifications for temperature-sensitive goods.
- SASO technical regulations:Saudi Arabia's tightening compliance requirements for food-contact materials are accelerating quality upgrades among domestic converters and creating import substitution opportunities.
- Lagos-Ibadan manufacturing corridor:Consumer goods processors in Nigeria are localizing supply chains, concentrating stretch and shrink film demand in West Africa's most active industrial zone.
Market Restraints
- Ethylene feedstock volatility:Regional resin pricing tracks naphtha and ethane differentials that swing with crude oil benchmarks, compressing converter margins unpredictably.
- Gulf producer concentration:Five integrated petrochemical complexes control over two-thirds of polyethylene resin supply into the region, limiting buyer negotiating leverage.
- NAFDAC migration testing delays:Nigeria's national food and drug regulator requires extended laboratory validation for imported film grades, extending certification timelines by four to eight months.
Strategic Opportunities
- Pharmaceutical barrier films:Moisture and gas permeability specifications in Egypt's expanding generic drug export sector are creating premium positioning for specialized coextruded constructions.
- EU Green Deal extraterritorial compliance:Export-oriented African converters are reformulating additive packages to meet European sustainability thresholds, opening technical service revenue streams.
- E-commerce fulfillment packaging:Last-mile delivery expansion in Kenya and Morocco is generating demand for lightweight, high-clarity shrink films optimized for automated sortation systems.
Industry Challenges
- Multilayer coextrusion expertise:Seven-layer blown film capability remains concentrated among Gulf-based producers, constraining sub-Saharan converters to commodity-grade output.
- ESMA certification complexity:The United Arab Emirates' Emirates Authority for Standardization and Metrology maintains divergent testing protocols from Saudi SASO, forcing dual-track compliance investments.
- Legacy equipment retrofit costs:Cast film lines predating 2015 lack precision gauge control required for pharmaceutical-grade specifications, requiring capital outlays that exceed regional bank lending appetite.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Plastic Packaging Films Market |
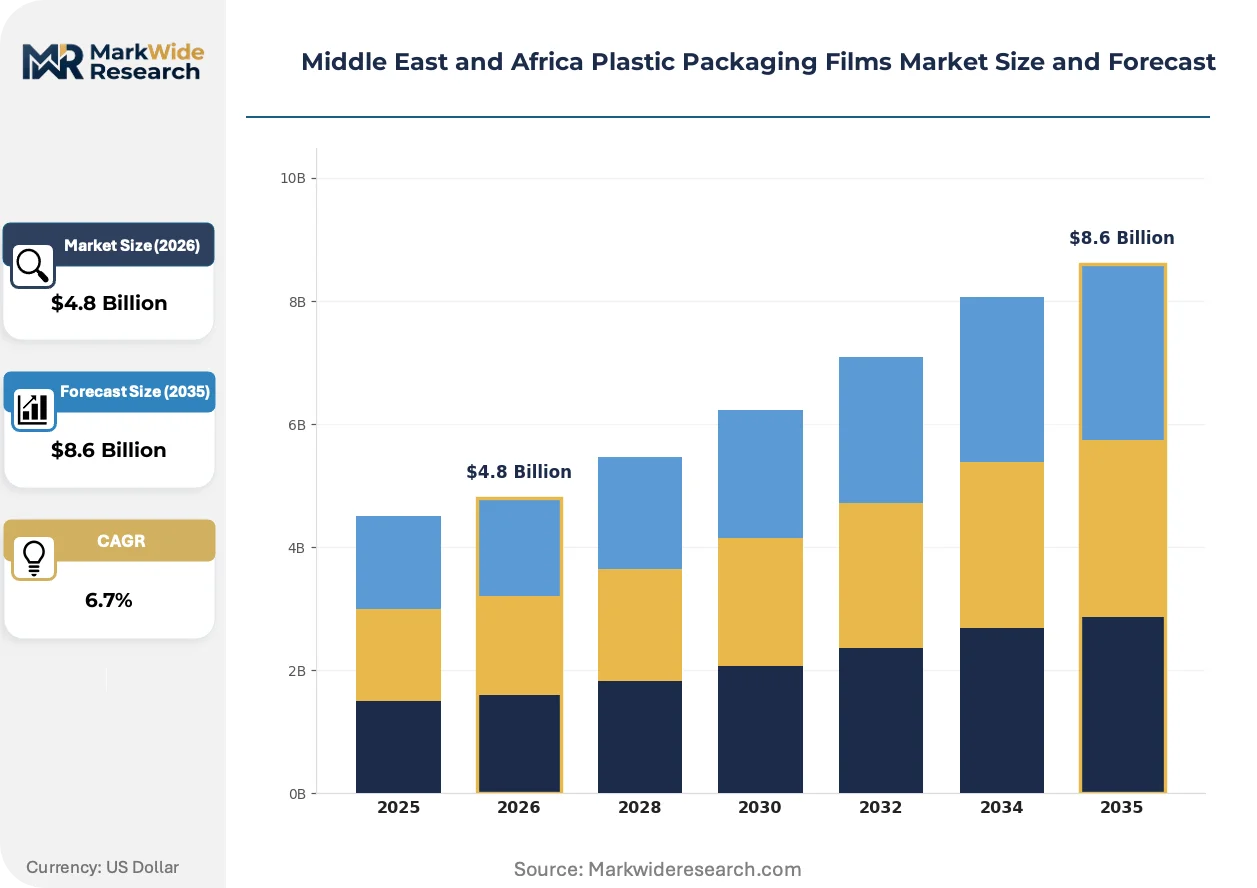
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Film, Shrink Film, Barrier Film, Rigid Film End User: Food & Beverage, Pharmaceuticals, Personal Care, Consumer Goods Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polyester Thickness: Thin Film, Medium Film, Thick Film, Ultra-Thin Film |
| Companies Covered | Amcor Group GmbH, Berry Global Inc., Aalmir Plastic Industries, 3P Gulf Group, Amber Packaging Industries LLC, Falcon Pack, Arabian Plastic Industrial Company Limited (APICO), Takween Advanced Industries, Interplast (Harwal Group of Companies), Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Plastic Packaging Films Market Trends and Innovations
Digital process control systems are virtualizing quality assurance workflows across regional converting operations. This shift is compressing batch-to-batch variation while enabling real-time specification adjustments that previously required manual intervention.
Machine vision inspection systems paired with AI-driven defect classification are virtualizing traditional manual quality checkpoints. Pharmaceutical film producers in Egypt and South Africa are deploying these systems fastest, cutting offline laboratory sampling by half while compressing release-to-ship timelines from days to hours. The technology is virtualizing the role of experienced shift supervisors, reducing reliance on tacit knowledge in high-turnover production environments.
Saudi SASO's 2024 updates to food-contact material technical regulations are mandating specific migration limits for heavy metals and primary aromatic amines. Domestic converters are reformulating masterbatch additive packages to comply, while importers face enhanced documentary evidence requirements at Gulf ports. The pharmaceutical segment is responding fastest, with several manufacturers accelerating transitions to pre-qualified resin grades that satisfy both SASO and EU regulatory thresholds.
Consolidated procurement by multinational consumer goods processors is replacing fragmented distributor purchasing across North African markets. Nestlé and Unilever regional hubs in Morocco and Egypt are centralizing film specifications and awarding multi-year contracts to converters with integrated resin supply. This concentration is most visible in the stretch film category, where palletization standardization is eliminating small-batch custom orders that previously sustained mid-tier regional players.
Middle East and Africa Plastic Packaging Films Market Segmentation
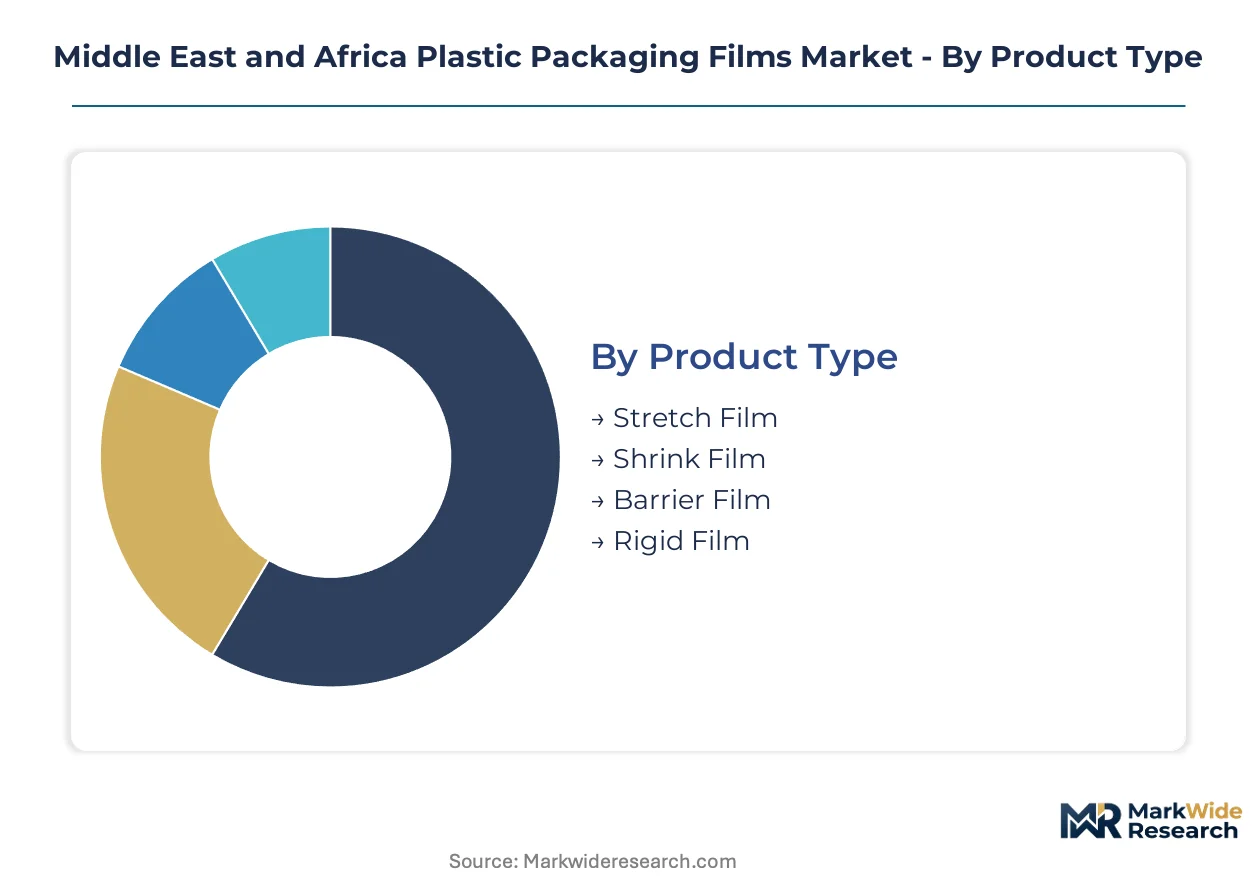
Segmentation in the Middle East and Africa Plastic Packaging Films Market reveals distinct procurement cycles and margin structures. Converters align production capacity to thickness and material specifications that match regional logistics infrastructure and regulatory compliance tiers.
Product Type:
Stretch film turns inventory fastest through palletization demand across Gulf logistics hubs, while barrier film sits longest in qualification cycles for pharmaceutical applications.
- Stretch Film:Linear low-density polyethylene formulations dominate, engineered for load containment and puncture resistance. Demand concentrates in Saudi Arabia's Jeddah Islamic Port and UAE's Jebel Ali Free Zone where containerized freight unitization drives volume. Cold-chain expansion across the Gulf Cooperation Council is accelerating specifications for high-clarity grades that support barcode scanning.
- Barrier Film:Multilayer coextrusions incorporating ethylene vinyl alcohol or polyamide layers control moisture and oxygen transmission. Egypt's generic pharmaceutical export sector is concentrating demand for specialized constructions that meet EU and SASO dual compliance. Migration testing protocols at Saudi ports extend certification timelines, favoring pre-qualified domestic converters.
- Shrink Film:Biaxially oriented constructions provide retail presentation and tamper evidence for consumer goods. Nigerian distributors in the Lagos-Ibadan corridor are localizing procurement for ambient temperature distribution networks.
- Rigid Film:Thermoformable sheets serve blister packaging and food tray applications. South Africa's pharmaceutical packaging cluster sustains specialized demand for high-impact polystyrene alternatives.
Stretch film dominates installed base. Barrier film is where expansion concentrates.
End User:
Customer procurement patterns split between multinational volume contracts and fragmented local processor spot purchasing.
- Food & Beverage:Multilayer laminations for modified atmosphere packaging protect perishables through extended distribution chains. Saudi Arabia's SASO technical regulations for food-contact materials are forcing reformulation of additive packages among imported film grades.
- Pharmaceuticals:Moisture vapor transmission rate specifications below 0.5 g/m²/day define premium positioning. Egypt's export-oriented generic drug manufacturers are qualifying specialized coextruded constructions for European market access.
- Personal Care:High-clarity films with enhanced printability support brand differentiation on retail shelves. Moroccan converters are capturing regional demand through proximity to Nestlé and Unilever North African hubs.
- Consumer Goods:Shrink and stretch configurations dominate e-commerce fulfillment packaging. Kenya's last-mile delivery expansion is generating demand for lightweight films optimized for automated sortation systems.
Food and beverage anchors volume throughput. Pharmaceuticals command the steepest expansion trajectory.
Material:
Resin selection tracks feedstock access and recycling infrastructure maturity across the region.
- Polyethylene:Low-density and linear low-density grades constitute the volume backbone. Gulf-based petrochemical complexes with captive ethane feedstock dictate regional pricing and supply security terms.
- Polypropylene:Cast and oriented constructions provide stiffness and heat resistance for retort and microwave applications. South Africa's polymer conversion sector sustains specialized demand for clarified random copolymer grades.
- Polyvinyl Chloride:Plasticized formulations serve medical device packaging and shrink sleeve applications. EU Green Deal restrictions on certain plasticizer chemistries are forcing additive reformulation among export-oriented African converters.
- Polyester:Biaxially oriented polyethylene terephthalate delivers optical clarity and dimensional stability. Egypt's pharmaceutical film producers are deploying this material for high-visibility blister lidding.
Polyethylene dominates installed base. Polypropylene is gaining share fastest in premium food packaging.
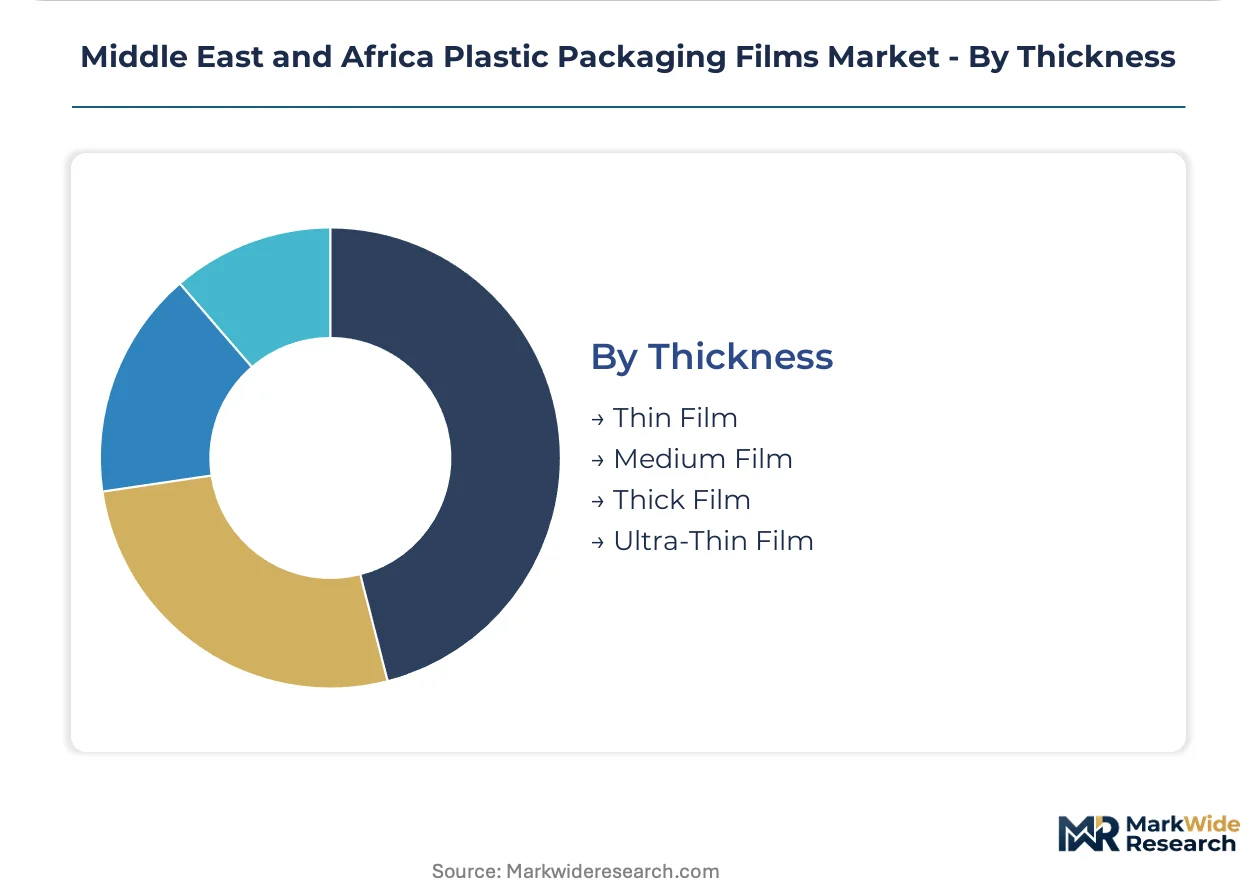
Thickness:
Caliper specifications correlate with mechanical performance requirements and resin cost optimization.
- Thin Film:12-30 micron constructions minimize material cost in high-volume stretch and overwrap applications. Nigerian consumer goods processors are specifying these grades for cost-sensitive ambient distribution.
- Medium Film:30-80 micron range balances puncture resistance and material efficiency. Saudi cold-chain programs are standardizing on multilayer medium caliper barrier constructions for temperature-sensitive proteins.
- Thick Film:80-150 micron specifications serve heavy-duty industrial bundling and deep-draw thermoforming. UAE logistics hubs are specifying these grades for export palletization of construction materials.
- Ultra-Thin Film:Sub-12 micron downgauging trials target resin reduction in compliant food-contact applications. Technical feasibility remains constrained by SASO migration testing validation protocols.
Medium film dominates installed base. Ultra-thin film is where technical development concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational consumer goods processors concentrate procurement through regional hubs, while local converters compete on proximity to manufacturing corridors. Gulf petrochemical complexes supply resin on captive terms, creating divergent cost structures across sub-Saharan markets.
Saudi Arabia
Cold-chain packaging programs for temperature-sensitive proteins and dairy products are expanding through Jeddah Islamic Port logistics hubs. SASO technical regulations for food-contact materials mandate specific migration limits for heavy metals and primary aromatic amines. Riyadh-based converters are upgrading multilayer coextrusion capabilities to serve domestic food processors replacing imported film grades.
United Arab Emirates
Jebel Ali Free Zone containerized freight unitization drives stretch film consumption for palletized export cargo. ESMA maintains divergent testing protocols from Saudi SASO, forcing dual-track compliance investments among regional suppliers. Dubai converters are capturing pharmaceutical film demand from GCC generic drug distributors seeking regional supply security.
Egypt
Generic pharmaceutical export manufacturers are qualifying specialized barrier film constructions for European market access. The country's national pharmaceutical regulator aligns migration testing with EU thresholds for moisture vapor transmission specifications. Cairo-Alexandria industrial corridor producers are deploying machine vision inspection systems to compress release-to-ship timelines.
Nigeria
Consumer goods processors in the Lagos-Ibadan manufacturing corridor are localizing stretch and shrink film procurement for ambient temperature distribution networks. NAFDAC requires extended laboratory validation for imported film grades, extending certification timelines by four to eight months. Domestic converters are capturing share from distributors previously sourcing from Gulf suppliers.
South Africa
Pharmaceutical packaging clusters sustain specialized demand for high-impact polystyrene alternatives in blister and thermoform applications. The country's national standards body maintains certification requirements for food-contact materials that track EU regulatory evolution. Gauteng-based producers are reformulating additive packages to meet EU Green Deal sustainability thresholds for export-oriented production.
Middle East and Africa Plastic Packaging Films Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. Gulf-based resin producers leverage captive feedstock positions to dictate long-term supply terms, while sub-Saharan converters face working capital constraints that limit participation in premium barrier film segments. Three archetypes dominate: integrated petrochemical downstream operators with resin security, regional converters with multilayer coextrusion expertise, and specialized niche players serving pharmaceutical qualification requirements. Competitive moves concentrate on backward integration into polyethylene resin streams and geographic expansion through Jebel Ali and Lagos-Ibadan corridor positioning.
Among Gulf-based integrated operators, Amcor Group GmbH and Berry Global Inc. exemplify the resin-secured archetype through regional converting footprints and captive supply arrangements. Aalmir Plastic Industries occupies a specialist position serving ambient distribution networks with formulated shrink film constructions. These three entities represent distinct competitive vectors: multinational scale with supply security, multinational scale with backward integration, and regional specialization with formulation expertise.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Berry Global Inc. |
| Aalmir Plastic Industries |
| 3P Gulf Group |
| Amber Packaging Industries LLC |
| Falcon Pack |
| Arabian Plastic Industrial Company Limited (APICO) |
| Takween Advanced Industries |
| Interplast (Harwal Group of Companies) |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Gulf-based polyethylene resin production is compressing converter margins while simultaneously extending supplier payment terms for sub-Saharan buyers. This utilization imbalance grants Saudi and UAE petrochemical complexes outsized pricing power over downstream film converters in Nigeria and Egypt.
Pricing Analysis
Cost-plus contracts indexed to naphtha and ethane differentials dominate resin procurement across the Middle East and Africa Plastic Packaging Films Market. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade barrier films with SASO pre-qualification from commodity stretch grades and generic shrink formulations. Pricing pressure stems from ethane feedstock volatility tracking crude benchmarks, which unpredictably squeezes converter margins. Nigerian consumer goods processors exhibit highest price sensitivity due to working capital constraints, while Egyptian pharmaceutical exporters accept premium positioning for EU-compliant barrier specifications.
Supply Chain Analysis
Tariff exposure between Gulf Cooperation Council members and sub-Saharan African markets dominates supply chain risk assessment for regional converters. Resin supply concentrates in Saudi Arabia, the United Arab Emirates, and Qatar, where integrated petrochemical complexes control captive ethane feedstock. Raw material dependencies rest on polyethylene resin grades, ethylene vinyl alcohol barrier layers, and specialized masterbatch additive packages. Single-source vulnerability pervades seven-layer coextrusion equipment, which remains concentrated among Gulf-based producers. Distribution runs through Jebel Ali Free Zone for re-export cargo and Lagos-Ibadan corridor for West African last-mile fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SASO's 2024 technical regulation updates constitute a regulatory inflection that will displace non-compliant imported film grades across Saudi Arabia's food-contact segment. This disruption creates asymmetric opportunity for domestic converters with pre-qualified resin supply arrangements.
For Market Incumbents: Insulate market position by accelerating backward integration into polyethylene resin streams and securing captive feedstock arrangements with Gulf petrochemical producers. Invest in seven-layer coextrusion capability to defend against emerging Egyptian and South African pharmaceutical film specialists. Prioritize dual-track SASO and ESMA certification to maintain cross-border supply flexibility.
For New Entrants and Emerging Players: Establish a beachhead in Nigeria's Lagos-Ibadan corridor by offering localized stretch and shrink film production with NAFDAC pre-certification. Target ambient temperature distribution networks where import substitution demand is accelerating due to extended certification timelines for Gulf-sourced grades. Deploy technical service capabilities to support consumer goods processors reformulating packaging for localized supply chains.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical barrier film segments due to machine vision inspection and multilayer coextrusion equipment requirements. Acquisition targets should display specialized coextrusion expertise with existing EU regulatory qualification. Monitor NAFDAC certification timeline compression as the signal indicating inflection in Nigerian import substitution viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive ethane feedstock access secures margin stability against naphtha price volatility. |
| Dual SASO-ESMA Certification Investment | Cross-border supply flexibility protects revenue across Saudi and UAE market boundaries. |
| Machine Vision Quality Systems Deployment | AI-driven defect classification compresses pharmaceutical film release-to-ship timelines. |
| NAFDAC Pre-Certification Program | Extended validation timelines for imports create four-to-eight month competitive moat. |
| Seven-Layer Coextrusion Capacity Addition | Barrier film expertise commands premium positioning in Egypt's generic drug export sector. |
Research Methodology
Desk research of customs trade databases, petrochemical producer disclosures, and national regulator technical guidance preceded structured interviews with plant managers at Gulf-based converting operations, procurement leads at Nigerian consumer goods processors, regulatory affairs specialists at Egyptian pharmaceutical manufacturers, and distribution channel partners across Jebel Ali Free Zone. Bottom-up capacity and utilization estimates were triangulated against top-down resin consumption figures from regional petrochemical associations.
Assumptions regarding SASO regulatory implementation timelines, ethane feedstock cost differentials, and NAFDAC certification processing durations were held fixed across baseline scenarios while stress-testing sensitivity to crude oil price bands and cold-chain infrastructure investment rates. Segmentation modeling incorporated product type, end-use industry, material specification, and thickness caliper dimensions. CAGRs were derived from regression analysis of historical resin consumption against industrial output indices.
Stress conditions across ethane-naphtha spreads, regulatory enforcement intensity, and sub-Saharan logistics cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and could revise substantially upon shifts in Gulf petrochemical capacity utilization or migration testing protocol harmonization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polyethylene Terephthalate (PET) Shrink Films Market
Poly film
Light Reflective Film Market
Poly film
Blown Film Extruder Market
Poly film
Polyethylene Film Market
Poly film
Bundling Film Market
Poly film
MDO-PE Films Market
Poly film
Italy Plastic Packaging Films Market
Poly film
Spain Plastic Packaging Films Market
Poly film
Canada Plastic Packaging Films Market
Poly film
Biaxially Oriented Polyamide (BOPA) Films Market
Poly film
Hexacomb Packaging Market
Poly film
China BOPP Film Market
Poly film
Global Fluoropolymer Films Market
Poly film
Germany Plastic Packaging Films Market
Poly film
Global PVDC Coated Films Market
Poly film
APET Film Market