
 Anti Fog Polycarbonate Films and Sheets Market | 2026-2036
Anti Fog Polycarbonate Films and Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Anti Fog Polycarbonate Films and Sheets Market Intelligence
Distribution through specialized industrial wholesalers is fragmenting as original equipment manufacturers pursue direct sourcing agreements for critical components. This shift favors large-scale producers with established global logistics. SABIC leverages its immense polycarbonate production capacity to serve high-volume automotive and electronics contracts directly. Covestro differentiates with its portfolio of advanced coating technologies for high-performance applications, while 3M competes on the strength of its integrated film and adhesive systems.
Anti-fog polycarbonate films and sheets are thermoplastic polymers treated with a hydrophilic surface coating to prevent condensation and maintain optical clarity. The coating works by causing water droplets to spread into a thin, transparent layer rather than forming view-obscuring fog. Within applications, the automotive sector's demand for head-up displays and sensor covers drives significant volume. Sheets, used in more demanding structural applications like machine guards and visors, typically offer higher value capture compared to thinner films used in packaging or electronics.
Market access is shaped by end-use industry standards, including material compliance for medical devices under the US FDA and EU MDR. In automotive, material performance is critical for components related to safety systems evaluated by programs like Euro NCAP. Furthermore, chemical substances used in coatings must adhere to regulations like the EU's REACH framework. Future competition will hinge on developing multi-functional materials that integrate anti-scratch and UV-blocking capabilities alongside anti-fog performance.
Market Dynamics
The central force shaping the market is the disintermediation of traditional distribution channels. Original equipment manufacturers in the automotive and electronics sectors are increasingly bypassing industrial wholesalers to establish direct sourcing contracts with large-scale film and sheet producers, consolidating the supply base.
Growth Catalysts
- Automotive Safety Mandates:The push for higher vehicle safety ratings from bodies like Euro NCAP drives adoption in ADAS sensor covers and head-up displays, where optical clarity is non-negotiable for system reliability.
- Medical Device Standards:Material compliance requirements under the US FDA and EU MDR for devices like surgical face shields, incubators, and diagnostic equipment create demand for certified, high-performance anti-fog materials.
- Multi-Functional Material Demand:End-users in industrial and consumer electronics seek integrated solutions, spurring development of films that combine anti-fog properties with anti-scratch, anti-glare, or UV-blocking capabilities in a single product.
Market Restraints
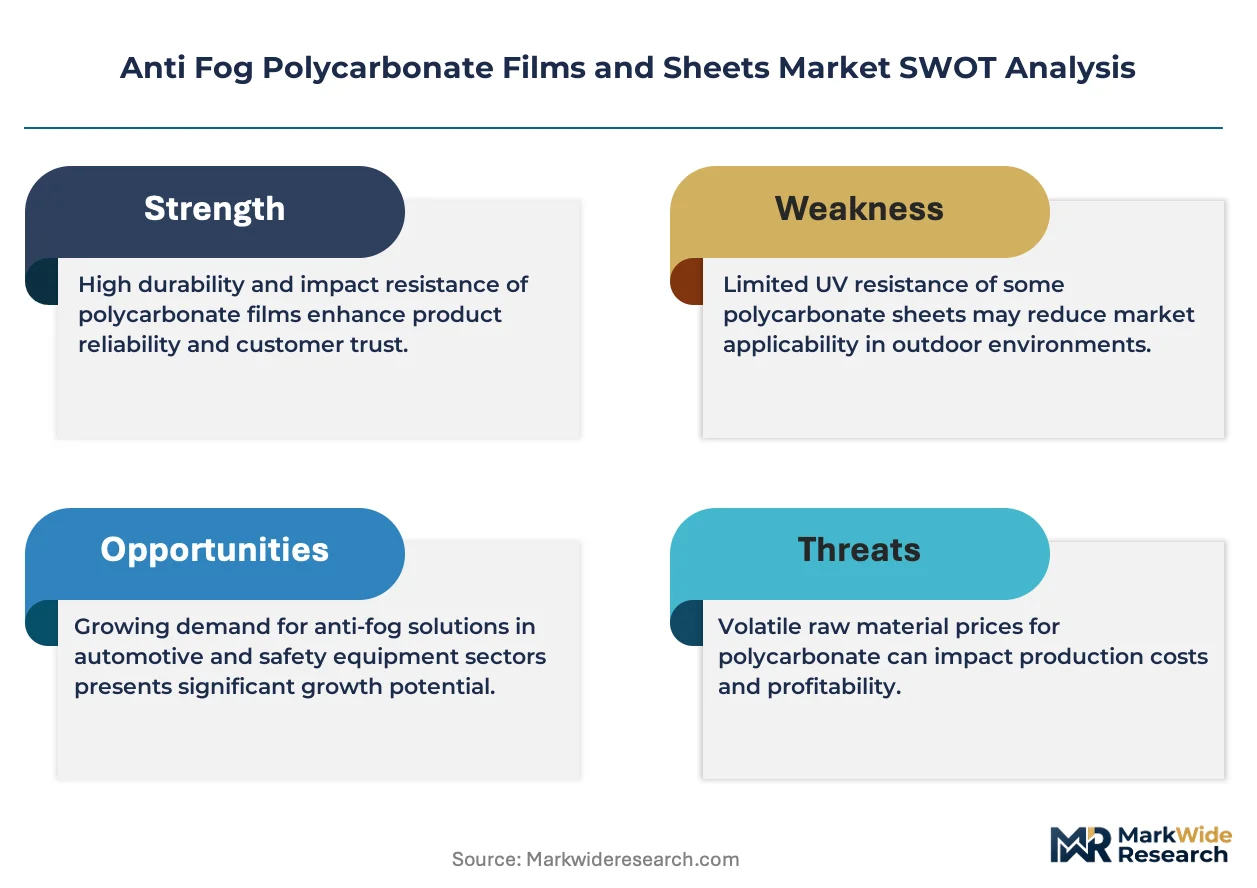
- Raw Material Price Volatility:Polycarbonate is derived from petrochemical feedstocks like Bisphenol A (BPA), making film and sheet prices susceptible to fluctuations in crude oil and chemical precursor markets, impacting production cost stability.
- Threat from Substitute Materials:Alternative polymers such as treated acrylic (PMMA) or coated PET films can offer competitive anti-fog performance in less demanding applications, posing a substitution risk, particularly in cost-sensitive segments.
- Coating Durability Limitations:The hydrophilic surface coatings that provide anti-fog properties can be vulnerable to degradation from abrasion, harsh cleaning chemicals, and prolonged UV exposure, limiting the product's effective lifespan in harsh environments.
Strategic Opportunities
- Emerging Wearable Technology:The expansion of augmented reality (AR) and virtual reality (VR) headsets, along with smart glasses, opens a significant new application category where preventing lens fogging is critical for user experience.
- Advanced Coating Integration:There is an opportunity to develop next-generation films that converge anti-fog functionality with other advanced properties like self-healing surfaces or embedded anti-microbial agents for medical and high-touch applications.
- Expansion in New Automotive Hubs:As automotive production grows in countries like Mexico, India, and across Eastern Europe, there is an opportunity to establish supply chains to serve these expanding manufacturing ecosystems directly.
Industry Challenges
- Complex Chemical Compliance:Manufacturers must navigate a complex web of chemical regulations, such as the EU's REACH framework, which governs the substances used in anti-fog coatings and can necessitate costly reformulations.
- Process Scalability and Uniformity:Achieving consistent, defect-free hydrophilic coating application across large-format polycarbonate sheets and high-speed film roll production is a significant technical and capital investment challenge.
- Intellectual Property Protection:Protecting proprietary coating formulations and application processes from imitation is a constant challenge, particularly in a market with increasing pressure from lower-cost regional competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti Fog Polycarbonate Films and Sheets Market |
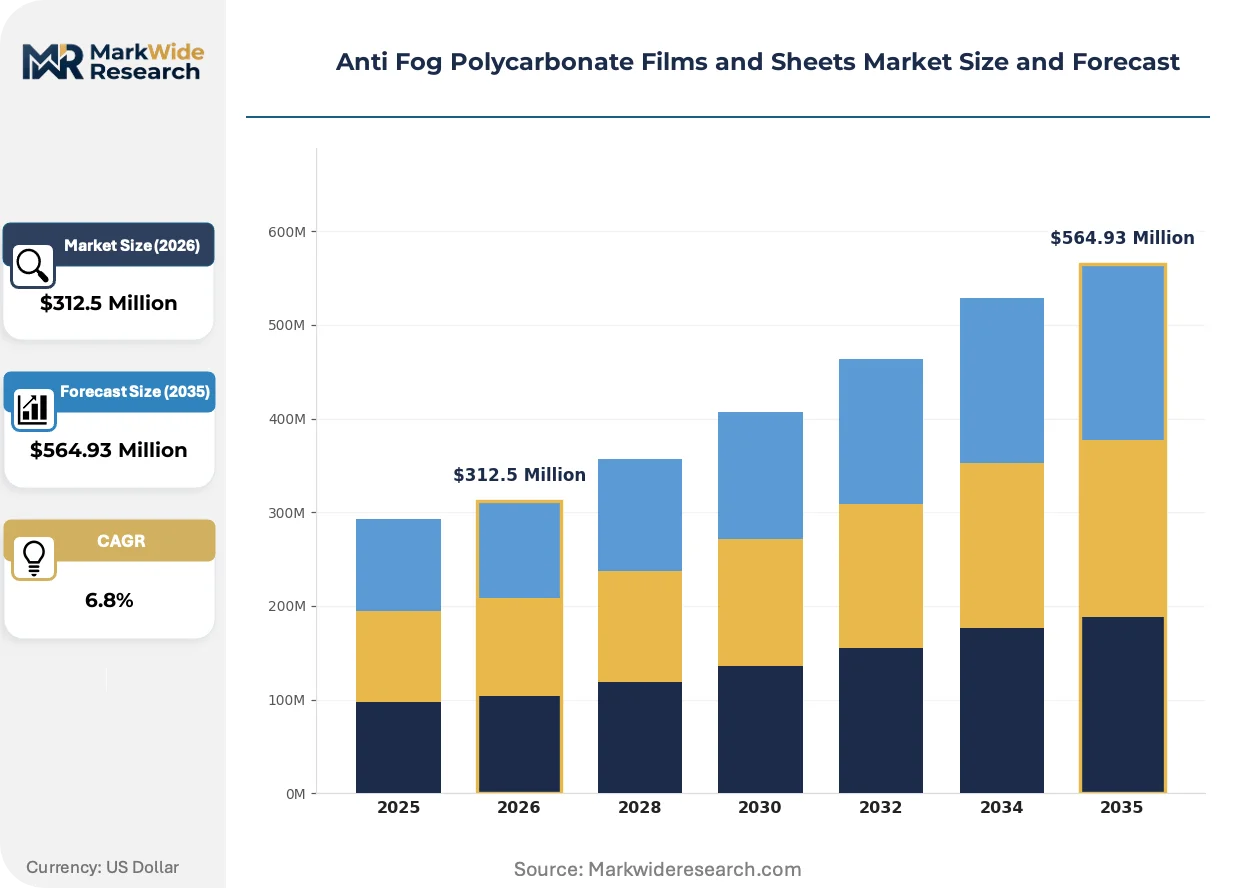
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Films, Sheets, Coatings, Laminates Application: Automotive, Construction, Healthcare, Consumer Electronics End User: Manufacturers, Distributors, Retailers, OEMs Distribution Channel: Online, Direct Sales, Retail Stores, Wholesalers |
| Companies Covered | SABIC, Covestro, 3M, Teijin, Celanese Corporation, DuPont, Mitsubishi Gas Chemical, Toray, Amcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti Fog Polycarbonate Films and Sheets Market Strategic Shifts & Innovations
Material science advancements are driving a shift from single-function products to integrated material systems. The focus is on developing polycarbonate films and sheets with inherent, multi-functional properties that solve several challenges simultaneously, reducing manufacturing complexity for end-users in automotive and electronics.
Multi-Functional Coating Integration
Advanced coatings that combine anti-fog, anti-scratch, and UV-resistant properties into a single, durable layer are gaining traction. High-end automotive manufacturers adopt these for components like head-up display screens, while industrial safety gear makers use them for premium protective visors. This integrated approach is rendering obsolete the multi-stage manufacturing process of applying separate, single-function coatings, thereby streamlining production and improving component reliability.
REACH Compliance Forcing Reformulation
The European Union's REACH regulation places stringent controls on chemical substances used within the trading bloc. This directly impacts anti-fog coating formulations, restricting or banning certain solvents and active ingredients previously common in the industry. Coating and film producers targeting the European market are consequently investing heavily in R&D to develop new, compliant, often water-based formulations that maintain high performance without using restricted chemicals.
Direct Sourcing by OEMs
A significant behavioral change involves major automotive and electronics OEMs establishing direct supply agreements for critical optical components like anti-fog films. This model displaces specialized industrial distributors, favoring large-scale producers who can manage global logistics and ensure quality control. The trend is most visible in the competitive automotive supply chains of Germany and Japan, where efficiency and component traceability are paramount.
Anti Fog Polycarbonate Films and Sheets Market Segmentation
Anti-fog polycarbonate films and sheets serve diverse needs across multiple industries. Understanding market segments reveals specific demand drivers and competitive dynamics within different product forms, applications, and customer types. This granular view helps identify high-growth areas and strategic entry points for manufacturers.
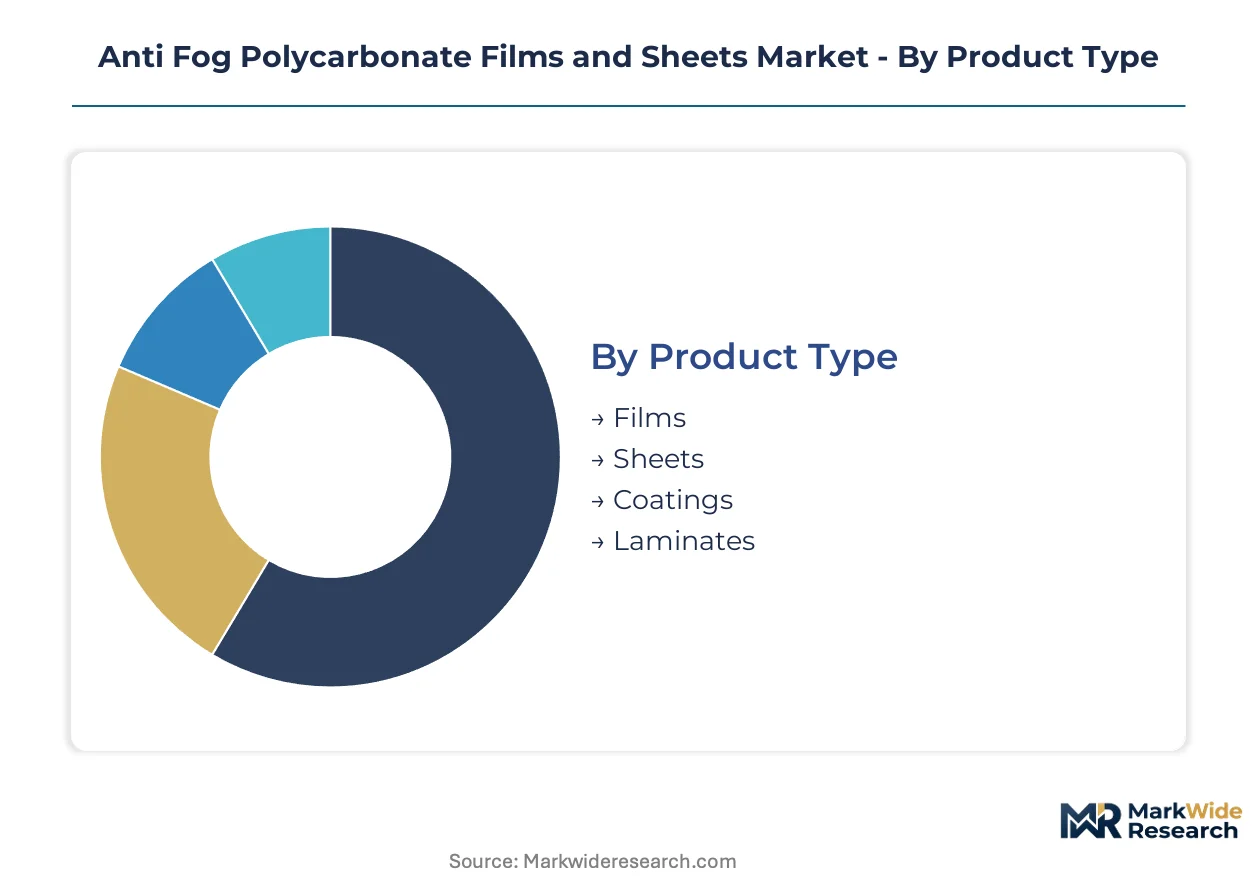
Product Type:
The product type segmentation delineates the anti-fog polycarbonate market based on material form factors, catering to a broad spectrum of optical clarity requirements.
- Films:These thin, flexible polycarbonate layers are often applied to existing surfaces or integrated into displays. Demand for films concentrates in consumer electronics and automotive head-up displays, where lightweight optical clarity is critical for user interface and system functionality.
- Sheets:Thicker, rigid polycarbonate sheets provide structural integrity alongside anti-fog properties for demanding applications. Automotive sensor covers and industrial machine guards drive significant sheet volume, requiring robust, impact-resistant optical solutions for safety systems.
- Coatings:Applied directly to polycarbonate substrates, these specialized chemical formulations impart anti-fog functionality.
- Laminates:Multiple layers of polycarbonate or other materials are bonded together, often incorporating anti-fog properties for enhanced durability.
The dominant share belongs to Films, while Sheets are gaining value share in demanding structural applications.
Application:
This segmentation highlights how diverse industry-specific demand drivers shape the adoption of anti-fog polycarbonate solutions.
- Automotive:This sector utilizes anti-fog polycarbonate for ADAS sensor covers, head-up displays, and interior components. Euro NCAP safety mandates and the need for reliable optical clarity in critical systems drive automotive demand.
- Healthcare:Medical devices like surgical face shields, incubators, and diagnostic equipment require certified anti-fog materials. US FDA and EU MDR compliance standards are critical for material selection in healthcare applications.
- Construction:Anti-fog polycarbonate finds use in skylights, safety glazing, and transparent barriers to maintain visibility in varying conditions.
- Consumer Electronics:This segment applies anti-fog films in smart glasses, AR/VR headsets, and display covers for enhanced user experience.
Innovation in anti-fog polycarbonate materials often concentrates within the Automotive and Healthcare sectors, driven by stringent performance and regulatory requirements.
End User:
The end-user segmentation differentiates market participants based on their position within the supply chain and their direct engagement with anti-fog polycarbonate products.
- Manufacturers:These entities produce the anti-fog polycarbonate films, sheets, or coatings themselves, supplying them to various industries. SABIC and Covestro are examples of large-scale manufacturers in this market.
- Distributors:These specialized industrial wholesalers traditionally connect producers with smaller end-users, though their role is shifting due to direct OEM sourcing.
- Retailers:Retailers offer finished products or components containing anti-fog polycarbonate directly to consumers or smaller businesses.
- OEMs:Original Equipment Manufacturers, particularly in automotive and electronics, directly integrate anti-fog polycarbonate components into their finished products. Their direct sourcing strategies favor large-scale producers with global logistics capabilities.
Procurement patterns are shifting significantly, with OEMs increasingly bypassing traditional Distributors for direct engagements with Manufacturers.
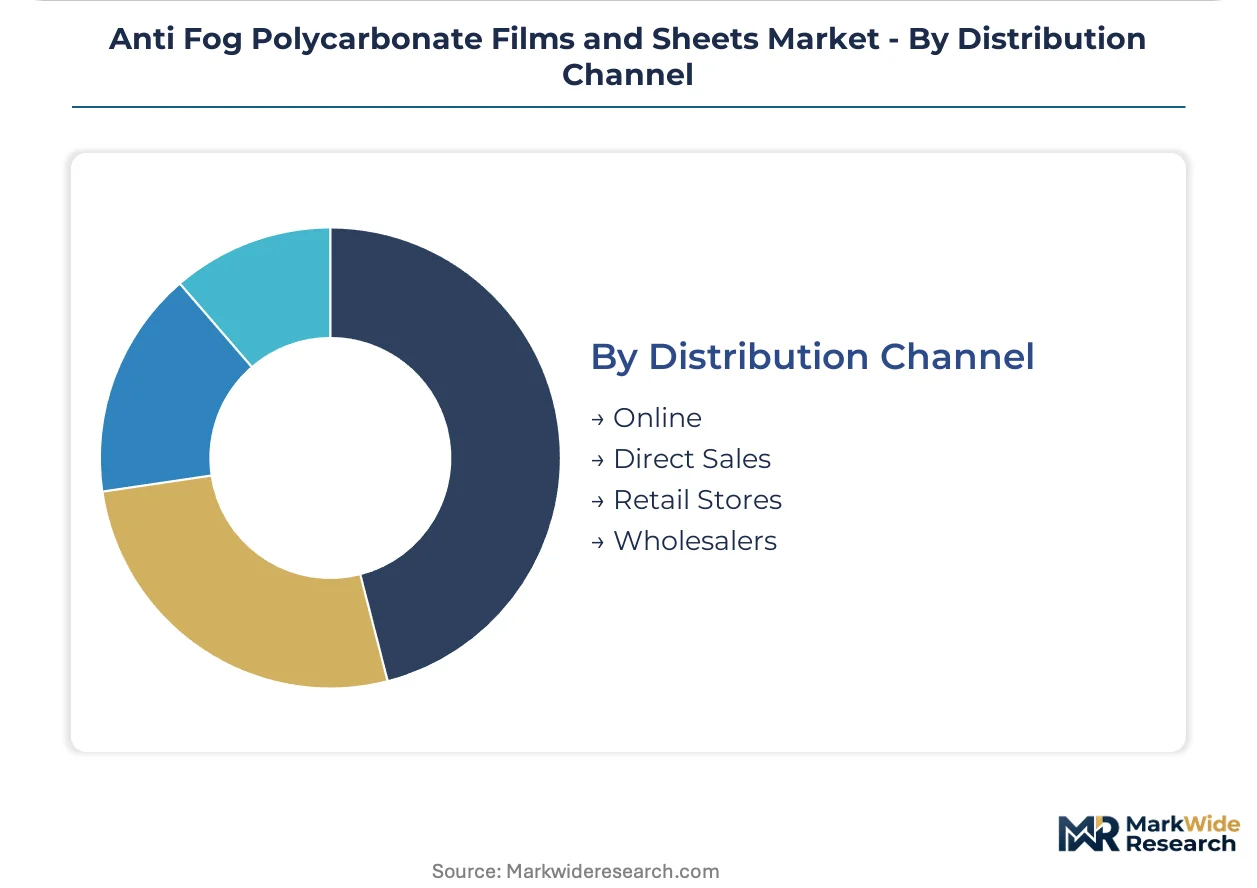
Distribution Channel:
Market access for anti-fog polycarbonate films and sheets varies significantly depending on the established distribution channels, from direct engagement to broader retail networks.
- Online:E-commerce platforms facilitate sales of anti-fog polycarbonate products, particularly for smaller orders or specialized applications.
- Direct Sales:This channel involves producers establishing direct sourcing agreements with large-volume customers, particularly OEMs in automotive and electronics. This model enhances quality control and strengthens supplier-customer relationships.
- Retail Stores:This channel includes physical outlets where finished products incorporating anti-fog materials are sold to end-consumers.
- Wholesalers:Industrial wholesalers historically served as intermediaries, distributing anti-fog materials to a fragmented customer base. Their role is fragmenting as major purchasers shift towards direct procurement.
The market is experiencing a disruption of traditional distribution models, with Direct Sales gaining prominence over Wholesalers for high-volume transactions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The push for stringent automotive safety ratings, such as those from Euro NCAP, and critical material compliance standards like US FDA and EU MDR, are key policy drivers for anti-fog polycarbonate adoption. These regulations mandate reliable optical clarity in applications ranging from vehicle components to medical devices, influencing material selection across major manufacturing economies.
Germany
Germany's automotive sector demands anti-fog polycarbonate for advanced driver-assistance systems and head-up displays. Vehicle component approvals by the KBA ensure material performance in critical safety applications. The Stuttgart region, a hub for leading automotive manufacturers, actively integrates these specialized films into new vehicle designs.
Japan
Japanese automotive and electronics industries require anti-fog films for next-generation displays and wearable technology. METI initiatives support advanced material development, ensuring high-performance solutions for domestic manufacturing. Major electronics and automotive R&D centers in the Tokyo region drive innovation for integrated anti-fog functionalities.
United States
United States demand for anti-fog polycarbonate stems from medical device manufacturing and consumer electronics applications. US FDA regulations mandate specific material compliance for healthcare products like surgical face shields. Silicon Valley, with its concentration of tech and medical device firms, integrates advanced anti-fog solutions into new product designs.
China
China's rapidly expanding automotive production and industrial sectors create substantial demand for anti-fog sheets and films. GB standards ensure quality and performance for various end-use applications, including safety equipment. The Yangtze River Delta, a major manufacturing base, sees significant integration of these materials into diverse industrial and consumer products.
India
Indian automotive manufacturing and healthcare sectors drive demand for anti-fog polycarbonate films and sheets. BIS standards guide material specifications for local production and import, supporting quality control. Automotive clusters around Chennai actively adopt these materials for vehicle safety components and interior displays.
Anti Fog Polycarbonate Films and Sheets Market Key Industry Players
On the supply side, the industry exhibits a dual structure, with fragmentation among specialized coating providers and consolidation among large-scale material producers. Major players fall into archetypes such as immense polycarbonate capacity holders, advanced coating technology specialists, and integrated film system suppliers. Companies are increasingly pursuing direct sourcing agreements with OEMs and investing in advanced coating R&D to differentiate their offerings.
Among the global material science corporations, SABIC, a Saudi Arabian multinational, leverages its substantial polycarbonate production capabilities to serve high-volume automotive and electronics contracts directly, emphasizing scale and supply chain efficiency. Covestro, a German-based materials company, differentiates its offerings through a portfolio of advanced coating technologies for high-performance applications, targeting specific performance requirements. The US-headquartered 3M Company competes on the strength of its integrated film and adhesive systems, providing comprehensive solutions that combine anti-fog properties with other functionalities for diverse industries.
| Leading Market Players |
|---|
| SABIC |
| Covestro |
| 3M |
| Teijin |
| Celanese Corporation |
| DuPont |
| Mitsubishi Gas Chemical |
| Toray |
| Amcor |
Cost & Logistics Intelligence
The Yangtze River Delta's concentrated production capacity for polycarbonate resins significantly influences downstream film and sheet pricing power. This regional supply concentration creates a competitive landscape where scale and efficiency dictate market access and profit margins.
Pricing Analysis
Certification level (US FDA, EU MDR, KBA-grade) creates the primary spread in anti-fog polycarbonate film and sheet pricing. Pricing stratifies across performance tiers, with higher value captured by multi-functional materials offering integrated anti-scratch or UV-blocking capabilities. Price differentiation also stems from customization levels and the volume scale of direct OEM contracts. Pricing pressure stems from large OEMs seeking cost efficiencies, particularly for standard film applications. End-users in medical devices and critical automotive safety components exhibit lower price sensitivity compared to those in consumer electronics.
Supply Chain Analysis
Large-scale material producers like SABIC and Covestro hold significant capacity across key manufacturing hubs in Germany, Japan, and China. The supply chain draws from petrochemical feedstocks such as Bisphenol A (BPA) and specialized coating chemicals. Raw material price volatility, influenced by crude oil and chemical precursor markets, represents a structural supply chain risk. Downstream distribution is shifting towards direct sales agreements between major producers and OEMs, displacing traditional industrial wholesalers for high-volume transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery driven by renewed automotive production volumes and sustained demand from the medical device sector.
For Market Incumbents:
Pre-empt competition from substitute materials by accelerating R&D into multi-functional coatings that offer inherent anti-scratch and UV-blocking properties. Consolidate market share through strategic acquisitions of specialized coating technology firms to enhance product differentiation. Invest in certification processes for new materials to meet stringent US FDA and EU MDR standards, mitigating regulatory threats and ensuring market access. Deepen direct sourcing relationships with major automotive OEMs to secure long-term, high-volume contracts against emerging regional competitors.
For New Entrants and Emerging Players:
Emerging wearable technology applications in augmented and virtual reality represent the most penetrable entry point for specialized anti-fog films. Target industrial safety equipment for specific niche applications requiring superior anti-abrasion and chemical resistance. Focus on developing cost-effective, REACH-compliant formulations for European markets, leveraging novel water-based coating technologies. A go-to-market angle emphasizing rapid customization and responsive technical support for smaller-volume, high-value applications can differentiate offerings.
For Investors and Strategic Acquirers:
Long-term, this sits as a technology-driven consolidation play because specialized coating IP offers significant differentiation and margin capture. Target mid-cap material science firms with proprietary advanced coating technologies or strong regional supply chain presence in growing automotive hubs. Focus on companies demonstrating robust R&D pipelines for next-generation multi-functional materials. The signal to watch is an increase in direct investment by automotive Tier 1 suppliers into advanced material development or strategic partnerships with coating specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Supports growing automotive and electronics manufacturing in China and India. |
| Advanced Coating R&D Investment | Integrates anti-scratch and UV-blocking properties, reducing component complexity for OEMs. |
| Direct OEM Engagement Model | Secures high-volume, long-term contracts and enhances quality control for critical applications. |
| REACH Compliant Reformulation | Ensures continued market access and regulatory adherence within the European Union. |
| Targeted Geographic Expansion | Establishes supply chains in new automotive manufacturing hubs like Mexico and Eastern Europe. |
Research Approach
Cross-validation between primary interviews with R&D directors and secondary data from industry association reports anchors the qualitative findings. This involved discussions with procurement managers in automotive and electronics, product development specialists, and regulatory compliance officers across key regions. Secondary sources included government publications from Euro NCAP and US FDA, company annual reports, and trade journals. The overall approach combined bottom-up segment data with top-down total market analysis for comprehensive insights.
The calibration approach involved aligning historical market performance with macroeconomic indicators over the projection horizon. The analytical framework modeled segmentation across product type (films, sheets), application (automotive, healthcare), end user (OEMs, manufacturers), distribution channel, and regional manufacturing clusters. Compound annual growth rates were derived from volume and value projections across the analysis window. Key forecast inputs included global automotive production forecasts and medical device regulatory approvals.
Macroeconomic conditions sit as an overlay; deviation in global automotive sales or crude oil prices would shift the trajectory. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Quarterly review of automotive production and chemical feedstock prices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
China BOPP Film Market
Poly film
Blown Film Extruder Market
Poly film
Wrap Around Label Films Market
Poly film
Poly Tubing Market
Poly film
Asia Pacific Plastic Packaging Film Market
Poly film
Bopet Films Market
Poly film
Global Thermoplastic Films Market
Poly film
Vinyl Films Market
Poly film
Polyethylene Furanoate Films Market
Poly film
Global Blown Stretch Packaging Films Market
Poly film
Polysaccharide Films Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
Poland Plastic Packaging Films Market
Poly film
Nylon Films for Liquid Packaging Market
Poly film
Metallized Film Market
Poly film
United Kingdom Plastic Packaging Films Market