
 BOPP Labels Market | 2026-2036
BOPP Labels Market Size, Share, and Industry Trends Forecast 2026-2036
BOPP Labels Market Analysis
Subscription-based print management and color-matching software is pivoting how converters bundle value beyond substrate supply. Avery Dennison Corporation leverages digital enablement tools to lock in long-term converter relationships. CCL Industries Inc. anchors its position through backward integration into precision coating and metallization. Constantia Flexibles Group GmbH differentiates via pharmaceutical-grade cleanroom certification and cold-chain label durability.
Biaxially oriented polypropylene labels are thin-film substrates produced by stretching polypropylene in machine and transverse directions to achieve high clarity, moisture resistance, and dimensional stability, typically ranging from 20 to 60 microns in thickness. They serve primarily as printable facestocks for product identification, tamper evidence, and brand communication across fast-moving consumer goods. Pressure sensitive formats dominate volume due to compatibility with high-speed applicators and diverse container geometries, while shrink sleeve configurations capture premium positioning in curved and contoured packaging. Digital printing technology is expanding fastest among print methods as brands shorten run lengths and pursue mass customization for regional campaigns.
The U.S. FDA governs label adhesives and indirect food contact substrates through 21 CFR compliance pathways, while the EU REACH regulation restricts certain phthalate plasticizers and mandates full substance disclosure across the supply chain. ISO 14001 environmental management certification is becoming a de facto qualifier for supplier qualification at multinational FMCG procurement desks. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in closed-loop recycling partnerships or bio-based polypropylene pilot programs.
Market Dynamics
Digital printing adoption is compressing converter economics and shortening brand procurement cycles, forcing substrate suppliers to bundle software-enabled color management and workflow tools alongside commodity film supply.
Growth Catalysts
- Food and beverage shelf-life extension:FMCG brands in India, Germany, and Brazil are specifying high-barrier BOPP facestocks to replace multi-layer laminates, reducing material complexity while maintaining oxygen and moisture protection.
- REACH substance disclosure mandates:Europe's ECHA enforcement of full supply-chain chemical transparency is accelerating substitution of solvent-based adhesives with UV-curable and hot-melt alternatives compatible with BOPP substrates.
- Digital print compatibility:Electrophotographic and inkjet presses running at 150+ meters per minute are overtaking flexographic methods for run lengths below 10,000 linear meters, expanding addressable label volume for short-batch pharmaceuticals and cosmetics.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking economics and regional refinery maintenance schedules in the US Gulf Coast and Middle East create month-to-month resin price instability that converters cannot fully pass through to brand customers.
- Metallized film supply concentration:Precision vacuum metallization capacity clusters in Germany, Japan, and South Korea, creating lead time vulnerability for premium cosmetic and confectionery labels requiring mirror-finish aesthetics.
- Adhesive migration limits:FDA 21 CFR indirect food contact thresholds restrict certain tackifier chemistries in pressure-sensitive constructions, complicating formulation for fatty and acidic food applications.
Strategic Opportunities
- Maharashtra and Gujarat production corridors:India's western industrial belt hosts expanding FMCG manufacturing clusters where domestic BOPP film capacity lags label demand, creating import substitution potential for regional converters.
- Cold-chain pharmaceutical labeling:Temperature-indicating and cryogenic-adhesive BOPP constructions are capturing share from direct thermal papers in vaccine and biologics distribution, supported by WHO prequalification pathways.
- Bio-based polypropylene pilot programs:Neste and Braskem offtake agreements for renewable feedstock-derived PP are enabling brand claims of mass-balance certified packaging, differentiating premium personal care lines.
Industry Challenges
- Color management talent scarcity:Converters lack sufficient press operators trained in G7 grayscale calibration and spot color replacement protocols, creating waste and rework costs during digital press changeovers.
- Cleanroom certification timelines:ISO 14644 Class 7 pharmaceutical label production requires 12-18 month facility validation cycles that delay market entry for mid-tier converters targeting regulated drug packaging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BOPP Labels Market |
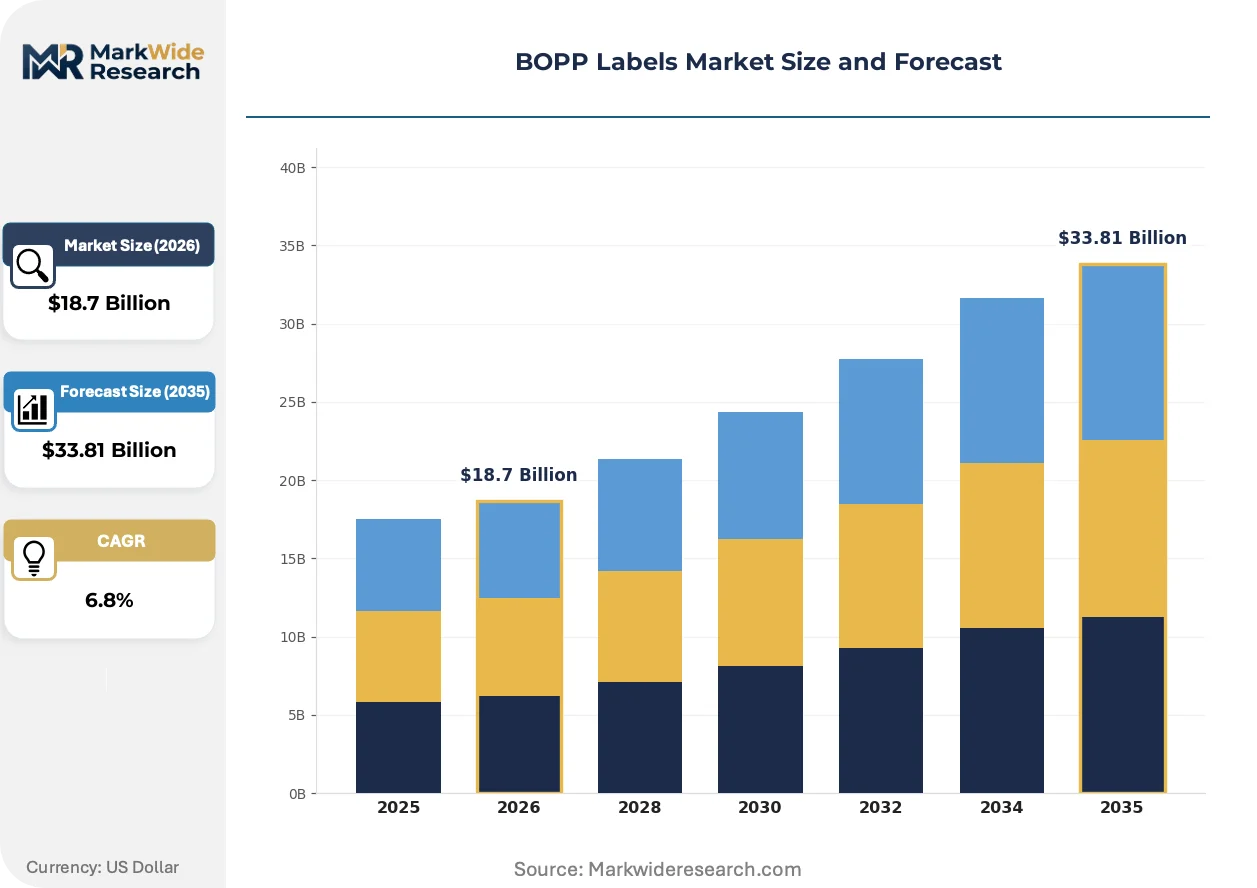
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensitive, Shrink Sleeve, In-Mold, Stretch Sleeve End Use Industry: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Application: Bottles, Jars, Boxes, Bags Technology: Flexographic Printing, Digital Printing, Gravure Printing, Screen Printing |
| Companies Covered | 3M Company, Coveris Holdings S.A., Avery Dennison Corporation, Huhtamaki Oyj, Mondi Group, CCL Industries Inc., Constantia Flexibles Group GmbH, LINTEC Corporation, UPM Raflatac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BOPP Labels Market Emerging Trajectories
Print technology convergence and regulatory chemical disclosure are rewriting converter capability requirements, while brand procurement models pivot from spot purchasing to integrated supply contracts bundling substrate, design, and inventory management.
Water-based inkjet formulations with sub-5 picoliter drop volumes and LED-UV curing are overtaking solvent flexography in high-end cosmetic and spirits labeling. Premium fragrance houses in France and Italy specify these systems for 500-2,000 unit test markets, compressing traditional cylinder engraving and plate-making lead times from two weeks to 48 hours. This capability is enabling same-week campaign launches and geographic versioning that flexographic workflows cannot match.
EU REACH Annex XVII restrictions on phthalate plasticizers and the forthcoming per- and polyfluoroalkyl substances (PFAS) ban are forcing adhesive reformulation across the value chain. European converters face 18-month requalification timelines for food-contact constructions as they migrate from fluorosilicone release coatings to plasma-treated linerless alternatives. Pharmaceutical label producers in Germany and Switzerland are most exposed, as migration testing protocols for new adhesive systems extend regulatory submission cycles.
Brand procurement teams are consolidating label spend under multi-year managed print services contracts that bundle substrate supply, prepress, and vendor-managed inventory. Unilever and Procter & Gamble operations in the Netherlands and Ohio have shifted 60% of their label sourcing to these arrangements, displacing transactional spot purchasing. This model concentrates volume among converters with integrated design-to-delivery platforms and penalizes pure-play substrate distributors lacking workflow software capabilities.
BOPP Labels Market Segmentation
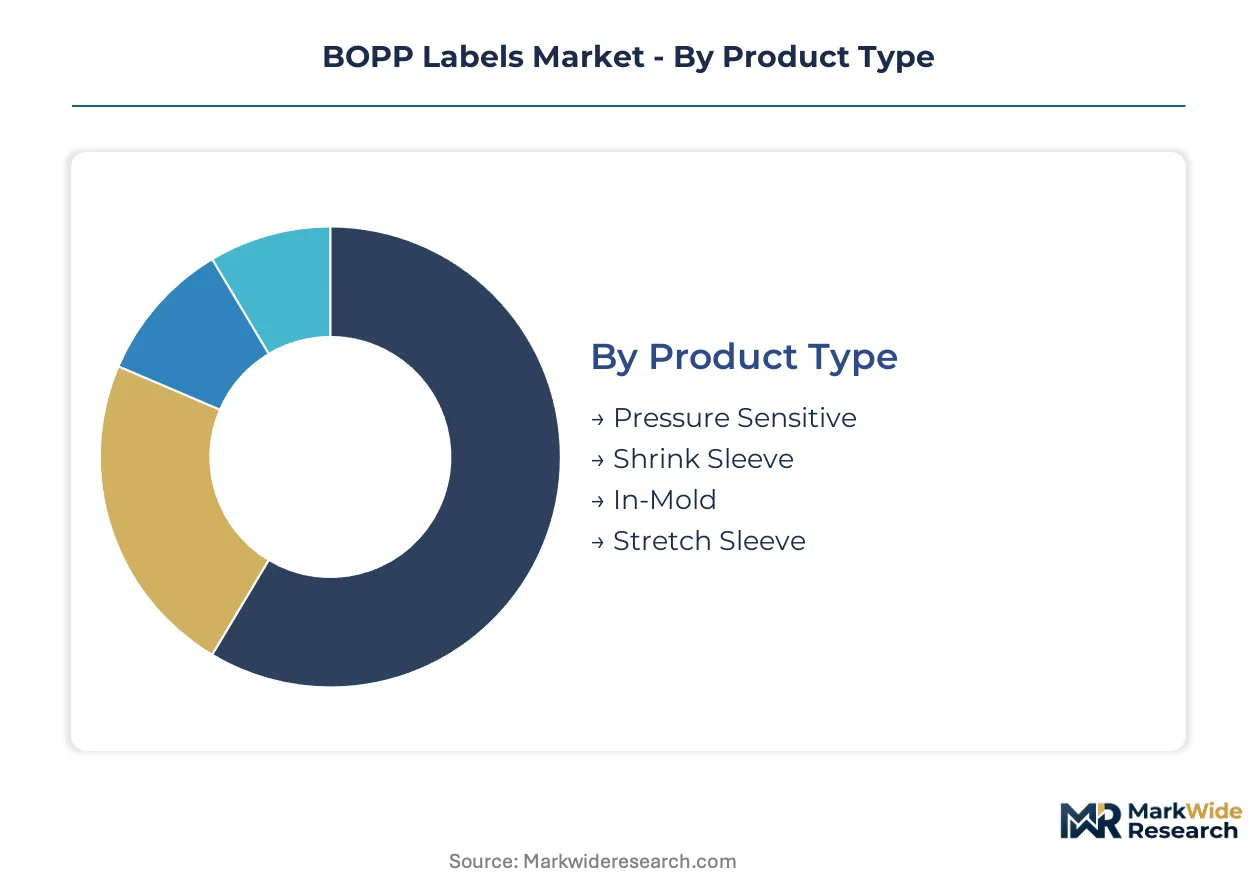
BOPP label procurement patterns diverge sharply across substrate formats, end-use specifications, and print technologies. Converters must align capability investments with the specific performance thresholds each segment demands.
Product Type:
Supply concentration in coating and metallization assets shapes competitive positioning across substrate formats.
- Pressure Sensitive:Acrylic or rubber-based adhesives laminated to release liners enable high-speed die-cutting and automatic application. Food and beverage bottlers in Maharashtra and Gujarat specify these constructions for carbonated drinks and edible oils, though FDA 21 CFR adhesive migration limits constrain fatty food applications.
- Shrink Sleeve:Oriented films with 40-70% shrink ratios conform to complex container geometries through steam or hot-air tunnels. Premium spirits and cosmetics brands in France and Italy deploy these for 360-degree decorative coverage, with metallized grades requiring vacuum deposition capacity concentrated in Germany and Japan.
- In-Mold:Labels fuse permanently with blow-molded containers during formation, eliminating separate application steps.
- Stretch Sleeve:Elastic films apply without adhesive or heat, suiting temperature-sensitive pharmaceutical vials.
Pressure Sensitive absorbs the bulk of installed capacity; Shrink Sleeve is expanding most quickly.
End Use Industry:
Margin profiles and certification requirements segment converter capabilities by vertical.
- Food & Beverage:Oxygen and moisture barrier specifications dominate procurement, with high-clarity BOPP replacing multi-layer laminates in India and Brazil. REACH substance disclosure mandates are accelerating UV-curable adhesive adoption across European supply chains.
- Pharmaceuticals:Cold-chain durability and tamper-evidence features command premium positioning. WHO prequalification pathways for temperature-indicating constructions are displacing direct thermal papers in vaccine distribution.
- Personal Care:Mass-balance certified bio-based polypropylene is gaining traction for premium skincare lines.
- Household Products:Chemical resistance and scuff-proofing prioritize durability over aesthetic refinement.
Food & Beverage commands the largest volume footprint; Pharmaceuticals posts the steepest expansion trajectory.
Application:
Container geometry dictates substrate specification and application equipment requirements.
- Bottles:Carbonated soft drinks and mineral water drive high-volume demand for clear BOPP with holographic security features.
- Jars:Condiment and preserve packaging requires moisture-resistant constructions with aggressive tack for glass adhesion.
- Boxes:E-commerce secondary packaging specifications are emerging for shipping label compatibility.
- Bags:Flexible pouch formats favor thinner gauge films for weight reduction.
Bottles anchor procurement volumes; Boxes are climbing the fastest as e-commerce fulfillment expands.
Technology:
Capital intensity and changeover economics stratify converter investment decisions.
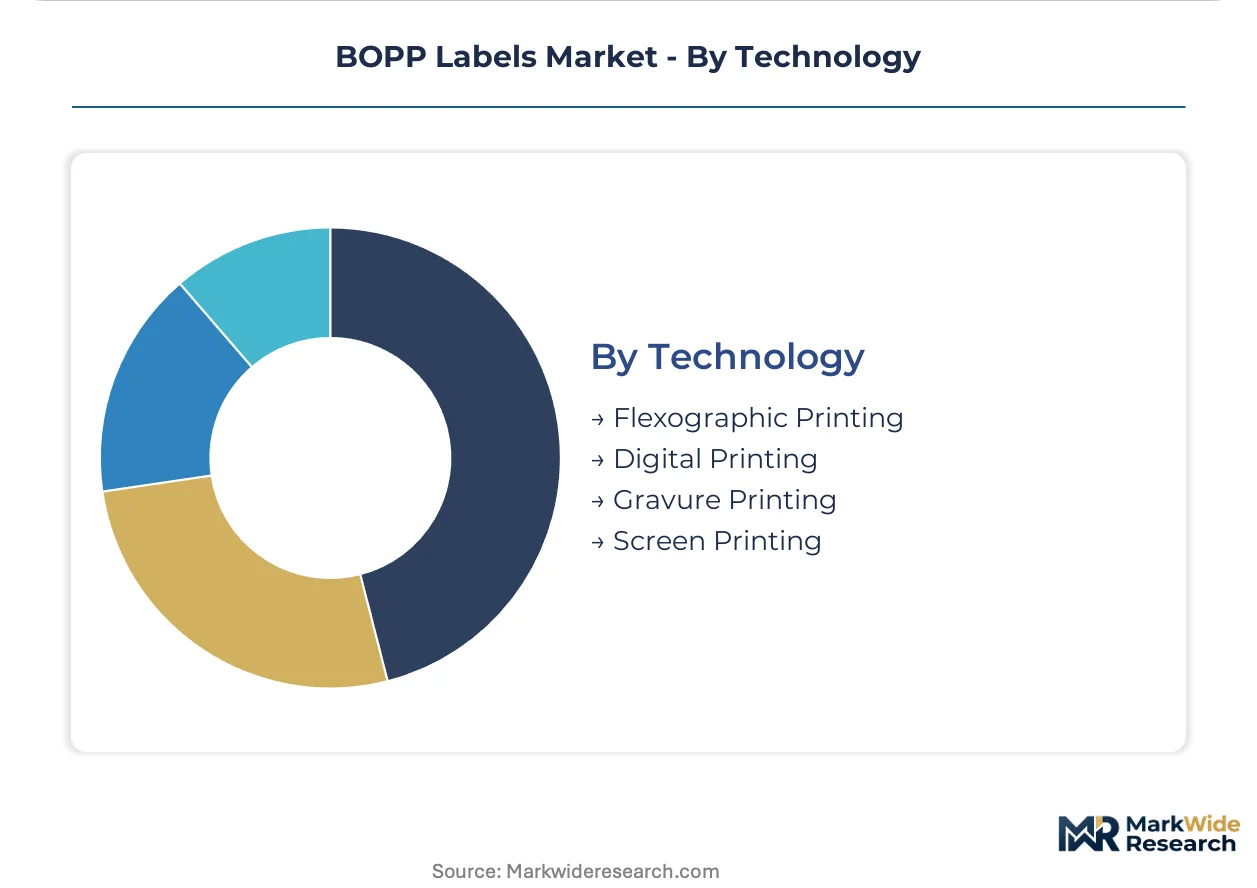
- Flexographic Printing:Cylinder engraving and solvent-based ink systems dominate runs above 10,000 linear meters. Long plate-making lead times constrain brand agility for seasonal campaigns.
- Digital Printing:Electrophotographic and inkjet presses at 150+ meters per minute enable 48-hour turnaround for test markets. G7 color calibration expertise scarcity creates waste during press changeovers.
- Gravure Printing:Cylinder-based systems deliver unmatched ink density for premium cosmetic metallization.
- Screen Printing:Thick ink deposits suit tactile and braille regulatory requirements.
Flexographic Printing retains the deepest installed base; Digital Printing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's industrial corridor around Mumbai and Pune anchors BOPP label demand through dense FMCG manufacturing clusters serving domestic and export markets.
United States
Food and beverage bottlers in Ohio and California specify high-barrier BOPP facestocks for extended shelf-life packaging. FDA 21 CFR compliance pathways govern adhesive migration limits for indirect food contact applications. Chicago-area converters bundle digital color management software with substrate supply to secure multi-year contracts with multinational brand owners.
Germany
REACH Annex XVII enforcement accelerates solvent-to-UV adhesive transitions across pharmaceutical and cosmetic label supply chains. ECHA substance disclosure mandates require full supply-chain chemical transparency from film suppliers. Stuttgart and Munich host precision metallization capacity for premium mirror-finish labels serving French and Italian luxury brands.
India
FMCG production expansion in Maharashtra and Gujarat outpaces domestic BOPP film capacity, creating import dependency for regional converters. FSSAI food packaging regulations align with international migration testing standards for fatty food applications. Ahmedabad and Surat clusters attract backward-integrated substrate suppliers seeking captive coating assets.
Japan
Electronics and precision equipment labeling demand thin-gauge BOPP with dimensional stability for automated assembly lines. METI industrial standards guide adhesive performance specifications for high-humidity environments. Osaka-Kobe manufacturing belt concentrates metallized film conversion for Asian cosmetic export markets.
Brazil
Beverage bottlers in São Paulo state specify clear BOPP with holographic security features for anti-counterfeiting protection. ANVISA pharmaceutical labeling regulations mandate tamper-evidence constructions for cold-chain biologics. Campinas industrial district hosts expanding converter capacity serving Mercosur regional distribution networks.
BOPP Labels Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a tiered structure where integrated film-coating-metallization assets define strategic positioning. The vendor base separates into three archetypes: multinational converters with captive substrate supply, regional specialists with precision coating capabilities, and pure-play distributors bundling software-enabled workflow tools. Consolidation pressures favor players with backward integration into resin compounding or forward integration into brand-managed print services. Geographic expansion and technology licensing represent the dominant competitive moves as converters seek to replicate integrated models across high-growth corridors.
Among North American-based multinationals, 3M Company and Avery Dennison Corporation exemplify the integrated converter archetype through combined substrate manufacturing and adhesive formulation capabilities. CCL Industries Inc. anchors the precision coating specialist tier with in-house metallization and pharmaceutical-grade cleanroom assets. Constantia Flexibles Group GmbH occupies a position bridging European regulatory expertise with emerging market production corridors. These three names represent divergent strategic postures rather than comparable scale metrics.
| Leading Market Players |
|---|
| 3M Company |
| Coveris Holdings S.A. |
| Avery Dennison Corporation |
| Huhtamaki Oyj |
| Mondi Group |
| CCL Industries Inc. |
| Constantia Flexibles Group GmbH |
| LINTEC Corporation |
| UPM Raflatac |
| Others |
Supply Flow & Price Mechanics
Precision metallization specialists in Stuttgart and Munich anchor premium-tier labor costs, widening the spread between mirror-finish cosmetic grades and standard pressure-sensitive constructions sourced from Maharashtra converter clusters.
Pricing Analysis
Throughput-based contracts tied to press uptime and color-matching accuracy anchor value-based pricing for digital-enabled converters. Three-tier pricing structure across pharmaceutical-grade, food-contact certified, and general industrial levels separates ISO 14644 cleanroom production from commodity facestock supply. Cost compression in standard pressure-sensitive tiers is intensifying because propylene feedstock volatility limits margin pass-through to brand customers. Mid-tier converters serving regional FMCG bottlers exhibit highest price sensitivity, while luxury cosmetic houses in France and Italy accept premium positioning for metallized shrink sleeves.
Supply Chain Analysis
Dual-sourcing requirements from Unilever and Procter & Gamble procurement desks mandate qualified backup suppliers for both BOPP film and adhesive formulations across their Netherlands and Ohio operations. Vacuum metallization capacity concentrates in Germany, Japan, and South Korea, while precision coating assets cluster in Gujarat and Maharashtra. Raw material dependencies span naphtha-derived polypropylene resin, acrylic adhesive polymers, and release liner silicones. Single-source vulnerability in metallized film supply creates lead time exposure for premium cosmetic labels. Distribution runs through converter-managed inventory programs rather than spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital printing technology is displacing flexographic workflows, compressing converter investment cycles and rewriting capability requirements across the value chain.
For Market Incumbents: Deepen backward integration into precision coating and metallization assets to defend against pure-play software distributors bundling color-management tools. Lock in multi-year managed print services contracts with FMCG brand owners to secure volume commitments. Prioritize ISO 14644 Class 7 cleanroom certification for pharmaceutical label production to capture cold-chain biologics demand.
For New Entrants and Emerging Players: Regional converter networks in Maharashtra and Gujarat offer partnership pathways to bypass capital-intensive film extrusion assets. Target import substitution opportunities where domestic BOPP capacity lags label demand in India's western industrial belt. Pursue WHO prequalification for temperature-indicating constructions to displace direct thermal papers in vaccine distribution.
For Investors and Strategic Acquirers: Re-rating potential sits with precision coating specialists given REACH substance disclosure mandates accelerating adhesive reformulation cycles. Long-term viability favors converters with captive metallization assets and pharmaceutical-grade certifications. Monitor ECHA enforcement patterns for fluorosilicone release coating restrictions as inflection indicator for linerless technology adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Assets | Captive precision coating capacity insulates margin pressure from metallized film supply concentration in Germany and Japan. |
| Digital Color Management Platform Deployment | Software-enabled workflow tools secure multi-year contracts with Unilever and Procter & Gamble procurement desks. |
| Pharmaceutical Cleanroom Certification | ISO 14644 Class 7 validation opens WHO prequalification pathways for vaccine and biologics labeling. |
| Bio-based Polypropylene Pilot Scaling | Neste and Braskem mass-balance certification enables premium personal care brand differentiation claims. |
| Regional Converter Network Partnership | Maharashtra and Gujarat corridor access addresses import dependency without greenfield extrusion investment. |
Methodological Framework
Multi-period observation of digital press adoption rates, adhesive formulation shifts, and REACH compliance timelines anchored the trend analysis, supplemented by interviews with plant managers at European coating facilities, procurement leads at Indian FMCG bottlers, technical R&D directors at adhesive suppliers, and channel partners in metallized film distribution. Secondary validation drew from ECHA substance disclosure databases, FDA 21 CFR indirect food contact guidance, SEC 10-K filings from listed converters, and customs trade data for BOPP film imports into India. Bottom-up capacity assessments triangulated against top-down brand procurement spend estimates.
Segment-weighting across product type, end-use industry, application format, print technology, and regional production cluster shaped the analytical framework. CAGRs were derived from fitted growth curves applied to base-year observations across the projection horizon. Industry-specific forecast inputs included propylene feedstock price volatility indices, digital press installation rates, and ECHA regulatory enforcement patterns.
Caveats apply where propylene feedstock volatility, REACH Annex XVII expansion, or digital press technology maturation could materially shift the outlook. Deviation in ECHA per- and polyfluoroalkyl substances ban timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Direct Thermal Labels Market
Labels
Retro-Reflective Labels Market
Labels
Global Sensormatic Labels Market
Labels
Safety Labels Market
Labels
Hot Melt Glue Labeler Market
Labels
Global Label Market
Labels
Water Dissolvable Labels Market
Labels
Healthcare and Laboratory Labels Market
Labels
Barcode Label Printer Market
Labels
Stretch Sleeve and Heat Shrink Labels Market
Labels
Polyester Labels Market
Labels
Global Laminated Labels Market
Labels
Global Resealable Packaging Labels Market
Labels
Global Pressure Labels Market
Labels
Braille Labels Market
Labels
Stand Alone Label Applicator Market