
 Thermoforming Films Market | 2026-2036
Thermoforming Films Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoforming Films Market Outlook
Buyer concentration among food processors and retail private-label suppliers is rebalancing as mid-sized co-packers fragment procurement across specialized film converters. Amcor leverages its integrated resin-to-film manufacturing footprint to secure multi-year supply agreements with protein packers. Berry Global sustains R&D intensity in recyclable polyethylene formulations for healthcare blister lines. Mondi Group anchors European demand through its kraft-paper hybrid solutions that reduce plastic tonnage per tray.
Thermoforming films are thermoplastic sheets engineered to 25-750 micron thicknesses that soften under controlled heat and vacuum-form into precise cavities for product containment and display. Polypropylene formulations dominate lidding film applications where clarity and seal integrity at 180-220°C define performance. Blister packaging commands the highest margin pool due to pharmaceutical validation requirements and low substitution elasticity. Polyethylene competes aggressively in food service trays where downgauging to thin and micro calipers cuts material cost per unit.
The FDA regulates direct-food-contact layers through 21 CFR 177.1520 compliance testing for olefin polymers, while the EU Green Deal's PPWR mandates 55% recycled content in plastic packaging by 2030. ECHA's REACH restrictions on phthalate plasticizers in PVC films push converters toward polypropylene and polystyrene alternatives. Stakeholders must monitor how state-level extended producer responsibility laws in California and New York reshape cost allocation between resin producers, film extruders, and brand owners.
Market Dynamics
The EU's Packaging and Packaging Waste Regulation is forcing a structural recalibration of resin sourcing, with converters scrambling to secure food-grade recycled polypropylene ahead of 2030 mandates. This regulatory pressure is compressing traditional virgin resin supply chains while fragmenting procurement across specialized recyclers and certified reprocessors.
Growth Catalysts
- EU Green Deal recycled content mandates:The 55% recycled plastic packaging target by 2030 is pulling investment into post-consumer polypropylene sorting and decontamination infrastructure.
- Ready-meal format expansion:Food service operators are scaling thermoformed tray procurement for grab-and-go and home-delivery formats, driving film consumption in centralized protein and dairy processing.
- Barrier coextrusion advances:Five- and seven-layer structures with ethylene vinyl alcohol are extending shelf life for modified atmosphere packaging in premium meat and cheese applications.
Market Restraints
- Food-grade recycled resin scarcity:Approved sources of post-consumer polypropylene meeting FDA 21 CFR 177.1520 and EFSA safety standards remain concentrated in Germany and the Netherlands.
- Phthalate substitution costs:ECHA REACH restrictions on plasticizers in PVC thermoforming films are forcing converters toward higher-cost styrenic and olefinic formulations.
- Energy-intensive forming:Electric infrared heating systems for thick-gauge industrial trays consume 40-60% more power per unit than conventional contact heating, squeezing margins in European manufacturing.
Strategic Opportunities
- Healthcare blister line conversion:Pharmaceutical packers are qualifying recyclable polyethylene and cyclic olefin copolymer alternatives to PVC-PVDC laminates ahead of EU Green Deal implementation.
- Kraft-paper hybrid tray systems:Fiber-based substrates with thin polymer barrier layers are capturing shelf-ready produce packaging share from all-plastic formats in German and French retail.
- Digital print-on-film integration:Direct-to-web inkjet systems are collapsing label application steps, enabling short-run private-label customization for regional dairy co-packers.
Industry Challenges
- Multilayer delamination complexity:Separating incompatible polymers in post-consumer thermoformed trays for chemical recycling requires capital-intensive density-based sorting and solvent washing lines.
- Validation timeline compression:Pharmaceutical blister packers face 18-24 month stability testing cycles for new barrier films, delaying revenue recognition on recyclable formulation switches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoforming Films Market |
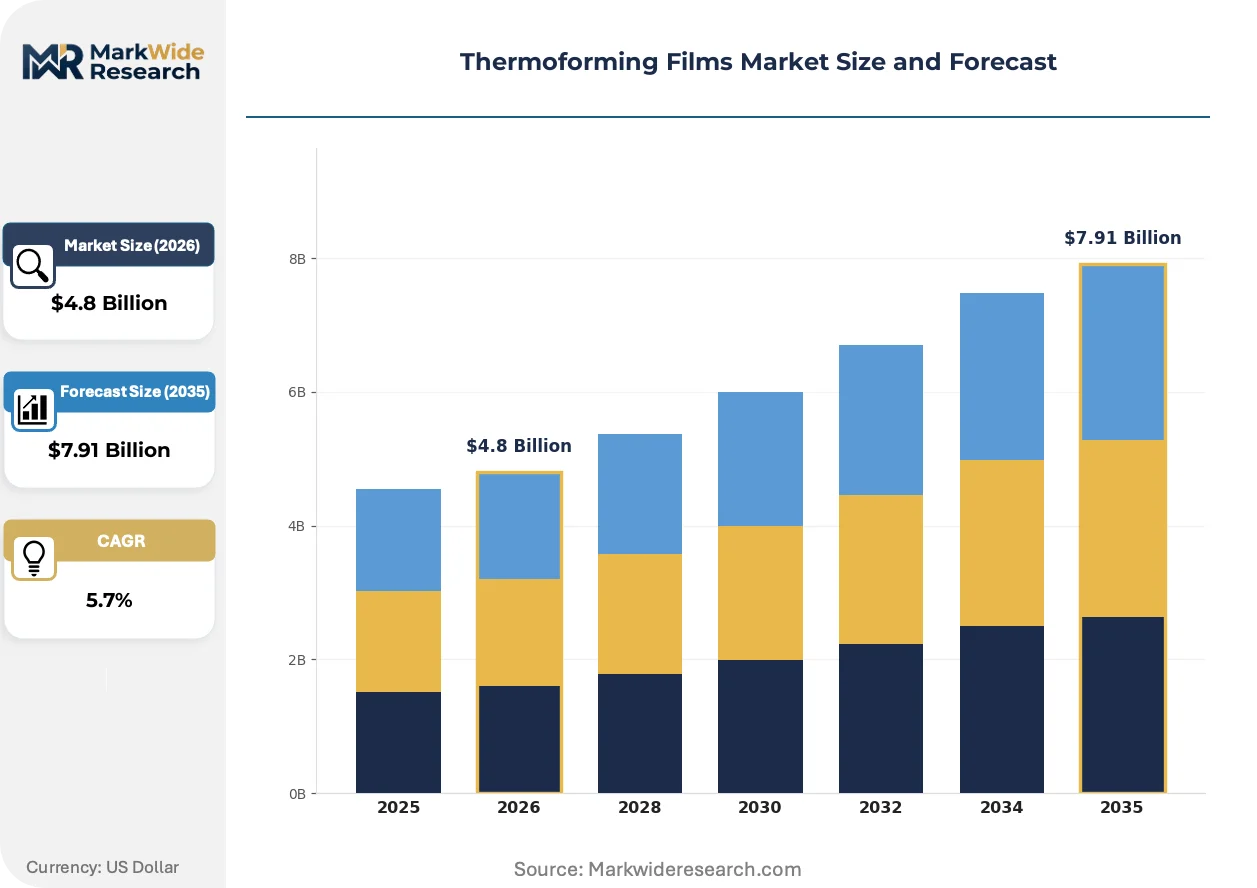
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
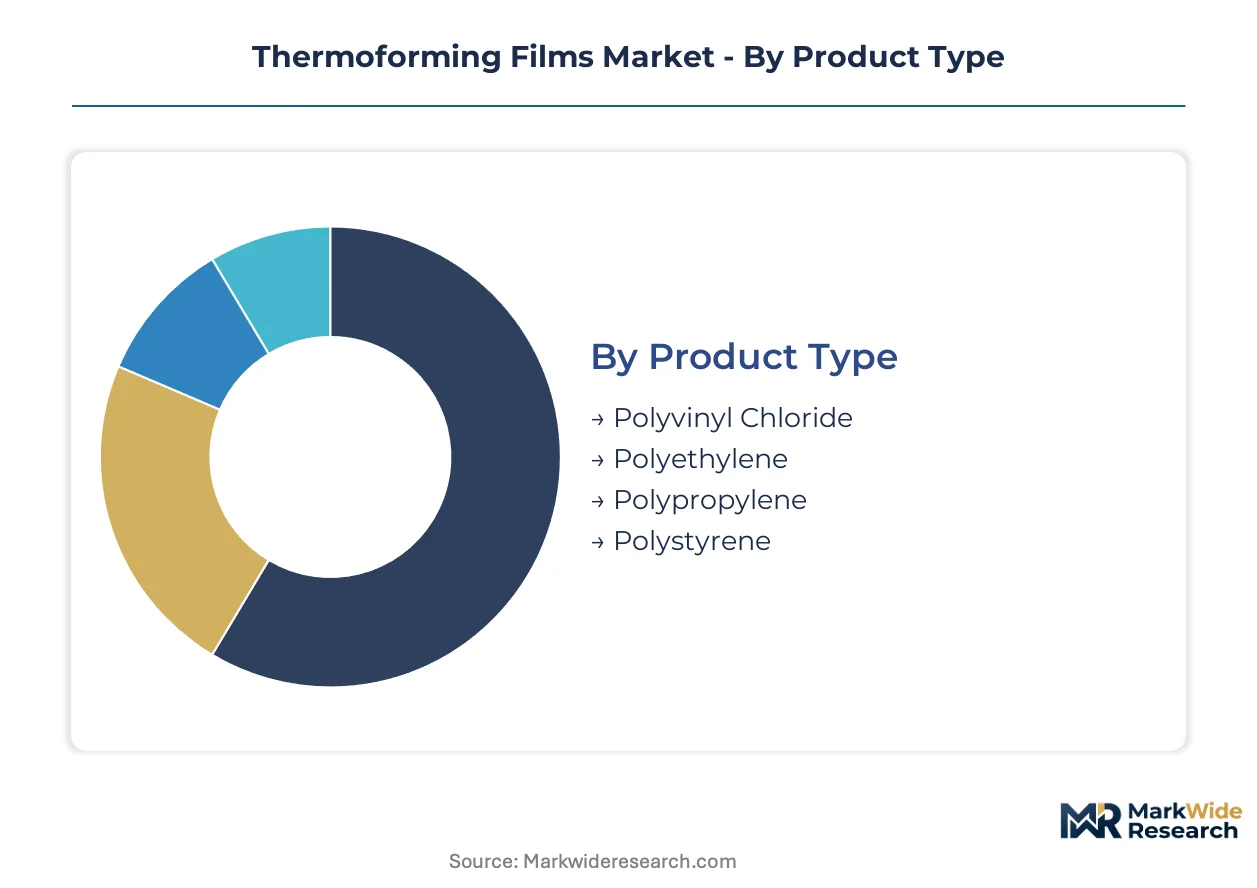
| Segmentation | Product Type: Polyvinyl Chloride, Polyethylene, Polypropylene, Polystyrene End User: Packaging, Automotive, Healthcare, Food Service Thickness: Micro, Thin, Medium, Heavy Application: Blister Packaging, Clamshells, Trays, Lidding Films |
| Companies Covered | Amcor, Berry Global, Sealed Air Corporation, Mondi Group, Winpak, Coveris, Klöckner Pentaplast, Sonoco Products Company, FlexPak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoforming Films Market Strategic Shifts
Active barrier technologies and digital manufacturing integration are compressing traditional film specification cycles. Converters now face compressed development timelines as brand owners demand simultaneous performance validation and sustainability certification.
Mono-material polyethylene structures with tuned seal-layer rheology are rewriting compatibility requirements for mechanical recycling streams. Dairy and fresh produce packers in Germany and France are qualifying these formulations for existing forming equipment without tool modification. The shift is rewriting how resin producers spec additive packages, with slip and anti-block chemistries now screened for recyclability certification.
The EU Green Deal's PPWR implementation timeline is accelerating capital deployment into chemical recycling and pyrolysis capacity. Film converters with offtake agreements for pyrolysis-derived naphtha are securing multiyear supply contracts with protein processors seeking mass-balance certification. The regulation is most pressuring mid-sized Italian and Spanish converters lacking integrated resin sourcing.
Brand owners are consolidating film procurement through direct converter relationships, bypassing traditional distribution intermediaries. Large retail private-label suppliers in Germany are negotiating specification-locked annual volumes with specialized extruders, displacing spot-market purchasing. The pattern is most visible in chilled ready-meal packaging, where Aldi and Lidl's central buying offices dictate barrier performance and recycled content minimums simultaneously.
Thermoforming Films Market Segmentation
Thermoforming film specifications vary dramatically across end-use applications, with resin selection and gauge thickness directly determining forming equipment compatibility and barrier performance. Procurement patterns fragment sharply between food-contact applications governed by FDA 21 CFR 177.1520 and pharmaceutical formats requiring EMA stability validation.
Product Type:
Resin supply concentrates among integrated petrochemical producers with captive polymerization capacity, locking converters into long-term offtake agreements for food-grade certifications.
- Polyvinyl Chloride:Plasticized formulations dominate pharmaceutical blister packs where thermoforming precision at 100-150°C enables deep-draw cavities for tablet containment. ECHA REACH restrictions on phthalate plasticizers are forcing German and Italian converters toward bio-based alternatives, compressing margins on legacy production lines.
- Polyethylene:Linear low-density grades with tuned seal-layer rheology are capturing chilled ready-meal tray share in German retail, driven by mono-material recyclability credentials that satisfy EU Green Deal PPWR mandates. Downgauging to micro calipers cuts material cost per unit in high-volume food service procurement.
- Polypropylene:Clarified random copolymers deliver optical properties for lidding film applications where seal integrity at 180-220°C defines performance.
- Polystyrene:High-impact grades serve cost-sensitive industrial tray formats where stiffness-to-weight ratios outweigh barrier requirements.
Polyethylene absorbs the bulk of installed capacity; polypropylene is expanding most quickly.
End User:
Customer concentration tilts toward multinational protein processors and retail private-label suppliers with centralized procurement functions spanning multiple production sites.
- Packaging:Modified atmosphere applications demand five- and seven-layer coextrusions with ethylene vinyl alcohol barrier layers, extending shelf life for premium meat and cheese formats in French and German retail.
- Healthcare:Pharmaceutical blister packers face 18-24 month stability testing cycles for new barrier films, delaying revenue recognition on recyclable formulation switches away from PVC-PVDC laminates.
- Automotive:Heavy-gauge industrial trays for component shipping prioritize dimensional stability over optical clarity.
- Food Service:Grab-and-go format expansion is scaling thermoformed clamshell procurement for home-delivery platforms.
Packaging commands the dominant revenue pool; healthcare offers the steepest expansion trajectory.
Thickness:
Gauge selection directly determines heating energy consumption and forming cycle speed, with thick-gauge formats squeezing margins in European manufacturing.
- Micro:Sub-100 micron calipers enable downgauging strategies that cut resin cost per unit in high-volume produce packaging for Aldi and Lidl central buying offices.
- Thin:100-250 micron specifications balance stiffness and material efficiency for standard food service trays.
- Medium:250-500 micron gauges serve industrial applications requiring structural rigidity during automated handling.
- Heavy:500-750 micron formats for automotive and logistics trays consume 40-60% more power per unit in electric infrared heating systems.
Thin gauges absorb the bulk of installed capacity; micro calipers are gaining share fastest.
Application:
Application-specific tooling investments lock converters into dedicated production lines, fragmenting capacity across forming equipment with limited format flexibility.
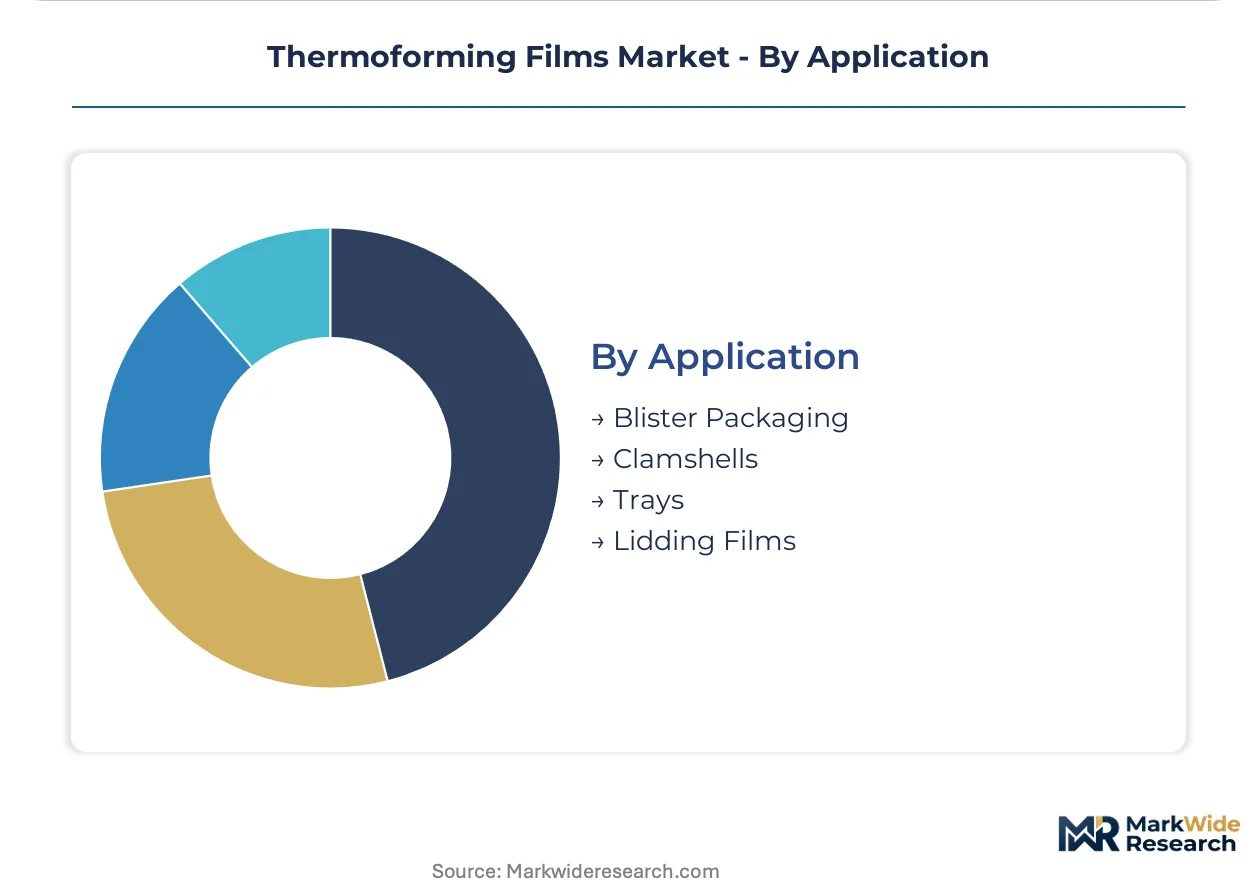
- Blister Packaging:Pharmaceutical validation requirements and low substitution elasticity create the highest margin pool, with packers qualifying recyclable polyethylene and cyclic olefin copolymer alternatives ahead of EU Green Deal implementation.
- Trays:Centralized dairy and meat processing in Germany drives high-volume film consumption for modified atmosphere protein packaging.
- Clamshells:Hinged formats for grab-and-go produce require precise score-line engineering to prevent hinge fracture during consumer handling.
- Lidding Films:Seal-layer compatibility with tray substrates determines line speed and leak resistance in high-speed filling operations.
Trays absorb the bulk of installed capacity; blister packaging is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Centralized protein and dairy processing clusters concentrate film demand in specific industrial corridors, with regulatory pressure on recycled content reshaping procurement geography across manufacturing regions.
Germany
The Ruhr industrial belt and Bavarian dairy corridors anchor European thermoforming film consumption through high-volume meat and cheese packaging operations. ECHA REACH restrictions on phthalate plasticizers force converters toward polypropylene alternatives, tightening formulation standards. Cologne-based film extruders secure multi-year supply agreements with Aldi and Lidl central buying offices for modified atmosphere tray specifications.
United States
FDA 21 CFR 177.1520 compliance requirements shape resin selection for direct-food-contact layers across Midwest protein processing hubs. State-level extended producer responsibility laws in California and New York fragment cost allocation between resin producers and brand owners. Chicago-area co-packers scale thermoformed clamshell procurement for home-delivery platform expansion.
China
Dual carbon goals and GB standards for food-contact plastics accelerate domestic converter investment in recyclable polyethylene formulations. Yangtze River Delta electronics manufacturers demand heavy-gauge industrial trays for component shipping with dimensional stability specifications. Shanghai-based film extruders integrate digital print-on-film systems for short-run customization.
France
Auvergne-Rhône-Alpes dairy processors and Île-de-France ready-meal packers drive lidding film demand where seal integrity at 180-220°C defines performance. EU Green Deal PPWR mandates pull investment into post-consumer polypropylene sorting infrastructure ahead of 2030 targets. Lyon-area converters qualify kraft-paper hybrid tray systems for retail produce packaging.
India
FSSAI food-contact regulations and PLI scheme incentives for packaging materials expand domestic film extrusion capacity across Maharashtra and Gujarat pharmaceutical corridors. Mumbai-based blister packers face compressed validation timelines for barrier film switches away from PVC-PVDC laminates. Ahmedabad converters develop mono-material polyethylene structures for dairy applications.
Thermoforming Films Market Competitive Environment
European producers anchor the integrated resin-to-film tier; North American specialists hold converter-focused positions. Market structure tilts toward consolidation among integrated petrochemical players with captive polymerization capacity, while mid-sized extruders fragment across specialized barrier formulations. Three archetypes dominate: integrated resin-film manufacturers securing long-term protein processor contracts, healthcare-focused converters prioritizing EMA validation cycles, and sustainability-oriented players with mass-balance certification capabilities. Capacity expansion and backward integration into resin sourcing represent the dominant competitive vectors.
Within the integrated manufacturing tier, Amcor and Berry Global exemplify scale-driven positions with captive supply chain control. Mondi Group occupies a distinct fiber-hybrid specialization, anchoring European demand through paper-based substrate alternatives that reduce plastic tonnage per tray. These three entities represent the structural concentration pattern where multi-year supply agreements with centralized retail buyers displace spot-market procurement.
| Leading Market Players |
|---|
| Amcor |
| Berry Global |
| Sealed Air Corporation |
| Mondi Group |
| Winpak |
| Coveris |
| Klöckner Pentaplast |
| Sonoco Products Company |
| FlexPak |
| Others |
Value Chain & Pricing Dynamics
Specialized polymer chemist clusters in the German Ruhr industrial belt drive labor-cost differentials that widen pricing-tier spreads between premium barrier coextrusions and commodity-grade polyethylene sheets.
Pricing Analysis
High-volume polyethylene tray films trade on razor-thin unit margins while pharmaceutical-grade PVC-PVDC laminates capture substantial value-add through EMA validation requirements. Price differentiation hinges on food-grade certification tier and barrier layer complexity, with FDA 21 CFR 177.1520 compliance commanding premiums over industrial applications. Pricing pressure stems from virgin polypropylene scarcity as EU Green Deal mandates compress recycled resin availability. Food service operators exhibit highest price sensitivity; pharmaceutical packers show lowest elasticity due to switching costs.
Supply Chain Analysis
Freight cost volatility from Middle Eastern resin feedstock routes disrupts European converter margins, particularly for inland processors lacking Rhine barge access. Supply concentrates in Germany, the Netherlands, and Belgium where integrated petrochemical complexes anchor resin-to-film manufacturing. Raw material dependencies center on propylene monomer, ethylene feedstock, and specialty barrier polymers like ethylene vinyl alcohol. Single-source vulnerability runs through concentrated German post-consumer polypropylene reprocessors. Distribution feeds through converter-direct relationships with Aldi and Lidl central buying offices, displacing traditional distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food-grade recycled polypropylene capacity bottlenecks prop pricing power for converters with secured offtake agreements, making this a supply-constrained market where resin access trumps volume scale.
For Market Incumbents: Extend backward integration into post-consumer polypropylene sorting and decontamination infrastructure ahead of EU Green Deal enforcement. Lock multi-year supply agreements with protein processors seeking mass-balance certification. Counter emerging sustainability-focused entrants by accelerating healthcare blister line conversions to recyclable polyethylene alternatives. For New Entrants and Emerging Players: EU Green Deal PPWR mandates in Germany open a window for specialized recyclers with EFSA-compliant decontamination capabilities. Target mid-sized Italian and Spanish converters lacking integrated resin sourcing as anchor customers. Penetrate through toll-manufacturing arrangements that bypass capital-intensive extrusion equipment investments. For Investors and Strategic Acquirers: The window for entry favors mass-balance-certified converters with pyrolysis offtake agreements and established pharmaceutical validation relationships. Prioritize acquisition targets with captive food-grade recycled resin access and healthcare barrier film pipelines. Watch for inflection when ECHA expands REACH restrictions beyond phthalates to additional plasticizer chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Resin Sourcing | Secures food-grade polypropylene supply ahead of EU Green Deal mandates. |
| Healthcare Blister Line Conversion | Captures pharmaceutical margin pools as EMA validates recyclable polyethylene alternatives. |
| Kraft-Paper Hybrid Tray Development | Reduces plastic tonnage per tray for Aldi and Lidl sustainability procurement criteria. |
| Digital Print-on-Film Integration | Enables short-run private-label customization for regional dairy co-packers. |
| Chemical Recycling Capacity Partnership | Locks mass-balance certification for protein processors facing PPWR compliance deadlines. |
Study Parameters
Independent corroboration across converter procurement directors, pharmaceutical packaging engineers, and resin sourcing managers underwrites the qualitative findings in this study. Primary fieldwork with film extrusion plant managers, retail private-label buyers at Aldi and Lidl, and EMA regulatory consultants combined with secondary validation from EU Green Deal implementation documents, ECHA REACH restriction filings, and trade customs data on polypropylene resin flows. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Comparable-period anchoring to historical resin price cycles and forming equipment utilization rates structured the forecast window across the analysis window. Segmentation dimensions modeled include resin chemistry tier, end-use application, gauge thickness specification, and geographic regulatory cluster. CAGRs derive from installed capacity expansion timelines correlated with protein processing volume growth and pharmaceutical packaging qualification pipelines. Forecast inputs incorporate EU Green Deal implementation pace and post-consumer polypropylene sorting infrastructure deployment.
The model assumes a particular technology adoption path; alternative pathways for chemical recycling scale-up would alter the outlook. Forecasts reflect assumptions about EMA validation timeline compression and ECHA regulatory expansion scope. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
India BOPP Films Market
Poly film
APET Film Market
Poly film
Global Blown Stretch Packaging Films Market
Poly film
Global Reclosable Films Market
Poly film
Hexacomb Packaging Market
Poly film
Thermoplastic Polyurethane (TPU) Films Market
Poly film
Twist Wrap Film Market
Poly film
Asia Pacific Plastic Packaging Film Market
Poly film
Printed Plastic Films Market
Poly film
Foamed Polypropylene Films Market
Poly film
Polyimide Films and Tapes Market
Poly film
PP Laminating Films Market
Poly film
Polyethylene Film Market
Poly film
Polyolefin Battery Separator Films Market
Poly film
UAE Plastic Packaging Films Market
Poly film
Polyethylene Furanoate Films Market