
 Soft Touch Film Market | 2026-2036
Soft Touch Film Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Touch Film Market Analytics
Premium cosmetics and luxury spirits brands is collapsing toward mass-market personal care and quick-service food packaging as the fastest-growing buyer archetype. Amcor Limited leverages its global converting footprint to sustain supply security for multinational CPG accounts. Avery Dennison Corporation anchors North American demand through specialized pressure-sensitive constructions. Cosmo Films competes on cost-efficient polypropylene formulations serving Asian label converters.
Soft touch film denotes a surface-modified polymer substrate engineered to deliver a velvet-like tactile sensation, typically achieved through UV-cured lacquer coatings or extruded matte layers measuring 12–50 micrometers in caliper, designed primarily to elevate perceived product value on retail shelves. Self-adhesive and pressure-sensitive formats dominate current volume as brand owners prioritize seamless integration with existing label application lines, while laminated constructions capture margin pools in electronics and automotive segments demanding superior scratch resistance. Polypropylene substrates lead unit economics due to favorable yield and printability, though PET formulations extend into healthcare and high-durability applications where dimensional stability governs specification.
REACH in Europe restricts phthalate plasticizers and mandates SVHC disclosure, compelling reformulation of PVC-based soft touch films toward non-halogen alternatives. FDA food-contact notification requirements govern migration limits for coatings in U.S. retail packaging, directly influencing material selection and supplier qualification timelines. ISO 9001 and ISO 14001 certifications function as baseline market access filters across developed economies, with automotive OEMs layering IATF 16949 demands onto healthcare-grade film suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks in the European Union and pending state-level packaging legislation in California and New York to anticipate compliance-driven specification shifts before they harden into procurement mandates.
Market Dynamics
REACH compliance deadlines are forcing immediate reformulation of PVC-based soft touch films toward non-halogen alternatives, compressing supplier qualification timelines and reshaping raw material procurement across European converting operations.
Growth Catalysts
- Cosmetics shelf differentiation:Premium beauty brands in Germany and France deploy velvet-touch laminates to command tactile attention in crowded retail environments, driving specialized film specifications.
- REACH SVHC disclosure mandates:ECHA's expanding candidate list accelerates substitution of phthalate plasticizers, creating specification windows for compliant polyurethane and acrylic coating systems.
- Automotive interior clusters:Frankfurt and Munich anchor luxury vehicle cockpit applications where soft touch films replace painted surfaces to reduce weight and assembly complexity.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene resin prices fluctuate with naphtha cracking economics, squeezing converter margins on fixed-price label contracts.
- East Asian supply concentration:BOPP substrate capacity clusters in Zhejiang and Jiangsu provinces, exposing European and North American buyers to shipping cost spikes and tariff uncertainty.
- Digital print substitution:Direct-to-shape inkjet on rigid containers eliminates label demand entirely in spirits and personal care segments above 500ml pack sizes.
Strategic Opportunities
- Indian personal care expansion:Mumbai and Delhi-based contract manufacturers serving Unilever and P&G affiliates lack qualified domestic soft touch suppliers, creating import substitution openings.
- Healthcare durable goods:ISO 10993-compliant PET formulations penetrate medical device housings and diagnostic equipment panels where antimicrobial surface properties command premium pricing.
- California SB 54 implementation:Extended producer responsibility rules for plastic packaging incentivize mono-material soft touch constructions that simplify post-consumer recycling streams.
Industry Challenges
- UV coating technician scarcity:European converters report 18-month training curves for operators mastering electron-beam and UV-LED curing parameter optimization.
- IATF 16949 certification burden:Automotive OEM qualification requires 24-month audit cycles that exclude smaller film coaters from tier-one supply pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Touch Film Market |
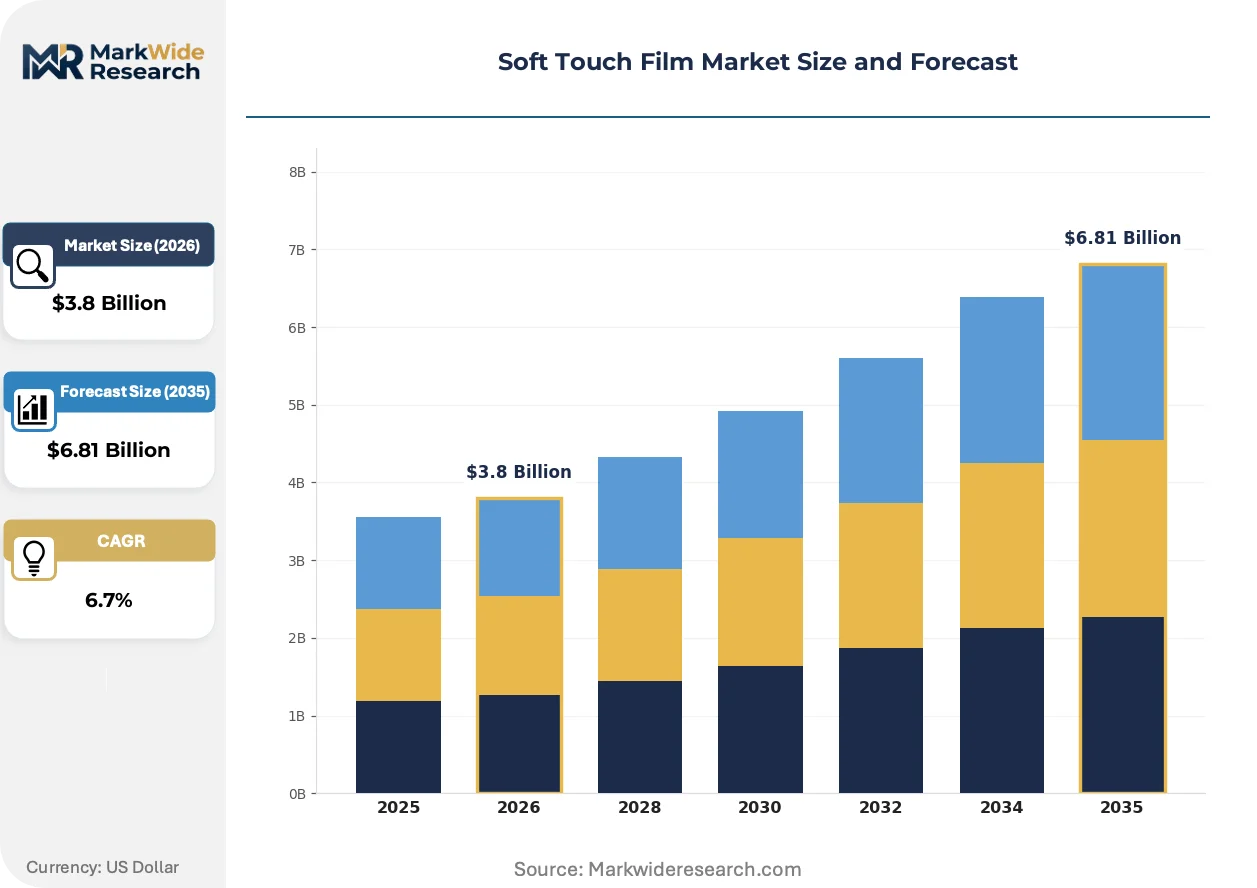
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhesive, Pressure-Sensitive, Laminated, Coated Application: Packed Goods, Retail Packaging, Labels, Book Covers Material: PVC, PET, Polypropylene, Nylon End User: Consumer Goods, Electronics, Automotive, Healthcare |
| Companies Covered | Amcor Limited, Avery Dennison Corporation, DUNMORE Corporation, Cosmo Films, Monotech Systems, Flex Films, Taghleef Industries, Jet Technologies, Doro Tape, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Touch Film Market Evolving Landscape
Water-based coating chemistries and energy-cured matte finishes are collapsing the historical trade-off between tactile performance and regulatory compliance, enabling simultaneous achievement of velvet hand-feel and food-contact safety.
Electron-beam cured silicone-urea hybrid coatings is supplanting solvent-based UV lacquers in high-speed converting lines. German automotive suppliers at KBA-registered facilities adopt these systems to eliminate volatile organic compound emissions while maintaining scratch resistance above 500g pencil hardness. The technology is supplanting incumbent coating houses that lack capital for accelerator infrastructure, consolidating specification authority among integrated film manufacturers.
EU F-Gas Regulation phase-down schedules are compressing availability of fluorinated polymer additives historically used for stain resistance in soft touch laminates. Converter operations in Italy and Spain face reformulation deadlines that collide with existing inventory amortization cycles, pushing accelerated qualification of ceramic nanoparticle alternatives. Healthcare packaging segments in Switzerland and the Netherlands experience the tightest compliance windows due to Swissmedic and parallel EMA device labeling requirements.
Brand owner consolidation into centralized procurement functions is collapsing historical distributor networks in favor of direct mill relationships. Large CPG accounts in the United Kingdom and Ireland now specify film performance metrics rather than finished label constructions, transferring coating and lamination risk to converters. This pattern concentrates most visibly in beverage alcohol, where Diageo and Pernod Ricard affiliates demand single-source accountability for tactile quality across 12+ bottling locations.
Soft Touch Film Market Segmentation
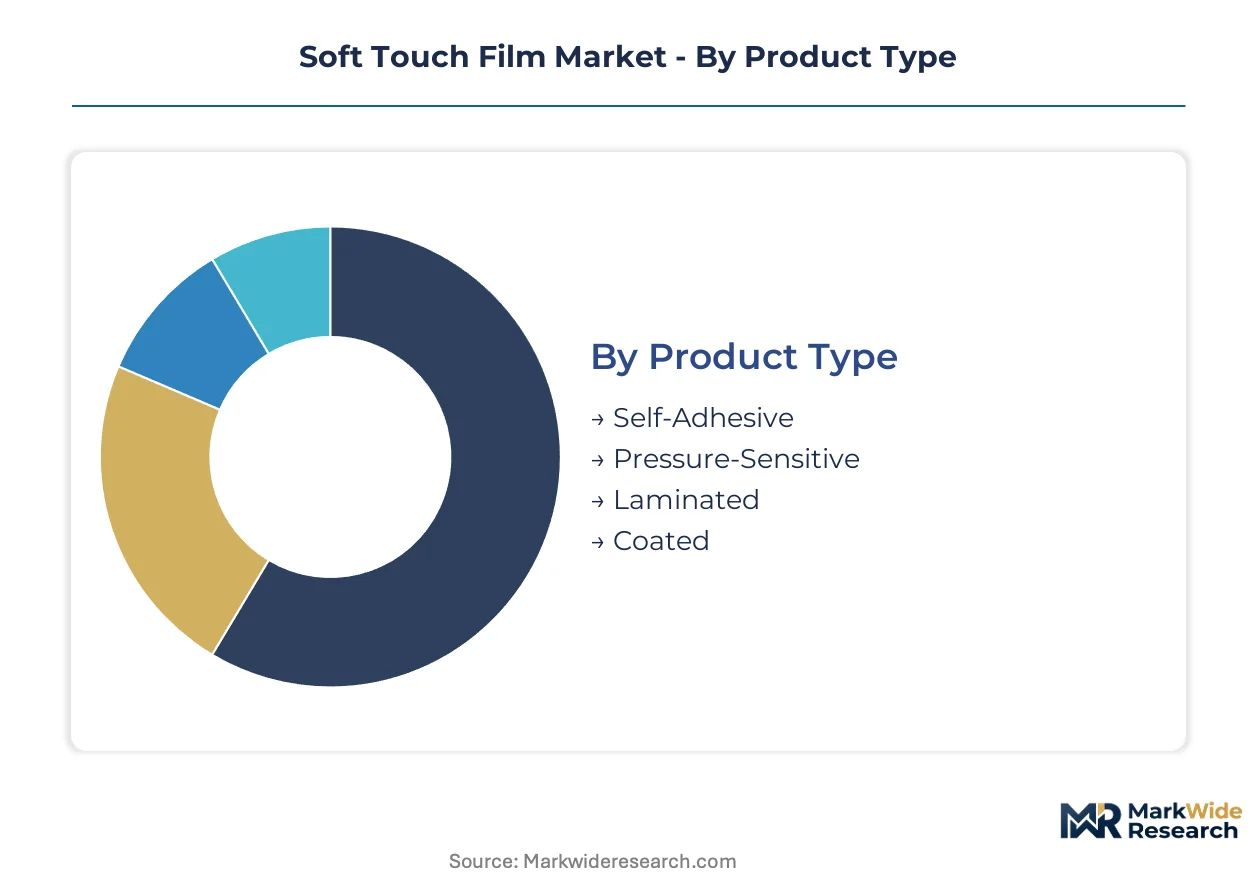
Soft touch film specifications fragment across adhesive chemistry, substrate selection, and end-use durability requirements. Procurement decisions trade tactile performance against regulatory compliance timelines and converting equipment compatibility.
Product Type:
Margin pools concentrate in laminated and pressure-sensitive formats where coating complexity and certification burdens limit supplier entry.
- Self-Adhesive:Acrylic or rubber-based adhesive layers bonded directly to soft-touch substrates enable immediate application without secondary gluing equipment. Demand clusters in German and French cosmetics labeling where brand owners mandate seamless integration with existing bottling lines.
- Pressure-Sensitive:Face stock, adhesive, and release liner constructions deliver repositionability and clean removability. Electronics and automotive segments in Frankfurt and Munich specify these formats for device housings and interior trim where residue-free removal governs warranty compliance.
- Laminated:Multi-layer constructions with protective top coats achieve superior scratch resistance above 500g pencil hardness.
- Coated:UV-cured or electron-beam cured surface treatments applied to base films create velvet tactile properties.
The dominant share belongs to pressure-sensitive formats, while laminated constructions are closing the gap fastest in automotive qualification pipelines.
Application:
Volume concentrates in retail-facing formats where shelf differentiation justifies material premiums over standard gloss laminates.
- Packed Goods:Food-contact compliant soft touch films for premium confectionery and spirits cartons require migration-tested coatings meeting FDA notification thresholds. REACH-compliant polyurethane systems are displacing legacy PVC formulations in European chocolate and liquor packaging.
- Labels:Pressure-sensitive and shrink-sleeve formats dominate beverage alcohol and personal care segments where tactile engagement drives unplanned purchase decisions. Diageo and Pernod Ricard affiliates specify velvet-touch labels across bottling locations in the United Kingdom and Ireland.
- Retail Packaging:Folding cartons and rigid box wraps for luxury cosmetics and jewelry leverage soft touch films to signal premium positioning.
- Book Covers:Educational and specialty publishing in India and Southeast Asia adopt matte-laminate alternatives for durability.
Labels command the largest volume position, though packed goods applications are expanding most quickly as food-contact coating technologies mature.
Material:
Unit economics and printability separate substrate choices, with regulatory pressure increasingly constraining historical PVC dominance.
- Polypropylene:Biaxially oriented polypropylene delivers favorable yield ratios and compatibility with flexographic and gravure printing. Asian converters in Zhejiang and Jiangsu provinces supply cost-efficient volumes serving mass-market personal care and quick-service food packaging.
- PET:Dimensional stability and chemical resistance extend into healthcare device housings and diagnostic equipment panels where ISO 10993 compliance and antimicrobial surface properties command premium specifications. Swissmedic and EMA device labeling requirements tighten qualification windows in Switzerland and the Netherlands.
- PVC:Phthalate plasticizer restrictions under REACH SVHC disclosure mandates are accelerating substitution toward non-halogen alternatives.
- Nylon:High-temperature stability and abrasion resistance serve specialized industrial and automotive under-hood applications.
Polypropylene substrates retain the dominant position, while PET formulations are gaining share fastest in healthcare and automotive durability segments.
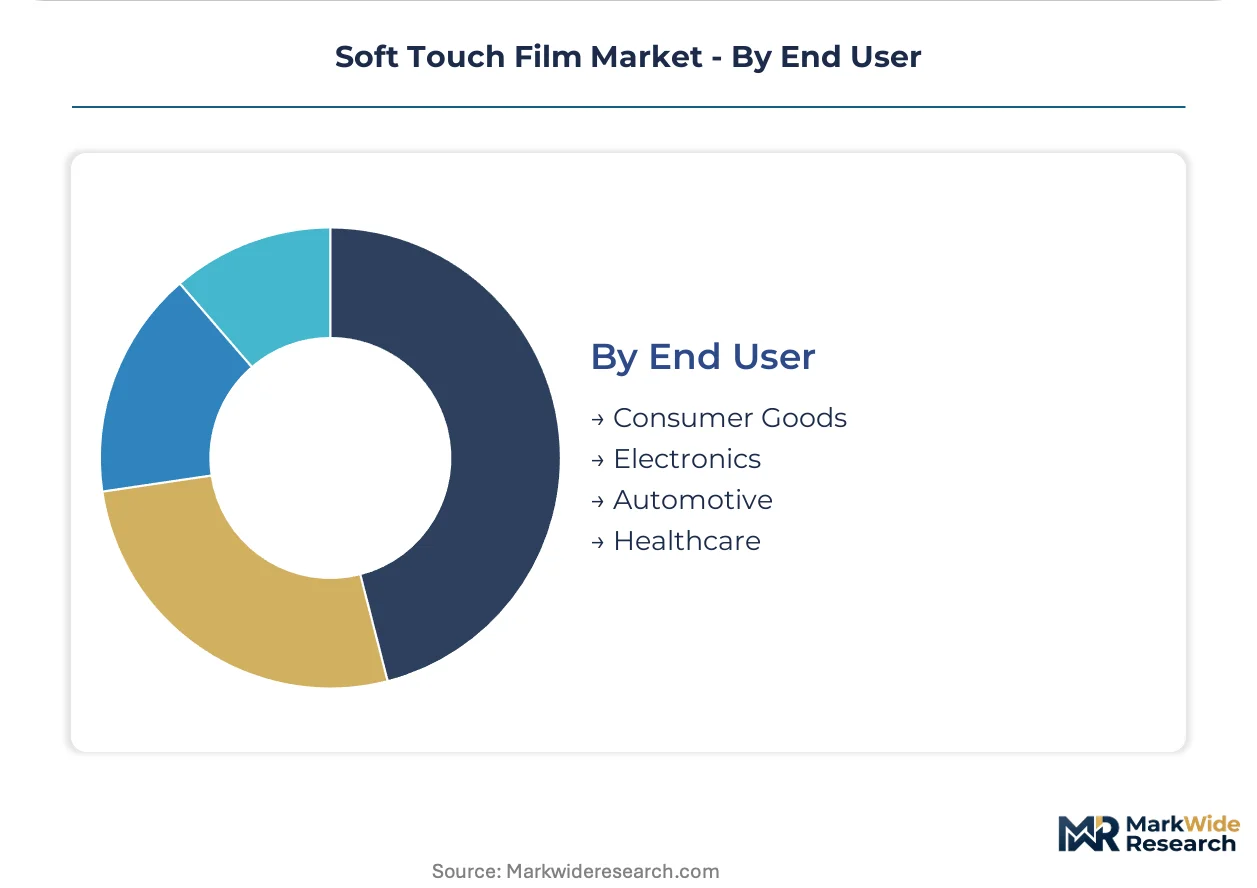
End User:
Customer concentration and specification authority concentrate in multinational CPG and automotive OEM accounts with centralized procurement functions.
- Consumer Goods:Premium cosmetics and luxury spirits brands in Germany and France deploy velvet-touch laminates for tactile shelf differentiation. Unilever and P&G affiliates in Mumbai and Delhi source through contract manufacturers lacking qualified domestic soft touch suppliers.
- Automotive:Frankfurt and Munich luxury vehicle cockpit applications replace painted surfaces with soft touch films to reduce weight and assembly complexity. IATF 16949 certification requirements exclude smaller film coaters from tier-one supply pools.
- Electronics:Device housings and accessory packaging specify scratch-resistant laminated constructions.
- Healthcare:Medical device panels and diagnostic equipment demand ISO 10993-compliant PET with antimicrobial properties.
Consumer goods absorbs the dominant demand share, while automotive applications are climbing the fastest as interior electrification trends accelerate surface material substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports biaxially oriented polypropylene substrates to European and North American label converters, while Germany ships specialized automotive-grade laminates to tier-one cockpit suppliers across the continent.
Germany
Luxury automotive interior applications and high-end cosmetics packaging drive specialized film consumption. ECHA's REACH SVHC disclosure mandates accelerate substitution of phthalate plasticizers in PVC-based formulations. Frankfurt and Munich anchor clusters where soft touch films replace painted surfaces in vehicle cockpits.
United States
Quick-service food packaging and mass-market personal care brands expand adoption of food-contact compliant coatings. FDA notification requirements govern migration limits for retail packaging coatings, directly influencing material selection timelines. Converting operations concentrate in the Midwest and Southeast serving multinational CPG accounts.
China
Cost-efficient polypropylene formulations serve Asian label converters and export markets. The country's national chemical regulator enforces evolving standards on plasticizer content in packaging materials. Zhejiang and Jiangsu provinces cluster BOPP substrate capacity, exposing buyers to shipping cost volatility.
India
Mumbai and Delhi-based contract manufacturers serving Unilever and P&G affiliates lack qualified domestic soft touch suppliers, creating import substitution openings. BIS certification requirements for packaging materials slow local qualification timelines. Maharashtra and Gujarat host emerging converting capacity targeting personal care export contracts.
Switzerland
Healthcare packaging segments demand ISO 10993-compliant PET formulations for medical device housings. Swissmedic device labeling requirements tighten compliance windows compared to parallel EMA standards. Basel and Zurich anchor precision film coating operations serving pharmaceutical OEMs.
Soft Touch Film Market Competitive Landscape
Player mix skews toward integrated film manufacturers with captive coating capacity and specialized converters serving automotive qualification pipelines. Market structure concentrates specification authority among tier-one suppliers holding IATF 16949 and ISO 10993 certifications, while mid-scale coaters compete on turnaround speed for cosmetics and beverage alcohol label contracts. Strategic archetypes include multinational packaging conglomerates with global converting footprints, regional substrate specialists optimizing polypropylene yield economics, and healthcare-focused coaters commanding premium pricing for antimicrobial surface properties. Dominant competitive moves encompass backward integration into resin compounding to secure feedstock margins and geographic expansion into underqualified markets like India.
Within the multinational conglomerate tier, Amcor Limited and Avery Dennison Corporation exemplify scale-driven positions. Amcor leverages its global converting footprint to sustain supply security for centralized CPG procurement functions. Avery Dennison anchors North American demand through specialized pressure-sensitive constructions. Among Asia-Pacific substrate specialists, Cosmo Films occupies a position competing on cost-efficient polypropylene formulations.
| Leading Market Players |
|---|
| Amcor Limited |
| Avery Dennison Corporation |
| DUNMORE Corporation |
| Cosmo Films |
| Monotech Systems |
| Flex Films |
| Taghleef Industries |
| Jet Technologies |
| Doro Tape |
| Others |
Value Network & Pricing Analysis
Electron-beam cured silicone-urea coatings displacing solvent-based UV lacquers simultaneously concentrates specification authority among German KBA-registered integrated manufacturers and collapses historical coating-house margins, reshaping procurement economics for European automotive and electronics buyers.
Pricing Analysis
Technology-generation pricing gaps separate electron-beam cured systems from legacy UV-LED and conventional solvent-based alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with IATF 16949-certified automotive laminates commanding sustained premiums over cosmetics-grade constructions. Cost compression in standard-tier polypropylene label films is intensifying because Zhejiang and Jiangsu substrate oversupply exposes converters to fixed-price contract renegotiations. Mass-market personal care brands exhibit highest price sensitivity, while healthcare OEMs purchasing ISO 10993-compliant PET formulations demonstrate lowest elasticity due to Swissmedic-mandated qualification timelines.
Supply Chain Analysis
Strategic stockpile preferences dominate automotive qualification pipelines where 24-month IATF audit cycles necessitate buffer inventory, contrasting with just-in-time practices in beverage alcohol label converting. Biaxially oriented polypropylene substrate supply concentrates in China, South Korea, and Germany, drawing from naphtha cracking economics and specialized resin compounding capabilities. Raw material dependencies rest on polypropylene resin, UV-curable acrylate oligomers, and electron-beam accelerator infrastructure. Single-source vulnerability in fluorinated polymer additives under EU F-Gas Regulation phase-down schedules threatens Italian and Spanish converter operations. Distribution runs through direct mill relationships with multinational CPG accounts, bypassing historical distributor networks in the United Kingdom and Ireland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soft touch film market sits in a cyclical recovery phase driven by automotive interior electrification trends accelerating surface material substitution away from painted components.
For Market Incumbents: Shield margin pools in automotive qualification pipelines by deepening backward integration into electron-beam accelerator infrastructure before KBA-registered competitors consolidate specification authority. Accelerate REACH-compliant polyurethane system R&D to preempt ECHA SVHC disclosure mandates that threaten legacy PVC formulation inventories. For New Entrants and Emerging Players: Anchor in Mumbai and Delhi contract manufacturing clusters serving Unilever and P&G affiliates where qualified domestic soft touch suppliers remain absent. Target food-contact compliant coating capabilities for quick-service food packaging as the most penetrable segment given FDA notification requirement maturation. Pursue technical licensing arrangements with established European coaters to compress BIS certification timelines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated film manufacturers with captive coating capacity and IATF 16949 certification infrastructure. Long-term viability hinges on exposure to healthcare durable goods and automotive electrification tailwinds rather than commoditized cosmetics label converting. Watch electron-beam curing adoption rates among German tier-one suppliers as the inflection indicator for specification authority concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Secures polypropylene feedstock margins against naphtha cracking volatility in Zhejiang supply clusters. |
| Electron-Beam Accelerator Infrastructure Deployment | Enables KBA-registered facilities to eliminate VOC emissions while maintaining 500g pencil hardness specifications. |
| ISO 10993 Certification Investment | Opens Swissmedic and EMA device labeling qualification windows for PET healthcare formulations. |
| Direct Mill Relationship Cultivation | Bypasses collapsing distributor networks serving Diageo and Pernod Ricard centralized procurement functions. |
| California SB 54 Compliant Mono-Material Development | Positions converters for extended producer responsibility rules simplifying post-consumer recycling streams. |
Research Methodology
A spread of perspectives from film coating line operators, automotive tier-one procurement managers, cosmetics brand packaging directors, and healthcare device OEMs converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC 10-K filings of multinational packaging conglomerates, ECHA SVHC candidate list publications, and FDA food-contact notification databases. Bottom-up triangulation across substrate volume estimates and top-down reconciliation against end-use demand patterns anchored the analytical framework.
Segmentation dimensions modeled encompass substrate material, adhesive chemistry format, coating technology generation, end-use durability tier, and regional regulatory cluster across the analysis window. CAGRs were derived from elasticity-adjusted demand projections and substitution rate assumptions for electron-beam curing adoption. Industry-specific forecast inputs incorporated REACH compliance deadline impacts on PVC formulation phase-out and IATF 16949 certification pipeline constraints.
Decision-makers should treat outputs as directional under assumptions of sustained automotive electrification investment and ECHA regulatory enforcement continuity; material deviation would warrant model refresh. Specific risk factors include fluorinated polymer additive supply disruptions under EU F-Gas Regulation and digital print substitution acceleration in spirits packaging above 500ml formats. Revision becomes warranted when electron-beam curing capital expenditure commitments among German coaters cross threshold inflection levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Middle East and Africa Plastic Packaging Films Market
Poly film
Peelable and Resealable Films Market
Poly film
Craft Plastic Films Market
Poly film
Poly Coated Kraft Paper Market
Poly film
PE Foam Films Market
Poly film
Global EVOH Films for Packaging Market
Poly film
Co Extruded Films Market
Poly film
Shrink Bundling Films Market
Poly film
Bio-PET Film Market
Poly film
High Density Polyethylene Film Market
Poly film
Asia Pacific Plastic Packaging Film Market
Poly film
Cellulose Film Packaging Market
Poly film
Global Blown Stretch Packaging Films Market
Poly film
Metallized Film Market
Poly film
Polysaccharide Films Market
Poly film
Hexacomb Packaging Market