
 Poly Coated Kraft Paper Market | 2026-2036
Poly Coated Kraft Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Poly Coated Kraft Paper Market Analytics
The EU Green Deal is realigning procurement specifications for food-contact packaging across European consumer goods supply chains. Mondi leverages integrated pulp-to-paper operations across Central European mills to sustain cost advantages in coated kraft output. WestRock Company anchors North American supply through extensive containerboard networks, while Billerud specializes in high-barrier Nordic kraft grades for premium food applications. Smurfit Kappa competes on converted packaging solutions that integrate coated kraft into finished box formats.
Poly coated kraft paper consists of unbleached or bleached kraft pulp sheets laminated with polyethylene or alternative barrier coatings, typically achieving moisture vapor transmission rates below 10 g/m²/day for food-grade specifications. This construction delivers grease resistance and structural rigidity for direct-contact food packaging, industrial wrapping, and moisture-sensitive labeling applications. Brown Kraft dominates volume throughput in e-commerce corrugated liners and shipping sacks where cost efficiency outweighs aesthetic requirements, while Specialty Kraft captures margin concentration in pharmaceutical serialization labels and medical device pouches demanding customized barrier properties. White Kraft occupies the premium tier in retail-ready food packaging where printability and consumer visibility intersect.
REACH compliance through ECHA governs coating chemical approvals across European supply chains, while FDA food-contact substance notifications regulate US import eligibility for polyethylene-coated grades. The EU Packaging and Packaging Waste Regulation, enforced through national agencies in France and Germany, mandates recyclability thresholds that favor mono-material or fiber-dominant constructions over multi-layer alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks and coating chemistry substitution timelines to preserve market access across diverging regulatory jurisdictions.
Market Dynamics
The EU Green Deal's packaging waste directives are compressing demand for multi-layer barrier films while accelerating specification shifts toward fiber-dominant, recyclable constructions across European food manufacturing supply chains.
Growth Catalysts
- E-commerce fulfillment expansion:Germany's industrial packaging corridor is scaling brown kraft output for corrugated liners and shipping sacks as online retail penetration deepens across Central European logistics networks.
- REACH-compliant coating chemistry:ECHA-approved polyethylene alternatives are unlocking food-contact applications previously restricted by legacy barrier material registrations.
- Grease-resistant food packaging mandates:Quick-service restaurant chains across France and Italy are converting fry cartons and sandwich wraps to poly-coated kraft formats meeting direct-contact specifications.
Market Restraints
- Polyethylene resin cost volatility:Fossil-based coating feedstock price swings compress margin predictability for converters operating on fixed-price annual contracts.
- Pulp supply concentration:Nordic kraft pulp integration into a limited mill base creates bottleneck risk for specialty-grade coated paper output.
- Mono-material substitution pressure:Uncoated high-performance kraft variants are capturing share in non-critical barrier applications where moisture protection requirements have softened.
Strategic Opportunities
- Pharmaceutical serialization labels:White kraft grades with customized barrier properties are penetrating medical device pouches and cold-chain documentation sleeves in Switzerland and Austria.
- Extended producer responsibility frameworks:France's national packaging agency is incentivizing fiber-dominant constructions through modulated eco-modulation fees that penalize non-recyclable multi-layer alternatives.
- Bio-based coating convergence:Polylactic acid and cellulose-derived barrier layers are converging with conventional kraft substrates to create compostable packaging qualified for industrial organic waste streams.
Industry Challenges
- Coating chemistry certification timelines:ECHA's substance evaluation windows for novel barrier polymers extend 18-24 months, delaying product launch schedules for reformulated grades.
- Recyclability testing protocol fragmentation:Divergent national accreditation requirements across Germany, France, and Italy force redundant laboratory validation for pan-European product qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poly Coated Kraft Paper Market |
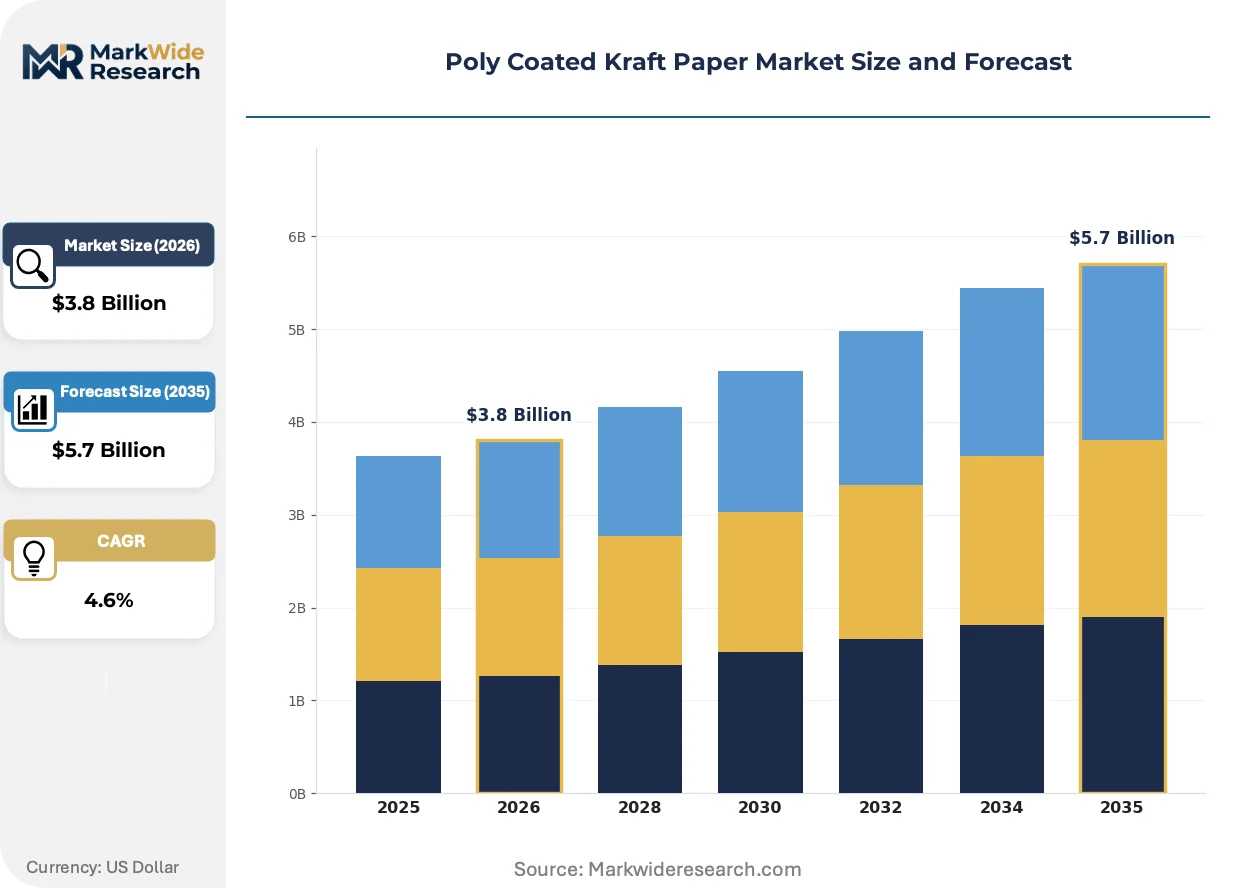
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Kraft, Brown Kraft, Colored Kraft, Specialty Kraft Application: Packaging, Printing, Labeling, Wrapping End User: Food Industry, Retail, Consumer Goods, Pharmaceutical Distribution Channel: Online, Offline, Direct Sales, Distributors |
| Companies Covered | Mondi, Segezha Group, WestRock Company, Stora Enso, International Paper, Smurfit Kappa, Billerud, Nordic Paper, Oji Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poly Coated Kraft Paper Market Evolving Landscape
Barrier coating chemistry is undergoing systematic substitution as regulatory thresholds tighten and brand owners accelerate decarbonization commitments across packaging procurement specifications.
Water-based dispersion coatings are absorbing market share from extruded polyethylene laminates in medium-barrier food applications. Bakery and confectionery packagers across Belgium and the Netherlands are piloting these formats at commercial scale. The technology is absorbing capital allocation from conventional extrusion lines as converters anticipate stricter recyclability mandates.
The EU Packaging and Packaging Waste Regulation is mandating design-for-recycling criteria that disqualify multi-material constructions from extended producer responsibility fee reductions. Industrial packaging buyers in Germany are rewriting technical specifications to favor mono-material kraft constructions. Food-contact segments are responding by accelerating qualification of fiber-dominant barrier solutions ahead of enforcement timelines.
Centralized procurement consolidation among pan-European food manufacturers is compressing supplier qualification cycles and demanding integrated coating-to-conversion capabilities. Legacy spot-buying arrangements through distributors are yielding to direct mill relationships with technical service integration. This pattern is most visible in Germany's Ruhr industrial corridor where major dairy and meat processors have consolidated packaging spend under category management structures.
Poly Coated Kraft Paper Market Segmentation
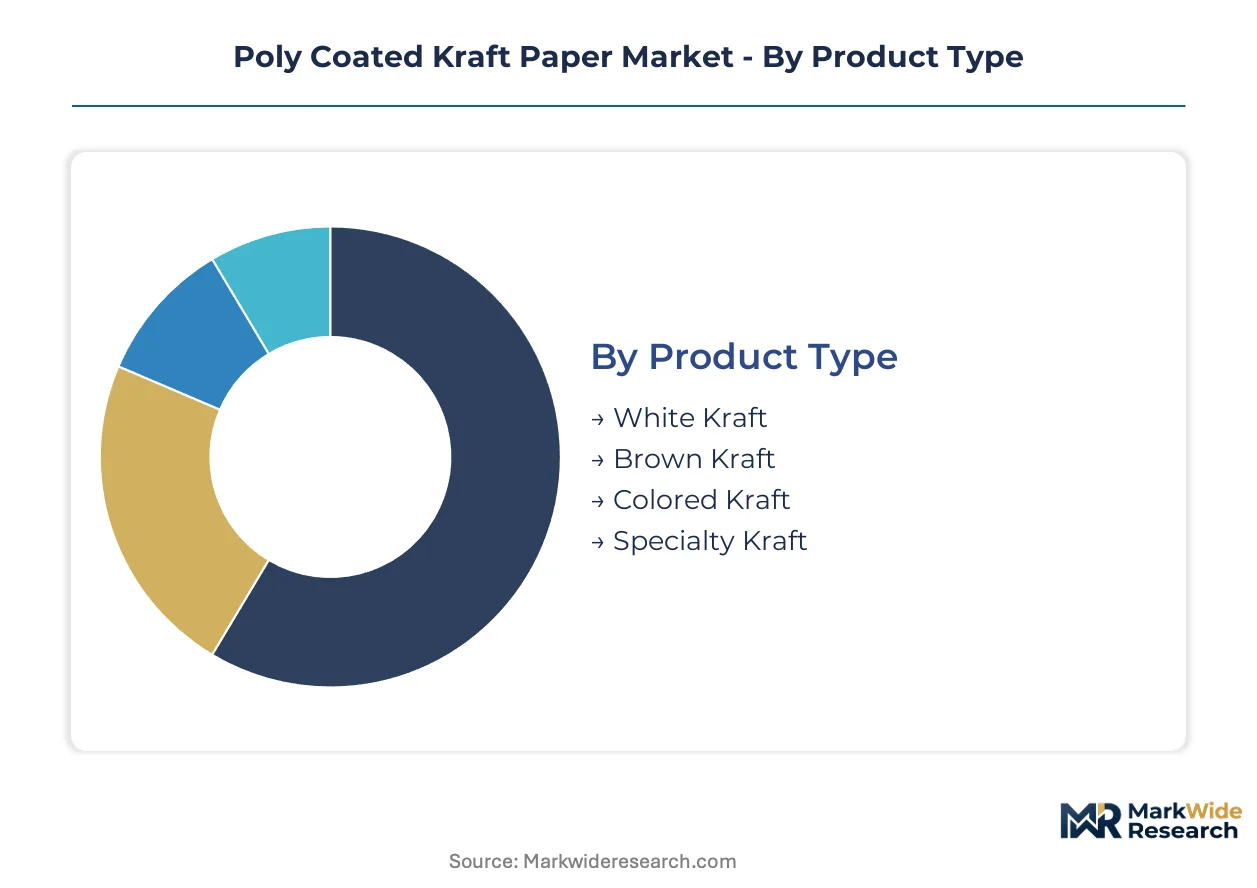
Poly coated kraft paper segmentation reveals distinct certification burdens across product grades, with food-contact specifications demanding REACH-compliant coatings through ECHA while industrial applications face lighter regulatory loads. End-user concentration in Central European food manufacturing and pharmaceutical corridors creates divergent margin profiles across segments.
Product Type:
FDA food-contact substance notifications govern white kraft grades destined for US import markets, while brown kraft shipping materials face minimal coating chemistry restrictions. Specialty kraft for medical applications triggers Swissmedic and EMA device packaging standards.
- Brown Kraft:Unbleached kraft pulp sheets laminated with standard polyethylene coatings achieve moisture vapor transmission rates below 10 g/m²/day. Demand concentrates in Germany's Ruhr industrial corridor for e-commerce corrugated liners and shipping sacks where cost efficiency outweighs aesthetic requirements.
- White Kraft:Bleached kraft substrates with premium barrier coatings deliver superior printability for retail-ready food packaging. Quick-service restaurant chains across France and Italy are converting sandwich wraps and fry cartons to this format as direct-contact specifications tighten.
- Colored Kraft:Pigmented kraft grades with matched coating tints serve branded retail packaging and gift wrap applications in Belgian and Dutch consumer goods markets.
- Specialty Kraft:Customized barrier constructions for pharmaceutical serialization labels and medical device pouches in Switzerland and Austria meet cold-chain documentation requirements.
Leading the category by volume: Brown Kraft. Growing fastest: Specialty Kraft.
Application:
Packaging applications absorb the heaviest regulatory scrutiny through the EU Packaging and Packaging Waste Regulation, while printing and labeling segments navigate divergent national recyclability testing protocols across Germany, France, and Italy.
- Packaging:Direct-contact food packaging dominates throughput, with bakery and confectionery packagers across Belgium and the Netherlands piloting water-based dispersion coatings at commercial scale.
- Printing:High-resolution flexographic and offset applications on white kraft grades serve retail advertising inserts and catalog covers where surface smoothness commands premium positioning.
- Labeling:Pharmaceutical serialization labels with customized barrier properties penetrate medical device pouches and cold-chain documentation sleeves in Swiss and Austrian healthcare supply chains.
- Wrapping:Industrial wrapping for moisture-sensitive machinery components leverages brown kraft's structural rigidity across German automotive and metalworking clusters.
Packaging commands the largest volume share. Labeling climbs fastest on pharmaceutical serialization mandates.
End User:
Food Industry procurement concentrates under category management structures that demand integrated coating-to-conversion capabilities, while Pharmaceutical buyers impose Swissmedic and EMA device packaging certifications.
- Food Industry:Dairy and meat processors in Germany's industrial packaging corridor have consolidated packaging spend under centralized procurement, rewriting technical specifications to favor mono-material kraft constructions ahead of EU enforcement timelines.
- Retail:E-commerce fulfillment networks across Central Europe scale brown kraft output for corrugated liners as online retail penetration deepens across logistics networks.
- Consumer Goods:Branded household products in Belgium and the Netherlands specify colored kraft for shelf differentiation and unboxing experience optimization.
- Pharmaceutical:Medical device manufacturers in Switzerland and Austria qualify white kraft grades with customized barrier properties for cold-chain documentation and serialization compliance.
Food Industry leads by volume. Pharmaceutical expands most quickly on barrier customization demand.
Distribution Channel:
Direct Sales relationships with technical service integration are displacing legacy spot-buying through distributors as pan-European food manufacturers consolidate procurement, while Online channels capture specification-grade orders for standardized grades.
- Direct Sales:Integrated coating-to-conversion capabilities anchor mill-direct relationships with major dairy and meat processors in Germany's Ruhr corridor, compressing supplier qualification cycles.
- Distributors:Regional paper merchants maintain inventory positions for brown kraft shipping materials serving fragmented industrial buyers across Central European manufacturing zones.
- Online:Digital procurement platforms capture standardized white and brown kraft grades from buyers with established specifications and reduced technical service requirements.
- Offline:Traditional trade relationships persist in specialty kraft segments where customized barrier properties demand face-to-face specification development.
Direct Sales dominates volume. Online channels gain share fastest on procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Nordic and Central European pulp-to-paper corridors, while consumption gravity pulls toward German industrial zones and Mediterranean food manufacturing clusters. This geographic split creates freight arbitrage opportunities for integrated mill operators with multi-country distribution networks.
Germany
Dairy and meat processors in the Ruhr industrial corridor drive brown kraft demand for corrugated shipping materials and direct-contact food packaging. The national packaging agency enforces EU Packaging and Packaging Waste Regulation recyclability thresholds that favor mono-material kraft constructions. Converter operations in North Rhine-Westphalia are scaling water-based dispersion coating lines ahead of 2025 enforcement timelines.
France
Quick-service restaurant chains across Île-de-France and Provence-Alpes-Côte d'Azur are converting fry cartons and sandwich wraps to poly-coated white kraft formats. ANSM and national environmental agencies administer extended producer responsibility fee modulation that penalizes non-recyclable multi-layer alternatives. Bakery packagers in the Hauts-de-France region are piloting commercial-scale fiber-dominant barrier solutions.
Italy
Confectionery and prepared food manufacturers in Lombardy and Emilia-Romagna specify grease-resistant kraft grades for retail-ready packaging applications. REACH compliance through ECHA governs coating chemical approvals for food-contact specifications across Italian supply chains. Industrial packaging buyers in the Veneto automotive cluster are rewriting technical specifications to exclude multi-material constructions.
Switzerland
Medical device manufacturers and pharmaceutical serialization operations in the Basel-Zurich corridor demand specialty kraft grades with customized barrier properties for cold-chain documentation. Swissmedic device packaging standards trigger certification requirements that exceed baseline EU specifications. Precision converters in the Mittelland region are qualifying white kraft substrates for pharmaceutical pouch applications.
Belgium
Branded consumer goods and retail packaging operations in Flanders specify colored kraft grades for shelf differentiation and unboxing experience optimization. National implementation of EU Green Deal packaging waste directives is compressing demand for legacy polyethylene-laminated formats. Logistics hubs in the Antwerp-Brussels corridor are scaling brown kraft output for e-commerce fulfillment networks serving Benelux markets.
Poly Coated Kraft Paper Market Competitive Landscape
The competitive structure tilts toward integrated pulp-to-paper conglomerates with captive coating capabilities and geographic diversification across multiple regulatory jurisdictions. Tier-one positions are occupied by Nordic and North American operators with backward integration into kraft pulp supply. Three archetypes dominate: integrated forest products groups with multi-continent mill networks, regional specialty converters focusing on high-barrier medical and food grades, and packaging solutions providers bundling coated kraft into finished box formats. Consolidation through mill acquisitions and strategic partnerships for bio-based coating development are the primary competitive moves reshaping supplier rankings.
Among Nordic-based integrated operators, Mondi and Billerud exemplify the forest-to-finished-product archetype with extensive Central European manufacturing footprints. WestRock Company anchors North American supply representation through containerboard network scale. Smurfit Kappa occupies a position within the converted packaging solutions tier, bundling coated kraft substrates into finished corrugated and folding carton formats for pan-European food manufacturing accounts.
| Leading Market Players |
|---|
| Mondi |
| Segezha Group |
| WestRock Company |
| Stora Enso |
| International Paper |
| Smurfit Kappa |
| Billerud |
| Nordic Paper |
| Oji Holdings Corporation |
| Others |
Value Network & Pricing Analysis
Coating chemistry specialists concentrated in Germany's North Rhine-Westphalia corridor command wage premiums that widen pricing spreads between REACH-certified specialty grades and standard industrial kraft. Labor-cost differentials between Nordic pulp integration zones and Central European conversion hubs feed directly into tiered product positioning across food-contact and industrial segments.
Pricing Analysis
Margin tightening in standard brown kraft reflects polyethylene resin cost volatility and fixed-price annual contract structures that compress converter profitability. Three-tier pricing structure across premium, standard, and economy levels separates Swissmedic-certified pharmaceutical grades from food-contact specifications and industrial shipping materials. Price differentiation traces to certification burden and volume scale, with dairy processors in Germany's Ruhr corridor leveraging centralized procurement for standard grades while medical device manufacturers absorb premiums for customized barrier properties. Quick-service restaurant chains exhibit highest price sensitivity, whereas pharmaceutical serialization operations prioritize barrier performance over unit cost.
Supply Chain Analysis
Regional distribution centers in the Antwerp-Rotterdam hub manage inventory positions for brown kraft shipping materials serving fragmented industrial buyers across Benelux and northern France. Supply concentrates in Sweden, Finland, and Germany where Nordic kraft pulp integration feeds captive coating operations. Raw material dependencies center on unbleached kraft pulp, polyethylene resin, and water-based dispersion chemistries. Single-source vulnerability in specialty-grade Nordic pulp creates bottleneck risk for pharmaceutical and medical-grade output. Distribution runs through mill-direct relationships for pan-European food manufacturers and regional paper merchants for spot industrial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as EU Green Deal recyclability mandates force sub-scale converters out of multi-layer barrier film production. Extended producer responsibility fee modulation in France and Germany accelerates shakeout among non-compliant suppliers.
For Market Incumbents: Acquire water-based dispersion coating capabilities to displace legacy extrusion lines ahead of enforcement timelines. Mondi and Billerud anchor positions through backward integration into Nordic pulp supply, but coating chemistry certification gaps expose vulnerability to REACH-compliant specialists. Defensive moves require ECHA pre-submission for novel barrier polymers and capacity rationalization in non-compliant multi-material constructions.
For New Entrants and Emerging Players: Begin with pharmaceutical serialization labels in Switzerland and Austria where Swissmedic certification barriers deter commodity competitors. White-space concentration sits in bio-based coating convergence with conventional kraft substrates for industrial organic waste streams. Go-to-market execution demands technical service integration with Basel-Zurich medical device manufacturers rather than spot-selling through distribution.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated coating-to-conversion specialists given centralized procurement consolidation among pan-European food manufacturers. Long-term viability favors operators with captive pulp supply and multi-country regulatory qualification. Target acquisition archetype: regional converters with ECHA-approved coating portfolios and established mill-direct relationships in Germany's industrial corridor. Signal to watch: qualification cycle compression for water-based dispersion formats in bakery and confectionery segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Kraft Pulp | Captive supply secures cost position for specialty-grade output amid pulp concentration risk. |
| ECHA Pre-Submission for Bio-Based Coatings | Early engagement compresses 18-24 month certification windows for compostable barrier launches. |
| Mill-Direct Relationship Expansion | Technical service integration captures category management consolidation in German dairy and meat processing. |
| Water-Based Dispersion Line Conversion | Anticipates EU Packaging and Packaging Waste Regulation design-for-recycling criteria enforcement. |
| Swissmedic Certification Investment | Unlocks pharmaceutical serialization label demand in Basel-Zurich medical device corridor. |
Research Methodology
Multi-period observation of coating chemistry substitution patterns and procurement consolidation trends anchored the trend analysis, supplemented by interviews with plant managers at Central European mills, procurement leads at German dairy and meat processors, distribution channel partners in Benelux logistics hubs, and technical R&D directors at barrier coating specialists. Secondary validation drew from ECHA substance registration databases, EU Packaging and Packaging Waste Regulation implementation notices, customs trade data for kraft paper flows, and SEC filings of integrated forest products groups. Bottom-up volume modeling triangulated against top-down demand aggregation across end-use segments.
Input-output matrices mapped unbleached kraft pulp supply through coating conversion to finished packaging demand across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry concentration, coating chemistry type, and regional regulatory cluster. CAGRs derived from slope analysis of historical volume trends adjusted for substitution elasticity between polyethylene-laminated and water-based dispersion formats. Forecast inputs incorporated ECHA evaluation window timelines and eco-modulation fee schedules from France's national packaging agency.
Underlying measurement precision varies by segment; pharmaceutical and medical-grade specialty kraft carries tighter precision than industrial brown kraft given certification documentation requirements. Forecasts reflect documented assumptions regarding REACH compliance timelines and EU Green Deal enforcement sequencing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Recyclable Lidding Films Market
Poly film
Wrap Around Label Films Market
Poly film
Spain Plastic Packaging Films Market
Poly film
Global PVDC Coated Films Market
Poly film
United Kingdom Plastic Packaging Films Market
Poly film
Stretch Films Packs Market
Poly film
Bi-Axially Oriented Polypropylene (BOPP) Market
Poly film
PET Lidding Films Market
Poly film
Surface Printed Film Market
Poly film
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Forming Films Market
Poly film
MOPP Packaging Films Market
Poly film
Polyolefin (POF) Shrink Film Market
Poly film
Poland Plastic Packaging Films Market
Poly film
Polytetrafluoroethylene (PTFE) Films Market
Poly film
PCR Lidding Films Market