
 Italy Plastic Packaging Films Market | 2026-2036
Italy Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Plastic Packaging Films Market Insights
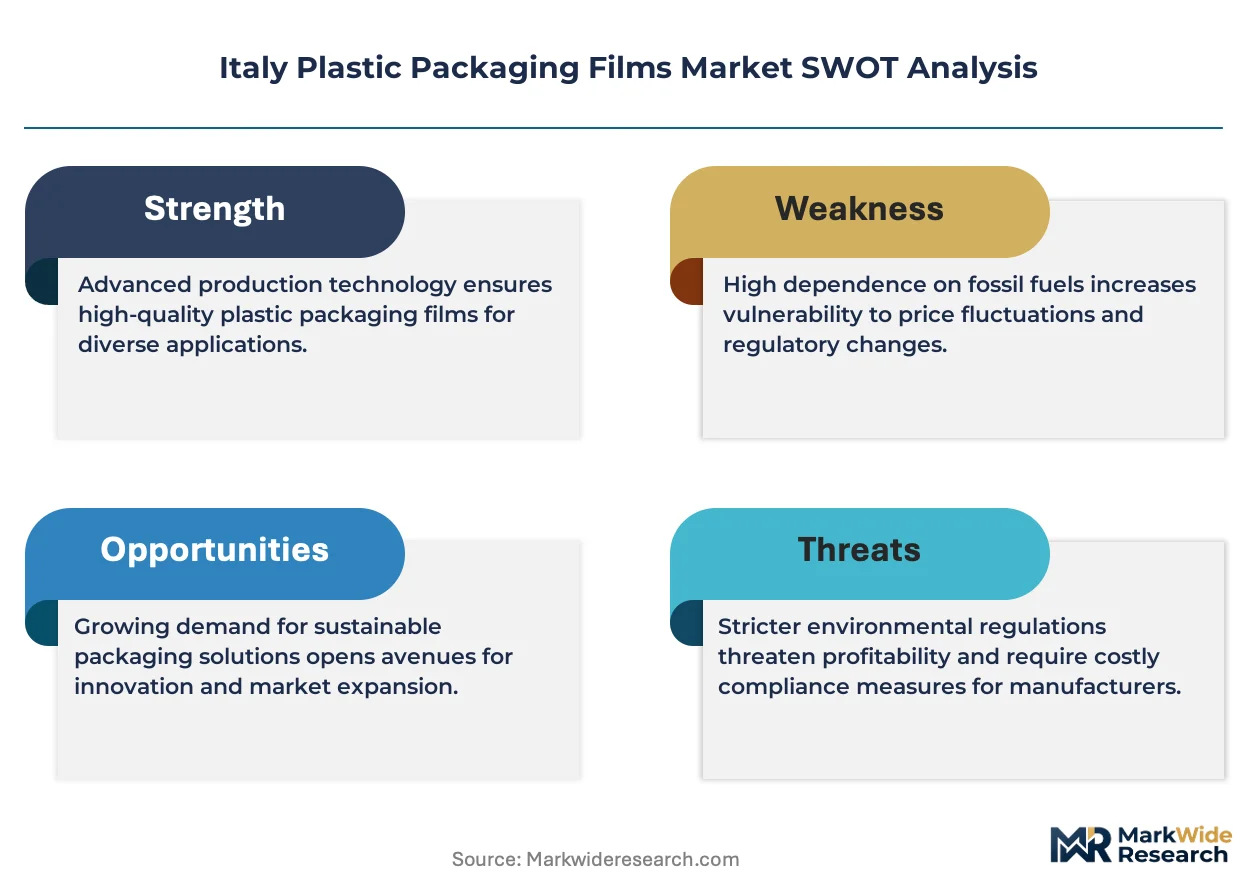
Italy is narrowing its flexible film capacity gap with northern European peers through sustained investment in Lombardy and Emilia-Romagna extrusion lines. Irplast S.p.A. leverages vertical integration across cast film and metallization to serve premium food clients. Taghleef Industries anchors biaxially oriented polypropylene supply for Italian snack and bakery segments. Manucor S.p.A. specializes in sustainable film grades aligned with retailer environmental protocols.
Plastic packaging films are thin, flexible polymer substrates engineered from LDPE, HDPE, PVC, or BOPP resins, typically ranging from 8 to 150 microns in gauge, manufactured via cast extrusion, blown extrusion, or biaxial orientation processes to deliver barrier, sealability, and printability for unitized product protection. Stretch films dominate volume throughput in Italian logistics and palletization, while barrier films command premium positioning in modified-atmosphere meat and cheese packaging where oxygen transmission rates below 1 cc/m²/day justify higher unit economics. BOPP films maintain mature, high-volume status in confectionery and label applications across the peninsula.
CONAI packaging fees, EU REACH chemical compliance, and Italy's transposed Single-Use Plastics Directive collectively elevate recycled content thresholds and restrict certain polymer additives in food-contact films. The European Commission's Packaging and Packaging Waste Regulation proposal tightens design-for-recycling standards that Italian converters must incorporate into new product development cycles. Stakeholders should monitor how upcoming extended producer responsibility fee structures reshape material selection between mechanical recycling-compatible mono-PE and emerging chemically recycled feedstocks.
Market Dynamics
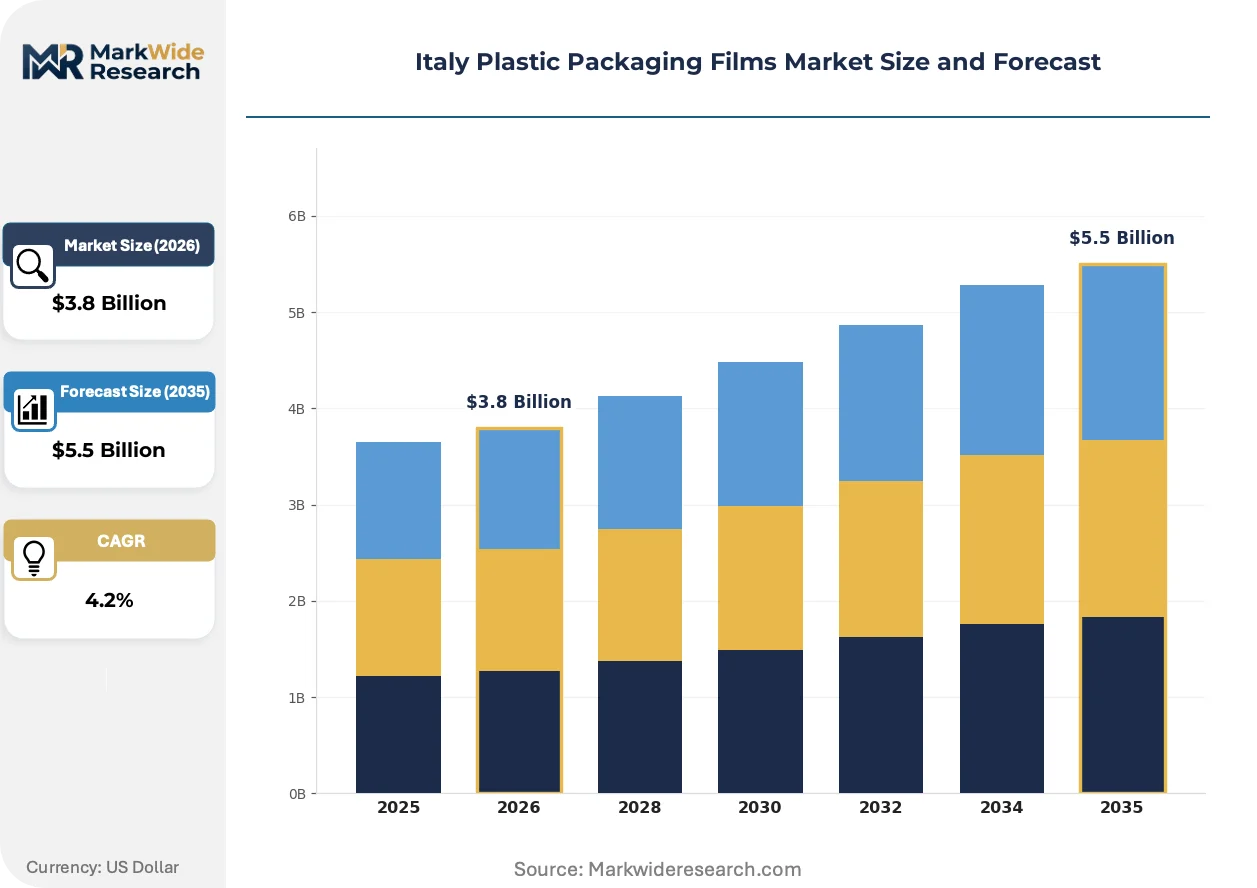
CONAI packaging fees and EU Green Deal mandates are compressing converter margins while forcing rapid material transitions toward mono-material and chemically recycled feedstocks across Lombardy and Emilia-Romagna production corridors.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Design-for-recycling standards accelerate converter investment in mono-PE lines compatible with Italian mechanical recycling infrastructure.
- Fresh food retail consolidation:Northern Italian supermarket chains demand high-barrier multilayer films for extended shelf-life meat and cheese applications.
- Bio-based resin development:Polymer producers near Milan advance PLA and PHA grades that meet CONAI fee reductions for renewable content thresholds.
Market Restraints
- Ethylene feedstock volatility:Crude-linked naphtha pricing swings compress margin predictability for LDPE and HDPE film extruders operating on quarterly contracts.
- Metallization equipment concentration:Vacuum deposition capacity clusters among three northern Italian converters, creating supply bottlenecks for premium barrier film segments.
- REACH chemical compliance friction:Restricted substance lists block certain slip agents and anti-fog additives from food-contact applications, forcing reformulation cycles.
Strategic Opportunities
- Chemically recycled feedstock adoption:Pyrolysis-derived PE and PP resins qualify for EU Green Deal circular content targets while bypassing mechanical recycling contamination limits.
- Pharmaceutical blister film conversion:PVC-to-PETG substitution in drug packaging opens specialty film demand from Milan-area pharmaceutical contract manufacturers.
- Extended producer responsibility fee structures:Upcoming CONAI rate adjustments favor lightweight mono-material designs over multilayer laminates in snack packaging applications.
Industry Challenges
- Extrusion technician scarcity:Specialized blown film line operators command wage premiums in the Bologna-Milan corridor as vocational pipeline output lags capacity expansion.
- Food-contact certification timelines:EFSA novel food approval processes for recycled content films extend new product qualification cycles beyond eighteen months.
- Legacy lamination asset stranding:Solvent-based adhesive coating lines face write-down pressure as water-based and solventless systems become CONAI-preferred for emissions profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Plastic Packaging Films Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Films, Shrink Films, Barrier Films, Blister Films End User: Food, Beverage, Healthcare, Personal Care Material: LDPE, HDPE, PVC, BOPP Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Irplast S.p.A., Berry Global Inc., Klöckner Pentaplast, Taghleef Industries, Innovia Films, SÜDPACK Holding GmbH, Mitsubishi Polyester Film GmbH, Jindal Films Europe, Manucor S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Plastic Packaging Films Market Trends and Innovations
Digital printing and web inspection systems are compressing minimum order quantities while enabling mass customization for regional Italian food brands previously locked into rotogravure volume commitments.
Mono-material barrier films incorporating EVOH coextrusion layers are collapsing the technical justification for aluminum-foil laminates in ambient pasta sauce and ready-meal packaging. Converters near Parma and Modena deploy these structures for Esselunga and Coop private-label lines. The shift eliminates separation complexity at Italian mechanical recycling facilities while maintaining twelve-month shelf stability.
Italy's transposed Single-Use Plastics Directive bans expanded polystyrene trays for fresh produce, forcing retailers to source PP and PET alternatives from domestic thermoformers. The regulation redirects film demand toward skin-pack and flow-wrap formats that use oriented PP and cast PET substrates. Northern Italian fruit cooperatives now specify these materials for grape and berry export packaging to German and Swiss buyers.
Brand owners in the Emilia-Romagna food cluster compress supplier panels from twelve converters to three strategic partners capable of delivering printed, metallized, and pouch-converted films under single-source accountability. This consolidation rewards extruders with in-house slitting, printing, and bag-making assets. The procurement pattern displaces fragmented toll-converter networks that previously managed each process step separately across multiple Lombardy subcontractors.
Italy Plastic Packaging Films Market Segmentation
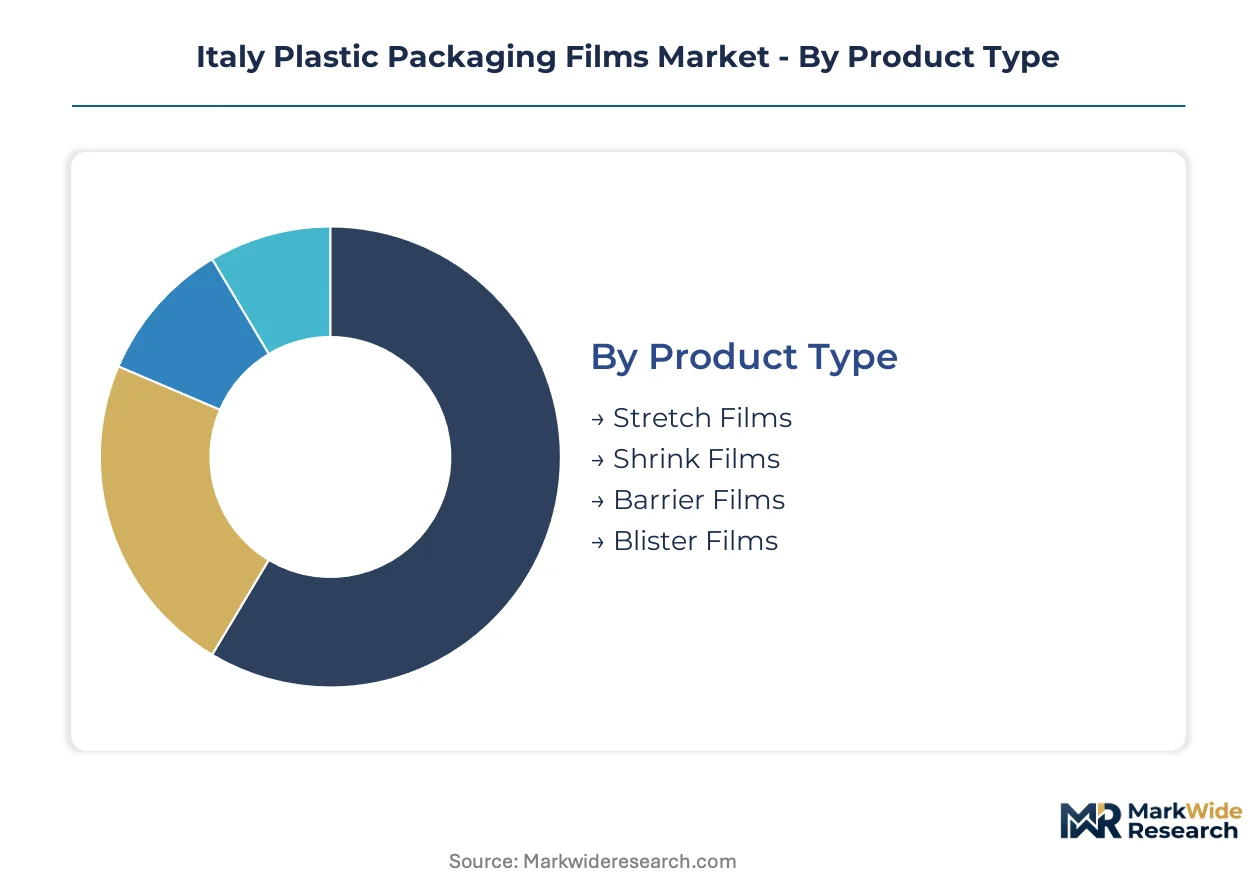
Segmentation reveals how Italian converters align film specifications with regulatory thresholds and retailer sustainability protocols. Each dimension exposes distinct margin structures and compliance burdens across the Lombardy-Emilia-Romagna production corridor.
Product Type:
Converters engineer these four formats to match unit load stability, shelf-life extension, and pharmaceutical protection requirements across Italian supply chains.
- Stretch Films:Linear low-density polyethylene formulations with 17-23 micron gauges dominate pallet unitization for Parmigiano-Reggiano and Prosciutto di Parma export logistics. Northern Italian 3PL providers specify high-cling cast grades that reduce film consumption per pallet while maintaining load integrity during Alpine transit to Swiss retail distribution centers.
- Barrier Films:Multilayer coextrusions incorporating EVOH or metallized BOPP achieve oxygen transmission rates below 1 cc/m²/day for modified-atmosphere packaging of fresh pasta and aged cheeses. Esselunga and Coop private-label specifications now mandate mono-material PE barrier structures compatible with CONAI mechanical recycling fee schedules.
- Shrink Films:Cross-linked polyolefin grades provide 40-60% shrink ratios for retail multipack collation of bottled water and soft drinks from San Pellegrino and Ferrarello production facilities.
- Blister Films:PVC and PETG thermoformable sheets serve pharmaceutical tablet and capsule packaging for Milan-area contract manufacturers supplying EU and MENA markets.
The dominant share belongs to Stretch Films, while Barrier Films is closing the gap fastest as retailers accelerate mono-material transitions.
End User:
Customer concentration patterns follow Italy's industrial geography, with food processing clusters driving film specification standards.
- Food:Pasta, cured meat, and dairy processors in Parma and Modena provinces consume high-barrier laminates and flow-wrap films. EFSA food-contact compliance timelines extend qualification cycles for recycled-content grades beyond eighteen months.
- Beverage:Mineral water and wine bottlers specify shrink-sleeve labels and collation films with printability for premium brand differentiation. Prosecco DOC producers near Treviso drive demand for metallized BOPP labels with moisture resistance.
- Healthcare:Pharmaceutical blister packs and medical device pouches require PVC-to-PETG conversion to meet EU MDR traceability and child-resistance mandates.
- Personal Care:Cosmetic and hygiene product manufacturers specify flexible pouches and sachets with high-definition rotogravure or digital printing for shelf impact in Sephora and Douglas retail channels.
Food commands the largest volume position, though Healthcare exhibits the steepest expansion trajectory as pharmaceutical outsourcing concentrates near Milan.
Material:
Resin selection balances mechanical performance, recycling compatibility, and CONAI fee structures that penalize multi-polymer constructions.
- LDPE:Cast and blown extrusion grades serve stretch film, shrink film, and general-purpose bag applications. Lombardy extruders favor metallocene-catalyzed grades for enhanced puncture resistance in automated pallet wrapping systems.
- BOPP:Biaxially oriented polypropylene dominates snack, confectionery, and label markets with high stiffness-to-thickness ratios. Taghleef Industries' Italian operations anchor regional supply for transparent and metallized grades.
- HDPE:Higher-density grades provide rigidity for retail carrier bags and industrial liners, though supermarket plastic bag bans in several municipalities constrain growth.
- PVC:Pharmaceutical blister and cling film applications face substitution pressure from PETG and PE alternatives under REACH additive restrictions and healthcare sustainability procurement guidelines.
LDPE retains volume leadership, while BOPP gains share fastest as snack packaging specifications migrate toward mono-material designs.
Distribution Channel:
Channel structure reflects consolidation trends among Italian brand owners seeking single-source accountability.
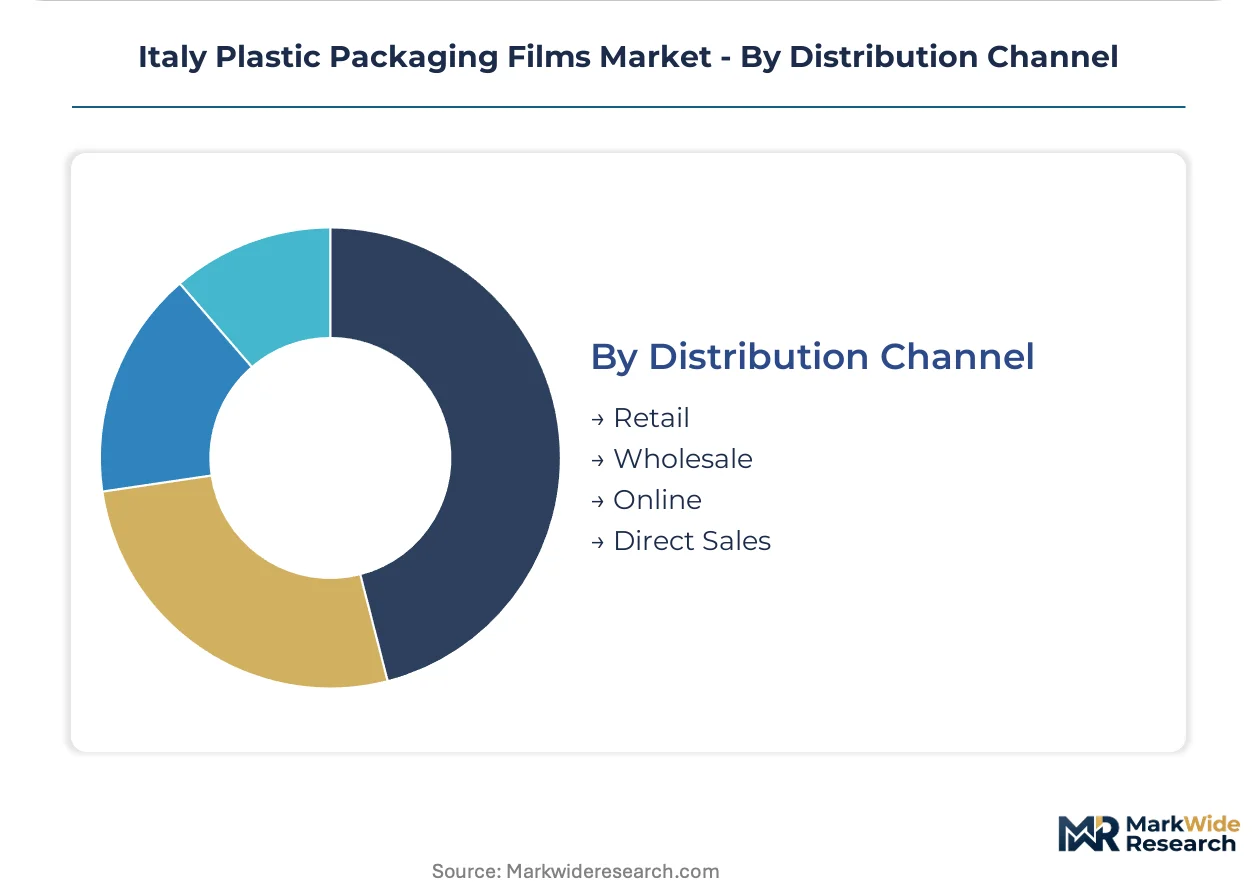
- Direct Sales:Large food and beverage manufacturers contract directly with Irplast, Manucor, and Taghleef for extruded, printed, and converted film supply. Procurement panels have compressed from twelve suppliers to three strategic partners capable of vertical integration across slitting, metallization, and pouch-making.
- Wholesale:Regional distributors stock standard gauge films for mid-tier converters and smaller food processors lacking volume for mill-direct relationships.
- Retail:Limited to specialty packaging retailers serving artisanal producers and pilot-scale operations.
- Online:Digital procurement platforms emerge for standardized stretch film and shrink film grades, though custom barrier laminates remain relationship-driven.
Direct Sales captures the predominant value flow, with Wholesale retaining relevance for fragmented SME demand across central and southern Italy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian demand for plastic packaging films concentrates in northern industrial corridors, while central and southern regions exhibit fragmented, import-dependent consumption patterns shaped by weaker food processing density and logistics infrastructure.
Lombardy
Stretch film demand from Milan-area 3PL providers drives specification standards for high-cling cast grades serving Alpine export routes. CONAI fee structures incentivize lightweight mono-PE designs in automated pallet wrapping systems. Extrusion capacity clusters around Bergamo and Brescia, where converters integrate metallization and printing for single-source accountability to pan-European retailers.
Emilia-Romagna
Modified-atmosphere barrier films for Parma ham and Parmigiano-Reggiano processors require oxygen transmission rates below 1 cc/m²/day. EU Packaging and Packaging Waste Regulation design-for-recycling standards force rapid transitions from multilayer laminates to mono-material PE structures. Bologna-Modena production corridors host vertically integrated converters supplying Esselunga and Coop private-label specifications.
Veneto
Prosecco DOC producers near Treviso generate specialized demand for metallized BOPP labels with moisture resistance and premium shelf differentiation. REACH chemical compliance restrictions on slip agents force reformulation cycles for food-contact films. Thermoforming capacity in Vicenza and Verona redirects toward PP and PET alternatives following Italy's expanded polystyrene tray ban under transposed Single-Use Plastics Directive.
Piedmont
Pharmaceutical blister film conversion from PVC to PETG accelerates around Turin-area contract manufacturers supplying EU MDR traceability mandates. EFSA novel food approval timelines for recycled content films extend qualification cycles beyond eighteen months. Novara and Alessandria host specialist converters serving Swiss and German pharmaceutical export markets.
Lazio
Rome-centric retail distribution generates demand for standardized shrink films and general-purpose bags with shorter lead times than northern supply chains. Wholesale distributors stock cast LDPE grades for mid-tier food processors lacking mill-direct volume relationships. Fiumicino logistics hubs handle imported film rolls from northern Italian extruders serving central and southern SME demand.
Italy Plastic Packaging Films Market Competitive Landscape
Capability concentration sits with vertically integrated specialists controlling extrusion, metallization, and conversion; scale advantage sits with multinational film producers leveraging pan-European resin procurement and distribution networks. The vendor base separates into three archetypes: northern Italian integrated converters with full-process control, European headquartered specialists with Italian production assets, and global resin-integrated film producers serving through distribution. Dominant competitive moves include backward integration into polymer compounding and strategic partnerships with retailer sustainability certification programs.
Among Italy-based specialists, Irplast S.p.A. and Manucor S.p.A. occupy positions exemplifying vertically integrated production models spanning cast film extrusion through pouch conversion. Taghleef Industries represents the European specialist archetype with biaxially oriented polypropylene supply anchored to Italian snack and bakery segments. These named entities serve as reference points for understanding how regional competitive positioning aligns with CONAI recycling mandates and retailer environmental procurement protocols.
| Leading Market Players |
|---|
| Irplast S.p.A. |
| Berry Global Inc. |
| Klöckner Pentaplast |
| Taghleef Industries |
| Innovia Films |
| SÜDPACK Holding GmbH |
| Mitsubishi Polyester Film GmbH |
| Jindal Films Europe |
| Manucor S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Alpine transit corridors from Milan to Swiss distribution centers impose fuel-linked freight volatility that amplifies margin compression for northern Italian extruders while enabling price premiums for converters with captive metallization and logistics control.
Pricing Analysis
Long-term offtake contracts dominate volume relationships between Lombardy extruders and Esselunga or Coop procurement panels, though spot purchasing persists for standard gauge stretch films among smaller food processors. Three-tier pricing structure across premium barrier, standard cast, and economy blown grades reflects oxygen transmission performance and CONAI recycling compatibility tiers. Pricing pressure stems from ethylene feedstock volatility linked to naphtha-crude spreads, compressing predictability for quarterly-contract converters. SME processors in central Italy exhibit highest price sensitivity due to fragmented volumes and wholesale distribution dependency, while vertically integrated brand owners with mill-direct relationships absorb cost swings through specification lock-ins.
Supply Chain Analysis
Extended payment terms from northern Italian supermarket chains strain working capital for mid-tier converters, accelerating supply-chain finance facility adoption among Bologna-Modena extruders. Raw material sourcing draws from Saudi and Qatari ethylene feedstock, German resin compounding, and domestic Lombardy polymer distribution hubs. Single-source vulnerability concentrates in vacuum metallization equipment, where three northern Italian converters control premium barrier film capacity. Distribution runs through direct mill relationships for large food manufacturers, with wholesale distributors bridging fragmented SME demand across central and southern regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as EU Packaging and Packaging Waste Regulation implementation forces asset replacement cycles among legacy multilayer laminate producers.
For Market Incumbents: Harden competitive position through backward integration into polymer compounding near Milan and captive metallization capacity expansion, defending against specialty chemical recyclers entering pyrolysis-derived PE supply. Prioritize CONAI-preferred mono-PE barrier line investments to capture retailer sustainability procurement shifts away from aluminum-foil laminates. For New Entrants and Emerging Players: Build out chemically recycled feedstock partnerships with Italian pyrolysis operators to bypass mechanical recycling contamination limits and qualify for EU Green Deal circular content thresholds. Target pharmaceutical blister film conversion from PVC to PETG around Turin-area contract manufacturers, leveraging EFSA approval timeline gaps that delay incumbent recycled-content qualification. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated converters with in-house slitting, printing, and pouch-making assets capable of single-source accountability to consolidated retailer panels. Long-term viability rests on mechanical recycling-compatible mono-material design capabilities rather than legacy multilayer lamination expertise. Monitor CONAI extended producer responsibility fee structure announcements as inflection signals for material substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-PE Barrier Line Investment | Captures Esselunga and Coop private-label specifications under CONAI recycling fee schedules. |
| Chemical Recycling Feedstock Partnership | Qualifies converters for EU Green Deal circular content targets while bypassing mechanical contamination limits. |
| Pharmaceutical Blister Film Conversion | Opens specialty demand from Milan-area contract manufacturers facing EU MDR traceability mandates. |
| Backward Integration into Compounding | Secures margin control over metallocene-catalyzed grades for automated pallet wrapping systems. |
| Digital Printing Platform Deployment | Compresses minimum order quantities for regional Italian food brands previously locked into rotogravure volumes. |
Research Methodology
Cross-validation between extrusion line operator interviews and CONAI fee schedule documentation anchors the qualitative findings on material transition economics. Primary fieldwork encompassed flexible packaging procurement managers at northern Italian retail chains, technical directors at Lombardy and Emilia-Romagna converters, and resin distribution specialists. Secondary sources included EU Packaging and Packaging Waste Regulation proposal texts, EFSA novel food approval databases, and Italian customs trade data on polymer imports. Bottom-up capacity estimates from named extrusion lines triangulate against top-down demand models from food processing cluster outputs.
Calibration against historical CONAI fee adjustments and EU directive implementation timelines shaped the projection framework across the analysis window. Segmentation dimensions modeled include film product type, end-use industry concentration, material resin family, and distribution channel structure. CAGRs derive from weighted capacity expansion announcements and food retail consolidation patterns. Forecast inputs incorporate EVOH coextrusion adoption rates for mono-material barrier films and pharmaceutical PVC-to-PETG substitution velocities.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by multinational resin-integrated producers would shift outcomes beyond modeled ranges. Macroeconomic volatility in crude-linked naphtha pricing, accelerated EU recycling mandate enforcement, or breakthrough bio-based resin cost parity would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Colourless Polyimide Films Market
Poly film
Peelable and Resealable Films Market
Poly film
China BOPP Film Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
Poland Plastic Packaging Films Market
Poly film
India BOPP Films Market
Poly film
Automotive Wrap Films Market
Poly film
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market
Poly film
Polyethylene Cast Film Market
Poly film
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Egypt Plastic Packaging Films Market
Poly film
Cast Stretch Packaging Films Market
Poly film
Twist Wrap Film Market
Poly film
Thermoforming Films Market
Poly film
In-Mould Label Film Market
Poly film
Poly Coated Paper Market