
 Poly Coated Paper Market | 2026-2036
Poly Coated Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Poly Coated Paper Market Outlook
Finnish integrated pulp-to-paper producers is broadening bleached kraft capacity dedicated to extrusion-grade substrates. WestRock Company leverages captive containerboard mills to control resin-paper lamination costs across North American corrugated food service lines. Nippon Paper Industries anchors Asia-Pacific supply through coated specialties optimized for moisture-sensitive confectionery wraps. Stora Enso sustains European market presence with biopolymer-coated alternatives certified under industrial composting protocols.
Poly coated paper consists of a cellulose base sheet laminated with polyethylene or biopolymer films through extrusion or hot-melt processes, typically achieving moisture vapor transmission rates below 10 g/m²/day for food-contact applications. The substrate serves as a grease-resistant, heat-sealable barrier in disposable packaging where pure paper fails. Water-resistant grades command premium positioning in frozen food and chilled dairy segments where condensation resistance extends shelf visibility. Eco-friendly grades represent the fastest-expanding category as brand owners shift procurement toward fiber-based solutions with certified recyclability streams. Industrial-grade volumes dominate tonnage through bulk supply contracts with quick-service restaurant chains and centralized bakery operations.
FDA food-contact substance notifications govern polymer migration limits for US-sold coated paper, while REACH and the EU Packaging and Packaging Waste Regulation enforce recyclability disclosures and restricted substance thresholds across European supply chains. China's GB standards for food packaging materials impose additional testing protocols on imported coated substrates, complicating market access for non-domestic producers. Stakeholders must monitor evolving extended producer responsibility schemes and polymer-ban timelines to calibrate resin selection and recycling infrastructure investments.
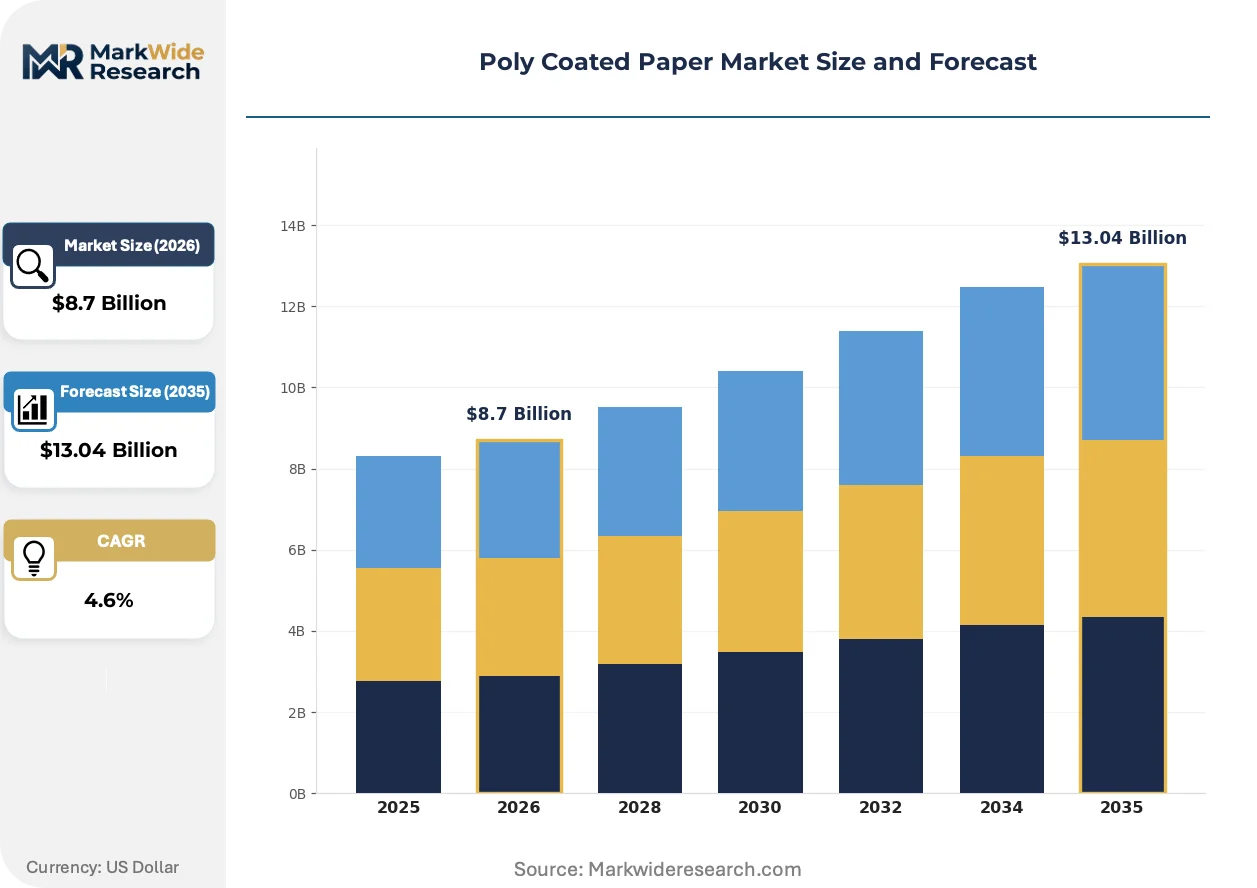
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing multi-material substrate viability, forcing converters to recalibrate resin selection and recycling infrastructure investments across European supply chains.
Growth Catalysts
- Food packaging polymer-barrier requirements:Quick-service restaurants and institutional catering operations are expanding specifications for grease-resistant, heat-sealable substrates in disposable applications where pure paper fails.
- REACH restricted substance thresholds:European enforcement of restricted substance disclosures is accelerating certified recyclability streams among brand owners seeking fiber-based solutions.
- Centralized retail distribution networks:Germany's high-volume logistics infrastructure concentrates demand for water-resistant grades in frozen food and chilled dairy segments.
Market Restraints
- Polyethylene resin cost volatility:Fossil-based feedstock price swings compress margin predictability for extrusion-grade substrate producers.
- Multi-material recyclability mandates:The EU Packaging and Packaging Waste Regulation creates structural friction for conventional polyethylene-laminated papers lacking certified separation protocols.
- Pulp supply concentration:Nordic bleached kraft capacity dominance exposes converters to regional fiber cost shocks and logistics bottlenecks.
Strategic Opportunities
- Biopolymer-coated alternatives:Industrial composting certification protocols create white space for fiber-based solutions displacing conventional multi-material barriers.
- Moisture-sensitive confectionery wraps:Asia-Pacific confectionery manufacturers are expanding specifications for coated specialties with sub-10 g/m²/day vapor transmission rates.
- Extended producer responsibility schemes:Evolving polymer-ban timelines in European jurisdictions reward early movers in recyclable mono-material substrate development.
Industry Challenges
- GB standards compliance complexity:China's food packaging material testing protocols impose certification timeline friction on non-domestic substrate producers seeking market access.
- Extrusion-grade substrate qualification:FDA food-contact substance notification requirements for polymer migration limits demand specialized technical documentation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poly Coated Paper Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glossy, Matte, Silk, Water-Resistant Grade: Standard, Premium, Industrial, Eco-Friendly End User: Packaging, Publishing, Labels, Advertising Application: Food Packaging, Retail Bags, Brochures, Stationery |
| Companies Covered | WestRock Company, Nippon Paper Industries, International Paper Company, Georgia-Pacific, Oji Holdings Corporation, Stora Enso, Sappi Limited, Smurfit Kappa Group, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poly Coated Paper Market Strategic Shifts
Active substitution of petroleum-derived barriers with bio-based alternatives is compressing conventional technology lifecycles while regulatory disclosure requirements reshape competitive positioning across fiber-based packaging.
Water-based barrier coatings derived from polysaccharide and protein matrices are absorbing moisture-resistance functions previously served by polyethylene extrusion. Frozen food packagers in North America and Europe are piloting these substrates at commercial scale. The technology is absorbing premium positioning in shelf-visibility applications where condensation resistance determines retail performance.
REACH and the EU Packaging and Packaging Waste Regulation now mandate recyclability disclosures and restricted substance thresholds across European supply chains. Industrial converters face accelerated reformulation timelines to maintain market access. Quick-service restaurant chains operating across Germany, France, and Italy are restructuring procurement specifications to preempt compliance exposure.
Brand-owner sustainability scorecards now weight certified recyclability streams above unit cost in annual packaging tenders. Centralized bakery operations and institutional catering distributors are consolidating supplier relationships around fiber-based solutions with documented end-of-life pathways. This preference compression is most visible in German retail networks where extended producer responsibility schemes penalize multi-material substrates.
Poly Coated Paper Market Segmentation
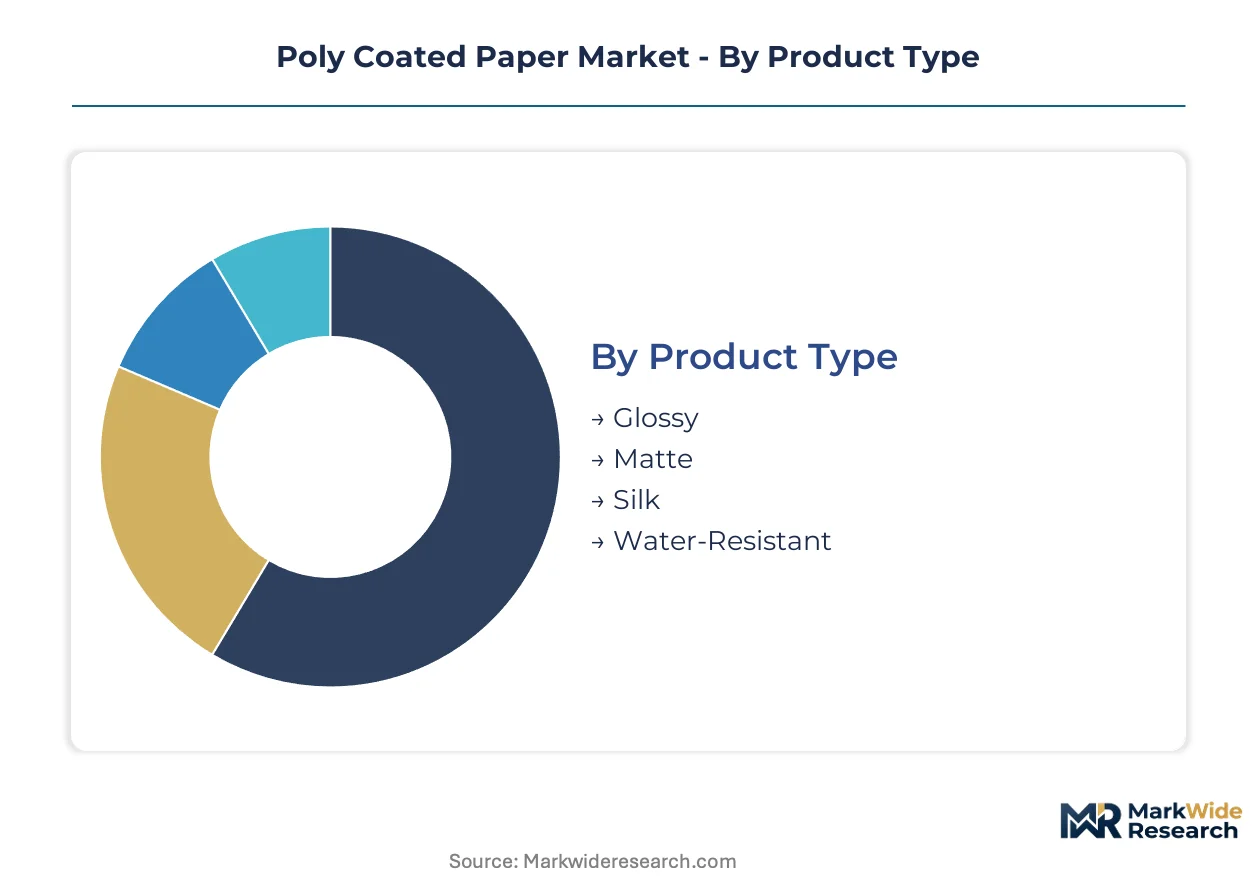
Poly coated paper segmentation reflects divergent technical specifications across moisture barriers, surface finishes, and end-use compliance requirements. Each category channels distinct resin formulations, coating weights, and certification protocols that determine converter selection criteria.
Product Type:
Surface finish customization spans high-gloss retail presentation to functional moisture barriers, with coating chemistry dictating printability and heat-seal performance trade-offs.
- Glossy:High-clarity polyethylene extrusion creates mirror-like surfaces for premium confectionery wraps and cosmetic cartons where shelf visibility drives purchase decisions. Demand concentrates in German retail chains requiring condensation-resistant frozen food packaging that maintains photographic print quality through cold-chain distribution.
- Water-Resistant:Multi-layer extrusion achieves sub-10 g/m²/day moisture vapor transmission rates through enhanced polymer barrier density. Quick-service restaurant chains in the United States specify these grades for chilled beverage cups and ice-cream packaging where structural integrity failures trigger food safety liabilities.
- Matte:Controlled surface roughness reduces glare for luxury stationery and high-end brochure applications where tactile sophistication signals brand positioning.
- Silk:Intermediate sheen balances print vibrancy with subdued elegance, serving pharmaceutical insert leaflets and premium chocolate box linings.
Leading the category by volume: Water-Resistant. Expanding most quickly: Glossy.
Grade:
Performance tiering separates commodity food-service volumes from certified compostable alternatives commanding sustainability premiums.
- Industrial:High-speed extrusion lines produce bulk tonnage at minimized coating weights for quick-service restaurant chains and centralized bakery operations. These grades dominate procurement contracts where unit cost compression outweighs barrier performance optimization.
- Eco-Friendly:Biopolymer coatings certified under industrial composting protocols displace conventional polyethylene in European markets where extended producer responsibility schemes penalize multi-material substrates. German retail networks and French institutional catering distributors are consolidating supplier relationships around these documented end-of-life pathways.
- Standard:Baseline polyethylene lamination serves general-purpose packaging with moderate moisture resistance requirements.
- Premium:Enhanced coating uniformity and lower extractable thresholds target pharmaceutical blister pack backers and medical device sterilization pouches.
Highest volume concentration: Industrial. Steepest expansion trajectory: Eco-Friendly.
End User:
Application-specific barrier requirements reshape coating chemistry selection across moisture sensitivity, grease resistance, and regulatory compliance dimensions.
- Packaging:Food-contact specifications dominate resin selection with FDA notifications governing polymer migration limits in US markets and REACH thresholds enforcing restricted substance disclosures across European supply chains. Frozen food and chilled dairy segments command water-resistant grades where condensation resistance extends retail shelf visibility.
- Labels:Adhesive compatibility and die-cutting performance dictate coating surface energy profiles for beverage bottle wraps and pharmaceutical serialization applications.
- Publishing:Cover stock durability requirements drive matte and silk finishes for annual reports and coffee-table books.
- Advertising:Short-run promotional materials utilize standard grades where weather resistance exceeds archival longevity requirements.
Dominant demand source: Packaging. Gaining share fastest: Labels.
Application:
Use-case fragmentation channels distinct coating weights, heat-seal temperatures, and print finishing requirements across disposable and durable product categories.
- Food Packaging:Grease-resistant, heat-sealable barriers serve quick-service restaurant disposable applications where pure paper fails. FDA food-contact substance notifications and China's GB standards impose parallel certification requirements on substrate producers seeking trans-Pacific market access.
- Retail Bags:Load-bearing capacity and moisture resistance specifications vary by merchandise category from frozen foods to apparel.
- Brochures:Surface finish and fold endurance requirements prioritize print aesthetics over barrier performance.
- Stationery:Writing compatibility and ink absorption characteristics influence coating porosity calibration.
Volume leader: Food Packaging. Climbing the fastest: Retail Bags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nordic bleached kraft pulp localities anchor poly coated paper feedstock availability across European and North American converting corridors. Germany's centralized retail distribution infrastructure concentrates high-volume demand for water-resistant grades in frozen food logistics. China's food packaging material standards reshape import qualification timelines for extrusion-grade substrate producers.
Germany
Quick-service restaurant chains and institutional catering distributors drive specifications for grease-resistant, heat-sealable barriers. The EU Packaging and Packaging Waste Regulation mandates recyclability disclosures that accelerate certified fiber-based procurement. The Rhine-Ruhr industrial corridor hosts converting operations supplying centralized bakery networks with industrial-grade coated tonnage.
United States
FDA food-contact substance notifications govern polymer migration limits for quick-service disposable applications. Frozen food packagers in the Midwest specify water-resistant grades where condensation resistance determines retail shelf visibility. The Chicago-Gary industrial cluster concentrates extrusion-grade substrate converting for national corrugated food service distribution.
China
GB standards for food packaging materials impose testing protocol complexity on imported coated substrates seeking domestic market access. Confectionery manufacturers in the Yangtze River Delta expand specifications for moisture-sensitive wraps with sub-10 g/m²/day vapor transmission rates. Shanghai's port infrastructure channels biopolymer-coated alternative imports facing dual carbon goal compliance scrutiny.
Japan
Moisture-sensitive confectionery applications anchor demand for coated specialties optimized for premium packaging presentation. METI industrial standards shape biopolymer coating certification protocols competing with conventional polyethylene lamination. The Kanto region around Tokyo concentrates pharmaceutical and food-contact converting operations serving domestic distribution networks.
Finland
Integrated pulp-to-paper producers expand bleached kraft capacity dedicated to extrusion-grade substrate supply. REACH restricted substance thresholds enforce supply chain documentation requirements for European export qualification. The Kemi-Tornio industrial cluster anchors biopolymer-coated alternative development certified under industrial composting protocols.
Poly Coated Paper Market Competitive Environment
Global majors compete with regional champions across resin-paper lamination technology and captive fiber supply control. The vendor base organizes around integrated pulp-to-paper producers, captive containerboard operators, and specialty coated converters serving moisture-sensitive applications. Three archetypes dominate: Nordic integrated fiber producers with backward kraft pulp control, North American corrugated specialists leveraging containerboard mill networks, and Asia-Pacific coated specialty houses optimizing confectionery barrier performance. Capacity expansion and biopolymer coating certification represent the dominant competitive vectors reshaping procurement relationships.
Within the integrated fiber producer tier, Stora Enso and Mondi Group exemplify European market presence through biopolymer-coated alternatives and industrial composting certification protocols. WestRock Company occupies a position among North American operators leveraging captive containerboard infrastructure. Nippon Paper Industries anchors Asia-Pacific supply positioning for moisture-sensitive confectionery applications. These archetype representatives illustrate how geographic fiber access and regulatory certification capabilities determine competitive positioning across quick-service restaurant, pharmaceutical, and retail distribution channels.
| Leading Market Players |
|---|
| WestRock Company |
| Nippon Paper Industries |
| International Paper Company |
| Georgia-Pacific |
| Oji Holdings Corporation |
| Stora Enso |
| Sappi Limited |
| Smurfit Kappa Group |
| Mondi Group |
| Others |
Value Chain & Pricing Dynamics
Polyethylene resin price indices cascade through poly coated paper supply chains, compressing margin structures for extrusion-grade substrate producers while biopolymer alternatives absorb sustainability premiums across European procurement contracts.
Pricing Analysis
Certification bundling separates industrial-grade polyethylene laminations from certified compostable alternatives carrying industrial composting documentation. Three-tier pricing structure across premium, standard, and economy levels reflects coating weight precision, barrier performance thresholds, and regulatory compliance depth. Cost compression in commodity food-service grades intensifies as quick-service restaurant chains consolidate volume contracts around unit-cost minimization. Centralized bakery operations exhibit highest price sensitivity; pharmaceutical blister pack backers demonstrate lowest.
Supply Chain Analysis
Bleached kraft pulp supply rests on Nordic integrated producers in Finland and Sweden, with secondary concentration in North American southeastern mills. Extrusion-grade substrates draw from polyethylene resin feedstocks, biopolymer coating innovations, and captive containerboard networks. Single-source vulnerability concentrates in Nordic fiber supply during winter logistics disruptions. Distribution runs through converting clusters serving quick-service restaurant chains and institutional catering distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poly coated paper markets are consolidating around integrated fiber producers with backward pulp control, as EU recyclability mandates force smaller converters into acquisition targets or exit.
For Market Incumbents: Anchor market position through captive bleached kraft capacity expansion in Finland and industrial composting certification investment for biopolymer-coated alternatives. Biopolymer substitution technology threatens conventional polyethylene lamination volumes; vertical integration into extrusion-grade substrate supply secures margin control against resin cost volatility. For New Entrants and Emerging Players: The premium-to-economy price-point gap in eco-friendly grades offers white-space entry for certified compostable specialists targeting German retail networks and French institutional catering distributors. Asia-Pacific confectionery barrier applications present secondary penetration opportunity with lower certification barriers. Go-to-market through sustainability scorecard alignment with brand-owner procurement teams. For Investors and Strategic Acquirers: Distressed-cycle entries favor Nordic integrated pulp-to-paper producers with stranded conventional polyethylene capacity facing EU Packaging and Packaging Waste Regulation compliance costs. Long-term viability centers on biopolymer coating certification capabilities and captive fiber supply control. Watch polymer-ban timeline acceleration in European jurisdictions as inflection indicator for asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bleached Kraft Pulp | Captive fiber supply insulates Finnish producers from Nordic winter logistics bottlenecks. |
| Industrial Composting Certification Investment | Biopolymer-coated alternatives unlock German retail procurement specifications penalizing multi-material substrates. |
| Extrusion-Grade Substrate Capacity Expansion | Enhanced coating weight precision serves quick-service restaurant chains consolidating supplier relationships. |
| Long-Term Supply Agreement with QSR Chains | Volume commitments from institutional catering distributors stabilize capacity utilization through demand cycles. |
| Joint Venture for Asia-Pacific Confectionery Barriers | Localized production addresses moisture-sensitive wrap specifications in Yangtze River Delta manufacturing clusters. |
Study Parameters
Independent corroboration across converter procurement directors, quick-service restaurant supply chain managers, and bleached kraft pulp procurement leads underwrites the qualitative findings in this study. Primary fieldwork with extrusion line operators, sustainability officers at brand owners, and regulatory compliance consultants combined with secondary validation from EU Packaging and Packaging Waste Regulation disclosure databases, FDA food-contact substance notification filings, and Nordic trade association capacity reports. Bottom-up segment sizing and top-down macroeconomic cross-checks established analytical triangulation.
Rate-of-change decomposition across product type, grade tier, end-use application, and regional regulatory cluster shaped the forecast framework. CAGRs were derived from segment-level volume trajectories calibrated against historical extrusion-grade substrate demand patterns and projected biopolymer coating adoption curves. Modeled inputs included quick-service restaurant expansion rates, EU extended producer responsibility scheme implementation timelines, and Nordic pulp capacity utilization assumptions.
Underlying measurement precision varies by segment; industrial-grade and food packaging applications carry tighter precision than emerging biopolymer-coated alternatives where certification protocol evolution introduces uncertainty. Forecasts reflect assumptions about regulatory compliance timelines and substitution technology maturation that polymer-ban acceleration or biopolymer cost parity breakthroughs could revise. A small set of regulatory trigger events and raw material price inflections warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
PVC Films Market
Poly film
Global EVOH Films for Packaging Market
Poly film
Cleanroom Film and Bags Market
Poly film
Polyolefin Films Market
Poly film
Global PVDC Coated Films Market
Poly film
Polyolefin Battery Separator Films Market
Poly film
Global Polyethylene Packaging Market
Poly film
Mexico Plastic Packaging Films Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
Nigeria Plastic Packaging Films Market
Poly film
US Cleanroom Film and Bags Market
Poly film
Global BOPET Packaging Films Market
Poly film
Printed Plastic Films Market
Poly film
Polyethylene Furanoate Films Market
Poly film
Polyurethane (PU) Film Market
Poly film
United States Polycarbonate Sheets and Films Market