
 Global Fluoropolymer Films Market | 2026-2036
Global Fluoropolymer Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fluoropolymer Films Market Foresight
ASTM D3368 qualification for electrical-grade PTFE films is unwinding the competitive landscape for suppliers serving aerospace wire-and-cable tiers. DuPont leverages captive fluoromonomer supply to sustain pricing power across high-performance insulation grades. AGC Chemicals anchors its position through backward integration into fluorspar processing and melt-extrusion capacity in Japan. Solvay differentiates via ETFE architectural film formulations that compete on solar transmission metrics for greenhouse and stadium envelopes.
Fluoropolymer films are thin-gauge extruded or cast membranes composed of perfluorinated or partially fluorinated carbon-chain polymers, typically 25–500 µm thick, engineered for thermal stability exceeding 260°C and chemical inertness across pH extremes. Their primary purpose is to deliver dielectric isolation, barrier protection, or weathering resistance in environments where hydrocarbon-based films degrade. PVDF films lead volume in photovoltaic backsheet laminates where moisture ingress resistance defines module longevity, while FEP and PFA grades capture margin pools in semiconductor process equipment gasketing where ultra-purity standards govern qualification. ETFE architectural films represent the fastest-growing product category as tensile-structure projects multiply and weight savings over glass drive specification shifts.
The EPA enforces TSCA Section 5 pre-manufacture notification for novel per- and polyfluoroalkyl substances, constraining new fluoropolymer introductions into US commerce. ECHA administers REACH restrictions and the EU F-Gas Regulation, which together tighten fluorinated precursor availability and elevate compliance costs for European film converters. China's MEE enforces dual carbon goals that pressure fluorochemical producers to abate process emissions and document carbon intensity across PTFE and PVDF supply chains. Stakeholders must monitor regulatory divergence across these three jurisdictions to anticipate qualification bottlenecks and redirect technical marketing resources toward compliant grade portfolios.
Market Dynamics
Photovoltaic backsheet specifications are tightening moisture-ingress thresholds, forcing film suppliers to recalibrate resin formulations and laminate adhesion protocols across module assembly tiers.
Growth Catalysts
- EU F-Gas Regulation phase-down schedules:The accelerated quota reductions for hydrofluorocarbons are redirecting converter investment toward PTFE and ETFE alternatives that bypass fluorinated gas precursors entirely.
- China's domestic PV manufacturing scale-up:Module production lines in Jiangsu and Zhejiang provinces are sourcing fluoropolymer films locally, compressing import dependence and amplifying regional supply chain density.
- ETFE tensile architecture:Stadium and greenhouse envelope projects are specifying ETFE cushions over glass, cutting structural dead load and accelerating installation cycles for membrane contractors.
Market Restraints
- Fluorspar supply concentration:Acid-grade fluorspar mining concentrates in Mexico and China, exposing film producers to export quota volatility and freight cost spikes.
- EPA TSCA Section 5 notification burdens:Novel per- and polyfluoroalkyl substances face extended review timelines, delaying commercialization of modified copolymer grades in US markets.
- Glass-glass module substitution:Bifacial solar panels with tempered glass rear sheets are displacing fluoropolymer backsheets in utility-scale installations where mechanical durability outweighs weight savings.
Strategic Opportunities
- India's solar park expansion:The country's National Solar Mission targets are creating qualified supplier vacancies for backsheet films as domestic module assembly accelerates in Gujarat and Rajasthan.
- Semiconductor process equipment gasketing:FEP and PFA ultra-purity grades are capturing specification share in etch chamber sealing as chip fabrication node sizes shrink below 3nm.
- Green hydrogen electrolyzer membranes:Proton exchange membrane electrolysis is adopting perfluorinated ionomer films for stack durability under alkaline crossover conditions.
Industry Challenges
- ASTM D3368 certification timelines:Aerospace wire-and-cable tiers require 18-24 month qualification cycles for electrical-grade PTFE films, freezing supplier switching and amplifying incumbent lock-in.
- Carbon intensity documentation:China's MEE enforcement of dual carbon goals demands process emission audits across PTFE and PVDF production chains, raising compliance overhead for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fluoropolymer Films Market |
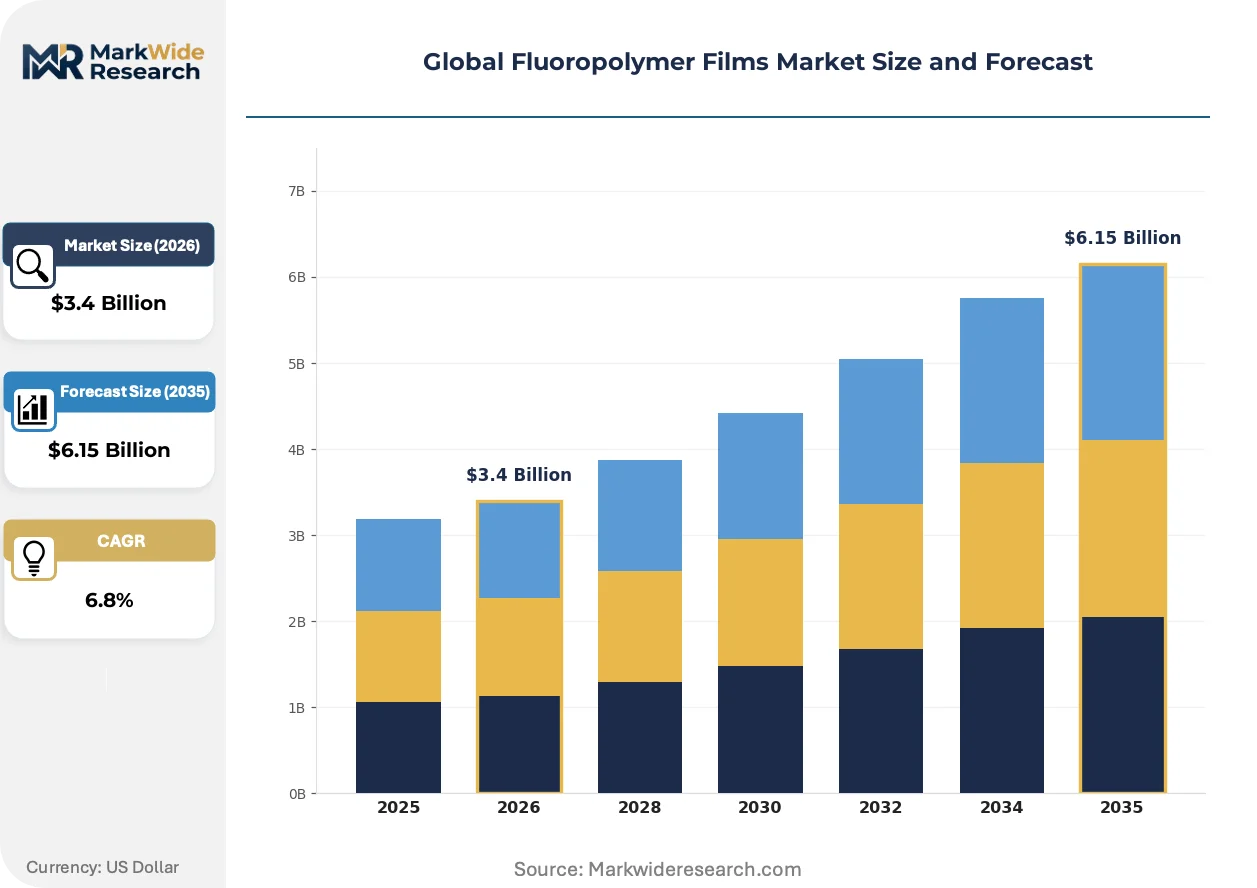
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE, PVDF, FEP, PFA, ETFE Application: Electrical Insulation, Chemical Processing, Food Packaging, Architectural Coatings, Automotive Components End User Industry: Electronics Manufacturing, Chemical Manufacturing, Food Processing, Construction, Vehicle Manufacturing Film Thickness: Ultra-Thin, Thin, Medium, Thick, Extra Thick |
| Companies Covered | Saint-Gobain, DuPont, 3M, AGC Chemicals, Arkema Group, DAIKIN INDUSTRIES, Ltd., Solvay, Asahi Kasei Corporation, The Chemours Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fluoropolymer Films Market Shifts & Advancements
Film suppliers are converging on thinner-gauge extrusion capabilities and modified copolymer architectures that reconcile thermal performance with regulatory constraints on fluorinated precursors.
Co-extruded multilayer PVDF-ETFE laminates are decomposing the traditional monolithic backsheet market by enabling zoned functionality—moisture barriers at the substrate interface, UV resistance at the exterior surface. Tier-1 module assemblers in China and Southeast Asia are trialing these structures for 30-year warranty alignment. The technology is decomposing incumbent single-resin supply relationships and forcing resin suppliers to qualify blend ratios rather than pure grades.
REACH restrictions on perfluorinated substances are tightening substance evaluation criteria for film additives and processing aids. European converters are reformulating slip agents and stabilizer packages to maintain extrusion throughput while satisfying SVHC disclosure thresholds. High-performance insulation grades for aerospace wire-and-cable applications face the steepest reformulation burden, as trace additive chemistry falls under heightened scrutiny.
Consolidated procurement by solar module tier-1s is compressing supplier negotiation cycles and unbundling technical service from material supply contracts. Buyers in China and India are negotiating direct resin supply agreements with fluoromonomer producers, bypassing film converter margins. This pattern concentrates specification-setting power with module manufacturers possessing in-house lamination expertise, marginalizing smaller converters lacking backward integration into resin supply.
Global Fluoropolymer Films Market Segmentation
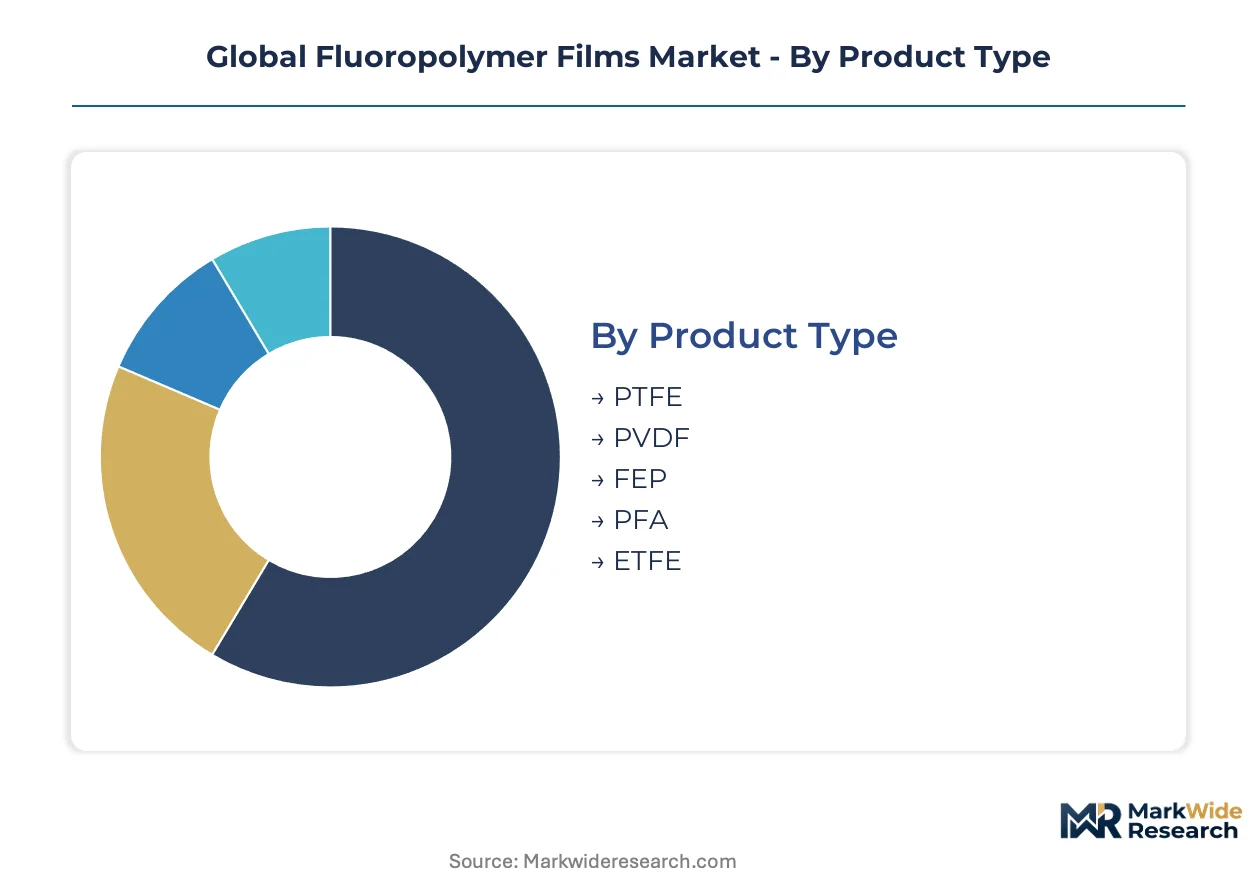
Fluoropolymer film suppliers calibrate grade portfolios across resin chemistry, end-use performance thresholds, and gauge specifications to capture margin pools in aerospace wire-and-cable, photovoltaic module assembly, and semiconductor process equipment. Segmentation discipline separates commodity converters from qualified specification holders in regulated applications.
Product Type:
PVDF and ETFE command premium pricing spreads over standard PTFE grades due to formulation complexity and architectural specification density.
- PVDF:Semi-crystalline fluoropolymer films deliver superior UV resistance and moisture barrier performance in photovoltaic backsheet laminates. Module assemblers in Jiangsu and Zhejiang provinces specify PVDF for 30-year warranty alignment under China's National Renewable Energy Administration standards.
- ETFE:Ethylene-tetrafluoroethylene copolymer films achieve 95% solar transmission while weighing 1% of equivalent glass panels. Stadium envelope contractors in Germany and greenhouse developers in the Netherlands specify ETFE cushions for structural dead load reduction and accelerated installation cycles.
- PTFE:Polytetrafluoroethylene films serve electrical insulation in aerospace wire-and-cable tiers requiring ASTM D3368 qualification.
- FEP:Fluorinated ethylene propylene films capture specification share in semiconductor process equipment gasketing where ultra-purity standards govern etch chamber sealing.
- PFA:Perfluoroalkoxy films extend thermal stability beyond FEP grades for chemical processing membrane applications.
PVDF holds installed capacity across Chinese PV supply chains. ETFE is rotating up the share rankings as tensile architecture projects multiply.
Application:
Electrical insulation and chemical processing applications concentrate qualification-intensive procurement with 18-24 month certification timelines.
- Electrical Insulation:PTFE and FEP films deliver dielectric isolation exceeding 260°C thermal thresholds in aerospace harness assemblies. Boeing and Airbus tier suppliers enforce lot traceability and additive disclosure under REACH SVHC protocols.
- Chemical Processing:PFA and PVDF membranes resist pH extremes in chlor-alkali electrolysis and sulfuric acid handling. German chemical manufacturers specify fluoropolymer films for process emission containment under EU Industrial Emissions Directive.
- Food Packaging:FEP release films enable high-temperature cooking surface applications with FDA compliance.
- Architectural Coatings:ETFE and PVDF films serve as protective topcoats for metal cladding systems.
- Automotive Components:Fuel cell membrane substrates adopt perfluorinated ionomer films for proton exchange durability.
Electrical insulation maintains qualification lock-in with aerospace OEMs. Chemical processing is expanding fastest as green hydrogen electrolyzer deployment accelerates.
End User Industry:
Electronics manufacturing and vehicle manufacturing concentrate growth investment as semiconductor node shrinkage and electric vehicle fuel cell adoption reshape demand profiles.
- Electronics Manufacturing:FEP and PFA ultra-purity grades seal etch chambers in sub-3nm chip fabrication. Taiwan Semiconductor Manufacturing and Samsung Electronics enforce particulate contamination thresholds below 0.1 particles per cubic foot.
- Vehicle Manufacturing:Proton exchange membrane electrolysis adopts perfluorinated ionomer films for stack durability under alkaline crossover conditions. Hyundai and Toyota fuel cell programs specify fluoropolymer membrane substrates for 10,000-hour operational life.
- Chemical Manufacturing:Process equipment linings and gasketing applications demand chemical inertness across pH extremes.
- Food Processing:High-temperature release surfaces and conveyor belt coatings utilize FEP non-stick properties.
- Construction:ETFE tensile structures and PVDF architectural coatings serve envelope and cladding applications.
Electronics manufacturing holds captive resin agreements with fluoromonomer producers. Vehicle manufacturing is climbing the fastest as fuel cell commercialization scales.
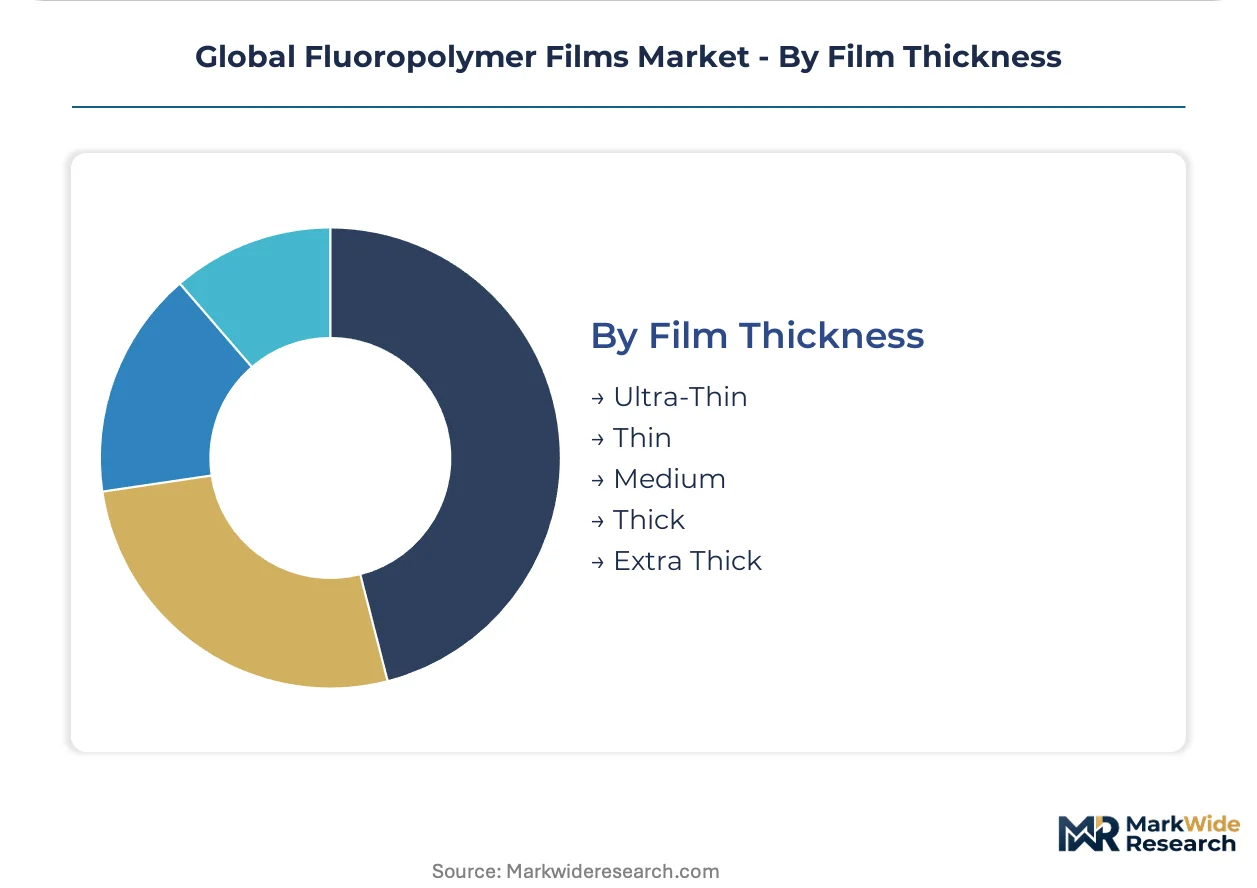
Film Thickness:
Ultra-thin and thin gauges concentrate aerospace and semiconductor applications where space constraints and thermal management dominate specification.
- Ultra-Thin:Sub-25 µm PTFE and FEP films enable miniaturized wire insulation in satellite harness assemblies. NASA and ESA contractors specify ultra-thin gauges for mass reduction in launch payload constraints.
- Thin:25-100 µm PVDF films balance moisture barrier performance with laminate flexibility in photovoltaic module backsheets. LONGi and JinkoSolar qualify thin-gauge suppliers for automated lamination line compatibility.
- Medium:100-250 µm films serve general industrial gasketing and chemical processing applications.
- Thick:250-400 µm grades provide structural integrity in architectural membrane cushions.
- Extra Thick:400-500 µm films deliver puncture resistance in heavy-duty chemical containment.
Ultra-thin maintains aerospace certification scarcity. Thin is gaining share fastest as PV module manufacturers optimize material yield per watt.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation phase-down schedules are redirecting converter investment toward PTFE and ETFE alternatives across European film markets. China's MEE dual carbon enforcement pressures fluorochemical producers to document carbon intensity. India's National Solar Mission targets create qualified supplier vacancies for backsheet films as domestic module assembly accelerates.
United States
Aerospace wire-and-cable tiers enforce ASTM D3368 qualification cycles for electrical-grade PTFE films. EPA TSCA Section 5 notification burdens delay commercialization of modified copolymer grades. Boeing and Airbus supply chains in the Pacific Northwest and Southeast maintain lot traceability and additive disclosure protocols under REACH SVHC alignment.
China
Module production lines in Jiangsu and Zhejiang provinces source fluoropolymer films locally, compressing import dependence. MEE enforces dual carbon goals that pressure PTFE and PVDF producers to abate process emissions. Yangtze River Delta PV manufacturing clusters amplify regional supply chain density for thin-gauge backsheet qualification.
Germany
ETFE stadium envelope contractors specify cushion systems for structural dead load reduction. ECHA REACH restrictions tighten substance evaluation criteria for film additives and processing aids. Greenhouse developers in the Netherlands and stadium projects across North Rhine-Westphalia drive specification shifts from glass to membrane architecture.
Japan
Semiconductor process equipment gasketing demands FEP and PFA ultra-purity grades for sub-3nm chip fabrication. METI industrial policy supports domestic fluorspar processing and melt-extrusion capacity. Kanto and Kansai electronics manufacturing clusters enforce particulate contamination thresholds below 0.1 particles per cubic foot.
India
National Solar Mission targets create qualified supplier vacancies for backsheet films as module assembly accelerates in Gujarat and Rajasthan. BIS standards alignment pressures film converters to qualify resin formulations for 30-year warranty coverage. Domestic lamination expertise concentrates procurement power with tier-1 module manufacturers in western and northern industrial corridors.
Global Fluoropolymer Films Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive fluoromonomer supply. The market structure concentrates specification-setting power among resin producers possessing backward integration into fluorspar processing and melt-extrusion capacity. Three archetypes dominate: integrated resin-to-film producers, specialized architectural film converters, and aerospace-qualified insulation grade suppliers. Competitive moves center on multilayer co-extrusion technology licensing and direct resin supply agreements that bypass traditional converter margins.
Among integrated chemical conglomerates, Saint-Gobain, DuPont, and AGC Chemicals occupy positions that exemplify the resin-backed archetype. These France-based, US-based, and Japan-based entities anchor the premium tier through captive supply chain control. Solvay represents the architectural specialization vector with ETFE formulation focus. The Chemours Company and DAIKIN INDUSTRIES, Ltd. sit within the fluoromonomer production tier that supplies downstream converters. 3M and Arkema Group exemplify diversified material science portfolios spanning multiple fluoropolymer grades. Asahi Kasei Corporation anchors Japanese domestic capacity for semiconductor-grade films.
| Leading Market Players |
|---|
| Saint-Gobain |
| DuPont |
| 3M |
| AGC Chemicals |
| Arkema Group |
| DAIKIN INDUSTRIES, Ltd. |
| Solvay |
| Asahi Kasei Corporation |
| The Chemours Company |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Chinese PV module manufacturers and fluoropolymer resin producers lock in multi-year supply access while fixing price visibility against acid-grade fluorspar volatility. These contracts concentrate procurement power with tier-1 assemblers possessing in-house lamination expertise, compressing converter margins and amplifying backward integration incentives across the Yangtze River Delta.
Pricing Analysis
Certification level creates the primary spread between aerospace-qualified PTFE grades and commodity converter offerings. Three-tier pricing structure across premium, standard, and economy levels stratifies by ASTM D3368 qualification status, resin purity tiers, and volume scale commitments. Cost compression in standard-grade PVDF backsheet films is intensifying because consolidated procurement by Chinese tier-1 module manufacturers unbundles technical service from material contracts. Utility-scale solar developers exhibit highest price sensitivity, while semiconductor etch chamber OEMs prioritize ultra-purity FEP grades with minimal negotiation leverage.
Supply Chain Analysis
Inventory buffers for acid-grade fluorspar extend to 90-120 days across Japanese melt-extrusion facilities, reflecting freight cost spikes from Mexican and Chinese mining concentration. Fluoropolymer film production draws from concentrated fluorspar supply in Mexico and China, tetrafluoroethylene monomer capacity in Japan and the United States, and specialized extrusion equipment anchored in German and Japanese engineering clusters. Single-source vulnerability in acid-grade fluorspar export quotas from China exposes film producers to supply interruption. Distribution runs through direct resin supply agreements that bypass traditional converter tiers, concentrating specification-setting power with backward-integrated chemical conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tier-1 PV module manufacturers through consolidated procurement and in-house lamination expertise, fragmenting converter margins and forcing supply chain restructuring toward direct resin relationships.
For Market Incumbents: Compound qualification lock-in by accelerating ASTM D3368 certification cycles for next-generation ETFE architectural grades, defending against glass-glass module substitution in utility-scale solar. Prioritize backward integration into fluorspar processing to offset Mexican and Chinese export quota volatility, while expanding melt-extrusion capacity in Japan and Germany to serve semiconductor gasketing demand. For New Entrants and Emerging Players: Anchor in India's National Solar Mission backsheet film vacancies, where BIS standards alignment creates qualified supplier gaps and domestic lamination expertise concentrates with western and northern module assemblers. Target green hydrogen electrolyzer membrane substrates as the most penetrable application, leveraging perfluorinated ionomer film demand from Hyundai and Toyota fuel cell programs with technical partnerships over volume scale. For Investors and Strategic Acquirers: Capital is best deployed toward integrated resin-to-film producers possessing captive fluoromonomer supply and fluorspar processing assets, as these archetypes sustain pricing power across regulated aerospace and semiconductor tiers. Watch for inflection in EU F-Gas Regulation enforcement intensity, which would accelerate converter investment toward PTFE and ETFE alternatives and reshape acquisition premiums for precursor-independent production assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Processing | Captive acid-grade supply insulates against Chinese export quota volatility and freight spikes. |
| Multilayer Co-Extrusion Technology Licensing | Enables zoned functionality in PVDF-ETFE laminates for 30-year warranty alignment with LONGi and JinkoSolar. |
| Direct Resin Supply Agreements | Bypasses converter margins and concentrates procurement power with tier-1 module manufacturers in Jiangsu. |
| ASTM D3368 Certification Investment | Locks in aerospace wire-and-cable tiers with 18-24 month qualification cycles and incumbent protection. |
| Green Manufacturing Transition | MEE dual carbon compliance documentation opens Chinese PV supply chains to carbon-audited European exporters. |
Research Methodology
Desk research of customs trade data, SEC 10-K filings from fluorochemical producers, ECHA REACH substance registrations, and Chinese MEE emission disclosure records preceded structured interviews with plant managers at melt-extrusion facilities, procurement leads at PV module tier-1s, distribution channel partners in architectural membrane contracting, and technical R&D directors at semiconductor equipment OEMs. Primary intelligence combined with secondary validation through bottom-up resin consumption modeling and top-down end-use demand aggregation.
Variance decomposition across product type, application, end-use industry, and film thickness dimensions isolates growth contribution by segment throughout the forecast period. CAGRs derive from elasticity-adjusted demand modeling against PV installation forecasts, semiconductor capital expenditure cycles, and architectural project pipelines. Industry-specific inputs include fluorspar export quota trajectories, EU F-Gas Regulation phase-down schedules, and MEE dual carbon enforcement intensity indices.
Material uncertainties — regulatory divergence across EPA TSCA Section 5, ECHA REACH restrictions, and Chinese MEE emission standards — sit outside the modeled envelope and could accelerate or delay commercialization timelines for modified copolymer grades. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Global Cast Polypropylene Packaging Films Market
Poly film
Blown Film Extruder Market
Poly film
APET Film Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
Printed Plastic Films Market
Poly film
Wrap Around Label Films Market
Poly film
Germany Plastic Packaging Films Market
Poly film
PCR Lidding Films Market
Poly film
Global Specialty Films Polymer Market
Poly film
MOPP Packaging Films Market
Poly film
Global PVDC Coated Films Market
Poly film
Peelable and Resealable Films Market
Poly film
PE Foam Films Market
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
Japan Polypropylene Packaging Films Market
Poly film
Poly Coated Kraft Paper Market