
 Shrink Bundling Films Market | 2026-2036
Shrink Bundling Films Market Size, Share, and Industry Trends Forecast 2026-2036
Shrink Bundling Films Market Analytics
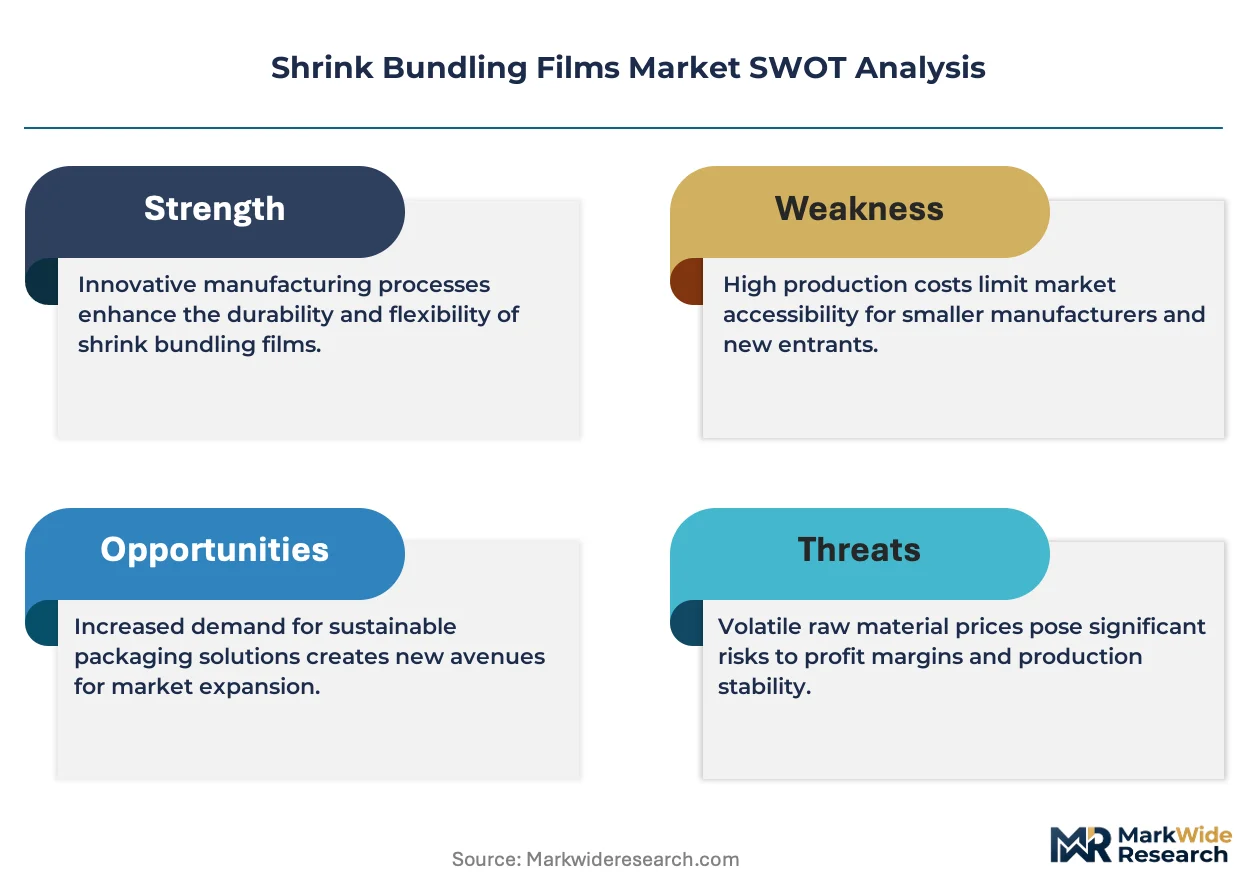
Asset-light leasing models for extrusion equipment is fragmenting competitive dynamics in shrink bundling films. Sealed Air Corporation leverages vertical integration across resin conversion and distribution to sustain margin control in North America. Berry Global Inc. anchors its position through manufacturing scale and captive supply of polyethylene formulations. Klöckner Pentaplast differentiates via specialized polyolefin grades engineered for high-speed beverage lines.
Shrink bundling films are thermoplastic polymer sheets, typically 25–150 microns thick, that contract uniformly when heated to 80–160°C, forming a tight unitized wrap around multipack consumer goods. The primary commercial purpose is to replace corrugated trays and reduce secondary packaging weight in beverage and personal care distribution. Polyethylene occupies the largest volume share due to its cost position and compatibility with existing heat-tunnel infrastructure across pallet shrink wrapping applications. Polyolefin films represent the fastest-expanding category, driven by demand for optical clarity and seal strength in retail packaging display applications.
The EPA regulates resin manufacturing emissions under the Clean Air Act, while FDA compliance governs direct food-contact film formulations in the United States. REACH and the EU Packaging and Packaging Waste Directive enforce recyclability thresholds and restricted substance limits for films sold in Europe. Stakeholders must monitor evolving extended producer responsibility schemes and recycled content mandates to determine resin sourcing strategies and capital allocation for extrusion line upgrades.
Market Dynamics
The EU Single-Use Plastics Directive and post-consumer recycled content mandates are forcing resin reformulation across extrusion lines, while beverage brands accelerate corrugated replacement programs. Asset-light equipment leasing is fragmenting competitive positioning between integrated majors and regional converters.
Growth Catalysts
- Corrugated displacement in beverage multipacks:Brands reduce secondary packaging weight by 60-80% through film substitution. Heat-tunnel infrastructure investments at Coca-Cola and PepsiCo bottlers validate the operational shift.
- REACH recyclability thresholds:The EU Packaging and Packaging Waste Directive mandates 50% plastic packaging recycling rates by 2025. Film producers engineer mono-material polyolefin grades to meet mechanical recycling stream requirements.
- Automated beverage line expansion:Germany's packaging machinery sector deploys high-speed shrink bundlers capable of 100+ cycles per minute. Optical clarity specifications tighten as retail display becomes a functional requirement.
Market Restraints
- Ethylene feedstock volatility:Crude oil and natural gas liquids pricing swings compress polyethylene margin structures. Producers lack pass-through mechanisms for spot resin cost spikes.
- Extrusion equipment supply concentration:German and Italian machinery builders control 70% of high-output blown film line capacity. Lead times extend 18-24 months during capacity expansion cycles.
- Mechanical recycling contamination limits:Multi-layer barrier films face downcycling constraints. Sorting infrastructure cannot separate polyolefin grades from PVC or PET contamination streams.
Strategic Opportunities
- India beverage packaging modernization:FSSAI food-contact compliance upgrades and organized retail expansion create demand for clarity-graded films. Domestic converters lack technical capability for high-speed line integration.
- Chemical recycling feedstock partnerships:Pyrolysis and depolymerization facilities in Netherlands and Spain seek consistent polyolefin waste streams. Film producers secure offtake agreements for non-mechanically recyclable volumes.
- Personal care e-commerce bundling:Subscription box fulfillment requires puncture-resistant films with printable surfaces. Amazon and Sephora distribution specifications drive specification divergence from beverage standards.
Industry Challenges
- Extrusion technician scarcity:Blown film die adjustment and gauge control expertise concentrates in aging workforces. Technical training programs lack alignment with Industry 4.0 sensor integration requirements.
- FDA food-contact notification timelines:Novel recycled content formulations require 180-day pre-market review cycles. Product development schedules misalign with brand sustainability commitment deadlines.
- Legacy heat-tunnel retrofit complexity:Existing beverage lines operate at fixed temperature profiles. Polyolefin films with higher shrink initiation temperatures demand air-flow system modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shrink Bundling Films Market |
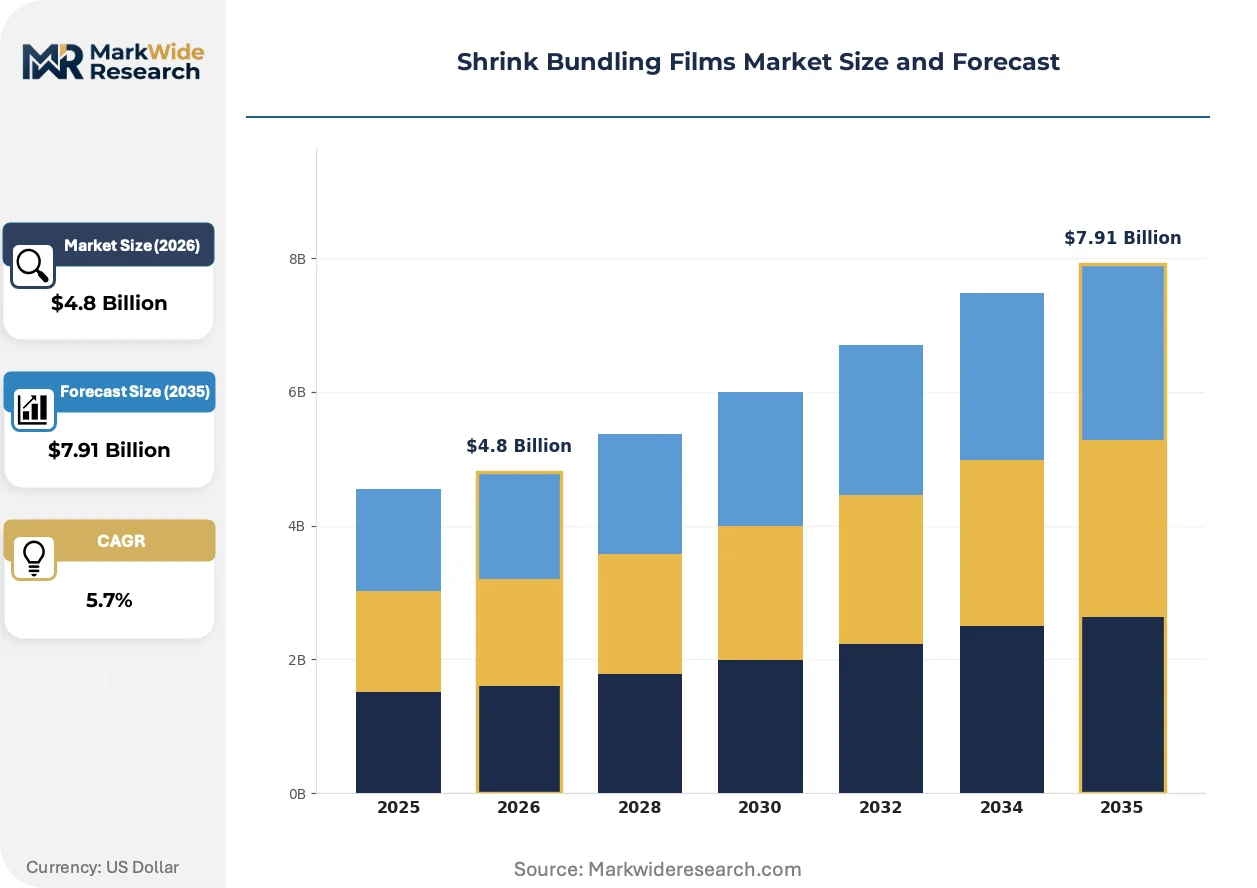
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polyvinyl Chloride, Polyolefin, Others End User: Food & Beverage, Consumer Goods, Healthcare, Electronics Thickness: Thin, Medium, Thick, Extra Thick Application: Pallet Shrink Wrapping, Multipack Shrink Wrapping, Retail Packaging, Industrial Packaging |
| Companies Covered | Berry Global Inc., Coveris Holdings S.A., Sigma Plastics Group, Fuji Seal International, CCL Industries, Sealed Air Corporation, Klöckner Pentaplast, Cosmo Films Limited, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shrink Bundling Films Market Evolving Landscape
Material science convergence with regulatory chemistry is redefining acceptable performance thresholds. Digital printing integration and closed-loop collection systems are emerging as competitive differentiators beyond unit cost.
Polyolefin shrink films is hybridizing polyethylene and polypropylene resin ratios to optimize tear propagation and optical haze simultaneously. High-speed beverage bottlers in Germany and the United States pilot these formulations at 15-20% line speed improvements. The technology is hybridizing conventional monolayer and multilayer extrusion equipment into single production assets, compressing capital requirements for mid-scale converters.
REACH restricted substance lists now explicitly regulate phthalate plasticizers and heavy metal pigments in packaging films. The European Chemicals Agency enforcement is disqualifying legacy PVC shrink formulations from food-contact applications. Personal care and pharmaceutical bundling applications in France and Italy are accelerating migration to polyolefin alternatives ahead of 2026 compliance deadlines.
Beverage brand technical buyers now specify recycled content certificates as mandatory procurement criteria rather than preferential attributes. Third-party verification through EuCertPlast and RecyClass schemes is displacing self-declared sustainability claims in European tender processes. The procurement pattern shift is most visible in German retail chains and Nordic beverage cooperatives with binding plastic reduction targets.
Shrink Bundling Films Market Segmentation
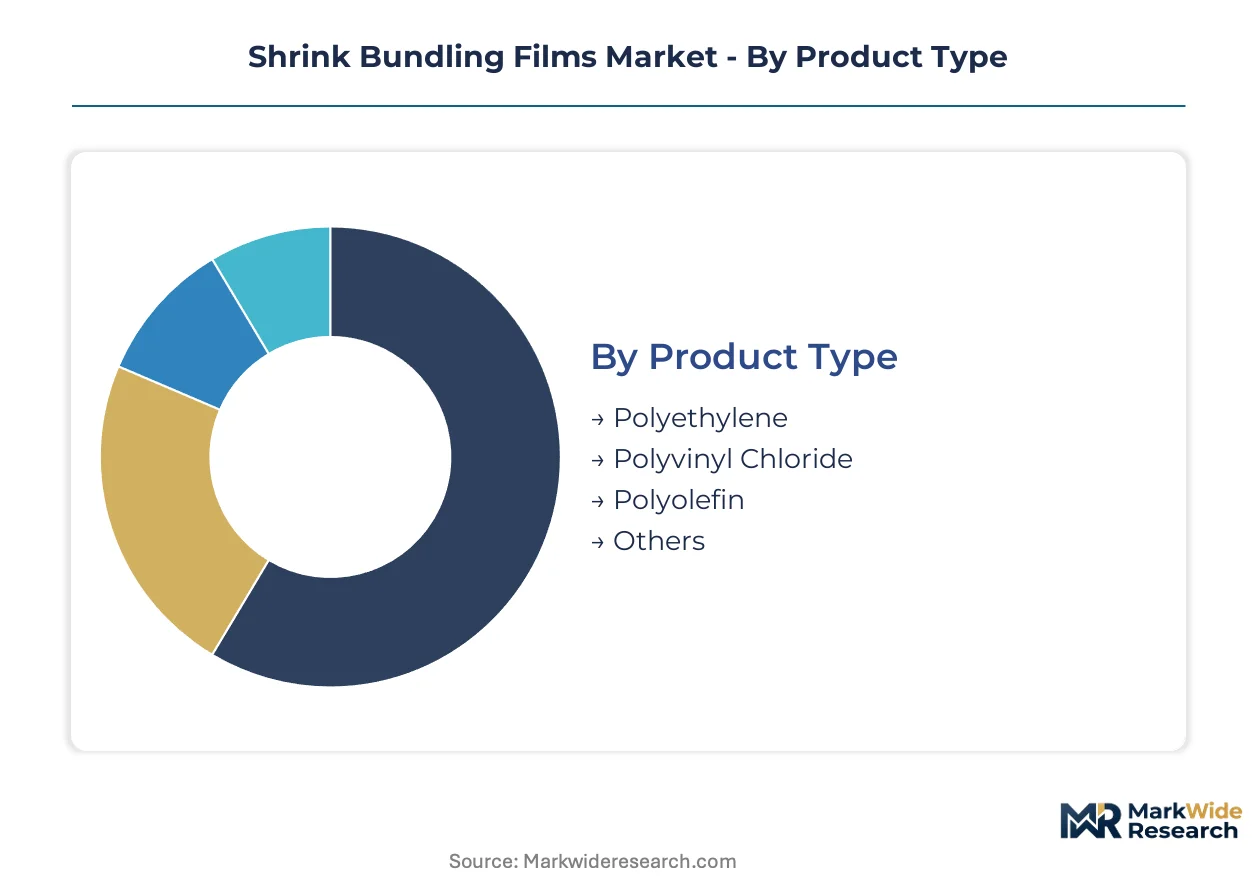
Segmentation in shrink bundling films determines resin sourcing strategies, extrusion equipment specifications, and heat-tunnel compatibility requirements. Technical buyers at beverage bottlers and personal care brands specify film grades based on line speed, optical clarity needs, and recyclability mandates. Understanding category boundaries clarifies where formulation innovation creates pricing power versus where commoditization pressures dominate.
Product Type:
After-sales service intensity varies sharply across resin chemistries, with polyolefin grades demanding specialized die adjustment support and formulation troubleshooting that polyethylene suppliers rarely provide.
- Polyethylene:Low-density and linear low-density formulations dominate pallet wrapping and heavy-duty industrial applications due to cost position and tear resistance. Demand concentrates in automated beverage distribution centers across Germany and the United States, where existing heat-tunnel infrastructure favors polyethylene's lower shrink initiation temperatures. Margin compression from ethylene feedstock volatility limits technical service investment from commodity resin suppliers.
- Polyolefin:Hybrid polyethylene-polypropylene grades deliver optical clarity below 3% haze and seal strengths exceeding 25 N/15mm for retail display applications. German high-speed bottlers at 100+ cycles per minute specify these formulations for multipack transparency requirements. The segment commands premium positioning through EuCertPlast recyclability certification and mono-material compatibility with mechanical recycling streams.
- Polyvinyl Chloride:Legacy formulations face REACH phthalate restrictions and heavy metal pigment bans in European food-contact applications.
- Others:PETG and PLA biopolymer grades serve niche pharmaceutical and organic personal care bundling with compostability claims.
By volume, Polyethylene leads. By growth pace, Polyolefin is ahead.
End User:
Cost tier stratification separates specification-intensive beverage accounts from price-sensitive industrial buyers, with healthcare and electronics occupying intermediate positions on technical service requirements.
- Food & Beverage:Multipack collation for carbonated soft drinks, bottled water, and alcoholic beverages drives the largest absolute volume, with Coca-Cola and PepsiCo bottlers validating heat-tunnel infrastructure investments. FDA food-contact notification timelines and FSSAI compliance upgrades in India create formulation barriers for regional converters lacking regulatory affairs capabilities.
- Consumer Goods:Personal care subscription boxes and e-commerce fulfillment require puncture-resistant films with printable surfaces for Amazon and Sephora distribution specifications. Amazon's Frustration-Free Packaging guidelines and puncture-testing protocols differentiate this segment from beverage standards on tear propagation and ink adhesion.
- Healthcare:Pharmaceutical bundling demands particulate-free films with lot-code traceability and tamper-evident seal indicators.
- Electronics:Anti-static formulations protect sensitive components during regional distribution, with ESD control specifications from German automotive electronics suppliers.
Food & Beverage captures the highest volume concentration. Consumer Goods shows the steepest specification divergence from commodity norms.
Thickness:
Volume scale concentrates in medium gauges where blown film line economics optimize output rates against gauge control precision requirements.
- Thin:25-50 micron films serve lightweight retail multipacks where material reduction targets outweigh puncture resistance needs. German discount retailers and Nordic beverage cooperatives specify these grades for plastic reduction commitments.
- Medium:50-100 micron films balance clarity, strength, and heat-tunnel compatibility across the broadest application range. Automated beverage lines in the United States and Germany standardize on this band for operational consistency.
- Thick:100-150 micron formulations protect irregular-shaped consumer goods and personal care bundles through distribution handling.
- Extra Thick:Above 150 micron grades serve heavy industrial pallet wrapping and export shipment unitization.
Medium thickness dominates current extrusion output. Thin films are gaining share fastest under material reduction mandates.
Application:
Supply concentration in high-output blown film equipment shapes competitive access, with pallet wrapping served by commodity converters and retail packaging demanding specialized optical-grade resin partnerships.
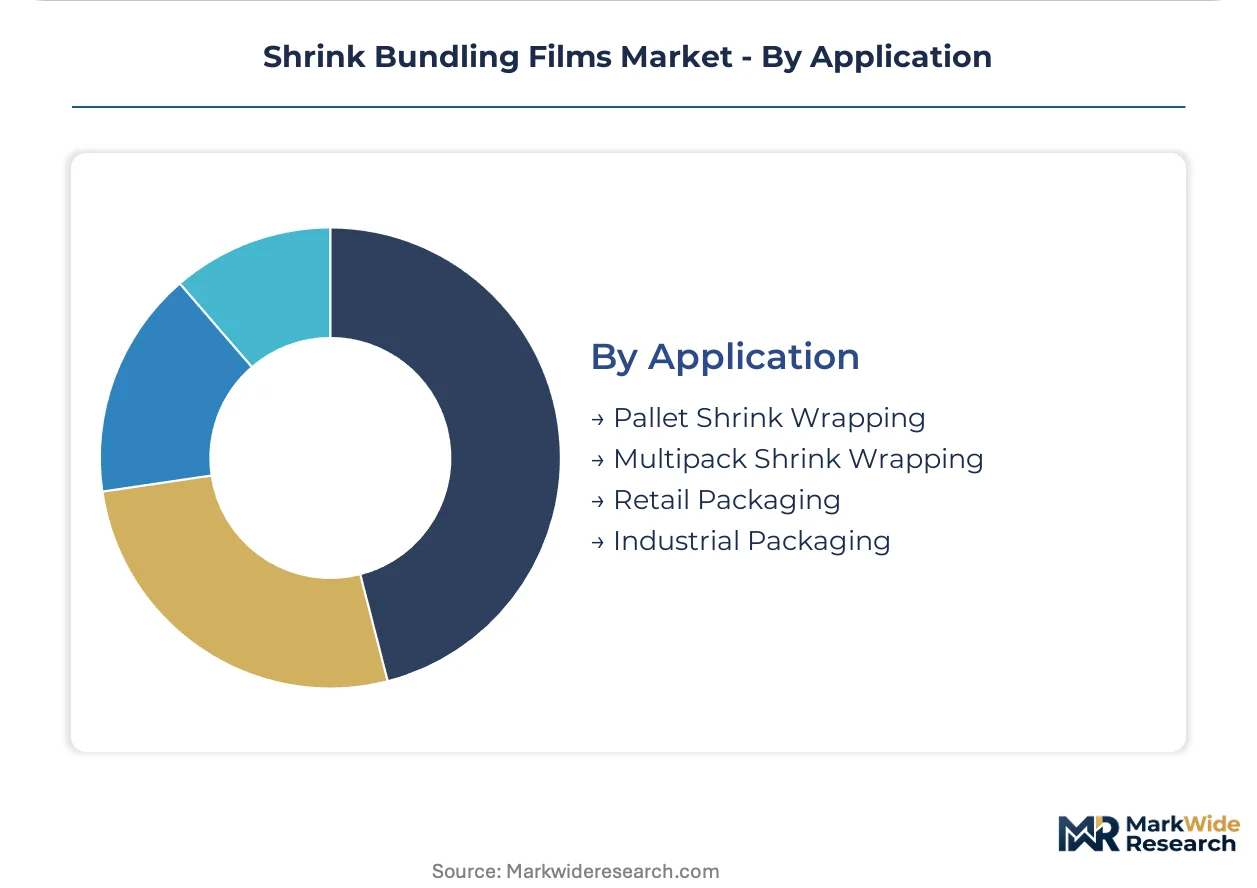
- Pallet Shrink Wrapping:Unitization of bulk shipments for distribution centers relies on polyethylene formulations with high holding force and UV stabilization for outdoor storage. Demand clusters at Coca-Cola and PepsiCo distribution hubs where corrugated displacement programs prioritize secondary packaging weight reduction over display aesthetics.
- Multipack Shrink Wrapping:Beverage collation into 6-packs and 12-packs requires precise shrink force control to prevent bottle deformation at 80-160°C tunnel temperatures. German packaging machinery builders specify optical clarity and seal strength thresholds that disqualify legacy PVC formulations.
- Retail Packaging:Shelf-ready display wrapping for consumer goods and personal care demands haze specifications below 5% and printable surfaces for promotional messaging.
- Industrial Packaging:Heavy-duty machinery and building product wrapping prioritizes puncture resistance and weatherability over optical properties.
Pallet Shrink Wrapping leads by installed equipment base. Multipack Shrink Wrapping is expanding most quickly under corrugated replacement programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in shrink bundling films tilt toward net-import positions in high-consumption beverage markets, while resin-rich economies maintain export surpluses in base polyethylene grades. Regulatory divergence on recycled content mandates is fragmenting regional sourcing patterns.
Germany
Automated beverage bottling lines at 100+ cycles per minute drive specification-grade polyolefin consumption. REACH and the EU Packaging and Packaging Waste Directive enforce 50% plastic recycling thresholds, disqualifying legacy PVC formulations. The Baden-Württemberg and Bavaria machinery clusters concentrate extrusion equipment supply and technical service capability.
United States
Coca-Cola and PepsiCo distribution centers validate heat-tunnel infrastructure investments for corrugated displacement programs. FDA food-contact notification timelines govern novel recycled content formulations, creating 180-day pre-market review cycles. The Midwest industrial corridor anchors blown film production capacity serving automated beverage lines.
China
Domestic beverage brands accelerate secondary packaging weight reduction targets, pulling optical-grade film imports. GB standards and MIIT industrial policy guide resin formulation approvals for food-contact applications. The Yangtze River Delta concentrates extrusion equipment manufacturing and technical workforce development programs.
India
Organized retail expansion and FSSAI food-contact compliance upgrades create demand for clarity-graded films that domestic converters cannot supply. The PLI scheme for packaging materials incentivizes imported machinery deployment. Maharashtra and Gujarat host the technical bottling lines requiring high-speed shrink bundler integration.
Netherlands
Chemical recycling pyrolysis facilities in Rotterdam and Moerdijk seek consistent polyolefin waste streams for feedstock supply agreements. ECHA enforcement of REACH restricted substance lists accelerates migration from PVC to polyolefin alternatives. The Randstad logistics hub positions the country as a redistribution point for EU beverage packaging films.
Shrink Bundling Films Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on resin formulation and die technology. The vendor base concentrates around integrated resin-to-film converters and regional blown film specialists, with mid-scale players leasing extrusion equipment to fragment capacity economics. Three archetypes dominate: captive resin suppliers with backward integration into polyethylene production, specialized polyolefin formulators serving high-speed beverage lines, and asset-light regional converters exploiting equipment leasing. Competitive moves center on chemical recycling feedstock partnerships and mono-material grade certification to meet EuCertPlast and RecyClass verification requirements.
Within the integrated resin converter tier, Berry Global Inc. and Sealed Air Corporation exemplify scale-driven positioning through captive supply chains. Klöckner Pentaplast occupies a specialist position on optical-grade polyolefin engineering. These three anchors demonstrate how backward integration into resin production, manufacturing scale, and formulation specialization respectively defend margin structures against feedstock volatility and regulatory compliance costs.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Coveris Holdings S.A. |
| Sigma Plastics Group |
| Fuji Seal International |
| CCL Industries |
| Sealed Air Corporation |
| Klöckner Pentaplast |
| Cosmo Films Limited |
| Amcor plc |
| Others |
Value Network & Pricing Analysis
Ethylene feedstock volatility compresses margin structures across polyethylene grades while simultaneously widening price spreads between commodity and certified polyolefin formulations. This single-source dependency on petrochemical resin pricing determines both three-tier pricing stratification and the geographic clustering of extrusion capacity around major resin production hubs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements that stabilize polyethylene pricing for pallet wrapping applications. Premium-mid-economy pricing differentiation separates EuCertPlast-certified polyolefin grades from standard formulations through optical clarity thresholds and seal strength guarantees. Cost compression in commodity polyethylene is intensifying because ethylene spot price spikes lack full pass-through mechanisms. Beverage bottlers show least price sensitivity for specification-grade films, while regional converters in emerging markets face acute margin pressure.
Supply Chain Analysis
German and Italian machinery builders control high-output blown film line manufacturing, with extrusion equipment supply concentrating in Baden-Württemberg and Bologna industrial clusters. Raw material flows draw from Saudi Arabian and U.S. Gulf Coast ethylene crackers, with European resin supply tethered to naphtha cracking economics. Single-source vulnerability sits with 18-24 month equipment lead times during capacity expansion cycles. Distribution runs through captive resin-to-film converter networks and regional blown film specialists serving beverage bottlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shrink bundling films occupy an early-cycle expansion phase as corrugated displacement programs accelerate across beverage distribution networks. The operational shift at Coca-Cola and PepsiCo bottlers validates heat-tunnel infrastructure investments as a durable demand tailwind.
For Market Incumbents: Pre-empt margin erosion from asset-light regional converters by securing captive supply of post-consumer recycled resin feedstocks. Deepen backward integration into pyrolysis partnerships with Rotterdam and Moerdijk chemical recycling facilities. Certification investment in RecyClass and EuCertPlast verification schemes creates switching costs against commodity competitors. For New Entrants and Emerging Players: Build out technical service capabilities for high-speed line integration in India, where FSSAI compliance upgrades outpace domestic converter expertise. Target Maharashtra and Gujarat beverage bottlers requiring clarity-graded films with localized die adjustment support. A go-to-market angle through equipment leasing partnerships fragments incumbent scale advantages. For Investors and Strategic Acquirers: REACH recyclability thresholds and the EU Packaging and Packaging Waste Directive reshape the acquisition landscape toward mono-material polyolefin formulators. Long-term viability centers on chemical recycling feedstock offtake agreements rather than mechanical recycling exposure. Watch for EuCertPlast certification velocity as the inflection signal distinguishing premium from commodity valuation tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Feedstock Partnership | Pyrolysis facilities in Netherlands and Spain secure consistent polyolefin waste streams for circular production. |
| Mono-Material Grade Certification | EuCertPlast and RecyClass verification meets EU Packaging and Packaging Waste Directive mechanical recycling requirements. |
| High-Speed Line Technical Service | Die adjustment expertise for 100+ cycle-per-minute German bottlers creates account stickiness against commodity suppliers. |
| Asset-Light Equipment Leasing | Regional converters fragment capacity economics without capital intensity of blown film line ownership. |
| Post-Consumer Recycled Content Scale-Up | FDA food-contact notification timelines for novel formulations align with brand sustainability procurement mandates. |
Research Methodology
The analysis maps polyethylene, polyolefin, and legacy PVC sub-sectors, each validated through extrusion equipment manufacturers, resin procurement leads at beverage bottlers, technical service directors, and distribution channel partners. Primary interviews with plant managers at German packaging machinery builders and blown film line operators combined with secondary validation from customs trade data, SEC 10-K filings of integrated resin converters, and ECHA REACH substance restriction updates. Bottom-up triangulation across resin formulation specifications and top-down cross-check against installed heat-tunnel infrastructure capacity anchored volume estimates.
Fixed assumptions across the analysis window held EU recycling rate mandates and FDA notification timelines constant, while ethylene feedstock pricing and equipment lead times varied stochastically. Segmentation dimensions modeled include resin chemistry grade, end-use application, thickness band, and regional regulatory cluster. CAGRs were derived from elasticity analysis of beverage multipack collation demand against corrugated substitution rates, with optical clarity specifications and seal strength thresholds as industry-specific forecast inputs.
Stress conditions across ethylene price volatility bands, extrusion equipment availability, and REACH enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory compliance timelines and brand sustainability commitment durability. Quarterly review of chemical recycling facility commissioning rates and EuCertPlast certification velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Germany Plastic Packaging Films Market
Poly film
Bio-PET Film Market
Poly film
Polystyrene Films Market
Poly film
Australia and New Zealand Plastic Packaging Film Market
Poly film
Brazil Plastic Packaging Films Market
Poly film
Silicone-Coated PET Films Market
Poly film
Indonesia Plastic Packaging Films Market
Poly film
Polycarbonate Films Market
Poly film
Blown Film Extruder Market
Poly film
North America Plastic Film Packaging Market
Poly film
UAE Plastic Packaging Films Market
Poly film
Light Reflective Film Market
Poly film
Global Fluoropolymer Films Market
Poly film
Forming Films Market
Poly film
PVC Cling Film Market
Poly film
Egypt Plastic Packaging Films Market