
 Polyolefin (POF) Shrink Film Market | 2026-2036
Polyolefin (POF) Shrink Film Market Size, Share, and Industry Trends Forecast 2026-2036
Polyolefin (POF) Shrink Film Market Analytics
Polyethylene is expanding its displacement of PVC across shrink-wrap applications, cutting unit costs while improving recyclability profiles. Sealed Air Corporation leverages integrated resin-to-film operations to sustain margin control across North American distribution. Amcor Plc anchors its position through pharmaceutical-grade certification and multi-layer coextrusion expertise. Berry Global Inc. competes on scale, operating one of the largest POF converting networks serving mass-market consumer goods.
Polyolefin shrink film comprises linear low-density polyethylene and polypropylene resins, extruded into biaxially oriented films with shrink initiation temperatures between 120°C and 160°C, engineered to conform tightly to product contours through controlled heat application. Cross-linked grades dominate premium applications where puncture resistance and clarity thresholds exceed standard film capabilities, while single-wound configurations lead volume throughput in automated wrapping lines. The food and beverage end-use segment channels the majority of value as processors specify below-60-micron films to balance material yield against barrier performance.
REACH restricts phthalate plasticizer migration in food-contact films across Europe, compelling converters to validate POF formulations through ECHA-registered supply chains. FDA maintains 21 CFR 177.1520 compliance thresholds for olefin polymers in direct food applications, creating a dual-certification burden for exporters serving both jurisdictions. Stakeholders must monitor evolving extended producer responsibility frameworks in key consuming countries, as packaging waste directives increasingly mandate recycled content minimums that current mechanical recycling infrastructure cannot yet satisfy at commercial scale.
Market Dynamics
Food processors are accelerating PVC replacement programs as ECHA-registered POF supply chains mature, while Chinese resin-to-film converters capture cross-linked grade capacity that Western incumbents had dominated.
Growth Catalysts
- REACH phthalate migration limits:European food-contact film specifications now exclude plasticized PVC, validating olefin-based alternatives through ECHA-registered supply chains and redirecting converter qualification programs.
- Cross-linked film technology:Puncture-resistant grades above 80% shrink ratios penetrate premium electronics and pharmaceutical bundling where clarity thresholds exceed standard film capabilities.
- China:Domestic resin producers backward-integrate into biaxial orientation lines, reducing import dependency for high-clarity food packaging substrates.
Market Restraints
- LLDPE resin price volatility:Ethylene feedstock exposure tied to naphtha-cracker economics compresses film converter margins during upstream petrochemical cycles.
- Mechanical recycling infrastructure gaps:Post-industrial POF scrap collection networks remain underdeveloped relative to polyethylene terephthalate streams, limiting circularity claims.
- High-barrier substitution:Ethylene vinyl alcohol laminates and polyethylene terephthalate glycol films capture oxygen-sensitive applications where POF barrier performance proves insufficient.
Strategic Opportunities
- India:FSSAI food-contact compliance pathways for olefin polymers remain underpenetrated relative to PVC incumbent specifications, creating first-mover certification advantages.
- Pharmaceutical serialization bundling:Track-and-trace mandates for secondary packaging drive demand for tamper-evident shrink configurations with integrated tear-tape features.
- EU Green Deal packaging waste directives:Extended producer responsibility frameworks with recycled content minimums favor mono-material POF over multi-layer barrier constructions.
Industry Challenges
- Biaxial orientation technician scarcity:Operating precision tenter-frame equipment requires specialized extrusion expertise that vocational pipelines have not replenished.
- Dual FDA-REACH certification timelines:Validating identical film formulations through 21 CFR 177.1520 and ECHA registration extends product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyolefin (POF) Shrink Film Market |
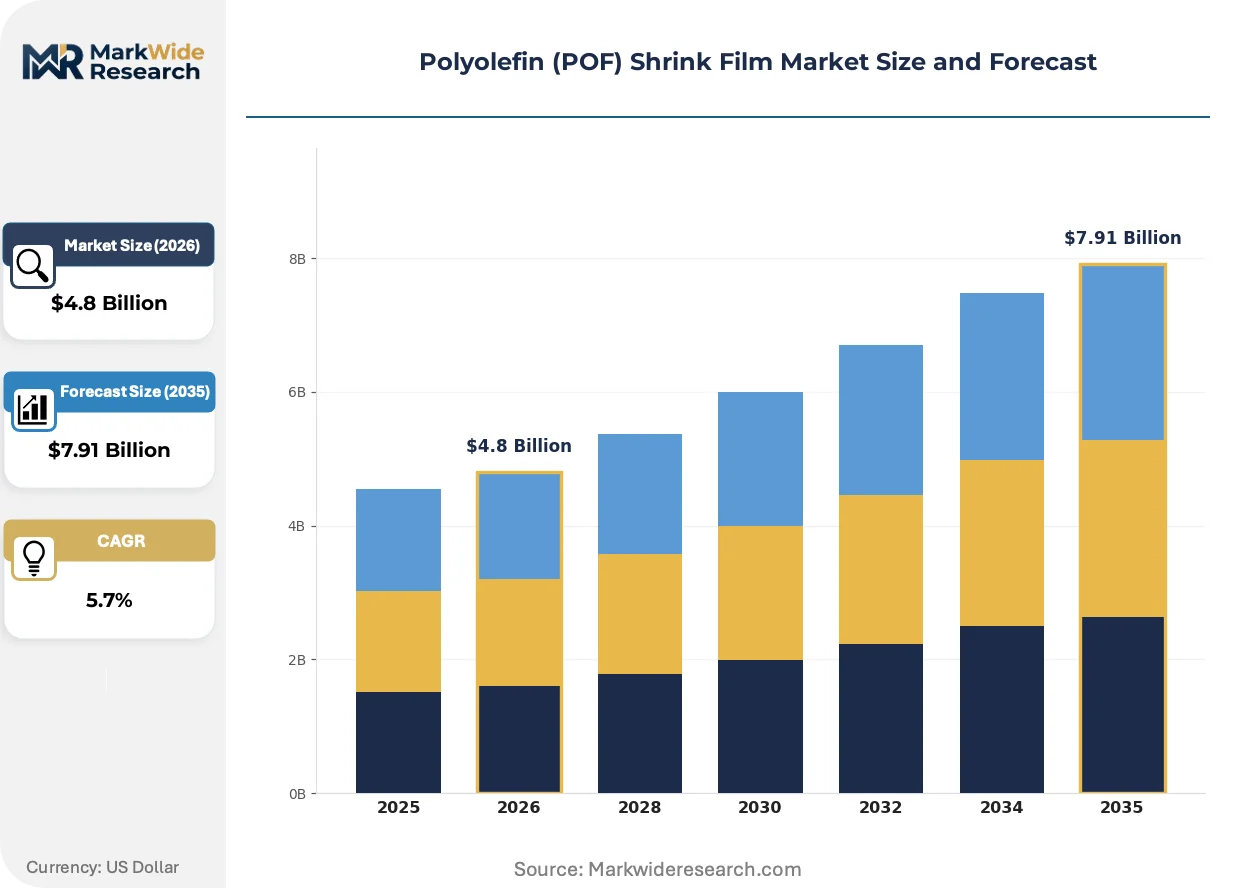
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Wound, Centerfold, Double-Wound, Cross-Linked Form: Rolls, Sheets, Bags, Tubing End Use Industry: Food & Beverage, Pharmaceuticals, Electronics, Consumer Goods Thickness: Below 40 Micron, 40-60 Micron, 60-80 Micron, Above 80 Micron |
| Companies Covered | Saudi Basic Industries Corporation, Bollore SE, Sealed Air Corporation, Clysar LLC, Sigma Plastics Group, Berry Global Inc., Intertape Polymer Group Inc., Allen Plastic Industries Co. Ltd., Amcor Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyolefin (POF) Shrink Film Market Evolving Landscape
Digital print compatibility and downgauging imperatives are restructuring film specifications, while regulatory pressure on packaging waste accelerates material substitution cycles across food and industrial end-uses.
Five-layer coextrusion with metallocene polyethylene is integrating discrete resin functionalities into unified film architectures. High-clarity food packagers in Germany and the Netherlands adopt these structures to sub-50-micron gauges without sacrificing seal integrity. This technology is integrating formerly separate converting steps, compressing the value chain between resin producer and finished rollstock.
REACH restriction proposals on intentionally added microplastics extend to film fragmentation behavior in marine environments. ECHA technical committees now require biodegradability validation for packaging films marketed as recyclable alternatives. European brand owners with marine-exposed distribution networks face the most acute compliance recalibration, accelerating bio-based olefin pilot programs.
Consolidated buying desks at multinational food retailers now specify film performance through outcome-based contracts rather than resin-grade procurement. Category managers at German and French hypermarket chains bundle shrink film with secondary packaging equipment service agreements. This pattern concentrates volume with converters offering integrated wrap-line optimization, squeezing standalone film suppliers in Western European supply bases.
Polyolefin (POF) Shrink Film Market Segmentation
POF shrink film specifications diverge sharply between high-throughput automated lines and precision manual applications. Film configuration, gauge, and orientation technology determine compatibility with wrapping equipment, barrier requirements, and regulatory compliance pathways across end-use verticals.
Product Type:
Volume throughput dominates cost structures, yet premium grades command margin through technical differentiation.
- Single-Wound:Single-layer film supplied on individual cores for automated L-bar sealers and side-seal equipment. High-speed food packaging lines in Germany and the Netherlands specify sub-50-micron single-wound rolls to maximize yield per pallet wrapped while maintaining seal integrity under 21 CFR 177.1520 compliance.
- Cross-Linked:Electron-beam or chemical cross-linking creates puncture-resistant molecular structures with shrink ratios exceeding 80%. Pharmaceutical bundling and premium electronics packaging in Japan demand these grades where clarity thresholds and abuse resistance exceed standard film capabilities.
- Centerfold:Film folded lengthwise during winding, enabling single-pass wrapping without separate bottom sealing. Manual and semi-automatic operations favor this configuration for flexibility across variable product dimensions.
- Double-Wound:Two film layers wound simultaneously on a common core, doubling throughput for high-volume operations with compatible equipment.
Today's leader: Single-Wound. Tomorrow's challenger: Cross-Linked.
Form:
Downstream converting integration reshapes how film reaches end-users.
- Rolls:Standard mill output for converter slitting and custom bag fabrication. Industrial distributors in the US stock master rolls for just-in-time slitting to customer width specifications.
- Bags:Pre-formed pouches with sealed bottoms, eliminating secondary converting for manual packaging operations. Small-batch food processors in India specify FSSAI-compliant POF bags to bypass capital investment in form-fill-seal equipment.
- Sheets:Cut-to-size flat film for manual overwrapping of irregular geometries. Artisanal confectionery and specialty retail applications drive demand.
- Tubing:Continuous seamless sleeves for centerfold conversion or direct use on form-fill-seal lines. Beverage multipack bundling consumes tubing for six-pack and twelve-pack configurations.
Rolls still capture the highest tonnage, yet bags are expanding most quickly as small-scale processors seek operational simplicity.
End Use Industry:
Regulatory stringency separates food-contact compliance from industrial performance specifications.
- Food & Beverage:Direct-contact applications demanding ECHA-registered supply chains and FDA 21 CFR 177.1520 validation. REACH phthalate migration limits have redirected European converter qualification programs entirely toward olefin-based alternatives, with German hypermarket chains now bundling film procurement with equipment service agreements.
- Pharmaceuticals:Secondary packaging for serialization compliance and tamper-evidence. Track-and-trace mandates across the EU and US drive demand for integrated tear-tape features and optical clarity for barcode verification.
- Electronics:Anti-static and abrasion-resistant grades for consumer device bundling. Premium shrink ratios protect products during distribution without compromising retail presentation.
- Consumer Goods:General merchandise wrapping where cost optimization outweighs specialized performance. Mass-market retail applications favor standard grades with broad equipment compatibility.
Food & Beverage anchors current volume. Pharmaceuticals are climbing the fastest as serialization mandates expand.
Thickness:
Downgauging imperatives compress material yields without sacrificing barrier or seal performance.
- Below 40 Micron:Ultra-thin grades enabled by metallocene polyethylene and five-layer coextrusion. German high-clarity food packagers adopt these structures to minimize material intensity while maintaining EFSA-compliant barrier performance.
- 40-60 Micron:Standard commercial grades balancing cost and durability. Automated wrapping lines across mass-market consumer goods specify this range for reliable handling without excessive gauge.
- 60-80 Micron:Heavy-duty applications requiring puncture resistance and load containment. Industrial bundling and sharp-edged products demand this mid-thick range.
- Above 80 Micron:Maximum abuse resistance for export shipping and extreme handling conditions. Limited specialty applications where mechanical protection overrides material efficiency.
Below 40 Micron leads innovation investment. 40-60 Micron retains the steepest expansion trajectory as downgauging diffuses beyond early adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors POF shrink film demand through integrated resin-to-film operations serving export-oriented food packaging clusters. Regulatory divergence between FDA and REACH compliance regimes shapes converter qualification strategies across major consuming regions.
China
Domestic resin producers backward-integrate into biaxial orientation lines, reducing import dependency for high-clarity substrates. SAMR food-contact standards and GB compliance frameworks govern olefin polymer specifications. Zhejiang and Jiangsu provinces concentrate cross-linked film capacity as converters capture premium electronics bundling applications previously dominated by Western suppliers.
United States
Food processors accelerate PVC replacement programs amid FDA 21 CFR 177.1520 validation requirements for direct-contact applications. Sealed Air Corporation leverages integrated resin-to-film operations across North American distribution networks. Midwest industrial corridors sustain master roll slitting operations for just-in-time delivery to mass-market consumer goods manufacturers.
Germany
REACH phthalate migration limits redirect converter qualification entirely toward ECHA-registered POF supply chains. German hypermarket chains bundle film procurement with secondary packaging equipment service agreements. The Ruhr industrial region and Bavarian packaging clusters drive adoption of sub-50-micron five-layer coextrusion structures for high-clarity food applications.
India
FSSAI food-contact compliance pathways for olefin polymers remain underpenetrated relative to PVC incumbent specifications. Small-batch food processors specify pre-formed POF bags to bypass capital investment in form-fill-seal equipment. Maharashtra and Gujarat industrial zones concentrate domestic converter capacity for pharmaceutical and specialty retail applications.
Japan
Premium electronics packaging demands cross-linked grades with shrink ratios exceeding 80% where clarity thresholds exceed standard film capabilities. METI industrial standards and JIS specifications govern material performance in secondary packaging applications. The Kanto region around Tokyo maintains specialized demand for pharmaceutical-grade bundling with integrated tear-tape features.
Polyolefin (POF) Shrink Film Market Competitive Landscape
Global majors compete with regional champions across resin integration and converter scale. The market structures around three tiers: integrated resin-to-film operators controlling upstream feedstock costs, specialized converters with pharmaceutical-grade certification, and mass-market rollstock suppliers competing on throughput. Strategic moves concentrate on backward integration into resin production and geographic expansion through distribution partnerships.
Within the integrated operator tier, Sealed Air Corporation and Berry Global Inc. exemplify scale-driven positioning through captive resin supply and broad distribution networks. Amcor Plc occupies a certification-specialist position, anchoring pharmaceutical-grade and multi-layer coextrusion expertise. Among Middle East-based resin suppliers, Saudi Basic Industries Corporation represents upstream feedstock integration into film-grade polymer production.
| Leading Market Players |
|---|
| Saudi Basic Industries Corporation |
| Bollore SE |
| Sealed Air Corporation |
| Clysar LLC |
| Sigma Plastics Group |
| Berry Global Inc. |
| Intertape Polymer Group Inc. |
| Allen Plastic Industries Co. Ltd. |
| Amcor Plc |
| Others |
Value Network & Pricing Analysis
Consolidated buying desks at German and French hypermarket chains negotiate film procurement through outcome-based contracts bundling shrink-wrap with equipment service agreements, compressing margin structures for standalone rollstock suppliers while rewarding integrated wrap-line optimizers with volume concentration.
Pricing Analysis
Ethylene feedstock pass-through from naphtha-cracker economics governs converter margin structures, with LLDPE resin volatility compressing film profitability during upstream petrochemical cycles. Three-tier pricing stratification separates pharmaceutical-grade certified films from standard food-contact grades and economy industrial rolls, with certification tier and volume scale as primary differentiation drivers. Price erosion runs through mass-market consumer goods segments as Chinese resin-to-film converters expand cross-linked capacity. Food and beverage processors show highest price sensitivity due to thin packaging margins, while pharmaceutical bundling tolerates premium positioning for serialization compliance.
Supply Chain Analysis
India's FSSAI domestic-content compliance pathways for olefin polymers are reshaping sourcing patterns as converters localize production to bypass import qualification timelines. Resin supply concentrates in China, Saudi Arabia, and the United States, with biaxial orientation equipment and metallocene catalyst technology as critical input dependencies. Single-source vulnerability in electron-beam cross-linking equipment creates bottleneck exposure for premium grade production. Distribution runs through master roll slitting operations in Midwest US industrial corridors and just-in-time converter networks serving European hypermarket chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as pharmaceutical serialization mandates and REACH phthalate restrictions displace commodity PVC toward premium POF specifications with compliance-driven pricing power.
For Market Incumbents: Deepen backward integration into metallocene polyethylene resin production to defend margin structures against Chinese converter expansion in cross-linked grades. Secure ECHA-registered supply chain certifications ahead of EU Green Deal recycled content mandates, while expanding pharmaceutical-grade capacity to capture track-and-trace bundling demand. For New Entrants and Emerging Players: REACH phthalate migration limits in Europe open a window for ECHA-registered supply chain qualification as a first-mover wedge against PVC incumbents. Target India's FSSAI compliance pathways for olefin polymers where certification penetration lags European benchmarks, and enter through pre-formed bag formats for small-batch food processors seeking operational simplicity without capital investment. For Investors and Strategic Acquirers: Resin-to-film integrated operators are the most active acquirer category in this space, consolidating regional converter networks to capture scale economies in distribution. Acquisition targets center on pharmaceutical-certified converters with multi-layer coextrusion expertise and established FDA-ECHA dual registration. Watch for inflection when EU extended producer responsibility frameworks mandate recycled content minimums that mechanical recycling infrastructure cannot satisfy, triggering bio-based olefin pilot program acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive LLDPE supply insulates Sealed Air and Berry Global from naphtha-cracker margin volatility. |
| Pharmaceutical-Grade Certification Investment | FDA 21 CFR 177.1520 validation opens serialization bundling demand for Amcor Plc and specialized converters. |
| Five-Layer Coextrusion Technology Deployment | Metallocene polyethylene integration enables sub-50-micron downgauging for German high-clarity food packagers. |
| Cross-Linked Film Capacity Expansion | Electron-beam orientation lines capture premium electronics bundling previously dominated by Japanese suppliers. |
| Equipment Service Agreement Bundling | Integrated wrap-line optimization contracts concentrate volume with converters serving German hypermarket procurement desks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with resin producers, film converter plant managers, and food processor procurement leads with secondary validation through customs trade data, SEC 10-K filings, and ECHA registration databases. Bottom-up volume builds from converter capacity utilization and end-use demand segmentation were cross-checked against top-down resin consumption trends across the analysis window.
Historical reference periods anchored the projection horizon through comparable-cycle analysis of ethylene feedstock cost trajectories and regulatory implementation timelines. Segmentation dimensions modeled include product configuration, thickness tier, end-use vertical, and regional compliance cluster, with CAGRs derived from elasticity-adjusted demand curves and capacity expansion pipelines. Forecast inputs incorporated REACH restriction proposal timelines and FSSAI compliance pathway maturation in India.
Revisions become necessary when LLDPE resin volatility exceeds historical bands or when EU Green Deal packaging waste directives accelerate recycled content mandates beyond mechanical recycling infrastructure readiness. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Global Blown Stretch Packaging Films Market
Poly film
US Cleanroom Film and Bags Market
Poly film
Asia Pacific Plastic Packaging Film Market
Poly film
Italy Plastic Packaging Films Market
Poly film
LDPE Films Market
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
China Plastic Packaging Film Market
Poly film
Co Extruded Films Market
Poly film
Global Cast Polypropylene Packaging Films Market
Poly film
Global Reclosable Films Market
Poly film
Soft Touch Film Market
Poly film
Global Fluoropolymer Films Market
Poly film
Poland Plastic Packaging Films Market
Poly film
Polylaminate Capsules Market
Poly film
PVC Cling Film Market
Poly film
Soft Touch Lamination Film Market